
 Plastic Ignition Holders Market | 2026-2036
Plastic Ignition Holders Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Ignition Holders Market Analytics
The EU Green Deal automotive decarbonization framework is broadening demand for thermally resilient ignition holder materials across European vehicle platforms. NGK Spark Plug Co., Ltd. leverages its ceramic-to-plastic hybrid expertise to sustain high-temperature portfolio leadership. Robert Bosch GmbH anchors continental OEM supply through integrated powertrain electronics divisions. DENSO Corporation competes on thermal engineering depth derived from hybrid powertrain programs.
Plastic ignition holders are injection-molded electrical connectors that secure spark plug terminals within engine compartments, typically fabricated from glass-filled polyamide or PPS compounds rated above 150°C continuous service temperature to resist vibration and thermal cycling. High-temperature holders lead product type margins due to material substitution away from metal in downsized turbocharged engines, while polypropylene grades dominate volume in cost-sensitive lighting and appliance applications where thermal loads remain moderate. Automotive OEMs represent the most structurally concentrated end-user channel, with tier-one suppliers negotiating multi-year platform contracts that lock in formulation specifications.
EPA tailpipe emissions enforcement and EU F-Gas Regulation on mobile air conditioning systems indirectly shape ignition holder durability standards by intensifying under-hood thermal management requirements. Japan's METI vehicle efficiency benchmarks and China's MIIT new energy vehicle mandates add parallel compliance layers for suppliers serving export markets. Stakeholders must monitor polymer feedstock volatility and OEM platform electrification timelines to calibrate capacity commitments between combustion-optimized and thermally generic product lines.
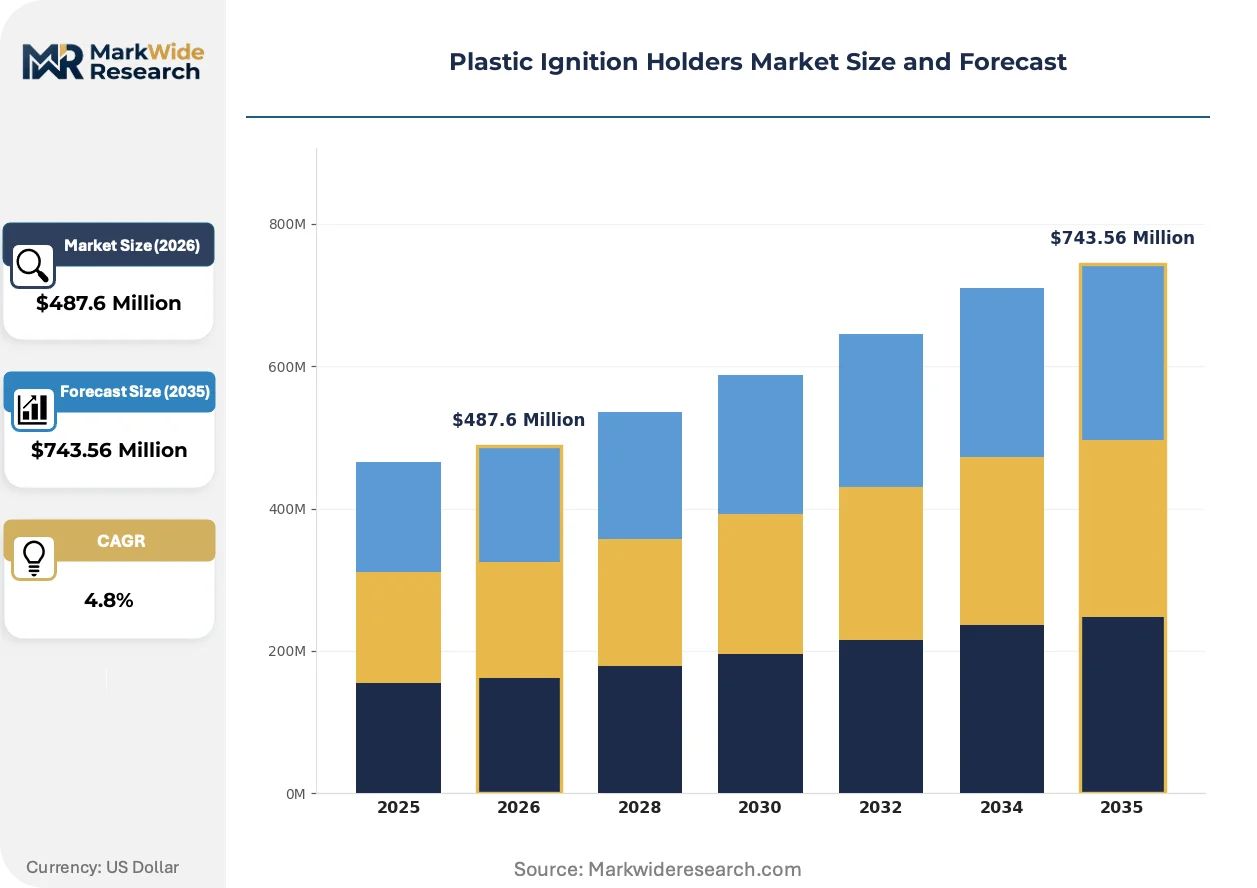
Market Dynamics
Powertrain electrification timelines are compressing combustion-optimized ignition holder demand while simultaneously tightening thermal specifications for remaining internal combustion platforms, forcing suppliers to straddle divergent material roadmaps.
Growth Catalysts
- EPA tailpipe emissions enforcement:Under-hood thermal management requirements intensify as US regulators tighten enforcement, expanding procurement of glass-filled polyamide holders rated above 180°C continuous service temperature.
- Downsized turbocharged engine proliferation:OEM powertrain strategies elevate vibration-resistant connector demand as smaller displacement engines generate higher specific thermal loads per liter.
- Germany:KBA vehicle type approval processes accelerate validation cycles for ceramic-to-plastic hybrid ignition architectures in premium automotive platforms.
Market Restraints
- Polymer feedstock volatility:PPS and high-performance polyamide resin prices fluctuate with benzene derivative markets, compressing formulation margins for specialized grades.
- Supplier concentration:Tier-one automotive electronics suppliers dominate platform contract negotiation, limiting mid-tier compounders to aftermarket or appliance subsegments.
- Electrification substitution:Battery electric vehicle architectures eliminate spark plug ignition systems entirely, eroding addressable volume in B-dedicated platforms.
Strategic Opportunities
- Hybrid powertrain thermal engineering:PHEV architectures retain internal combustion ignition systems with unique cycling profiles, creating specification white space for thermal fatigue-optimized holders.
- Japan METI vehicle efficiency benchmarks:Export-oriented suppliers align product development to Japanese regulatory timelines, accessing OEM sourcing pools for Asia-bound vehicle platforms.
- 48V mild-hybrid system proliferation:Belt-integrated starter-generator architectures sustain ignition component demand while requiring modified vibration damping specifications.
Industry Challenges
- Material science talent scarcity:Formulation chemists with high-temperature polymer compounding expertise command premium compensation, constraining R&D expansion at mid-cap suppliers.
- Multi-platform certification complexity:OEMs require simultaneous validation to USCAR, LV, and JASO standards, extending qualification timelines and freezing engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Ignition Holders Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Holders, High-Temperature Holders, Mini Holders, Adjustable Holders End User: Automotive OEMs, Aftermarket Providers, Electrical Manufacturers, Appliance Manufacturers Material: Polypropylene, PVC, ABS, Polycarbonate Application: Ignition Systems, Lighting Solutions, Power Tools, Home Appliances |
| Companies Covered | NGK Spark Plug Co., Ltd., DENSO Corporation, Robert Bosch GmbH, Standard Motor Products, Inc., HELLA GmbH & Co. KGaA, Valeo SA, Hitachi Astemo, Ltd., Marelli Corporation, BorgWarner Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Ignition Holders Market Evolving Landscape
Thermal management engineering is migrating from component-level specification to system-integrated design, collapsing traditional boundaries between ignition holders, wiring harnesses, and powertrain control modules.
Ceramic-reinforced polymer compounds are displacing conventional glass-filled grades in turbocharged gasoline direct injection applications. Tier-one suppliers specify these materials for cylinder head-mounted holders where surface temperatures exceed 200°C intermittently. The technology is modularizing supplier relationships as compounders integrate compounding and connector molding under single-source contracts.
EU F-Gas Regulation on mobile air conditioning systems indirectly elevates ignition holder durability standards by intensifying holistic under-hood thermal management requirements. Component suppliers must now validate thermal cycling performance across integrated climate-powertrain operating envelopes. European OEMs are responding with consolidated procurement of ignition and thermal management components from shared supplier pools.
Automotive electronics distributors are consolidating fragmented aftermarket channels through direct-to-workshop digital platforms. Traditional jobber networks lose share as independent repair shops source ignition holders via integrated parts-procurement systems. This channel compression is most visible in Germany and the United States where workshop management software penetration exceeds 60 percent.
Plastic Ignition Holders Market Segmentation
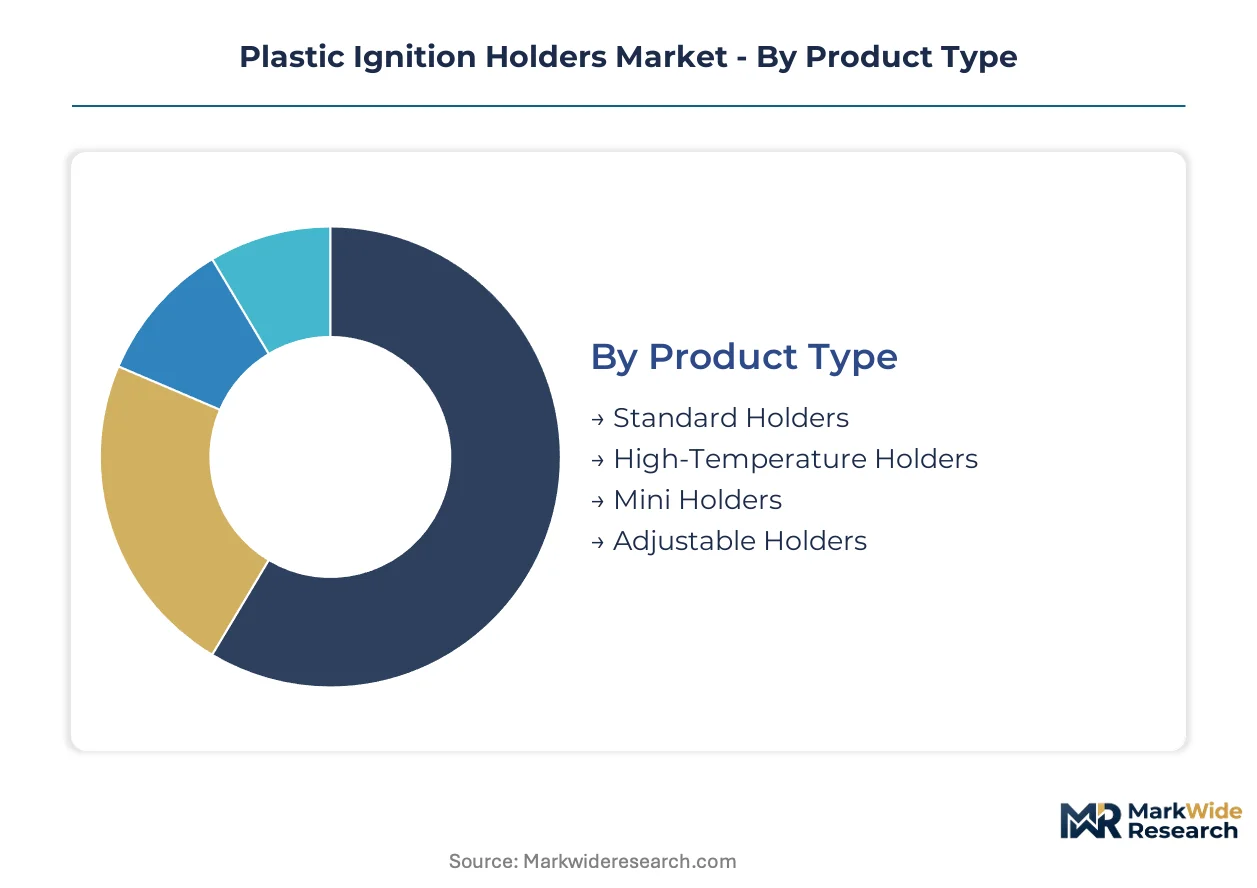
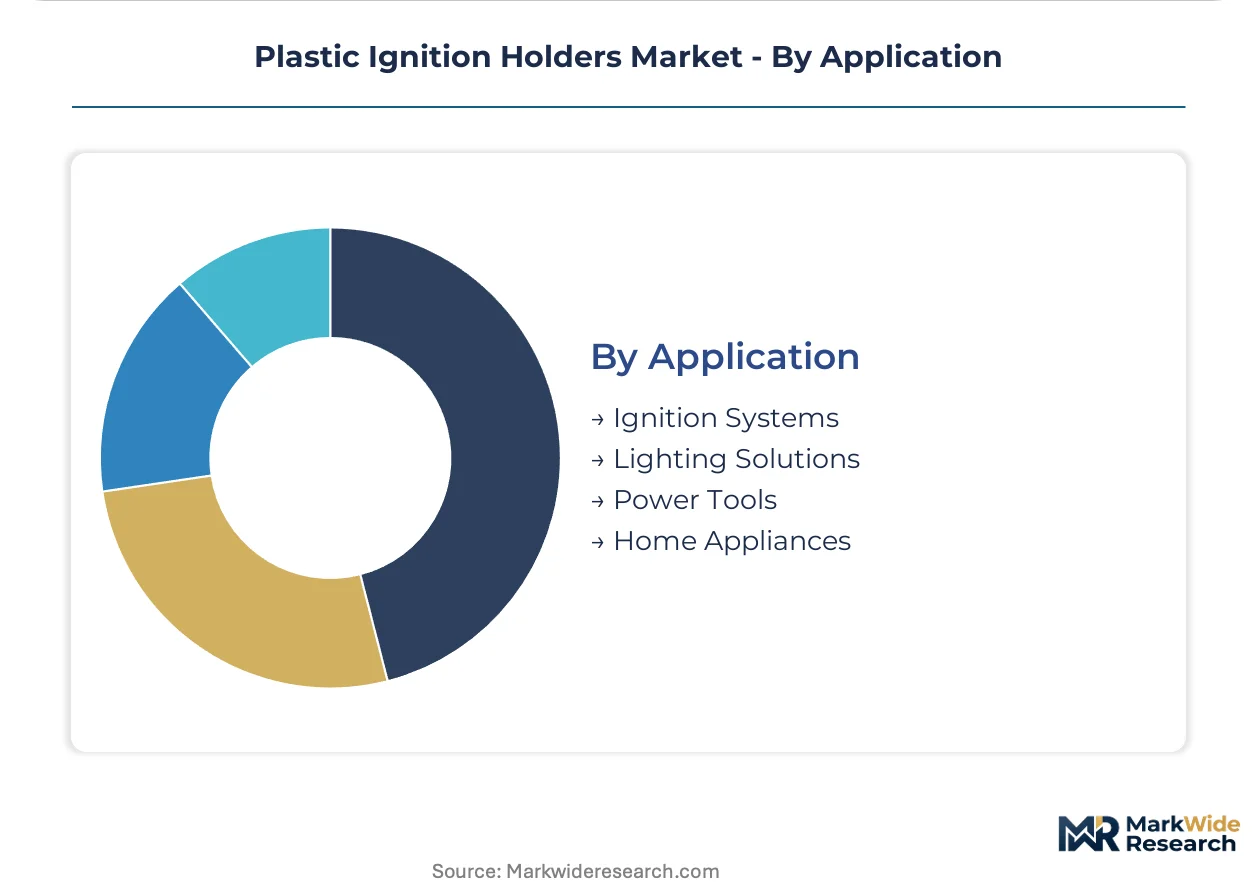
Plastic ignition holder specifications diverge sharply across thermal load profiles and regulatory exposure, with certification requirements from USCAR, LV, and JASO standards fragmenting supplier portfolios. Material selection and end-user channel concentration determine margin structures more than volume scale alone.
Product Type:
USCAR-2 and LV 112-1 thermal cycling certifications gate entry for high-temperature variants, while standard grades navigate less stringent appliance-grade benchmarks. OEM platform contracts specify validation tiers that compounders must pre-qualify before quotation.
- High-Temperature Holders:Glass-filled polyamide and PPS compounds rated above 180°C continuous service temperature dominate turbocharged gasoline direct injection applications. German KBA type approval processes validate these holders for cylinder head mounting where intermittent surface temperatures exceed 200°C.
- Standard Holders:Polypropylene and ABS formulations serve moderate thermal environments in lighting and appliance applications, with procurement concentrating among cost-sensitive electrical manufacturers in appliance manufacturing clusters.
- Mini Holders:Compact form factors address space-constrained engine bay packaging in downsized powertrain architectures.
- Adjustable Holders:Modular terminal positioning accommodates variant spark plug geometries across multi-platform OEM sourcing pools.
Standard holders sit at the top of the volume ranking, with high-temperature holders climbing the fastest.
End User:
Channel economics separate multi-year platform lock-ins from spot-market procurement, with tier-one automotive electronics suppliers commanding formulation specification authority.
- Automotive OEMs:Powertrain electrification timelines compress combustion-optimized demand while tightening thermal specifications for remaining internal combustion platforms. EPA emissions enforcement and EU Green Deal mandates reshape procurement toward ceramic-reinforced polymer grades.
- Aftermarket Providers:Digital direct-to-workshop platforms consolidate fragmented distribution in Germany and the United States, with workshop management software penetration exceeding sixty percent in mature markets.
- Electrical Manufacturers:Lighting and industrial control applications drive polypropylene volume through cost-optimized specifications.
- Appliance Manufacturers:Moderate thermal loads and extended production runs favor standardized holder geometries with minimal customization overhead.
Automotive OEMs anchor revenue concentration, with aftermarket providers gaining channel share fastest through platform consolidation.
Material:
Feedstock volatility in benzene derivative markets compresses formulation margins for specialized grades, separating commodity resin procurement from engineered compound development.
- Polypropylene:Cost-sensitive volume leader in appliance and lighting applications where thermal loads remain below 120°C continuous exposure.
- PPS:Sulfur-containing aromatic polymer delivers hydrolysis resistance and dimensional stability for turbocharged engine bay mounting.
- ABS:Balanced impact strength and processability serve mid-tier thermal specifications in power tool and lighting connector applications.
- Polycarbonate:Optical clarity and ignition resistance properties address specialized lighting holder geometries with transparency requirements.
Polypropylene dominates unit volume, with PPS expanding most quickly on turbocharged powertrain proliferation.
Application:
Functional thermal cycling profiles separate automotive ignition duty from intermittent appliance use, with validation protocols scaling accordingly.
- Ignition Systems:Engine bay thermal management requirements intensify under EPA emissions standards and EU F-Gas Regulation compliance, elevating glass-filled polyamide procurement for spark plug terminal security.
- Lighting Solutions:Heat sink integration and LED driver thermal profiles drive holder specification toward moderate-temperature engineering plastics with color stability requirements.
- Power Tools:Vibration resistance and intermittent thermal spikes from motor commutation shape connector design for cordless and corded equipment platforms.
- Home Appliances:Extended service life expectations and moderate thermal exposure favor standardized polypropylene holders with minimal material premium.
Home appliances generate the highest unit volumes, with ignition systems capturing the steepest expansion trajectory on regulatory thermal management tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plastic ignition holder manufacturing scaled through German automotive supplier networks in the 1980s, spreading to Japanese tier-one electronics houses and US Midwest automotive corridors as engine bay thermal specifications tightened.
Germany
KBA vehicle type approval processes accelerate validation cycles for ceramic-to-plastic hybrid ignition architectures. The EU Green Deal automotive decarbonization framework broadens procurement of thermally resilient materials across European vehicle platforms. Stuttgart and Munich automotive clusters anchor continental OEM supply relationships for high-temperature holder specifications.
United States
EPA tailpipe emissions enforcement intensifies under-hood thermal management requirements, expanding procurement of glass-filled polyamide holders rated above 180°C continuous service temperature. The IRA domestic content provisions reshape supplier qualification criteria for electrification-transitioning platforms. Detroit and Southeast automotive manufacturing corridors concentrate tier-one electronics supplier engineering resources.
Japan
METI vehicle efficiency benchmarks drive export-oriented product development alignment for Asia-bound vehicle platforms. Hybrid powertrain thermal engineering creates specification white space for thermal fatigue-optimized holders. Nagoya and Tokyo-Yokohama industrial clusters sustain ceramic-to-polymer hybrid expertise through integrated powertrain electronics divisions.
China
MIIT new energy vehicle mandates add parallel compliance layers for suppliers serving domestic and export markets simultaneously. Dual carbon goals accelerate powertrain electrification timelines while sustaining ignition component demand for remaining internal combustion platforms. Yangtze River Delta manufacturing clusters concentrate cost-optimized holder production for appliance and lighting applications.
South Korea
MFDS automotive component quality frameworks intersect with OEM platform electrification timelines, calibrating capacity commitments between combustion-optimized and thermally generic product lines. 48V mild-hybrid system proliferation sustains ignition component demand with modified vibration damping specifications. Seoul Capital Area electronics suppliers negotiate multi-year platform contracts that lock in formulation specifications.
Plastic Ignition Holders Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the plastic ignition holder supply base. Tier-one automotive electronics suppliers dominate platform contract negotiation, while mid-tier compounders serve aftermarket or appliance subsegments. Three archetypes populate the competitive map: integrated powertrain electronics divisions, specialized ceramic-to-polymer hybrid engineers, and cost-optimized volume manufacturers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as electrification timelines compress.
Within the integrated powertrain tier, Robert Bosch GmbH and DENSO Corporation exemplify thermal engineering depth derived from hybrid program exposure. NGK Spark Plug Co., Ltd. occupies a position bridging ceramic heritage with polymer compounding adaptation. These three anchors represent contrasting geographic and structural approaches to the combustion-electrification transition.
| Leading Market Players |
|---|
| NGK Spark Plug Co., Ltd. |
| DENSO Corporation |
| Robert Bosch GmbH |
| Standard Motor Products, Inc. |
| HELLA GmbH & Co. KGaA |
| Valeo SA |
| Hitachi Astemo, Ltd. |
| Marelli Corporation |
| BorgWarner Inc. |
| Others |
Value Network & Pricing Analysis
Ceramic-reinforced polymer compounding technology is displacing conventional glass-filled grades across turbocharged powertrain platforms, simultaneously elevating raw material cost structures and concentrating formulation expertise among German and Japanese specialty compounders with captive compounding-molding integration.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with USCAR-2 and LV 112-1 certification tiers separating high-temperature automotive grades from appliance-grade polypropylene specifications. Price differentiation hinges on thermal rating thresholds and OEM platform validation depth, with automotive OEMs exhibiting lowest price sensitivity due to multi-year contract lock-ins while appliance manufacturers drive hard volume negotiations.
Supply Chain Analysis
PPS and high-performance polyamide resin supply rests on German, Japanese, and South Korean specialty chemical producers, with benzene derivative feedstock volatility transmitting directly into formulation margins. Raw material dependencies encompass aromatic polymer precursors, glass fiber reinforcements, and ceramic filler compounds, with single-source vulnerability concentrated in sulfur-containing polymer grades. Distribution runs through tier-one automotive electronics suppliers commanding specification authority over OEM platform contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic ignition holders market reads as a late-cycle quality story, with powertrain electrification timelines compressing volume while elevating thermal specification premiums for remaining combustion platforms.
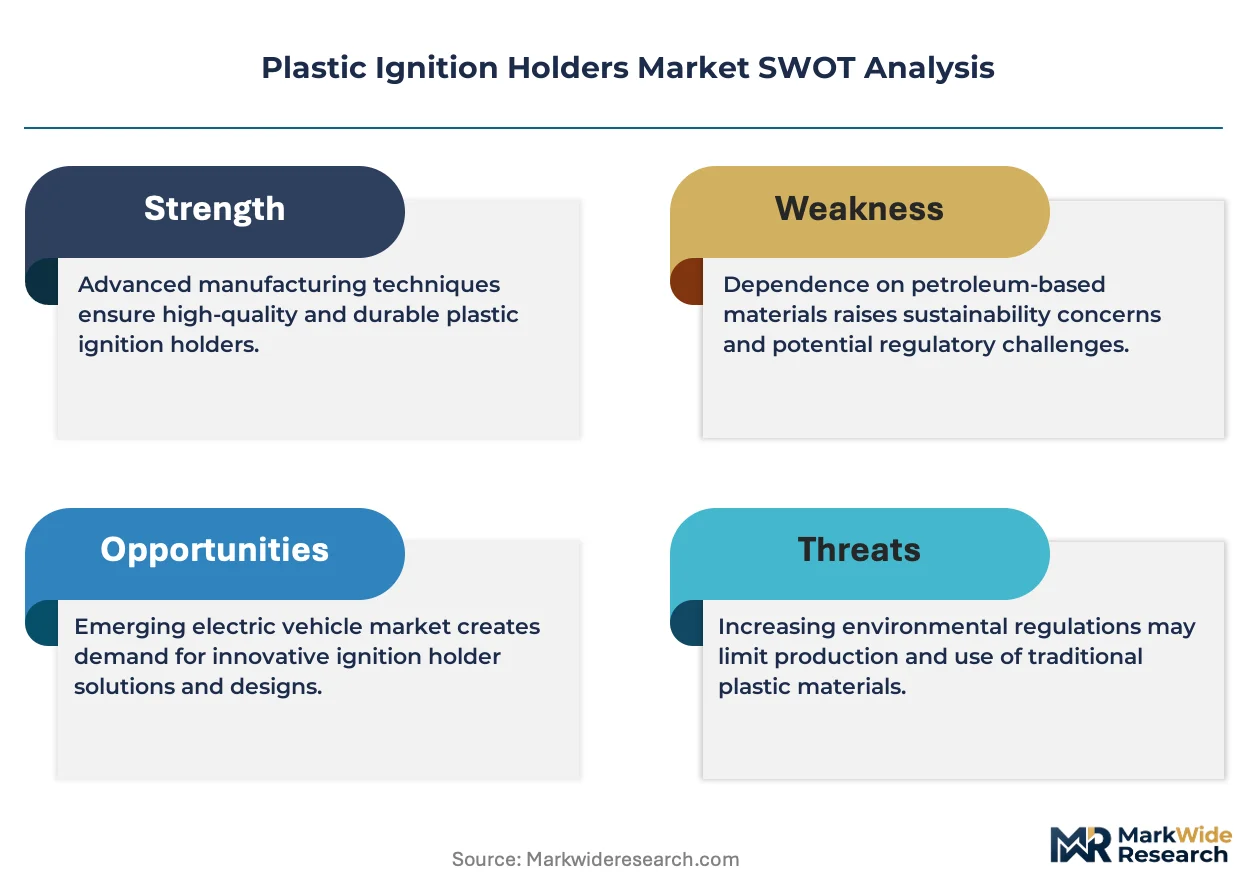
For Market Incumbents: Acquire ceramic-to-polymer hybrid formulation capabilities to defend against electrification substitution eroding addressable volume in B-dedicated platforms. Deepen backward integration into PPS resin supply to offset benzene derivative volatility compressing margins on high-temperature grades. Lock multi-year platform contracts with 48V mild-hybrid system producers before specification windows close. For New Entrants and Emerging Players: Tier-two aftermarket distributors represent the most penetrable channel partner type for bypassing tier-one supplier concentration gating OEM platform access. Target appliance manufacturing clusters in China's Yangtze River Delta for cost-optimized polypropylene volume build, leveraging standardized geometries with minimal customization overhead. Pursue direct-to-workshop digital platform partnerships in Germany and the United States where workshop management software penetration exceeds sixty percent. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap compounders with stranded combustion-optimized capacity yet intact thermal engineering talent pools. Long-term viability hinges on hybrid powertrain thermal fatigue specification capture through the electrification transition window. Watch PHEV platform procurement acceleration as the inflection signal separating combustion-optimized from thermally generic product line viability.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic-Polymer Hybrid Formulation Investment | NGK Spark Plug Co. and Robert Bosch GmbH anchor premium tier positioning through integrated thermal engineering depth. |
| Backward Integration into PPS Resin Supply | DENSO Corporation secures formulation margin protection against benzene derivative volatility in specialty polymer markets. |
| Multi-Year Platform Contract Lock-In | Tier-one suppliers freeze specification authority with OEMs before 48V mild-hybrid and PHEV procurement windows compress. |
| Direct-to-Workshop Digital Platform Launch | Aftermarket channel compression in Germany and the United States bypasses traditional jobber network intermediation. |
| Appliance Manufacturing Cluster Capacity Addition | China's Yangtze River Delta concentration enables cost-optimized polypropylene holder scale for lighting and industrial control applications. |
Research Methodology
Direct dialogue with tier-one automotive electronics procurement officers, OEM platform engineers, aftermarket distributor operations heads, and specialty polymer compounding technical directors grounded qualitative assessment, cross-referenced against customs trade data, SEC 10-K filings from listed automotive suppliers, vehicle production databases, and IHS Markit registration statistics. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Segment-level demand projections across product type, material grade, end-user channel, and application thermal profile fed into an analytical framework spanning the projection horizon, with CAGRs derived from regression against powertrain electrification timeline scenarios and regulatory thermal management tightening trajectories. Hybrid powertrain penetration rates and EPA emissions enforcement intensity served as primary forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to BEV platform cancellation rates, PHEV specification durability requirements, and polymer feedstock volatility spikes. A small set of triggers—MIIT new energy vehicle mandate acceleration, EU F-Gas Regulation enforcement tightening, and OEM platform electrification commitment reversals—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Recycled Plastics
Non-Ferrous Scrap Recycling Market
Recycled Plastics
Vietnam Recycled Plastics Market
Recycled Plastics
Microplastic Recycling Market
Recycled Plastics
North America Plastic Waste Management Market
Recycled Plastics
Green Polyvinyl Chloride Market
Recycled Plastics
Plastic Waste Management Market
Recycled Plastics
Advanced-Recycled Polyolefin Resins for Consumer and Industrial Applications Market
Recycled Plastics
Myanmar Plastics Market
Recycled Plastics
Plastics-To-Fuel (PTF) Market
Recycled Plastics
US Recycled Plastics Market
Recycled Plastics
Post-Consumer Recycled Plastics in Consumer Electronics Market
Recycled Plastics
Saudi Arabia Plastic Components Market
Recycled Plastics
Plastic Compounds Market
Recycled Plastics
Iron Recycling Market
Recycled Plastics
Recycled Thermoplastic Market
Recycled Plastics
Plastic Lumber Market