
 Polyvinyl Butyral (PVB) Market | 2026-2036
Polyvinyl Butyral (PVB) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Butyral (PVB) Market Intelligence
Chinese resin producers is restructuring capacity to serve the domestic automotive and architectural glass sectors, tightening supply availability for export markets. Eastman Chemical Company leverages its integrated butyraldehyde-to-PVB film chain to sustain cost discipline across North American and Asian operations. Kuraray Co., Ltd. anchors premium acoustic and high-strength grades through proprietary plasticization technology. Sekisui Chemical Co., Ltd. competes on optical clarity standards for heads-up display laminates.
Polyvinyl butyral is a thermoplastic resin synthesized through acetalization of polyvinyl alcohol with butyraldehyde, typically containing 15-25% hydroxyl groups by weight to control adhesion and moisture sensitivity. The resin forms transparent, elastomeric films that bond glass layers under heat and pressure, absorbing impact energy and preventing shatter dispersion in automotive windshields and architectural glazing. Standard PVB and acoustic PVB together occupy the dominant volume positions, though margin pools concentrate in high-strength and UV resistant variants where specification thresholds exclude commodity producers. Solar panel encapsulation represents the fastest-growing application segment, driven by photovoltaic module manufacturers seeking edge-seal alternatives to ethylene-vinyl acetate.
FDA regulations govern PVB contact applications in food packaging and medical devices, while NHTSA and ECE R43 standards dictate laminated glass performance for vehicle glazing across the United States and European type-approval systems. The EU Green Deal and REACH substance restrictions are forcing reformulation of plasticizer packages to eliminate orthophthalate chemistries, reshaping supplier qualification protocols. Stakeholders must monitor evolving building codes in China and India, where energy-efficiency mandates for commercial facades are accelerating specification upgrades from standard to low-emission PVB grades.
Market Dynamics
Automotive electrification is compressing specification cycles for acoustic and safety-grade interlayers, forcing resin-to-film supply chains to synchronize R&D timelines with EV platform launches rather than traditional model-year refresh schedules.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are redirecting specification authority toward laminated glass solutions with lower lifecycle warming potential, elevating PVB against gas-filled alternatives in commercial facade retrofits.
- Photovoltaic encapsulation:Module manufacturers seeking edge-seal durability beyond ethylene-vinyl acetate are qualifying PVB for frameless and bifacial panel architectures, opening volume positions outside traditional glazing.
- China:Domestic automakers and glass laminators are consolidating procurement around state-backed resin corridors, concentrating demand pull within integrated manufacturing zones that bypass import-dependent supply chains.
Market Restraints
- Butyraldehyde cost volatility:Crude-linked n-butanol feedstock swings compress margin predictability for non-integrated film producers lacking captive aldehyde supply.
- East Asian supply concentration:Resin and film capacity clusters in China, Japan, and South Korea expose buyers to single-source risk during regional logistics disruptions or export licensing shifts.
- REACH orthophthalate restrictions:ECHA substance evaluations are forcing plasticizer reformulations that extend qualification timelines and raise compliance costs for European supply contracts.
Strategic Opportunities
- India:Bureau of Indian Standards energy-efficiency mandates for commercial buildings are accelerating specification upgrades from unplasticized to low-emission PVB grades in facade retrofits.
- Heads-up display laminates:Optical clarity specifications for augmented-reality windshields are creating premium tier positions distinct from commodity acoustic and standard safety grades.
- GB standards harmonization:China's alignment of automotive glass testing protocols with ECE R43 is simplifying cross-qualification for exporters targeting domestic EV supply chains.
Industry Challenges
- Acoustic engineering talent scarcity:Formulation chemists capable of tuning damping properties across temperature and frequency ranges command premium compensation, constraining mid-tier producer R&D scaling.
- Cleanroom film extrusion capex:Optical-grade capacity for HUD applications requires particulate-controlled manufacturing environments that extend payback periods beyond standard safety film investments.
- Dual carbon compliance timelines:China's MEE disclosure requirements and EU CSRD scope 3 reporting are forcing parallel carbon accounting system implementations across multinational supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Butyral (PVB) Market |
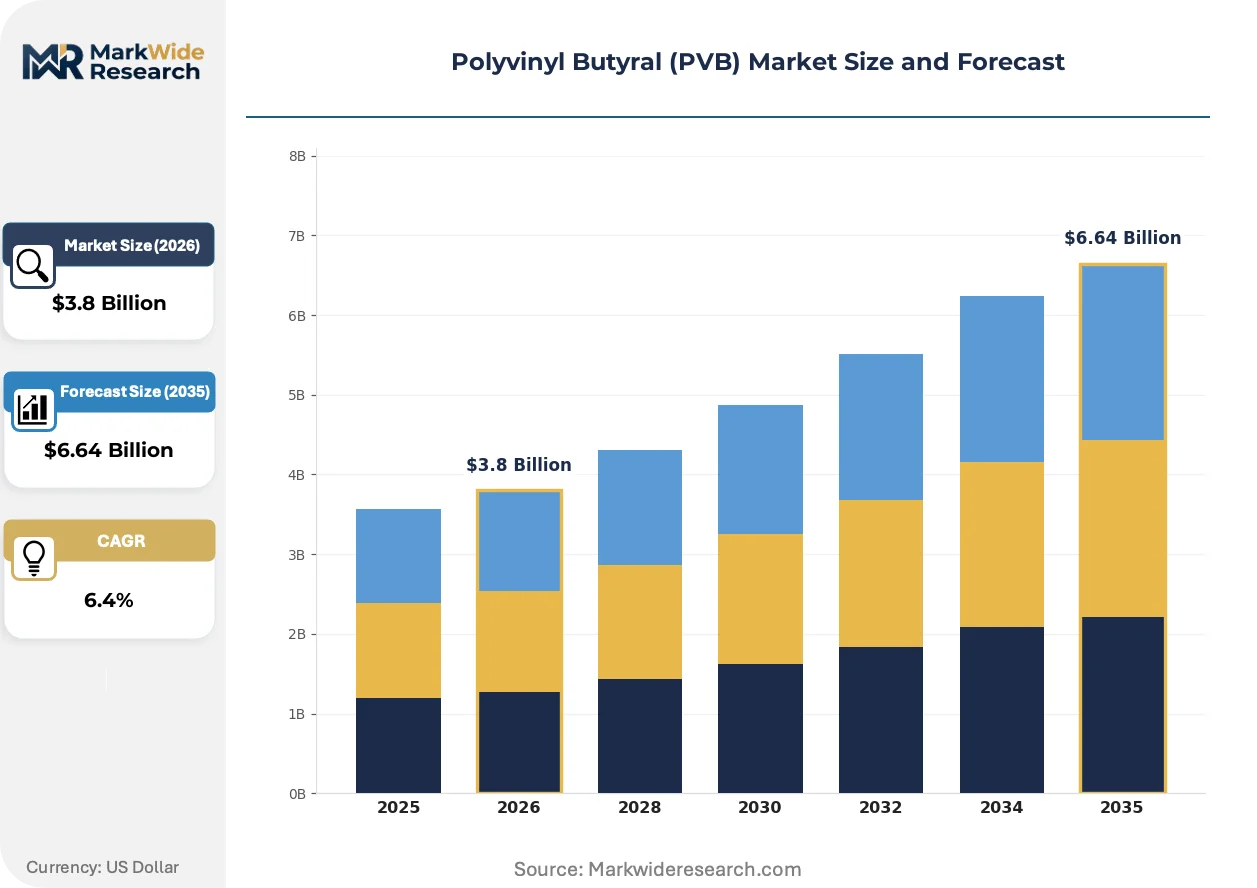
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard PVB, Acoustic PVB, High-Strength PVB, UV Resistant PVB, Low Emission PVB Application: Automotive Laminated Glass, Architectural Laminated Glass, Solar Panel Encapsulation, Safety Glass, Electrical Insulation End User Industry: Vehicle Manufacturers, Building & Construction Firms, Renewable Energy Producers, Electrical Equipment Manufacturers Form: Films, Resin Pellets, Sheets, Powder |
| Companies Covered | Chang Chun Group, Kingboard Fogang Specialty Resin Co., Ltd., Eastman Chemical Company, Anhui Wanwei Bisheng New Materials Co., Ltd., Huakai Plastic (Chongqing) Co., Kuraray Co., Ltd., Saint-Gobain, Everlam, Sekisui Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Butyral (PVB) Market Strategic Shifts & Innovations
Digital twin simulation of laminate performance is compressing development cycles and enabling real-time specification tuning for automakers launching multiple EV variants on shared platforms.
Thermoplastic polyurethane interlayers are decentralizing competitive positioning in premium acoustic applications by offering comparable damping coefficients at reduced thickness, enabling weight reduction targets that PVB suppliers must match through modified plasticizer packages. German OEMs have accelerated TPU qualification for flagship electric sedans, compressing the timeline for incumbent film producers to demonstrate equivalent performance in head-to-head NVH benchmarking. The technology is decentralizing specification authority from traditional safety-grade suppliers toward materials science specialists with polymer physics capabilities.
REACH substance restriction proposals targeting orthophthalate plasticizers are forcing reformulation investments across European PVB supply chains, with ECHA dossier evaluations extending qualification timelines for legacy product lines. Film producers are accelerating bio-based and non-phthalate alternative testing to maintain automotive OEM approval status ahead of sunset dates. Architectural specification consultants are already inserting plasticizer chemistry disclosure clauses into facade procurement templates, shifting competitive differentiation toward transparency rather than performance metrics alone.
Automotive procurement teams are consolidating interlayer purchasing under platform-level agreements rather than glass-laminator-mediated contracts, compressing supplier negotiation leverage and accelerating price discovery. Tier-one laminators in China and Germany are responding by developing captive specification capabilities and direct OEM technical relationships. The pattern is most visible in Volkswagen Group and BYD supply chains, where resin producers now participate in platform-definition stage gates previously restricted to glass fabricators.
Polyvinyl Butyral (PVB) Market Segmentation
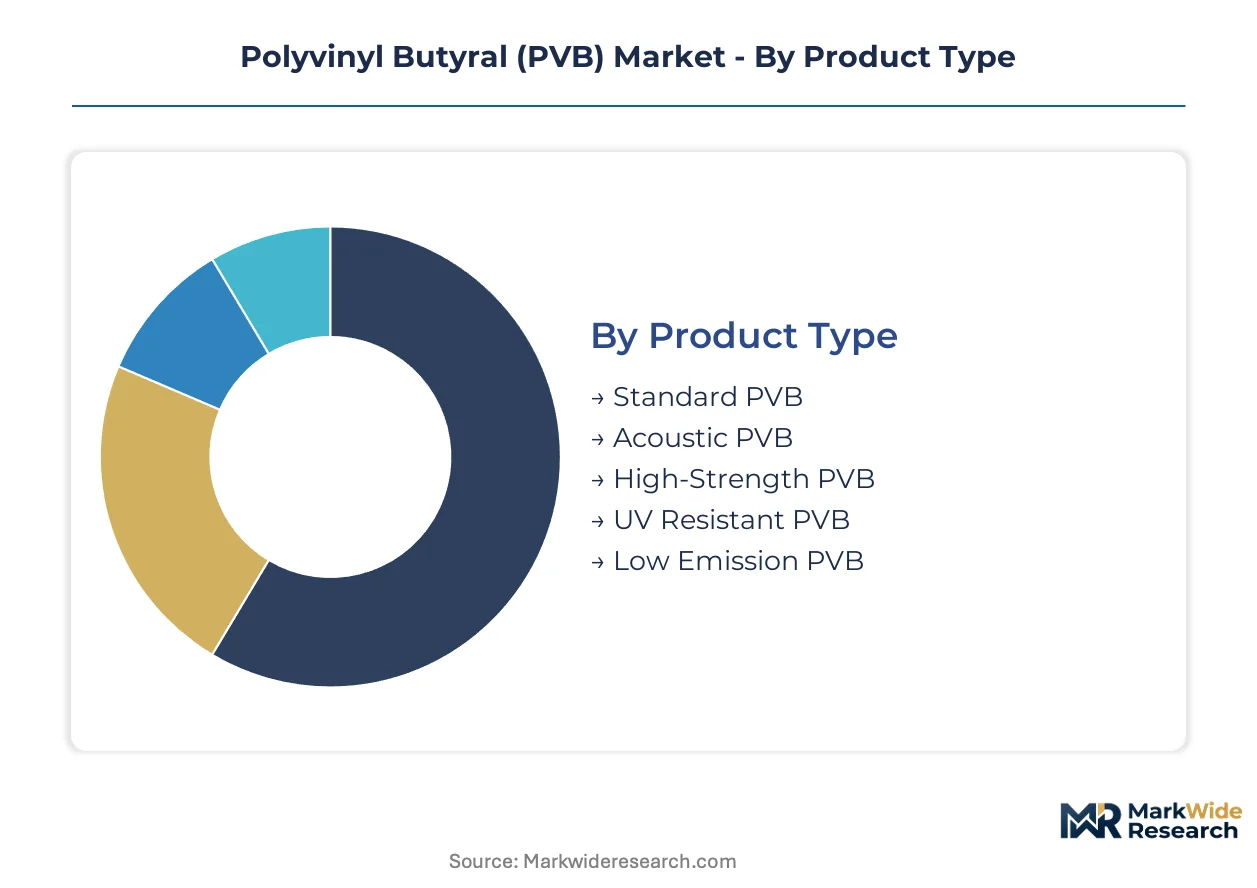
PVB segmentation reflects divergent capital requirements across resin synthesis, film extrusion, and application-specific qualification. Product grade differentiation demands specialized plasticizer chemistry and cleanroom infrastructure, while application segments impose distinct certification timelines and customer concentration patterns.
Product Type:
Capital intensity peaks in acoustic and optical-grade segments where particulate-controlled extrusion lines and proprietary damping formulations require extended depreciation schedules. Standard grades run on commodity equipment with lower barrier-to-entry thresholds.
- Standard PVB:Baseline resin formulation with 15-25% hydroxyl content delivers fundamental adhesion and impact absorption for mass-market automotive windshields. Demand concentrates in China where domestic glass laminators source from state-backed resin corridors to bypass import dependencies.
- Acoustic PVB:Modified plasticizer packages tune damping coefficients across temperature and frequency ranges to meet electric vehicle NVH specifications. German OEMs have accelerated qualification timelines for flagship sedans, compressing development cycles for incumbent suppliers.
- High-Strength PVB:Elevated molecular weight architectures for hurricane-resistant architectural glazing and premium safety applications.
- UV Resistant PVB:Stabilizer packages for prolonged outdoor exposure in solar encapsulation and tropical facade installations.
- Low Emission PVB:Reformulated plasticizer systems eliminating orthophthalate chemistries to satisfy REACH restrictions and green building certification schemes.
Most installed capacity flows through Standard PVB. Expansion is steepest in Acoustic PVB.
Application:
Customer qualification intensity varies sharply across segments, with automotive OEM direct procurement compressing traditional laminator-mediated supply chains. Solar encapsulation carries the shortest certification runway but demands frameless panel durability testing.
- Automotive Laminated Glass:Windshield and side-lite applications absorbing impact energy while preventing shatter dispersion. Procurement consolidation under platform-level agreements at Volkswagen Group and BYD is shifting negotiation leverage toward resin producers.
- Solar Panel Encapsulation:Edge-seal and bifacial panel architectures seeking alternatives to ethylene-vinyl acetate. Module manufacturers in China and Germany are qualifying PVB for frameless designs exposed to thermal cycling stress.
- Architectural Laminated Glass:Commercial facade retrofits responding to EU F-Gas Regulation phase-down mandates and energy-efficiency codes.
- Safety Glass:Hurricane and blast-resistant glazing for institutional and high-security buildings.
- Electrical Insulation:Niche applications in transformer and cable manufacturing requiring dielectric stability.
Automotive Laminated Glass commands the dominant revenue share. Solar Panel Encapsulation is climbing the fastest.
End User Industry:
Buyer concentration and technical specification authority differ materially across verticals, with vehicle manufacturers exerting direct R&D stage-gate involvement while construction firms delegate to specification consultants.
- Vehicle Manufacturers:Electric vehicle platforms are compressing interlayer specification cycles to synchronize with accelerated model launches rather than traditional refresh schedules. Acoustic performance targets for cabin quietness are elevating grade requirements.
- Building & Construction Firms:Commercial facade retrofits in India are accelerating under Bureau of Indian Standards energy-efficiency mandates, shifting procurement from unplasticized to low-emission grades.
- Renewable Energy Producers:Photovoltaic developers seeking 25-year edge-seal durability for utility-scale installations.
- Electrical Equipment Manufacturers:Transformer and cable OEMs with stable but low-volume demand profiles.
Vehicle Manufacturers absorb the highest premium-grade volume. Renewable Energy Producers are expanding most quickly.
Form:
Manufacturing asset specificity determines competitive moats, with film extrusion requiring continuous web handling expertise while resin pellet production rewards feedstock integration.
- Films:Continuous extrusion and calendering into interlayer sheets with controlled thickness tolerance for optical clarity. Heads-up display applications demand cleanroom environments that extend payback periods beyond standard safety film investments.
- Resin Pellets:Acetalized polyvinyl alcohol feedstock for captive film production or merchant sale to third-party extruders. Eastman Chemical's integrated butyraldehyde-to-pellet chain sustains cost discipline against non-integrated competitors.
- Sheets:Thicker gauge formats for specialty lamination and prototype development.
- Powder:Compounding feedstock for coating and adhesive formulations.
Films represent the dominant value capture point. Resin Pellets are gaining share fastest through backward integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands resin capacity expansion while Germany drives acoustic-grade specification standards for electric vehicle platforms.
China
Domestic automakers BYD and NIO compress interlayer procurement cycles to match accelerated EV platform launches. MIIT enforces GB standards harmonization with ECE R43 for automotive glass type-approval. The Yangtze River Delta concentrates integrated resin-to-film manufacturing corridors serving state-backed glass laminators.
Germany
Volkswagen Group and BMW consolidate platform-level interlayer agreements, bypassing traditional laminator mediation. KBA enforces ECE R43 compliance timelines that synchronize with EU F-Gas Regulation phase-down mandates. The Stuttgart-Munich corridor anchors acoustic PVB R&D for flagship electric sedan NVH benchmarking.
United States
Detroit Three OEMs prioritize heads-up display optical clarity specifications for augmented-reality windshields. NHTSA maintains laminated glass performance standards under FMVSS 205 while California CARB rules influence low-emission grade procurement. The Great Lakes region sustains butyraldehyde-integrated film production chains.
India
Commercial facade retrofits accelerate under Bureau of Indian Standards energy-efficiency mandates shifting procurement to low-emission grades. CDSCO regulates medical device applications where PVB contact limits apply. Maharashtra and Gujarat host emerging glass laminator clusters serving domestic construction demand.
Japan
Premium acoustic and optical-grade specifications dominate procurement from domestic automakers Toyota and Honda. METI oversees JIS standards alignment with international automotive glass testing protocols. The Nagoya-Osaka corridor maintains specialty resin formulation capabilities for high-strength architectural applications.
Polyvinyl Butyral (PVB) Market Key Industry Players
East Asian producers anchor the integrated resin-to-film tier; European and North American specialists hold premium acoustic and optical-grade positions. The vendor base splits between scale-driven commodity suppliers and formulation-focused technology licensors. Three archetypes dominate: captive aldehyde-integrated resin producers, cleanroom film extrusion specialists, and platform-direct automotive qualification partners. Capacity expansion and plasticizer reformulation investments constitute the dominant competitive moves as REACH restrictions tighten.
Among Japanese chemical conglomerates, Kuraray Co., Ltd. and Sekisui Chemical Co., Ltd. exemplify the premium-grade archetype through proprietary damping and optical clarity capabilities. Eastman Chemical Company represents the integrated cost-structure model with captive butyraldehyde supply chains spanning North American and Asian operations. These three anchors demonstrate how geographic feedstock control and cleanroom manufacturing infrastructure stratify competitive positioning across standard and specialty grade tiers.
| Leading Market Players |
|---|
| Chang Chun Group |
| Kingboard Fogang Specialty Resin Co., Ltd. |
| Eastman Chemical Company |
| Anhui Wanwei Bisheng New Materials Co., Ltd. |
| Huakai Plastic (Chongqing) Co. |
| Kuraray Co., Ltd. |
| Saint-Gobain |
| Everlam |
| Sekisui Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Automotive OEM platform procurement teams are compressing interlayer negotiations into consolidated agreements that bypass traditional laminator mediation, shifting pricing power toward resin producers with captive butyraldehyde supply chains and acoustic formulation capabilities.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade resin while premium acoustic and optical tiers sustain margin buffers through qualification barriers. Three-tier pricing structure across premium, standard, and economy levels separates HUD-grade optical clarity from mass-market safety film. Price differentiation hinges on ECE R43 certification tier and cleanroom manufacturing infrastructure. Pricing pressure stems from butyraldehyde cost volatility linked to crude-linked n-butanol feedstock swings. Building and construction firms show highest price sensitivity, while vehicle manufacturers absorb premiums for NVH-optimized grades.
Supply Chain Analysis
Dual-sourcing mandates from Volkswagen Group and BYD platform procurement teams are forcing resin producers to qualify secondary film extrusion partners across integrated manufacturing corridors. Geographic supply concentrates in China, Japan, and South Korea, with Yangtze River Delta clusters serving state-backed domestic demand. Raw material dependencies rest on n-butanol feedstock, butyraldehyde intermediates, and polyvinyl alcohol resin. Single-source vulnerability escalates during regional logistics disruptions or export licensing shifts. Distribution runs through captive resin-to-film chains and third-party merchant extruders serving architectural laminators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electric vehicle acoustic specifications are displacing commodity-grade procurement, rewarding producers with platform-direct OEM relationships and REACH-compliant plasticizer portfolios.
For Market Incumbents: Cement platform-direct technical relationships with BYD and Volkswagen Group procurement teams before laminator mediation erodes entirely. Prioritize backward integration into butyraldehyde supply to defend margin position against n-butanol volatility. Accelerate non-phthalate plasticizer qualification ahead of ECHA sunset dates to maintain automotive OEM approval status. For New Entrants and Emerging Players: Begin with solar panel encapsulation edge-seal applications where qualification timelines compress versus automotive grade certification. Target India commercial facade retrofits responding to Bureau of Indian Standards energy-efficiency mandates as the most penetrable geography. Pursue direct technical partnerships with frameless bifacial module manufacturers seeking alternatives to ethylene-vinyl acetate. For Investors and Strategic Acquirers: Chemical conglomerates with captive aldehyde infrastructure are the most active acquirer in this space, consolidating resin capacity to serve integrated film production. Long-term viability centers on producers with dual carbon compliance systems spanning China's MEE disclosure and EU CSRD scope 3 reporting. Monitor ECHA orthophthalate restriction implementation timelines as the critical inflection signal for plasticizer reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butyraldehyde | Eastman Chemical's captive supply chain sustains cost discipline against n-butanol volatility. |
| Non-Phthalate Plasticizer Reformulation | REACH orthophthalate restrictions force qualification investments ahead of ECHA sunset dates. |
| Cleanroom Film Extrusion Capacity | Optical-grade HUD applications require particulate-controlled environments extending payback periods. |
| Platform-Direct OEM Qualification | Volkswagen Group and BYD procurement consolidation shifts negotiation leverage toward resin producers. |
| Solar Encapsulation Edge-Seal Qualification | Frameless bifacial module architectures open volume positions outside traditional glazing applications. |
Research Approach
Direct dialogue with resin plant managers, automotive platform engineers at BYD and Volkswagen Group, glass laminator procurement leads, and acoustic R&D directors grounded qualitative insights in operational reality. Secondary validation drew from MIIT GB standards documentation, ECHA REACH dossier evaluations, customs trade data for butyraldehyde and PVB film flows, and SEC 10-K disclosures from integrated chemical producers. Bottom-up capacity modeling and top-down demand triangulation across automotive, architectural, and solar application segments ensured cross-verified outputs.
Segment-level value and volume estimates emerged from grade-tier splits across standard, acoustic, high-strength, UV-resistant, and low-emission formulations, crossed with end-use industry procurement patterns and regional production hub concentrations. CAGRs were derived from elasticity-adjusted demand projections incorporating EV platform launch schedules and solar module deployment trajectories. Forecast inputs included butyraldehyde feedstock cost indices and REACH compliance timeline assumptions.
Caveats apply where ECHA orthophthalate restriction implementation delays or China export licensing shifts could materially shift the outlook. Deviation in electric vehicle platform launch cadence or solar module frameless architecture adoption would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Polyimides Market
Polymers & Resins
PA66 Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Global Styrenic Polymers Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Rosin Resin Market