
 Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market | 2026-2036
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market Analysis
Automotive glazing is decoupling from traditional glass supply chains as electric vehicle manufacturers prioritize weight reduction. Evonik Industries leverages its specialty methacrylate chemistry to dominate optical-grade PMMA for head-up displays. Mitsubishi Chemical anchors Asia-Pacific supply through integrated MMA-to-PMMA production in Japan and Thailand. Sabic competes on scale, sustaining bulk extruded sheet output for Middle Eastern construction markets.
Synthetic and bio-based PMMA denotes thermoplastic polymers of methyl methacrylate, available in amorphous form with light transmission exceeding 92% and density near 1.18 g/cm³, serving as shatter-resistant alternatives to glass across optical, architectural, and medical applications. Cast sheets retain premium positioning in museum display and aircraft cabin windows where optical clarity commands margin pools, while extruded grades occupy volume-led signage and lighting diffuser segments. Biopolymer-based technology remains nascent but captures sustainability premiums in European healthcare prosthetics where REACH compliance constrains petrochemical sourcing.
EMA medical device regulations and EU REACH chemical registration frameworks elevate purity standards for healthcare-grade PMMA, while EPA and OSHA guidelines govern MMA monomer emissions at US production sites. FDA 21 CFR compliance separates implantable dental and bone cement applications from commodity grades, creating tiered market access barriers. Stakeholders must monitor bio-based feedstock certification schemes and polymer recycling infrastructure buildout as determinants of long-term feedstock positioning.
Market Dynamics
Automotive electrification is decoupling glazing material selection from legacy glass supply chains, forcing polymer suppliers to recalibrate optical-grade specifications against weight-reduction mandates.
Growth Catalysts
- EU F-Gas Regulation:Carbon footprint disclosure requirements for petrochemical-derived polymers are accelerating bio-based feedstock qualification programs among European compounders.
- Head-up display integration:Optical-grade PMMA sheets with haze below 1% are displacing polycarbonate in premium electric vehicle instrument clusters.
- German chemical clustering:Rhine-Ruhr and Ludwigshafen production hubs concentrate specialty methacrylate expertise, reducing qualification timelines for medical device grades.
Market Restraints
- MMA monomer volatility:Acetone cyanohydrin route feedstock costs fluctuate with propylene and ammonia pricing, compressing margin stability for non-integrated producers.
- REACH registration burden:ECHA substance evaluation timelines for new bio-based monomers extend commercialization cycles by 18-36 months versus petrochemical equivalents.
- Polycarbonate substitution in thick sections:Impact-resistant applications above 6mm wall thickness favor aromatic carbonate polymers, capping PMMA penetration in heavy glazing.
Strategic Opportunities
- Thailand automotive manufacturing:Japanese OEM transplant operations are localizing optical-grade sheet specification to ASEAN supply bases.
- Chemical recycling infrastructure:Pyrolysis-based MMA recovery from end-of-life acrylic is creating circular feedstock pools for ESG-compliant product lines.
- ISO 13485 certification expansion:Medical device quality management adoption in Eastern European contract manufacturers is opening healthcare-grade supply relationships.
Industry Challenges
- Optical metrology talent scarcity:Interferometry and spectrophotometry expertise for sub-micron thickness control commands wage premiums exceeding 40% above commodity polymer processing.
- Cleanroom retrofit capex:FDA 21 CFR Part 820 compliance for implantable dental applications requires Class 7 environment investments exceeding $15 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market |
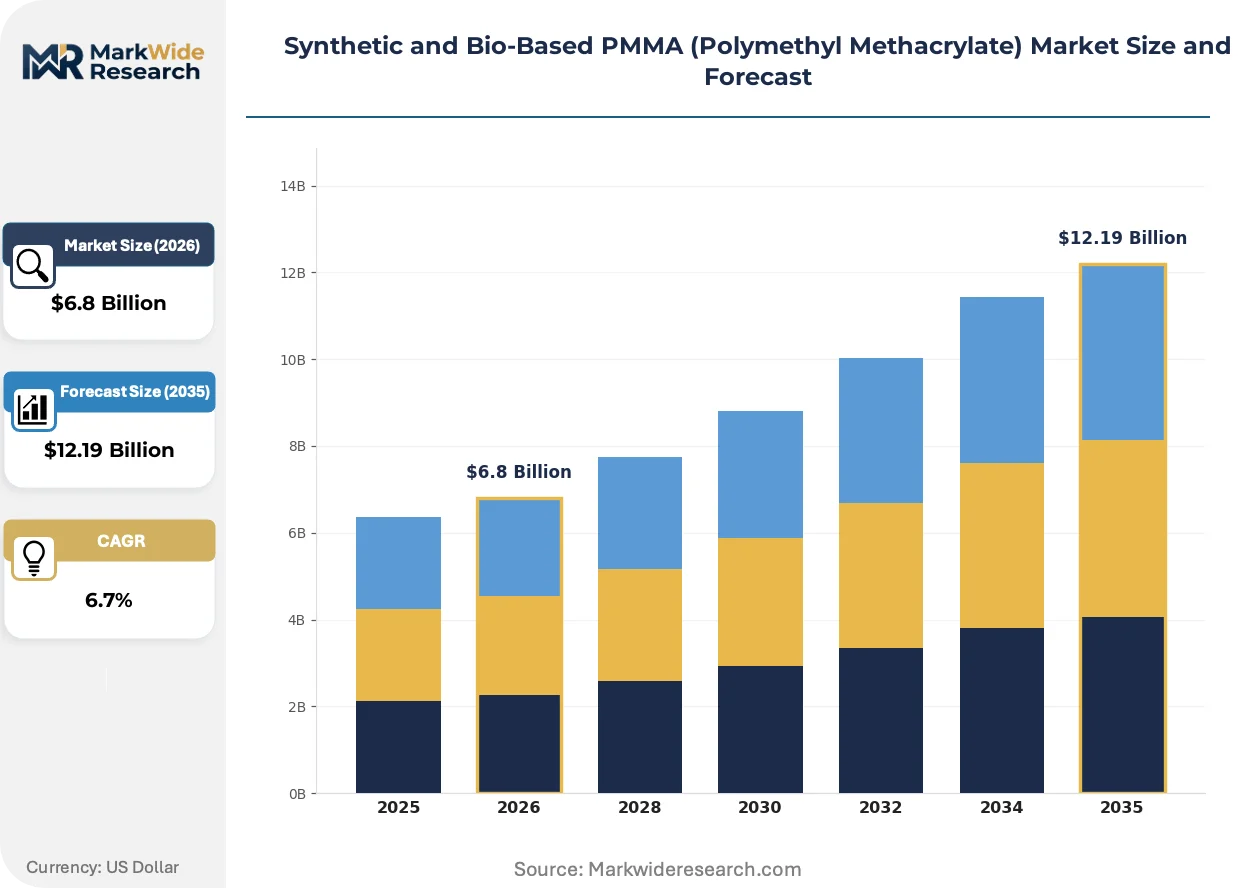
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extruded, Cast, Molding, Sheets End User: Automotive, Electronics, Construction, Healthcare Application: Signage, Display, Lighting, Prosthetics Technology: Conventional, Biopolymer-Based, Nano-composite, Hybrid |
| Companies Covered | Altuglas International, Asahi Kasei Corp., Evonik Industries, Sabic, Sumitomo Chemical Co., Ltd, Arkema SA, Kuraray Group, LG MMA Corp., Mitsubishi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market Emerging Trajectories
Material science convergence with digital manufacturing is collapsing traditional boundaries between commodity extrusion and precision optical fabrication.
Continuous cast sheet technology is consolidating position in museum and aircraft cabin applications where wavefront distortion below 50 nanometers commands specification lock-in. Curators at Frankfurt's Städel Museum and procurement teams at Airbus Hamburg are specifying cast grades exclusively for display cases and passenger windows. This consolidation is compressing extruded sheet margins in adjacent segments as optical performance becomes the non-negotiable qualifier.
EMA's Medical Device Regulation implementation is forcing healthcare-grade producers to maintain dual REACH and MDR technical documentation systems. The industrial consequence is a bifurcation between implantable dental cement suppliers and commodity dental prosthetics molders. German and Swiss manufacturers are absorbing compliance costs through dedicated medical business units, while Italian and Spanish compounders are exiting implantable grades entirely.
Specification authority is migrating from brand owners to tier-one automotive glazing integrators. Saint-Gobain Sekurit and Webasto are consolidating PMMA purchasing decisions previously fragmented across OEM engineering departments. This concentration is visible most acutely in Stuttgart and Munich, where Mercedes-Benz and BMW procurement teams have delegated optical polymer selection to windshield subsystem suppliers under total-cost-of-ownership contracts.
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market Segmentation
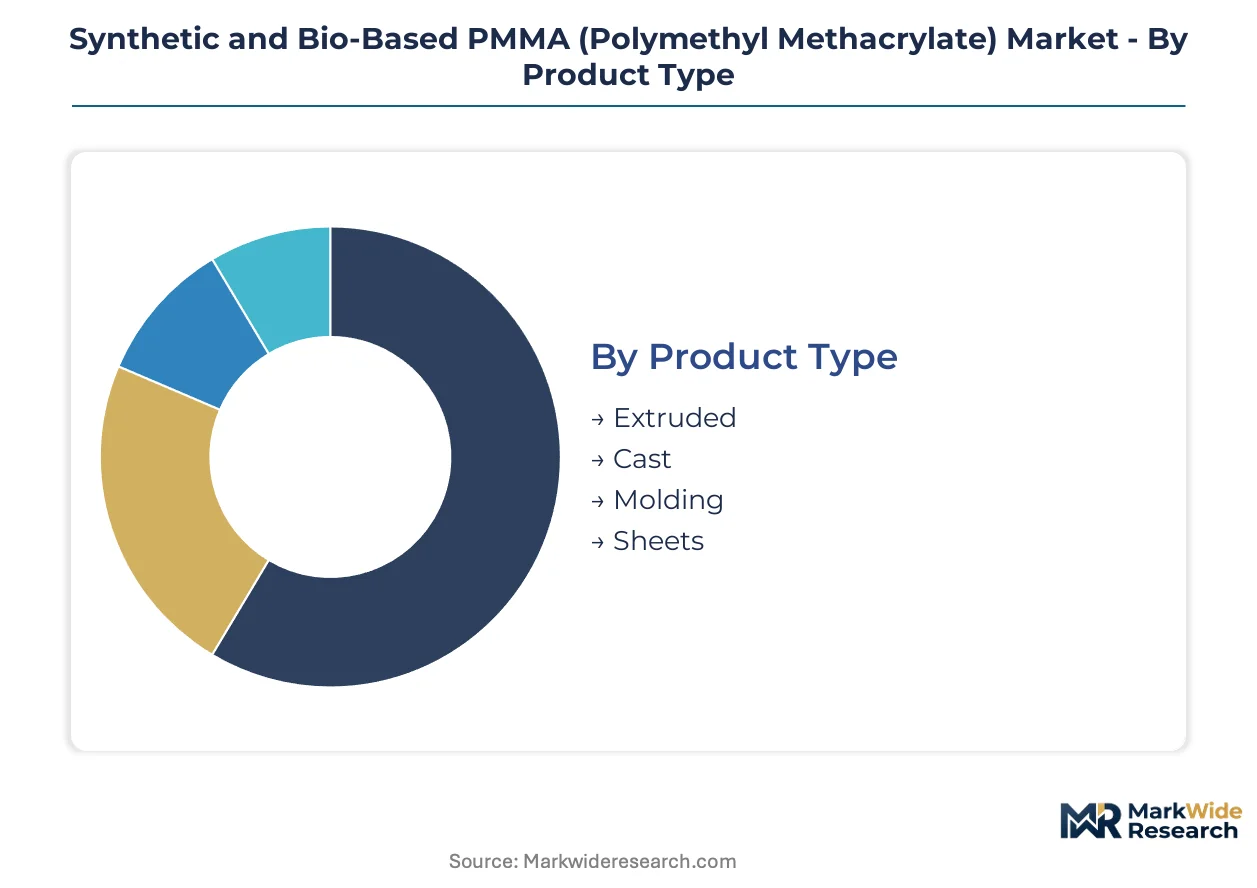
PMMA procurement decisions diverge sharply across processing routes and purity grades. End-use specifications for automotive head-up displays impose optical tolerances incompatible with commodity signage requirements, fragmenting supplier qualification pathways.
Product Type:
Upgrade cycles in optical applications are compressing extruded sheet margins while cast and molding grades capture specification premiums.
- Extruded:Continuous production delivers dimensional uniformity for volume lighting diffusers and retail signage. German compounders dominate European supply, though Thai producers are qualifying for Japanese automotive transplant programs.
- Cast:Batch-processed sheets achieve wavefront distortion below 50 nanometers, satisfying Airbus Hamburg cabin window specifications and Frankfurt museum display case requirements. Cell-cast technology commands margin pools inaccessible to extrusion competitors.
- Molding:Pellet grades serve precision optical components and dental prosthetics where melt-flow consistency determines molded part clarity.
- Sheets:Standardized dimensions for construction glazing and protective barriers, with thickness stratification separating architectural from industrial applications.
Cast sits at the top of the volume ranking, with molding climbing the fastest on medical device qualification timelines.
End User:
Cost tier stratification separates implantable dental applications from commodity construction glazing.
- Automotive:Electric vehicle OEMs in Stuttgart and Munich specify optical-grade PMMA for head-up displays under delegated procurement to Saint-Gobain Sekurit and Webasto. Weight reduction mandates displace conventional glass in windshield subsystems.
- Healthcare:EMA MDR compliance bifurcates implantable dental cement from commodity prosthetics. German and Swiss manufacturers absorb documentation costs through dedicated medical units; Italian compounders exit implantable grades entirely.
- Electronics:Display substrates and light-guide plates demand haze values below 1%, concentrating supply among Japanese and German specialty producers.
- Construction:Bulk extruded sheet for Middle Eastern façade applications competes on scale, with Sabic sustaining volume leadership through integrated petrochemical feedstocks.
Construction maintains volume leadership, though healthcare expands most quickly on regulatory-driven purity premiums.
Application:
Customer type fragmentation separates curator-specified museum display from mass-market signage procurement.
- Signage:Volume-led outdoor advertising and retail branding consumes extruded grades where weathering resistance determines replacement cycles.
- Display:Museum cases and aircraft cabin windows specify cast-grade optical clarity, with Frankfurt's Städel Museum and Airbus Hamburg procurement teams locking in cell-cast suppliers.
- Lighting:LED diffuser panels require controlled light transmission and UV stability, with extruded sheet dominating retrofit installations.
- Prosthetics:Bio-based PMMA captures sustainability premiums in European healthcare where REACH compliance constrains petrochemical sourcing for bone cements.
Signage holds the largest installed base, with prosthetics gaining share fastest on bio-based feedstock qualification.
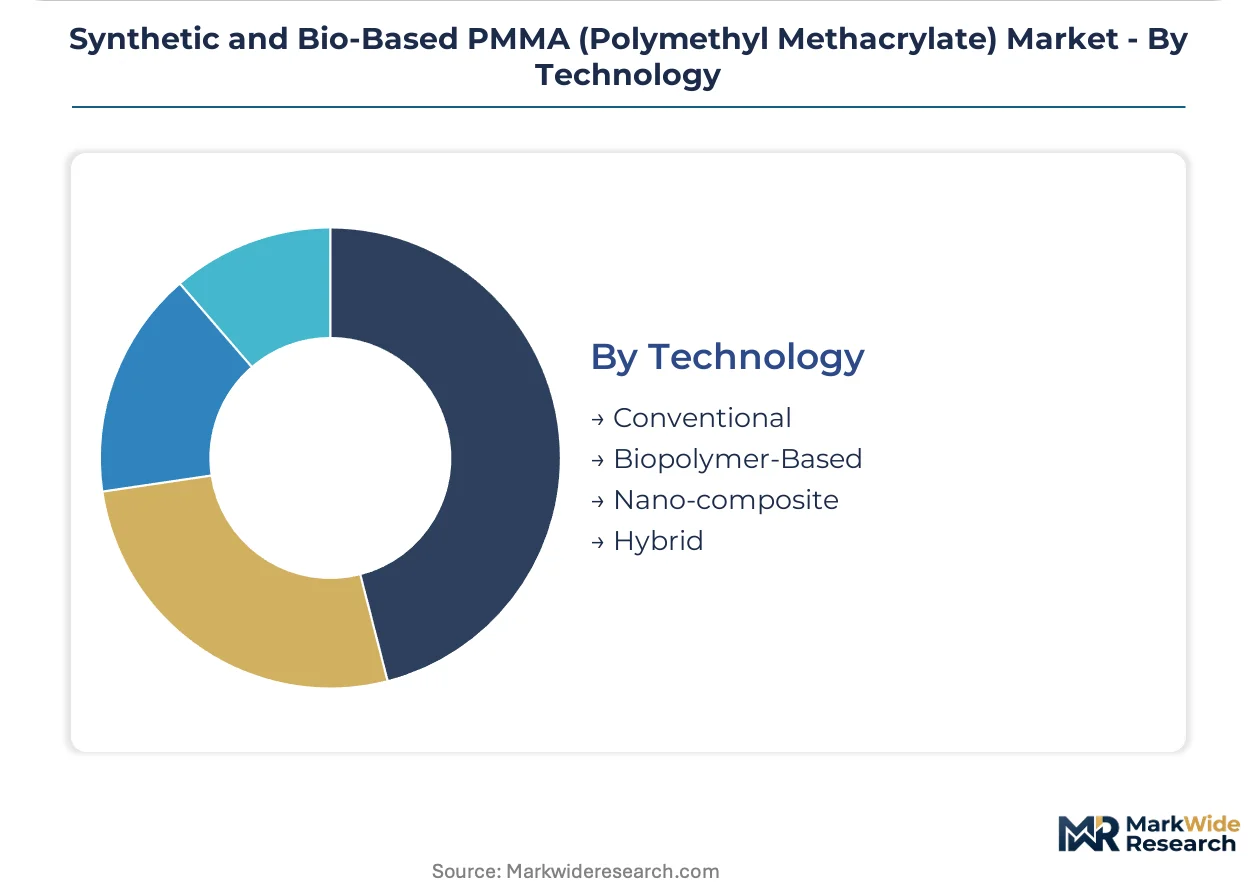
Technology:
Supply concentration in German chemical clusters shapes technology adoption timelines for medical and automotive grades.
- Conventional:Acetone cyanohydrin-derived MMA dominates volume production, with propylene and ammonia feedstock costs compressing margin stability for non-integrated compounders.
- Biopolymer-Based:ECHA registration timelines extend commercialization cycles by 18-36 months versus petrochemical equivalents, though EU F-Gas Regulation accelerates feedstock qualification programs.
- Nano-composite:Reinforced grades for impact-resistant glazing compete with polycarbonate in thin-wall applications below 6mm thickness.
- Hybrid:Blended bio-petrochemical formulations balance performance and sustainability credentials for premium packaging and consumer goods.
Conventional technology retains volume dominance, while biopolymer-based approaches show the steepest expansion trajectory on regulatory carbon disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rhine-Ruhr chemical clustering anchors European specialty methacrylate production, while Japanese and Thai integrated sites supply Asia-Pacific automotive glazing. German regulatory frameworks and Japanese OEM supply chains shape qualification timelines across both regions.
Germany
Head-up display integration drives optical-grade PMMA consumption among Stuttgart and Munich electric vehicle manufacturers. EU F-Gas Regulation carbon disclosure requirements accelerate bio-based feedstock qualification programs at Ludwigshafen and Marl production sites. BASF and Evonik anchor specialty chemical expertise in Rhine-Ruhr and Ludwigshafen hubs.
Japan
Mitsubishi Chemical's integrated MMA-to-PMMA production serves domestic electronics and display substrate demand. METI industrial standards govern optical-grade specifications for automotive and healthcare applications. Nagoya and Yokkaichi chemical complexes concentrate precision polymer compounding capabilities.
Thailand
Japanese OEM transplant operations localize optical-grade sheet procurement for ASEAN automotive manufacturing. Board of Investment incentives support petrochemical downstream expansion at Map Ta Phut and Rayong industrial zones. Thai producers qualify for Japanese parent company supply chain integration.
United States
FDA 21 CFR compliance separates implantable dental applications from commodity PMMA grades, creating tiered market access. EPA and OSHA guidelines govern MMA monomer emissions at Texas and Louisiana production sites. Gulf Coast petrochemical infrastructure supports bulk extruded sheet output for construction and signage.
Saudi Arabia
Sabic leverages integrated petrochemical feedstocks to sustain volume leadership in Middle Eastern construction glazing. Saudi Vision 2030 industrial diversification programs encourage specialty chemical downstream investment. Yanbu and Jubail industrial cities concentrate methacrylate production scale for regional export.
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market Vendor Landscape
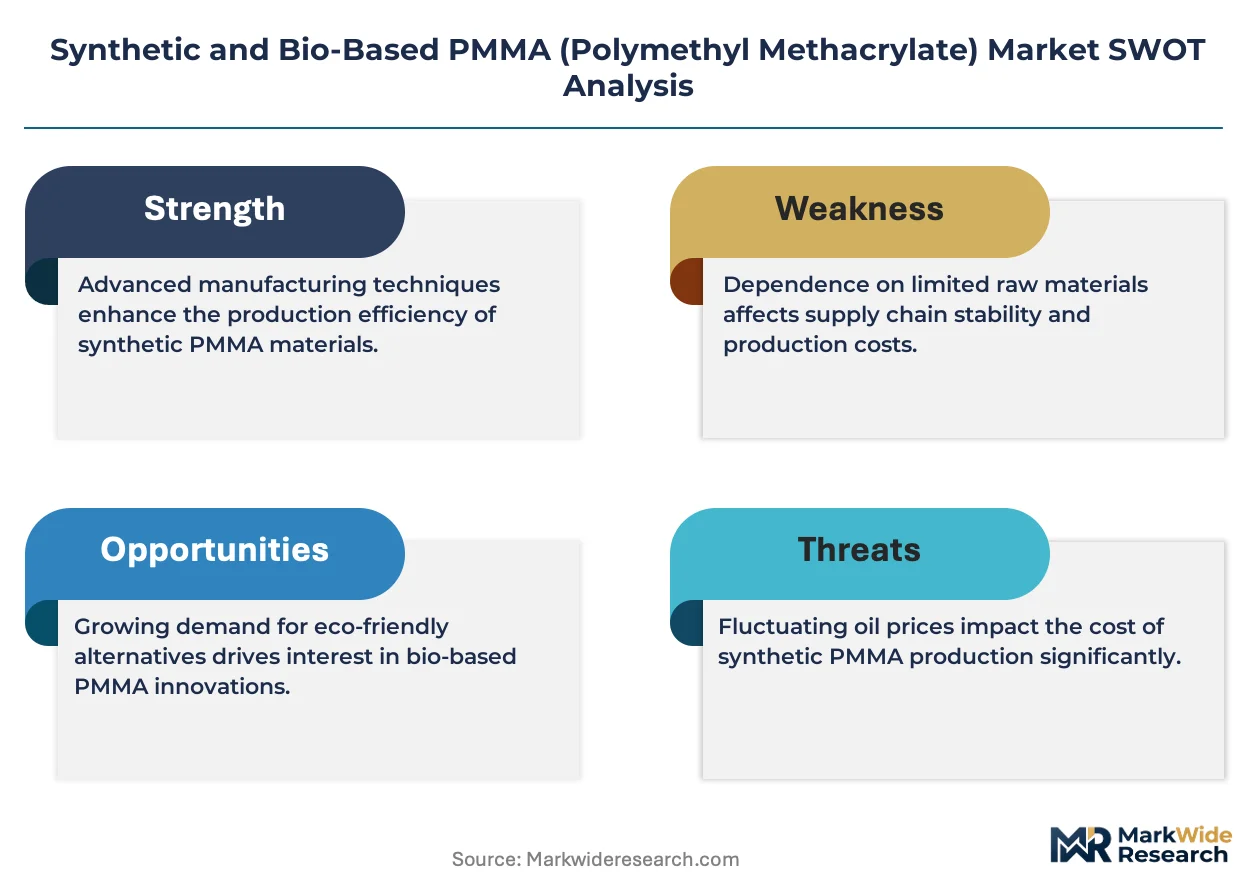
Capacity expansion dominates the current landscape as integrated producers extend MMA-to-PMMA value chain control. The market structures around three tiers: petrochemical majors with captive monomer supply, specialty chemical houses with optical-grade certification, and regional compounders serving construction and signage volume. Strategic archetypes separate integrated feedstock players from medical-grade specialists and extruded sheet commodity producers. M&A activity and backward integration into methacrylate monomer production represent the dominant competitive moves.
Among German specialty chemical producers, Evonik Industries and Arkema SA exemplify the optical-grade certification tier, while Mitsubishi Chemical anchors the Asia-Pacific integrated production archetype. These three occupy positions defined by regulatory qualification depth and geographic supply chain configuration rather than scale alone.
| Leading Market Players |
|---|
| Altuglas International |
| Asahi Kasei Corp. |
| Evonik Industries |
| Sabic |
| Sumitomo Chemical Co., Ltd |
| Arkema SA |
| Kuraray Group |
| LG MMA Corp. |
| Mitsubishi Chemical |
| Others |
Supply Flow & Price Mechanics
Captive MMA-to-PMMA integration anchors both supply security and margin control for European and Asian producers, insulating optical-grade specialists from acetone cyanohydrin feedstock volatility while compressing pricing power for non-integrated compounders dependent on spot monomer markets.
Pricing Analysis
Acetone cyanohydrin feedstock costs transmit directly into MMA monomer pricing, creating margin compression for non-integrated compounders when propylene and ammonia markets tighten. Three-tier pricing structure across optical-grade, medical-grade, and commodity extruded tiers separates Saint-Gobain Sekurit-specified automotive glazing from bulk construction signage. Cost compression in extruded sheet intensifies as Thai producers qualify for Japanese OEM supply chains. Construction glazing buyers exhibit highest price sensitivity; implantable dental cement purchasers prioritize EMA MDR compliance over unit economics.
Supply Chain Analysis
Container freight rate volatility from Asia to Europe disrupts just-in-time delivery schedules for optical-grade sheet dependent on interferometry-calibrated thickness control. Production gravity centers on Germany, Japan, and Thailand, with Mitsubishi Chemical's Yokkaichi complex and Evonik's Marl site anchoring specialty methacrylate supply. Feedstock draws from propylene crackers and ammonia synthesis units; energy costs constitute a structural vulnerability. Distribution runs through tier-one automotive glazing integrators consolidating procurement authority previously fragmented across OEM engineering departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation carbon disclosure requirements versus Gulf Coast petrochemical cost advantages create arbitrageable positioning for producers with bio-based feedstock certification and integrated European production assets.
For Market Incumbents: Acquire chemical recycling pyrolysis assets to secure circular MMA feedstock pools ahead of ESG-compliant product line mandates. Deepen backward integration into methacrylate monomer production to defend margin stability against acetone cyanohydrin route volatility. Prioritize ISO 13485 certification expansion in Eastern European contract manufacturers to capture healthcare-grade supply relationships as Italian compounders exit implantable grades.
For New Entrants and Emerging Players: Begin with bio-based PMMA qualification for European healthcare prosthetics where REACH compliance constrains petrochemical sourcing and sustainability premiums persist. Target ASEAN automotive glazing as Japanese OEM transplant operations localize optical-grade sheet procurement away from parent-company supply chains. Pursue qualification partnerships with Saint-Gobain Sekurit or Webasto to bypass fragmented OEM engineering procurement.
For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR compliance costs bifurcate implantable dental cement suppliers from commodity molders, creating distressed acquisition targets among Italian and Spanish compounders exiting medical grades. Specialty chemical houses with optical-grade certification and captive monomer supply represent the durable long-term archetype. Monitor ECHA substance evaluation timelines for bio-based monomers as inflection indicator for feedstock transition velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Monomer | Captive acetone cyanohydrin supply insulates Evonik and Mitsubishi Chemical from propylene volatility. |
| Chemical Recycling Infrastructure Buildout | Pyrolysis-based MMA recovery creates circular feedstock pools qualifying for EU Green Deal compliance. |
| ISO 13485 Certification Expansion | Eastern European contract manufacturers unlock healthcare-grade supply relationships with German device OEMs. |
| Automotive Glazing Integrator Partnership | Saint-Gobain Sekurit consolidation delegates procurement authority away from fragmented OEM engineering. |
| Bio-Based Feedstock Qualification | ECHA-registered biopolmer routes capture sustainability premiums in REACH-constrained European healthcare. |
Methodological Framework
Bottom-up automotive and healthcare end-use modeling reconciled against top-down methacrylate monomer capacity tracking forms the analytical core of this study. Primary interviews with optical-grade sheet procurement managers at tier-one glazing integrators, plant managers at Ludwigshafen and Marl chemical complexes, and regulatory affairs leads navigating EMA MDR compliance were validated against secondary sources including ECHA substance registration databases, EU F-Gas Regulation implementation guidance, and SEC filings from disclosed PMMA producers. Customs data on MMA monomer trade flows and automotive production statistics from Stuttgart and Munich OEM clusters provided cross-reference anchors.
Historical trendline analysis across cast sheet, extruded sheet, and molding grade volume trajectories established baseline growth patterns extrapolated across the projection horizon. Segmentation dimensions modeled include processing route, purity grade tier, end-use industry, and regional production hub configuration. CAGRs were derived from elasticity-adjusted demand curves incorporating electric vehicle glazing adoption curves and medical device regulatory qualification timelines. Feedstock cost pass-through coefficients and optical metrology talent scarcity premiums informed margin compression scenarios.
Several conditions sit outside the modeled scope, including unannounced capacity additions by integrated petrochemical majors, breakthrough bio-based monomer technologies bypassing ECHA registration timelines, and polycarbonate formulation advances displacing PMMA in thick-section glazing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Plastic Resins Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Polyimides Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Silane-Modified Polymers Market