
 Global Construction Silicone Sealants Market | 2026-2036
Global Construction Silicone Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Construction Silicone Sealants Market Analysis
China is rewriting capacity dynamics in construction silicone sealants as domestic producers expand polymerization and compounding operations to serve Asia-Pacific infrastructure build-outs. Dow leverages backward integration into siloxane feedstocks to secure cost positions across acetic and neutral cure grades. Wacker Chemie AG anchors European supply through its Burghausen manufacturing complex, while Sika AG competes via construction chemical distribution networks that bundle sealants with waterproofing membranes.
Construction silicone sealants are elastomeric compounds based on polydimethylsiloxane polymers that cure through moisture-induced crosslinking to form flexible, weather-resistant joints with movement accommodation exceeding 25 percent. Their primary purpose is to seal building envelopes against air and water infiltration while accommodating thermal expansion and structural settling. Neutral cure silicone dominates facade and structural glazing applications where acetic acid byproducts would corrode metals or stain stone substrates. Specialty silicone formulations command margin premiums in high-rise projects requiring fire-rated or ultra-low-modulus performance, while alcohol-rooted silicones are gaining share in sensitive interior environments.
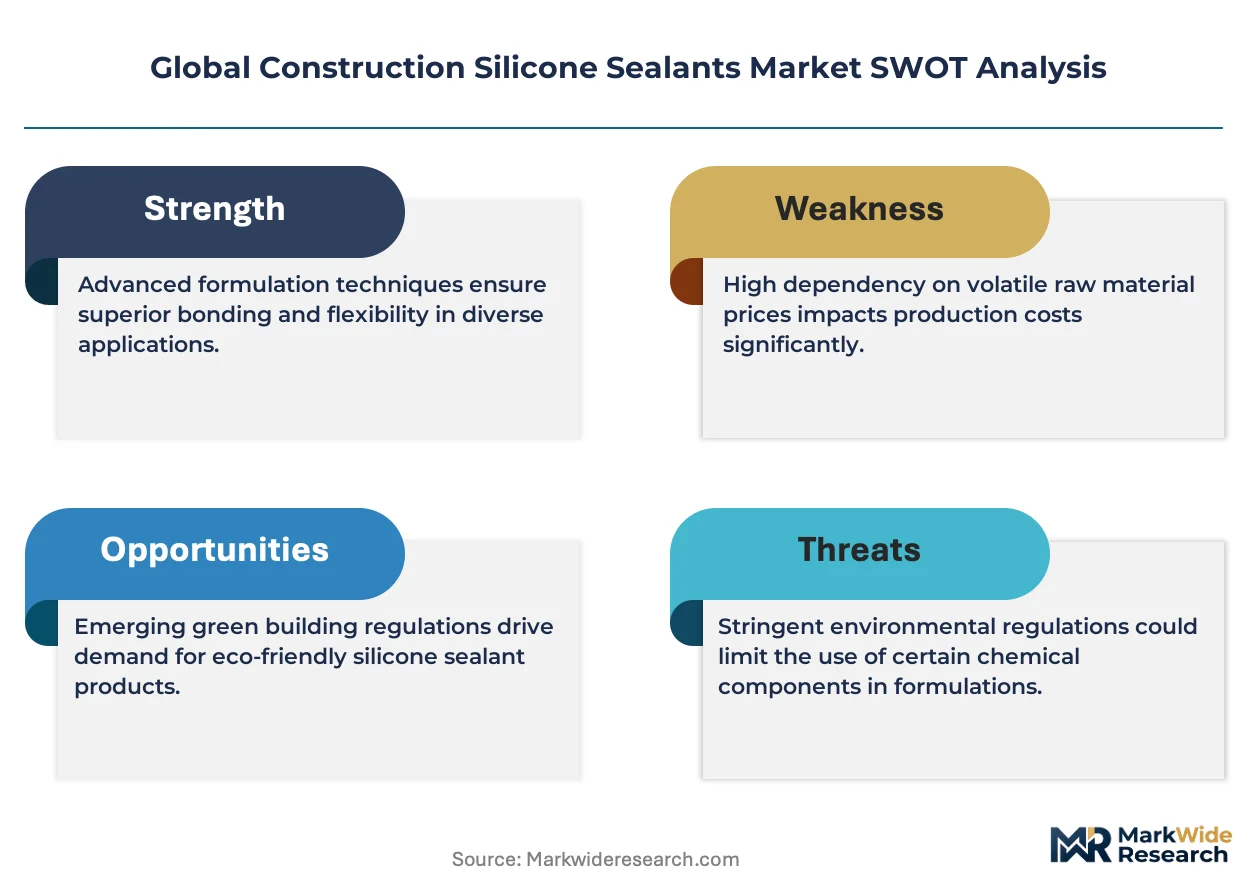
REACH restricts certain tin catalysts used in condensation-cure silicones, compelling European formulators to certify alternative tin-free systems under ECHA guidance. China's GB standards and MEE environmental inspections enforce VOC content ceilings that filter out non-compliant imports and smaller domestic blenders. The US EPA and state-level air quality districts impose overlapping limits on solvent emissions during sealant application, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must track regulatory divergence between low-VOC mandates in Europe, GB standard harmonization in China, and emerging state-level rules in the US to anticipate which chemistries will retain market access across major demand centers.
Market Dynamics
EU Green Deal embodied carbon mandates are forcing wholesale reformulation of silicone sealant chemistries, compressing margins for producers reliant on legacy tin-catalyzed systems while advantaging early movers into tin-free architectures.
Growth Catalysts
- High-rise glazing specification:Architects in the United Arab Emirates are specifying premium neutral-cure silicones for Dubai and Abu Dhabi mega-projects, absorbing volumes that defy regional construction cycles.
- REACH tin catalyst restrictions:ECHA guidance on alternative certification pathways is accelerating tin-free system adoption across European facade applications where metal corrosion resistance is non-negotiable.
- GB standard harmonization:China's MEE environmental inspections and VOC content ceilings are filtering non-compliant imports, consolidating domestic supply for Asia-Pacific infrastructure build-outs.
Market Restraints
- Siloxane feedstock concentration:Backward integration into siloxane monomers remains limited to a handful of chemical conglomerates, exposing independent formulators to raw material volatility.
- Acetic acid corrosion legacy:Acetoxy-cure silicones retain cost advantages in interior markets but face structural displacement wherever metal substrates or natural stone appear.
- US regulatory fragmentation:Overlapping EPA federal limits and state-level air quality district rules create compliance complexity that favors large suppliers with dedicated regulatory affairs infrastructure.
Strategic Opportunities
- Fire-rated specialty formulations:Ultra-low-modulus and intumescent silicones for high-rise structural glazing command margin premiums where standard grades fail certification thresholds.
- Alcohol-cure interior penetration:Oxime and alkoxy-cure systems are displacing acetoxy grades in healthcare and hospitality environments where odor and substrate sensitivity matter.
- Bundled construction chemical distribution:Waterproofing membrane and sealant combination sales through integrated distribution networks capture specification influence earlier in project timelines.
Industry Challenges
- Tin-free catalyst formulation expertise:The shift away from dibutyltin dilaurate systems requires polymer scientists with scarce crosslinking chemistry experience, constraining European and Asian formulator expansion.
- Multi-jurisdiction certification timelines:Simultaneous ECHA REACH dossier preparation, Chinese GB testing, and US EPA state-level registrations extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Construction Silicone Sealants Market |
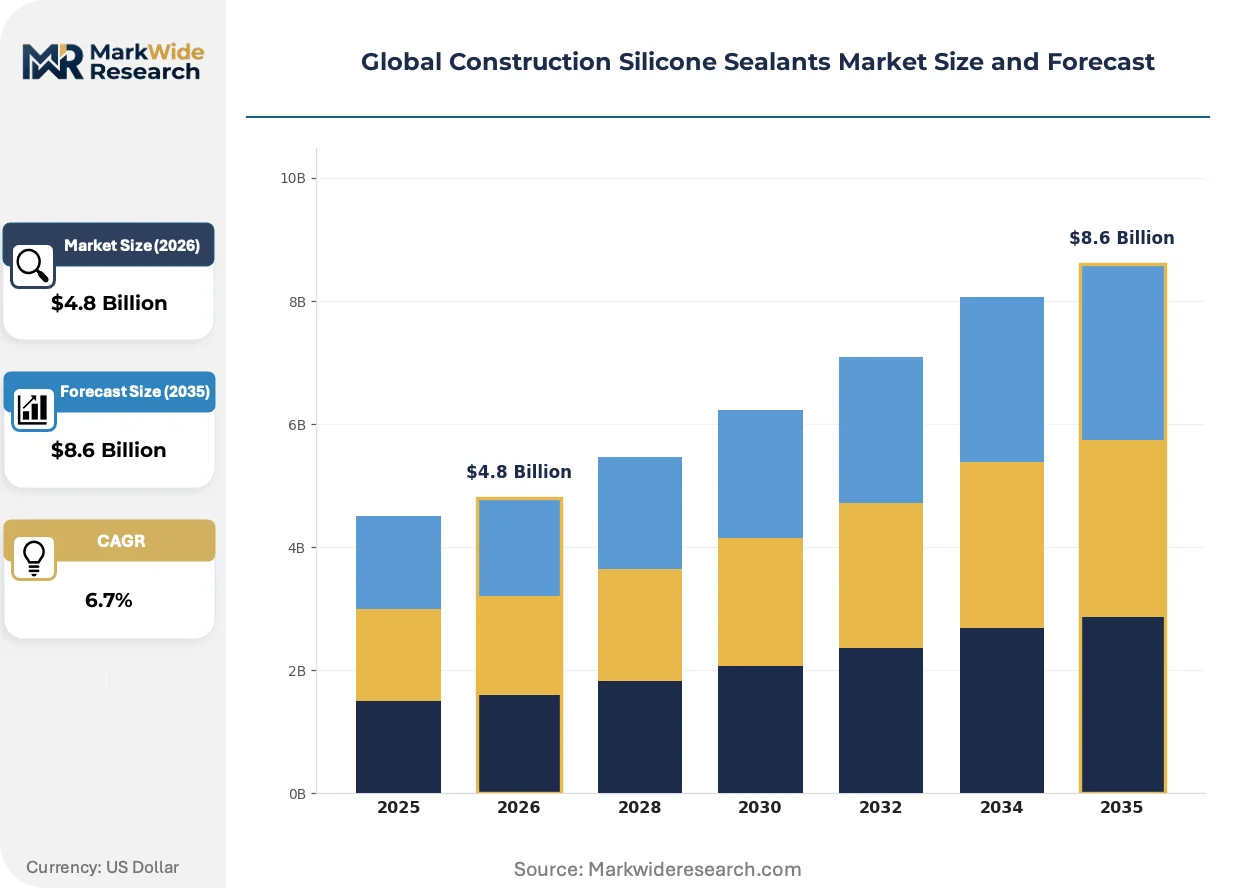
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetic Silicone, Alcohol-Rooted Silicone, Neutral Cure Silicone, Specialty Silicone Application: Windows, Doors, Facades, Flooring End User: Residential, Commercial, Industrial, Infrastructure Distribution Channel: Online Retail, Direct Sales, Wholesale, Distributors |
| Companies Covered | Shin-Etsu Chemical Company, Bostik, Dow, Henkel Corporation, Tremco Incorporated, Sika AG, 3M, H.B. Fuller, Wacker Chemie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Construction Silicone Sealants Market Emerging Trajectories
Moisture-cure silicone chemistry is undergoing accelerated evolution as regulatory pressure intersects with performance demands from ever-taller building envelopes and sensitive interior environments.
Two-part silicone systems are collapsing the installation timeline for structural glazing projects. Curtain wall contractors in the UAE and Singapore are adopting these materials for high-rise towers where single-component cure times would stall critical path schedules. The technology is collapsing the traditional trade-off between factory-controlled curing speed and field-applied convenience.
REACH authorization requirements for certain organotin compounds are forcing European formulators to validate alternative condensation catalysts by 2025. ECHA's sunset date enforcement is accelerating R&D spending on bismuth, zirconium, and titanium-based systems. Facade specialists with metal or stone substrates are absorbing modest price premiums for certified tin-free grades to preempt liability exposure.
Specification authority is migrating from general contractors to facade consultants and envelope engineers who control weatherproofing system selection. These technical buyers prioritize movement accommodation data and 25-year durability warranties over unit cost, compressing price competition among undifferentiated commodity grades. The shift is most visible in German and Swiss commercial construction where envelope performance guarantees are standard contract terms.
Global Construction Silicone Sealants Market Segmentation
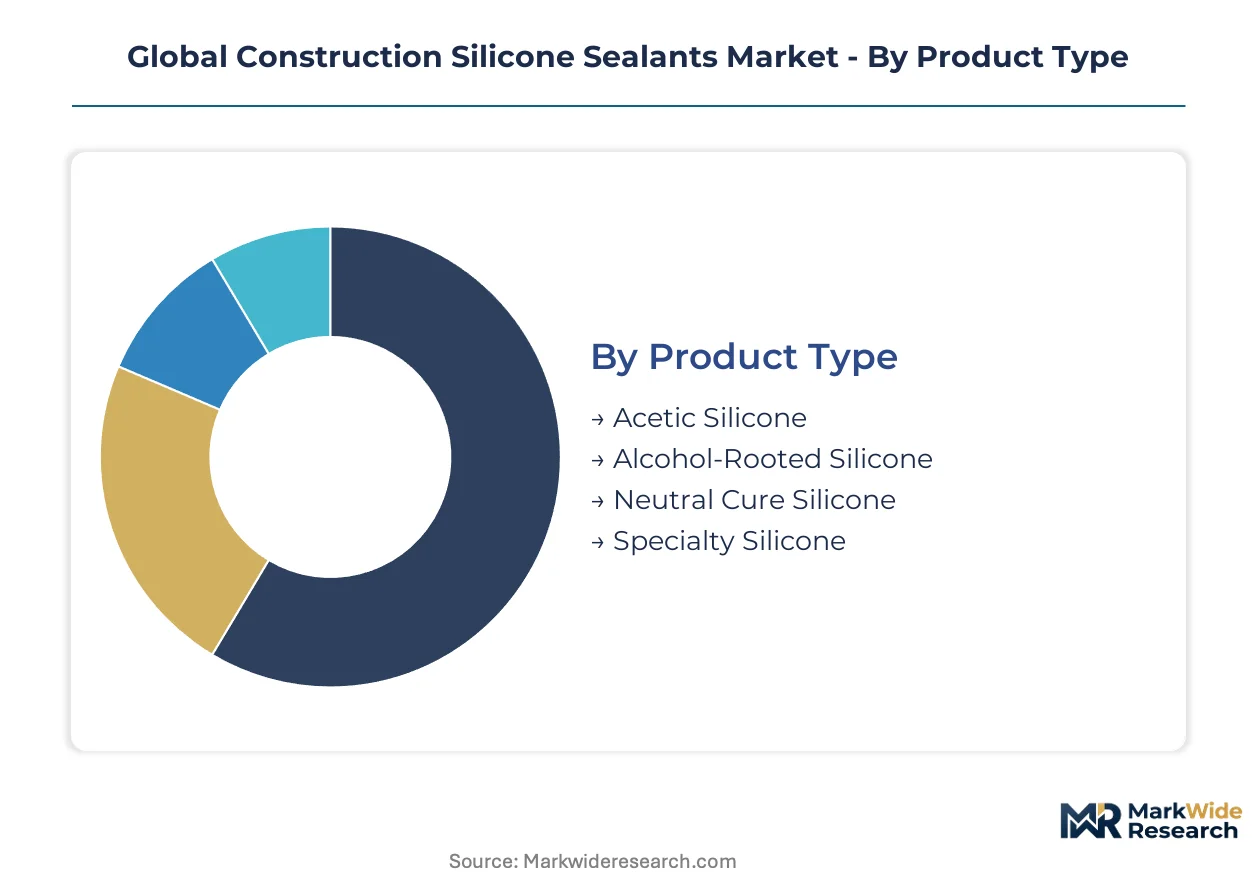
Construction silicone sealants fragment across multiple technical and commercial dimensions that determine specification authority, margin structure, and channel economics. Understanding these splits reveals where formulators capture premium pricing versus where volume commoditization dominates procurement decisions.
Product Type:
After-sales service intensity varies sharply by cure chemistry, with neutral-cure and specialty grades demanding facade consultant support and warranty-backed performance validation that acetic grades rarely require.
- Acetic Silicone:Releases acetic acid during moisture cure, producing the distinctive vinegar odor that signals complete crosslinking. These formulations retain cost advantages in interior residential applications across India and Southeast Asia where metal corrosion and substrate staining present minimal risk. By volume, acetic silicone leads. By growth pace, neutral cure is ahead.
- Neutral Cure Silicone:Crosslinks through alkoxy condensation without corrosive byproducts, making these grades mandatory for aluminum curtain walls, structural glazing, and natural stone facades. Demand concentrates in the United Arab Emirates and Saudi Arabia where mega-projects specify certified metal-compatible sealants for high-rise envelopes.
- Alcohol-Rooted Silicone:Oxime and alkoxy-cure systems release neutral alcohols rather than acids, penetrating healthcare and hospitality interiors where odor sensitivity and patient safety override material cost considerations.
- Specialty Silicone:Fire-rated intumescent and ultra-low-modulus formulations command specification in high-rise structural glazing where standard grades fail movement accommodation or fire resistance thresholds.
Neutral cure dominates facade specification while specialty grades capture the steepest margin expansion as building heights and code complexity escalate.
Application:
Application segments diverge by installation complexity, with facade and structural glazing requiring engineered joint design and third-party certification that window and door sealing rarely demands.
- Facades:Curtain wall and structural glazing joints must accommodate thermal expansion, wind load deflection, and inter-story drift while maintaining air and water tightness across 25-year design lives. Specification authority rests with envelope engineers in Germany and Switzerland who mandate certified movement accommodation data.
- Windows:Perimeter sealing of frame-to-wall interfaces represents high-volume, lower-specification work where contractor familiarity and unit cost drive selection across residential and light commercial construction.
- Doors:Threshold and frame sealing applications prioritize rapid skin-over times and paint compatibility, favoring acetic-cure grades in cost-sensitive markets.
- Flooring:Expansion joint sealing in commercial and industrial slabs requires abrasion resistance and chemical compatibility that modified silicone and hybrid formulations increasingly address.
Facade applications absorb the highest per-project sealant volumes while window replacement cycles generate the most recurring demand.
End User:
End-user segments separate by procurement sophistication, with commercial and infrastructure buyers employing technical specifications that residential contractors rarely deploy.
- Commercial:Office towers, retail centers, and hospitality projects specify neutral-cure and specialty grades through facade consultants who control weatherproofing system selection and warranty terms.
- Infrastructure:Airports, transit stations, and stadiums demand fire-rated and high-movement formulations with documented durability testing, extending procurement cycles but securing long-term supply agreements.
- Residential:Single-family and multi-family construction prioritizes cost and availability over technical performance, channeling volume through distributor and retail networks.
- Industrial:Manufacturing facilities and warehouses require chemical-resistant and high-temperature grades for specialized joint conditions.
Commercial projects concentrate premium-grade demand while residential construction sustains volume throughput for standard formulations.
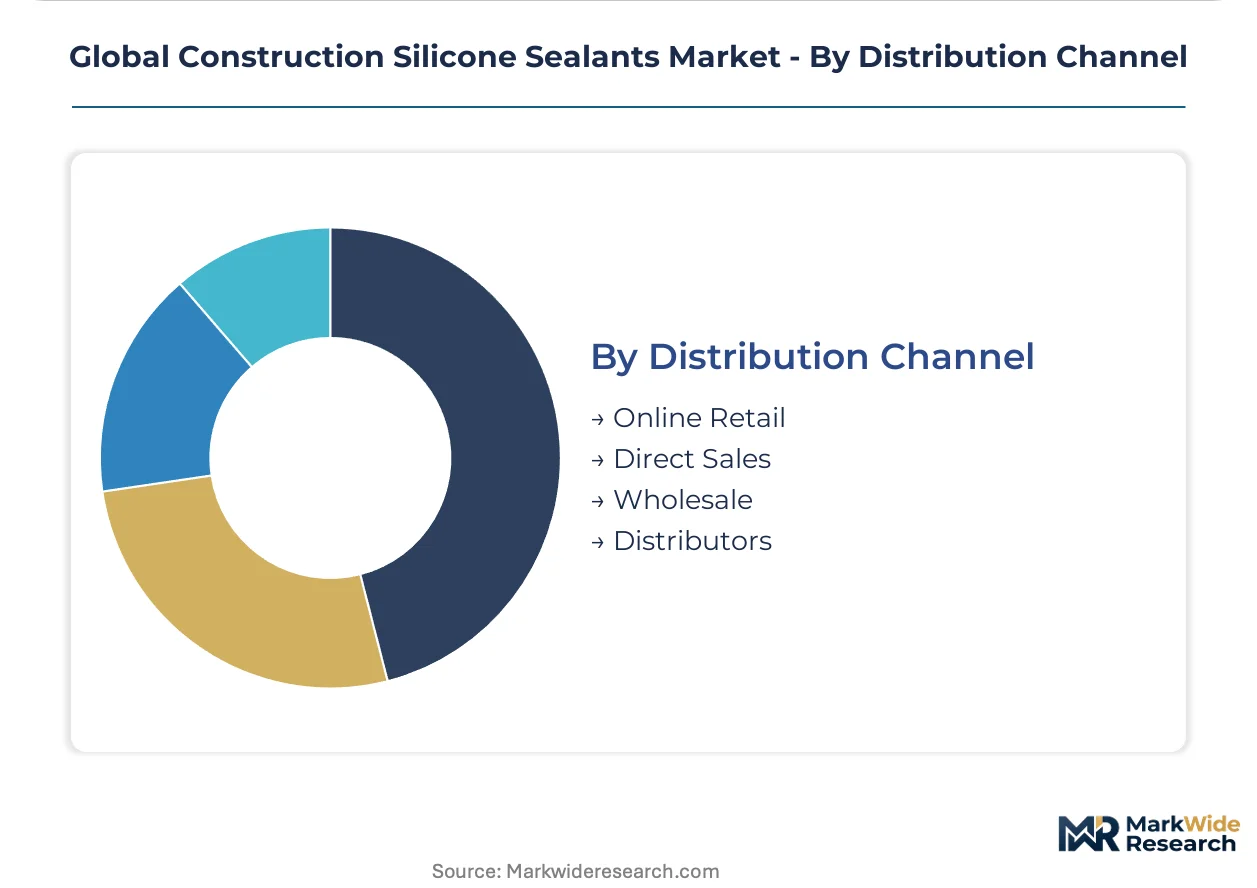
Distribution Channel:
Channel selection tracks project scale and specification timing, with direct sales capturing engineered projects early while distributors serve spot-market and replacement demand.
- Distributors:Construction chemical specialists bundle sealants with waterproofing membranes and ancillary products, capturing specification influence through integrated project support across Germany and the UAE.
- Direct Sales:Major formulators maintain technical service teams for structural glazing contractors and facade consultants requiring joint design assistance and warranty backing.
- Wholesale:Regional building material wholesalers serve mid-tier contractors with standard grades and bulk pricing.
- Online Retail:E-commerce penetration remains limited to small-project and DIY segments where technical consultation requirements are minimal.
Distributor networks dominate volume throughput while direct sales secure the highest-margin specification-driven projects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE environmental inspections and GB standards enforcement in China filter non-compliant imports while consolidating domestic supply for Asia-Pacific infrastructure build-outs. The EU Green Deal's embodied carbon mandates compress margins for legacy tin-catalyzed systems across European facade applications. Specification authority concentrates with envelope engineers in Germany and Switzerland who mandate certified movement accommodation data.
United States
High-rise glazing contractors in New York and Chicago specify premium neutral-cure silicones for curtain wall retrofits and new commercial towers. EPA federal limits and California Air Resources Board rules create overlapping compliance complexity that favors suppliers with dedicated regulatory infrastructure. The Pacific Northwest corridor absorbs volumes for mass timber construction requiring specialized joint accommodation.
Germany
Facade consultants in Munich and Frankfurt control weatherproofing system selection through envelope performance guarantees standard in commercial contracts. REACH authorization requirements for organotin compounds force formulators to validate bismuth and zirconium-based catalysts by 2025. The Burghausen manufacturing complex anchors European supply for tin-free grades penetrating metal and stone substrate applications.
China
Domestic producers expand polymerization and compounding operations to serve Yangtze River Delta infrastructure build-outs including Shanghai metro extensions and Hangzhou commercial towers. MEE environmental inspections enforce VOC content ceilings that filter out non-compliant imports and smaller domestic blenders. Pearl River Delta facade projects specify certified metal-compatible sealants for Shenzhen and Guangzhou high-rise envelopes.
United Arab Emirates
Mega-project construction in Dubai and Abu Dhabi consumes premium sealant volumes for high-rise glazing and curtain wall systems defying regional construction cycles. MOHAP pharmaceutical and building material regulations align with Gulf standardization initiatives for facade performance certification. Specification authority rests with envelope engineers on Burj Khalifa-scale towers requiring 25-year durability warranties.
India
Residential and commercial construction in Mumbai and Bangalore channels volume through distributor networks serving cost-sensitive markets where acetic-cure grades retain share. BIS standards for construction chemicals filter non-compliant imports while domestic formulators expand compounding capacity. The Delhi-NCR corridor absorbs neutral-cure volumes for airport and metro infrastructure requiring metal-compatible specifications.
Global Construction Silicone Sealants Market Vendor Landscape
Vertically integrated chemical conglomerates and construction chemical specialists split the market between captive feedstock security and distribution bundling advantages. Three archetypes dominate: siloxane-integrated producers with backward control over monomer supply, construction chemical distributors bundling sealants with waterproofing membranes, and regional formulators serving price-sensitive interior markets. Competitive moves concentrate on tin-free catalyst certification and direct technical service deployment for structural glazing contractors.
Within the siloxane-integrated tier, Dow and Wacker Chemie AG exemplify producers with captive feedstock positions spanning acetic and neutral cure grades. Sika AG occupies a position among construction chemical distributors leveraging integrated networks that bundle sealants with waterproofing systems. These three anchors represent divergent pathways to specification influence: upstream control versus channel integration versus facade consultant relationships.
| Leading Market Players |
|---|
| Shin-Etsu Chemical Company |
| Bostik |
| Dow |
| Henkel Corporation |
| Tremco Incorporated |
| Sika AG |
| 3M |
| H.B. Fuller |
| Wacker Chemie AG |
| Others |
Supply Flow & Price Mechanics
Burghausen's siloxane polymerization capacity anchors European supply for tin-free silicone sealants, translating captive feedstock control into pricing power over independent formulators dependent on spot siloxane markets. The concentration of upstream monomer production in Germany and China creates divergent cost structures that ripple through neutral-cure and specialty grade quotations.
Pricing Analysis
Price spreads between the UAE and India exceed thirty percent for identical neutral-cure formulations, reflecting freight differentials and specification complexity. Three-tier pricing structure across premium, standard, and economy levels separates certified tin-free facade grades from commodity acetic-cure interior products. Pricing pressure stems from REACH compliance costs accelerating tin-free catalyst adoption. Residential contractors in India exhibit highest price sensitivity; envelope engineers in Germany and Switzerland demonstrate lowest.
Supply Chain Analysis
Export-control regimes on organotin catalyst precursors limit cross-border flows of legacy condensation-cure systems into European markets. Supply concentrates in Germany, China, and the United States for siloxane monomer production. Raw material dependencies include methyl chloride, silicon metal, and platinum-group catalysts. Single-source vulnerability characterizes high-purity siloxane supply for structural glazing grades. Distribution runs through construction chemical specialists bundling sealants with waterproofing membranes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, GB standards, and US state-level rules fragments specification authority, creating niche opportunities for formulators with multi-jurisdiction certification capabilities.
For Market Incumbents: Insulate margin positions through captive siloxane supply and accelerated tin-free catalyst validation ahead of ECHA sunset deadlines. Backward integration into siloxane feedstocks neutralizes raw material volatility threatening independent blenders. Certification investment in bismuth and zirconium-based systems defends European facade market share against Asian imports. For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia represent the most penetrable entry point, with Indonesia and Vietnam absorbing volumes that bypass established distributor relationships in mature markets. Alcohol-cure interior applications in healthcare and hospitality offer specification pathways less dominated by incumbent technical service teams. Direct sales to facade consultants bypass bundled distribution networks controlling German and UAE project influence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with polymerization capabilities rather than pure blending operations. Five-to-ten year viability hinges on tin-free catalyst expertise scarcity constraining European and Asian expansion. Acquisition targets should demonstrate validated alternative catalyst systems and direct envelope engineer relationships. The signal to watch is ECHA authorization timeline acceleration forcing consolidation among tin-dependent formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Tin-Free Catalyst Certification | ECHA REACH authorization validates bismuth and zirconium systems for metal-substrate facade applications. |
| Backward Integration into Siloxane | Captive monomer supply secures cost positions across acetic and neutral cure grade portfolios. |
| Direct Technical Service Deployment | Facade consultant relationships capture specification authority before distributor bundling influences project timelines. |
| Fire-Rated Formulation Development | Intumescent and ultra-low-modulus grades command margin premiums in high-rise structural glazing certification. |
| Multi-Jurisdiction Registration | Simultaneous REACH, GB standard, and EPA state-level approvals compress competitor launch cycles. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical company filings, ECHA REACH dossiers, and construction chemical association reports. Interviews with polymerization plant managers, facade consultant specification writers, curtain wall contractor procurement leads, and waterproofing membrane distributors informed demand-side validation. Bottom-up project pipeline analysis across Dubai, Shanghai, and Frankfurt commercial towers triangulated against top-down siloxane consumption estimates.
Forecast inputs incorporate cure chemistry grade splits, facade versus interior application shares, and end-user procurement sophistication tiers across the projection horizon. Segmentation dimensions modeled include product type, application complexity, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves responding to embodied carbon mandates and high-rise construction intensity. Siloxane feedstock capacity additions and tin-free catalyst adoption curves serve as industry-specific forecast inputs.
Practitioners should monitor ECHA authorization timeline acceleration, MEE enforcement intensity in China, and UAE mega-project award cycles for early signals of forecast revision. Material shifts in REACH sunset date enforcement or Gulf standardization initiative alignment would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
North America Flock Adhesives Market
Adhesives & Sealants
Ethylene Butyl Acrylate Market
Adhesives & Sealants
Middle-East and Africa Electronics Adhesives Market
Adhesives & Sealants
Fuel Resistant Sealant Market
Adhesives & Sealants
Latin America Adhesives and Sealants Market
Adhesives & Sealants
North America Adhesives Market
Adhesives & Sealants
United Kingdom Sealants Market
Adhesives & Sealants
Indonesia Adhesives and Sealants Market
Adhesives & Sealants
Australia Adhesives Market
Adhesives & Sealants
Industrial Adhesives Market
Adhesives & Sealants
Hot Melt Adhesives Market
Adhesives & Sealants
Reactive Adhesives Market
Adhesives & Sealants
Marine Adhesives Market
Adhesives & Sealants
Urethane Adhesives Market
Adhesives & Sealants
South America Polyurethane (PU) Hot-Melt Adhesives Market
Adhesives & Sealants
Global Vascular Sealant Market