
 Organosilicon Polymers (Polysiloxane) Market | 2026-2036
Organosilicon Polymers (Polysiloxane) Market Size, Share, and Industry Trends Forecast 2026-2036
Organosilicon Polymers (Polysiloxane) Market Analytics
The organosilicon polymers market is pivoting on a widening gap between high-purity silicone fluids for semiconductor fabrication and commodity-grade silicone rubbers for construction sealants. Dow leverages captive siloxane production to control cost positions in medical-grade gels. Wacker Chemie AG anchors European supply through its Burghausen integrated site, sustaining specifications for automotive thermal interface materials. Shin-Etsu Chemical Co., Ltd. dominates advanced resin output for electronics packaging in Japan and Taiwan.
Organosilicon polymers, or polysiloxanes, comprise repeating silicon-oxygen backbones with organic side groups, typically methyl or phenyl substituents, yielding thermal stability from -60°C to 250°C depending on crosslink density. Manufacturers produce these materials via hydrolysis of chlorosilanes followed by polycondensation, with platinum-catalyzed hydrosilylation governing cure kinetics for most industrial grades. Silicone rubber leads product type value generation due to its penetration across automotive gasketing and healthcare tubing, while silicone fluids capture the fastest expansion from datacenter liquid cooling demand. Elastomers command the deepest margin pools within application segments, driven by long-term supply agreements with aerospace OEMs requiring flame-retardant certification.
EPA oversees volatile organic compound limits for solvent-based silicone coatings in the United States, while REACH governs siloxane D4/D5/D6 restrictions across European formulations. China's MEE enforces emission standards at organosilicon monomer plants along the Yangtze River industrial corridor. Stakeholders must monitor regulatory divergence between jurisdictions on cyclic siloxane content, as compliance investments will determine which product grades maintain cross-border market access.
Market Dynamics
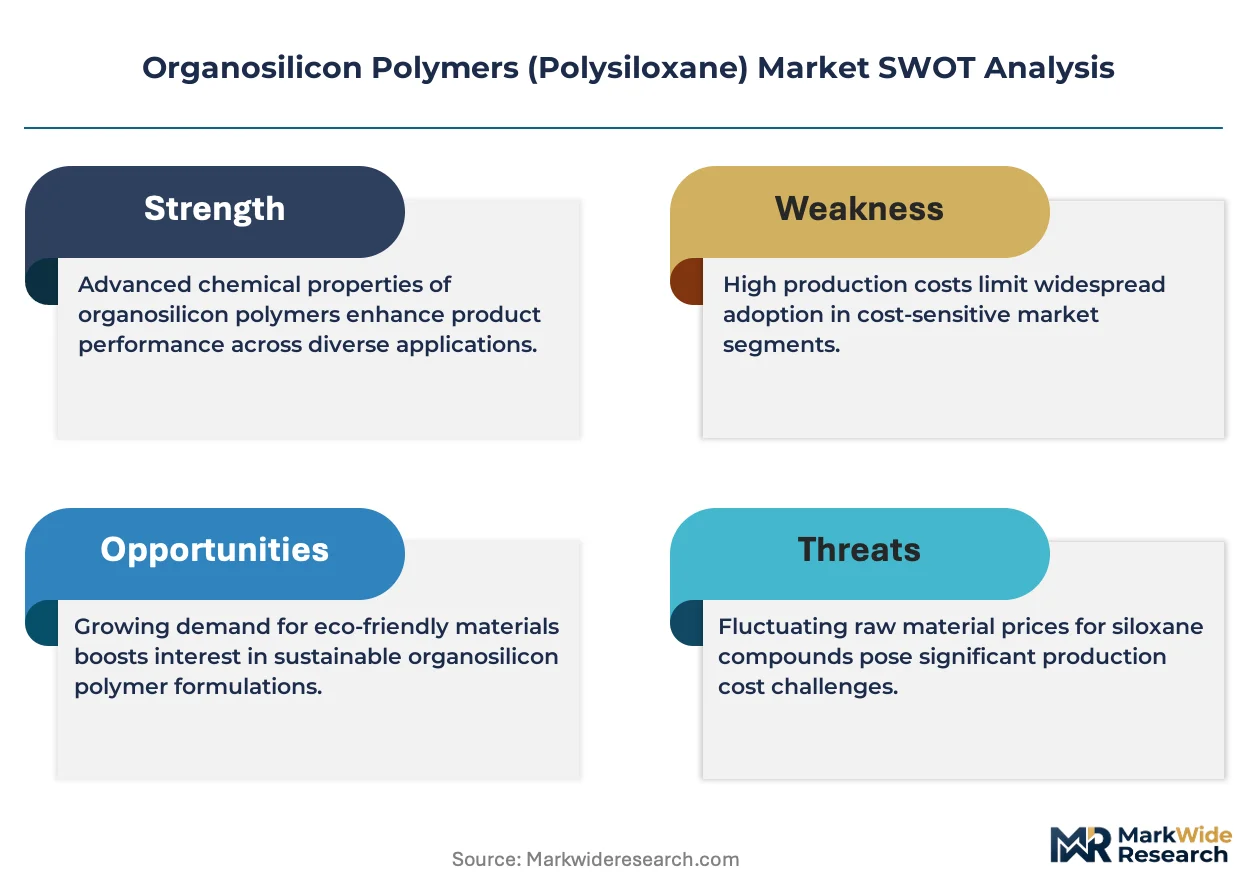
Polysiloxane producers face intensifying pressure from semiconductor-grade purity specifications colliding with construction-grade cost floors, forcing asset reconfiguration toward captive siloxane streams. The divergence between electronics thermal management demand and commodity sealant oversupply is compressing mid-tier formulation margins.
Growth Catalysts
- Datacenter liquid cooling adoption:Hyperscale operators in Singapore and Ireland are specifying low-viscosity silicone fluids for direct-to-chip thermal management, pulling high-purity volumes from traditional cosmetic applications.
- REACH D4/D5/D6 restrictions:ECHA's tightening cyclic siloxane limits in leave-on personal care products is redirecting European capacity toward industrial sealants and automotive gasketing.
- Automotive OEM localization:Guangdong-based electric vehicle manufacturers are consolidating adhesive sourcing within provincial boundaries, reducing import dependency for battery pack encapsulation grades.
Market Restraints
- Methyl chloride feedstock volatility:Siloxane monomer economics remain tethered to methanol and silicon metal pricing swings, with Chinese producers absorbing margin compression during Q4 inventory cycles.
- Burghausen-Rotterdam supply corridor concentration:European elastomer supply depends on two integrated manufacturing complexes, creating vulnerability during Rhine logistics disruptions or force majeure events.
- Fluoropolymer substitution in aerospace:FKM and FFKM materials are capturing high-temperature gasket applications above 300°C, capping silicone rubber penetration in next-generation engine architectures.
Strategic Opportunities
- Indian electronics manufacturing incentives:PLI scheme disbursements for semiconductor packaging are creating first-mover advantage for thermal interface material suppliers establishing Gujarat or Tamil Nadu compounding facilities.
- Bio-based siloxane feedstocks:Fermentation-derived silicone precursors from agricultural waste streams offer compliance pathways under EU Green Deal carbon border adjustments.
- Medical device miniaturization:Micro-molding grade liquid silicone rubber for implantable neuromodulation devices commands 40-60 point margin premiums over industrial equivalents.
Industry Challenges
- Platinum catalyst sourcing constraints:Hydrosilylation cure systems depend on South African and Russian platinum group metal supply, with fabricators facing 90-120 day procurement cycles for hydrosilylation-grade complexes.
- ISO 10993 biocompatibility certification timelines:Medical-grade gel formulations require 18-24 month cytotoxicity and sensitization testing protocols, delaying revenue recognition for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organosilicon Polymers (Polysiloxane) Market |
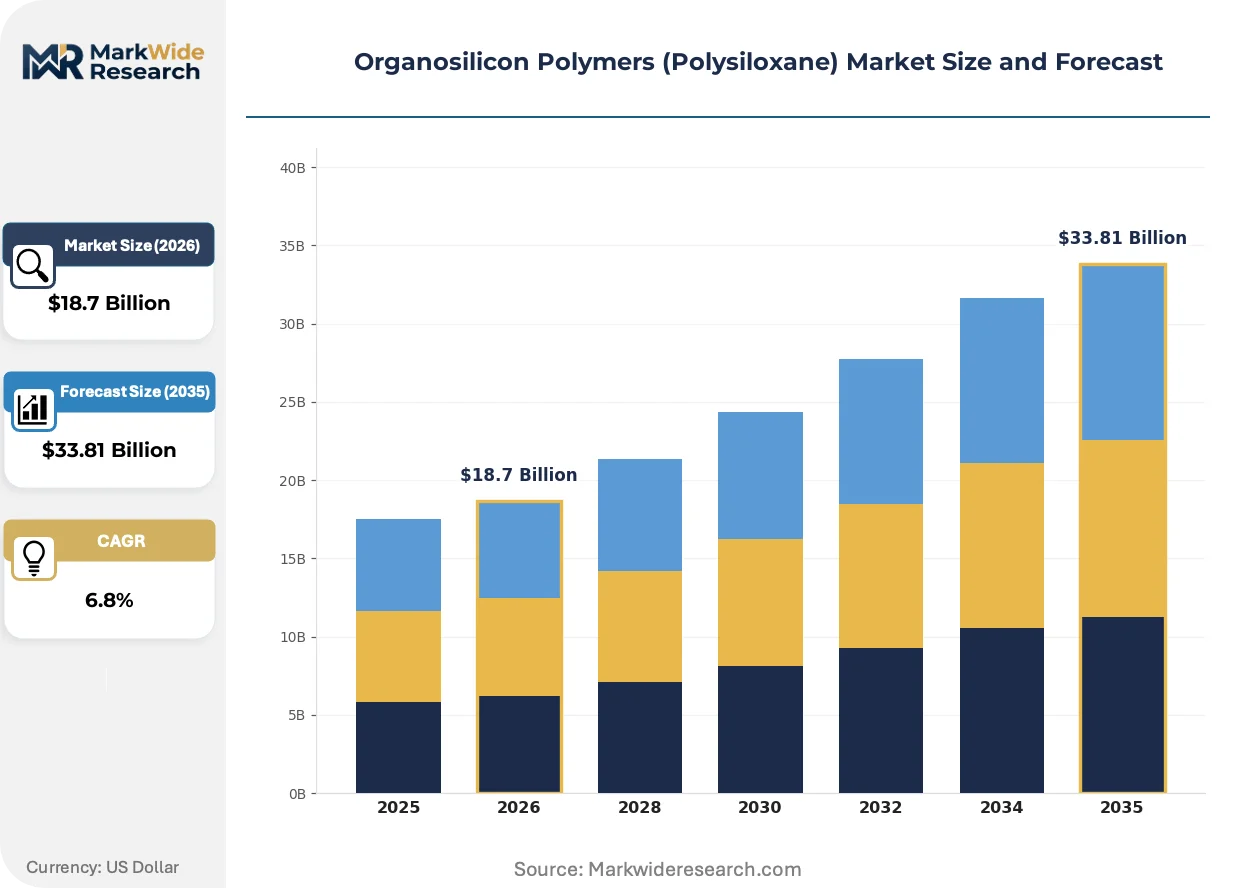
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Sealants, Adhesives, Coatings, Elastomers Product Type: Silicone Fluids, Silicone Resins, Silicone Rubber, Silicone Gels End User: Automotive, Electronics, Construction, Healthcare Form: Liquid, Gel, Solid, Paste |
| Companies Covered | Dow, BASF, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Covestro, DIC Corporation, Mitsui Chemicals, Huntsman International, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organosilicon Polymers (Polysiloxane) Market Evolving Landscape
Formulation science is bifurcating between atomically precise semiconductor fluids and construction-grade sealants, with manufacturing technology determining competitive survival. This divergence is reshaping capital allocation patterns across the value chain.
Atomically controlled vapor deposition precursors for 3D NAND fabrication is consolidating supply relationships between Japanese resin specialists and Taiwan-based foundry operators. These materials require sub-ppb metallic impurity specifications that commodity producers cannot meet. The technology is consolidating procurement authority within semiconductor materials divisions, bypassing traditional distributor channels.
EPA's volatile organic compound limits for solvent-based silicone coatings are forcing architectural sealant reformulation toward high-solids and water-based cure systems. Industrial maintenance applications in the US Gulf Coast petrochemical corridor face 250 g/L VOC ceilings, compelling applicators to retool spray equipment and retrain field crews.
Direct contracting between automotive OEMs and siloxane monomer producers is displacing tiered distribution for thermal interface materials. Battery pack assemblers in Stuttgart and Shanghai are negotiating annual volume commitments with integrated producers, extracting price transparency previously obscured by distributor markups. This pattern is most pronounced in electric vehicle platforms exceeding 100,000 unit annual production.
Organosilicon Polymers (Polysiloxane) Market Segmentation
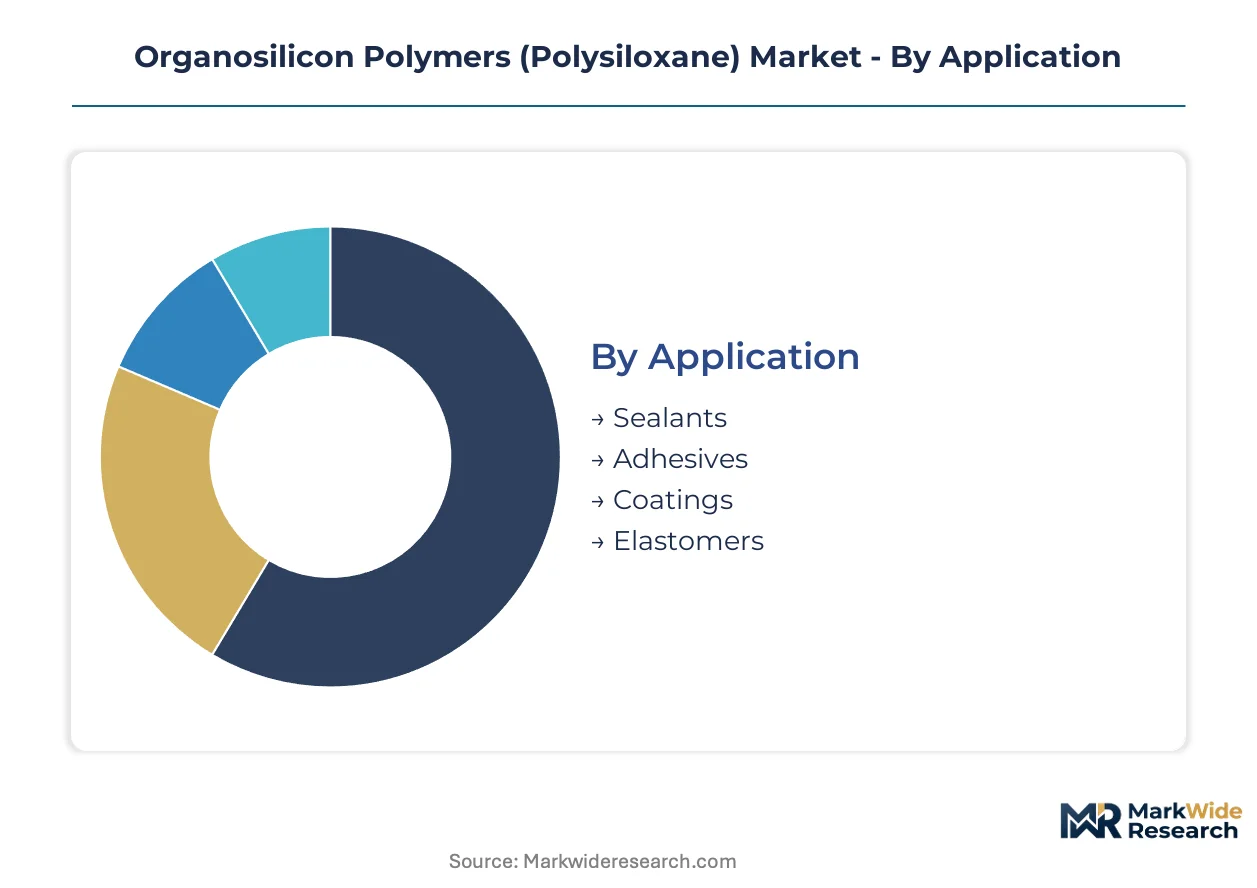
Polysiloxane manufacturers configure assets around divergent purity thresholds and cure chemistry requirements. Segmentation discipline separates semiconductor-grade specifications from construction commodity volumes, determining which product lines sustain margin.
Application:
Volume concentration sits in construction sealants while premium capture concentrates in aerospace elastomers.
- Sealants:Formulations cure through moisture-activated alkoxy or acetoxy systems, delivering weatherproofing for curtainwall glazing and infrastructure expansion joints. Demand clusters in China's Guangdong province where municipal transit projects specify low-modulus silicone for concrete movement accommodation.
- Elastomers:High-consistency rubber and liquid silicone rubber grades withstand thermal cycling from -60°C to 250°C through platinum-catalyzed hydrosilylation. Aerospace OEMs in Toulouse and Seattle mandate flame-retardant certification per FAA smoke toxicity standards, locking in long-term supply agreements at 40-60 point margin premiums over industrial equivalents.
- Adhesives:Structural bonding grades for electric vehicle battery pack assembly require primerless adhesion to aluminum and engineered plastics.
- Coatings:Solvent-based and high-solids formulations face EPA VOC ceilings of 250 g/L in US industrial maintenance applications.
Today's leader: Elastomers. Tomorrow's challenger: Adhesives.
Product Type:
Silicone rubber generates deepest revenue pools while silicone fluids climb fastest on datacenter thermal management pull.
- Silicone Rubber:High-consistency and liquid injection molding grades dominate automotive gasketing and healthcare tubing through controlled crosslink density. Medical device manufacturers in Minnesota and Bavaria specify ISO 10993 biocompatibility certification, requiring 18-24 month cytotoxicity testing protocols that delay competitor entry.
- Silicone Fluids:Low-viscosity dimethylsiloxane polymers enable direct-to-chip liquid cooling for hyperscale datacenters in Singapore and Ireland. Purity specifications reach sub-ppb metallic impurity thresholds for semiconductor fabrication precursors, consolidating procurement relationships with Japanese resin specialists.
- Silicone Resins:Methyl and phenyl silicate polymers provide thermal stability for electronics packaging and industrial coatings.
- Silicone Gels:Soft, unfilled networks encapsulate sensitive electronic components and medical implants.
Silicone rubber commands current revenue concentration. Silicone fluids are expanding most quickly.
End User:
Electronics manufacturing concentrates highest-purity demand while construction absorbs commodity-grade volume.
- Electronics:Semiconductor packaging and thermal interface materials require atomically controlled vapor deposition precursors. Taiwan-based foundry operators consolidate supply relationships with integrated Japanese producers, bypassing traditional distribution channels for 3D NAND fabrication materials.
- Automotive:Electric vehicle battery pack encapsulation and thermal management drive localization of adhesive sourcing. Stuttgart and Shanghai OEMs negotiate direct annual volume commitments with siloxane monomer producers, extracting price transparency previously obscured by distributor markups.
- Construction:Curtainwall glazing and infrastructure sealants absorb the largest tonnage volumes.
- Healthcare:Implantable neuromodulation devices and diagnostic tubing demand medical-grade liquid silicone rubber.
Electronics leads premium capture. Automotive is gaining share fastest on electrification.
Form:
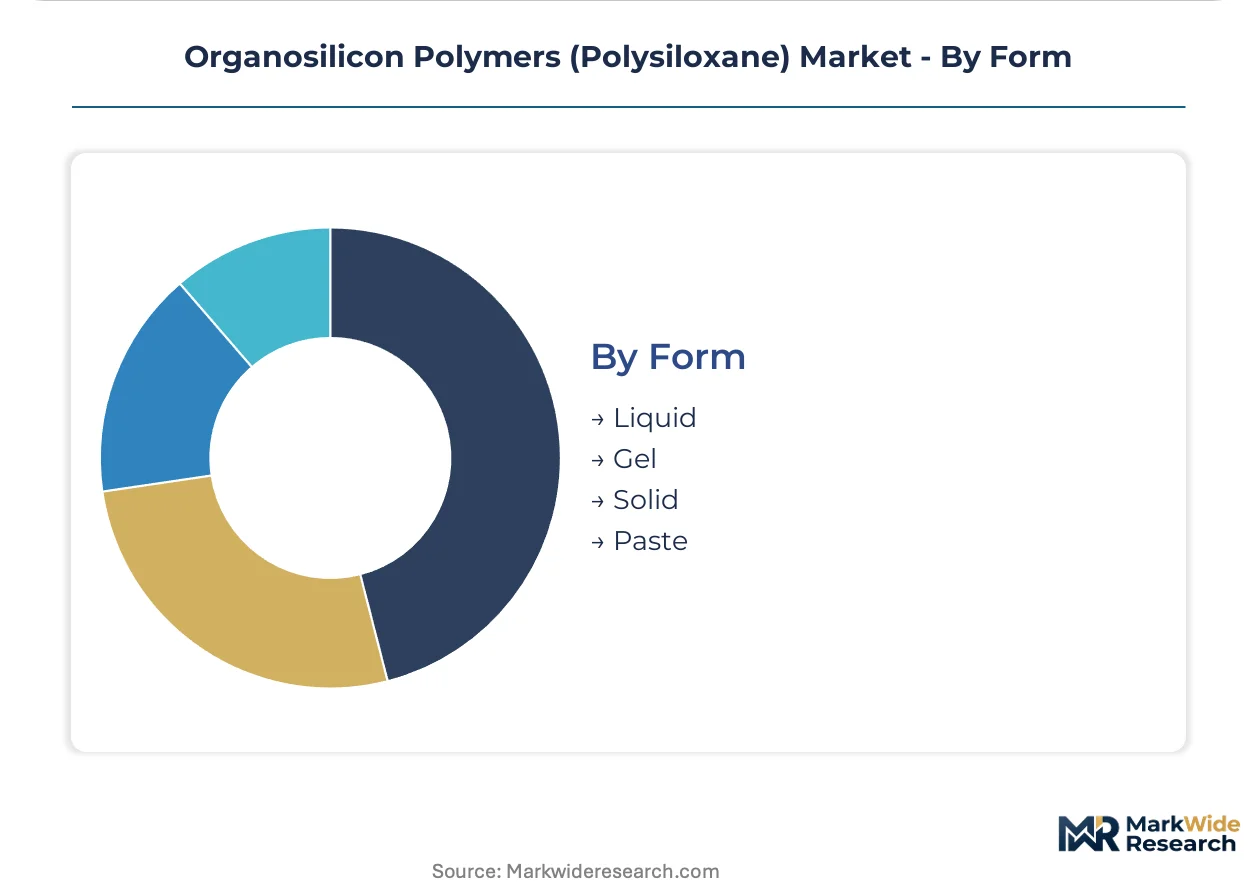
Liquid formulations dominate industrial processing while gel states capture medical miniaturization premiums.
- Liquid:Pumpable dimethylsiloxane polymers serve datacenter cooling circuits and cosmetic formulations. REACH D4/D5/D6 restrictions on cyclic siloxanes in European leave-on personal care products redirect capacity toward industrial sealants and automotive gasketing.
- Gel:Soft, compliant networks encapsulate implantable medical devices and sensitive electronics. Micro-molding grades for neuromodulation implants command steep margin premiums through ISO 10993 certification barriers.
- Solid:High-consistency rubber compounds require mill mixing or injection molding equipment.
- Paste:Thixotropic formulations enable vertical application in construction sealants.
Liquid forms anchor current volume. Gel states hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polymer chemists and materials engineers concentrate in Germany's Ruhr industrial corridor, Japan's Kanto region, and China's Yangtze River Delta, anchoring three distinct supply ecosystems for organosilicon production.
United States
Hyperscale datacenter operators in Virginia's Loudoun County and Texas's Dallas-Fort Worth metroplex drive demand for low-viscosity silicone thermal fluids. EPA VOC ceilings of 250 g/L constrain solvent-based coating formulations across Gulf Coast petrochemical maintenance applications. Minnesota's Twin Cities corridor hosts medical device manufacturers specifying ISO 10993 biocompatibility certification for implantable neuromodulation components.
Germany
Automotive OEMs in Stuttgart and Wolfsburg negotiate direct annual volume commitments for battery pack encapsulation adhesives. ECHA's REACH D4/D5/D6 restrictions on cyclic siloxanes redirect European capacity from personal care toward industrial sealants. Wacker Chemie's Burghausen integrated site sustains specifications for flame-retardant aerospace elastomers serving Toulouse and Seattle OEMs.
China
Electric vehicle manufacturers in Guangdong province localize silicone adhesive sourcing for battery thermal management systems. MEE enforces emission standards at organosilicon monomer plants along the Yangtze River industrial corridor. Shanghai's Pudong district concentrates semiconductor packaging demand for atomically controlled vapor deposition precursors.
Japan
Advanced resin output for 3D NAND fabrication consolidates supply relationships between Japanese specialists and Taiwan-based foundry operators. METI industrial policy supports domestic siloxane monomer production for electronics packaging materials. Shin-Etsu Chemical's Tokyo operations anchor high-purity silicone fluid specifications for direct-to-chip liquid cooling applications.
India
PLI scheme disbursements for semiconductor packaging create first-mover advantage for thermal interface material suppliers. CDSCO medical device regulations govern import substitution strategies for healthcare-grade liquid silicone rubber. Gujarat's Dahej industrial zone attracts compounding facility investments targeting electronics manufacturing incentives.
Organosilicon Polymers (Polysiloxane) Market Competitive Landscape
Top-tier vendors anchor integrated siloxane production, while mid-scale formulators compete on application-specific certifications. The vendor base stratifies between captive monomer producers and specialty compounders dependent on merchant siloxane supply. Three archetypes dominate: integrated chemical conglomerates with backward siloxane control, regional elastomer specialists serving aerospace long-term agreements, and medical-grade gel purveyors carrying ISO 10993 certification barriers. Capacity expansion and direct OEM contracting represent the two dominant competitive vectors reshaping distribution economics.
Among integrated chemical producers, Dow, Wacker Chemie AG, and Shin-Etsu Chemical Co., Ltd. occupy positions exemplifying distinct geographic and technological anchoring. Dow represents North American captive production capabilities. Wacker Chemie AG exemplifies European integrated site economics. Shin-Etsu Chemical Co., Ltd. anchors Asia-Pacific advanced resin specialization for semiconductor applications.
| Leading Market Players |
|---|
| Dow |
| BASF |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Covestro |
| DIC Corporation |
| Mitsui Chemicals |
| Huntsman International |
| LANXESS |
| Others |
Value Network & Pricing Analysis
REACH D4/D5/D6 restrictions on cyclic siloxanes in European personal care formulations are redirecting merchant siloxane volumes toward industrial sealants, tightening spot availability for commodity-grade producers and compressing mid-tier formulation margins. This regulatory-driven demand reallocation forces supply chain reconfiguration around captive siloxane streams, with integrated producers extracting pricing power from formulators lacking backward integration.
Pricing Analysis
Bundled long-term supply agreements with direct OEM contracting dominate premium thermal interface materials, while unbundled spot transactions govern construction sealant grades. Three-tier pricing structure across semiconductor-grade, automotive-certified, and commodity industrial levels separates sub-ppb purity precursors from standard elastomer compounds. Cost compression in mid-tier sealant formulations is intensifying because Guangdong-based electric vehicle manufacturers are consolidating adhesive sourcing within provincial boundaries. Automotive OEMs exhibit lowest price sensitivity due to flame-retardant certification requirements, while construction distributors face highest sensitivity on undifferentiated glazing sealants.
Supply Chain Analysis
Rhine logistics disruptions and force majeure exposure at the Burghausen-Rotterdam corridor elevate freight cost premiums for European elastomer delivery. Production gravity centers on Germany, China, and Japan, with siloxane monomer output tethered to methanol and silicon metal feedstock economics. Raw material dependencies include methyl chloride, platinum group metals for hydrosilylation catalysts, and high-purity silicon metal. Single-source vulnerability concentrates in South African and Russian platinum supply for cure systems. Distribution runs through direct OEM channels for thermal interface materials and regional distributor networks for construction sealants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European REACH compliance costs and Chinese MEE emission standard enforcement, with producers locating siloxane monomer capacity in jurisdictions with lower carbon border adjustment exposure.
For Market Incumbents: Hedge platinum group metal supply disruption through long-term offtake agreements with alternative source jurisdictions, and defend margin position by deepening captive siloxane integration at Yangtze River corridor sites. Fluoropolymer substitution in aerospace applications above 300°C threatens silicone rubber penetration, requiring accelerated flame-retardant certification investment for next-generation engine architectures.
For New Entrants and Emerging Players: The 40-60 point margin gap between medical-grade liquid silicone rubber and industrial elastomers offers white-space entry through ISO 10993 certification investment in Minnesota or Bavaria clusters. Target India's PLI scheme disbursements for semiconductor packaging to establish Gujarat or Tamil Nadu compounding facilities. Pursue direct contracting with hyperscale datacenter operators in Singapore and Ireland for low-viscosity thermal fluid supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with medical-grade gel purveyors carrying 18-24 month biocompatibility certification barriers that delay competitor entry. Long-term viability over a multi-year horizon favors integrated producers with backward siloxane control over merchant-dependent formulators. Monitor ECHA regulatory divergence on cyclic siloxane content limits as the inflection signal for cross-border product grade access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Monomer Production | Captive supply secures cost positions against methanol and silicon metal volatility at Yangtze River sites. |
| Long-term Supply Agreement with Automotive OEMs | Direct annual volume commitments with Stuttgart and Shanghai battery pack assemblers extract price transparency from distributor markups. |
| ISO 10993 Biocompatibility Certification Investment | Medical-grade liquid silicone rubber for Minnesota implantable neuromodulation devices commands steep margin premiums. |
| Green Manufacturing Transition via Bio-based Feedstocks | Fermentation-derived silicone precursors from agricultural waste offer EU Green Deal carbon border adjustment compliance pathways. |
| Joint Venture for Semiconductor-Grade Resin Production | Atomically controlled vapor deposition precursors for Taiwan-based foundry operators consolidate supply relationships with Japanese specialists. |
Research Methodology
Coverage spans Germany, China, Japan, and the United States, with primary inputs from each region combined with secondary validation. Interviews with plant managers at integrated siloxane sites, procurement leads at automotive OEMs, distribution channel partners for construction sealants, and technical R&D directors for medical-grade formulations generated demand-side intelligence. Secondary sources include customs and trade data from relevant export authorities, chemical industry association reports, SEC 10-K filings from listed producers, and ECHA regulatory submission databases. Bottom-up volume modeling and top-down value reconciliation provided cross-check triangulation across the analysis window.
Granularity-level modeling disaggregated the market by product type, application, end-use industry, form state, and regional production hub across the projection horizon. Silicone rubber, fluids, resins, and gels were tracked separately with purity-grade differentiation. Semiconductor packaging, automotive, construction, and healthcare end-uses carried distinct specification requirements. CAGRs were derived from segment-level volume trajectories calibrated to named demand drivers including datacenter liquid cooling adoption and electric vehicle battery encapsulation growth.
Caveats apply where platinum catalyst sourcing constraints, REACH regulatory divergence on cyclic siloxanes, or methyl chloride feedstock volatility could materially shift the outlook. Forecasts reflect assumptions about continued semiconductor fabrication expansion and automotive electrification penetration without specific policy intervention. A model refresh is warranted upon material change in ECHA D4/D5/D6 restriction enforcement or MEE emission standard implementation at Yangtze River organosilicon monomer plants.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Polyethersulfone (PES) Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polymer Reinforcing Filler Market