
 Modified Epoxy Resins Market | 2026-2036
Modified Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Epoxy Resins Market Foresight
Polyurethane is shifting select protective coating applications away from conventional modified epoxy systems in transportation infrastructure, forcing resin suppliers to reformulate for adhesion and chemical resistance parity. Olin Corporation leverages its integrated bisphenol A and epichlorohydrin position to control feedstock costs across Americas manufacturing. Huntsman Corporation anchors its competitiveness in aerospace-qualified systems through differentiated curing agent portfolios. Kukdo Chemical Co., Ltd dominates Asian electronics laminate supply with high-purity low-ionic-content resins.
Modified epoxy resins are thermosetting polymers produced by reacting epichlorohydrin with bisphenol A or bisphenol F, then functionalized with reactive diluents, flexibilizers, or toughening agents to achieve specific mechanical, thermal, or processing properties for demanding industrial applications. Rigid formulations occupy the largest volume share in construction composites and civil engineering rehabilitation where load-bearing performance commands premium positioning. High-temperature grades represent the fastest-expanding category as aerospace engine nacelles and electric vehicle battery enclosures push glass transition temperature requirements above 180°C. Liquid form factors sustain margin pools in automated dispensing and infusion processes for wind blade and automotive structural part manufacturing.
EPA regulates volatile organic compound emissions from coatings and adhesives containing epoxy constituents under Clean Air Act Title I, compelling reformulation toward exempt solvents or 100% solids systems. REACH registration requirements and ECHA substance evaluation restrict certain amine hardeners and bisphenol A derivatives in European consumer-facing and food-contact applications. China's MEE enforces GB standards on hazardous substance limits in electronics-grade resins exported under dual carbon compliance frameworks. Stakeholders must monitor evolving substance restrictions across multiple jurisdictions while building formulation flexibility into R&D pipelines.
Market Dynamics
Wind turbine blade scaling beyond 100-meter lengths is compressing cure-cycle windows and demanding resin systems with simultaneous low-viscosity infusion and elevated glass transition temperature performance.
Growth Catalysts
- EU Green Deal compliance mandates:REACH restrictions on bisphenol A derivatives are accelerating bio-based hardener R&D pipelines across European formulators serving food-contact and consumer-facing coatings.
- China domestic epoxy capacity expansion:MEE enforcement of GB standards on hazardous substance limits is capturing electronics laminate demand previously served by imported resin systems.
- Automotive structural composites:Electric vehicle battery enclosure manufacturers are specifying high-temperature modified epoxy grades with glass transition temperatures exceeding 180°C for thermal runaway protection.
Market Restraints
- Epichlorohydrin feedstock volatility:Chlor-alkali capacity constraints and energy cost spikes in European and Asian manufacturing clusters are compressing margin pools for non-integrated resin producers.
- Polyurethane substitution in protective coatings:Transportation infrastructure maintenance programs are specifying polyurethane systems for improved flexibility and UV resistance in bridge deck and rail applications.
- Amine hardener supply concentration:Cycloaliphatic and aromatic amine production concentrates in select German and Chinese chemical parks, creating single-source vulnerability for aerospace-qualified curing agents.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and PCB fabrication are creating localized demand for high-purity low-ionic-content laminating resins previously imported from Northeast Asian suppliers.
- 100% solids UV-curable systems:EPA Clean Air Act Title I compliance pressures are opening formulation white space for solvent-free epoxy acrylates in wood furniture and industrial coating applications.
- Digital twin-enabled cure monitoring:Integration of embedded fiber optic sensors with predictive process models is enabling real-time viscosity and exotherm management in automated wind blade infusion.
Industry Challenges
- Aerospace qualification timelines:OEM certification protocols for modified epoxy systems require 18-36 month validation cycles, locking out reformulated products from aftermarket revenue streams.
- Multi-jurisdiction substance tracking:Formulators must maintain parallel compliance dossiers for EPA TSCA, REACH SVHC candidate lists, and China's MEE hazardous chemical catalog updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Epoxy Resins Market |
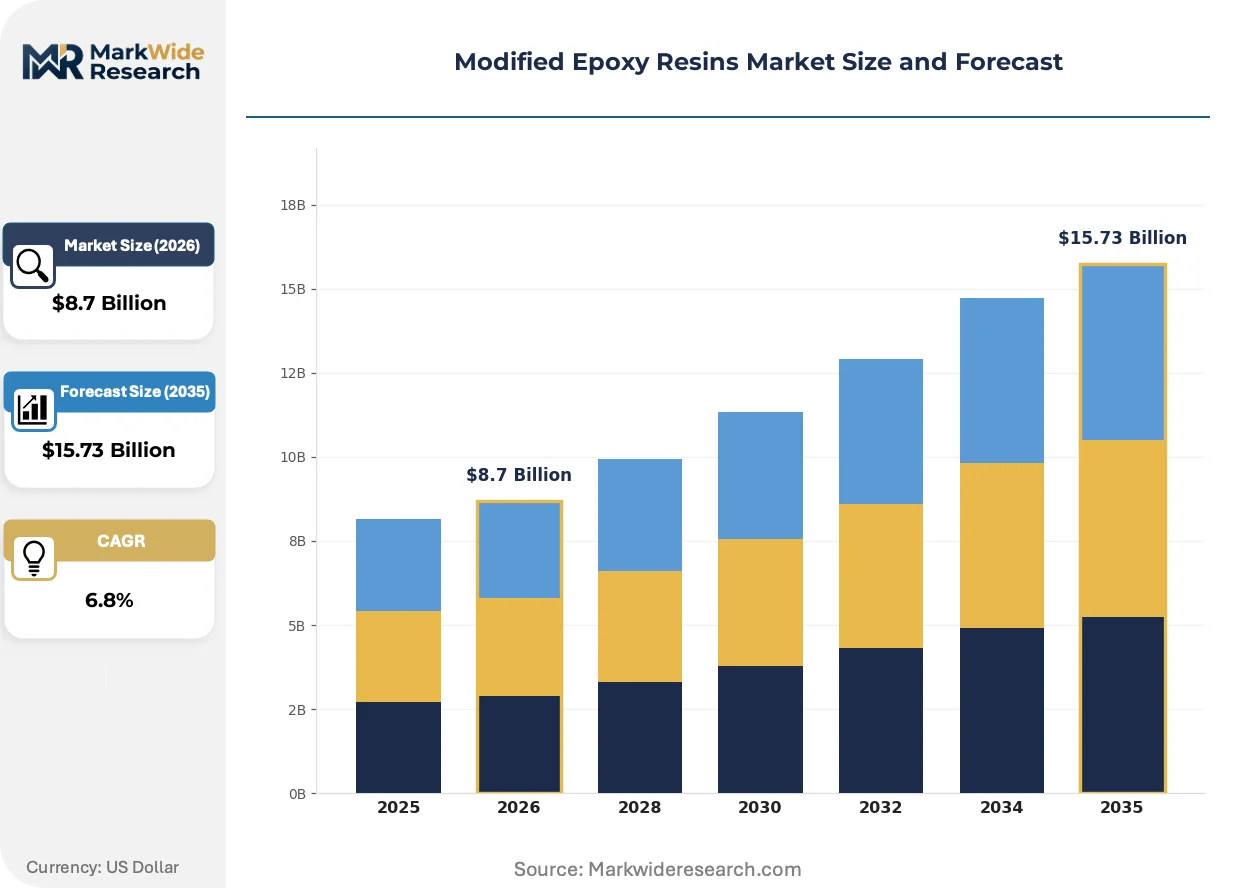
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible, Rigid, High-Temperature, Low-Viscosity End Use Industry: Aerospace, Automotive, Construction, Electronics Form: Liquid, Solid, Powder, Paste Application: Coatings, Adhesives, Composites, Sealants |
| Companies Covered | Olin Corporation, Hexion Inc., Huntsman Corporation, Aditya Birla Chemicals, Kukdo Chemical Co., Ltd, BASF SE, Dow Inc., Nan Ya Plastics Corporation, Adeka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Epoxy Resins Market Shifts & Advancements
Reformulation priorities are pivoting from incremental property enhancement toward radical VOC elimination and embedded intelligence, driven by tightening emission ceilings and process automation imperatives.
Bio-based reactive diluents derived from lignin and vegetable oil epoxides are expanding into marine coating and flooring applications where petrochemical supply security concerns intersect with EU Green Deal procurement mandates. Shipyards in the Netherlands and Denmark are piloting these systems for ballast tank protection. The technology is expanding into specification-driven segments previously closed to non-fossil feedstocks.
REACH authorization requirements for certain aromatic amine hardeners are forcing reformulation toward aliphatic and modified polyamide alternatives in European consumer goods and construction applications. ECHA substance evaluation timelines are compressing product lifecycle planning windows. Electronics laminate manufacturers serving EU markets are accelerating substitution programs ahead of sunset date uncertainties.
Specification-driven procurement is consolidating buyer power among wind turbine OEMs and Tier-1 aerospace contractors, squeezing regional distributor networks and forcing direct technical service relationships with resin formulators. Long-term offtake agreements with volume commitments and joint development clauses are displacing spot-market transactions. This concentration is most visible in China's wind energy supply chain and Germany's automotive composites sector.
Modified Epoxy Resins Market Segmentation
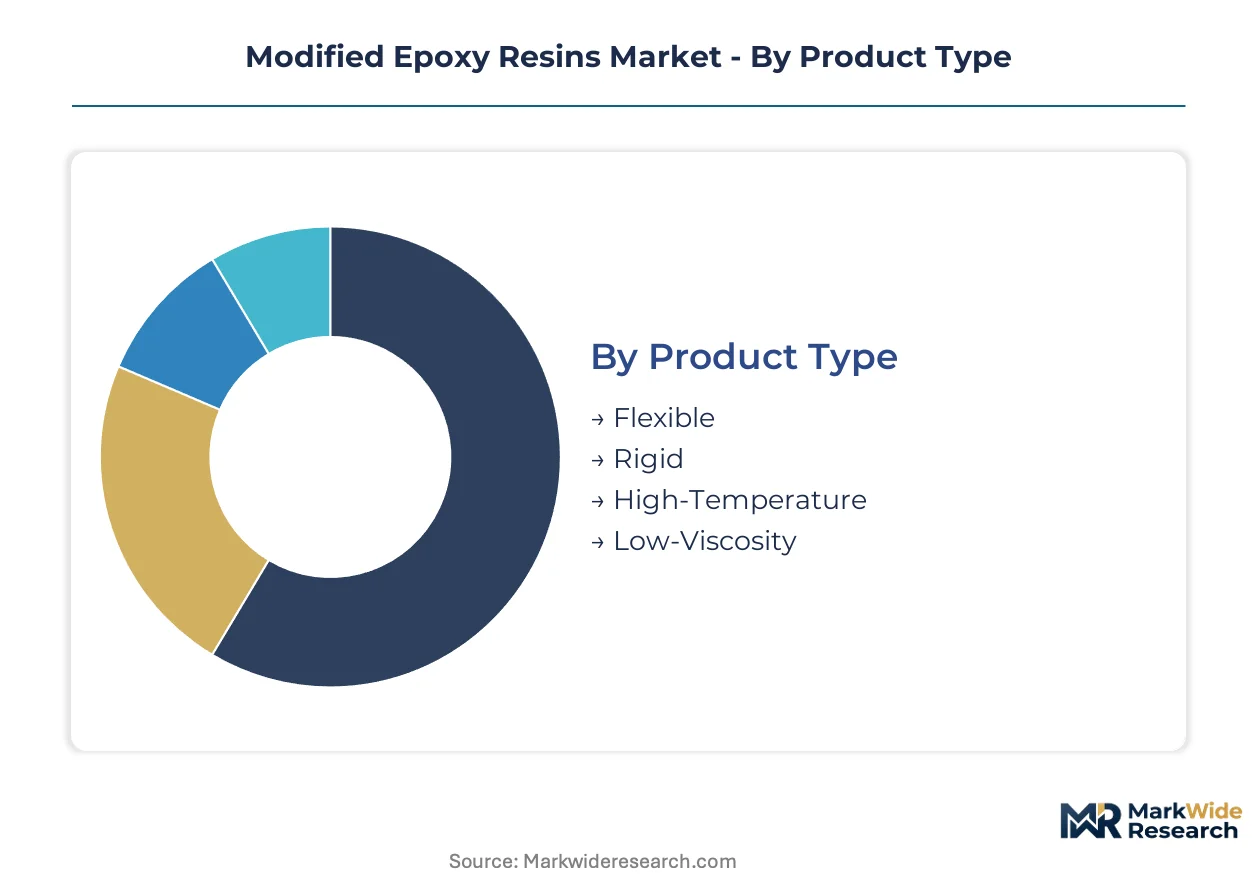
Modified epoxy resins serve radically different performance requirements across wind blade infusion, aerospace qualification, and electronics lamination. Segmentation reveals how formulation chemistry, physical form, and application method combine to determine pricing power and technical barriers to entry.
Product Type:
Glass transition temperature and modulus differentiation separate commodity volumes from specification-premium positions.
- Rigid:High crosslink density formulations based on standard bisphenol A or bisphenol F backbones dominate construction composites and civil engineering rehabilitation. Load-bearing performance in bridge strengthening and structural repair commands premium positioning over flexible alternatives.
- High-Temperature:Functionalized with elevated functionality hardeners and toughening agents to achieve glass transition temperatures exceeding 180°C. Aerospace engine nacelles and electric vehicle battery enclosures in Germany and China are compressing qualification timelines for these grades.
- Flexible:Incorporates long-chain reactive diluents or rubber toughening to improve impact resistance and thermal cycling durability. Marine coating applications in Dutch and Danish shipyards specify these systems for ballast tank flexibility requirements.
- Low-Viscosity:Optimized for automated dispensing and vacuum infusion processes in wind turbine blade manufacturing. OEMs scaling beyond 100-meter blade lengths demand simultaneous low-viscosity flow and elevated cured Tg performance.
Rigid formulations lead on scale; high-temperature grades lead on momentum.
End Use Industry:
Customer concentration and qualification protocols fragment margin structures across application verticals.
- Electronics:High-purity low-ionic-content laminating resins serve PCB and semiconductor packaging applications. China's domestic epoxy capacity expansion is capturing demand previously served by imported systems under MEE hazardous substance enforcement.
- Automotive:Structural composites for electric vehicle battery enclosures specify thermal runaway protection grades. OEMs in Germany and China are consolidating supplier relationships around direct technical service partnerships.
- Aerospace:Qualified systems require 18-36 month certification cycles locking out reformulated products from aftermarket revenue. Cycloaliphatic and aromatic amine curing agent concentration in German and Chinese chemical parks creates supply vulnerability.
- Construction:Civil engineering rehabilitation and composite reinforcement applications consume volume in rigid formulations. EU Green Deal procurement mandates are accelerating bio-based hardener adoption in Dutch and Danish infrastructure projects.
Electronics leads on scale; automotive leads on momentum.
Form:
Processing automation and VOC compliance are restructuring form factor preferences across coating and composite applications.
- Liquid:Sustains margin pools in automated dispensing and infusion processes for wind blade manufacturing. REACH restrictions on volatile organic compounds are pushing formulators toward 100% solids liquid alternatives in European consumer-facing applications.
- Solid:Powder and flake forms serve hot-melt adhesive and powder coating applications where solvent elimination is mandatory. EPA Clean Air Act Title I compliance pressures are opening formulation white space for solvent-free systems.
- Powder:Electrostatic spray applications in industrial coatings benefit from zero-VOC emission profiles. Transportation infrastructure maintenance programs are specifying these systems for bridge deck and rail applications.
- Paste:Thixotropic formulations enable trowel-applied repair compounds and gap-filling adhesives. Construction sector demand concentrates in civil engineering rehabilitation where manual application persists.
Liquid leads on scale; solid leads on momentum.
Application:
Performance specifications and regulatory exposure vary sharply across surface protection, bonding, and structural functions.
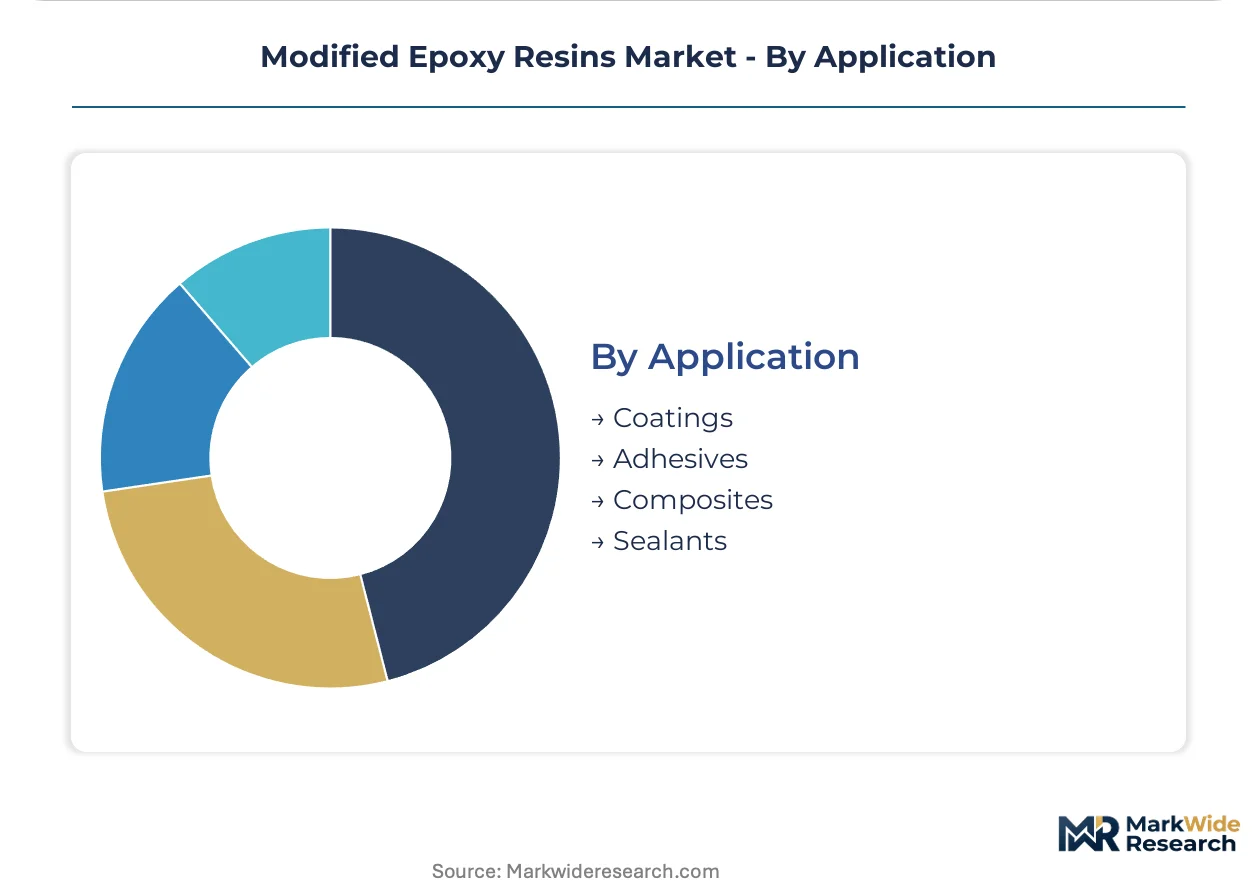
- Composites:Fiber-reinforced systems dominate wind turbine blade and automotive structural part manufacturing. Specification-driven procurement is consolidating buyer power among Tier-1 contractors and squeezing regional distributor networks.
- Coatings:Protective and marine applications face polyurethane substitution pressure in transportation infrastructure. Bio-based reactive diluents derived from lignin are expanding into specification-driven segments previously closed to non-fossil feedstocks.
- Adhesives:Structural bonding applications in aerospace and automotive require matched thermal expansion coefficients. Long-term offtake agreements with volume commitments are displacing spot-market transactions.
- Sealants:Joint sealing and encapsulation functions in electronics and construction demand moisture resistance and dielectric stability. China's GB standards on hazardous substance limits are reshaping export compliance requirements.
Composites lead on scale; coatings lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors modified epoxy resin demand through integrated electronics laminating and wind blade manufacturing clusters serving domestic and export markets.
China
Domestic epoxy capacity expansion in Jiangsu and Zhejiang provinces captures electronics laminate demand previously served by imported resin systems. MEE enforcement of GB standards on hazardous substance limits reshapes export compliance frameworks for dual carbon goals. Shanghai and Ningbo chemical parks concentrate high-purity low-ionic-content resin production for semiconductor packaging applications.
Germany
Automotive structural composites for electric vehicle battery enclosures drive high-temperature grade specifications exceeding 180°C glass transition temperatures. ECHA substance evaluation timelines under REACH compress product lifecycle planning for aromatic amine hardeners. The Ruhr industrial corridor and Bavarian chemical parks concentrate cycloaliphatic curing agent production for aerospace-qualified systems.
United States
Wind turbine blade scaling beyond 100-meter lengths demands resin systems with simultaneous low-viscosity infusion and elevated cured performance. EPA Clean Air Act Title I regulates volatile organic compound emissions from coatings and adhesives, compelling reformulation toward 100% solids systems. Texas and Iowa wind manufacturing corridors concentrate automated infusion capacity serving domestic renewable energy deployment.
India
PLI scheme incentives for semiconductor and PCB fabrication create localized demand for high-purity laminating resins previously imported from Northeast Asian suppliers. BIS certification requirements for electronics-grade materials reshape procurement patterns among domestic fabricators. Gujarat and Maharashtra industrial zones concentrate emerging laminating capacity serving smartphone and automotive electronics supply chains.
Netherlands
EU Green Deal procurement mandates accelerate bio-based hardener adoption in marine coating applications for ballast tank protection. REACH restrictions on bisphenol A derivatives push formulators toward reduced volatile organic compound systems in consumer-facing applications. Rotterdam chemical clusters and Dutch shipyards pilot lignin-derived reactive diluents in specification-driven segments previously closed to non-fossil feedstocks.
Modified Epoxy Resins Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated feedstock producers leverage captive bisphenol A and epichlorohydrin positions to compress non-integrated competitor margins. The vendor base stratifies across three archetypes: petrochemical majors with backward integration into epichlorohydrin, specialty chemical houses with differentiated curing agent portfolios, and regional electronics-grade specialists with ionic purity capabilities. M&A activity and geographic expansion constitute the dominant competitive moves, with European and Asian players establishing technical service partnerships near wind and automotive OEM clusters.
Among North American integrated producers, Olin Corporation exemplifies the feedstock-control archetype through its bisphenol A and epichlorohydrin position. Huntsman Corporation occupies a position within the specialty curing agent tier, while Kukdo Chemical Co., Ltd anchors the Asian electronics-grade specialist segment with high-purity resin capabilities. These three represent distinct strategic postures: captive raw material security, differentiated hardener technology, and ionic-content precision for laminating applications.
| Leading Market Players |
|---|
| Olin Corporation |
| Hexion Inc. |
| Huntsman Corporation |
| Aditya Birla Chemicals |
| Kukdo Chemical Co., Ltd |
| BASF SE |
| Dow Inc. |
| Nan Ya Plastics Corporation |
| Adeka Corporation |
| Others |
Supply & Pricing Matrix
Wind turbine OEMs and Tier-1 aerospace contractors have consolidated procurement around long-term offtake agreements with volume commitments and joint development clauses, displacing spot-market transactions and compressing margin pools for non-integrated resin suppliers.
Pricing Analysis
Epichlorohydrin and bisphenol A cost pass-through dominates modified epoxy resin pricing, with integrated producers leveraging captive feedstock positions to undercut non-integrated competitors on standard grades. Pricing stratifies across aerospace-qualified premium tiers, automotive specification-mid tiers, and construction commodity-economy tiers based on glass transition temperature certification and ionic purity testing. Cost compression in European chlor-alkali clusters is intensifying because energy price spikes and regulatory compliance burdens are squeezing non-integrated formulators. Electronics laminate manufacturers in China exhibit highest price sensitivity due to domestic capacity expansion, while aerospace OEMs demonstrate lowest sensitivity given 18-36 month qualification lock-ins.
Supply Chain Analysis
Bulk liquid resin freight costs from Jiangsu and Zhejiang chemical parks to European wind blade manufacturing corridors have become a decisive factor in supplier selection, favoring regional production over transoceanic supply. Feedstock supply concentrates in China, Germany, and the United States, with epichlorohydrin production anchored in chlor-alkali complexes across these three manufacturing clusters. Raw material dependencies rest on bisphenol A, epichlorohydrin, and cycloaliphatic amine hardeners sourced from integrated petrochemical majors. Single-source vulnerability in German and Chinese chemical parks for aerospace-qualified curing agents creates structural supply risk. Distribution runs through direct technical service partnerships with wind and automotive OEM clusters, bypassing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in modified epoxy resins hinges on feedstock cost control and premium-tier qualification investments, with backward integration into epichlorohydrin offering the clearest path to sustainable profitability.
For Market Incumbents: Acquire captive chlor-alkali capacity or secure long-term bisphenol A supply agreements to defend against polyurethane substitution in protective coatings and margin compression from Chinese domestic capacity expansion. Prioritize aerospace qualification investments to lock in 18-36 month certification cycles that exclude reformulated competitors from aftermarket revenue streams. Establish technical service partnerships near German automotive and Chinese wind energy OEM clusters to consolidate specification-driven procurement relationships. For New Entrants and Emerging Players: Regional distributors serving mid-size wind blade manufacturers in India and Southeast Asia represent the most accessible channel for building volume without confronting integrated producer scale advantages. Target India's PLI scheme-driven electronics laminate segment, where localized high-purity resin demand outpaces domestic supply capacity. Lead with bio-based hardener formulations that satisfy EU Green Deal procurement mandates in Dutch marine coating applications, using sustainability credentials to bypass entrenched petrochemical supplier relationships. For Investors and Strategic Acquirers: Specialty chemical houses with differentiated curing agent portfolios are the most active acquirer in this space, seeking ionic-purity capabilities and regional formulation expertise. Long-term viability centers on backward integration depth and qualification-timeline capture rather than commodity volume scale. Monitor ECHA substance evaluation timelines for aromatic amine hardeners as the critical inflection signal—accelerated sunset dates would trigger consolidation among formulators lacking aliphatic alternative pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epichlorohydrin | Captive feedstock supply from chlor-alkali complexes insulates margin pools from energy cost volatility in European manufacturing. |
| Aerospace Qualification Investment | 18-36 month OEM certification cycles lock reformulated products out of aftermarket revenue streams for engine nacelle applications. |
| Bio-Based Hardener Development | REACH authorization pressures on aromatic amines create formulation white space for lignin-derived systems in Dutch shipyard trials. |
| Regional Technical Service Partnership | Direct relationships with wind turbine OEMs in China's Yangtze River Delta displace distributor networks in specification-driven procurement. |
| High-Purity Ionic Content Capacity | MEE enforcement of GB standards captures electronics laminate demand previously served by imported Northeast Asian resin systems. |
Research Methodology
Coverage spans China, Germany, the United States, India, and the Netherlands, with primary inputs from each region combined with secondary validation across multiple data categories. Primary research incorporated interviews with resin plant managers, procurement leads at wind turbine and automotive OEMs, distribution channel partners, and technical R&D directors at formulator facilities. Secondary sources included customs and trade flow data, ACC and Cefic industry reports, SEC 10-K filings from integrated chemical producers, EPA Clean Air Act regulatory filings, and ECHA REACH registration databases. Bottom-up volume modeling triangulated against top-down value estimates to reconcile production capacity with end-use consumption patterns.
Granularity-level modeling operated at product type, end-use industry, physical form, and application method dimensions, with additional segmentation by glass transition temperature tier and ionic purity grade for electronics applications. CAGRs were derived from fitted trend analysis across the projection horizon, incorporating wind turbine blade scaling trajectories, electric vehicle battery enclosure adoption curves, and electronics laminate demand shifts. Industry-specific forecast inputs included chlor-alkali capacity utilization rates, REACH authorization timeline scenarios, and MEE hazardous substance enforcement intensity indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA substance evaluation timelines, epichlorohydrin feedstock volatility, and polyurethane substitution rates in transportation infrastructure. Forecasts reflect assumptions about regulatory enforcement continuity, OEM qualification protocol stability, and dual carbon policy implementation trajectories in China. Stakeholders should weight assumptions against their own operating context and monitor evolving substance restrictions across multiple jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Global Encapsulation Resins Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Europe Polycarbonate (PC) Market