
 Global Exterior Architectural Coatings Market | 2026-2036
Global Exterior Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Exterior Architectural Coatings Market Analysis
Performance-based maintenance contracts and color-matching subscription services is hardening as a distinct revenue layer in exterior coatings. The Sherwin-Williams Company leverages its controlled distribution network to sustain margin capture in professional contractor channels. PPG Industries, Inc. anchors its position through R&D intensity in weatherable resin chemistry. AkzoNobel N.V. differentiates via geographic dominance in European decorative specifications.
Exterior architectural coatings are protective and decorative film-forming systems applied to building substrates, typically comprising binders, pigments, solvents or water carriers, and functional additives engineered to resist UV degradation, moisture ingress, and thermal cycling for service lives exceeding ten years. Their primary purpose is to preserve structural integrity while enabling aesthetic customization across facades, trim, and exterior building elements. Water-based coatings lead volume globally due to regulatory compression of solvent-borne volatile organic compounds, though UV-cured technologies represent the fastest-growing technology segment for prefabricated cladding and modular construction. The residential application channel remains the deepest margin pool, as homeowner repurchase cycles and color refresh preferences generate recurring demand that commercial and institutional projects rarely replicate.
The US EPA regulates volatile organic compound content under architectural coatings rules, while the EU REACH framework and F-Gas Regulation constrain hydrofluorocarbon propellants and hazardous substance thresholds in imported formulations. China's MEE enforces dual carbon goals that compel domestic manufacturers toward low-emission water-based systems and energy-cured alternatives. India's BIS certification mandates product performance testing for exterior durability, shaping market access for both domestic producers and imported brands. Stakeholders must monitor accelerating regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
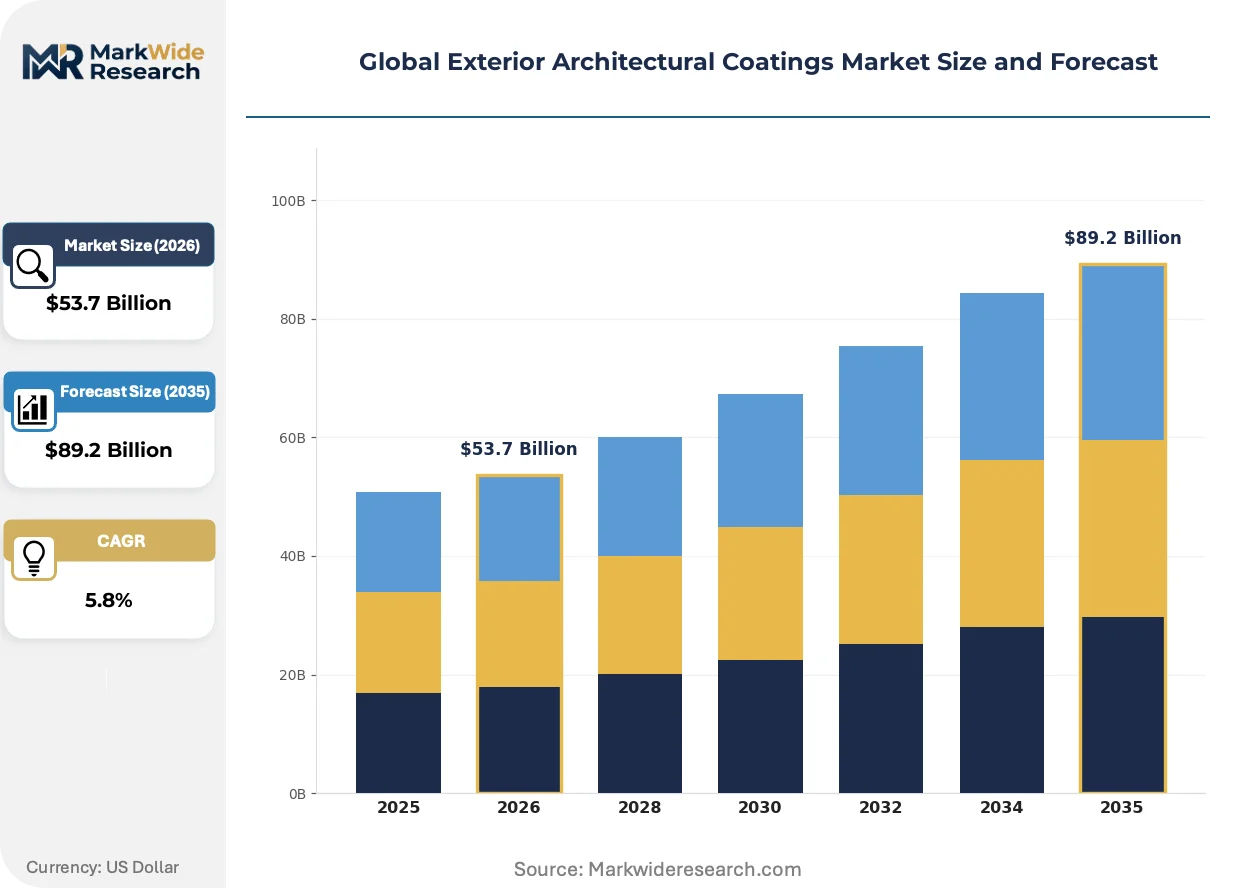
Market Dynamics
Water-based formulation mandates across major manufacturing jurisdictions are compressing solvent-borne capacity while concentrating procurement power among national distributors with certified low-VOC inventories.
Growth Catalysts
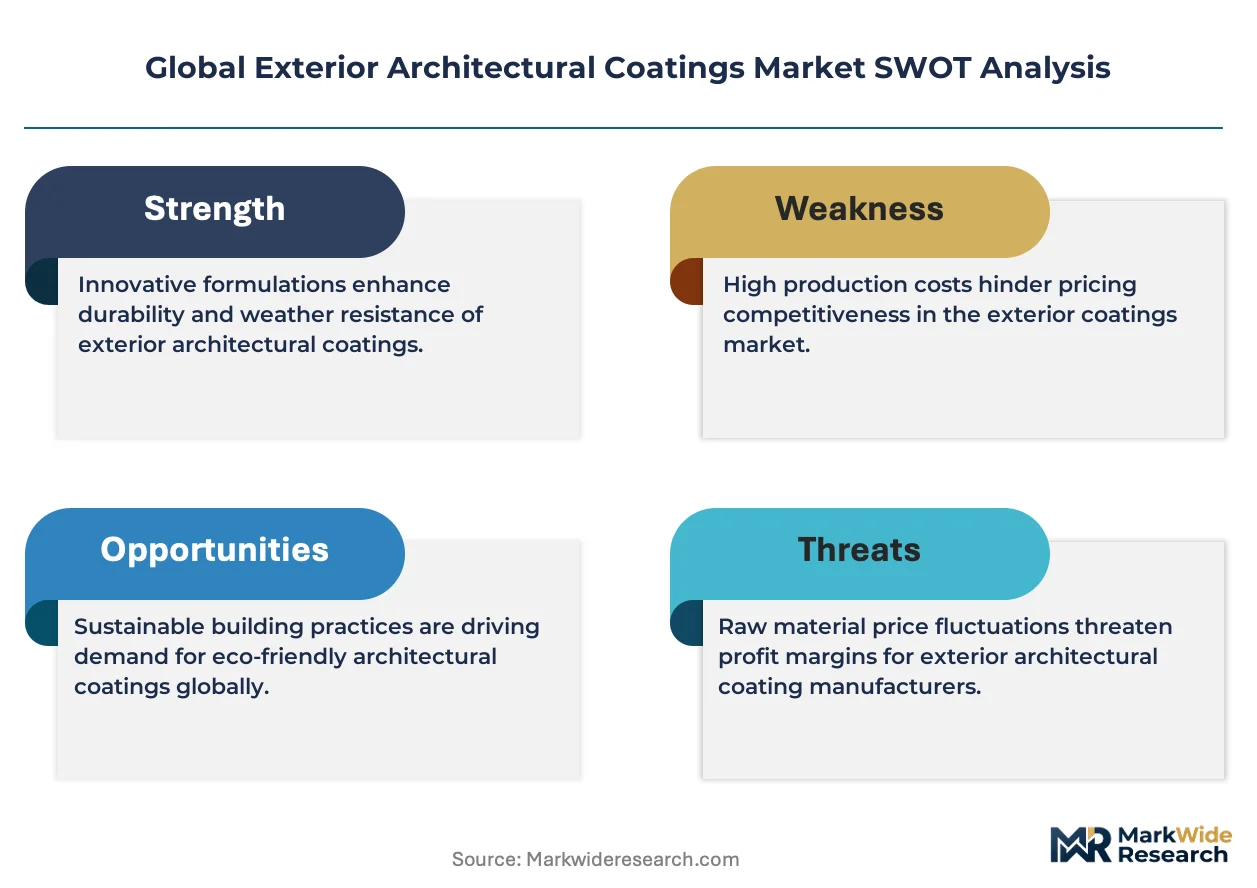
- Facade refurbishment cycles:Commercial building envelope renovation across the United States and Germany is accelerating specification of high-performance elastomeric systems with extended service warranties.
- GB standard enforcement:China's MEE volatile organic compound thresholds are compelling domestic manufacturers to retool toward water-based acrylic and polyurethane dispersions.
- UV-cured technology diffusion:Prefabricated cladding producers in Japan and South Korea are adopting energy-cured coatings for factory-applied finishes with instant handling properties.
Market Restraints
- Titanium dioxide supply concentration:Pigment sourcing dependence on Chinese sulfate-process capacity creates margin volatility for water-based white and pastel formulations.
- REACH authorization delays:ECHA substance evaluation timelines for novel biocidal actives extend product registration cycles by 18-24 months.
- Silicone resin cost structure:Organosilane feedstock exposure to natural gas and methanol pricing compresses profitability of premium weatherable topcoats.
Strategic Opportunities
- Indian urban corridors:Builder-contractor procurement consolidation in Mumbai, Bangalore, and Hyderabad corridors favors suppliers with regional tinting infrastructure and technical service presence.
- Performance-based maintenance:Subscription color-matching and scheduled recoating contracts offer recurring revenue capture from institutional property managers.
- Modular construction integration:Offsite manufacturing of building envelopes in the United Kingdom and Netherlands creates factory-applied coating specifications with precise film build control.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in weatherable resin design and additive synergies remains concentrated among retiring technical staff in Western European R&D centers.
- Multi-jurisdiction certification:Divergent BIS, EPA, and REACH testing protocols force parallel product development tracks with non-overlapping validation data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Exterior Architectural Coatings Market |
| Market Size in 2026 | $53.7 Billion |
| Market Size in 2035 | $89.2 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paints, Sealants, Stains, Primers Application: Residential, Commercial, Industrial, Institutional Coating Technology: Water-Based, Solvent-Based, Powder Coatings, UV-Cured End User: Contractors, Architects, Homeowners, Builders |
| Companies Covered | The Sherwin-Williams Company, PPG Industries, Inc., AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., Asian Paints Ltd., BASF SE, Jotun A/S, Kansai Paint Co., Ltd., RPM International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Exterior Architectural Coatings Market Emerging Trajectories
Self-cleaning and photocatalytic surface functionalities are migrating from premium niche to mid-tier specification, while digital color-matching tools compress the traditional sample-and-approval cycle between architects and applicators.
Photocatalytic titanium dioxide surface treatments are consolidating specification share in high-visibility commercial facades where soiling resistance reduces maintenance frequency. Property developers in the Netherlands and Singapore specify these systems for signature structures with cleaning-access constraints. The technology is consolidating demand around coating suppliers with in-house photocatalyst dispersion capabilities and validated performance warranties.
REACH F-Gas Regulation constraints on hydrofluorocarbon propellants are forcing aerosol format reformulation toward compressed gas and bag-on-valve alternatives. Aerosol touch-up and trim product manufacturers serving the European professional decorator channel face compressed timelines for propellant transition. The decorative maintenance segment is responding with concentrated liquid alternatives and trigger-spray formats that bypass propellant classification entirely.
Professional contractor channel consolidation is compressing the independent distributor tier as national buying groups aggregate purchasing across metropolitan markets. Mid-sized regional applicators in France and Italy now procure through centralized platforms that bypass traditional merchant relationships. This concentration is most visible in the French Ile-de-France and Italian Lombardy construction corridors where project scale favors direct manufacturer contracting.
Global Exterior Architectural Coatings Market Segmentation
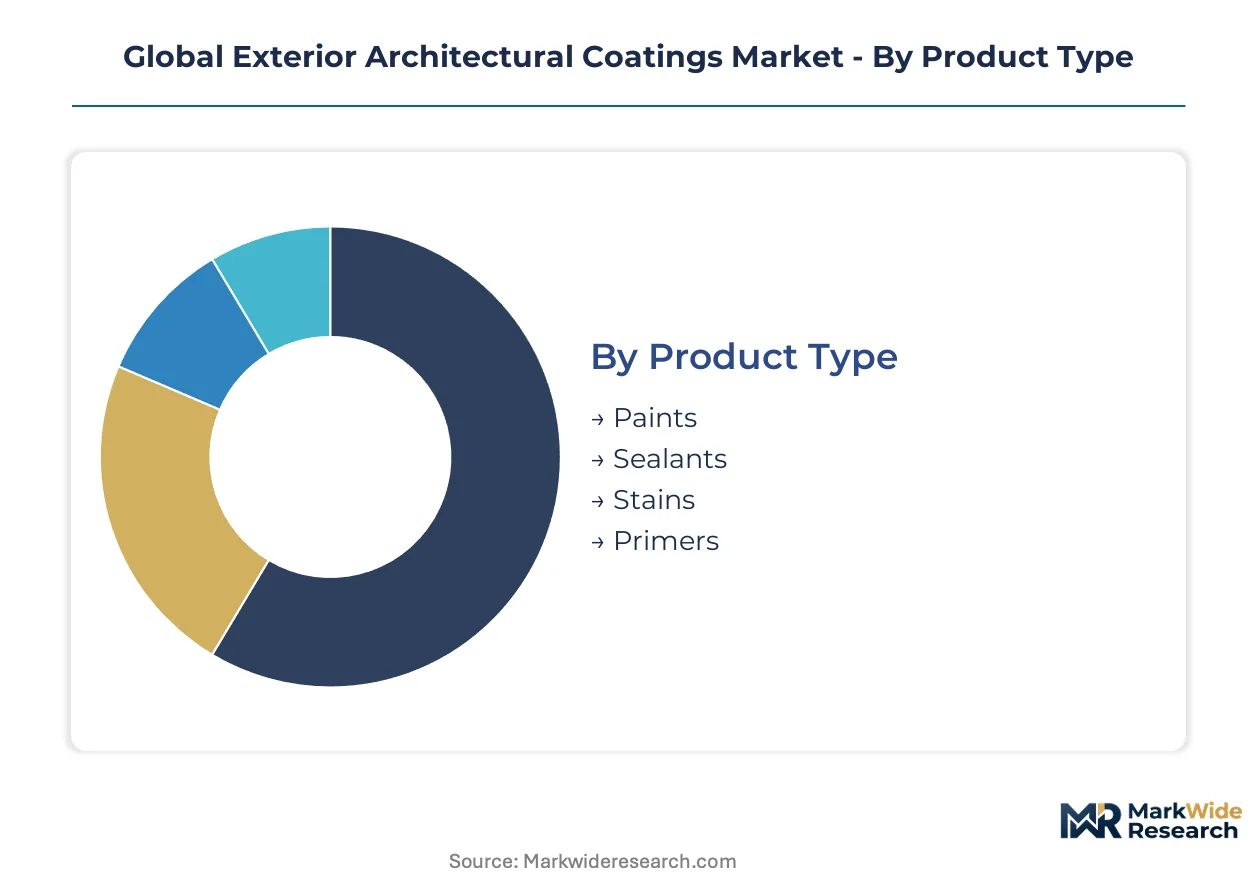
Segmentation in exterior architectural coatings reveals how formulation chemistry, application context, and procurement behavior create distinct competitive arenas. Each axis carries unique margin profiles and regulatory exposure that shape supplier strategy and channel investment priorities.
Product Type:
Product categories map directly to substrate protection requirements and reapplication cycles across building envelopes.
- Paints:Acrylic and elastomeric film-forming systems dominate volume through facade weatherproofing and aesthetic customization. Demand concentrates in North American residential repaint cycles where homeowner color refresh preferences drive recurring specification. Water-based acrylics capture share as EPA VOC thresholds tighten.
- Sealants:Polyurethane and silicone joint-sealing compounds bridge structural movement gaps while blocking moisture ingress. Commercial curtain wall installations across Germany and the Netherlands specify movement-capable formulations with validated durability warranties. Building envelope performance guarantees now mandate compatible sealant-coating systems.
- Stains:Penetrating oil-modified and water-borne systems protect wood substrates without film build. Deck and siding applications in US Pacific Northwest and Scandinavian markets favor semi-transparent finishes that preserve natural grain visibility.
- Primers:Bond-promoting and stain-blocking undercoats ensure topcoat adhesion across varied substrates. Multi-family residential new construction in India specifies alkali-resistant primers for fresh masonry surfaces.
Paints lead on scale; UV-curable topcoats lead on momentum in prefabricated cladding applications.
Application:
Building type determines performance specification intensity, warranty expectations, and procurement channel structure.
- Residential:Single-family and multi-family housing drives the deepest recurring demand through homeowner-driven repaint cycles. Color refresh preferences and DIY maintenance behavior generate margin-rich aftermarket sales that commercial projects rarely replicate. Professional contractor channels in US Sun Belt metros capture volume through builder partnerships.
- Commercial:Office, retail, and hospitality facades specify high-performance elastomeric and ceramic systems with extended service warranties. Refurbishment cycles across aging US and German commercial stock accelerate demand for weatherable topcoats with documented durability.
- Industrial:Manufacturing facilities and warehouses require chemical-resistant and high-build protective systems. Corrosion protection specifications for steel substrates in coastal Chinese manufacturing zones favor epoxy-modified water-based formulations.
- Institutional:Schools, hospitals, and government buildings balance durability with low-odor application constraints. Public procurement frameworks in France and Italy mandate certified low-VOC systems with verified emissions testing.
Residential leads on scale; commercial refurbishment leads on specification value per square meter.
Coating Technology:
Technology choice reflects regulatory compression, application efficiency, and substrate compatibility requirements.
- Water-Based:Acrylic and polyurethane dispersions carry the majority of global volume through regulatory-driven solvent displacement. China's MEE VOC enforcement and US EPA architectural coatings rules accelerate manufacturing retooling toward low-emission aqueous systems. Pigment compatibility and freeze-thaw stability remain formulation priorities.
- Solvent-Based:Alkyd and urethane systems retain specification in extreme climate exposure and rapid-cure requirements. Industrial maintenance applications in Russia and Middle Eastern markets specify solventborne corrosion protection where water-based alternatives fail on recoat windows.
- Powder Coatings:Thermoset epoxy and polyester systems serve factory-applied metal finishing with zero VOC emissions. Aluminum window and door manufacturers in Turkey and Vietnam integrate powder coating lines for durable architectural metalwork.
- UV-Cured:Energy-cured acrylate systems enable instant handling for prefabricated cladding and modular construction. Japanese and South Korean offsite manufacturing facilities specify UV coatings for factory-controlled film build and immediate stackability.
Water-based leads on scale; UV-cured systems are gaining share fastest in modular construction integration.
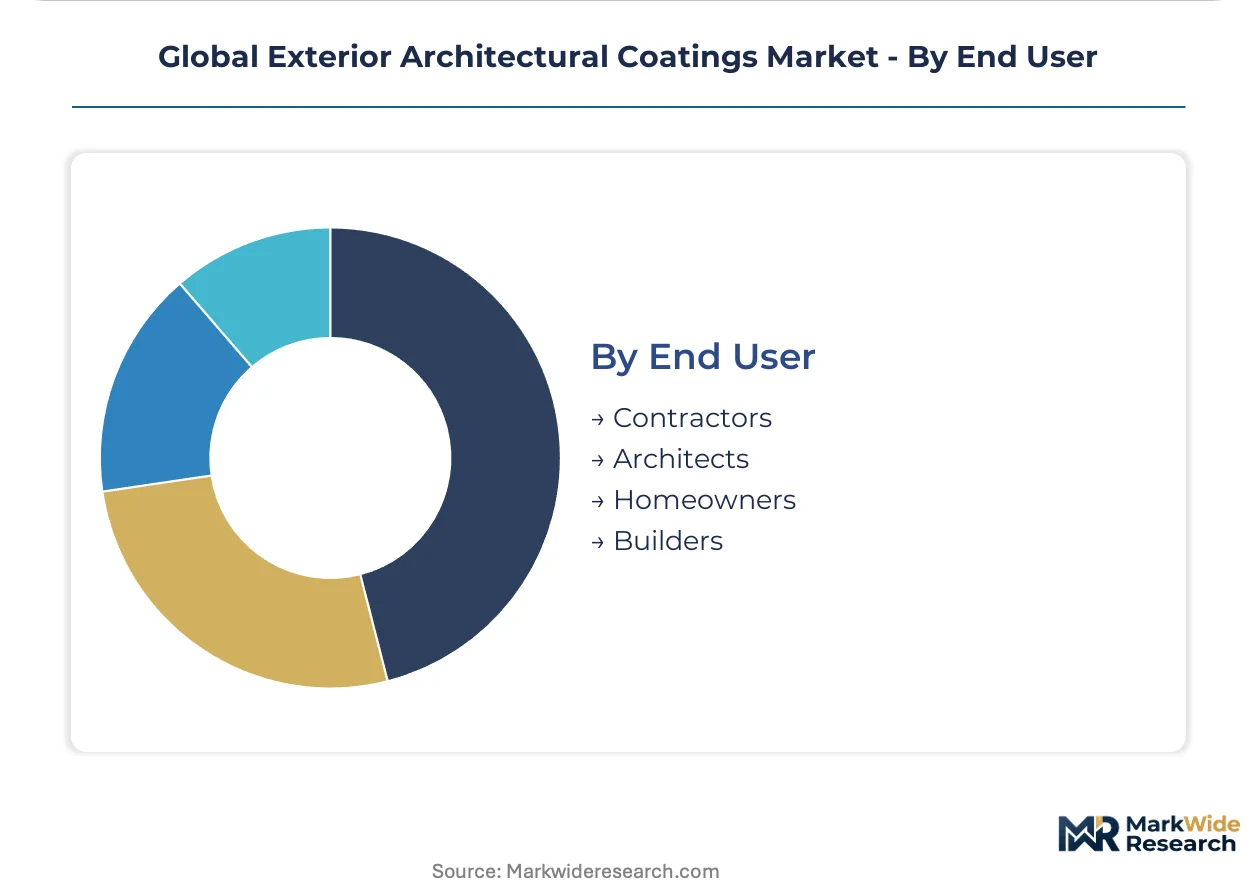
End User:
Procurement authority and technical sophistication vary sharply across buyer types, shaping channel strategy and service requirements.
- Contractors:Professional painting and finishing contractors aggregate project-level purchasing with specification influence. US national buying groups and French artisan cooperatives concentrate procurement power through centralized platforms that negotiate direct manufacturer terms.
- Architects:Design professionals specify coating systems within performance-based facade specifications. Dutch and Singaporean signature projects increasingly mandate photocatalytic self-cleaning functionalities with validated warranty support.
- Homeowners:Individual consumers drive DIY retail volume through color preference and convenience purchasing. Big-box home improvement channels in North American suburbs capture recurring repaint demand through loyalty programs and digital color matching.
- Builders:Production homebuilders and commercial developers specify coating packages at scale with cost and schedule priorities. Indian urban corridor builders in Mumbai and Bangalore consolidate procurement through regional distributor partnerships with tinting infrastructure.
Contractors lead on volume aggregation; architects lead on premium specification influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale and India's construction velocity diverge sharply from the refurbishment-driven demand patterns visible across mature Western markets. Each geography imprints distinct regulatory and procurement signatures on coating specifications.
United States
Commercial facade refurbishment across aging office stock in Chicago and New York accelerates elastomeric system specifications with extended warranties. EPA architectural coatings rules enforce VOC thresholds that compress solvent-borne capacity. Sun Belt metro contractor networks in Phoenix and Dallas concentrate procurement through national buying groups.
China
Urban residential construction corridors in Chengdu and Hangzhou generate volume for durable exterior paints with builder-contractor procurement consolidation. MEE dual carbon goals and GB standards on volatile organic compound emissions compel domestic manufacturers toward water-based acrylic dispersions. Yangtze River Delta manufacturing bases retool production lines to meet tightening formulation requirements.
Germany
Commercial building envelope renovation drives specification of high-performance weatherable topcoats across aging Frankfurt and Munich office stock. ECHA REACH framework and F-Gas Regulation constrain hydrofluorocarbon propellants and hazardous substance thresholds in imported formulations. Bavarian and North Rhine-Westphalia industrial clusters concentrate technical service infrastructure for facade refurbishment projects.
India
Mumbai, Bangalore, and Hyderabad urban corridors intensify builder-contractor procurement of durable exterior paints for multi-family residential construction. BIS certification mandates product performance testing for exterior durability, shaping market access for domestic producers and imported brands. Western and Southern regional distributor partnerships with tinting infrastructure capture consolidating demand.
Japan
Prefabricated cladding producers adopt UV-cured coatings for factory-applied finishes with instant handling properties. METI industrial standards shape quality benchmarks for offsite manufacturing integration. Kanto and Kansai manufacturing zones concentrate energy-cured technology adoption for modular construction specifications.
Global Exterior Architectural Coatings Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation-intensive players capturing specification value while toll manufacturers serve volume tiers. The vendor base concentrates around three strategic archetypes: integrated resin-to-coating multinationals, regional decorative specialists with controlled distribution, and technology licensors supplying modular construction integrators. Competitive positioning hardens through M&A-driven portfolio diversification and geographic expansion into Indian and Southeast Asian urban corridors.
Within the integrated multinational tier, The Sherwin-Williams Company and PPG Industries, Inc. exemplify divergent channel strategies, with one anchoring professional contractor networks and the other emphasizing R&D intensity in weatherable resin chemistry. AkzoNobel N.V. occupies a position representing European decorative specification dominance through geographic concentration. These three entities collectively illustrate how scale, distribution control, and regional specialization partition competitive terrain across residential repaint, commercial refurbishment, and industrial maintenance segments.
| Leading Market Players |
|---|
| The Sherwin-Williams Company |
| PPG Industries, Inc. |
| AkzoNobel N.V. |
| Nippon Paint Holdings Co., Ltd. |
| Asian Paints Ltd. |
| BASF SE |
| Jotun A/S |
| Kansai Paint Co., Ltd. |
| RPM International, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap decorative specialists across Southern Europe anchor supply discipline through generational ownership structures that resist margin-eroding volume chasing. Their concentrated control over regional tinting infrastructure feeds pricing power into contractor channels, while titanium dioxide sourcing exposure to Chinese sulfate-process capacity creates asymmetric cost pressure on water-based white formulations.
Pricing Analysis
Capacity additions in Southeast Asian water-based acrylic dispersion plants are reshaping price floors for standard-grade exterior paints. Three-tier pricing structure across premium elastomeric systems, standard acrylic formulations, and economy-grade builder packages differentiates on weatherability warranty length and VOC certification tier. Cost compression in economy tiers is intensifying because Indian builder-contractor procurement consolidation extracts volume discounts. Homeowners in North American DIY channels show least price sensitivity, while commercial property managers in European refurbishment markets prioritize lifecycle cost over unit price.
Supply Chain Analysis
Titanium dioxide pigment supply rests on Chinese sulfate-process capacity, German chloride-process specialty production, and Ukrainian feedstock exposure. Organosilane feedstocks for silicone resin binders draw from German and Japanese petrochemical complexes, while acrylic monomer supply anchors in US Gulf Coast and Northeast Asian crackers. Single-source vulnerability concentrates in Chinese TiO2 sulfate-process expansion decisions. Distribution runs through national buying groups in US Sun Belt metros, regional distributor partnerships in Indian urban corridors, and direct manufacturer contracting for European commercial refurbishment projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The exterior architectural coatings market functions as a stable compounder, with facade refurbishment cycles across aging commercial stock in the United States and Germany generating predictable specification demand that smooths volatility.
For Market Incumbents: Hedge titanium dioxide cost volatility through captive supply agreements with chloride-process producers in Germany and long-term offtake structures with emerging sulfate-process capacity in Saudi Arabia. Deepen backward integration into weatherable resin chemistry to defend margin position against specialty chemical feedstock price swings. Prioritize certification investment for India's BIS exterior durability testing to preempt market access friction. For New Entrants and Emerging Players: National buying groups in US metropolitan markets offer the most penetrable channel entry point for water-based system specialists lacking legacy distributor relationships. Target Indian urban corridor builder-contractor procurement through regional tinting infrastructure partnerships in Mumbai and Bangalore. Pursue photocatalytic self-cleaning functionality licensing from Japanese METI-validated technology holders to differentiate specification influence. For Investors and Strategic Acquirers: Valuations sit cheapest among European family-owned mid-cap decorative specialists with concentrated regional tinting infrastructure and underexploited Indian corridor expansion potential. Five-to-ten year viability hinges on water-based formulation transition completion and modular construction integration capture. Monitor Chinese MEE dual carbon goal enforcement stringency as the primary inflection signal for domestic manufacturing retooling urgency and import substitution opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Weatherable Resin Chemistry | Captures margin from silicone and polyurethane dispersion supply currently dominated by German and Japanese petrochemical specialists. |
| Regional Tinting Infrastructure Expansion | Secures builder-contractor procurement consolidation in Indian urban corridors where BIS certification mandates shape market access. |
| Photocatalytic Self-Cleaning Technology Licensing | Addresses Dutch and Singaporean commercial facade specifications where soiling resistance reduces maintenance frequency. |
| Long-Term Supply Agreement with TiO2 Producers | Mitigates pigment sourcing dependence on Chinese sulfate-process capacity that creates margin volatility for white formulations. |
| UV-Cured Coating Platform Development | Captures factory-applied specification demand from Japanese and South Korean prefabricated cladding producers. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build grounded demand estimates. Primary fieldwork engaged formulation chemists at Western European R&D centers, procurement leads at US national buying groups, technical service directors at Indian regional distributors, and plant managers at Yangtze River Delta manufacturing bases. Secondary validation drew from EPA architectural coatings rulemakings, ECHA REACH substance evaluations, China MEE dual carbon policy disclosures, Indian BIS certification registries, and customs trade data on titanium dioxide and organosilane feedstock flows. Bottom-up project pipeline analysis and top-down macro construction spend triangulation anchored volume and value outputs.
Segment-weighting applied technology type, application channel, and regional regulatory cluster as primary stratification dimensions across the modeling period. Water-based, solvent-based, powder, and UV-cured technology shares were modeled against MEE and EPA enforcement timelines. Residential, commercial, industrial, and institutional application splits tracked refurbishment cycle intensity and new construction velocity by geography. CAGRs derived from regression against construction spend, regulatory phase-in schedules, and technology substitution curves, with cross-validation against historical coating consumption elasticities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Chinese dual carbon policy enforcement stringency, titanium dioxide capacity expansion decisions, and modular construction adoption rates in European offsite manufacturing. Forecasts reflect documented assumptions on regulatory phase-in timelines, feedstock price trajectories, and channel consolidation velocity. A small set of named triggers—MEE VOC threshold tightening pace, REACH authorization delays for novel biocidal actives, and Indian urban corridor construction permit issuance—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Mosquito-Repellent Paints Market
Paints & Coatings
Global Construction Paints and Coatings Market
Paints & Coatings
India Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Acrylic Paints Market
Paints & Coatings
United Arab Emirates (UAE) Paints and Coatings Market
Paints & Coatings
Nigeria Paint and Protective Coatings Market
Paints & Coatings
Automotive Paints and Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Market
Paints & Coatings
Paint Thinner Market
Paints & Coatings
Anti-Fungal and Anti-Bacterial Paints Market
Paints & Coatings
Bio-Based and Low VOC Paints Market