
 Glass Mat Thermoplastic Market | 2026-2036
Glass Mat Thermoplastic Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Mat Thermoplastic Market Analysis
Continuous fiber-reinforced thermoplastic processing is reconfiguring composite manufacturing economics by enabling sub-60-second cycle times and end-of-life recyclability. SABIC leverages its upstream polymer integration to control resin feedstock costs across polypropylene and polyamide grades. BASF SE anchors European supply through its Ludwigshafen production complex, while Hanwha Advanced Materials competes on scale from its Asian manufacturing base.
Glass mat thermoplastic consists of chopped or continuous glass fibers impregnated with a thermoplastic matrix, typically polypropylene or polyamide, formed under heat and pressure into semi-structural sheets with specific flexural strength exceeding 200 MPa. The material serves primarily as a metal replacement in weight-sensitive applications requiring impact resistance and design freedom. Polypropylene dominates volume due to its cost position and established automotive recycling streams, while polyamide captures margin in under-hood and electrical enclosure segments where thermal resistance thresholds exceed 150°C. Application demand clusters in automotive interiors, where OEMs specify GMT for door panels, headliners, and load floors to meet fleet efficiency targets.
EPA fuel economy standards in the United States and EU Green Deal material circularity requirements are tightening specifications for automotive interior substrates, directly expanding addressable demand for recyclable thermoplastic composites. REACH compliance in Europe and GB standards in China govern glass fiber surface chemistry and volatile organic compound emissions from processing, creating differentiated compliance burdens by geography. Stakeholders must monitor evolving automotive platform electrification timelines, as battery enclosure thermal management specifications will determine whether polyamide displaces polypropylene in next-generation vehicle architectures.
Market Dynamics
Continuous fiber-reinforced thermoplastic processing is compressing automotive component cycle times below 60 seconds, forcing metal stamping operations to defend their cost position against recyclable composite substitution. This manufacturing velocity advantage is reconfiguring supplier selection criteria across European and Asian automotive platforms.
Growth Catalysts
- EU Green Deal material mandates:The EU Green Deal's circular economy requirements are accelerating metal-to-plastic substitution in automotive interiors across German manufacturing corridors.
- Automotive OEM lightweighting:Fleet efficiency targets under EPA fuel economy standards are expanding specification of glass mat thermoplastic for door panels and load floors in North American vehicle programs.
- Polypropylene recycling infrastructure:Established automotive recycling streams for polypropylene matrix resins are lowering lifecycle cost calculations for GMT versus thermoset alternatives.
Market Restraints
- Glass fiber supply concentration:Chopped and continuous glass fiber production concentrates in Chinese and European manufacturing bases, exposing converters to freight cost volatility and geopolitical supply friction.
- Polyamide resin cost structure:Caprolactam feedstock price sensitivity for polyamide grades compresses margins in under-hood applications requiring thermal resistance above 150°C.
- Thermoset substitution persistence:Sheet molding compound retains cost advantages in low-volume automotive programs where GMT tooling investments cannot be amortized across sufficient production runs.
Strategic Opportunities
- Battery enclosure thermal management:Electric vehicle platform electrification timelines are creating specification windows for polyamide-based GMT in battery housing applications where thermal conductivity requirements exceed polypropylene capabilities.
- REACH-compliant surface chemistry:ECHA registration requirements for glass fiber sizing agents are favoring European compounders with in-house silane chemistry expertise over import-dependent competitors.
- Direct-to-Tier-1 digital channels:Automotive material specification platforms are compressing distributor layers, enabling compounders to capture margin previously allocated to regional distribution networks.
Industry Challenges
- Continuous fiber processing expertise:The sub-60-second compression molding cycle requires operators trained in thermoplastic rheology and fiber orientation control, creating talent scarcity in regions transitioning from thermoset operations.
- Platform certification timelines:Automotive OEM validation protocols for interior substrate flammability and fogging performance extend 18-24 months, delaying revenue recognition for new compound formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Mat Thermoplastic Market |
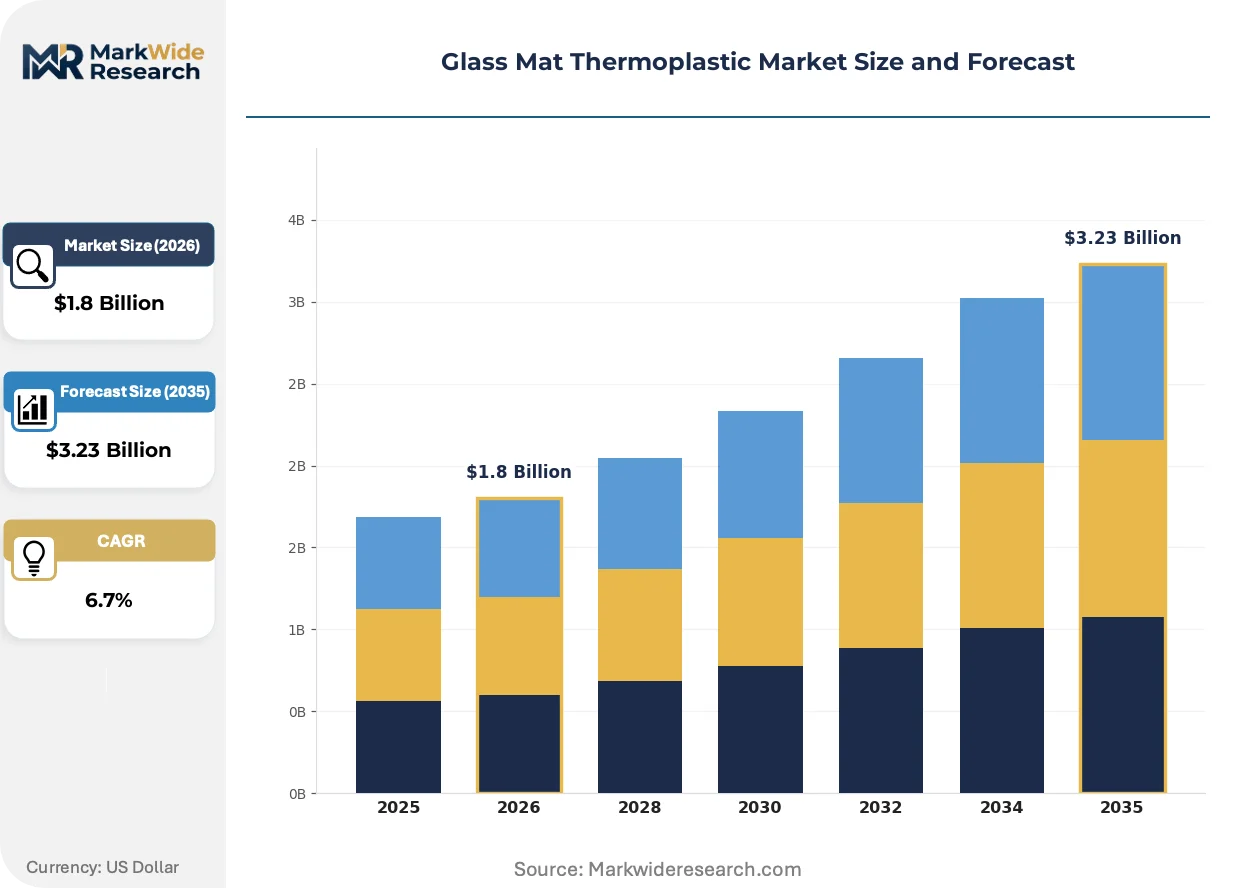
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyamide, Thermoplastic Polyurethane, Polyethylene Application: Automotive Interiors, Aerospace Components, Electrical Enclosures, Consumer Goods End User: OEMs, Tier-1 Suppliers, Fabricators, Manufacturers Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | SABIC, BASF SE, Quadrant Plastic Composites AG, Cytec Solvay Group, Royal DSM, Hanwha Advanced Materials, RTP Company, Mitsubishi Chemical Group, JFE Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Mat Thermoplastic Market Emerging Trajectories
Processing technology advances and regulatory material mandates are converging to displace conventional metal and thermoset applications across transportation and industrial end-uses. These shifts are compressing supplier qualification cycles and rewarding integrated resin-to-composite capabilities.
Hybrid GMT-LFT processing is virtualizing the boundary between glass mat and long fiber thermoplastic categories. Tier-1 suppliers in Stuttgart and Wolfsburg are adopting these hybrid systems to reduce tooling inventory across vehicle platform variants. The technology is virtualizing traditional segmentation between semi-structural and structural composite applications, enabling single-line flexibility that metal stamping cannot replicate.
REACH Annex XVII restrictions on silane-based fiber sizing chemistry are forcing reformulation of glass fiber surface treatments across European compounding operations. The industrial consequence is elevated R&D expenditure for ECHA-compliant sizing systems that maintain fiber-matrix adhesion. German automotive suppliers are responding by consolidating specification approval around pre-qualified European compounders with validated alternative chemistries.
Automotive OEMs are unbundling material specification from legacy systems integrator contracts, creating direct procurement relationships with specialized thermoplastic composite suppliers. This channel disintermediation is most visible in Volkswagen Group and BMW sourcing reorganizations, where material scientists now interface directly with compounders rather than through Tier-1 intermediaries. The shift compresses feedback loops for formulation customization but exposes compounders to OEM price negotiation pressure previously absorbed by systems integrators.
Glass Mat Thermoplastic Market Segmentation
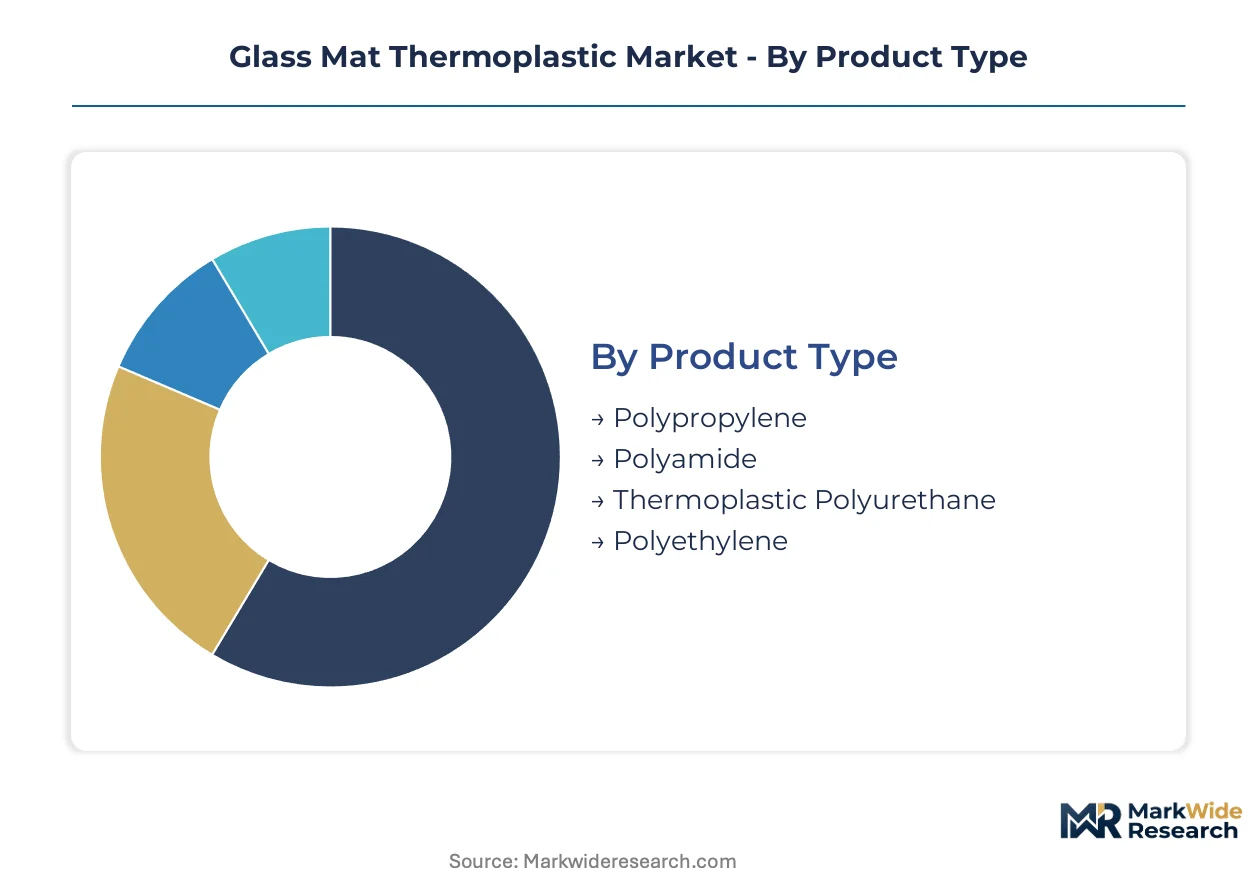
Segmentation in the Glass Mat Thermoplastic Market reveals how resin chemistry, application thermal requirements, and procurement channel economics create distinct competitive arenas with varying margin profiles and qualification timelines. Understanding these segment boundaries enables suppliers to allocate R&D and capacity investments toward positions where cycle-time advantages compound most effectively.
Product Type:
Cycle-time economics vary dramatically by matrix resin, with polypropylene formulations achieving sub-60-second molding cycles while polyamide grades require extended thermal management protocols that compress line throughput by 15-25%.
- Polypropylene:Chopped glass fiber reinforcement within isotactic polypropylene homopolymer delivers flexural modulus above 5 GPa at densities below 1.2 g/cm³. Automotive OEMs in Stuttgart and Wolfsburg specify this grade for door panels and load floors where established recycling streams lower lifecycle cost calculations. EPA fuel economy standards accelerate specification velocity for this segment.
- Polyamide:Continuous glass fiber impregnation within PA6 or PA66 matrices achieves thermal resistance thresholds exceeding 150°C required for under-hood battery enclosure applications. Electric vehicle platform electrification in Germany and China is expanding addressable demand for this grade despite caprolactam feedstock price sensitivity.
- Thermoplastic Polyurethane:Elastomeric matrix systems offering impact absorption and surface aesthetics for consumer electronics housings and sporting equipment components.
- Polyethylene:Cost-positioned grades for industrial packaging and material handling applications where chemical resistance outweighs mechanical performance requirements.
Polypropylene anchors the volume base while polyamide gains share at the steepest rate.
Application:
Margin stratification across applications correlates directly with thermal performance thresholds and automotive OEM qualification burden, with aerospace and electrical segments commanding premium pricing against standardized interior substrates.
- Automotive Interiors:Door panels, headliners, and load floors requiring flammability compliance to FMVSS 302 and fogging performance to SAE J1756. Tier-1 suppliers in Germany's manufacturing corridor source this segment for series production programs under EU Green Deal material mandates. OEM lightweighting targets under EPA standards expand North American specification velocity.
- Aerospace Components:Semi-structural interior panels and cargo liners requiring FAR 25.853 fire resistance certification and specific strength metrics above 150 MPa. Boeing and Airbus qualification protocols extend 24-36 months, creating substantial barriers to entry for non-integrated compounders.
- Electrical Enclosures:Junction boxes, battery housings, and power distribution modules where IEC 60695 glow-wire ignition thresholds govern material selection. REACH-compliant surface chemistry requirements favor European compounders with validated alternative sizing systems.
- Consumer Goods:Luggage shells, furniture components, and appliance housings where cost position and design freedom outweigh performance certification burden.
Automotive interiors dominate shipment volumes while aerospace components deliver the steepest margin expansion trajectory.
End User:
Procurement authority concentration determines pricing power distribution, with OEM direct relationships compressing distributor margins while Tier-1 intermediaries absorb formulation customization costs.
- OEMs:Volkswagen Group and BMW sourcing reorganizations now place material scientists in direct interface with compounders, bypassing traditional systems integrator layers. This channel disintermediation compresses feedback loops for formulation customization but exposes suppliers to price negotiation pressure previously absorbed by Tier-1 intermediaries.
- Tier-1 Suppliers:Continental, Faurecia, and Magna maintain specification influence through integrated interior system contracts, though OEM unbundling trends erode this position progressively.
- Fabricators:Specialized converters operating compression molding cells for niche automotive programs and industrial applications where tooling amortization constraints exclude integrated Tier-1 participation.
- Manufacturers:Industrial end-users in material handling, construction equipment, and agricultural machinery specifying GMT for proprietary component production.
Tier-1 suppliers retain the largest procurement volume while OEM direct channels expand most rapidly.
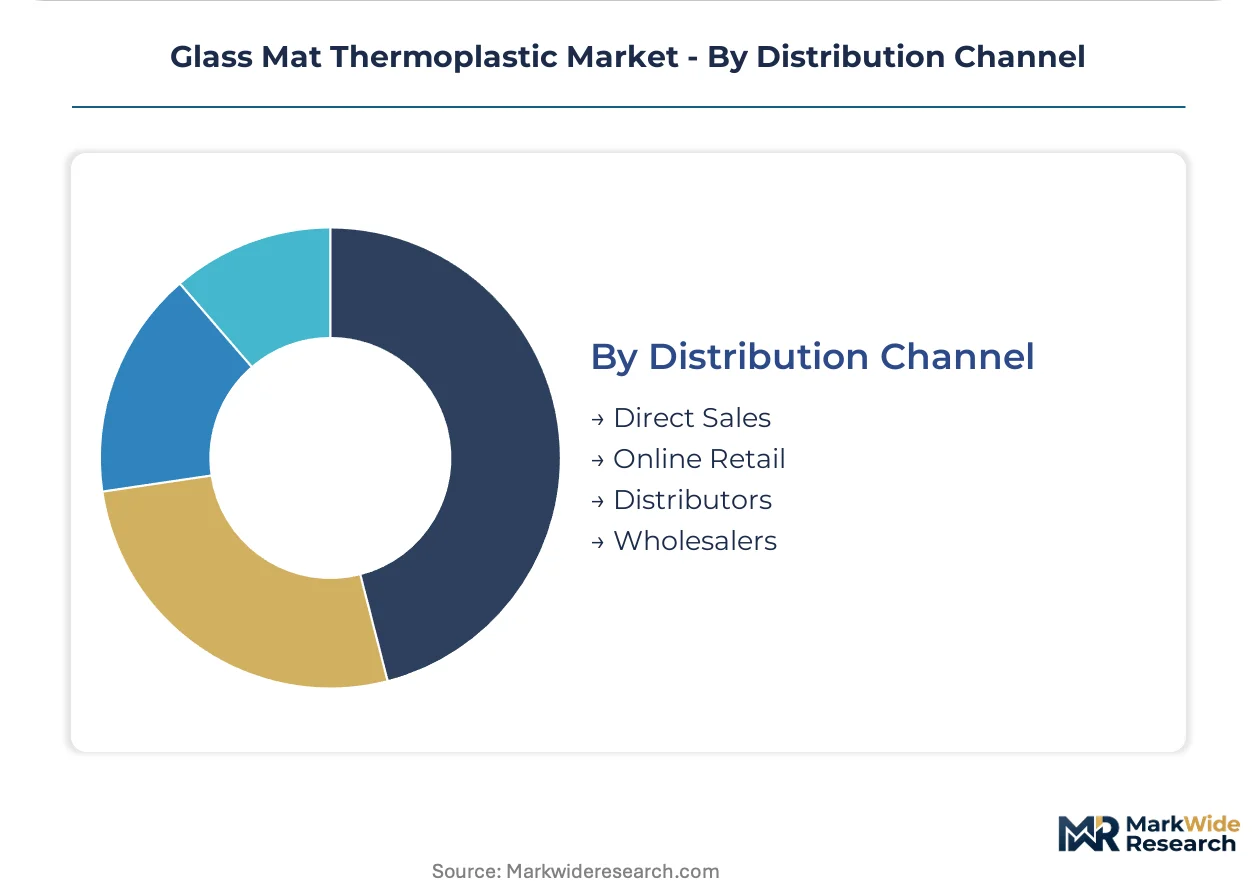
Distribution Channel:
Channel economics reflect lot size requirements and technical service intensity, with direct sales capturing formulation-intensive accounts while distributors serve fragmented regional demand.
- Direct Sales:Technical service teams co-develop formulations with OEM material scientists and Tier-1 application engineers. German automotive suppliers consolidate specification approval around pre-qualified European compounders with REACH-compliant sizing expertise.
- Distributors:Regional inventory positioning for standard polypropylene grades serving fabricators and manufacturers with shorter lead time requirements and lower volume thresholds.
- Online Retail:Emerging channels for research quantities and prototype development, though automotive qualification protocols limit commercial penetration.
- Wholesalers:Volume aggregation for industrial applications in construction and agriculture where material specifications remain standardized.
Direct sales command the value concentration while distributor channels maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs export GMT interior panels to assembly plants across the United States and China, establishing a transatlantic-Pacific trade corridor that concentrates value capture in Stuttgart and Wolfsburg.
United States
EPA fuel economy standards drive OEM lightweighting programs for door panels and load floors. NHTSA flammability protocols under FMVSS 302 govern interior substrate specifications. Detroit's automotive manufacturing corridor sources GMT through Tier-1 suppliers for series production programs.
Germany
EU Green Deal material circularity mandates accelerate metal-to-plastic substitution in vehicle interiors. ECHA REACH compliance requirements for glass fiber sizing chemistry favor domestic compounders. The Stuttgart-Wolfsburg manufacturing axis anchors European GMT demand through Volkswagen Group and BMW procurement.
China
Dual carbon goals and GB standards for automotive emissions tighten material efficiency requirements for domestic OEMs. MIIT regulations on new energy vehicle production quotas expand battery enclosure applications. The Yangtze River Delta hosts compression molding operations supplying BYD and NIO platforms.
Japan
METI carbon neutrality roadmaps pressure automotive suppliers to reduce lifecycle emissions from interior components. JIS standards govern composite mechanical performance specifications. Toyota City and Nagoya manufacturing clusters source GMT for hybrid vehicle lightweighting initiatives.
South Korea
Corporate average fuel economy standards from the Ministry of Trade, Industry and Energy drive Hyundai-Kia lightweighting investments. MFDS chemical safety assessments apply to glass fiber surface treatments. The Busan-Ulsan industrial corridor hosts GMT compounding for export-oriented vehicle programs.
Glass Mat Thermoplastic Market Vendor Landscape
On the supply side, the industry is consolidating around integrated resin producers and specialized compounders with validated automotive qualification histories. Three archetypes dominate: petrochemical majors with captive polymer feedstock, European compounders with REACH-compliant sizing expertise, and Asian fabricators competing on scale. Capacity expansion and strategic partnerships represent the primary competitive vectors as suppliers position for electric vehicle platform certifications.
Among petrochemical-integrated majors, SABIC and BASF SE exemplify the upstream-control archetype, leveraging polymer production to manage resin cost volatility. Hanwha Advanced Materials occupies a position within the Asian scale-driven tier, supplying standardized grades to high-volume automotive programs. These three anchors illustrate how geographic specialization and feedstock integration create differentiated competitive positions across the value chain.
| Leading Market Players |
|---|
| SABIC |
| BASF SE |
| Quadrant Plastic Composites AG |
| Cytec Solvay Group |
| Royal DSM |
| Hanwha Advanced Materials |
| RTP Company |
| Mitsubishi Chemical Group |
| JFE Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
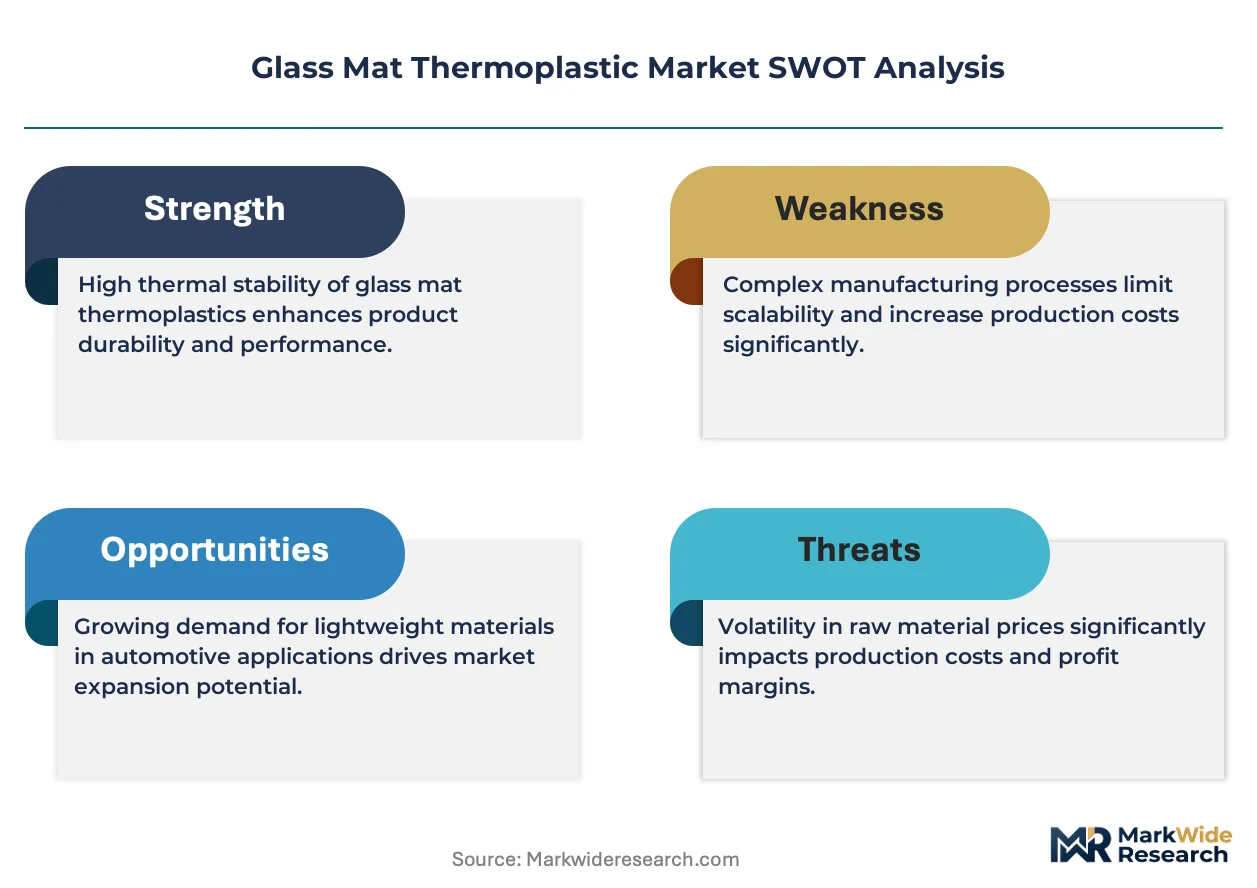
Caprolactam feedstock price volatility for polyamide grades determines both the spread between premium and standard tiers and the geographic shape of resin sourcing networks. This single-input sensitivity compresses margins in under-hood applications while forcing compounders toward backward integration or long-term offtake structures.
Pricing Analysis
Technology-generation pricing gaps separate established polypropylene formulations from emerging polyamide battery enclosure grades and next-generation hybrid GMT-LFT systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by thermal performance threshold and automotive OEM qualification status. Cost compression in polypropylene grades is intensifying because established recycling streams attract new converter capacity. Tier-1 suppliers exhibit the highest price sensitivity due to OEM transfer pricing pressure, while direct OEM relationships absorb premium for formulation customization.
Supply Chain Analysis
Tariff exposure between Chinese glass fiber producers and European compounders dominates supply chain risk calculations for the industry. Manufacturing concentrates in China, Germany, and South Korea, with chopped and continuous fiber production drawing from borosilicate raw material streams centered in Shandong Province. The supply chain rests on silane-based sizing chemistry dependencies subject to ECHA REACH Annex XVII restrictions. Distribution runs through direct technical sales for automotive qualification programs and regional distributors for standard industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ECHA REACH compliance requirements for glass fiber surface chemistry create switching costs that lock qualified compounders into long-term OEM specification cycles.
For Market Incumbents: Pre-empt thermoset substitution persistence by accelerating hybrid GMT-LFT processing investments in Stuttgart and Wolfsburg manufacturing corridors. Secure captive caprolactam supply or long-term resin offtake agreements to defend margin position against feedstock volatility. Consolidate specification approval relationships with Volkswagen Group and BMW material science teams before platform electrification timelines accelerate. For New Entrants and Emerging Players: Establish a beachhead in battery enclosure thermal management applications where polyamide grade demand outpaces qualified European supply. Target Chinese domestic OEMs under MIIT new energy vehicle quotas as the most penetrable geography, leveraging Yangtze River Delta compression molding infrastructure. Pursue direct-to-OEM digital specification channels to bypass entrenched Tier-1 distributor relationships. For Investors and Strategic Acquirers: EU Green Deal material circularity mandates reshape the acquisition landscape by elevating compounders with validated REACH-compliant sizing chemistries above import-dependent competitors. The five-to-ten-year viability window favors targets with integrated resin-to-composite capabilities and active automotive platform certifications. Monitor electric vehicle thermal management specification velocity as the signal indicating polyamide displacement of polypropylene in next-generation architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | Secures resin cost position for polyamide grades serving battery enclosure thermal management specifications. |
| REACH-Compliant Sizing Chemistry Investment | Locks qualification status with German automotive OEMs under ECHA Annex XVII restrictions. |
| Hybrid GMT-LFT Processing Scale-Up | Enables single-line flexibility across semi-structural and structural applications for Stuttgart Tier-1 suppliers. |
| Direct-to-OEM Digital Channel Development | Captures margin previously allocated to regional distribution networks in Volkswagen Group sourcing reorganizations. |
| Long-Term Resin Offtake Agreements | Hedges polypropylene feedstock volatility against EPA fuel economy standard-driven demand expansion. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier-1 supplier procurement leads, thermoplastic compounding plant managers, and ECHA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings from petrochemical majors, customs and trade data from German and Chinese export authorities, and automotive production databases tracking vehicle program specifications. Bottom-up volume estimates from compression molding cell capacity and top-down demand triangulation from OEM lightweighting targets were reconciled across the analysis window.
Demand-supply balance modeling anchored the forecast framework across the projection horizon. Segmentation dimensions included resin chemistry tier, automotive application thermal requirement, procurement channel structure, and regional manufacturing cluster. CAGRs were derived from production volume trajectories mapped against platform electrification timelines and regulatory compliance phase-ins. Industry-specific inputs incorporated EPA fuel economy standard stringency curves and EU Green Deal material mandate implementation schedules.
Stress conditions across caprolactam price volatility, glass fiber tariff regimes, and automotive platform certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about electric vehicle adoption velocity and REACH enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Decorative Glass Market
Glass
Mirrored Glass Market
Glass
United States Flat Glass Market
Glass
Foam Glass Market
Glass
Low Iron Glass Market
Glass
Silica Market
Glass
Spherical Silica Market
Glass
Optical Materials Market
Glass
Laboratory Glass Container Market
Glass
Patterned Glass Market
Glass
Global Glass Tempering System Market
Glass
Glass Prepreg Market
Glass
Glass Mat Market
Glass
Glass Grade Dolomite Market
Glass
Insulating Glass Market
Glass
Europe Silica Sand for Glass Making Market