
 Rosin Resin Market | 2026-2036
Rosin Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Rosin Resin Market Analysis
The EU Green Deal is decoupling European rosin resin procurement from fossil-derived alternatives. Eastman Chemical Company leverages backward integration into tall oil fractionation to secure feedstock certainty. Arakawa Chemical Industries anchors its position through specialized hydrogenated rosin derivatives for electronics-grade adhesives. Harima Chemicals Group competes on modified rosin capacity serving Asian coating formulators.
Rosin resin comprises abietic acid and pimaric acid derivatives extracted from pine oleoresin or tall oil pitch, functioning primarily as tackifiers, film-formers, and viscosity modifiers across industrial formulations. Gum rosin dominates volume flows due to established Chinese tapping infrastructure and lower processing overhead, while modified rosin commands margin premiums through esterification and disproportionation upgrades that expand thermal stability. The adhesives application segment leads value capture as hot-melt and pressure-sensitive formulations replace solvent-based systems, whereas electronics end-use demand is accelerating fastest on miniaturization-driven precision bonding requirements.
REACH registration in Europe, EPA TSCA oversight in the United States, and China's GB standards for industrial chemicals collectively constrain unverified feedstock entry and elevate compliance costs for uncertified producers. ECHA substance evaluation is tightening impurity thresholds for polycyclic aromatic content, redirecting formulation R&D toward refined distillation methods. Stakeholders must monitor regulatory divergence between bio-based certification schemes and conventional chemical registrations to anticipate which product grades retain cross-border market access.
Market Dynamics
REACH registration deadlines are compressing the European supplier base toward certified tall oil fractionators, while Chinese gum rosin infrastructure captures incremental coating and packaging demand through established tapping networks.
Growth Catalysts
- Hot-melt adhesive substitution:Solvent-based bonding systems face MEE emissions enforcement in China, redirecting formulators toward rosin ester tackifiers with lower volatile organic compound profiles.
- EU Green Deal bio-based mandates:Public procurement rules now require minimum renewable content thresholds in packaging adhesives, elevating disproportionated rosin derivatives above petroleum-based alternatives.
- Electronics miniaturization:Precision bonding requirements for semiconductor packaging and flexible circuit assembly are pulling hydrogenated rosin grades into high-purity flux formulations.
Market Restraints
- Crude tall oil supply concentration:Nordic pulp mill output limits constrain backward-integrated rosin resin producers dependent on captive fractionation feedstock.
- ECHA impurity thresholds:Polycyclic aromatic hydrocarbon limits under REACH substance evaluation are forcing costly distillation upgrades for uncertified gum rosin imports.
- Petroleum tackifier price volatility:C5/C9 hydrocarbon resin competition intensifies during crude oil price troughs, compressing rosin derivative margin premiums in commodity adhesives.
Strategic Opportunities
- India packaging expansion:FSSAI food-contact regulations and PLI scheme incentives for domestic manufacturing are opening demand for esterified rosin in carton sealing and lamination.
- Carbon accounting convergence:ISO 14067 product carbon footprint standards and EU CSRD disclosure requirements are creating certification premiums for mass-balance tall oil derivatives.
- 3D printing resin compatibility:Photocurable rosin-acrylate oligomers are penetrating stereolithography formulations for dental and jewelry casting applications.
Industry Challenges
- Distillation technician scarcity:Specialized fractionation operation expertise concentrates among aging workforces at legacy pine chemical facilities in Portugal and Brazil.
- Multi-standard compliance burden:Simultaneous GB standard registration, REACH dossier maintenance, and EPA TSCA inventory listing extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rosin Resin Market |
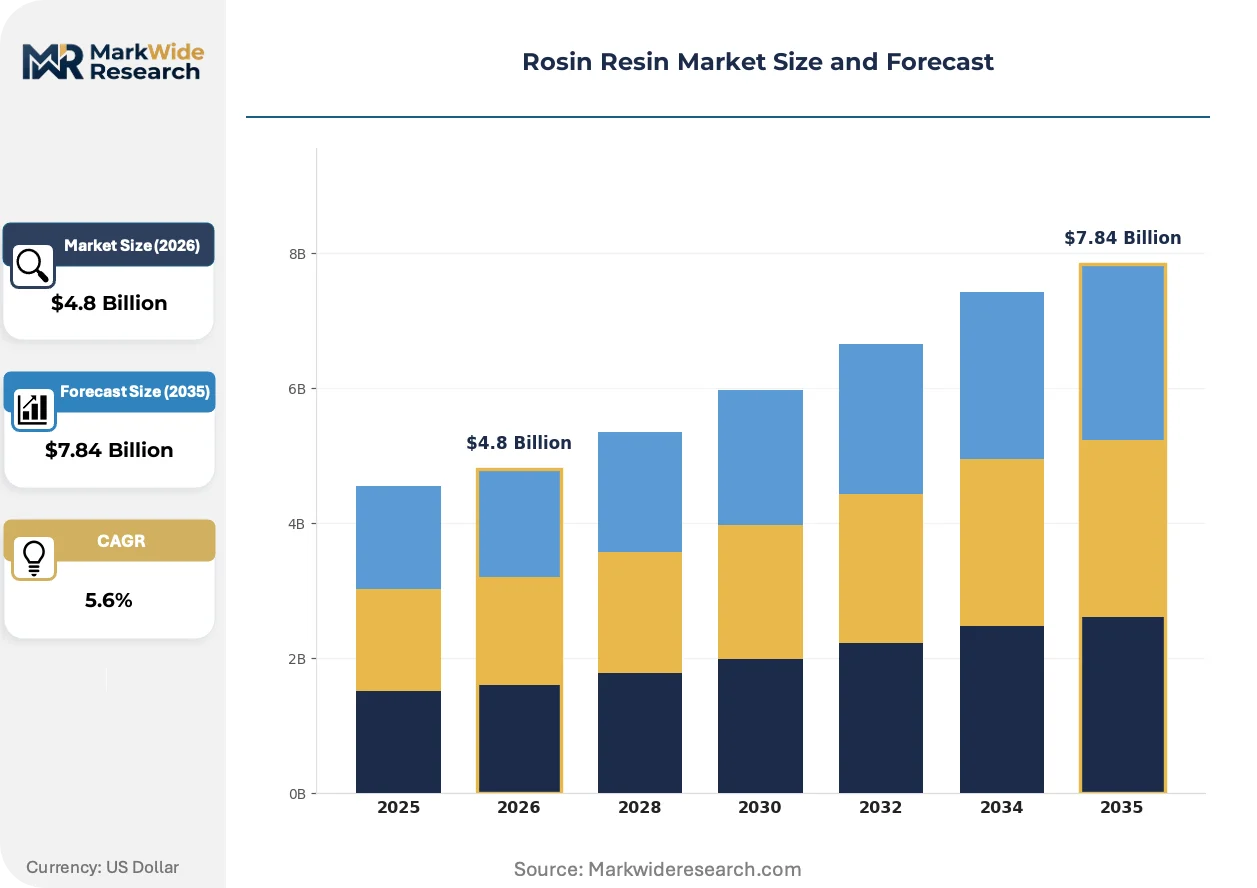
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrocarbon Rosin, Gum Rosin, Wood Rosin, Modified Rosin Application: Adhesives, Inks, Coatings, Cosmetics End User: Construction, Automotive, Packaging, Electronics Form: Solid, Liquid, Powder, Granule |
| Companies Covered | Eastman Chemical Company, Arakawa Chemical Industries, Harima Chemicals Group, Foreverest Resources, BaoLin, Kraton Corporation, DRT, Ingevity Corporation, Formosa Produce Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rosin Resin Market Emerging Trajectories
Formulation chemistry is pivoting toward thermal stability and low-color specifications as electronics and automotive adhesives displace commodity construction applications.
Hydrogenated rosin derivatives are absorbing demand from conventional gum rosin in pressure-sensitive adhesive tapes requiring oxidative stability. Electronics contract manufacturers in South Korea and Taiwan specify these grades for display bonding applications. The technology is absorbing volume that would otherwise flow to synthetic tackifiers, compressing petroleum resin pricing power in premium segments.
REACH substance evaluation under ECHA is tightening polycyclic aromatic hydrocarbon limits for industrial chemicals. European importers now demand third-party certified distillation certificates for Chinese gum rosin shipments. Coating formulators in Germany and the Netherlands are qualifying alternative tall oil feedstocks to preempt supply interruption risks.
Direct mill relationships are displacing spot market purchases among large adhesive compounders seeking mass-balance certification. Henkel and Bostik procurement teams now contract directly with Finnish and Swedish pulp mills for carbon-accounted tall oil pitch. This pattern is most visible in Nordic supply chains where CSRD disclosure requirements mandate Scope 3 emissions traceability.
Rosin Resin Market Segmentation
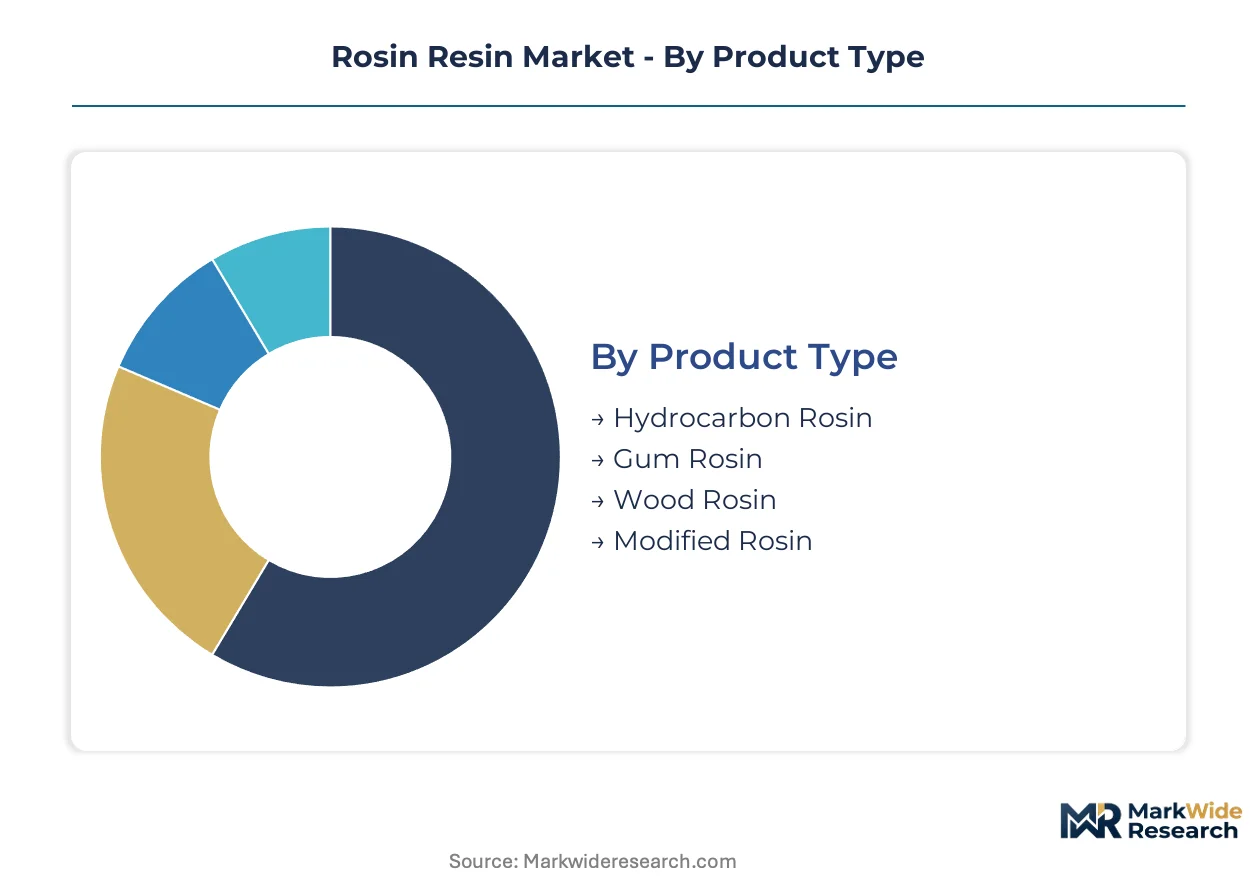
Rosin resin procurement decisions hinge on feedstock origin, thermal stability requirements, and regulatory compliance thresholds. Distinct processing intensities and certification burdens across product categories create divergent margin profiles and supplier consolidation patterns.
Product Type:
Capital intensity varies sharply across extraction and modification pathways, with hydrogenation and esterification demanding specialized reactor infrastructure.
- Gum Rosin:Direct oleoresin tapping from living pine stands yields unmodified abietic and pimaric acid mixtures with minimal processing overhead. Chinese tapping networks in Guangxi and Yunnan provinces supply volume to coating formulators facing REACH polycyclic aromatic thresholds.
- Modified Rosin:Esterification and disproportionation upgrades expand thermal stability and oxidative resistance for hot-melt adhesive specifications. South Korean electronics contract manufacturers specify hydrogenated grades for display bonding fluxes where color stability commands premium positioning.
- Hydrocarbon Rosin:Petroleum-derived C5/C9 fractions compete on price during crude oil troughs but face EU Green Deal bio-content mandates in public procurement.
- Wood Rosin:Stump extraction and solvent recovery from aged pine roots yields darker, higher-impurity grades concentrated in legacy Portuguese and Brazilian facilities.
Most installed capacity flows through Gum Rosin. Expansion is steepest in Modified Rosin.
Application:
Formulation complexity and regulatory exposure determine value capture, with food-contact and electronics specifications carrying the steepest compliance burdens.
- Adhesives:Hot-melt and pressure-sensitive formulations consume disproportionated rosin esters as tackifiers replacing solvent-based systems under MEE emissions enforcement. Henkel and Bostik procurement teams contract directly with Nordic pulp mills for carbon-accounted tall oil pitch.
- Coatings:Film-forming and viscosity modification applications in industrial and automotive finishes demand low-color specifications. German and Dutch formulators are qualifying alternative tall oil feedstocks to preempt supply interruption risks from ECHA substance evaluation.
- Inks:Offset and gravure printing applications utilize rosin-modified phenolic resins for gloss and adhesion.
- Cosmetics:Fragrance fixatives and emulsion stabilizers require pharmaceutical-grade distillation certificates.
Adhesives command the deepest supplier relationships. Coatings are climbing the fastest on sustainability-linked specification changes.
End User:
Precision requirements and traceability mandates segment procurement sophistication, with electronics and automotive demanding batch-level carbon accounting.
- Packaging:Carton sealing and lamination applications in India are expanding under FSSAI food-contact regulations and PLI scheme incentives for domestic manufacturing.
- Electronics:Semiconductor packaging and flexible circuit assembly pull hydrogenated rosin into high-purity flux formulations. Taiwan and South Korea contract manufacturers specify oxidative stability grades that compress petroleum resin pricing power.
- Construction:Commodity adhesives and sealants face petroleum tackifier competition during crude price troughs.
- Automotive:Interior bonding and NVH applications require low-emission certifications under evolving OEM sustainability scorecards.
Electronics concentrates the highest-margin demand. Packaging is gaining share fastest on emerging market manufacturing expansion.
Form:
Logistics economics and handling automation shape regional form preferences, with powder and granule formats reducing freight costs for distant supply chains.
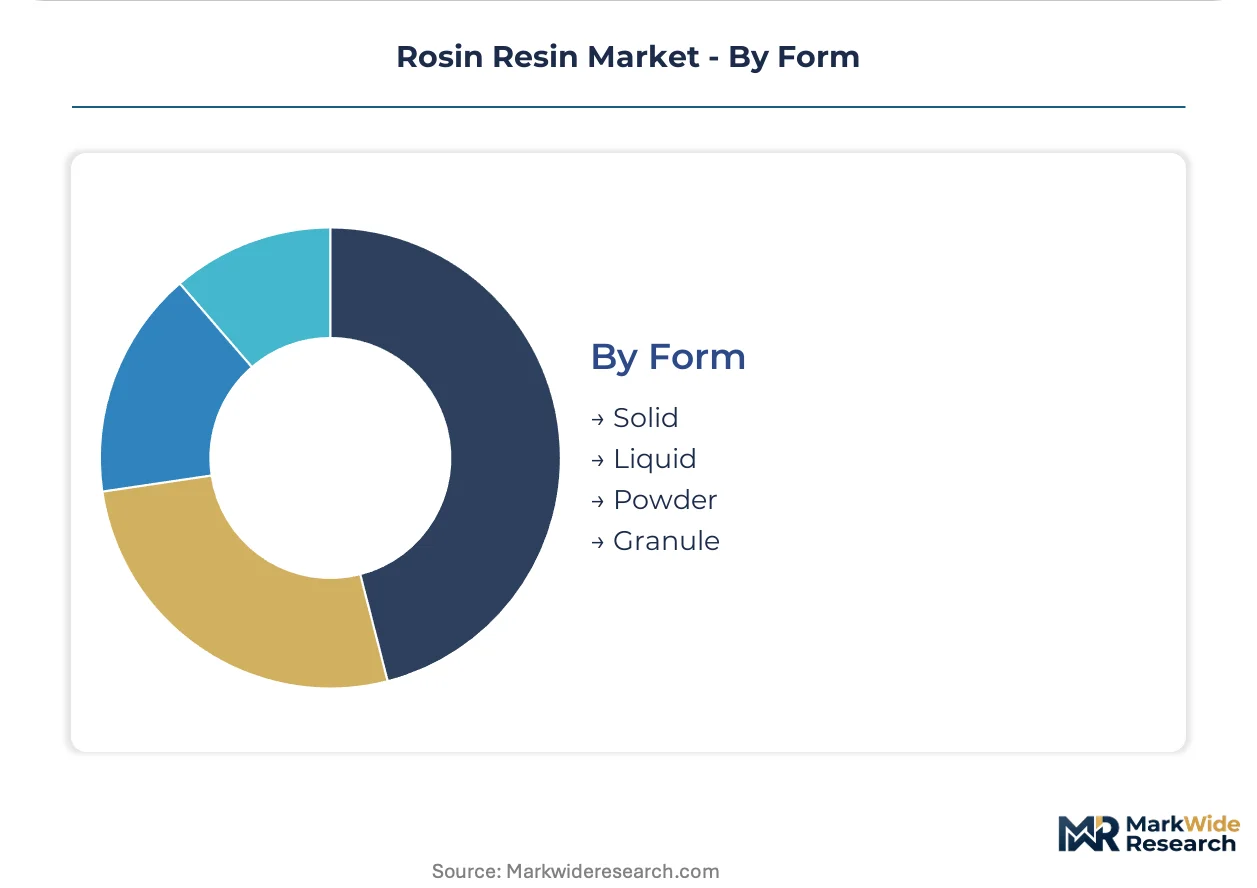
- Solid:Blocks and flakes dominate established gum rosin trade flows from Chinese ports to European coating houses.
- Liquid:Pre-dispersed ester solutions reduce formulator mixing energy and enable just-in-time delivery to adhesive compounders.
- Powder:Micronized grades serve automated dosing systems in high-volume hot-melt production.
- Granule:Dust-reduced formats improve workplace safety compliance under OSHA and REACH occupational exposure limits.
Solid form holds the most established trade infrastructure. Granule is expanding most quickly on automation and safety compliance drivers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized distillation technicians concentrate in legacy pine chemical facilities across Portugal and Brazil, anchoring regional supply capabilities for refined rosin derivatives. Their expertise shapes where high-purity processing capacity clusters geographically.
China
Guangxi and Yunnan tapping networks supply volume to coating formulators facing ECHA polycyclic aromatic thresholds. GB standards for industrial chemicals constrain unverified feedstock entry. Domestic packaging and coating output scaling in the Yangtze River Delta pulls disproportionated rosin esters into hot-melt adhesive production.
United States
EPA TSCA oversight elevates compliance costs for uncertified producers while electronics contract manufacturers specify oxidative stability grades. The Southeast pulp corridor anchors tall oil fractionation infrastructure serving adhesive compounders. Direct mill relationships with Finnish and Swedish suppliers are displacing spot market purchases among large formulators.
Germany
Coating formulators in the Ruhr and Lower Rhine industrial zones qualify alternative tall oil feedstocks to preempt supply interruption risks. REACH registration deadlines compress the European supplier base toward certified fractionators. ECHA substance evaluation tightens impurity thresholds, redirecting R&D toward refined distillation methods.
South Korea
Electronics contract manufacturers in Gyeonggi Province specify hydrogenated rosin grades for display bonding fluxes. Precision bonding requirements for semiconductor packaging pull high-purity formulations from domestic compounders. Taiwan and South Korean procurement teams contract for batch-level carbon accounting under OEM sustainability scorecards.
India
Carton sealing and lamination applications expand under FSSAI food-contact regulations and PLI scheme incentives for domestic manufacturing. Maharashtra and Gujarat packaging clusters drive esterified rosin demand for carton sealing adhesives. The country's national chemical regulator maintains parallel registration requirements alongside state-level industrial safety mandates.
Rosin Resin Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the rosin resin value chain. Tall oil fractionators with captive pulp mill feedstock face off against gum rosin traders dependent on Chinese tapping networks. Three archetypes dominate: backward-integrated chemical majors with Nordic pulp partnerships, Asian specialists in hydrogenated derivatives for electronics, and Chinese gum rosin processors leveraging established tapping infrastructure. Capacity expansion and direct mill contracting represent the dominant competitive moves as procurement teams seek mass-balance certification.
Among Japanese specialists in high-purity derivatives, Arakawa Chemical Industries and Harima Chemicals Group exemplify the electronics-grade hydrogenated rosin archetype. Eastman Chemical Company anchors the backward-integrated tier with upstream control over tall oil fractionation. These three occupy positions across the premium specification spectrum where thermal stability and low-color requirements command margin premiums.
| Leading Market Players |
|---|
| Eastman Chemical Company |
| Arakawa Chemical Industries |
| Harima Chemicals Group |
| Foreverest Resources |
| BaoLin |
| Kraton Corporation |
| DRT |
| Ingevity Corporation |
| Formosa Produce Corporation |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between REACH-registered tall oil derivatives and uncertified gum rosin imports manifests in divergent margin structures and procurement routing. Premium hydrogenated grades command carbon-accounted supply chains through direct Nordic pulp mill contracts, while commodity esters flow through spot-traded Chinese tapping networks facing ECHA polycyclic aromatic enforcement.
Pricing Analysis
Carbon-accounted tall oil pitch and uncertified gum rosin trade on fundamentally unbundled service models. Three-tier pricing structure separates mass-balance certified hydrogenated derivatives from standard disproportionated esters and economy gum rosin blocks. Price differentiation rests on REACH dossier completeness and batch-level carbon footprint documentation. Cost compression in commodity adhesives intensifies as petroleum C5/C9 resins undercut rosin esters during crude price troughs. Packaging formulators in India exhibit highest price sensitivity, while South Korean electronics contract manufacturers absorb premiums for oxidative stability specifications.
Supply Chain Analysis
Dual-sourcing requirements now dominate procurement protocols as adhesive compounders qualify both Nordic tall oil fractionators and Chinese gum rosin refiners to preempt ECHA supply interruption risks. Geographic concentration centers on Finland, Sweden, and China as primary feedstock origins. Raw material dependencies draw from pine oleoresin tapping networks, crude tall oil pitch from Kraft pulping, and specialized hydrogenation catalysts. Single-source vulnerability concentrates in Nordic pulp mill output limits constraining backward-integrated producers. Distribution runs through direct mill relationships displacing spot market purchases among large compounders seeking Scope 3 emissions traceability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through carbon certification premiums as EU CSRD disclosure requirements and ISO 14067 standards elevate mass-balance tall oil derivatives above commodity alternatives.
For Market Incumbents: Anticipate regulatory divergence between bio-based certification schemes and conventional chemical registrations by deepening backward integration into captive tall oil fractionation. Secure distillation technician pipelines at legacy Portuguese and Brazilian facilities to preempt capability attrition. Prioritize hydrogenated rosin capacity expansion in South Korea and Taiwan to capture electronics-grade demand from semiconductor packaging miniaturization. For New Entrants and Emerging Players: Launch via direct-to-mill contracting models targeting Indian packaging clusters under FSSAI food-contact regulations and PLI scheme incentives. White-space targets concentrate in esterified rosin for carton sealing adhesives in Maharashtra and Gujarat, plus photocurable rosin-acrylate oligomers for dental and jewelry casting 3D printing applications. Pursue qualification partnerships with Nordic pulp mills for carbon-accounted feedstock access rather than competing on gum rosin volume. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-standard compliance burdens extend product launch timelines and specialized fractionation expertise concentrates among aging workforces. Long-term viability favors asset-heavy producers with captive feedstock and certification infrastructure over traders dependent on Chinese spot markets. Target acquisition archetype: hydrogenated rosin specialists with electronics-grade specifications and existing OEM sustainability scorecard approvals. Signal to watch: ECHA substance evaluation outcomes on polycyclic aromatic thresholds that would disqualify uncertified gum rosin imports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tall Oil Fractionation | Eastman Chemical's upstream control secures feedstock certainty against Nordic pulp mill output constraints. |
| Hydrogenated Rosin Capacity Expansion | Arakawa Chemical and Harima Chemicals capture electronics-grade demand from Taiwan and South Korea contract manufacturers. |
| Carbon Certification Investment | Mass-balance tall oil derivatives qualify for EU Green Deal bio-based mandates in public procurement packaging adhesives. |
| Direct Mill Relationship Development | Henkel and Bostik procurement teams secure Scope 3 traceability under CSRD disclosure requirements. |
| Specialized Distillation Technician Pipeline | Legacy Portuguese and Brazilian facilities anchor high-purity processing capacity against workforce aging. |
Methodological Framework
Direct dialogue with adhesive compounder procurement leads, pine chemical plant managers, electronics contract manufacturer technical directors, and ECHA regulatory affairs specialists grounded qualitative insights. Secondary validation drew from customs trade data, SEC 10-K filings of listed chemical producers, Cefic industry reports, and REACH registration dossiers. Bottom-up demand modeling across application segments triangulated against top-down tall oil fractionation capacity assessments.
Segment-level projections across product type, application, end user, and form dimensions generated volume and value trajectories across the analysis window. CAGRs derived from regression analysis of historical trade flows and forward-looking capacity expansion announcements. Industry-specific inputs included MEE emissions enforcement timelines in China, EU Green Deal procurement threshold implementations, and electronics miniaturization-driven specification shifts in semiconductor packaging.
Several conditions sit outside the modeled scope, including abrupt pulp mill closures altering crude tall oil availability, breakthrough synthetic tackifier technologies displacing rosin derivatives, and geopolitical trade restrictions on Chinese gum rosin imports. Deviation in ECHA polycyclic aromatic threshold enforcement or carbon accounting standard convergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Naphthalate Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Tie Layer Resin Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market