
 Thailand Plastics Market | 2026-2036
Thailand Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Plastics Market Analytics
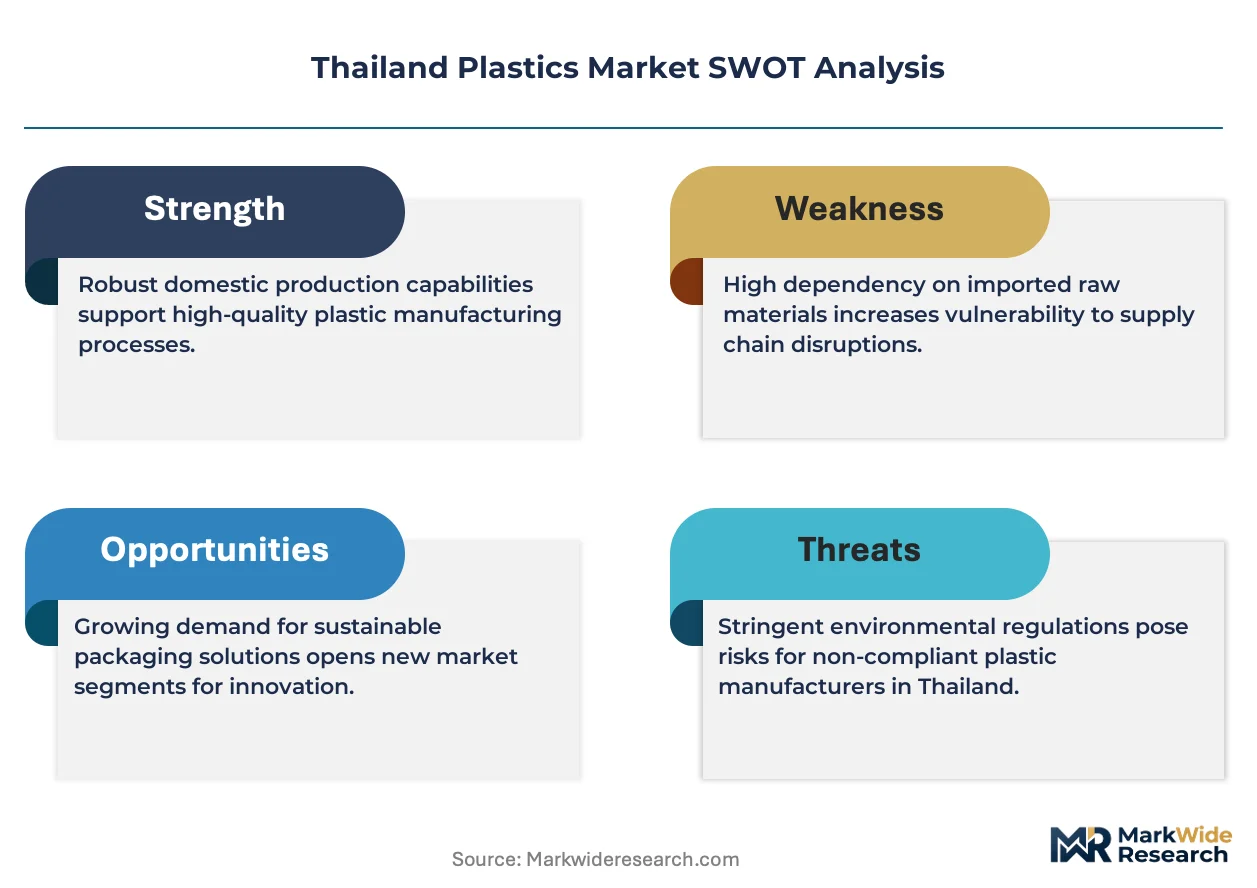
Post-manufacturing resin subscription and technical service bundling is consolidating how Thai converters procure feedstock. SCG Chemicals Co. Ltd leverages its integrated olefin complex to lock in downstream offtake. Indorama Ventures Public Company Limited anchors global recycled PET capacity from its Bangkok headquarters. PTT Global Chemical Public Company Limited dominates domestic propylene supply through its Map Ta Phut refinery integration.
Thailand plastics comprise synthetic polymer resins—primarily olefin-based thermoplastics with melt flow indices ranging from 0.3 to 50 g/10min—processed through injection molding, extrusion, and blow molding for durable and disposable goods. Polyethylene and polypropylene together absorb the majority of domestic resin offtake, with polyethylene leading volume due to flexible packaging dominance. Food grade specifications command premium positioning over industrial grade alternatives as FDA-aligned safety protocols tighten across ASEAN export channels. Recycled grade output is accelerating fastest, though from a smaller base, driven by brand-led packaging commitments and extended producer responsibility frameworks.
Thailand's Ministry of Industry enforces polymer safety standards through the Thai Industrial Standards Institute, while the Pollution Control Department regulates plastic waste management under national circular economy roadmaps. These frameworks compel domestic producers to certify biodegradability claims and document recycled content percentages for market access. Stakeholders must monitor how bio-based feedstock mandates and carbon border adjustments in key export destinations reshape cost structures and capital allocation priorities.
Market Dynamics
Thailand's plastics sector is reconfiguring around circular economy mandates that force converters to certify recycled content percentages and biodegradability claims under TISI and Pollution Control Department frameworks. This regulatory pressure is compressing legacy resin procurement models while elevating technical service bundling as a competitive differentiator.
Growth Catalysts
- Eastern Economic Corridor concentration:Industrial clustering in Rayong and Chonburi provinces creates dense converter ecosystems with shared logistics infrastructure and co-located polymer processing capabilities.
- Bio-based feedstock mandates:Thailand's national bio-plastics roadmap redirects public and private R&D investment toward cassava-derived and sugarcane-based polymer streams with government procurement preferences.
- Extended Producer Responsibility frameworks:Brand-led packaging commitments under ASEAN-aligned EPR schemes accelerate demand for food-grade recycled resins with documented chain-of-custody certification.
Market Restraints
- Naphtha price volatility:Feedstock cost swings for olefin production at Map Ta Phut complex compress margin predictability for domestic polyethylene and polypropylene converters.
- Propylene supply concentration:Single-source refinery integration at Rayong creates downstream dependency risk for polypropylene compounders lacking alternative feedstock arrangements.
- Mechanical recycling yield limits:Contamination thresholds in post-consumer PET collection systems cap recycled resin output quality for food-contact applications.
Strategic Opportunities
- Chemical recycling scale-up:Pyrolysis and depolymerization investments unlock mixed-plastic waste streams currently excluded from mechanical reprocessing circuits.
- Carbon border adjustment positioning:EU CBAM preparatory phase creates first-mover advantage for Thai exporters documenting embedded emissions in polymer production.
- Subscription resin procurement:Volume-commitment contracts with embedded technical service and inventory management displace spot-market purchasing among mid-tier converters.
Industry Challenges
- Polymer engineer scarcity:Specialized melt-flow characterization and food-grade certification expertise concentrates among senior technicians at SCG Chemicals and PTTGC, constraining workforce mobility.
- Multi-standard compliance timelines:Simultaneous TISI safety certification, FDA-aligned export documentation, and EU REACH registration create administrative bottlenecks for SME compounders.
- Legacy extrusion asset retrofit:Circular economy resin blends with varying melt indices require screw and die modifications that extend capital deployment cycles beyond typical depreciation schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Plastics Market |
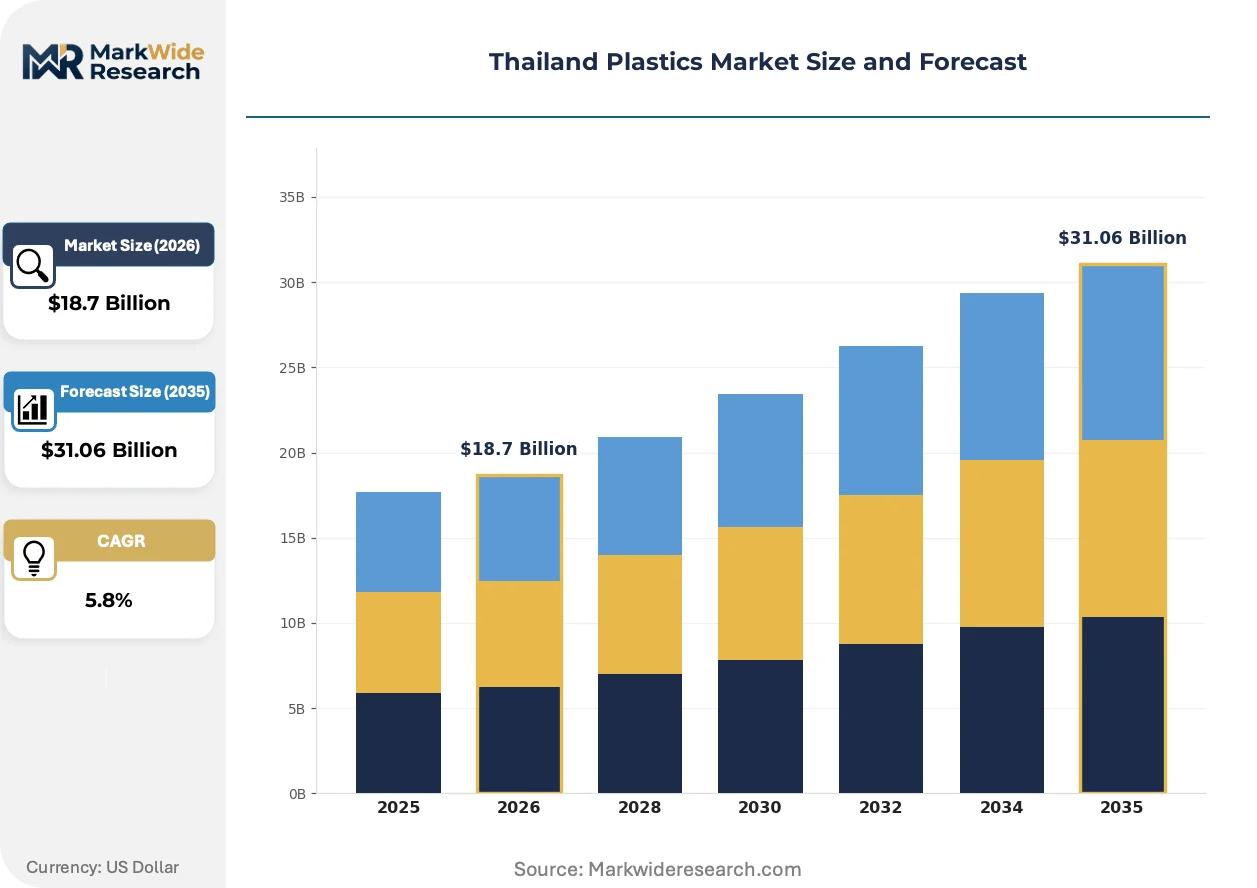
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polystyrene, PVC Application: Automotive Components, Packaging Materials, Consumer Goods, Electronics End User: Manufacturing, Construction, Agriculture, Healthcare Grade: Industrial Grade, Food Grade, Recycled Grade, Specialty Grade |
| Companies Covered | Indorama Ventures Public Company Limited, SCG Chemicals Co. Ltd, PTT Global Chemical Public Company Limited, Thai Plastic Industries Co. Ltd, INEOS Styrolution Group GmbH, Covestro AG, HMC Polymers Thailand, IRPC Public Company Limited, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Plastics Market Evolving Landscape
Active transformation in Thailand's plastics landscape centers on process intensification, regulatory data architecture, and procurement model restructuring. These shifts are compressing traditional value chain positions while opening new service-layer revenue pools.
Advanced process control systems using real-time rheology monitoring are integrating into continuous extrusion lines at major flexible packaging converters. Food and beverage brand owners specify these sensor arrays as a condition of long-term supply agreements. The technology is integrating quality assurance directly into production workflows, reducing offline laboratory testing cycles and compressing batch release timelines.
Thailand's Pollution Control Department is enforcing mandatory recycled content disclosure under national circular economy roadmaps with phased implementation timelines. Domestic producers must submit third-party verified mass-balance documentation for market access. Flexible packaging exporters to EU markets face the most stringent audit requirements, driving investment in blockchain-tracked collection systems.
Resin procurement is consolidating around technical service bundling rather than commodity spot transactions. Mid-tier converters in Samut Prakan and Pathum Thani provinces now prioritize suppliers offering formulation support, inventory financing, and regulatory documentation over base resin pricing alone. This behavioral shift is most pronounced among automotive tier-one suppliers facing just-in-time delivery mandates from Japanese OEM assembly plants in the Eastern Economic Corridor.
Thailand Plastics Market Segmentation
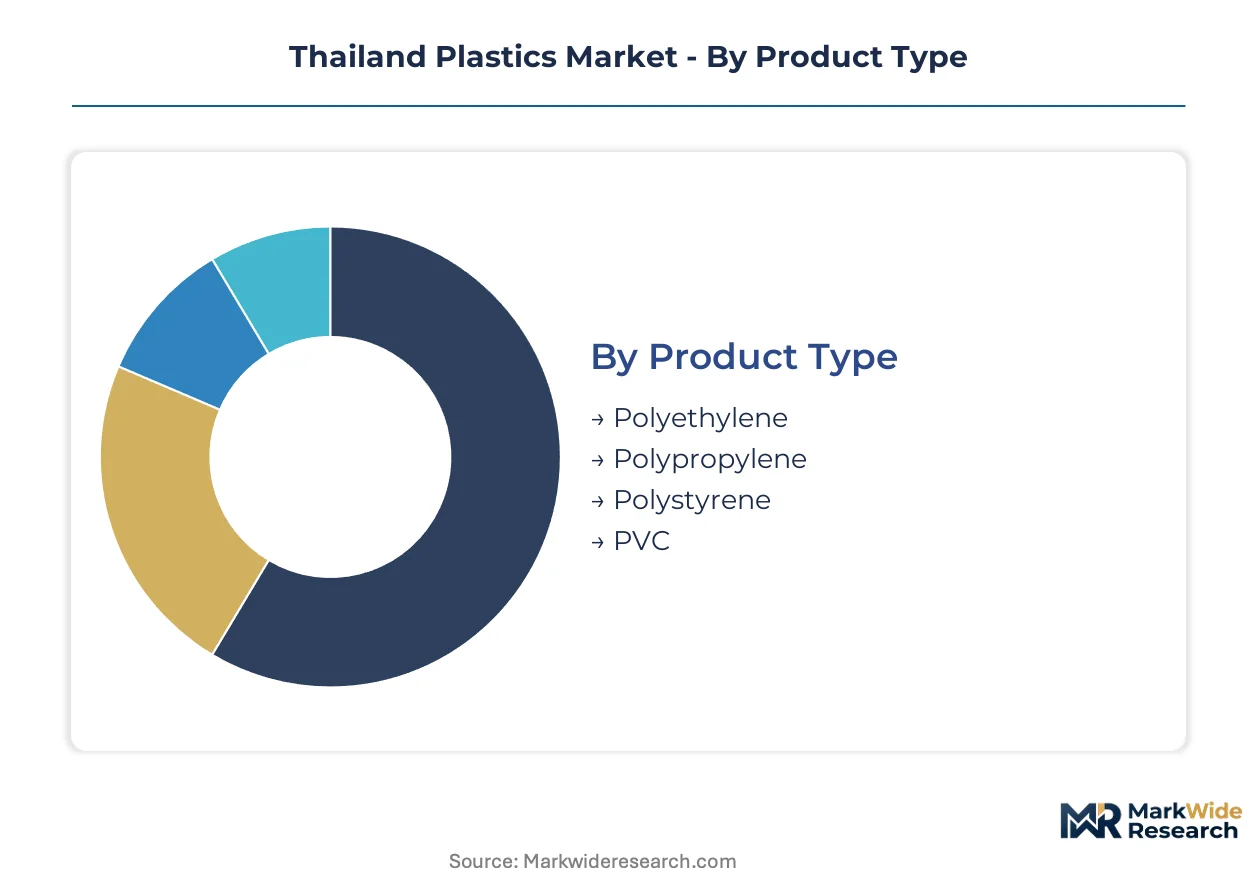
Thailand's plastics market fragments across resin chemistry, end-use specifications, and regulatory compliance tiers that determine converter procurement priorities. Understanding these segment boundaries reveals where margin pools concentrate and which technical capabilities differentiate suppliers in the Eastern Economic Corridor.
Product Type:
Converter selection hinges on melt-flow characteristics and downstream processing compatibility rather than commodity pricing alone.
- Polyethylene:Linear low-density and high-density variants dominate flexible packaging applications with melt indices spanning 0.3 to 50 g/10min. Rayong-based converters absorb the majority of domestic offtake for food-contact film and shrink-wrap applications under tightening FDA-aligned export protocols.
- Polypropylene:Homopolymer and copolymer grades serve injection-molded automotive components and rigid containers. Map Ta Phut refinery integration secures propylene monomer supply for domestic compounders serving Japanese OEM tier-one suppliers in Chonburi province.
- Polystyrene:General-purpose and high-impact grades target consumer electronics housings and disposable foodservice items.
- PVC:Rigid and plasticized formulations split between construction piping and medical device applications.
Polyethylene leads on scale; polypropylene leads on momentum as automotive lightweighting accelerates procurement of engineered compounds.
Application:
End-use performance requirements dictate resin specification complexity and certification burden.
- Packaging Materials:Flexible film, rigid containers, and barrier laminates absorb the majority of Thai resin volume. Food and beverage brand owners mandate real-time rheology monitoring and blockchain-tracked recycled content documentation for EU export eligibility.
- Automotive Components:Interior trim, under-hood applications, and structural composites demand heat-deflection temperatures above 100°C. Japanese OEM assembly plants in the Eastern Economic Corridor enforce just-in-time delivery mandates that favor co-located compounders with technical service bundling.
- Consumer Goods:Durable housewares and personal care packaging utilize commodity grades with shorter specification cycles.
- Electronics:Housings and connectors require flame-retardant formulations meeting IEC standards for ASEAN distribution.
Packaging materials command volume concentration; automotive components drive premium-grade expansion.
End User:
Sector-specific regulatory exposure and capital intensity shape procurement contract structures.
- Manufacturing:Tier-one automotive suppliers and electronics assemblers in Samut Prakan province prioritize subscription resin contracts with embedded inventory financing.
- Construction:PVC piping and geomembrane applications follow infrastructure investment cycles with price-sensitive spot purchasing.
- Agriculture:Mulch films and irrigation tubing demand UV-stabilized formulations for tropical climate durability.
- Healthcare:Sterile packaging and medical devices require ISO 13485-aligned quality systems with lot-traceability documentation.
Manufacturing dominates contract value; healthcare exhibits the steepest expansion trajectory as domestic medical device production scales.
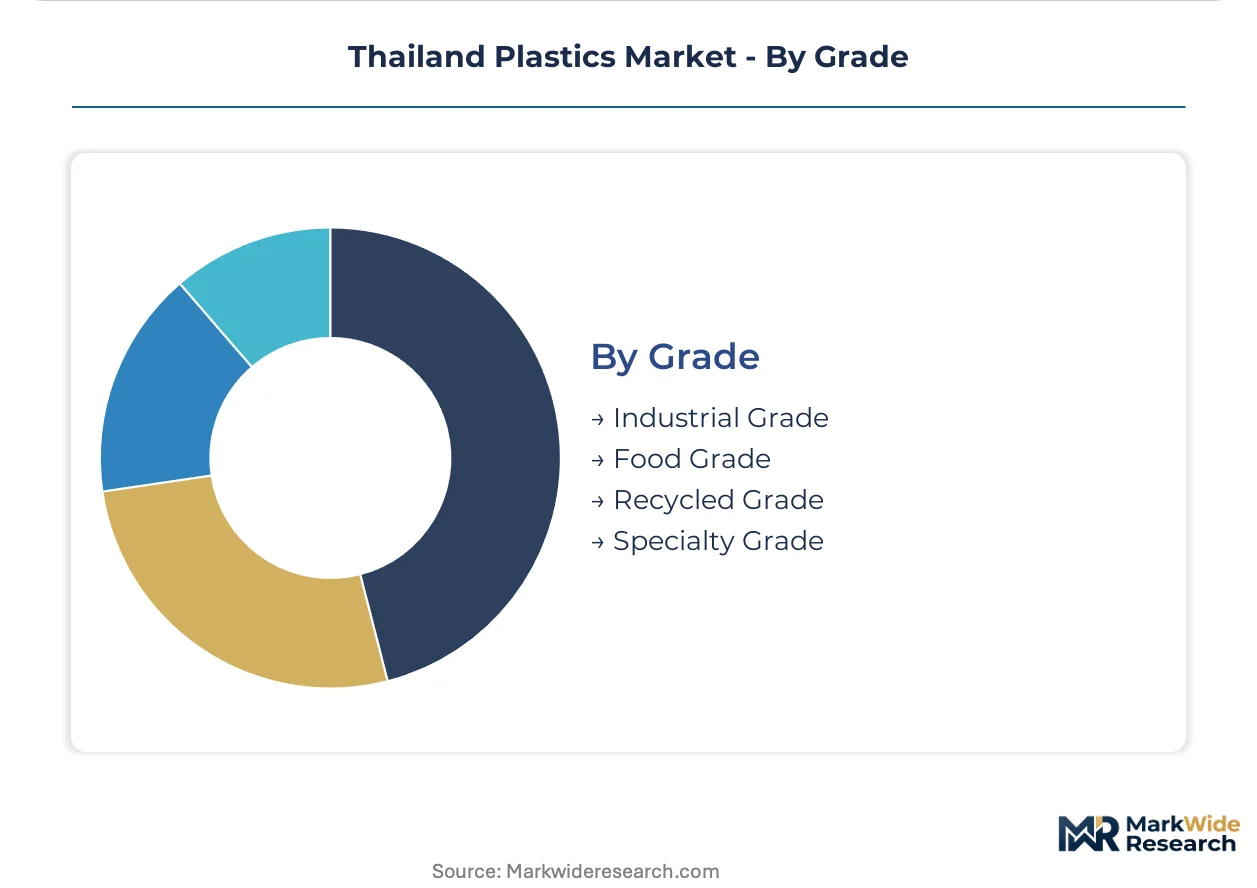
Grade:
Certification tier determines market access permissions and pricing power in export channels.
- Food Grade:FDA-aligned safety protocols and TISI certification command premium positioning over industrial alternatives. Thai Industrial Standards Institute enforcement tightens contaminant thresholds for ASEAN cross-border shipments.
- Recycled Grade:Post-consumer PET and mechanically reprocessed polyolefins accelerate fastest from a smaller base. Extended producer responsibility frameworks and brand-led packaging commitments drive investment in blockchain-tracked collection systems.
- Industrial Grade:Uncertified commodity resins serve non-contact applications with minimal regulatory documentation.
- Specialty Grade:Conductive, optical, and bio-based formulations target niche medical and electronics applications.
Food grade captures margin premiums; recycled grade gains share fastest as circular economy mandates harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting polymer production toward jurisdictions with lower compliance friction. Thai converters exploit this gap by serving ASEAN markets from the Eastern Economic Corridor while positioning for EU carbon border exposure.
Chonburi Province
Automotive tier-one suppliers and Japanese OEM assembly plants cluster around Laem Chabang port. The Thai Industrial Standards Institute enforces polymer safety certifications for export-bound components. Just-in-time delivery mandates from Toyota and Honda assembly lines favor co-located compounders with technical service bundling.
Rayong Province
Map Ta Phut refinery integration anchors domestic propylene supply for polypropylene compounders. The Pollution Control Department regulates plastic waste management under circular economy roadmaps. Dense converter ecosystems share logistics infrastructure with SCG Chemicals and PTT Global Chemical olefin complexes.
Samut Prakan Province
Mid-tier converters prioritize subscription resin contracts with embedded inventory financing. Extended producer responsibility frameworks accelerate demand for food-grade recycled resins. Electronics assemblers and packaging specialists concentrate near Suvarnabhumi Airport for ASEAN distribution.
Pathum Thani Province
Automotive component molders and consumer goods fabricators source from Bangkok-headquartered distributors. Bio-based feedstock mandates redirect procurement toward cassava-derived polymer streams. The province sits within the Greater Bangkok industrial belt with rail-linked resin terminals.
Thailand Plastics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The Thailand plastics sector concentrates around integrated petrochemical complexes and specialized compounders with formulation expertise. Three archetypes dominate: refinery-integrated resin producers, global recycled PET specialists, and regional technical service bundlers. Competitive moves center on backward integration into olefin production and chemical recycling capacity expansion.
Within the integrated producer tier, SCG Chemicals Co. Ltd and PTT Global Chemical Public Company Limited exemplify refinery-anchored market positions. Indorama Ventures Public Company Limited occupies a distinct position as a Bangkok-headquartered global recycled PET specialist. These three entities represent the dominant competitive anchors shaping procurement patterns across the Eastern Economic Corridor.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| SCG Chemicals Co. Ltd |
| PTT Global Chemical Public Company Limited |
| Thai Plastic Industries Co. Ltd |
| INEOS Styrolution Group GmbH |
| Covestro AG |
| HMC Polymers Thailand |
| IRPC Public Company Limited |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Thailand's national bio-plastics roadmap gates qualified supply access for converters seeking premium-tier positioning, with government procurement preferences and TISI biodegradability certification requirements creating parallel barriers to entry and price floor elevation for compliant resin streams.
Pricing Analysis
Capacity additions in Vietnam and Indonesia are reshaping price floors for commodity polyethylene and polypropylene grades across Southeast Asian spot markets. Three-tier pricing structure across food-grade certified, industrial-grade, and recycled-content tiers separates converters serving EU export channels from domestic spot buyers. Cost compression in standard-grade polyolefins is intensifying because naphtha-linked feedstock volatility at Map Ta Phut compresses margin predictability. Tier-one automotive suppliers in Chonburi exhibit the lowest price sensitivity due to just-in-time technical service bundling requirements, while construction-sector PVC buyers in Greater Bangkok remain highly sensitive to spot resin movements.
Supply Chain Analysis
Freight cost differentials between deepwater ports and inland converter clusters favor co-location with olefin production assets. Thailand's plastics supply chain draws from Saudi Arabia and South Korea for naphtha feedstock, while specialty additive packages feed from Germany and Japan. Single-source propylene dependency at Rayong creates downstream vulnerability for polypropylene compounders lacking alternative monomer arrangements. Distribution runs through Bangkok-headquartered distributors with rail-linked terminals serving the Eastern Economic Corridor, though containerized resin moves directly from Map Ta Phut to Laem Chabang for export-bound converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Thailand's Pollution Control Department circular economy mandates and EU carbon border adjustment preparatory phases are accelerating demand for documented chain-of-custody certification and embedded emissions accounting.
For Market Incumbents: Extend chemical recycling capacity to unlock mixed-plastic waste streams currently excluded from mechanical reprocessing circuits, defending against pyrolysis-focused entrants from Singapore and South Korea. Deepen backward integration into cassava-derived bio-polymer feedstocks to capture government procurement preferences under the national bio-plastics roadmap. For New Entrants and Emerging Players: Begin with food-grade recycled PET collection systems in Samut Prakan province, where blockchain-tracked documentation gaps create white-space opportunity for EU-exporting flexible packaging converters. Target mid-tier automotive tier-two suppliers in Pathum Thani with subscription resin contracts embedding inventory financing and real-time rheology monitoring as the primary go-to-market wedge. For Investors and Strategic Acquirers: Roll-up economics work for regional technical service bundlers because procurement consolidation among mid-tier converters creates captive offtake relationships that resist commodity price volatility. Long-term viability hinges on positioning ahead of EU CBAM implementation, with acquisition targets screening for mass-balance documentation capabilities and pyrolysis pilot assets as the inflection signal to monitor.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis investments at Map Ta Phut unlock mixed-plastic waste streams for food-contact resin output. |
| Backward Integration into Bio-Feedstocks | Cassava-derived polymer production captures Thai government procurement preferences under national roadmap mandates. |
| Subscription Resin Procurement Contracts | Volume-commitment agreements with technical service bundling displace spot-market purchasing among EEC converters. |
| Carbon Border Adjustment Positioning | Embedded emissions documentation creates first-mover advantage for Thai exporters facing EU CBAM exposure. |
| Blockchain-Tracked Collection Systems | Third-party verified mass-balance documentation satisfies Pollution Control Department recycled content disclosure requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant managers at Rayong olefin complexes, procurement leads at Chonburi automotive tier-one suppliers, distribution channel partners in Bangkok, and technical R&D directors at bio-polymer pilot facilities with secondary validation from Thai Industrial Standards Institute certification records, customs and trade data, SEC filings of listed petrochemical groups, and Pollution Control Department circular economy roadmap documentation. Bottom-up resin consumption estimates across packaging, automotive, and electronics end-uses triangulated against top-down production capacity data from Map Ta Phut and Laem Chabang industrial zones.
Segment-weighting approaches modeled resin chemistry splits, grade certification tiers, and regional production hub concentrations across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating naphtha price volatility coefficients and bio-based feedstock substitution rates. Industry-specific forecast inputs included Japanese OEM content-per-vehicle trajectories for polypropylene compounds and EU packaging recycled content mandate compliance schedules.
Caveats apply where naphtha price volatility spikes, EU carbon border adjustment scope expansion, or bio-based feedstock crop yield disruptions could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Epoxy Resin Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market