
 Middle East and Africa Polyurethane Market | 2026-2036
Middle East and Africa Polyurethane Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Polyurethane Market Analysis
Saudi Arabia's petrochemical capacity build-out is reshaping polyurethane feedstock availability across the Middle East and Africa. BASF SE leverages its integrated material science platform to sustain technical service density in Gulf markets. Covestro AG anchors its regional competitiveness through specialized aliphatic isocyanate production tailored to coatings applications. Huntsman Corporation differentiates via rigid foam systems optimized for Middle Eastern climate conditions.
Polyurethane denotes a class of polymers formed by reacting a di- or poly-isocyanate with a polyol, yielding materials with tunable density, elasticity, and thermal resistance ranging from flexible foams to rigid structural insulants. These polymers serve as essential inputs for cushioning, thermal barrier systems, protective coatings, and adhesive bonding across industrial and consumer applications. Flexible Foam commands the largest volume share in regional consumption, driven by furniture and automotive seating demand. Rigid Foam represents the fastest-expanding category, propelled by Gulf construction codes mandating higher thermal efficiency in building envelopes. Coatings concentrate margin pools where specification-grade aliphatic systems command premium positioning in infrastructure and industrial maintenance.
Saudi Arabia's SFDA and the UAE's MOHAP enforce chemical safety standards affecting polyurethane raw material handling and finished product certification in consumer-facing applications. REACH-equivalent frameworks under development in Gulf Cooperation Council states are tightening disclosure requirements for isocyanate content in construction materials. South Africa's national environmental regulator imposes volatile organic compound limits on polyurethane coatings used in industrial and automotive finishing. Stakeholders must monitor evolving chemical registration timelines and building energy codes to align capacity investments with compliant product portfolios.
Market Dynamics
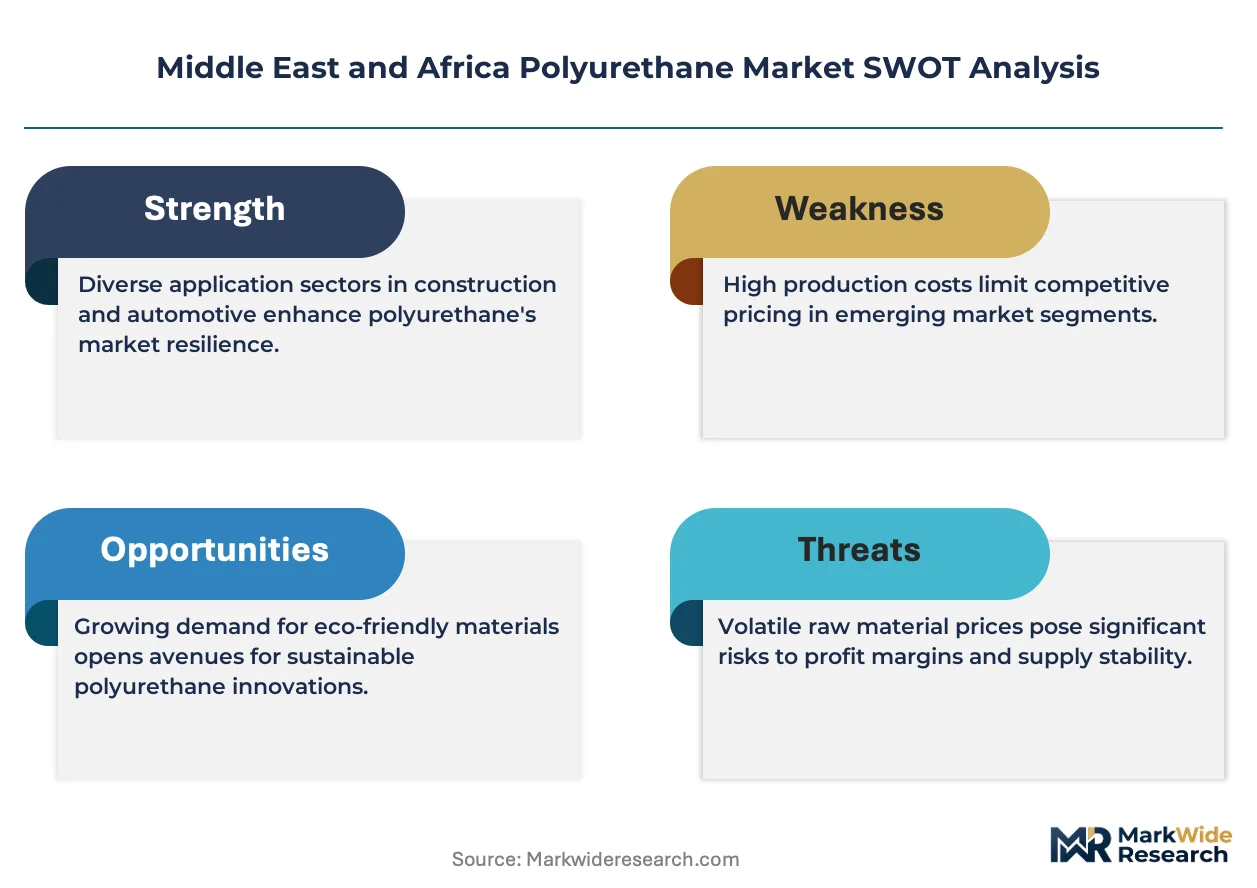
Feedstock concentration around Saudi Arabia's Jubail Industrial City is compressing regional supply chains while Gulf building codes mandate polyurethane thermal barriers in new construction envelopes.
Growth Catalysts
- SFDA chemical safety frameworks:Saudi Arabia's tightened isocyanate handling standards are professionalizing distribution channels and accelerating compliant system house investments.
- Automotive seating demand:Gauteng province's vehicle assembly plants are sourcing flexible foam locally, reducing import dependency for interior components.
- Aliphatic isocyanate coatings:Infrastructure maintenance specifications across UAE megaprojects are specifying weather-resistant polyurethane finishes for extended asset life cycles.
Market Restraints
- MDI feedstock volatility:Crude-linked benzene pricing transmits directly to polyurethane raw material costs, squeezing system house margins during upstream spikes.
- European supplier concentration:Specialty polyol and catalyst sourcing remains concentrated among Rotterdam-Antwerp corridor producers, exposing African converters to freight cost surges.
- Isocyanate sensitivity:TDI and MDI handling requirements demand controlled atmosphere facilities that inflate capex thresholds for new market entrants.
Strategic Opportunities
- East African construction codes:Kenya and Ethiopia are adopting thermal efficiency standards that will mandate rigid foam insulation in commercial building envelopes within five years.
- Waterborne coating conversion:South Africa's VOC limits are pushing industrial finishers toward low-emission polyurethane dispersions for automotive refinishing applications.
- Recycled content mandates:Circular economy frameworks under development in GCC states will create certified demand for post-industrial flexible foam regrind in cushioning products.
Industry Challenges
- Formulation chemist scarcity:System houses struggle to recruit polyurethane application engineers with climate-specific rigid foam expertise for Gulf humidity conditions.
- REACH-equivalent compliance timelines:Evolving chemical registration deadlines across multiple GCC jurisdictions create portfolio planning uncertainty for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Polyurethane Market |
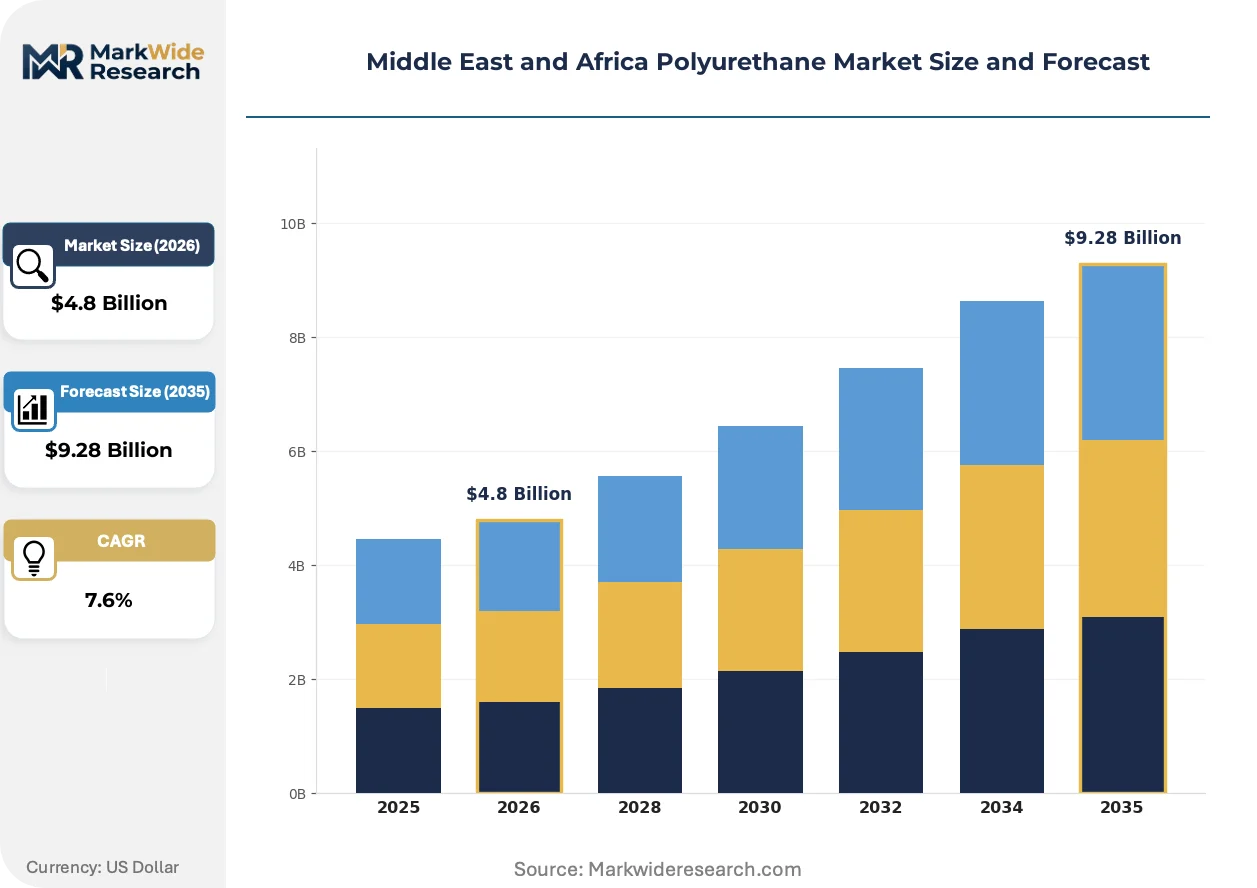
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Foam, Rigid Foam, Coatings, Adhesives End Use Industry: Automotive, Furniture, Construction, Footwear Technology: Spray, Injection Molding, Casting, Thermoforming Application: Upholstery, Insulation, Sealants, Packaging |
| Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, Dow Chemical Company, SABIC, Sika AG, Recticel NV, Kingspan Group, Mitsui Chemicals, Inc., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Polyurethane Market Emerging Trajectories
Polyurethane chemistry is pivoting toward lower-emission curing systems and bio-based feedstocks as Gulf regulators tighten construction material disclosures and African automotive assemblers localize supply chains.
Polyurethane rigid foam blowing agent technology is migrating from hydrofluorocarbon systems to hydrofluoroolefin and hydrocarbon alternatives. Saudi building code enforcement is accelerating adoption timelines for new residential and commercial projects. This transition is compressing capital equipment depreciation schedules for incumbent foam producers while creating specification advantages for early movers with certified low-GWP product lines.
MOHAP's chemical substance notification requirements are expanding disclosure obligations for isocyanate-containing construction materials imported into UAE free zones. Industrial coatings and adhesive formulators must now submit detailed safety data sheets prior to customs clearance. Specialty aliphatic systems for infrastructure projects face extended approval timelines, favoring suppliers with established Dubai-based technical service laboratories.
Direct procurement relationships between end-users and system houses are displacing traditional distributor networks for large-volume rigid foam contracts. Saudi cement and construction conglomerates are negotiating annual supply agreements with integrated material suppliers for pre-insulated panel projects. This channel consolidation is most visible in Riyadh and Jeddah metropolitan construction corridors where project scale justifies dedicated technical support commitments.
Middle East and Africa Polyurethane Market Segmentation
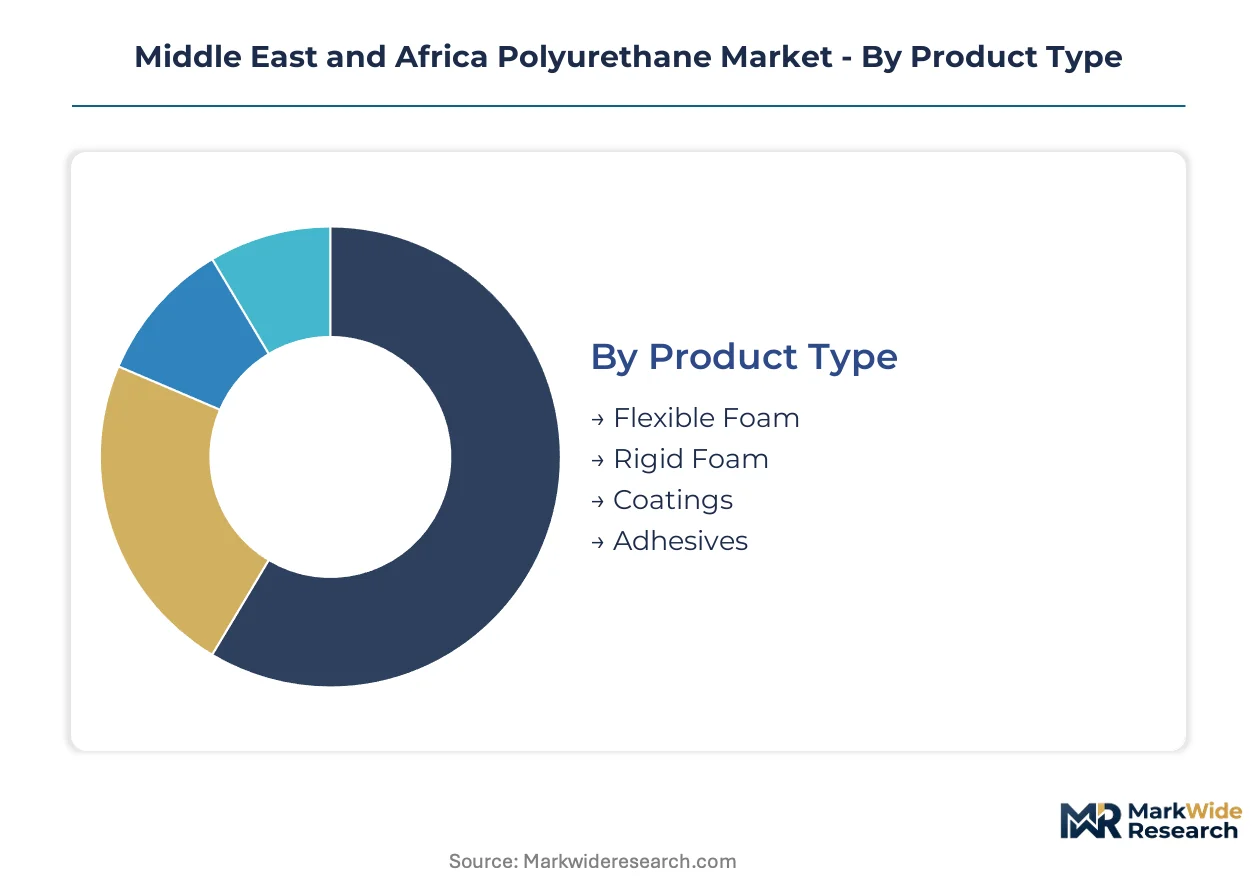
Polyurethane segmentation in the Middle East and Africa reflects divergent technical requirements across climate extremes and industrial maturity. Gulf construction codes and South African automotive localization create distinct demand profiles that reshape product mix priorities.
Product Type:
Flexible Foam dominates volume flows through furniture and automotive channels, while Rigid Foam captures specification-grade premiums in energy-efficient building envelopes.
- Flexible Foam:Open-cell polyether formulations deliver compressive resilience for cushioning applications. Gauteng province's vehicle assembly plants and Saudi furniture manufacturing clusters absorb regional flexible foam output, with TDI-based systems preferred for cost-sensitive seating.
- Rigid Foam:Closed-cell structures with hydrofluoroolefin blowing agents achieve thermal conductivity below 20 mW/m·K. Gulf Cooperation Council building codes mandate rigid foam insulation in commercial envelopes, compressing payback periods for energy retrofit projects.
- Coatings:Aliphatic isocyanate systems provide UV-stable finishes for UAE infrastructure megaprojects.
- Adhesives:Reactive hot-melt and two-component formulations bond composite panels in Saudi pre-fabricated construction.
Established volume favors Flexible Foam; emerging adoption favors Rigid Foam.
End Use Industry:
Cost tiers separate specification-driven construction applications from price-sensitive consumer goods manufacturing.
- Construction:Rigid foam insulation and protective coatings command premium positioning where Gulf energy codes enforce thermal performance standards. Cement conglomerates in Riyadh and Jeddah corridors source pre-insulated panel systems through direct procurement channels.
- Automotive:Flexible foam seating and interior trim concentrate in South Africa's vehicle assembly ecosystem. Local sourcing mandates reduce import dependency for interior components while quality specifications align with export market requirements.
- Furniture:Mattress and upholstery manufacturers in Egypt and Morocco absorb commodity-grade flexible foam volumes.
- Footwear:Microcellular polyurethane soles serve North African export-oriented manufacturing.
Construction commands margin premiums; automotive drives localization investment.
Technology:
Processing method selection hinges on part complexity, production scale, and capital equipment availability across regional manufacturing bases.
- Spray:On-site application of rigid foam insulation dominates Gulf building retrofit and cold storage construction. Equipment portability suits project-based workflows where fixed production lines prove uneconomical.
- Injection Molding:High-pressure impingement mixing enables complex automotive seating components with integrated skin surfaces. Tooling investments concentrate at Tier-1 suppliers serving Gauteng assembly plants.
- Casting:Open-pour methods serve low-volume industrial rollers and mining equipment components.
- Thermoforming:Limited regional adoption for polyurethane sheet applications.
Spray technology anchors field-applied insulation; injection molding secures automotive integration.
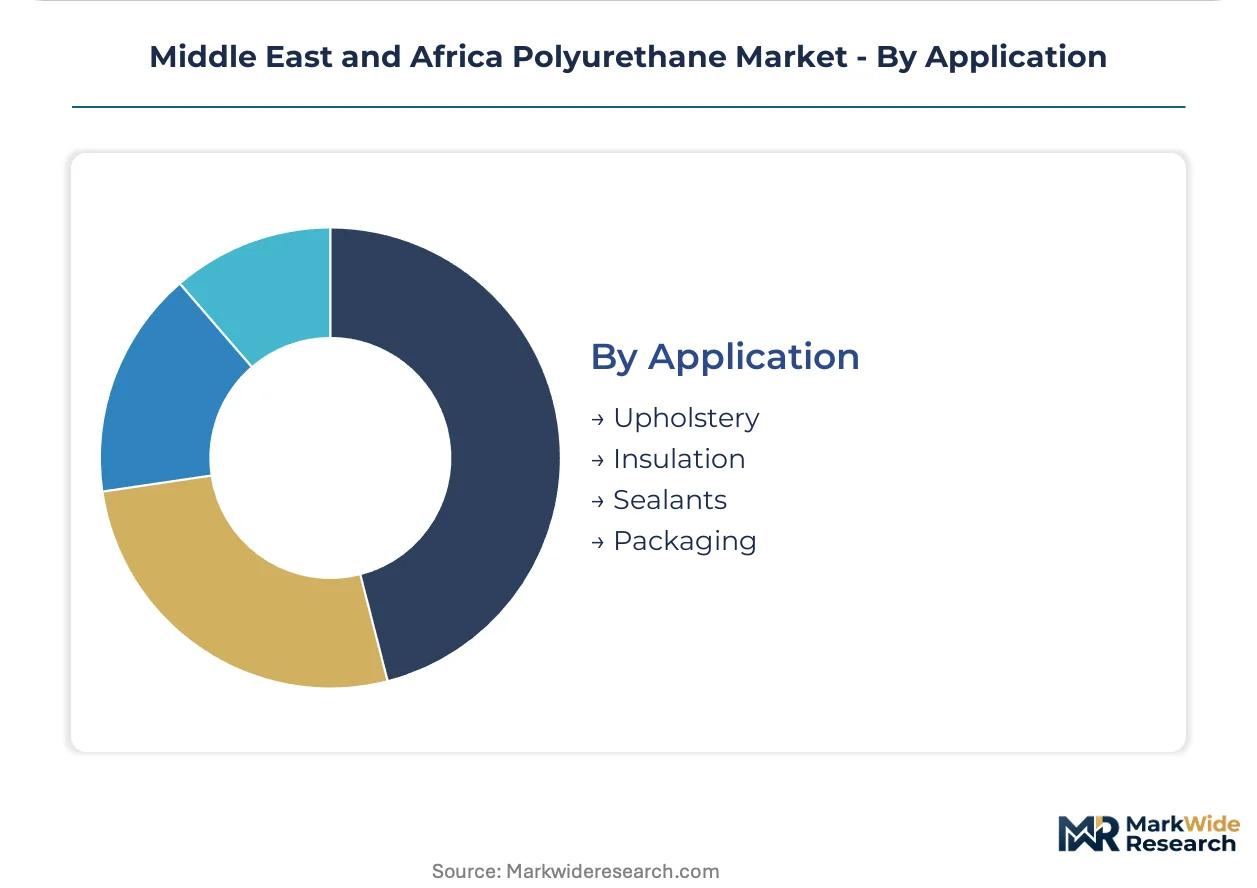
Application:
Customer type differentiation separates project-based construction contractors from OEM manufacturing programs with formal qualification requirements.
- Insulation:Rigid foam boards and spray-applied systems address Gulf cooling load reduction mandates. Saudi building code enforcement accelerates specification upgrades for residential and commercial envelopes.
- Upholstery:Flexible foam cushions serve furniture manufacturing across Egypt, Morocco, and South Africa. Density and indentation force deflection specifications vary by price tier and export destination.
- Sealants:Polyurethane caulks and adhesives bond construction joints in high-movement Gulf climate conditions.
- Packaging:Limited regional demand for protective foam inserts.
Insulation applications expand most quickly; upholstery maintains volume stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA's chemical safety frameworks anchor polyurethane regulation across Saudi Arabia, the region's dominant production hub. Gulf building codes and South African automotive localization create divergent demand profiles that reshape supply chain investments.
Saudi Arabia
Jubail Industrial City's petrochemical expansion feeds rigid foam insulation demand from Riyadh and Jeddah construction corridors. SFDA tightened isocyanate handling standards in 2024, accelerating compliant system house investments. Cement conglomerates negotiate direct procurement contracts for pre-insulated panel projects.
United Arab Emirates
MOHAP's chemical substance notification requirements extend disclosure obligations for isocyanate-containing construction materials. Infrastructure megaprojects specify weather-resistant aliphatic polyurethane coatings for extended asset life cycles. Dubai-based technical service laboratories face extended approval timelines for specialty systems.
South Africa
Gauteng province's vehicle assembly plants source flexible foam seating locally, reducing import dependency for interior components. The national environmental regulator imposes volatile organic compound limits on polyurethane coatings used in industrial and automotive finishing. Tier-1 suppliers concentrate tooling investments at injection molding facilities serving export markets.
Egypt
Mattress and upholstery manufacturers absorb commodity-grade flexible foam volumes for domestic and export markets. The country's industrial development zones attract foam converters seeking proximity to North African furniture production. Cairo-Alexandria corridor distribution networks handle bulk polyol shipments from European suppliers.
Kenya
East African construction code adoption will mandate rigid foam insulation in commercial building envelopes within five years. Nairobi's construction sector anticipates thermal efficiency standards similar to Gulf Cooperation Council templates. Local converters lack controlled atmosphere facilities for isocyanate handling, inflating import dependency for finished foam products.
Middle East and Africa Polyurethane Market Vendor Landscape
Capability concentration sits with integrated petrochemical producers; scale advantage sits with global system houses with regional technical service density. Saudi feedstock integration compresses supply chains for regional converters. Three archetypes dominate: Gulf-based petrochemical integrators with captive isocyanate supply, European system houses with specification-grade formulation expertise, and Asian producers with cost-optimized flexible foam platforms. Competitive moves center on direct procurement channel capture and low-GWP blowing agent certification.
Among European system houses, BASF SE and Covestro AG exemplify the specification-grade tier, anchoring regional competitiveness through material science platforms and specialized aliphatic isocyanate production respectively. Huntsman Corporation represents the climate-specific formulation archetype, with rigid foam systems optimized for Middle Eastern humidity conditions. SABIC anchors the petrochemical integration vector as a Jubail-based producer reshaping regional feedstock availability.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| Dow Chemical Company |
| SABIC |
| Sika AG |
| Recticel NV |
| Kingspan Group |
| Mitsui Chemicals, Inc. |
| Others |
Supply Flow & Price Mechanics
Jubail Industrial City's petrochemical capacity expansion is compressing regional feedstock costs and shifting pricing power toward integrated producers serving Gulf construction markets. This concentration enables backward-integrated system houses to undercut import-dependent competitors on rigid foam contracts while European specialty suppliers defend aliphatic coatings premiums through Dubai-based technical service density.
Pricing Analysis
Price spreads between Rotterdam-sourced specialty polyols and Jubail-produced commodity MDI systems exceed thirty percent on delivered terms to African converters. Three-tier pricing structure across specification-grade, performance-standard, and commodity-economy levels tracks certification status for Gulf building code compliance. Cost compression in flexible foam seating is intensifying because Gauteng automotive assemblers negotiate annual volume commitments with local system houses. Tier-1 construction contractors demonstrate lowest price sensitivity for pre-insulated panel systems with SFDA-compliant isocyanate documentation; furniture manufacturers in Egypt and Morocco remain most exposed to spot TDI volatility.
Supply Chain Analysis
Tariff exposure between European specialty chemical producers and East African foam converters dominates supply chain risk profiles for non-integrated distributors. Feedstock concentration rests on Saudi Arabia, Germany, and Belgium for isocyanate and catalyst supply; Chinese flexible foam equipment and Korean blowing agent technology complete the input matrix. Single-source vulnerability concentrates in aliphatic isocyanate precursors where Rotterdam-Antwerp corridor producers control specification-grade coating formulations. Distribution runs through Dubai Jebel Ali free zone warehousing for Gulf markets, with direct procurement relationships displacing traditional distributor networks for large-volume rigid foam contracts in Riyadh and Jeddah corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa polyurethane market is entering a cyclical recovery phase as Gulf construction activity rebounds from code-transition delays and South African automotive production stabilizes. This cyclical upswing favors suppliers with certified low-GWP product portfolios and established technical service infrastructure.
For Market Incumbents: Entrench specification-grade positioning by securing SFDA pre-certification for rigid foam systems ahead of REACH-equivalent GCC implementation timelines. Cement conglomerate direct procurement channels in Saudi Arabia represent the priority defensive perimeter; capacity addition in Jubail Industrial City preserves feedstock cost advantage against European import competition. Aliphatic isocyanate coating formulations for UAE infrastructure megaprojects offer margin defense against Asian commodity foam encroachment. For New Entrants and Emerging Players: Build out controlled atmosphere blending facilities in Kenya ahead of anticipated thermal efficiency code mandates for commercial building envelopes. Nairobi construction sector penetration offers the most accessible white-space target given current import dependency for finished foam products. Partnership with established Dubai distributors provides go-to-market acceleration without captive logistics investment. For Investors and Strategic Acquirers: Long-term, this sits as a petrochemical integration play because feedstock cost positioning determines competitive survival in commodity foam tiers. Acquisition targets should screen for system houses with climate-specific formulation expertise for Gulf humidity conditions and established relationships with SFDA regulatory affairs consultants. The signal to watch is accelerated direct procurement contract announcements from Saudi cement conglomerates, indicating channel consolidation velocity that will strand distributor-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Feedstock | SABIC's Jubail expansion demonstrates how captive isocyanate supply secures rigid foam margin pools in Gulf construction. |
| Low-GWP Blowing Agent Certification | Saudi building code enforcement accelerates payback for early movers with hydrofluoroolefin transition completion. |
| Dubai Technical Service Laboratory Establishment | MOHAP extended approval timelines favor suppliers with local formulation support for infrastructure coating specifications. |
| Gauteng Flexible Foam Capacity Expansion | Tier-1 supplier tooling investments align with South African automotive localization mandates reducing import dependency. |
| SFDA Regulatory Affairs Partnership | Pre-certification investment de-risks portfolio planning uncertainty from evolving GCC chemical registration timelines. |
Methodological Framework
Operator-level perspectives from rigid foam system house technical directors, polyurethane procurement leads at Saudi cement conglomerates, SFDA regulatory affairs consultants, and flexible foam plant managers in Gauteng province anchored the qualitative base. Secondary validation drew from customs and trade data, GCC construction code documentation, SEC filings of listed chemical producers, and SABIC capacity expansion disclosures. Bottom-up segment sizing triangulated against top-down petrochemical feedstock availability assessments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with sensitivity analysis on MDI feedstock cost trajectories and Gulf building code enforcement intensity. Segmentation dimensions modeled included product type tier, end-use industry concentration, processing technology deployment, and regional regulatory cluster. CAGRs derived from regression against construction spending indices and automotive production forecasts, with explicit incorporation of SFDA chemical safety framework implementation pace and Kenya thermal efficiency code adoption trajectory.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Asian petrochemical producers or accelerated REACH-equivalent GCC harmonization would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
PE Resins Market
Polymers & Resins
Global Bio Polyamide Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
PEKK Market