
 Polyimides Market | 2026-2036
Polyimides Market Size, Share, and Industry Trends Forecast 2026-2036
Polyimides Market Outlook
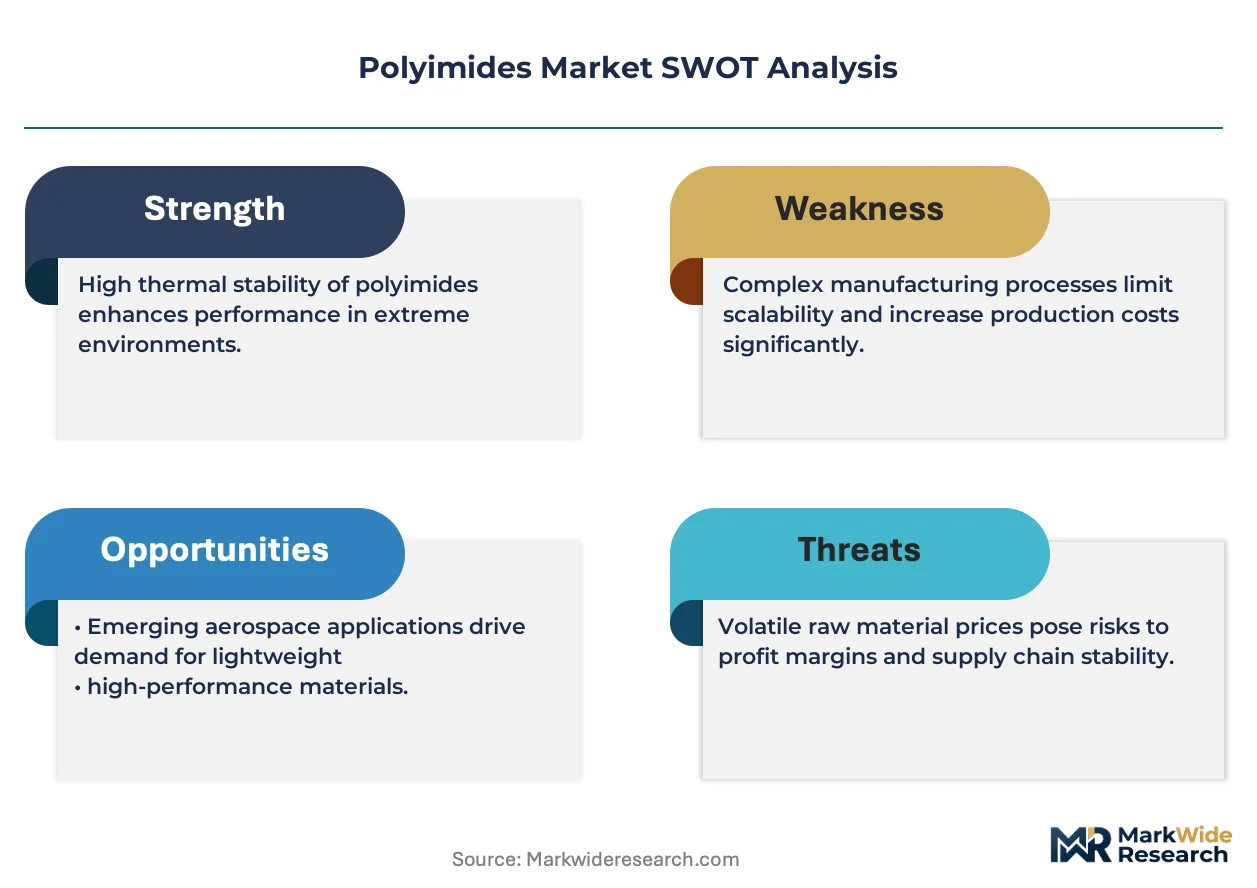
China is tilting its polyimide capacity build-out toward electronic-grade films and high-purity resins for domestic semiconductor self-sufficiency. DuPont leverages its century-long polymer science heritage and vertical integration across monomer-to-film production to sustain premium positioning in aerospace and flexible electronics substrates. Kaneka Corporation anchors the Asia-Pacific supply base through proprietary biphenyl-tetracarboxylic dianhydride chemistry and captive demand from its own electronics materials downstream operations. PI Advanced Materials Co., Ltd. competes aggressively on price-performance metrics for display-oriented polyimide films, while Toray Industries, Inc. extends its carbon fiber composites expertise into thermoplastic polyimide structures for lightweighting applications.
Polyimides constitute a class of high-performance polymers characterized by imide ring structures in their backbone, typically synthesized from dianhydrides and diamines through a two-step polycondensation yielding thermal stability exceeding 300 degrees Celsius and dielectric constants below 3.5. These properties enable their primary function as insulating substrates, protective coatings, and structural components in environments where conventional polymers degrade. Polyimide films currently dominate value generation due to their irreplaceable role in flexible printed circuit boards and chip packaging, while thermoplastic polyimides represent the fastest-growing product category as moldable alternatives to thermosets in automotive thermal management and connector housings. Semiconductor companies among end users command the deepest margin pools because their qualification cycles create sticky supplier relationships and justify premium pricing for lot-controlled electronic-grade material.
The EPA regulates perfluorinated compound emissions from polyimide precursor manufacturing under the Toxic Substances Control Act, compelling U.S. producers to invest in closed-loop solvent recovery and alternative dianhydride feedstocks. REACH registration requirements and the EU F-Gas Regulation constrain fluorinated monomer availability for certain specialty polyimide grades, redirecting formulation development toward partially fluorinated or non-fluorinated architectures in Europe. China's GB standards and MIIT industrial policy directives are accelerating domestic substitution campaigns that favor local producers like PI Advanced Materials while tightening import specifications for foreign suppliers. Stakeholders must monitor how divergent regulatory timelines for chemical hazard reclassification across these jurisdictions reshape competitive access and qualification burdens without assuming synchronized implementation.
Market Dynamics
Semiconductor packaging miniaturization is compressing dielectric thickness requirements below 5 micrometers, forcing polyimide suppliers to retool solvent casting lines and validate new dianhydride formulations under accelerated thermal cycling protocols.
Growth Catalysts
- Flexible Display Substrate Demand:Foldable smartphone panel manufacturers in South Korea are qualifying colorless polyimide films for cover window applications, pulling capacity away from traditional yellow Kapton-type supply chains.
- REACH Substance Restrictions:The EU F-Gas Regulation and ECHA candidate list updates are disqualifying perfluorinated precursors, creating first-mover advantage for European producers with non-fluorinated dianhydride capabilities.
- High-Temperature Connector Resins:Electric vehicle inverters operating above 150 degrees Celsius are specifying thermoplastic polyimide housings, displacing PPS and PEEK in 800-volt architectures.
Market Restraints
- Pyromellitic Dianhydride Supply Concentration:Chinese producers control 70% of PMDA feedstock for standard polyimide grades, exposing non-integrated film manufacturers to export quota volatility and freight cost spikes.
- Fluorinated Monomer Cost Structure:Heptafluoroisopropylidene dianhydride prices track refrigerant chemical markets, creating 40% input cost swings for low-dielectric semiconductor-grade formulations.
- Thermoset Processing Limitations:C-stage imidization requires 300-degree curing ovens that constrain substrate width and throughput, capping film production economics versus extrudable thermoplastic alternatives.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging and display assembly are attracting polyimide film qualification programs from first-tier substrate laminators in Gujarat and Tamil Nadu.
- AI Accelerator Thermal Interface:Chiplet architectures with 1000-watt TDP envelopes are specifying polyimide-based phase change materials as TIM substrates, opening a $200-million addressable pool by 2030.
- EU Battery Separator Coatings:The EU Green Deal's domestic cell production mandates are driving ceramic-coated polyimide separator trials for solid-state lithium metal prototypes.
Industry Challenges
- Electronic-Grade Chemist Scarcity:Polycondensation process engineers with cleanroom monomer synthesis experience command 40% salary premiums, constraining capacity expansion timelines for mid-tier producers.
- Automotive Qualification Cycles:PPAP submission and thermal aging validation for under-hood connectors extends 18-24 months, freezing formulation changes and locking suppliers into legacy dianhydride sources.
- Closed-Loop Solvent Recovery:N-methyl-2-pyrrolidone recycling infrastructure requires $50-million capital commitments per production line, disadvantaging regional players against integrated chemical conglomerates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyimides Market |
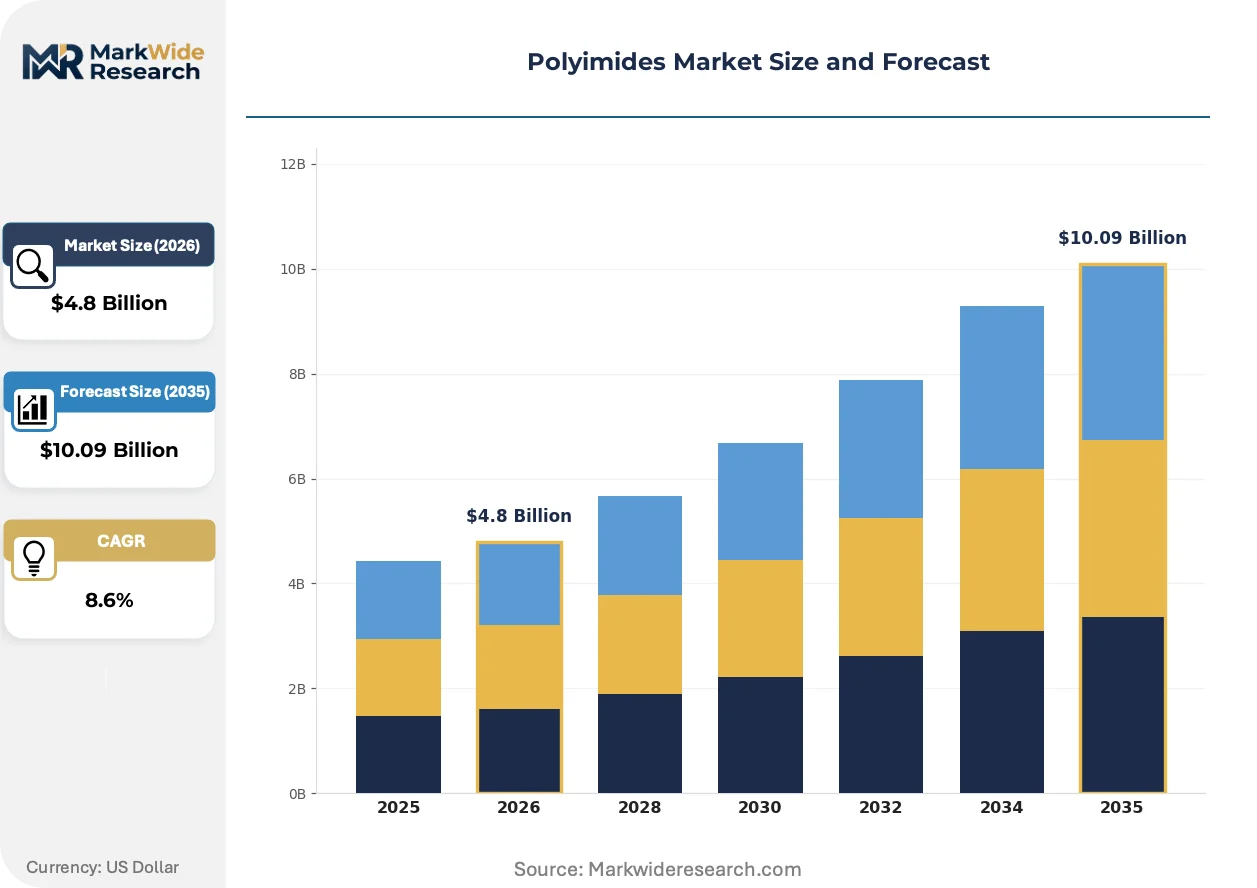
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soluble Polyimides, Thermoplastic Polyimides, Polyimide Films, Polyimide Resins Application: Aerospace, Electronics, Automotive, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Semiconductor Companies, Telecom Providers Distribution Channel: Distributors, Online Retail, Direct Sales, B2B Sales |
| Companies Covered | DuPont, Kaneka Corporation, PI Advanced Materials Co., Ltd., Ube Industries Ltd., Toray Industries, Inc., Arkema, Kolon Industries, Inc., Taimide Tech. Inc., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyimides Market Strategic Shifts
Digital twin deployment across polyimide film casting operations is compressing defect detection latency from hours to seconds, while regulatory chemistry restrictions and buyer consolidation are rewriting supplier qualification hierarchies.
Colorless polyimide synthesis via alicyclic dianhydride substitution is digitizing quality control workflows throughout the supply chain. Display panel manufacturers in South Korea and China are adopting these films for foldable device cover windows at qualification rates exceeding 500,000 square meters annually. The technology is digitizing incoming inspection protocols, replacing visual birefringence checks with automated optical metrology that feeds directly into MES systems.
The EPA's Toxic Substances Control Act Section 5 premanufacture notification requirements for new dianhydride chemistries are lengthening commercialization timelines for US-based innovators. Industrial consequence includes a 12-18 month gap between laboratory validation and commercial film sampling, favoring incumbent producers with existing substance inventories. Semiconductor packaging substrate suppliers are responding by dual-sourcing from European and Asian producers with REACH-registered alternative monomers.
Consolidated procurement by display panel oligopolists is compressing supplier margins and mandating vendor-managed inventory arrangements. Samsung Display and BOE Technology are replacing spot purchasing with three-year take-or-pay contracts indexed to wafer starts, displacing distributor intermediaries. This pattern is most visible in South Korea, where domestic polyimide producers maintain 48-hour finished goods availability at customer fabs under consignment stocking agreements.
Polyimides Market Segmentation
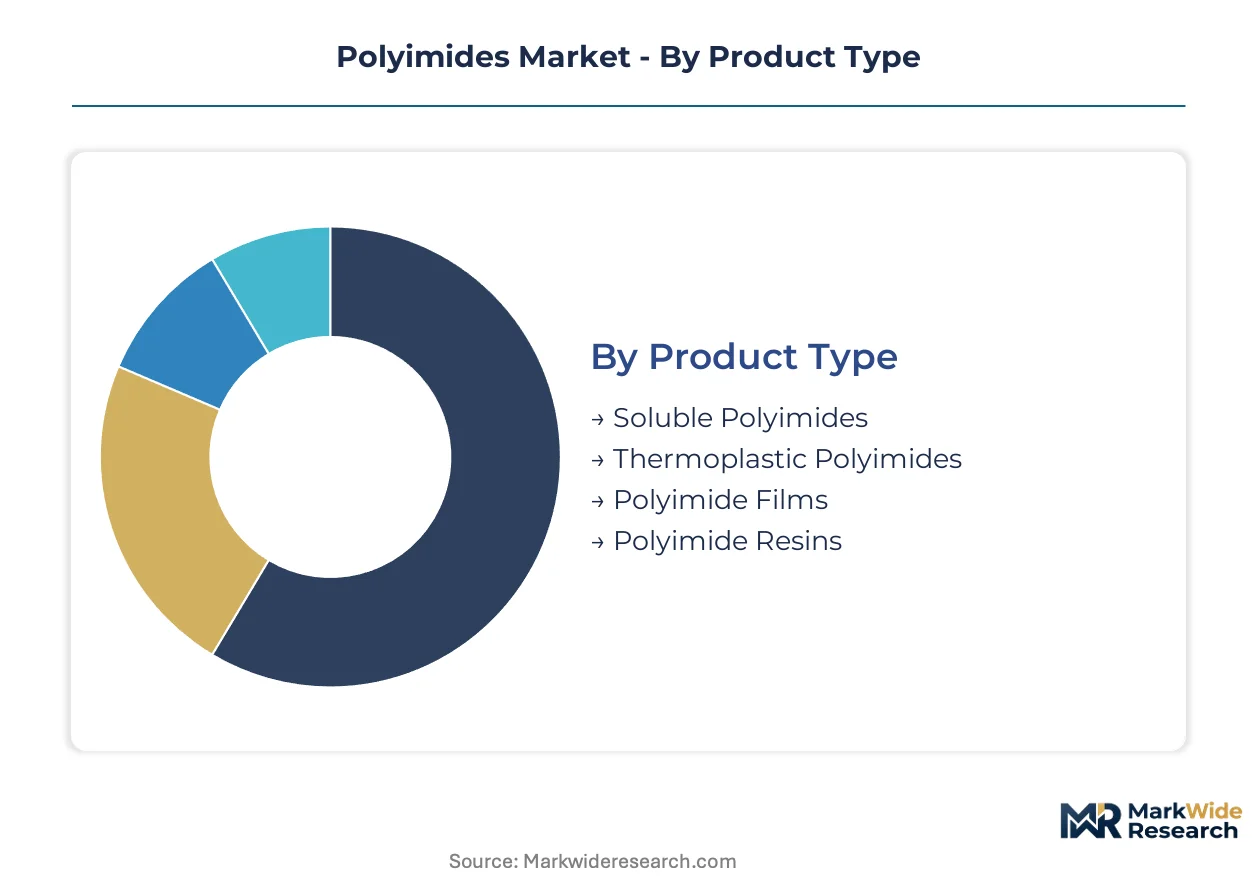
Polyimide buyers source across four distinct category hierarchies, each with divergent procurement cycles and qualification burdens. Semiconductor-grade films demand 18-month validation timelines, while industrial resin spot purchases turn within weeks.
Product Type:
Cycle times vary dramatically: polyimide films lock customers into multi-year supply agreements, whereas soluble polyimides sample within days.
- Polyimide Films:Cast from polyamic acid precursors on stainless steel drums, these substrates achieve sub-5-micron thickness for chip-scale packaging. Samsung Display and BOE Technology in South Korea are pulling capacity toward colorless cover-window grades for foldable panels, tightening availability for traditional yellow Kapton-type supply chains.
- Thermoplastic Polyimides:Moldable alternatives to thermoset architectures, these resins melt-process at 300-350 degrees Celsius without post-curing ovens. Electric vehicle inverter manufacturers in Germany are specifying these housings for 800-volt architectures, displacing PPS and PEEK in high-temperature connector applications.
- Soluble Polyimides:Pre-imidized polymers dissolved in amide solvents for thin-film coating applications.
- Polyimide Resins:Powder and liquid formulations for composite matrices and adhesive bonding.
Polyimide films anchor the volume base while thermoplastic polyimides gain share at the steepest rate.
Application:
Margin structures diverge sharply: aerospace programs amortize R&D across decade-long contracts, whereas electronics contracts reprice annually.
- Electronics:Flexible printed circuit boards and chip packaging substrates consume the majority of electronic-grade film output. South Korean semiconductor fabs are scaling procurement for advanced node production, with qualification cycles creating sticky supplier relationships that justify lot-controlled material premiums.
- Aerospace:Wire insulation and thermal blankets on commercial aircraft leverage polyimide's 300-plus-degree Celsius stability. DuPont maintains premium positioning here through FAA-certified material traceability and vertical integration from monomer to finished film.
- Automotive:Under-hood connectors and thermal management components.
- Industrial Equipment:Bearings, seals, and process equipment coatings.
Electronics commands the deepest margin pools while automotive expands most quickly as electrification thermal requirements intensify.
End User:
Procurement sophistication separates semiconductor companies with cleanroom monomer specifications from industrial OEMs buying standard grades.
- Semiconductor Companies:These buyers enforce lot-controlled electronic-grade standards with sub-ppm metallic impurity limits. REACH and RoHS compliance requirements in the European Union are tightening material purity standards and reshaping supplier qualification protocols for this segment.
- Tier-1 Suppliers:Automotive and electronics contract manufacturers qualifying polyimide components for downstream OEM assembly.
- OEMs:Original equipment manufacturers with captive molding operations.
- Telecom Providers:Infrastructure builders specifying cable and substrate materials.
Semiconductor companies concentrate procurement value while Tier-1 suppliers multiply qualified vendor counts to mitigate disruption risk.
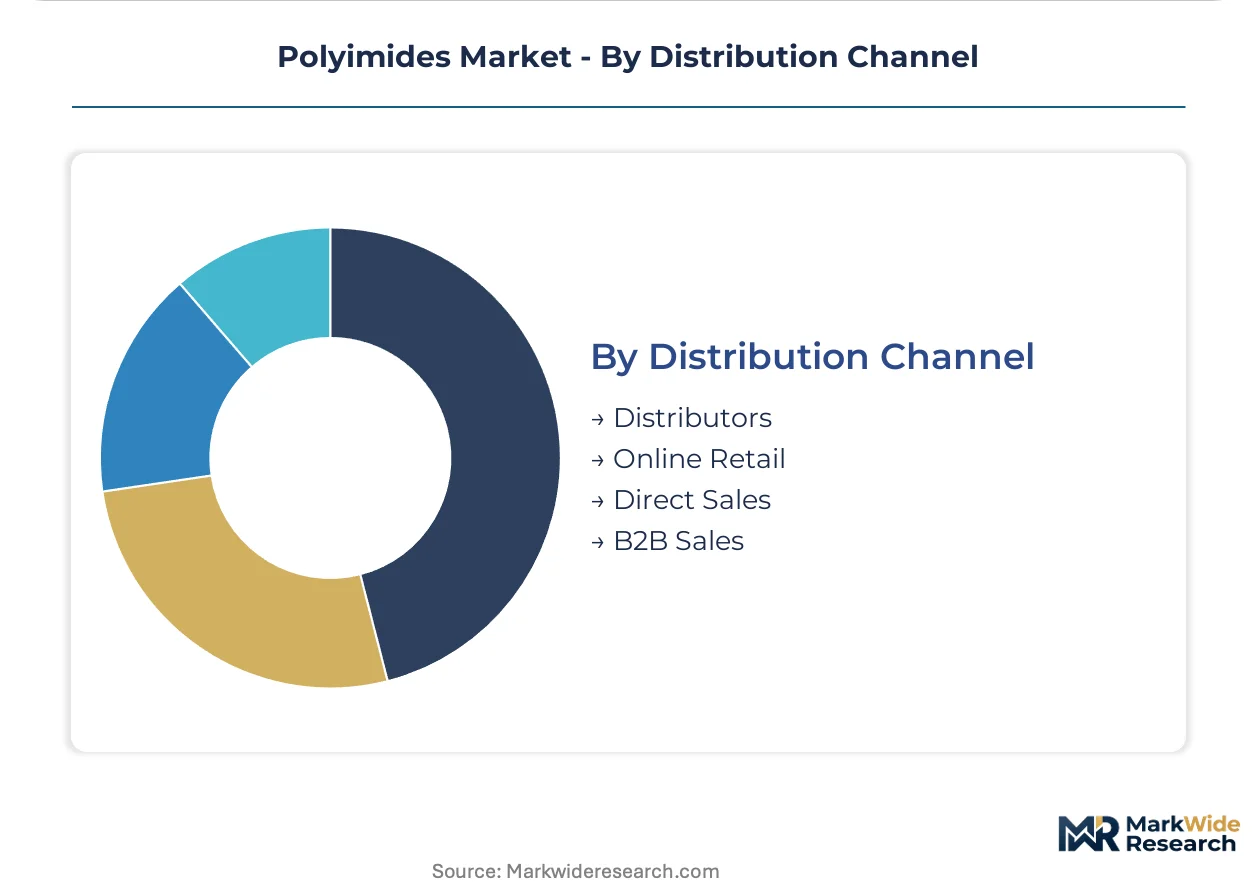
Distribution Channel:
Channel economics reflect order fragmentation: direct sales capture bulk film contracts, while distributors serve small-lot resin buyers.
- Direct Sales:Film manufacturers maintain dedicated account teams for display panel oligopolists. Samsung Display and BOE Technology have replaced spot purchasing with three-year take-or-pay contracts indexed to wafer starts, displacing distributor intermediaries entirely.
- B2B Sales:Long-term supply agreements with industrial compounders and laminators.
- Distributors:Regional stocking points for standard-grade resins and small-volume film orders.
- Online Retail:Catalog sales of research quantities and specialty formulations.
Direct sales anchors contract value while B2B sales climbs fastest as procurement centralizes among consolidated buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese producers command 70% of pyromellitic dianhydride feedstock for standard polyimide grades, concentrating upstream chemical supply in East Asia while South Korean semiconductor fabs and display panel makers drive downstream demand concentration.
United States
EPA regulations under the Toxic Substances Control Act govern perfluorinated compound emissions from polyimide precursor manufacturing. The agency's Section 5 premanufacture notification requirements extend commercialization timelines for new dianhydride chemistries by 12-18 months. Aerospace wire insulation demand clusters in California and Washington state, where DuPont maintains FAA-certified material traceability systems.
Germany
Electric vehicle inverter manufacturers specify thermoplastic polyimide housings for 800-volt architectures, displacing PPS and PEEK in high-temperature connector applications. The EU F-Gas Regulation and ECHA candidate list updates disqualify perfluorinated precursors, redirecting formulation development toward non-fluorinated architectures. Automotive qualification activity concentrates in Baden-Württemberg and Bavaria.
South Korea
Samsung Display and domestic semiconductor fabs scale polyimide procurement for advanced node production and foldable smartphone panel manufacturing. REACH and RoHS compliance requirements reshape supplier qualification protocols for electronics-grade material. Seoul Capital Area producers maintain 48-hour finished goods availability under consignment stocking agreements.
China
MIIT industrial policy directives and GB standards accelerate domestic substitution campaigns favoring local producers. Yangtze River Delta capacity build-out targets electronic-grade films and high-purity resins for semiconductor self-sufficiency. PI Advanced Materials competes aggressively on price-performance metrics for display-oriented films from production bases in this cluster.
India
PLI scheme incentives for semiconductor packaging and display assembly attract polyimide film qualification programs from substrate laminators. Gujarat and Tamil Nadu host the primary concentration of new electronics manufacturing capacity. The country's national chemical regulator tightens import specifications as domestic production scales.
Polyimides Market Competitive Environment
Integrated chemical conglomerates and specialized polymer film producers split the market into distinct capability tiers. Consolidation pressures concentrate among mid-scale resin compounders lacking captive monomer supply. Three archetypes dominate: vertically integrated monomer-to-film operators, electronics-focused substrate specialists, and diversified materials conglomerates with aerospace heritage. Capacity expansion and backward integration into dianhydride feedstocks constitute the dominant competitive moves.
Within the integrated chemical tier, DuPont and Kaneka Corporation exemplify archetypes built on polymer science heritage and proprietary biphenyl-tetracarboxylic dianhydride chemistry respectively. PI Advanced Materials Co., Ltd. occupies a position representing aggressive price-performance competition for display-oriented applications. These three entities anchor the competitive structure without exhausting the vendor landscape.
| Leading Market Players |
|---|
| DuPont |
| Kaneka Corporation |
| PI Advanced Materials Co., Ltd. |
| Ube Industries Ltd. |
| Toray Industries, Inc. |
| Arkema |
| Kolon Industries, Inc. |
| Taimide Tech. Inc. |
| SABIC |
| Others |
Value Chain & Pricing Dynamics
Chinese PMDA export quota volatility determines both the spread between electronic-grade and industrial-grade pricing tiers and the geographic configuration of film manufacturing capacity. Semiconductor packaging substrate suppliers respond to this feedstock concentration by dual-sourcing from South Korean and European producers with captive dianhydride supply, compressing margins for non-integrated compounders while amplifying pricing power for vertically integrated operators.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across the European supply base, where non-fluorinated dianhydride capabilities command 15-20% premiums over standard grades. Three-tier pricing structure across premium, standard, and economy levels separates lot-controlled electronic-grade film from display-grade commercial material and industrial resin spot purchases. Cost compression in standard-grade segments is intensifying because Chinese producers are expanding electronic-grade capacity for domestic semiconductor self-sufficiency. Display panel oligopolists exhibit the least price sensitivity due to three-year take-or-pay contracts, while industrial OEMs buying soluble polyimides on spot terms face the most volatility.
Supply Chain Analysis
Extended payment terms from display panel oligopolists are reshaping working capital requirements for mid-scale film manufacturers, favoring chemical conglomerates with balance-sheet depth. Raw material supply concentrates in China for pyromellitic dianhydride, South Korea for electronic-grade films, and Germany for thermoplastic polyimide compounds. The supply chain draws from fluorinated monomer feedstocks, high-purity diamine precursors, and stainless steel casting equipment as critical inputs. Single-source vulnerability runs through Chinese PMDA export quotas, which expose non-integrated producers to abrupt feedstock disruption. Distribution runs through direct sales teams for display and semiconductor customers, with regional distributors serving small-lot industrial resin buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement by Samsung Display and BOE Technology has shifted bargaining power decisively toward substrate buyers, forcing suppliers into vendor-managed inventory arrangements and multi-year contract structures that freeze formulation flexibility.
For Market Incumbents: Build regulatory moats around REACH-registered alternative monomers and EPA-compliant closed-loop solvent recovery systems. DuPont and Kaneka Corporation should deepen backward integration into biphenyl-tetracarboxylic dianhydride feedstocks to insulate margin structures from Chinese PMDA quota volatility. Capacity addition in South Korea's Seoul Capital Area reinforces proximity to Samsung Display's consignment stocking requirements. For New Entrants and Emerging Players: Thermoplastic polyimide supply for 800-volt electric vehicle inverters in Germany represents the most penetrable entry point, given 18-24 month automotive qualification cycles that freeze incumbent formulations. India's Gujarat and Tamil Nadu electronics manufacturing clusters under PLI scheme incentives offer second-mover qualification opportunities as substrate laminators diversify beyond South Korean supply. A technical service partnership with German Tier 1 automotive suppliers accelerates PPAP submission timelines. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated monomer-to-film operators with electronic-grade certification and captive dianhydride supply. Long-term viability over the next decade hinges on positioning against Chinese domestic substitution campaigns and EU F-Gas regulatory trajectories. Watch for ECHA candidate list updates on fluorinated precursors as the inflection signal that reallocates value toward non-fluorinated formulation capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dianhydride Feedstocks | Captive PMDA supply insulates margin structures from Chinese export quota volatility. |
| Non-Fluorinated Formulation Development | REACH compliance creates first-mover advantage in European semiconductor packaging supply. |
| Consignment Stocking Agreements | 48-hour finished goods availability at Samsung Display fabs locks out distributor intermediaries. |
| Automotive Qualification Programs | PPAP submission for 800-volt inverter housings displaces PPS and PEEK in thermal management. |
| India PLI Scheme Localization | Gujarat and Tamil Nadu substrate laminator partnerships capture electronics manufacturing incentives. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polyimide plant managers, procurement leads at semiconductor packaging substrate suppliers, distribution channel partners for industrial resin sales, and technical R&D directors at film casting operations. Secondary validation drew from customs and trade data, chemical industry association reports, SEC 10-K filings for listed materials conglomerates, and EPA Toxic Substances Control Act premanufacture notification records. Bottom-up capacity and utilization estimates triangulated against top-down demand segmentation across electronics, aerospace, and automotive end-uses.
Calibration against historical price series and capacity expansion announcements anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type hierarchy, application-grade tier, end-user procurement sophistication, and regional production hub classification. CAGRs were derived from elasticity-adjusted demand projections and supply-side constraint modeling. Forecast inputs incorporated semiconductor wafer start forecasts, electric vehicle inverter production ramps, and display panel area expansion schedules.
Practitioners should monitor regulatory chemistry reclassification timelines, Chinese MIIT industrial policy directive updates, and automotive OEM thermal management specification shifts for early signals of forecast deviation. Assumptions underlying projections reflect current qualification cycle durations, feedstock trade flow patterns, and buyer consolidation trajectories. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Acrylic Monomers Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Polyetherketoneketone (PEKK) Market