
 Polyvinyl Alcohol (PVA) Market | 2026-2036
Polyvinyl Alcohol (PVA) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyvinyl Alcohol (PVA) Market Analytics
Maintenance and technical support contracts for polymer processing equipment is expanding as a distinct revenue layer in PVA value chains. Kuraray Co., Ltd. leverages its captive vinyl acetate supply to anchor high-purity grades for optical films. Wacker Chemie AG competes through specialized dispersions for European construction adhesives. Sekisui Chemical Co., Ltd. dominates medical-grade PVA hydrogel formulations for ophthalmic applications.
Polyvinyl alcohol is a synthetic water-soluble polymer produced through partial or complete hydrolysis of polyvinyl acetate, with degrees of hydrolysis ranging from 80% to 99%+ determining solubility and crystallinity profiles. It functions primarily as a film-forming agent, emulsifier, and adhesive binder across paper, textile, and packaging industries. Fully hydrolyzed PVA grades command premium positioning in barrier film applications where oxygen resistance and oil repellency justify higher formulation costs. Partially hydrolyzed PVA sustains volume leadership in textile warp sizing and paper surface coatings where moderate water solubility optimizes process economics. Specialty-grade PVA copolymers represent the fastest-expanding margin pool, particularly in pharmaceutical tablet coatings and agricultural seed-tape formulations.
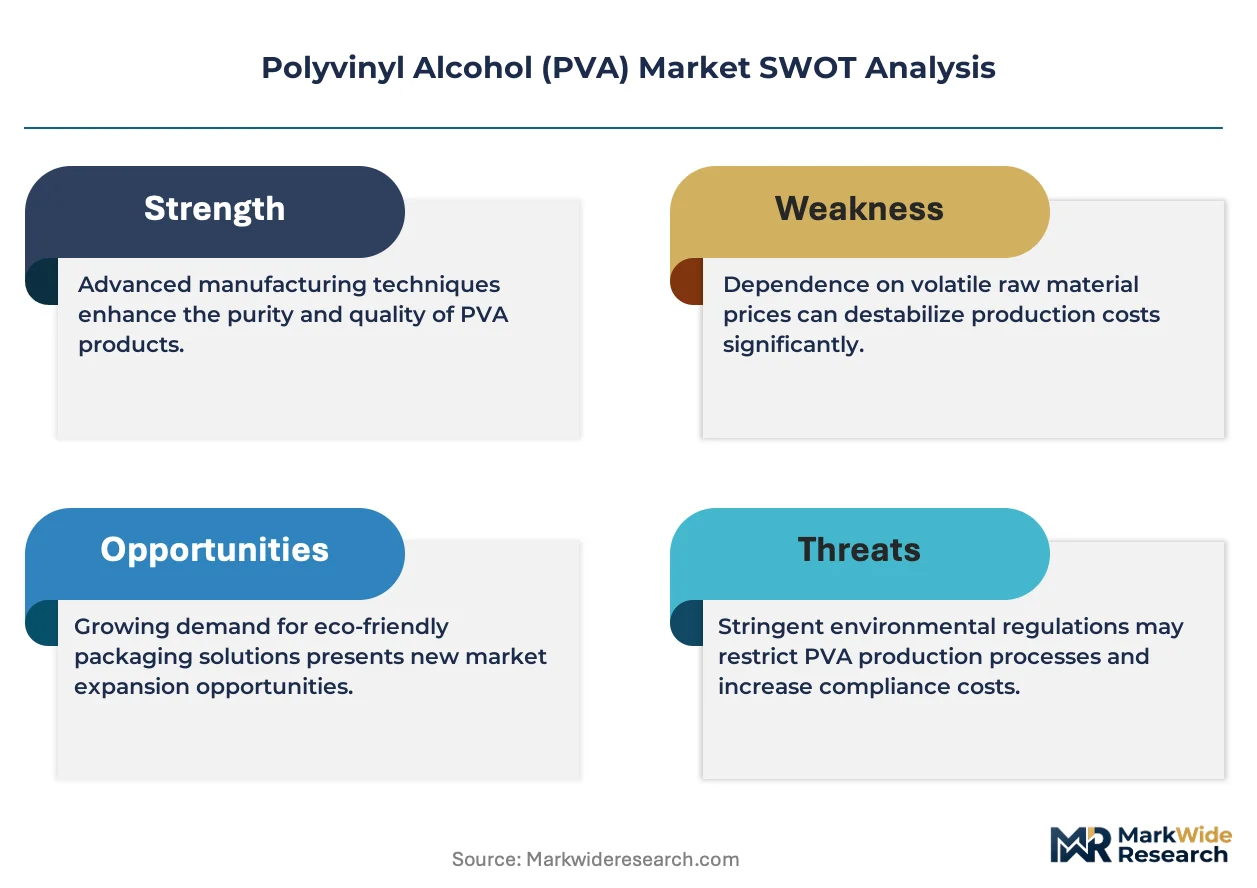
REACH registration requirements in Europe and China's GB standards for food-contact materials constrain import eligibility and reformulation timelines for non-compliant producers. The EPA's emerging framework on per- and polyfluoroalkyl substance alternatives is redirecting coating manufacturers toward PVA-based barrier systems in US consumer goods. Japan's PMDA and METI jointly govern medical-device-grade PVA through JIS standards and pharmaceutical excipient monographs. Stakeholders must monitor regulatory divergence between biodegradable certification schemes and actual composting infrastructure readiness before committing capital to next-generation water-soluble packaging lines.
Market Dynamics
Water-soluble film demand in unit-dose detergents and agrochemicals is compressing formulation timelines while China's GB standards and Japan's METI circular-economy guidelines tighten material specifications across East Asian manufacturing clusters.
Growth Catalysts
- Biodegradable packaging mandates:China's GB standards for food-contact materials and compostable film certification are accelerating PVA substitution for conventional plastics in Shanghai corridor manufacturing.
- Agrochemical unit-dose adoption:Water-soluble PVA film for pesticide and fertilizer packaging eliminates manual measuring hazards while enabling precise application rates in precision agriculture systems.
- Per- and polyfluoroalkyl substance phase-outs:The EPA's emerging framework on PFAS alternatives redirects coating manufacturers toward PVA-based barrier systems in US consumer goods.
Market Restraints
- Vinyl acetate monomer volatility:Acetic acid and ethylene feedstock price swings compress margin stability for non-integrated PVA producers lacking captive vinyl acetate supply.
- Composting infrastructure gaps:Biodegradable certification schemes in Europe and North America outrun actual industrial composting facility availability, creating performance-validity disputes for water-soluble packaging claims.
- Polyethylene competition:Linear low-density polyethylene maintains cost advantage in non-soluble film applications where disposal convenience outweighs biodegradability premiums.
Strategic Opportunities
- Medical-grade hydrogel expansion:PMDA and METI joint governance of pharmaceutical excipient monographs in Japan creates compliance moats for ophthalmic and wound-care hydrogel formulations.
- Construction adhesive specialization:European dispersion markets reward PVA copolymers with modified hydrolysis profiles for cementitious binder and tile adhesive applications.
- Seed-tape agricultural automation:Precision planting equipment adoption in North American and European large-scale farming creates demand for PVA-encapsulated seed tapes with controlled dissolution rates.
Industry Challenges
- REACH registration timelines:ECHA substance evaluation protocols for imported PVA grades extend reformulation windows by 18-24 months for non-European producers seeking European construction adhesive markets.
- Degree-of-hydrolysis customization:Textile warp sizing and paper coating segments require precise 80-99% hydrolysis range matching, demanding flexible reactor configurations that strain capital deployment efficiency.
- Cross-regulatory divergence:Japan's JIS standards for medical-device-grade PVA, China's GB food-contact protocols, and EPA emerging chemical frameworks create fragmented compliance documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyvinyl Alcohol (PVA) Market |
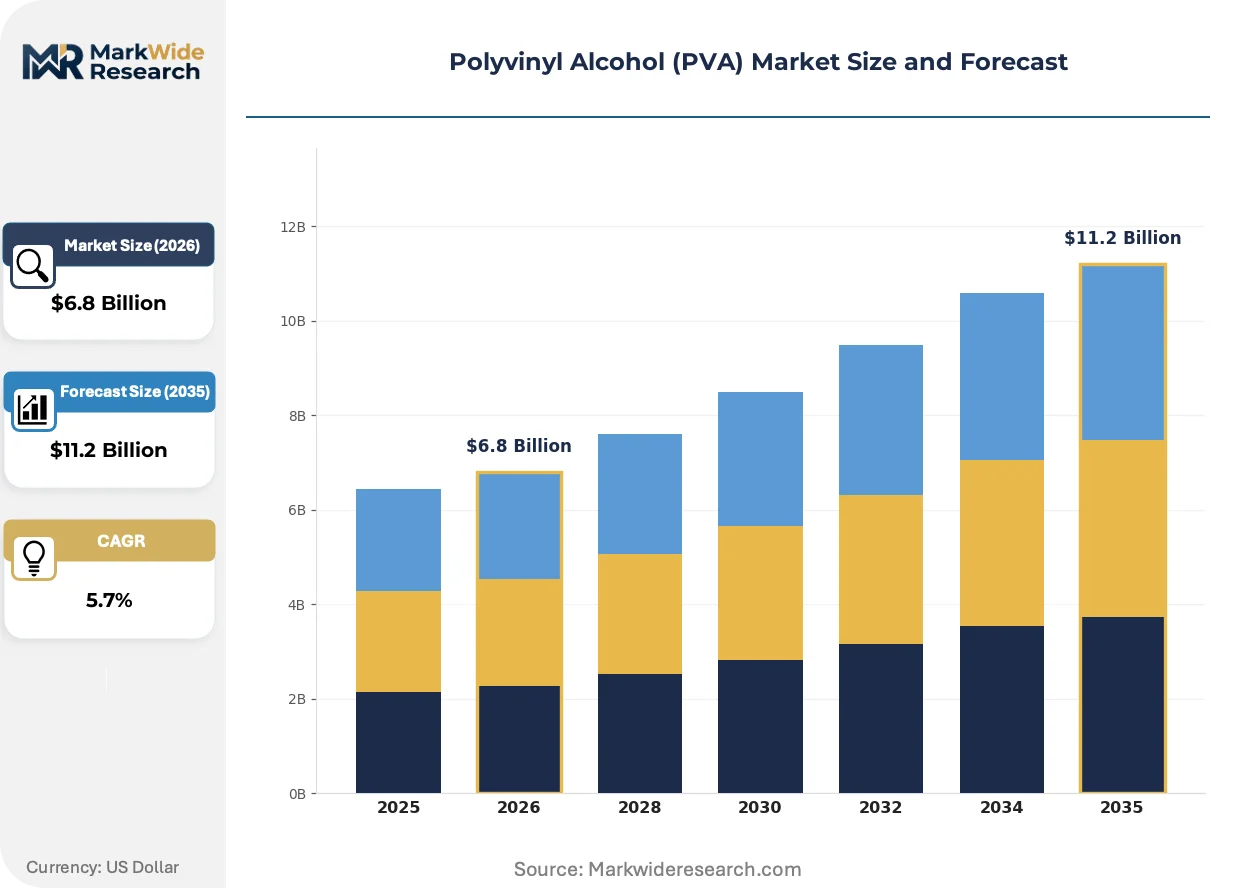
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrolyzed PVA, Partially Hydrolyzed PVA, Fully Hydrolyzed PVA, PVA Copolymers Application: Textiles, Paper Coatings, Adhesives, Films End User: Construction, Healthcare, Packaging, Agriculture Grade: High-Performance, Standard, Industrial, Specialty |
| Companies Covered | Aicello Corporation, Wacker Chemie AG, Kuraray Co., Ltd., Nippon Synthetic Chemical Industry Co., Eastman Chemical Company, Sekisui Chemical Co., Ltd., Chang Chun Group, Anhui Wanwei Group Co., Ltd., Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyvinyl Alcohol (PVA) Market Evolving Landscape
Continuous hydrolysis reactor automation and real-time degree-of-hydrolysis monitoring are compressing batch-to-batch variability while regulatory divergence between biodegradable certification schemes and composting infrastructure readiness is forcing capital commitment delays.
Advanced process control systems with inline viscometry and near-infrared spectroscopy are automating hydrolysis endpoint detection in PVA production. Specialty-grade manufacturers in Osaka and Shanghai industrial corridors are deploying these systems to reduce off-specification rates. This automation is compressing quality assurance labor costs while enabling just-in-time customization for pharmaceutical and optical film clients.
REACH registration requirements in Europe now mandate granular substance identity documentation for polyvinyl acetate hydrolysis intermediates. The industrial consequence extends reformulation timelines for Asian exporters seeking construction adhesive and paper coating markets. German and French chemical distributors are responding by consolidating import documentation services to offset compliance friction.
Unit-dose detergent brands are unbundling film specification from equipment supply contracts, creating direct procurement relationships with PVA resin producers. This channel disintermediation bypasses traditional compounder intermediaries in European and North American household goods supply chains. The shift is most visible in German and US markets where private-label detergent concentration accelerates price transparency demands.
Polyvinyl Alcohol (PVA) Market Segmentation
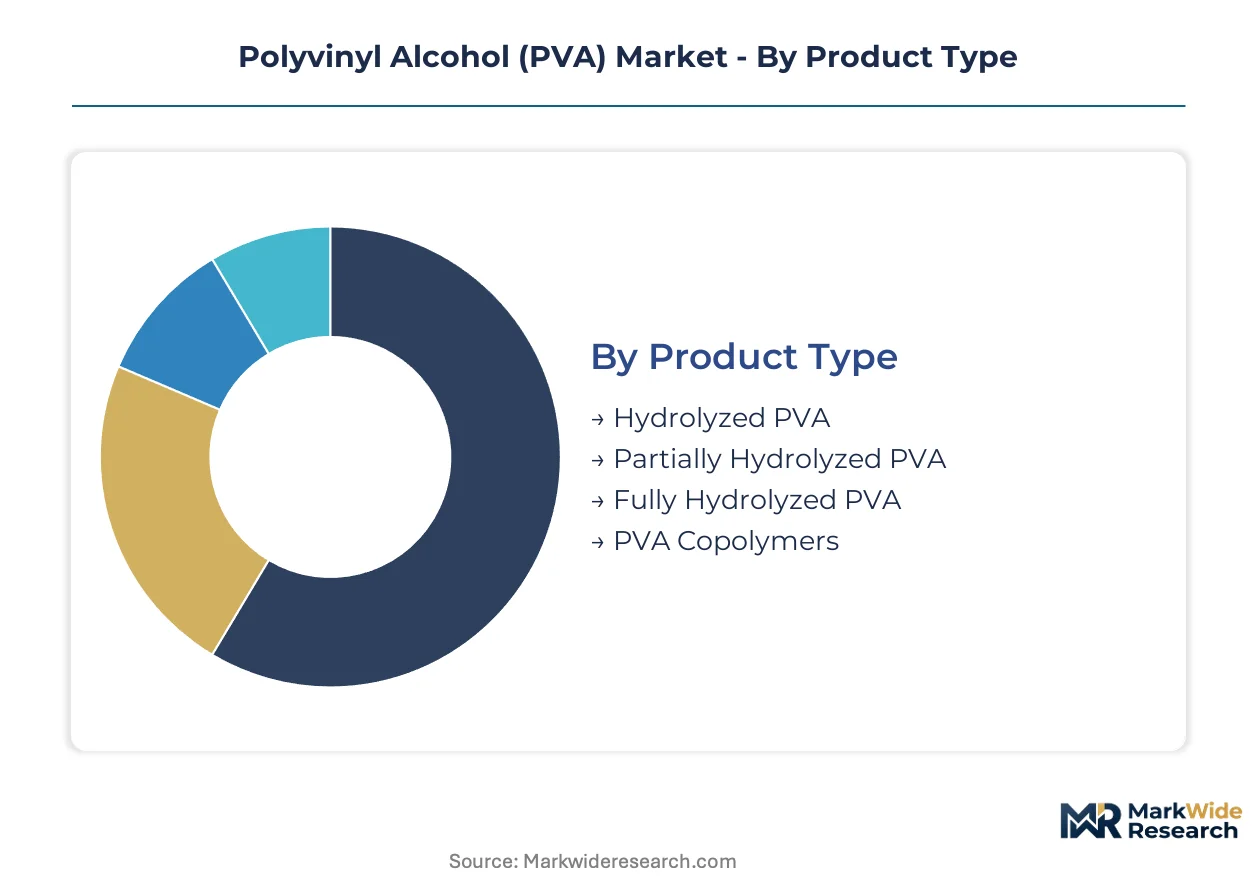
Segmentation in PVA markets reveals how hydrolysis chemistry, application performance thresholds, and regulatory compliance tiers create distinct margin architectures. Manufacturers configure reactor assets and certification pathways around specific segment requirements rather than pursuing undifferentiated commodity scale.
Product Type:
Supply concentration in East Asian vinyl acetate corridors shapes competitive positioning across hydrolysis grades, with captive monomer integration determining purity thresholds and cost structures.
- Fully Hydrolyzed PVA:These grades achieve 98-99%+ hydrolysis with minimal residual acetate groups, delivering superior oxygen barrier and oil repellency for food-contact films. Demand concentrates in Japanese optical film manufacturing and Chinese biodegradable packaging lines serving Shanghai-based consumer goods brands. Kuraray and Sekisui Chemical dominate supply through proprietary continuous hydrolysis systems.
- Partially Hydrolyzed PVA:Retaining 12-20% acetate content, these grades balance water solubility with film flexibility for textile warp sizing and paper surface coatings. Volume leadership sits with Chinese producers supplying Yangtze River Delta textile mills where process economics favor moderate hydrolysis over premium barrier performance.
- Hydrolyzed PVA:Intermediate grades spanning 87-98% hydrolysis serve adhesive formulators requiring tunable viscosity and set times for construction and woodworking applications.
- PVA Copolymers:Modified backbones incorporating ethylene, acrylic acid, or silanol groups expand thermal stability and crosslinking density for specialty coatings.
Fully hydrolyzed grades absorb the bulk of installed capacity in Japanese and Korean optical film corridors; PVA copolymers are expanding most quickly in pharmaceutical excipient and seed-tape encapsulation segments.
Application:
Cost tier differentiation separates commodity film converters from specialty adhesive compounders, with certification requirements and formulation complexity driving margin stratification.
- Films:Water-soluble PVA film for unit-dose detergents and agrochemical packaging commands premium positioning through biodegradability certifications and dissolution rate precision. German detergent brands and Chinese agrochemical distributors are consolidating direct procurement relationships with resin producers, bypassing traditional compounder intermediaries.
- Adhesives:Construction-grade dispersions and woodworking glues represent the largest volume pool, with European cementitious binder specifications rewarding copolymer grades with modified hydrolysis profiles for tile adhesive and mortar applications.
- Textiles:Warp sizing applications in Indian and Vietnamese spinning mills sustain steady demand for partially hydrolyzed grades where moderate water solubility optimizes desizing economics.
- Paper Coatings:Surface sizing and barrier coatings for food-contact paperboard require precise viscosity control and FDA or GB standard compliance.
Adhesive applications absorb the bulk of installed capacity across European and Asian manufacturing bases; water-soluble film is gaining share fastest in agrochemical unit-dose and precision agriculture systems.
End User:
Customer type segmentation exposes how regulatory stringency and performance validation requirements fragment procurement patterns across construction commodity buyers and healthcare specification-driven purchasers.
- Healthcare:Medical-grade hydrogels for ophthalmic lenses, wound dressings, and drug delivery matrices require PMDA pharmaceutical excipient monographs and JIS medical device standards. Sekisui Chemical and Kuraray maintain compliance moats through dedicated clean-room production assets in Osaka and Okayama prefectures.
- Packaging:Food-contact films and biodegradable consumer goods packaging face divergent certification schemes—China's GB standards, EU compostability frameworks, and EPA emerging chemical guidelines—creating fragmented reformulation timelines for multinational brand owners.
- Construction:Cementitious binders, tile adhesives, and exterior insulation finish systems represent high-volume, price-sensitive demand concentrated in European and Chinese infrastructure spending cycles.
- Agriculture:Seed-tape encapsulation and controlled-release fertilizer coatings are climbing the fastest as precision planting equipment adoption spreads across North American and European large-scale farming operations.
Construction absorbs the bulk of installed capacity in standard-grade dispersions; healthcare hydrogels are expanding most quickly through ophthalmic and advanced wound-care applications.
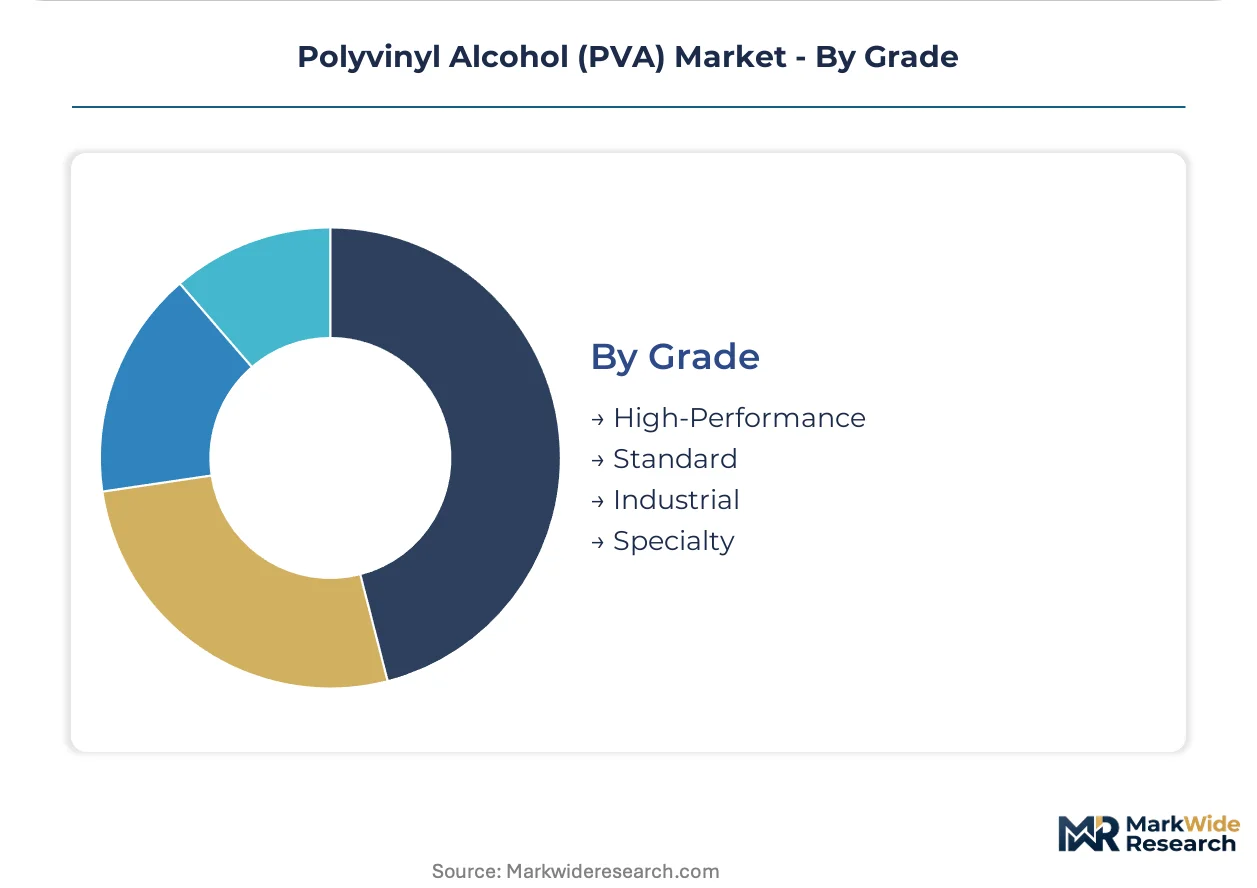
Grade:
Margin concentration tracks certification depth and batch documentation requirements, with specialty and high-performance grades capturing disproportionate value despite smaller production volumes.
- Specialty:Pharmaceutical excipients, optical film substrates, and medical-device-grade hydrogels demand sub-ppm impurity thresholds, chain-of-custody documentation, and regulator-audited manufacturing. Japanese producers leverage METI circular-economy guidelines and PMDA joint governance to defend positioning.
- High-Performance:Barrier films for oxygen-sensitive foods and industrial laminates require narrow molecular weight distribution and controlled crystallinity through advanced process control systems with inline viscometry.
- Standard:General-purpose adhesives, textile sizes, and paper coatings serve price-competitive segments where hydrolysis range flexibility and logistics efficiency outweigh specification intensity.
- Industrial:Bulk construction and woodworking applications prioritize viscosity stability and moisture resistance over certification documentation.
Standard grades absorb the bulk of installed capacity across Asian commodity manufacturing; specialty grades are expanding most quickly in pharmaceutical and optical film segments where regulatory compliance creates defendable margin structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian vinyl acetate corridors dominate PVA production capacity, while European and North American markets absorb specialty grades for regulated applications. This geographic split shapes trade flows and certification requirements across hydrolysis grades.
China
Unit-dose detergent packaging and agrochemical film applications drive consumption growth along the Yangtze River Delta. GB standards for biodegradable food-contact materials tighten import eligibility for non-compliant producers. Shanghai corridor manufacturers are consolidating direct procurement relationships with resin suppliers, bypassing traditional compounder intermediaries.
Japan
Optical film substrates and medical-grade hydrogels sustain premium positioning for fully hydrolyzed grades. METI circular-economy guidelines and PMDA pharmaceutical excipient monographs jointly govern compliance pathways. Osaka and Okayama prefectures host clean-room production assets dedicated to ophthalmic and wound-care formulations.
Germany
Construction adhesive dispersions and cementitious binders absorb standard-grade volumes across cementitious binder and tile adhesive applications. REACH registration requirements extend reformulation timelines for imported grades seeking European market access. German chemical distributors are consolidating import documentation services to offset compliance friction.
United States
PFAS phase-out frameworks redirect coating manufacturers toward PVA-based barrier systems in consumer goods applications. EPA emerging chemical guidelines create reformulation windows for household goods brands. Midwest and Southeast manufacturing clusters are adapting packaging lines to accommodate water-soluble film specifications.
India
Textile warp sizing in Gujarat and Maharashtra spinning mills sustains demand for partially hydrolyzed grades where moderate water solubility optimizes desizing economics. BIS standards for industrial chemicals constrain specification flexibility for imported resin. Mumbai-Pune industrial corridor distributors are expanding technical service capabilities for sizing formulation support.
Polyvinyl Alcohol (PVA) Market Competitive Landscape
Capital-heavy producers compete with asset-light compounders across distinct margin tiers. Integrated vinyl acetate producers command cost advantages in standard-grade markets, while specialty manufacturers defend positioning through certification depth and reactor flexibility. Three archetypes dominate: captive monomer integrators, regional volume suppliers, and niche-grade specialists. Consolidation through strategic partnerships and capacity expansion in East Asian corridors represents the dominant competitive dynamic.
Among Japanese chemical conglomerates, Kuraray Co., Ltd. and Sekisui Chemical Co., Ltd. exemplify the specialty-grade archetype through dedicated production assets and regulator-audited manufacturing protocols. Wacker Chemie AG represents the European dispersion specialist model, serving construction adhesive markets with modified hydrolysis profiles. These three anchors demonstrate how geographic clustering around regulatory hubs creates defendable competitive positioning.
| Leading Market Players |
|---|
| Aicello Corporation |
| Wacker Chemie AG |
| Kuraray Co., Ltd. |
| Nippon Synthetic Chemical Industry Co. |
| Eastman Chemical Company |
| Sekisui Chemical Co., Ltd. |
| Chang Chun Group |
| Anhui Wanwei Group Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Others |
Value Network & Pricing Analysis
Direct procurement relationships between Shanghai-based detergent brands and resin producers are compressing compounder margins while forcing supply chains to absorb documentation costs for GB-compliant biodegradable certification. This buyer-driven consolidation reshapes pricing power toward integrated vinyl acetate producers with captive purity control.
Pricing Analysis
Margin tightening in standard-grade construction dispersions reflects vinyl acetate monomer volatility and Chinese oversupply. Three-tier pricing structure across pharmaceutical-grade, optical-film, and industrial-adhesive levels separates sub-ppm impurity thresholds from commodity viscosity grades. Pricing pressure stems from Yangtze River Delta textile mills demanding 80-87% hydrolysis flexibility without premium payment. Construction adhesive buyers exhibit highest price sensitivity; ophthalmic hydrogel purchasers accept substantial premiums for PMDA-audited documentation.
Supply Chain Analysis
Container freight from Osaka and Shanghai industrial corridors to European construction markets adds 8-12% landed cost premiums versus regional sourcing. Production gravity centers on China, Japan, and South Korea, with vinyl acetate supply drawing from ethylene-cracker corridors along the Yangtze and Osaka Bay. Single-source vulnerability concentrates in high-purity fully hydrolyzed grades where Kuraray and Sekisui operate dedicated continuous hydrolysis assets. Distribution runs through German chemical distributors consolidating REACH documentation services and direct mill relationships in Gujarat textile clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around captive vinyl acetate integration and certification depth, with vinyl acetate monomer volatility and REACH registration timelines forcing non-integrated compounders toward exit or acquisition.
For Market Incumbents: Hedge margin exposure through backward integration into vinyl acetate supply or long-term offtake contracts with ethylene-cracker operators. Defend positioning by expanding clean-room capacity in Osaka and Okayama prefectures for PMDA-audited medical-grade hydrogels before emerging Korean producers secure excipient monographs. Channel control through direct procurement portals for Shanghai detergent brands reduces compounder disintermediation risk. For New Entrants and Emerging Players: Begin with seed-tape encapsulation for North American precision agriculture equipment, where controlled-dissolution PVA copolymers face limited incumbent specialization. Target European construction adhesive dispersion markets through modified hydrolysis profiles for cementitious binders, leveraging German distributor consolidation for REACH documentation support. Go-to-market through technical service partnerships with Mumbai-Pune industrial corridor distributors for Indian textile warp sizing formulations. For Investors and Strategic Acquirers: The window for entry favors mid-cap compounders with flexible reactor configurations and existing GB or REACH registration portfolios. Long-term viability rests on specialty-grade migration toward pharmaceutical excipients and optical film substrates where regulatory compliance creates defendable moats. Watch EPA PFAS alternative framework implementation velocity as inflection indicator for PVA barrier film demand acceleration in US consumer goods packaging.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vinyl Acetate | Captive monomer supply anchors margin stability against ethylene feedstock volatility for non-integrated producers. |
| Clean-Room Capacity Expansion | PMDA-audited manufacturing assets in Osaka defend medical-grade hydrogel positioning against Korean entrants. |
| Direct Procurement Portal Development | Shanghai detergent brand relationships bypass compounder intermediaries facing REACH registration delays. |
| Modified Hydrolysis Profile R&D | Construction adhesive specialization for German cementitious binder specifications captures dispersion market share. |
| Seed-Tape Encapsulation Partnerships | North American precision agriculture equipment adoption creates controlled-dissolution copolymer demand. |
Research Methodology
Document review covered customs and trade flow databases, SEC and TSE filings from vinyl acetate producers, and GB standard certification registries, complemented by interviews with polymer plant managers, procurement leads at German construction adhesive compounders, distribution channel partners in Mumbai-Pune industrial corridors, and technical R&D directors at Japanese optical film manufacturers. Secondary validation drew from ECHA substance evaluation protocols, EPA emerging chemical framework disclosures, and METI circular-economy guideline documentation. Bottom-up demand modeling across hydrolysis grades and end-use applications was triangulated against top-down capacity assessments from East Asian vinyl acetate corridors.
Cross-referencing historical price and volume trajectories against panel input from procurement executives at Shanghai detergent brands and Osaka medical-device manufacturers shaped the analytical framework across the analysis window. Segmentation dimensions modeled included hydrolysis grade tier, end-use industry concentration, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and capacity utilization assumptions. Industry-specific forecast inputs incorporated vinyl acetate monomer price volatility indices and precision agriculture equipment adoption curves.
Underlying measurement precision varies by segment; pharmaceutical-grade and optical-film categories carry tighter precision than commodity construction adhesive volumes due to documented batch certification requirements. Forecasts reflect assumptions about REACH registration timeline resolution, GB standard enforcement consistency, and EPA PFAS alternative framework finalization. Stakeholders should weight assumptions against their own operating context and regional regulatory exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Polycyclohexylenedimethylene Terephthalate (PCT) Market
Polymers & Resins
PA66 Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Petroleum Resins Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
Thailand Plastics Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market