
 Middle East and Africa Poly Vinyl Chloride (PVC) Market | 2026-2036
Middle East and Africa Poly Vinyl Chloride (PVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Poly Vinyl Chloride (PVC) Market Insights
Regional petrochemical distribution is fragmenting as state-backed producers and Asian exporters compete for contractor loyalty in overlapping territories. SABIC leverages its integrated feedstock position across Saudi industrial cities to secure bulk supply contracts. Sasol anchors southern African demand through its Secunda-based chlor-alkali chain and downstream compounding capabilities. Egyptian Petrochemical Co. competes on proximity to Nile Delta construction clusters, reducing landed costs for domestic pipe extruders.
Poly Vinyl Chloride is a thermoplastic polymer synthesized from vinyl chloride monomer through suspension, emulsion, or bulk polymerization, typically containing 57% chlorine by mass and exhibiting flame resistance, chemical stability, and electrical insulation properties. The material serves primarily as a cost-effective substitute for metal, wood, and rubber in infrastructure, transportation, and consumer goods. Rigid PVC dominates construction pipe and profile applications where dimensional stability and pressure ratings command premium positioning, while flexible PVC compounds capture automotive wire sheathing and medical tubing segments requiring plasticizer compatibility. PVC resin as a commodity feedstock concentrates margin volatility with ethylene and chlorine price swings, compelling processors to maintain flexible sourcing arrangements.
Saudi Arabia's SFDA and building code authorities enforce material safety certifications for potable water contact applications, while Egypt's Ministry of Housing mandates BIS-equivalent testing for imported resin batches used in public infrastructure. The UAE's civil defense regulations specify smoke density limits for PVC electrical conduits in high-rise developments, creating compliance differentiation among suppliers. Stakeholders must monitor feedstock cost pass-through mechanisms and evolving Gulf standardization harmonization to align capacity investments with procurement cycle timing.
Market Dynamics
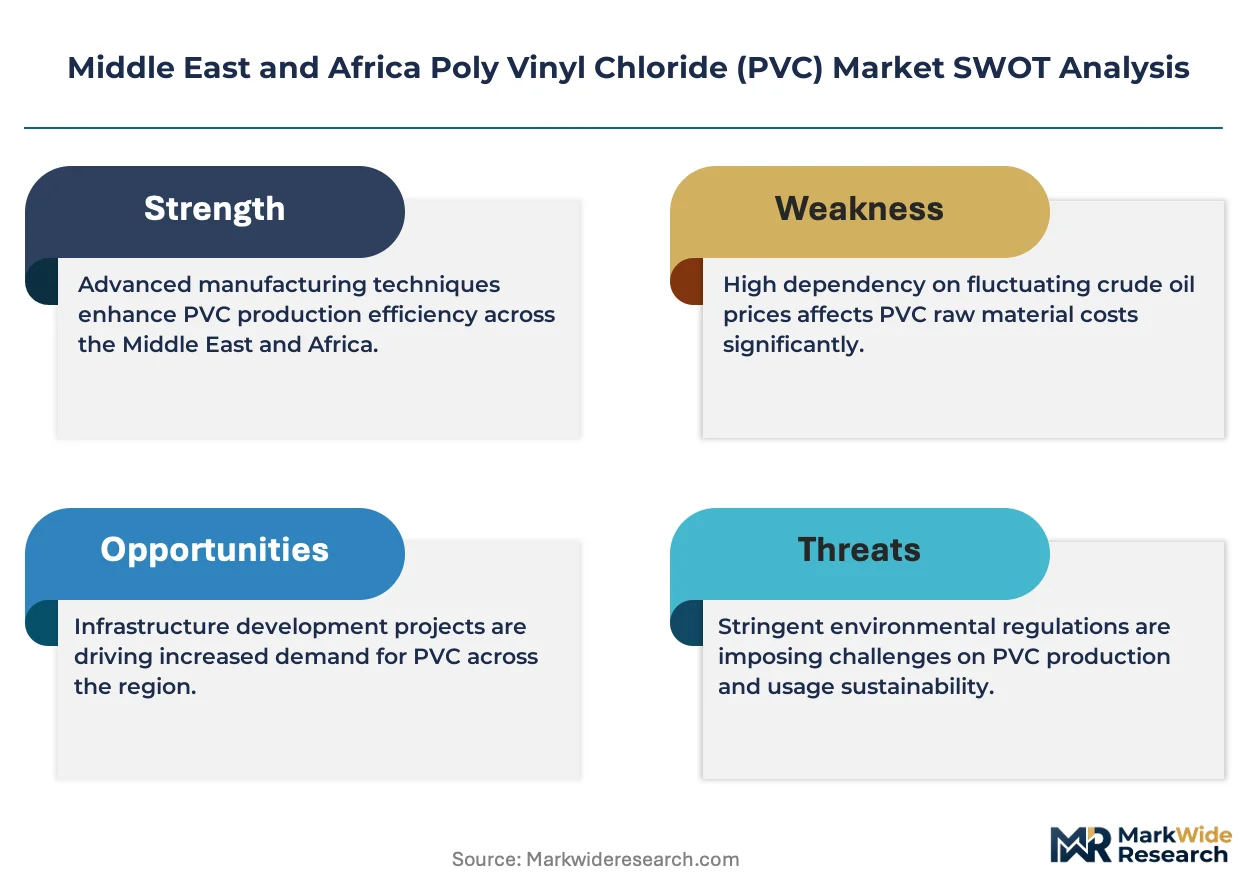
Feedstock cost pass-through mechanisms and Gulf standardization harmonization are compressing margin predictability for resin processors across Middle East and Africa construction procurement cycles.
Growth Catalysts
- Gulf Cooperation Council infrastructure pipelines:Rigid PVC pipe demand accelerates from water distribution and district cooling networks in Saudi Arabia, Qatar, and the UAE. State-backed contractors specify certified material grades for 50-year design-life installations.
- SFDA potable water certification mandates:Saudi Arabia's tightening material safety requirements for drinking water contact applications force specification upgrades. Domestic extruders capture replacement demand from uncertified imports.
- Nigeria residential construction expansion:Urban housing stock growth drives plumbing and electrical conduit procurement. Local compounders scale batch production to serve contractor loyalty programs in Lagos and Abuja clusters.
Market Restraints
- Ethylene-chlorine margin volatility:PVC resin pricing tracks naphtha and caustic soda input swings. Egyptian and South African processors maintain minimal inventory cover to limit working capital exposure.
- Asian exporter price pressure:Chinese and Indian resin suppliers flood spot markets during domestic oversupply periods. Gulf producers defend contract volumes through integrated feedstock positions.
- Substitution by HDPE in pressure pipes:High-density polyethylene captures potable water segments requiring flexibility and impact resistance. PE100 material grades displace PVC in directional drilling applications.
Strategic Opportunities
- Ethiopia and Kenya infrastructure build-out:East African power transmission and irrigation projects create virgin demand for cable conduits and pressure piping. Regional traders establish stocking points in Mombasa and Djibouti.
- Medical-grade flexible PVC compounding:Blood bag and tubing manufacturers seek phthalate-free formulations. Egyptian and South African compounders invest in clean-room extrusion lines for hospital supply chains.
- UAE civil defense smoke density compliance:High-rise electrical conduit specifications now mandate low-smoke halogen-free grades. First-mover suppliers capture premium positioning in Dubai and Abu Dhabi developments.
Industry Challenges
- Certification timeline compression:SFDA and Egypt's Ministry of Housing testing protocols extend batch approval cycles. Importers face project delays when documentation gaps trigger re-testing requirements.
- Skilled compounding technician scarcity:Formulation expertise for impact-modified and UV-stabilized grades concentrates in Saudi and South African facilities. Nigerian and Egyptian processors struggle to retain trained staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Poly Vinyl Chloride (PVC) Market |
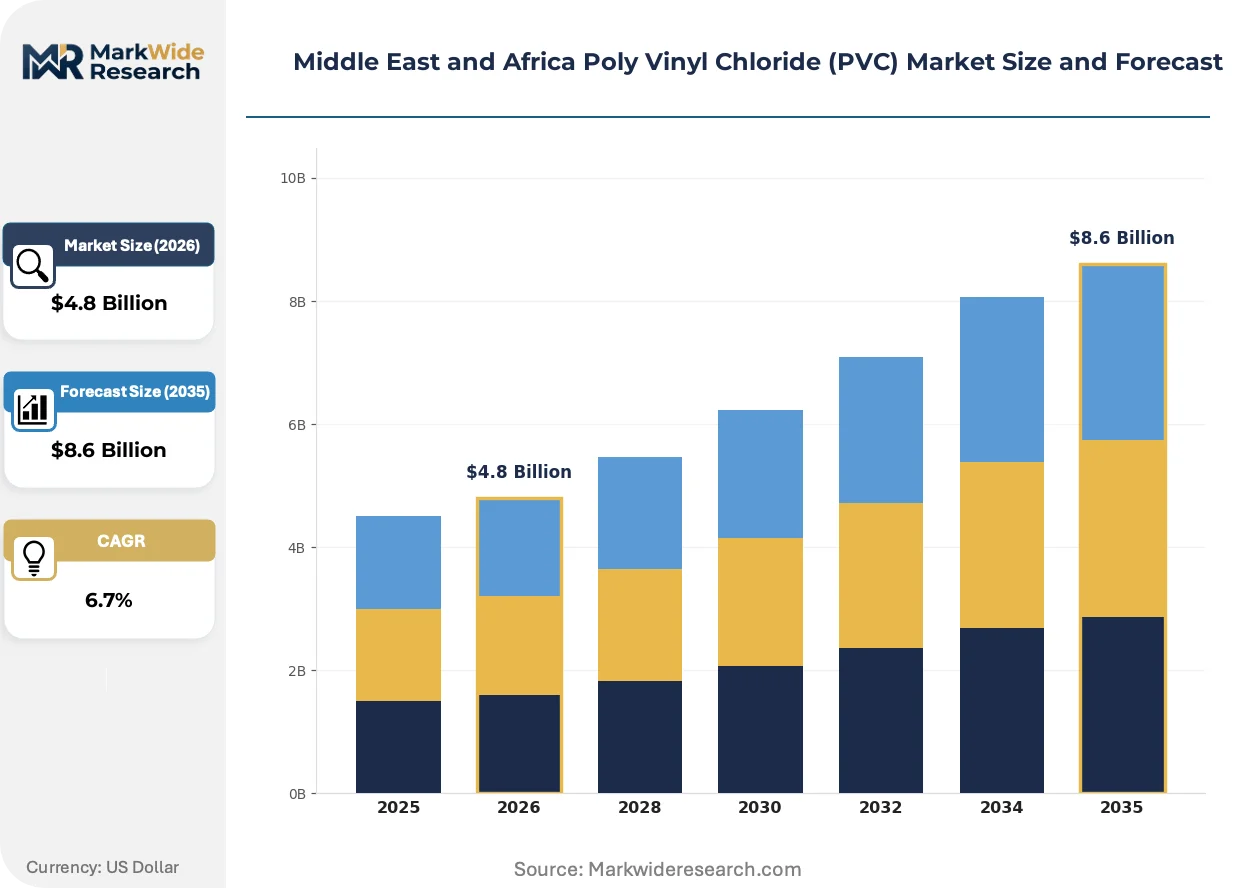
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid PVC, Flexible PVC, PVC Cops, PVC Resin Application: Construction, Automotive, Packaging, Electrical End User: Manufacturers, Contractors, Distributors, Retailers Form: Sheets, Films, Pipes, Profile |
| Companies Covered | SABIC, Egyptian Petrochemical Co., Sasol, Westlake Chemical Corporation, The Sanmar Group, Formosa Plastics Corporation, LG Chem, Shin-Etsu Chemical Co., Ltd., INEOS, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Poly Vinyl Chloride (PVC) Market Trends and Innovations
Material formulation, regulatory compliance architecture, and procurement digitization are converging to reshape competitive positioning across Middle East and Africa PVC value chains.
Calcium-zinc stabilizer systems are hybridizing with traditional lead-based formulations in rigid pipe extrusion. Saudi and UAE processors lead adoption as SFDA and MOHAP deadlines approach. The transition compresses formulation cost differentials between domestic and imported resin grades while accelerating equipment upgrade cycles.
REACH-equivalent substance restrictions are migrating into Gulf Cooperation Council technical regulations. ECHA candidate list substances face parallel scrutiny in Saudi and UAE building codes. Electrical conduit and profile extruders reformulate plasticizer packages to maintain export access to European project specifications.
Contractor-direct procurement platforms are consolidating material specification and logistics coordination. Large Saudi and UAE construction groups bypass traditional distributor networks for bulk resin and compound orders. Digital tendering visibility concentrates volume with integrated suppliers offering real-time certification documentation.
Middle East and Africa Poly Vinyl Chloride (PVC) Market Segmentation
Segmentation reveals how PVC procurement patterns diverge across construction, automotive, and electrical channels. Technical specifications, certification requirements, and supply chain proximity determine winner-take-most dynamics in each slice.
Product Type:
After-sales service intensity varies sharply across product types, with rigid PVC pipe installations demanding decades-long technical support versus commodity resin transactions.
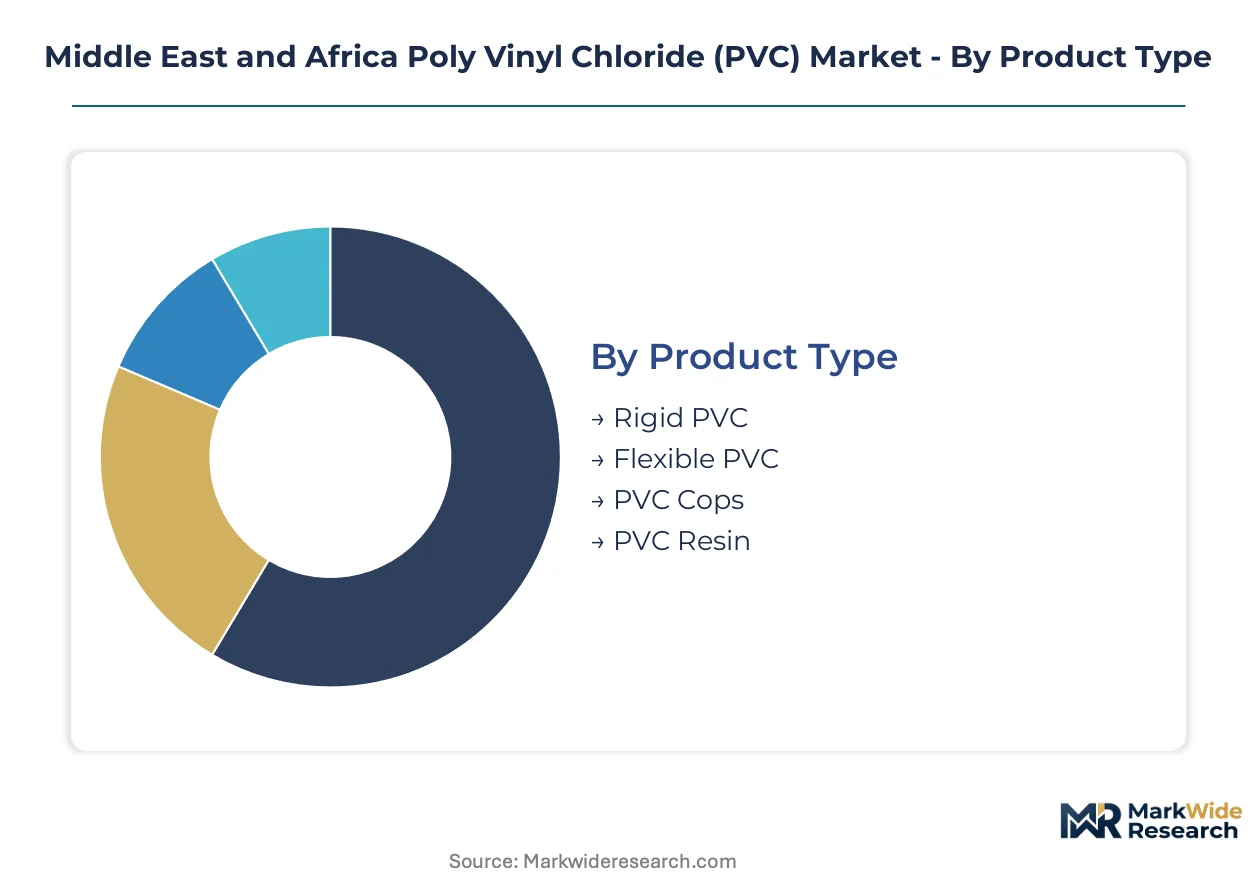
- Rigid PVC:Unplasticized formulations containing zero phthalate additives deliver dimensional stability for pressure-rated pipe and window profiles. Saudi Aramco-backed contractors specify certified grades for 50-year infrastructure lifecycles in Jubail and Yanbu industrial corridors.
- Flexible PVC:Plasticizer-loaded compounds achieve Shore A hardness ratings from 60-90 for wire insulation and medical tubing. South African automotive harness manufacturers in Eastern Cape prefer locally compounded grades to minimize import lead times.
- PVC Cops:Suspension-grade particles serve as intermediate feedstock for specialty compounders. Egyptian processors blend imported cops with calcium-zinc stabilizers for Nile Delta extrusion houses.
- PVC Resin:Base polymer powder concentrates margin exposure to ethylene and chlorine input costs. Nigerian distributors stock K67 and K57 viscosity grades to serve Lagos construction clusters.
Rigid PVC holds the largest share; momentum sits with flexible PVC as medical-grade formulations climb the fastest.
Application:
Application segmentation tracks capital deployment cycles, with construction commanding multi-year project horizons versus automotive's model-year refresh cadence.
- Construction:Pipe, profile, and sheet applications absorb bulk regional resin volumes. UAE district cooling networks specify low-smoke halogen-free conduit for Dubai high-rise compliance.
- Automotive:Underbody coatings and interior trim require UV-stabilized formulations. Moroccan wiring harness exporters to European OEMs demand REACH-equivalent substance documentation.
- Packaging:Blister packs and shrink films compete with PET and PP alternatives. South African pharmaceutical converters favor PVC for moisture barrier properties.
- Electrical:Cable insulation and conduit face HDPE substitution in directional drilling. Saudi SFDA mandates material safety certifications for potable water contact applications.
Construction dominates volume; electrical applications are expanding most quickly on infrastructure electrification programs.
End User:
End-user structure reflects procurement sophistication gradients, from manufacturer technical specifications to retailer shelf-stock decisions.
- Manufacturers:Pipe extruders and profile mills negotiate annual resin contracts with SABIC and Sasol. Integrated compounders maintain captive chlor-alkali capacity to buffer feedstock volatility.
- Contractors:Saudi Binladin Group and UAE-based Arabtec specify certified material grades with full traceability documentation. Direct procurement platforms bypass traditional distributor markups.
- Distributors:Regional traders maintain Mombasa and Djibouti stocking points for East African project supply. Inventory cover averages 3-4 weeks given working capital constraints.
- Retailers:Hardware chains in Lagos and Cairo stock plumbing fittings and electrical conduit for residential repair markets. SKU breadth concentrates on Kitemark-equivalent certified grades.
Manufacturers command the largest procurement volumes; contractors are gaining share fastest on digital tendering consolidation.
Form:
Form factor segmentation aligns with downstream processing equipment and logistics cost structures across the value chain.
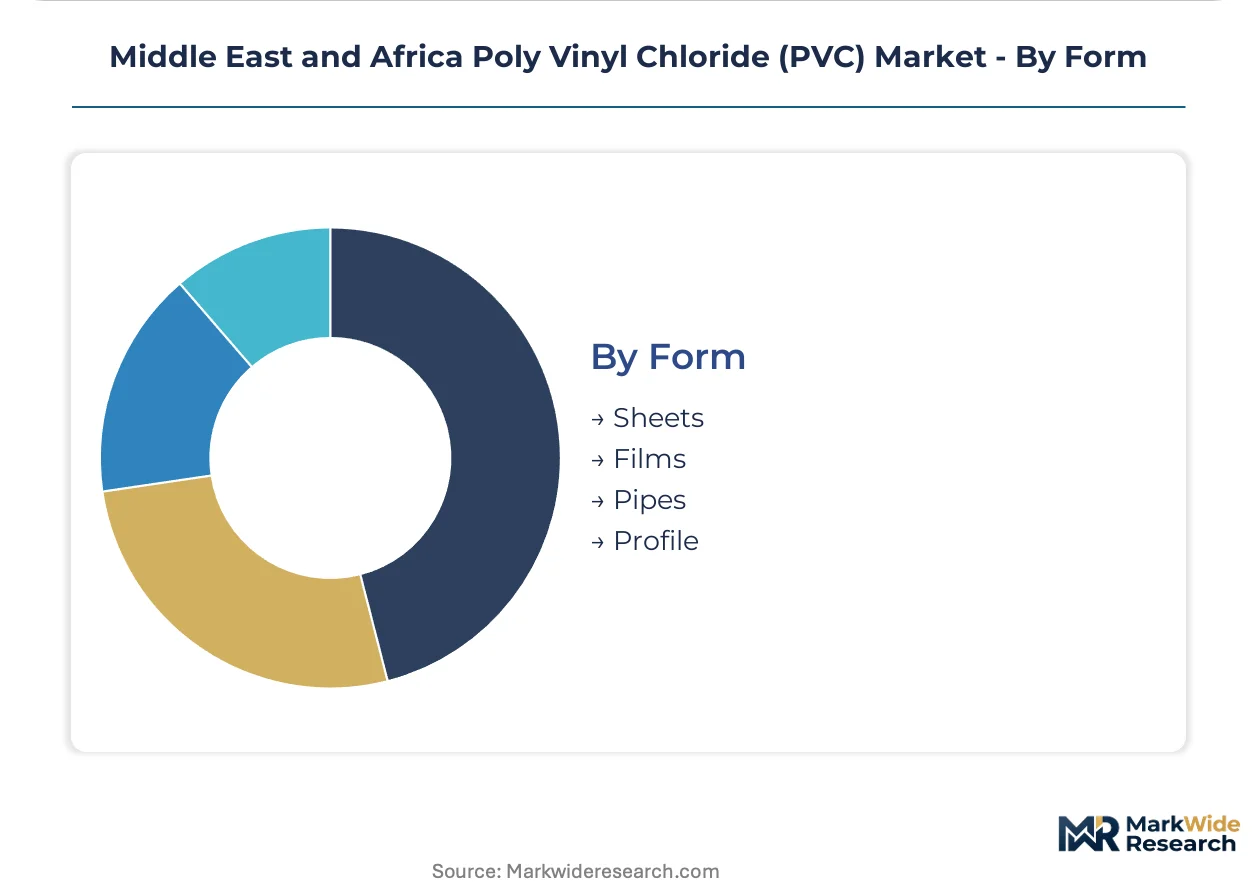
- Sheets:Calendered products serve advertising signage and thermoformed packaging. Egyptian converters supply European point-of-purchase display markets.
- Films:Blown and cast variants target agricultural greenhouse and food wrap segments. Kenyan horticulture exporters drive multilayer film specifications.
- Pipes:Extruded pressure and drainage products anchor construction procurement. Nigerian residential plumbing codes mandate specific wall thickness schedules for Lagos high-rises.
- Profile:Window frames and door systems compete with aluminum in Gulf climate zones. Saudi processors lead regional capacity for co-extruded multi-chamber designs.
Pipes represent the dominant form; profile applications show steepest expansion trajectory on energy-efficiency building codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia commands pricing leverage through captive ethylene supply, while Nigerian processors absorb volatile import premiums. This asymmetry shapes procurement patterns across construction corridors.
Saudi Arabia
Jubail and Yanbu industrial cities anchor rigid PVC pipe production for GCC water infrastructure. SFDA mandates material safety certifications for potable water contact applications. Domestic extruders capture replacement demand from uncertified Asian imports.
United Arab Emirates
Dubai high-rise developments drive low-smoke halogen-free electrical conduit specifications. MOHAP and civil defense regulations enforce smoke density limits for vertical installations. Abu Dhabi-based contractors consolidate procurement through direct digital tendering platforms.
Egypt
Nile Delta construction clusters consume suspension-grade PVC cops blended with calcium-zinc stabilizers. The Ministry of Housing mandates BIS-equivalent testing for imported resin batches used in public infrastructure. Alexandria and Cairo extruders compete on landed cost proximity to domestic pipe mills.
South Africa
Secunda-based chlor-alkali integration buffers Sasol's downstream compounding operations. Automotive wire harness manufacturers in Eastern Cape prefer locally compounded flexible PVC grades. REACH-equivalent substance documentation pressures reformulation for European export markets.
Nigeria
Lagos and Abuja residential construction clusters scale plumbing and electrical conduit procurement. Local compounders expand batch production to serve contractor loyalty programs. Working capital constraints limit inventory cover to 3-4 weeks for Mombasa-traded resin.
Middle East and Africa Poly Vinyl Chloride (PVC) Market Competitive Landscape
Integrated petrochemical majors and regional compounders split the market along feedstock access lines. State-backed producers leverage captive ethylene-chlorine chains to defend contract volumes against Asian spot exporters. Three archetypes dominate: Gulf-based integrated resin producers with industrial city infrastructure, African regional compounders with downstream formulation expertise, and Asian exporters competing on price during domestic oversupply periods. Competitive moves concentrate on certification documentation automation and direct procurement platform integration.
Within the integrated-resin tier, SABIC and Sasol exemplify feedstock-backward positioning. SABIC leverages Saudi industrial city infrastructure across Jubail and Yanbu to secure bulk supply contracts. Sasol anchors southern African demand through Secunda-based chlor-alkali integration. Egyptian Petrochemical Co. occupies a proximity-driven position serving Nile Delta construction clusters.
| Leading Market Players |
|---|
| SABIC |
| Egyptian Petrochemical Co. |
| Sasol |
| Westlake Chemical Corporation |
| The Sanmar Group |
| Formosa Plastics Corporation |
| LG Chem |
| Shin-Etsu Chemical Co., Ltd. |
| INEOS |
| Others |
Pricing and Supply Chain Analysis
Ethylene-chlorine margin volatility compresses pricing tier spreads while forcing supply chain reconfiguration toward integrated feedstock sources. Gulf producers with captive chlor-alkali capacity capture premium positioning for certified grades, while import-dependent processors absorb spot market swings that widen standard-economy spreads.
Pricing Analysis
Configured-to-order pricing for SFDA-certified potable water grades commands substantial premiums over standard K67 resin transactions. Three-tier pricing structure across premium certified, standard industrial, and economy spot grades differentiates on compliance documentation and batch traceability. Pricing pressure stems from Asian exporter spot flooding during domestic oversupply periods. Contractor-direct procurement platforms concentrate volume with integrated suppliers, squeezing distributor margins most severely.
Supply Chain Analysis
Export-control regime friction on chlor-alkali technology transfers limits African capacity expansion outside South African and Egyptian corridors. Supply concentrates in Saudi Arabia, South Africa, and Egypt, with raw material dependencies on naphtha-derived ethylene and salt-sourced chlorine. Single-source vulnerability concentrates around Gulf ethylene pipeline access for regional extruders. Distribution runs through contractor-direct platforms in Saudi Arabia and UAE, bypassing traditional trader networks for bulk resin procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HDPE substitution in pressure pipe applications threatens PVC volume retention, compelling incumbents to defend specification positions through certification differentiation and lifecycle cost positioning.
For Market Incumbents: Harden specification defenses by accelerating calcium-zinc stabilizer transitions ahead of SFDA enforcement deadlines. Deepen backward integration into captive ethylene supply where industrial city infrastructure permits, reducing exposure to naphtha price swings. Secure long-term offtake agreements with Saudi Aramco-backed contractors to lock in 50-year infrastructure project volumes. For New Entrants and Emerging Players: Establish a beachhead in East African cable conduit supply through Mombasa and Djibouti stocking points serving Ethiopian and Kenyan power transmission projects. Target medical-grade flexible PVC compounding for blood bag manufacturers seeking phthalate-free formulations. Lead with clean-room extrusion capabilities and REACH-equivalent substance documentation to differentiate from commodity resin traders. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated producers with feedstock backwardness and certification automation capabilities. Long-term viability hinges on Gulf standardization harmonization and substitution defense execution. Watch for HDPE displacement rates in directional drilling applications as the critical inflection signal for PVC demand elasticity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | SABIC and Sasol leverage captive ethylene-chlorine chains to defend contract volumes against Asian spot exporters. |
| SFDA Certification Automation | Domestic extruders capture replacement demand from uncertified imports through real-time batch documentation platforms. |
| East African Distribution Buildout | Regional traders establish Mombasa and Djibouti stocking points to serve Ethiopian and Kenyan infrastructure electrification. |
| Medical-Grade Compounding Investment | Egyptian and South African compounders deploy clean-room extrusion lines for phthalate-free blood bag formulations. |
| Low-Smoke Halogen-Free Formulation | First-mover suppliers capture premium positioning in Dubai and Abu Dhabi high-rise electrical conduit specifications. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC filings from petrochemical majors, and Gulf building code authority documentation. Plant managers at Saudi and South African resin facilities, procurement leads at Nigerian pipe extruders, and distribution channel partners in Mombasa and Cairo provided operational validation. Bottom-up volume triangulation against top-down ethylene consumption models ensures cross-verification of regional demand estimates.
Forecast inputs include grade tier segmentation across rigid, flexible, and copolymer formulations; end-use industry splits between construction, automotive, and electrical channels; and regional production hub capacity utilization rates. CAGRs derive from ethylene price elasticity modeling and infrastructure procurement cycle timing across the projection horizon. Chlor-alkali margin forecasts and SFDA certification timeline assumptions shape trajectory confidence intervals.
Sensitivities concentrate around ethylene price volatility, Asian exporter spot pricing discipline, and HDPE substitution acceleration in pressure pipe segments. Forecasts reflect documented assumptions on Gulf Cooperation Council infrastructure commitment durability and Nigerian residential construction credit availability. Material shifts in REACH-equivalent substance restriction timelines or Saudi feedstock subsidy policies would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
PVDF Resin Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Linear Low Density Polyethylene Lldpe Market
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Global Resin Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market