
 Polypropylene Copolymer Market | 2026-2036
Polypropylene Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Copolymer Market Intelligence
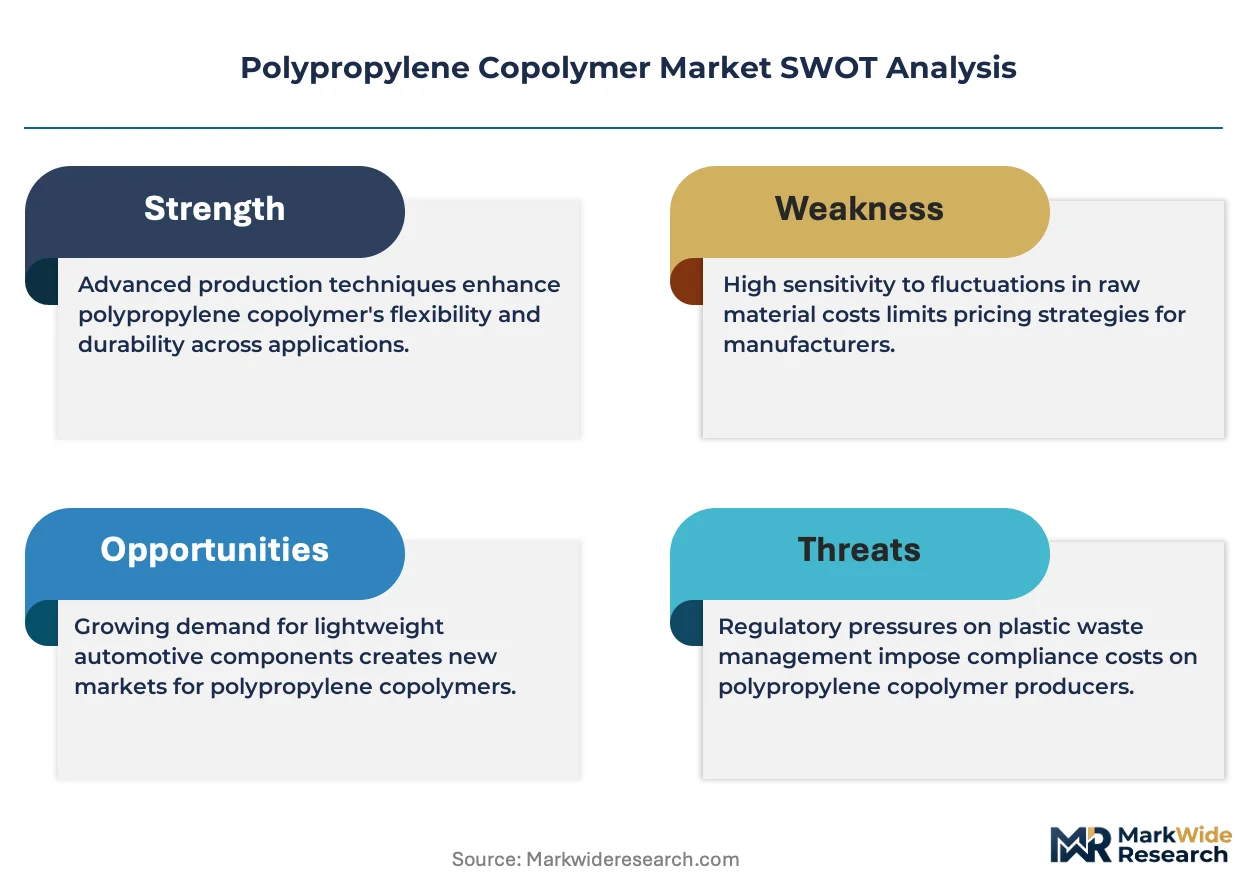
High-density polyethylene is expanding its displacement of conventional homopolymer polypropylene in thin-wall injection molding, forcing copolymer producers to emphasize toughness and clarity premiums. LyondellBasell Industries leverages its Spheripol technology platform to sustain margin capture in differentiated random copolymer grades. Sinopec anchors domestic supply security across China's coastal petrochemical belt through integrated refinery-polypropylene complexes. Braskem differentiates via bio-based propylene feedstock integration, occupying a niche position among sustainability-scrutinized European automotive OEMs.
Polypropylene copolymer denotes a thermoplastic polymer family incorporating ethylene comonomer units into a polypropylene backbone, typically achieving melt flow indices between 1 and 50 g/10 min and notched Izod impact strengths exceeding 50 J/m. These materials deliver balanced stiffness, thermal resistance, and processability for demanding molded and extruded applications across packaging, automotive, and durable goods sectors. Random copolymer grades command premium positioning in transparent rigid packaging where optical clarity requirements exclude homopolymer alternatives. Block copolymer formulations lead automotive bumper and interior panel applications due to superior low-temperature ductility. Injection molding technology dominates conversion economics, though blow molding is gaining share in large-format container production.
REACH registration obligations and EU F-Gas Regulation compliance costs are redirecting European compounders toward lower-emission production architectures. China's GB standards for automotive interior emissions and SAMR food-contact material certifications shape import-access requirements for multinational resin suppliers. The US EPA and FDA maintain parallel jurisdiction over packaging migration limits and industrial air emissions, creating dual compliance burdens for North American producers. Stakeholders must monitor propylene feedstock cost volatility and regional carbon-border adjustment mechanisms to calibrate capacity investment timing and geographic sourcing strategies.
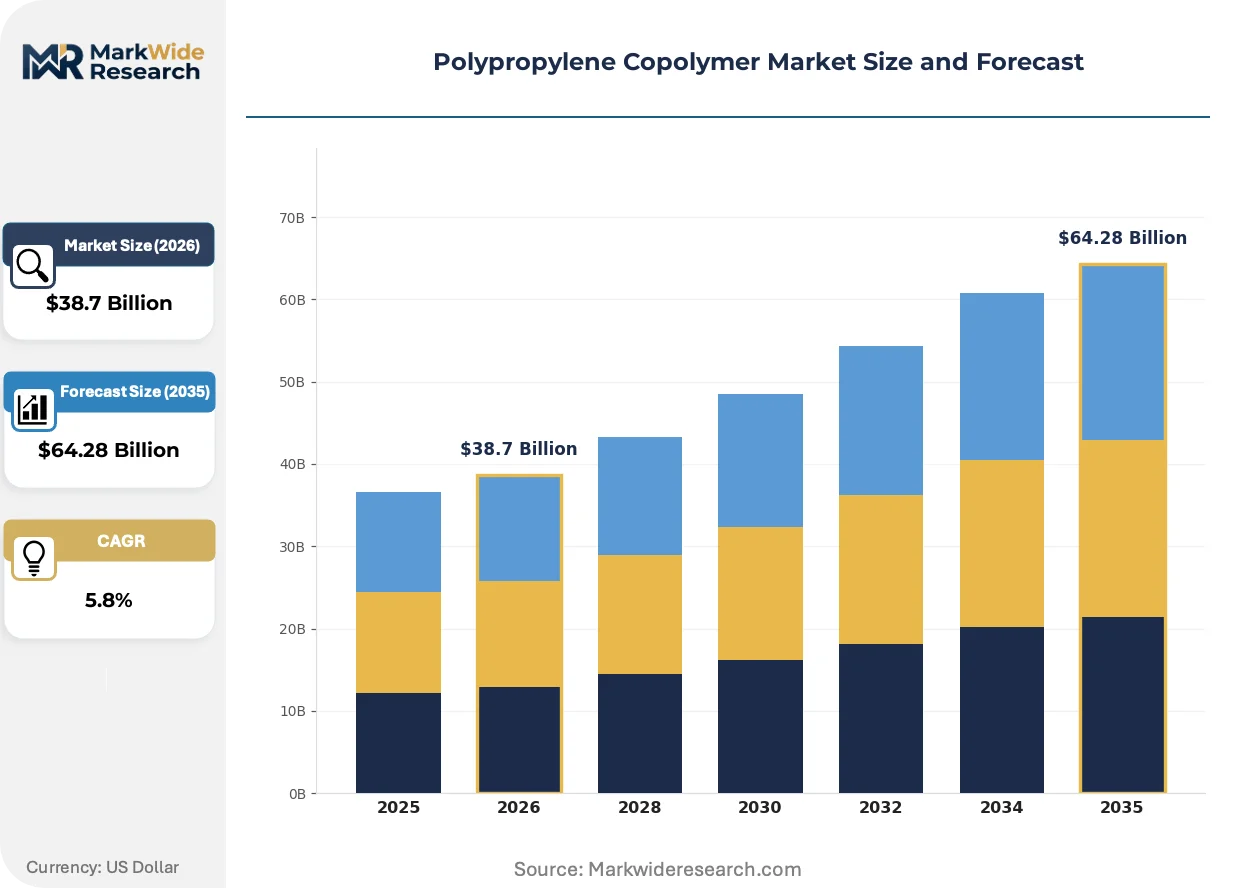
Market Dynamics
Automotive lightweighting mandates are compressing substitution timelines for metal components, forcing copolymer producers to accelerate impact-modified grade development cycles and secure long-term propylene supply contracts ahead of capacity expansions.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon blowing agents in automotive insulation redirects demand toward polypropylene copolymer foam cores with lower global warming potential.
- Thin-wall packaging converters:Food service brands in East China are adopting clarified random copolymer grades to replace polystyrene in refrigerated display applications.
- Spheripol process advances:Next-generation Ziegler-Natta catalyst systems enable broader ethylene incorporation ranges, expanding the property window for single-reactor block copolymer production.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and PDH unit operating rates in the Middle East create margin squeeze for non-integrated compounders.
- High-density polyethylene substitution:HDPE's improved flow characteristics in thin-wall injection molding threaten copolymer volume in food container segments.
- REACH registration costs:ECHA substance evaluation obligations for novel nucleating agents add compliance overhead for European compounders developing next-generation grades.
Strategic Opportunities
- India automotive interior standards:BIS adoption of stricter VOC emission limits for passenger vehicles creates specification upgrade demand currently served by imports.
- Mechanical recycling integration:Advanced decontamination and odor-removal technologies enable post-consumer copolymer streams to re-enter automotive specification chains.
- LyondellBasell's CirculenRenew:Mass-balance certified bio-based propylene pathways allow premium positioning among sustainability-scrutinized European OEM procurement panels.
Industry Challenges
- Color-matching certification timelines:Automotive interior suppliers face extended approval cycles for new pigment packages meeting OEM weathering and fogging standards.
- Legacy extrusion asset retrofit:Converters with dated single-screw lines struggle to process high-melt-strength copolymer grades for thermoforming applications without capital-intensive screw and die redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Copolymer Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Copolymer, Random Copolymer, Impact Copolymer, Other End User: Packaging, Automotive, Consumer Goods, Industrial Application: Films, Fibers, Containers, Tapes Technology: Catalytic, Extrusion, Injection Molding, Blow Molding |
| Companies Covered | Borealis AG, Sinopec, LyondellBasell Industries, Formosa Plastics, INEOS, ExxonMobil Chemical, Braskem, Repsol, SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Copolymer Market Strategic Shifts & Innovations
Digital twin modeling of reactor kinetics is compressing new grade development cycles, while regulatory pressure on embodied carbon intensifies scrutiny of both fossil and bio-based feedstock pathways across specification-driven end uses.
Reactor-grade thermoplastic polyolefin (TPO) technology is converging with in-reactor rubber incorporation techniques, eliminating the compounding step traditionally required for automotive bumper fascia production. Tier-one suppliers in Germany and Japan are qualifying these materials for Class A surface applications previously reserved for painted acrylonitrile-butadiene-styrene. This convergence is collapsing the historical cost gap between injection-molded copolymer systems and higher-performance engineered thermoplastics in exterior automotive panels.
China's GB standards for automotive interior emissions are tightening volatile organic compound limits for dashboard and door panel substrates, forcing compounders to reformulate nucleating and antioxidant packages. The MIIT implementation timeline accelerates testing and certification burdens for both domestic producers and import brands. European resin suppliers are responding by pre-certifying modified grades through SAMR-recognized laboratories to maintain access to Yangtze River Delta automotive clusters.
Automotive OEMs are consolidating resin supplier panels from six-plus qualified sources to three preferred partners per geographic region, compressing switching flexibility and lengthening contract durations. This concentration shifts negotiation leverage toward compounders with integrated propylene supply and in-house compounding capabilities. The pattern is most pronounced in North American light truck programs, where single-source qualification for bumper beam substrates now spans five-year model cycles.
Polypropylene Copolymer Market Segmentation
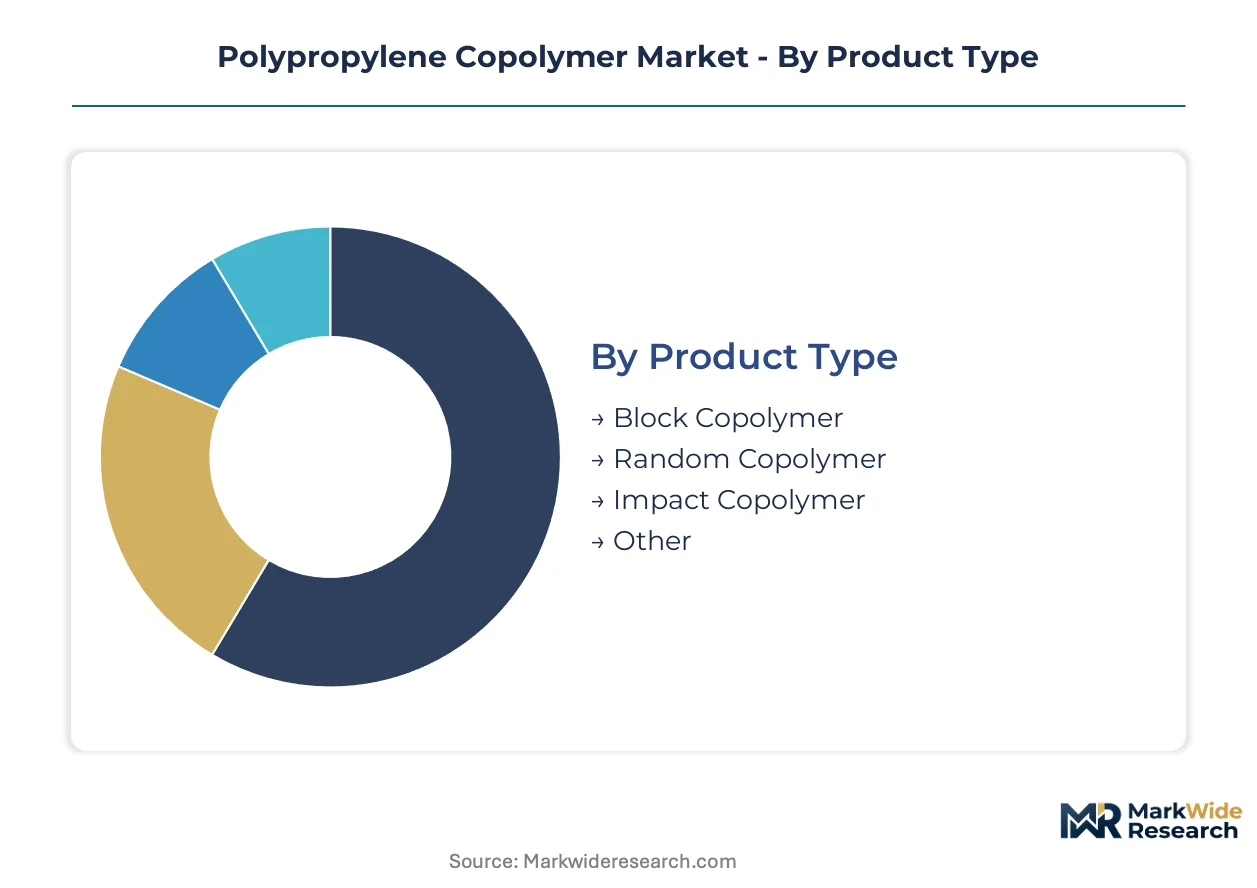
Polypropylene copolymer producers differentiate formulations by comonomer architecture, conversion technology, and end-use performance requirements. Each segmentation dimension carries distinct margin profiles and technical barriers that shape competitive positioning across automotive, packaging, and industrial supply chains.
Product Type:
Buyers in this category prioritize impact resistance, optical clarity, or processability depending on whether components face structural loads, aesthetic scrutiny, or high-speed conversion.
- Block Copolymer:Ethylene-rich rubber domains distributed in discrete phases deliver superior low-temperature ductility for automotive bumper beams and interior panels. German Tier-one suppliers specify these grades for Class A surface applications requiring paint adhesion and dimensional stability across temperature cycling.
- Random Copolymer:Ethylene units insert randomly along the polypropylene chain, reducing crystallinity and enabling optical clarity above homopolymer alternatives. East Chinese food service brands specify clarified random grades for refrigerated display containers replacing polystyrene.
- Impact Copolymer:Reactor-blended rubber content balances stiffness and toughness for durable goods housings and appliance components.
- Other:Specialty grades include high-melt-strength variants for thermoforming and nucleated formulations for thin-wall injection molding.
Block copolymer leads volumes today; random copolymer is gaining share fastest.
End User:
Volume concentration and specification intensity diverge sharply between cyclical automotive programs and steady-state packaging consumption.
- Automotive:Lightweighting mandates from China's MIIT and Europe's CO2 fleet standards accelerate metal-to-plastic substitution in bumper systems, dashboard carriers, and door panels. Impact-modified grades command premium pricing for crash-performance certification.
- Packaging:Thin-wall food containers and rigid display packaging drive clarified random copolymer consumption. East China's Yangtze River Delta converters source reactor-grade material from integrated refinery complexes.
- Consumer Goods:Appliance housings and furniture components utilize standard impact grades with moderate flow characteristics.
- Industrial:Pallet bins, bulk containers, and construction membranes specify UV-stabilized block copolymer for outdoor durability.
Automotive generates the highest per-kilogram margins; packaging provides volume foundation.
Application:
Conversion physics—stretch ratios, orientation, and wall thickness—determine which copolymer architecture delivers process efficiency and finished properties.
- Films:Biaxially oriented polypropylene films for snack packaging and label stock require random copolymer for heat-seal initiation temperatures and clarity. Cast film lines in Japan and South Korea run high-output grades with narrow molecular weight distribution.
- Fibers:Spunbond and meltblown nonwovens for hygiene applications utilize high-flow homopolymer-copolymer blends, though pure copolymer grades penetrate carpet backing and geotextiles.
- Containers:Injection-molded thin-wall cups and tubs represent the most contested application, with HDPE displacing copolymer in cost-sensitive segments.
- Tapes:Strapping and filament yarns exploit the stiffness-toughness balance of block copolymer for load-bearing performance.
Containers dominate current offtake; films show steepest expansion trajectory.
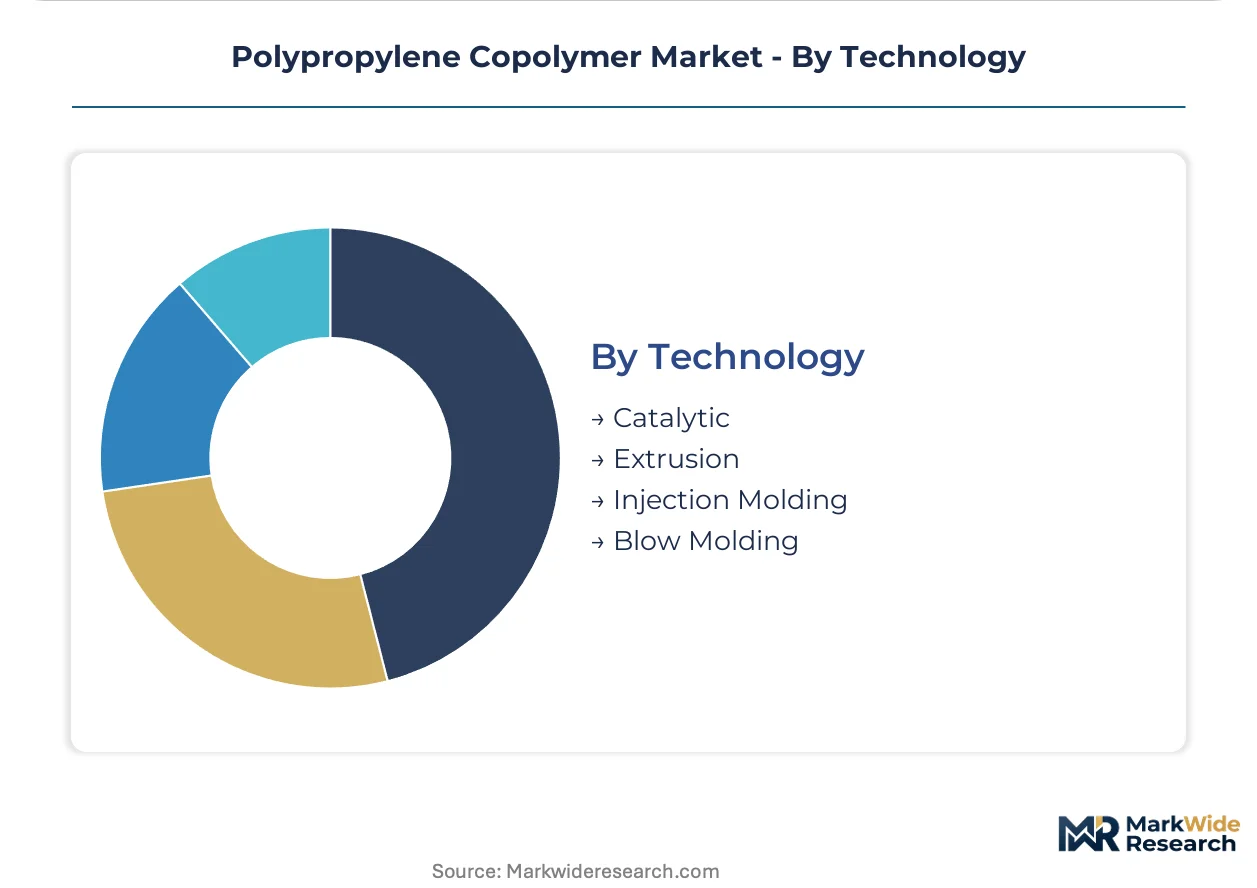
Technology:
Capital intensity and scale economies separate integrated producers with proprietary catalyst systems from toll compounders serving niche specifications.
- Catalytic:Ziegler-Natta and metallocene systems govern ethylene incorporation efficiency, molecular weight distribution, and isotacticity. LyondellBasell's Spheripol platform enables single-reactor block copolymer production, collapsing compounding costs.
- Extrusion:Sheet and profile lines process copolymer into thermoforming feedstock and construction membranes. Twin-screw extruders with venting sections handle high-melt-strength grades.
- Injection Molding:Thin-wall packaging and automotive components run on electric presses with sequential valve gating. High-flow grades reduce cycle times.
- Blow Molding:Large-format industrial containers and automotive ducts exploit copolymer melt strength for parison stability.
Injection molding anchors installed capacity; blow molding is climbing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta petrochemical corridors anchor polypropylene copolymer demand concentration. Automotive lightweighting mandates and packaging converter clusters drive regional differentiation. Regulatory tightening on vehicle emissions and food-contact materials shapes market access requirements.
China
MIIT fuel-efficiency standards accelerate metal-to-plastic substitution in bumper systems and interior panels. SAMR food-contact certifications constrain import access for non-compliant resin streams. Ningbo-Zhoushan petrochemical complexes supply clarified random copolymer grades to East Chinese thin-wall packaging converters.
Germany
REACH registration obligations redirect compounders toward lower-emission production architectures. EU F-Gas Regulation phase-down redirects automotive insulation demand toward polypropylene copolymer foam cores. Ruhr Valley chemical clusters integrate Spheripol-derived block copolymer production for Tier-one automotive suppliers.
United States
EPA industrial air emissions standards and FDA packaging migration limits create dual compliance burdens for domestic producers. NHTSA corporate average fuel economy standards sustain lightweighting program momentum. Gulf Coast propylene-to-polymer complexes serve injection molders across the Midwest automotive belt.
Japan
METI carbon-neutrality roadmaps pressure resin suppliers to certify bio-based feedstock pathways. JIS standards for automotive interior emissions align with tightening VOC limits in export markets. Chubu region petrochemical complexes supply high-flow grades to precision packaging converters in Aichi and Shizuoka prefectures.
India
BIS adoption of stricter VOC emission limits for passenger vehicles creates specification upgrade demand currently served by imports. Automotive OEM localization programs concentrate procurement around Delhi-NCR and Chennai manufacturing clusters. Gujarat petrochemical corridors expand propylene derivative capacity to reduce import dependence.
Polypropylene Copolymer Market Key Industry Players
Global majors compete with regional champions across integrated supply security and specialty grade development. The market structure tiers between scale-driven petrochemical conglomerates with captive propylene supply and technology-differentiated compounders serving specification-intensive automotive programs. Three archetypes dominate: integrated refinery-polymer complexes, catalyst technology licensors, and bio-based feedstock specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure long-term raw material positions.
Within the integrated supply tier, Sinopec anchors domestic supply security across China's coastal petrochemical belt through refinery-polypropylene complexes. LyondellBasell Industries occupies a technology-differentiated position through its Spheripol platform for random and block copolymer production. Braskem represents the bio-based feedstock archetype among sustainability-scrutinized European automotive OEM procurement panels.
| Leading Market Players |
|---|
| Borealis AG |
| Sinopec |
| LyondellBasell Industries |
| Formosa Plastics |
| INEOS |
| ExxonMobil Chemical |
| Braskem |
| Repsol |
| SABIC |
| Others |
Cost & Logistics Intelligence
Sovereign-backed producers across China's coastal petrochemical belt anchor supply security and pricing discipline through integrated refinery-polypropylene complexes. This ownership pattern compresses margin capture for non-integrated compounders while concentrating negotiation leverage among state-controlled entities with captive propylene positions.
Pricing Analysis
Propylene feedstock pass-through from naphtha-cracking economics and PDH unit operating rates in the Middle East governs contract negotiations. Three-tier pricing structure across premium, standard, and economy levels separates reactor-grade block copolymers from clarified random grades and commodity impact formulations. Cost compression in standard grades is intensifying because high-density polyethylene displacement in thin-wall injection molding erodes volume. Packaging converters in East China exhibit highest price sensitivity; German Tier-one automotive suppliers accept premiums for crash-performance certification.
Supply Chain Analysis
Propylene supply rests on integrated refinery complexes in China, Saudi Arabia, and the United States. Key inputs include ethylene comonomer, Ziegler-Natta catalyst systems, and nucleating agent packages. Single-source vulnerability concentrates in LyondellBasell's Spheripol technology licensing for differentiated grade production. Distribution runs through Yangtze River Delta petrochemical corridors to domestic automotive clusters and packaging converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polypropylene copolymer market reads as a late-cycle quality story. Automotive OEM consolidation toward three preferred suppliers per region shifts procurement toward specification-certified grades with embedded technical service.
For Market Incumbents: Deploy catalyst technology licensing as the primary lever. Deepen Spheripol platform utilization to collapse compounding costs for block copolymer grades. Secure long-term propylene supply contracts ahead of capacity expansions to defend against Middle Eastern PDH unit margin pressure. For New Entrants and Emerging Players: Direct-to-automotive-Tier-one digital qualification platforms offer the lowest-friction entry path. Target India's BIS-mandated VOC emission upgrade demand currently served by imports. Develop SAMR-recognized laboratory partnerships to bypass certification bottlenecks for Yangtze River Delta access. For Investors and Strategic Acquirers: Integrated petrochemical conglomerates with captive propylene supply are the most active acquirers in this space. Five-to-ten year viability hinges on mechanical recycling integration for post-consumer copolymer stream re-entry. Watch for carbon-border adjustment mechanism implementation as the inflection signal for bio-based feedstock pathway valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Supply | Sinopec's refinery-polypropylene complexes eliminate feedstock volatility exposure for downstream automotive grades. |
| Green Manufacturing Transition | Braskem's bio-based propylene pathways capture premium positioning among EU F-Gas Regulation-compliant automotive OEMs. |
| Long-term Supply Agreement | LyondellBasell's CirculenRenew mass-balance certification locks in five-year model cycle commitments from German Tier-one suppliers. |
| Joint Venture | Ningbo-Zhoushan petrochemical partnerships localize clarified random copolymer production for East Chinese thin-wall packaging converters. |
| Capacity Expansion | Gujarat petrochemical corridors add propylene derivative capacity to reduce India's import dependence for specification-grade automotive materials. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary discussions included technical R&D directors at catalyst technology licensors, procurement leads at German Tier-one automotive suppliers, plant managers at Yangtze River Delta integrated complexes, and distribution channel partners serving packaging converters. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from listed petrochemical majors, and SAMR food-contact certification databases. Bottom-up grade-level volume estimates triangulated against top-down regional consumption models.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity utilization and post-recovery automotive production normalization. The analytical framework modeled segmentation across copolymer architecture, end-use industry, conversion technology, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating MIIT fuel-efficiency mandate implementation timelines and REACH registration cost pass-through assumptions.
The model assumes a particular technology adoption path; alternative pathways for reactor-grade thermoplastic polyolefin convergence would alter the outlook. Forecasts reflect assumptions regarding propylene feedstock cost stability and EU carbon-border adjustment mechanism scope. A small set of triggers—including BIS VOC standard enforcement in India and mechanical recycling decontamination cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Aromatic Ketone Polymer Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
Modified Epoxy Resins Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Middle East Polyethylene Market