
 Middle East Polyethylene Market | 2026-2036
Middle East Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Polyethylene Market Foresight
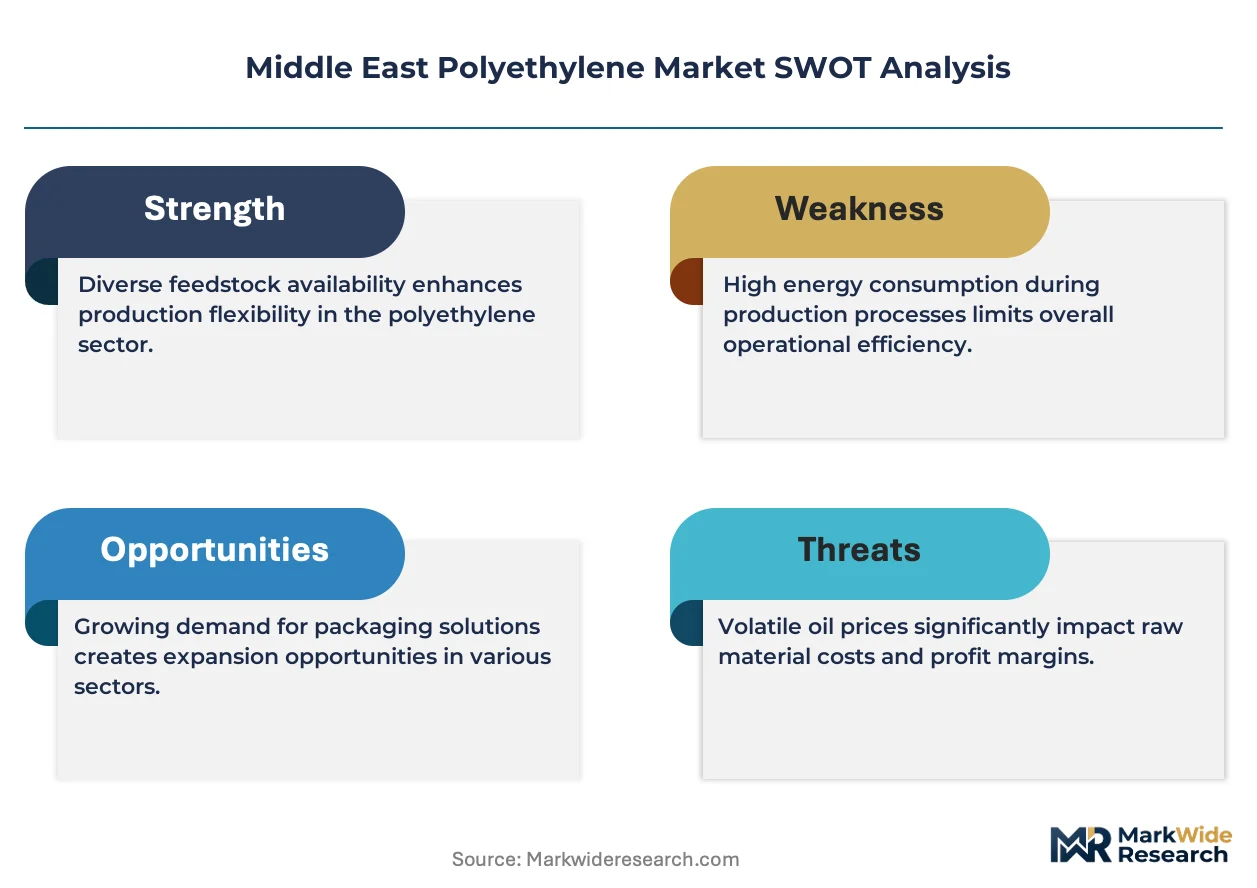
Saudi Arabia's ethane-rich feedstock position is recalibrating regional cost curves and export competitiveness. SABIC leverages fully integrated cracker-to-polymer complexes along the Gulf coast to sustain margin advantages against naphtha-based Asian rivals. Borouge anchors high-value differentiated polyethylene output through its Abu Dhabi Ruwais complex, while Qatar Petrochemical Company (QAPCO) competes on reliability and Gulf-wide logistics access.
Polyethylene comprises thermoplastic polymers formed through ethylene polymerization, with density grades spanning crystalline high-density variants to branched low-density forms produced via slurry, solution, or gas-phase processes. The material serves primarily as a barrier, structural, and flexible packaging substrate across consumer and industrial supply chains. High-Density Polyethylene dominates construction pipe and rigid container applications where stiffness and chemical resistance command premium pricing, while Linear Low-Density Polyethylene leads film and sheet growth due to downgauging trends in food packaging. Film and Sheet application volumes outpace blow molding in the Middle East, reflecting regional food industry expansion and limited local automotive assembly depth.
Saudi Food and Drug Authority (SFDA) food-contact compliance requirements and Gulf Standardization Organization (GSO) technical regulations for plastic building materials shape product certification and market access across Gulf Cooperation Council member states. The UAE's Ministry of Industry and Advanced Technology (MoIAT) conformity assessment schemes for imported polymers add procedural layers for non-Gulf suppliers seeking Emirates market entry. Stakeholders must monitor evolving extended producer responsibility frameworks and circularity mandates, as these will determine feedstock qualification criteria and capital allocation priorities for new cracker investments.
Market Dynamics
Metallocene catalyst technology is redirecting capital allocation across Gulf polyethylene producers, compressing the cost-performance gap between commodity and differentiated grades while SFDA food-contact compliance requirements reshape product certification roadmaps.
Growth Catalysts
- SFDA food-contact regulations:Saudi Arabia's tightened material safety standards are forcing packaging converters to upgrade extrusion capabilities, creating qualified supplier premiums for certified resin producers.
- Jebel Ali logistics infrastructure:The UAE free zone's bonded warehousing and re-export customs efficiencies position Gulf producers to capture East African and South Asian film demand growth.
- Ethane feedstock economics:Saudi Arabia's advantaged natural gas liquids access sustains cracker margin spreads against naphtha-based Asian competitors, preserving export competitiveness.
Market Restraints
- Naphtha price volatility:Regional producers with mixed feedstock exposure face margin compression when oil-indexed naphtha costs spike against stable ethane contracts.
- Supply concentration in the Gulf coast:Over half of regional polyethylene output clusters within SABIC's integrated complexes, creating single-source vulnerability for specialized grades.
- Mechanical recycling contamination limits:Current reprocessing technologies cannot reliably eliminate odor and color defects for food-contact applications, capping circular feedstock adoption.
Strategic Opportunities
- Qatar's RLP expansion corridor:Ras Laffan's planned derivatives cluster offers greenfield sites for producers seeking captive ethane and Gulf-wide tanker access.
- Metallocene-linear low-density convergence:Downgauging trends in flexible food packaging are accelerating demand for puncture-resistant film grades with enhanced optical properties.
- Extended producer responsibility frameworks:Pending circularity mandates across GCC states will qualify chemically recycled feedstocks for premium pricing in sustainability-linked procurement.
Industry Challenges
- Polymer process engineering talent scarcity:Regional universities produce insufficient gas-phase reactor specialists, forcing producers to import expertise for catalyst optimization projects.
- SFDA certification timelines:Food-contact material approvals now require 18-24 month validation cycles, delaying new grade commercialization and locking in incumbent formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Polyethylene Market |
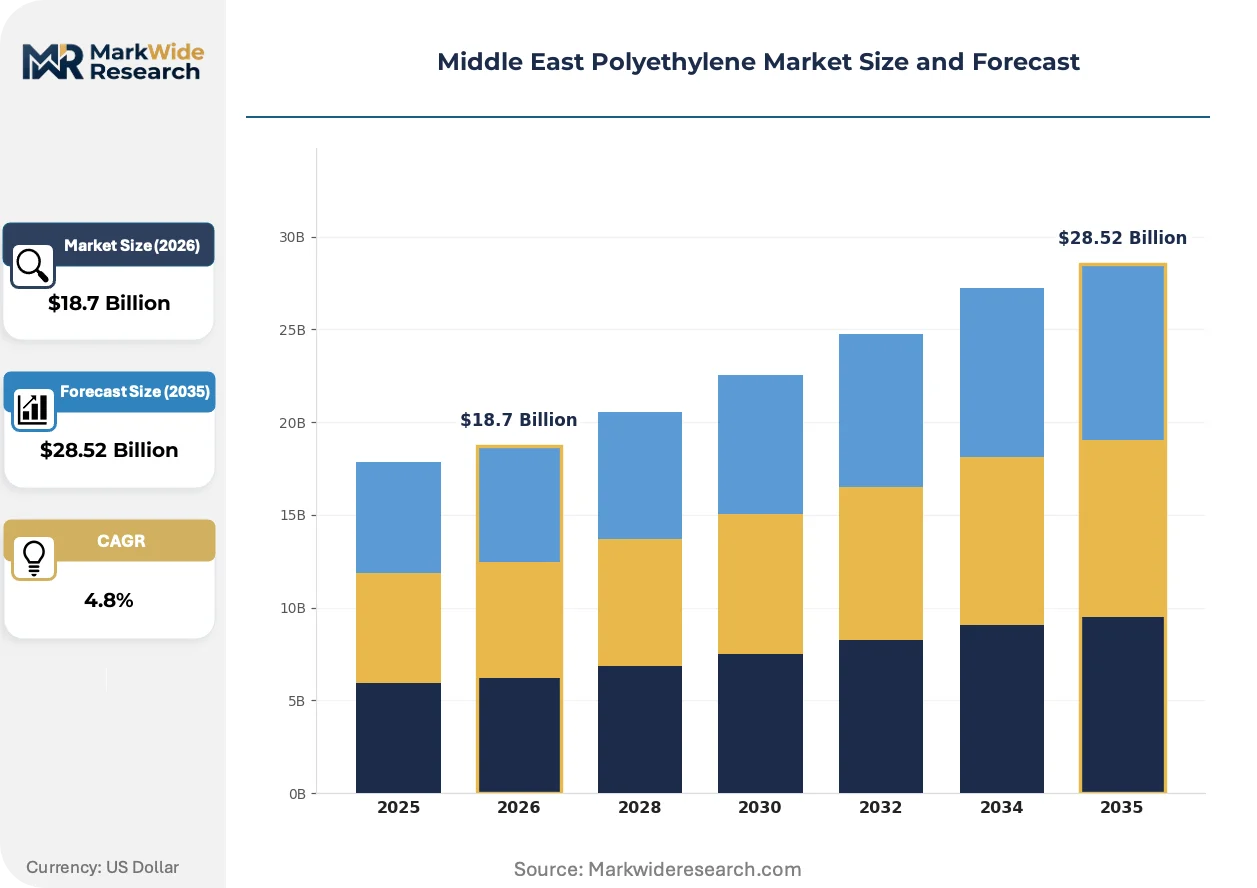
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Linear Low-Density Polyethylene, Ultra-Low-Density Polyethylene End User: Packaging, Automotive, Construction, Textiles Application: Film & Sheet, Injection Molding, Blow Molding, Extrusion Coating Distribution Channel: Direct Sales, Distributors, Online Retailers, Wholesale Suppliers |
| Companies Covered | SABIC, Borouge, Saudi Ethylene and Polyethylene Co. (Tasnee), Qatar Petrochemical Company (QAPCO), ExxonMobil Corporation, Dow, LyondellBasell Industries Holdings BV, Sharq - Eastern Petrochemical Co. (SDPC), Advanced Petrochemical Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Polyethylene Market Shifts & Advancements
Active catalyst research and regulatory tightening are compressing product development cycles across Middle East polyethylene value chains, forcing simultaneous investment in performance differentiation and compliance infrastructure.
Advanced metallocene single-site catalyst systems are decentralizing grade development authority from central R&D labs to individual reactor lines. Packaging converters in the UAE and Saudi Arabia are adopting these systems at accelerating rates to produce lot-specific melt-index tailored to customer downgauging requirements. This capability is decentralizing technical service relationships, allowing mid-size extruders to bypass traditional distributor technical support and negotiate direct resin specifications with producers.
Gulf Standardization Organization technical regulations for plastic building materials are tightening migration limits and mechanical property thresholds across GCC member states. Industrial pipe and geomembrane segments face the steepest compliance burdens, with HDPE pressure pipe grades now requiring enhanced slow-crack-growth resistance certification. Producers are responding by accelerating bimodal reactor technology deployment to meet these specifications without sacrificing processability.
Buyers across East African re-export corridors are consolidating film-grade procurement through Dubai-based trading houses rather than direct mill relationships. Kenyan and Ethiopian packaging converters now specify resin through Jebel Ali inventory pools, compressing order cycles from quarterly to monthly while shifting price risk to intermediaries. This channel consolidation is most visible in LLDPE stretch film and shrink wrap categories, where standardized grades dominate and technical differentiation carries limited premium.
Middle East Polyethylene Market Segmentation
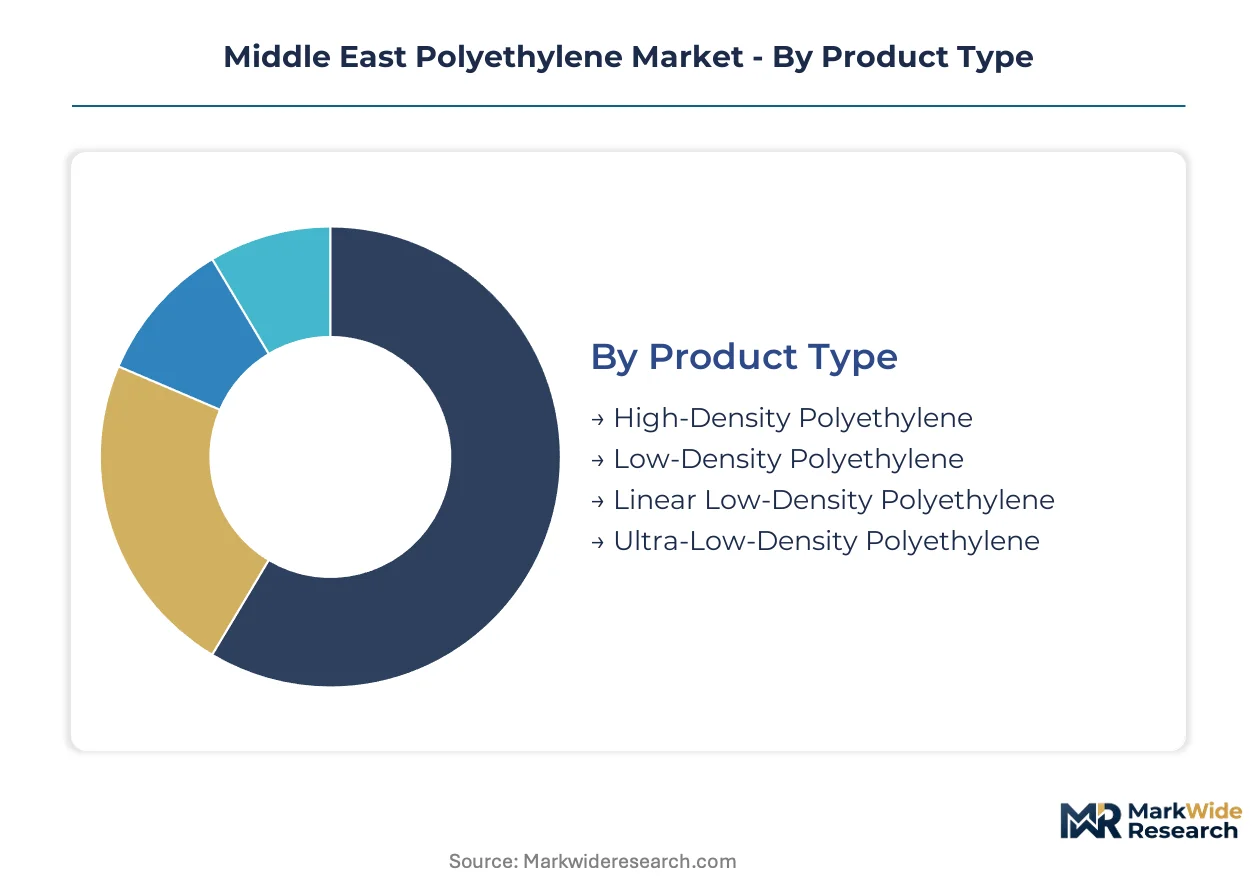
Polyethylene grade selection across the Middle East hinges on catalyst technology and density specifications that determine barrier properties, processability, and compliance with Saudi SFDA food-contact mandates. Each segment category reflects distinct technical requirements and procurement patterns shaped by regional converter capabilities and re-export logistics through Jebel Ali.
Product Type:
Density grades differentiate polyethylene by crystallinity, molecular weight distribution, and catalyst system, directly determining mechanical properties and regulatory compliance pathways.
- High-Density Polyethylene:Linear polymer chains with minimal branching yield stiffness and chemical resistance for pressure pipe and rigid container applications. Saudi construction sector demand concentrates in water infrastructure projects where GSO technical regulations mandate enhanced slow-crack-growth resistance certification.
- Linear Low-Density Polyethylene:Short-chain branching from alpha-olefin comonomers delivers puncture resistance and optical clarity for downgauged food packaging films. UAE packaging converters at Jebel Ali free zone drive procurement volumes for re-export to Kenyan and Ethiopian markets.
- Low-Density Polyethylene:Highly branched structure from high-pressure radical polymerization produces clarity and flexibility for shrink wrap and general-purpose films. Qatar Petrochemical Company supplies this grade through Gulf-wide tanker distribution networks.
- Ultra-Low-Density Polyethylene:Very low crystallinity enables soft-touch applications and impact modifiers for specialty compounding. Limited regional production forces reliance on imported material for medical and consumer goods segments.
High-Density Polyethylene leads on scale; Linear Low-Density Polyethylene leads on momentum.
End User:
Customer verticals concentrate demand differently across the Gulf Cooperation Council, with packaging dominating film extrusion investments and construction driving pipe grade specifications.
- Packaging:Flexible and rigid food-contact applications dominate regional polyethylene consumption. SFDA compliance requirements force converters toward certified resin grades with documented migration testing.
- Construction:HDPE pressure pipe and geomembrane applications require bimodal reactor technology to meet GSO mechanical property thresholds. Saudi infrastructure spending anchors this vertical's procurement scale.
- Automotive:Limited regional vehicle assembly depth constrains fuel tank and interior trim demand. Imported compound formulations serve niche tier supplier requirements.
- Textiles:Fiber and nonwoven applications from metallocene-catalyzed grades supply regional hygiene product manufacturing. UAE-based converters source through direct mill relationships for spunbond production.
Packaging commands absolute volume; Construction shows steepest expansion trajectory from infrastructure investment cycles.
Application:
Processing method determines resin specifications, with film extrusion requiring narrow melt-index distributions and blow molding demanding broader process windows.
- Film & Sheet:Cast and blown film lines across GCC states process LLDPE and LDPE for food packaging, stretch wrap, and agricultural films. Downgauging trends accelerate metallocene grade adoption for thickness reduction without performance loss.
- Blow Molding:HDPE and LLDPE grades form hollow containers for chemicals, lubricants, and food products. Saudi Arabia's chemical industry proximity supports captive supply chains for industrial drum applications.
- Injection Molding:High-flow HDPE grades serve crate, pallet, and closure production with fast cycle times. Limited regional automotive presence constrains technical compound growth.
- Extrusion Coating:LDPE and specialty copolymers laminate paper and foil substrates for liquid packaging. Food-contact compliance complexity favors established supplier relationships over spot procurement.
Film & Sheet dominates current output; Blow Molding gains share fastest from chemical packaging demand.
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and inventory risk tolerance across converter segments.
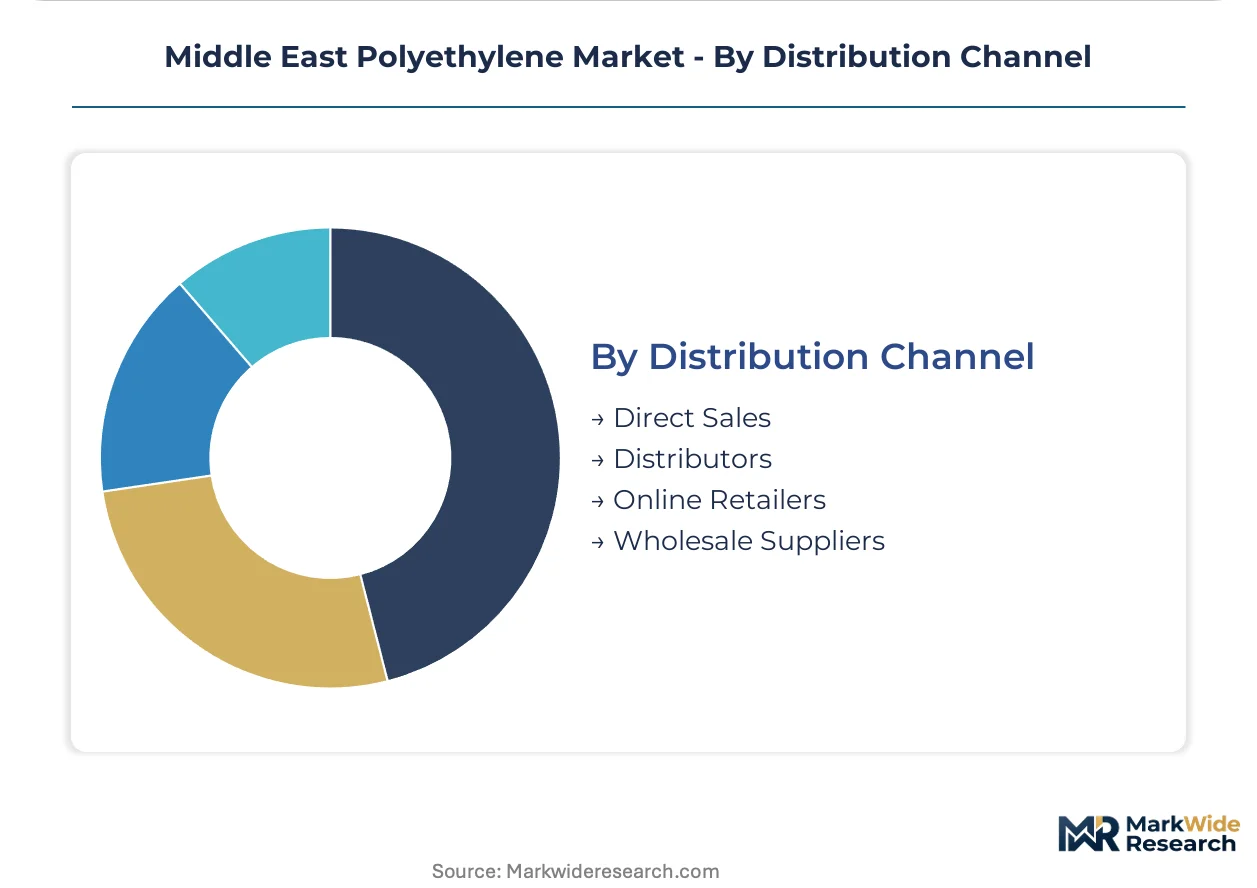
- Distributors:Dubai-based trading houses consolidate procurement for East African re-export markets, compressing order cycles and absorbing price volatility. Jebel Ali bonded warehousing enables monthly rather than quarterly purchasing.
- Direct Sales:Large-volume converters negotiate resin specifications directly with SABIC, Borouge, and QAPCO for captive cracker supply. Technical service relationships center on catalyst optimization and grade customization.
- Wholesale Suppliers:Regional inventory pools serve mid-size extruders without tank storage capacity. Price risk transfers to intermediaries in standardized grade categories.
- Online Retailers:Emerging digital platforms target small-batch specialty compound and masterbatch procurement. Limited penetration reflects polyethylene's commodity logistics requirements.
Distributors lead on transaction volume; Direct Sales leads on margin capture and technical integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's ethane-advantaged crackers command margin leadership against Qatar's reliability-focused complexes, while UAE logistics infrastructure captures re-export arbitrage across East African corridors.
Saudi Arabia
SABIC's integrated Gulf coast complexes process captive ethane into high-density pipe grades for water infrastructure projects. SFDA food-contact material regulations now require 18-24 month certification cycles, locking converters into approved resin formulations. The Eastern Province concentration around Jubail Industrial City anchors specialty grade development for construction and packaging verticals.
United Arab Emirates
Jebel Ali free zone bonded warehousing enables monthly procurement cycles for Kenyan and Ethiopian packaging converters seeking linear low-density film grades. MOIAT conformity assessment schemes add procedural layers for non-Gulf polymer suppliers targeting Emirates market entry. Dubai-based trading houses consolidate East African re-export demand, compressing price risk onto intermediary inventory pools.
Qatar
QAPCO leverages Ras Laffan's tanker-accessible derivatives cluster for Gulf-wide polyethylene distribution with emphasis on schedule reliability. The planned RLP expansion corridor offers greenfield sites with captive ethane access for producers seeking regional scale. Industrial Mesaieed concentrates downstream conversion capacity for export-oriented film and injection molding applications.
Kuwait
Petrochemical Industries Company operates mixed-feed crackers with exposure to naphtha price volatility against regional ethane-based rivals. Domestic packaging demand remains constrained by population scale, directing output toward re-export through Gulf Cooperation Council distribution networks. Shuaiba Industrial Area hosts conversion facilities serving Iraqi and Jordanian cross-border markets.
Oman
Orpic's Liwa Plastics Industries Complex represents the sultanate's push into polyethylene self-sufficiency with bimodal reactor technology for pressure pipe certification. Sohar Port and Freezone logistics infrastructure positions Omani output for Indian subcontinent and East African export corridors. Duqm Special Economic Zone offers tax-advantaged sites for downstream film extrusion investments.
Middle East Polyethylene Market Competitive Landscape
Gulf state producers anchor the integrated tier; international specialists with regional trading offices hold the import-supply position. Market structure concentrates around three domestic ethane-advantaged operators with single-source dominance in specialized grades, while distributors fragment standardized film-grade procurement. Strategic archetypes separate fully integrated cracker-to-polymer operators, logistics-anchored trading intermediaries, and catalyst-technology licensors. Capacity expansion and metallocene grade diversification represent the dominant competitive vectors reshaping supply positioning.
Within the integrated operator tier, SABIC, Borouge, and QAPCO occupy positions defined by feedstock access and Gulf coast logistics infrastructure. SABIC exemplifies the ethane-integrated archetype through its Jubail and Yanbu complex network. Borouge represents the joint-venture model combining regional feedstock with international catalyst technology access. QAPCO anchors the reliability-specialist position through Ras Laffan's tanker-distribution reach across Gulf Cooperation Council markets.
| Leading Market Players |
|---|
| SABIC |
| Borouge |
| Saudi Ethylene and Polyethylene Co. (Tasnee) |
| Qatar Petrochemical Company (QAPCO) |
| ExxonMobil Corporation |
| Dow |
| LyondellBasell Industries Holdings BV |
| Sharq - Eastern Petrochemical Co. (SDPC) |
| Advanced Petrochemical Company |
| Others |
Supply & Pricing Matrix
Captive ethane integration across Saudi Arabia's Gulf coast complexes anchors both supply security and margin structure for regional polyethylene producers. SABIC's cracker-to-polymer network leverages fixed-cost ethane contracts against naphtha-indexed Asian rivals, compressing price floors while preserving export competitiveness through Jubail and Yanbu logistics hubs.
Pricing Analysis
Capacity additions in Qatar's Ras Laffan corridor are reshaping price floors for linear low-density film grades serving East African re-export markets. Contract-based long-term offtake dominates procurement between integrated producers and large-volume converters, with price differentiation driven by SFDA food-contact certification tier and volume scale. Pricing pressure stems from naphtha cost volatility at Kuwait's mixed-feed crackers, which forces spot market exposure against stable ethane economics. Small-batch compound buyers show highest price sensitivity; certified resin purchasers for medical and food-contact applications show lowest.
Supply Chain Analysis
Ethane feedstock supply rests on Saudi Arabia's natural gas liquids infrastructure and Qatar's North Field expansion output. Specialty catalyst systems draw from limited global licensors, while bimodal reactor components source from German and Japanese engineering specialists. Single-source vulnerability concentrates in SABIC's specialty grade dominance, where over half of regional high-performance polyethylene output clusters within Jubail complexes. Distribution runs through Jebel Ali bonded warehousing for re-export to Kenyan and Ethiopian converters, with direct mill relationships serving large GCC-based film extruders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through metallocene catalyst adoption, where premium-grade price premiums widen against commodity polyethylene spreads. Ethane cost advantages at integrated Gulf coast complexes sustain structural profitability even during naphtha price spikes.
For Market Incumbents: To counter naphtha price volatility exposure at mixed-feed assets, deepen backward integration into captive ethane supply through Qatar's North Field access or Saudi master gas system expansion. Accelerate bimodal reactor deployment to capture GSO-certified pipe grade premiums. Prioritize SFDA food-contact certification investment to lock in 18-24 month approval cycles that freeze out unqualified resin competitors. For New Entrants and Emerging Players: Digital trading platforms targeting small-batch specialty compound procurement offer the lowest friction entry path around established distributor relationships. White-space concentrates in ultra-low-density polyethylene for medical applications, where regional production gaps force import dependence. Target Oman's Duqm Special Economic Zone for tax-advantaged film extrusion serving Indian subcontinent export corridors. For Investors and Strategic Acquirers: Roll-up economics work for mid-size distributors consolidating East African re-export procurement because Jebel Ali logistics infrastructure enables inventory pooling across fragmented Kenyan and Ethiopian converter bases. Five-to-ten year viability hinges on circularity mandate timing across GCC states. Watch for extended producer responsibility framework implementation as the inflection signal qualifying chemically recycled feedstocks for premium pricing.| Strategic Initiative | Industry Significance |
|---|---|
| Metallocene Catalyst Deployment | Enables downgauged film grades with enhanced puncture resistance for SFDA-compliant food packaging. |
| Backward Integration into Ethane Supply | Secures fixed-cost feedstock advantage against naphtha-indexed Asian competitors at Ras Laffan. |
| SFDA Certification Investment | Locks converters into approved resin formulations through 18-24 month validation cycles. |
| Jebel Ali Logistics Expansion | Captures East African re-export arbitrage through bonded warehousing and monthly procurement cycles. |
| Bimodal Reactor Technology Adoption | Meets GSO slow-crack-growth resistance mandates for Saudi water infrastructure pipe grades. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polyethylene plant managers, procurement leads at UAE packaging converters, Jebel Ali distribution channel partners, and SFDA regulatory affairs specialists with secondary validation. Trade data from Gulf Cooperation Council customs authorities, SABIC and Borouge technical disclosures, and GSO technical regulation filings anchored volume estimates. Bottom-up grade-level consumption models triangulated against top-down cracker capacity utilization assessments.
Historical reference periods spanning pre-pandemic baseline through recent capacity expansion waves anchored the projection horizon. Segmentation modeling covered density grade tier, end-use vertical, processing application, and regional production hub. CAGRs derived from ethane-naphtha spread trajectories, SFDA regulatory implementation timelines, and metallocene adoption curves across GCC film extrusion investments. Forecast inputs included catalyst technology licensing rates and circularity mandate legislative progression.
The model assumes a particular technology adoption path; alternative pathways for chemical recycling commercialization would alter the outlook. Forecasts reflect assumptions around ethane contract stability, SFDA certification timeline consistency, and Jebel Ali logistics capacity expansion. Material deviation in naphtha price volatility, circularity mandate acceleration, or catalyst licensor supply constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Resin Intermediate Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market