
 Chlorinated Polyvinyl Chloride (CPVC) Market | 2026-2036
Chlorinated Polyvinyl Chloride (CPVC) Market Size, Share, and Industry Trends Forecast 2026-2036
Chlorinated Polyvinyl Chloride (CPVC) Market Analysis
The premium-commodity split in CPVC is rebalancing around ASTM F441 compliance grades versus basic plumbing formulations. The Lubrizol Corporation leverages its vertical integration from chlorine to finished resin to sustain margin capture across both tiers. Sekisui Chemical anchors its position through proprietary peroxide suspension technology that differentiates its output in Japanese and Southeast Asian specifications. KEM ONE competes on scale from its Fos-sur-Mer complex, where captive chlorine supply controls feedstock volatility.
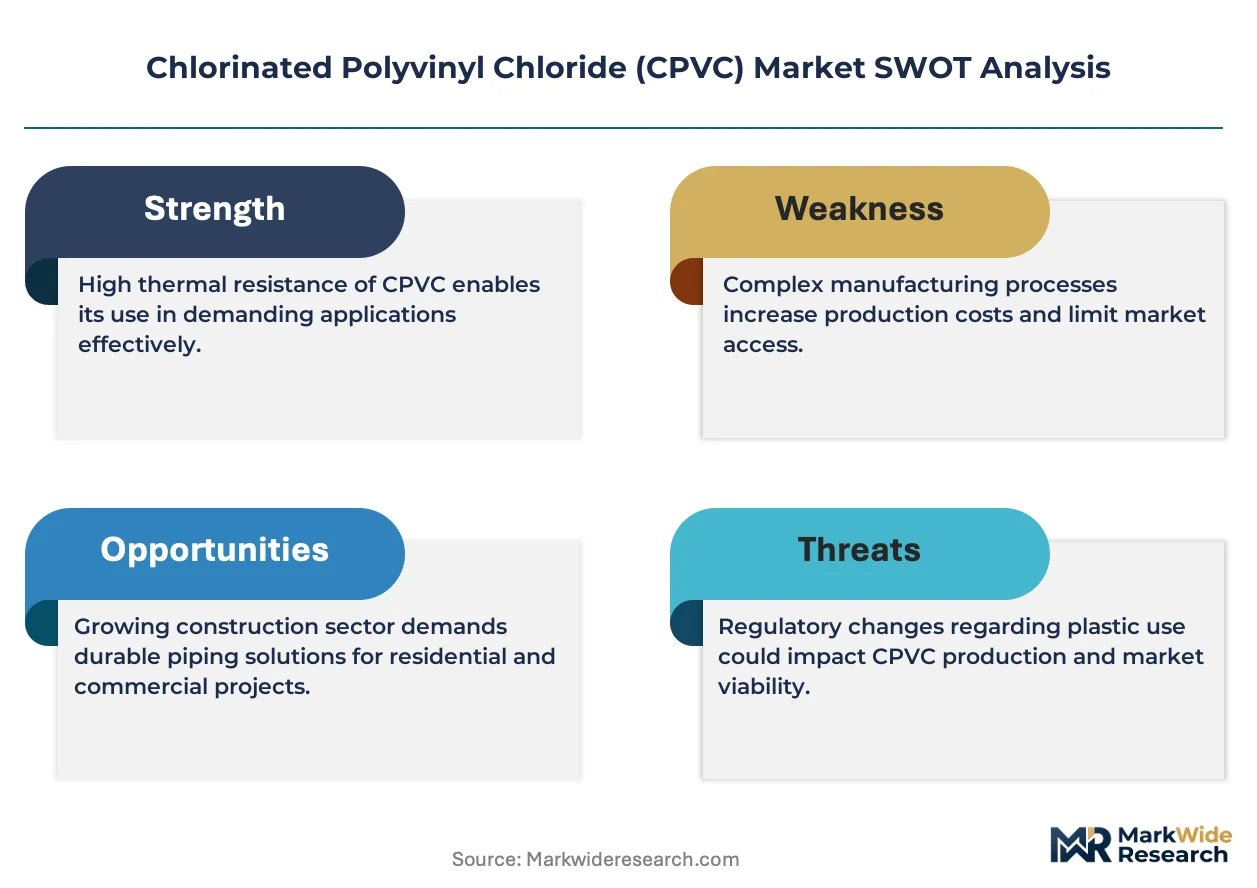
Chlorinated polyvinyl chloride is a thermoplastic polymer produced by post-chlorination of PVC resin, typically achieving 63-69% chlorine content by weight to raise heat distortion temperature above 100°C for pressurized hot-fluid conveyance. CPVC pipes dominate volume flows in construction applications, where residential hot water plumbing represents the most mature demand pool with thinning margins. CPVC fittings command disproportionate margin contribution in chemical processing, where corrosive fluid handling specifications from end users in industrial sectors sustain premium pricing for injection-molded specialty configurations.
ASTM F441 and NSF/ANSI 61 govern potable water contact in the US market, while India's BIS IS 15778 mandates mechanical and leaching standards that shape import eligibility and domestic manufacturing investment. The EPA's lead-free plumbing requirements under the Safe Drinking Water Act and REACH restrictions on plasticizer migration in Europe are converging to elevate specification stringency across jurisdictions. Stakeholders must monitor how India's PLI scheme for chemicals and petrochemicals alters domestic chlor-alkali capacity, as this upstream expansion will reshape regional cost structures and export competitiveness.
Market Dynamics
India's BIS certification tightening for potable water piping is compressing import eligibility windows and forcing domestic capacity expansion decisions by resin compounders and extrusion manufacturers.
Growth Catalysts
- Residential hot water plumbing:Plumbing contractors in India's western states are specifying CPVC for pressurized distribution systems in new housing stock.
- BIS IS 15778 compliance mandates:Mechanical and leaching standards are redirecting procurement toward certified domestic manufacturers.
- Peroxide suspension chlorination:Advanced resin production methods are expanding heat distortion temperature thresholds for industrial chemical handling.
Market Restraints
- Chlor-alkali feedstock volatility:Captive chlorine supply concentration in coastal chemical complexes exposes compounders to caustic soda co-product demand swings.
- PVC resin import dependence:Domestic Indian chlor-alkali capacity gaps force reliance on Middle Eastern and Southeast Asian base resin flows.
- PEX tubing substitution:Cross-linked polyethylene alternatives are capturing share in residential plumbing specifications where flexibility outweighs temperature rating.
Strategic Opportunities
- Gujarat-Maharashtra chemical processing corridor:Industrial-grade CPVC consumption for corrosive fluid conveyance remains underpenetrated versus metallic alternatives.
- PLI scheme for chemicals and petrochemicals:Production-linked incentives are accelerating domestic chlor-alkali capacity additions that reshape regional cost structures.
- NSF/ANSI 61 certification convergence:Harmonized potable water standards are opening export pathways for Indian extruders into Middle Eastern and African markets.
Industry Challenges
- ASTM F441 certification timelines:Extended third-party testing protocols for pressure-rated compounds delay product launches by 12-18 months.
- Injection-molding tooling capex:Specialty fitting production requires high-cavitation molds that strain mid-tier compounder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlorinated Polyvinyl Chloride (CPVC) Market |
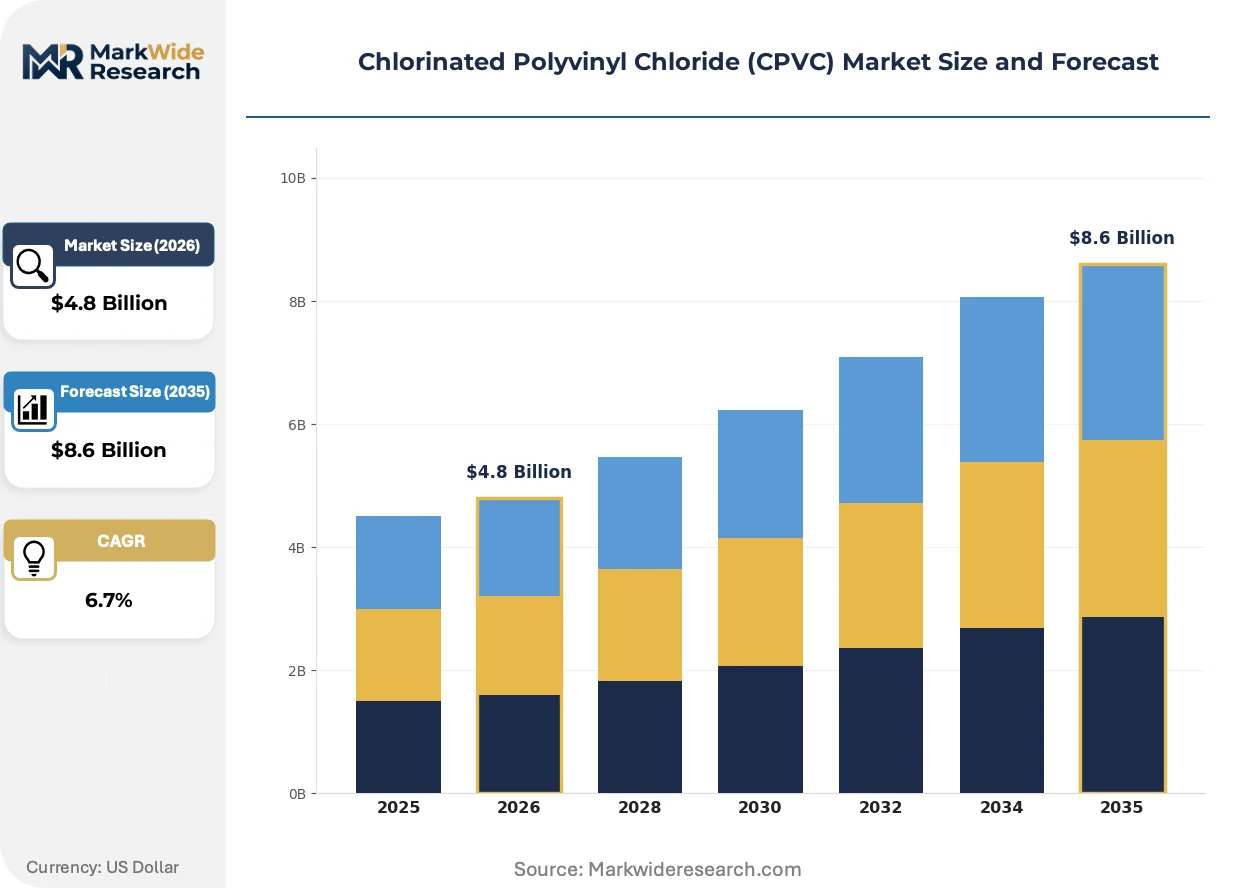
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CPVC Pipes, CPVC Fittings, CPVC Valves, CPVC Sheets Application: Construction, Chemical Processing, Water Distribution, HVAC End User: Residential, Commercial, Industrial, Government Form: Solid, Granular, Liquid, Powder |
| Companies Covered | The Lubrizol Corporation, Sekisui Chemical Co., Ltd., KEM ONE, Kaneka Corporation, Shandong Novista Chemical Co., Ltd., Meghmani Finechem Limited, DCW Limited, Epigral Limited, Finolex Industries Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlorinated Polyvinyl Chloride (CPVC) Market Emerging Trajectories
CPVC formulation science is pivoting toward higher chlorine content grades that expand temperature envelopes while regulatory pressure on plasticizer migration forces compound redesigns across jurisdictions.
High-chlorine content suspension resins are decentralizing production geography by enabling smaller-batch compounders to achieve industrial-grade performance without massive chlorination infrastructure. Regional extruders in India and Southeast Asia are adopting these feedstocks to serve chemical processing clusters. The technology is decentralizing supply chain power from integrated petrochemical giants toward specialized compounders with formulation expertise.
REACH restrictions on plasticizer migration in Europe are converging with EPA lead-free plumbing requirements under the Safe Drinking Water Act to elevate specification stringency. Compounders must now validate leaching profiles across multiple jurisdictions simultaneously. ASTM F441 and NSF/ANSI 61 certification costs are rising fastest for mid-tier extruders serving both export and domestic Indian markets.
Specification-driven procurement is compressing supplier qualification cycles as end users demand bundled certification packages covering mechanical, leaching, and fire performance. Distributors in India's western construction corridors are consolidating around compounders with pre-certified resin libraries. The shift is most visible in Gujarat's residential plumbing contractor networks, where BIS compliance documentation now precedes price negotiation.
Chlorinated Polyvinyl Chloride (CPVC) Market Segmentation
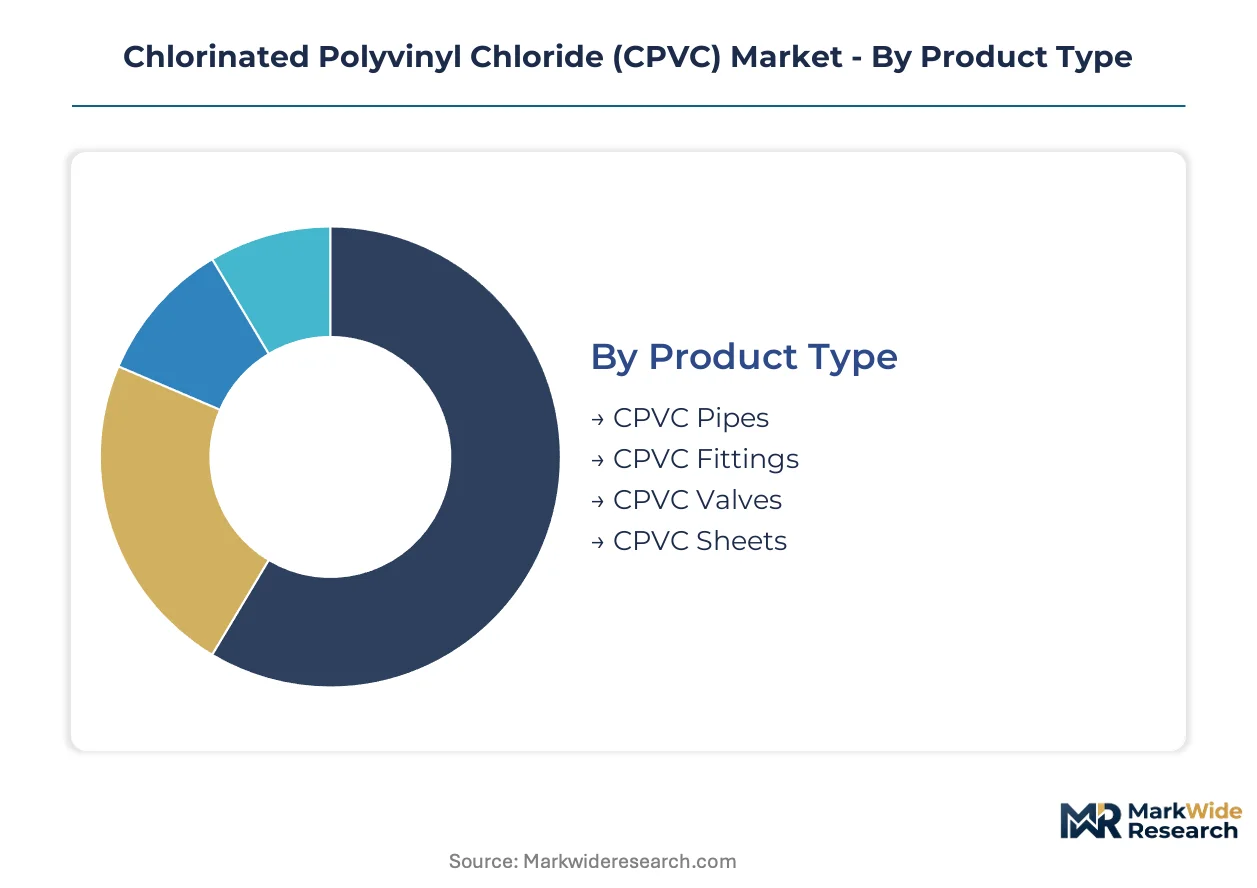
CPVC procurement decisions diverge sharply across end-use contexts. Specification stringency, temperature exposure, and regulatory compliance requirements reshape buyer priorities from residential plumbing contractors to chemical plant engineers.
Product Type:
Buyers prioritize pressure rating and joint reliability over unit cost when selecting among CPVC product categories.
- CPVC Pipes:Extruded tubular products dominate construction volume flows, particularly in residential hot water distribution where ASTM F441 compliance governs pressure-temperature ratings. Gujarat and Maharashtra plumbing contractors specify Schedule 40 and Schedule 80 variants based on static head requirements in multi-story housing stock.
- CPVC Fittings:Injection-molded elbows, tees, and couplings command disproportionate margin contribution in chemical processing applications. Corrosive fluid handling specifications from industrial end users sustain premium pricing for specialty configurations with enhanced chemical resistance.
- CPVC Valves:Ball valves and diaphragm valves serve industrial process control with higher chlorine content grades for elevated temperature thresholds.
- CPVC Sheets:Flat-rolled stock supports tank lining and fabrication applications in chemical processing infrastructure.
Volume sits with CPVC Pipes; growth tilts toward CPVC Fittings as industrial specification penetration deepens.
Application:
Temperature exposure and fluid chemistry determine material grade selection across use cases.
- Construction:Residential and commercial building systems consume standard-grade formulations for potable hot water conveyance. BIS IS 15778 certification mandates in India redirect procurement toward domestic manufacturers with validated leaching profiles.
- Chemical Processing:Chlor-alkali plants, fertilizer complexes, and acid handling facilities specify high-chlorine content resins for heat distortion temperatures exceeding 100°C. Peroxide suspension chlorination technology expands addressable process conditions.
- Water Distribution:Municipal and industrial water networks require NSF/ANSI 61 compliance for potable contact applications.
- HVAC:Chilled water and heating system piping leverages CPVC's corrosion resistance versus metallic alternatives in coastal humidity environments.
Construction captures current volume leadership; chemical processing exhibits the steepest expansion trajectory as metallic replacement accelerates.
End User:
Procurement authority and specification control vary dramatically across buyer types.
- Residential:Plumbing contractors in India's western states drive specification for new housing stock, with BIS compliance documentation now preceding price negotiation in distributor relationships.
- Commercial:Hotels, hospitals, and institutional buildings balance first-cost against lifecycle replacement risk in piping system decisions.
- Industrial:Chemical processing plant engineers mandate certified resin libraries with bundled mechanical, leaching, and fire performance documentation.
- Government:Public infrastructure projects impose extended third-party testing protocols that delay product launches by 12-18 months.
Residential segment holds installed base dominance; industrial buyers are gaining share fastest through specification upgrading.
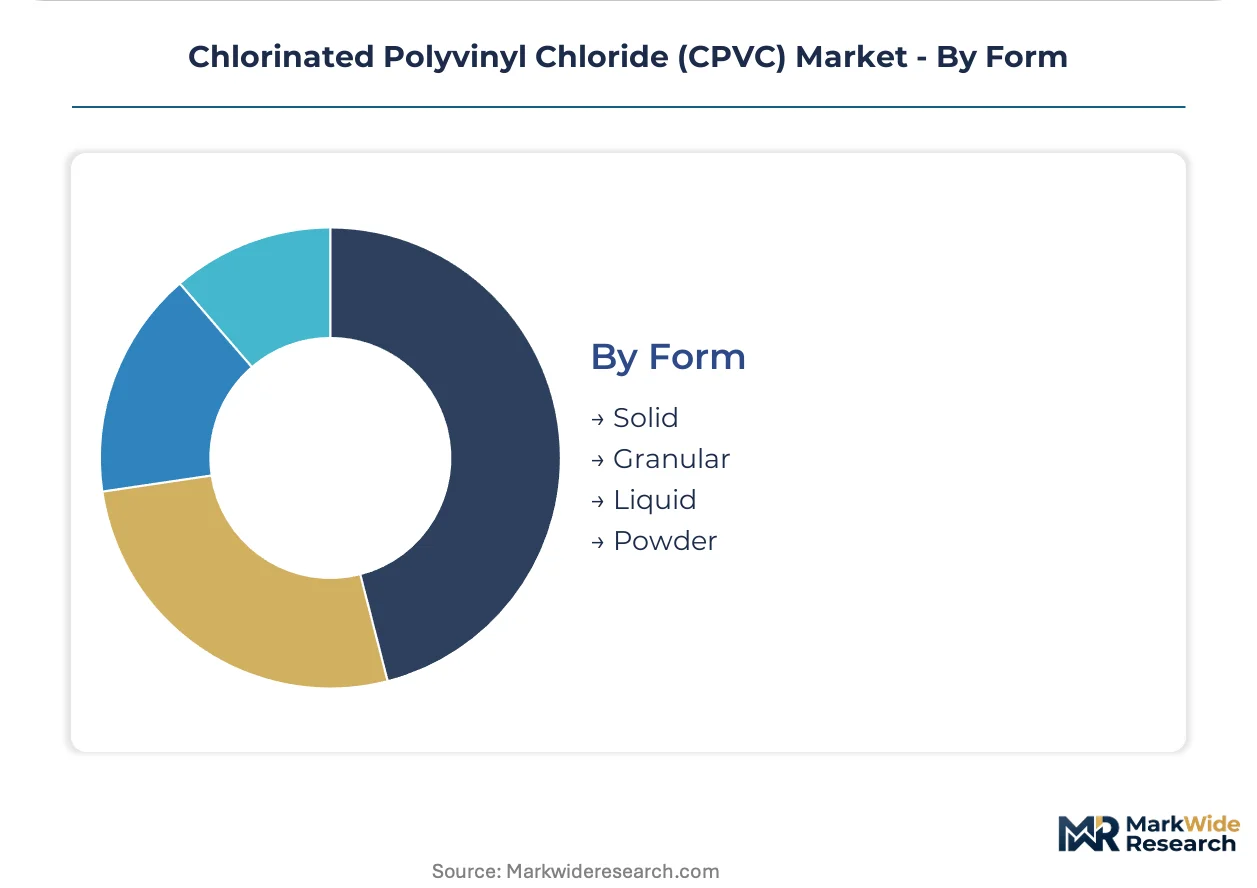
Form:
Downstream processing requirements dictate feedstock format preferences.
- Solid:Rods and bars support machining of specialty components for chemical processing equipment.
- Granular:Pelletized resin enables extrusion of pipes and profiles with consistent melt flow characteristics.
- Liquid:Dispersions and solutions serve coating and adhesive formulations in niche industrial applications.
- Powder:Fine-ground resin supports compression molding and dry-blend compounding for custom formulations.
Granular form dominates extrusion throughput; powder formats are climbing fastest as regional compounders adopt high-chlorine content suspension resins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Gujarat-Maharashtra chemical processing corridor anchors CPVC demand concentration in western India, where chlor-alkali feedstock availability intersects with residential construction expansion and industrial fluid handling specifications.
United States
Plumbing contractors in Texas and Florida drive residential hot water system specifications, with ASTM F441 compliance governing pressure-temperature ratings. EPA lead-free plumbing requirements under the Safe Drinking Water Act elevate certification costs for extrusion manufacturers. Houston's petrochemical complex sustains captive chlorine supply for regional compounders serving Gulf Coast chemical processing facilities.
India
Maharashtra and Gujarat residential contractors specify CPVC for multi-story housing distribution systems amid urbanization acceleration. BIS IS 15778 mandates on mechanical and leaching standards compress import eligibility and redirect procurement toward certified domestic manufacturers. The Gujarat chemical processing corridor at Dahej and Mundra drives industrial-grade consumption for corrosive fluid conveyance in chlor-alkali and fertilizer complexes.
China
Shandong Peninsula and Yangtze River Delta construction markets consume standard-grade formulations for commercial building hot water systems. GB standards for potable water contact materials shape domestic manufacturing investment and import substitution patterns. Qingdao's chemical processing clusters specify high-chlorine content resins for elevated temperature thresholds in acid handling infrastructure.
Germany
REACH restrictions on plasticizer migration converge with industrial HVAC specifications in North Rhine-Westphalia's manufacturing belt. ECHA compliance documentation requirements elevate compounder qualification costs for extruders serving export and domestic markets. The Ruhr industrial corridor sustains demand for specialty fittings in chemical processing applications where metallic replacement accelerates.
Japan
Tokyo-Osaka construction markets balance lifecycle replacement risk against first-cost in commercial building system decisions. JIS standards for pressure-rated thermoplastics govern procurement in institutional and hospitality sectors. Kansai chemical processing facilities specify peroxide suspension chlorination grades for heat distortion temperatures exceeding 100°C in process fluid networks.
Chlorinated Polyvinyl Chloride (CPVC) Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade stratification, with ASTM F441 and NSF/ANSI 61 compliance separating pricing tiers. The vendor base concentrates around integrated petrochemical giants controlling captive chlorine supply, specialized compounders with formulation expertise, and regional extruders serving construction distributor networks. Strategic archetypes include backward-integrated resin producers, technology-licensed suspension chlorination specialists, and specification-focused fitting manufacturers. Dominant competitive moves encompass domestic capacity expansion responding to India's BIS tightening, and technology licensing partnerships enabling regional compounders to access high-chlorine content suspension resin formulations.
Within the integrated producer tier, The Lubrizol Corporation and Sekisui Chemical Co., Ltd. occupy positions exemplifying backward integration from chlorine to finished resin. KEM ONE represents the scale-driven European archetype with coastal chemical complex positioning. These three companies anchor competitive dynamics through differentiated control over feedstock volatility, proprietary chlorination technology, and regional specification capture.
| Leading Market Players |
|---|
| The Lubrizol Corporation |
| Sekisui Chemical Co., Ltd. |
| KEM ONE |
| Kaneka Corporation |
| Shandong Novista Chemical Co., Ltd. |
| Meghmani Finechem Limited |
| DCW Limited |
| Epigral Limited |
| Finolex Industries Limited |
| Others |
Supply Flow & Price Mechanics
Peroxide suspension chlorination technology adoption is compressing production scale requirements while redistributing margin capture toward specialized compounders with formulation expertise rather than integrated petrochemical giants with captive chlorine assets. This method transition simultaneously lowers entry barriers for regional producers in India and Southeast Asia while fragmenting pricing power across the value chain.
Pricing Analysis
Certification-grade anchoring determines price realization, with ASTM F441 and NSF/ANSI 61 compliance separating premium resin tiers from basic plumbing formulations. Price differentiation rests on heat distortion temperature thresholds and leaching validation depth, with industrial chemical processing buyers least sensitive and residential plumbing contractors in India's western states most responsive to unit cost. Pricing pressure intensifies in standard-grade pipes as PEX tubing substitution accelerates in flexible-installation residential specifications.
Supply Chain Analysis
Scrap resin recovery and recompounding flows are underdeveloped across CPVC value chains, creating stranded material losses at extrusion and injection-molding stages. Supply concentrates in the United States, India, and Japan, with chlor-alkali feedstock availability governing regional cost structures. Raw material dependencies span chlorine gas, PVC base resin, and peroxide initiators, with single-source vulnerability concentrated in Middle Eastern PVC resin flows to Indian compounders. Distribution runs through construction distributor networks in residential segments and direct mill-to-plant relationships in chemical processing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CPVC formulation science is transitioning from aqueous suspension chlorination toward higher-efficiency peroxide-initiated processes that displace legacy production assets. This technology replacement phase rewards compounders with flexible batch capabilities over massive integrated chlor-alkali complexes.
For Market Incumbents: To counter PEX tubing capture in residential plumbing specifications, prioritize BIS IS 15778 pre-certification investments that compress domestic competitor qualification timelines in India. Deepen captive chlorine integration through coastal chemical complex expansion that insulates margin structures from caustic soda co-product demand volatility. For New Entrants and Emerging Players: Begin with Gujarat-Maharashtra industrial corridor penetration where metallic pipe replacement in chemical processing remains incomplete and specification documentation requirements have thinned import eligibility. Target high-chlorine content suspension resin compounding for specialty fitting production, leveraging technology licensing partnerships to bypass chlorination infrastructure capex barriers. For Investors and Strategic Acquirers: Re-rating potential sits with mid-tier compounders possessing validated resin libraries and pre-certified formulation portfolios given India's PLI scheme acceleration of domestic chlor-alkali capacity. Long-term viability centers on backward integration into chlorine supply or forward integration into specification-heavy industrial segments. Monitor BIS enforcement intensity and ASTM F441 certification backlog durations as inflection signals for domestic manufacturer pricing power recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlor-Alkali | Captive chlorine supply insulates KEM ONE and Lubrizol from feedstock volatility at Fos-sur-Mer and Texas Gulf Coast complexes. |
| Peroxide Suspension Technology Licensing | Sekisui Chemical's proprietary methods enable regional compounders in India to achieve industrial-grade heat distortion thresholds without massive chlorination assets. |
| BIS IS 15778 Pre-Certification Investment | Domestic Indian extruders with validated leaching profiles capture procurement redirection as import eligibility windows compress under tightening mandates. |
| High-Chlorine Content Resin Capacity Expansion | Specialized compounders serving Dahej and Mundra chemical corridors address unmet demand for elevated temperature specifications in acid handling infrastructure. |
| NSF/ANSI 61 Certification Convergence | Harmonized potable water standards open export pathways for Indian extruders into Middle Eastern and African distributor networks. |
Methodological Framework
Trade databases, chlor-alkali industry association filings, and BIS certification registries formed the secondary backbone, cross-referenced with primary interviews involving CPVC plant managers, plumbing contractor procurement leads, chemical processing maintenance directors, and construction distributor channel partners. Bottom-up volume estimates from extrusion throughput data and top-down validation from resin producer capacity disclosures were triangulated to establish market sizing.
Historical trendline analysis of chlor-alkali capacity utilization, PVC resin import flows, and CPVC pipe installation rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include product grade tier, end-use application context, chlorine content specification, and regional production hub. CAGRs were derived from elasticity-adjusted demand curves incorporating construction activity indices and chemical processing capital expenditure patterns.
Feedstock cost volatility, regulatory enforcement intensity shifts, and substitution acceleration by PEX tubing are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions about PLI scheme implementation pace and BIS certification timeline standardization. Practitioners should monitor chlor-alkali capacity commissioning announcements and ASTM F441 testing protocol changes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Asia-Pacific Super Absorbent Polymers (SAP) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Global Polypropylene Homopolymer (PPH) Market
Polymers & Resins
Global Polyol and Polyurethane Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market