
 Asia-Pacific Polycarbonate (PC) Market | 2026-2036
Asia-Pacific Polycarbonate (PC) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Polycarbonate (PC) Market Insights
Automotive electrification specialists and medical device contract manufacturers are bifurcating the buyer base that once centered on consumer electronics molders. LG Chem leverages its integrated petrochemical complex in Yeosu to sustain captive bisphenol A and PC resin output for Korean EV battery housing programs. Wanhua Chemical Group anchors domestic supply security through its Yantai operations, while Covestro AG competes on optical-grade specialization for Asian smartphone camera lens modules.
Polycarbonate is an amorphous thermoplastic polymer synthesized from bisphenol A and phosgene or via melt transesterification, prized for optical clarity, impact resistance, and dimensional stability across temperatures from minus 40 to 135 degrees Celsius. Its primary commercial purpose centers on substituting glass and metal in weight-critical, transparent, or electrically insulating applications. Injection molding formulations dominate volume throughput for automotive and electronics housings where thin-wall precision commands premium pricing, while extrusion-grade sheets capture construction and safety glazing demand with longer production runs and tighter margin structures. Optical lenses represent a concentrated margin pool where material purity and birefringence control differentiate suppliers.
China's MIIT enforces GB standards for automotive interior flame retardancy that elevate halogen-free PC blend specifications, while Japan's METI administers JIS standards governing optical disc and lens-grade material consistency. South Korea's MFDS and KATS frameworks regulate medical device PC biocompatibility for dialysis equipment and surgical instrument housings. Stakeholders must monitor how China's dual carbon trajectory and extended producer responsibility schemes redirect capital toward chemical recycling and non-phosgene PC process investments rather than conventional capacity additions.
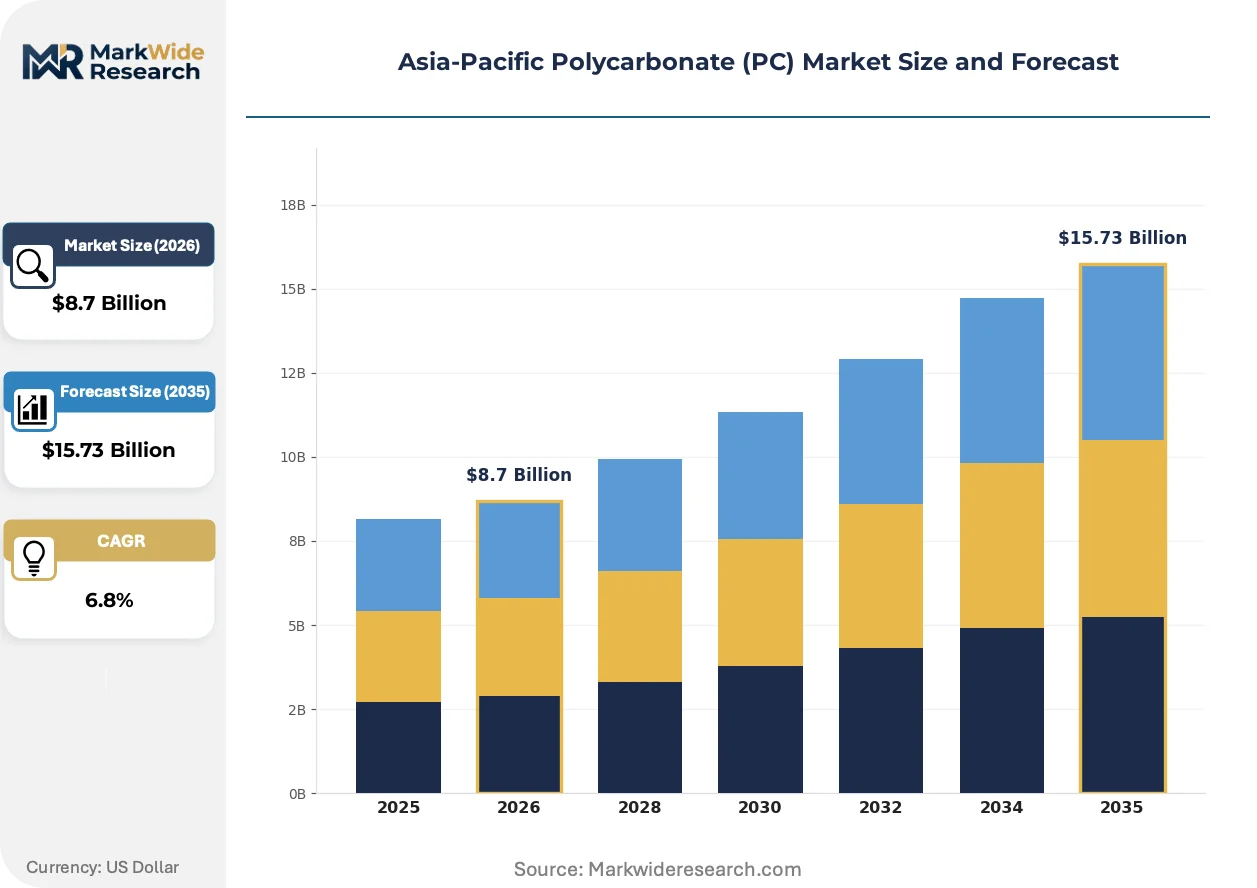
Market Dynamics
Automotive electrification across China, Japan, and South Korea is compressing specification cycles for high-heat, flame-retardant PC grades while redirecting resin flows away from optical disc legacy demand toward battery housing and thermal management applications.
Growth Catalysts
- MIIT Flame-Retardancy Mandates:China's GB standards for halogen-free automotive interiors are elevating specification tiers for PC-ABS blends in EV battery enclosures and charging infrastructure housings.
- Photovoltaic Backsheet Substitution:Extrusion-grade polycarbonate sheets are capturing share from fluoropolymer films in solar module manufacturing across eastern China's Yangtze River Delta cluster.
- Medical Device Reshoring:South Korea's MFDS biocompatibility frameworks and Japan's PMDA quality protocols are concentrating dialysis equipment and surgical instrument housing demand within regulated domestic supply chains.
Market Restraints
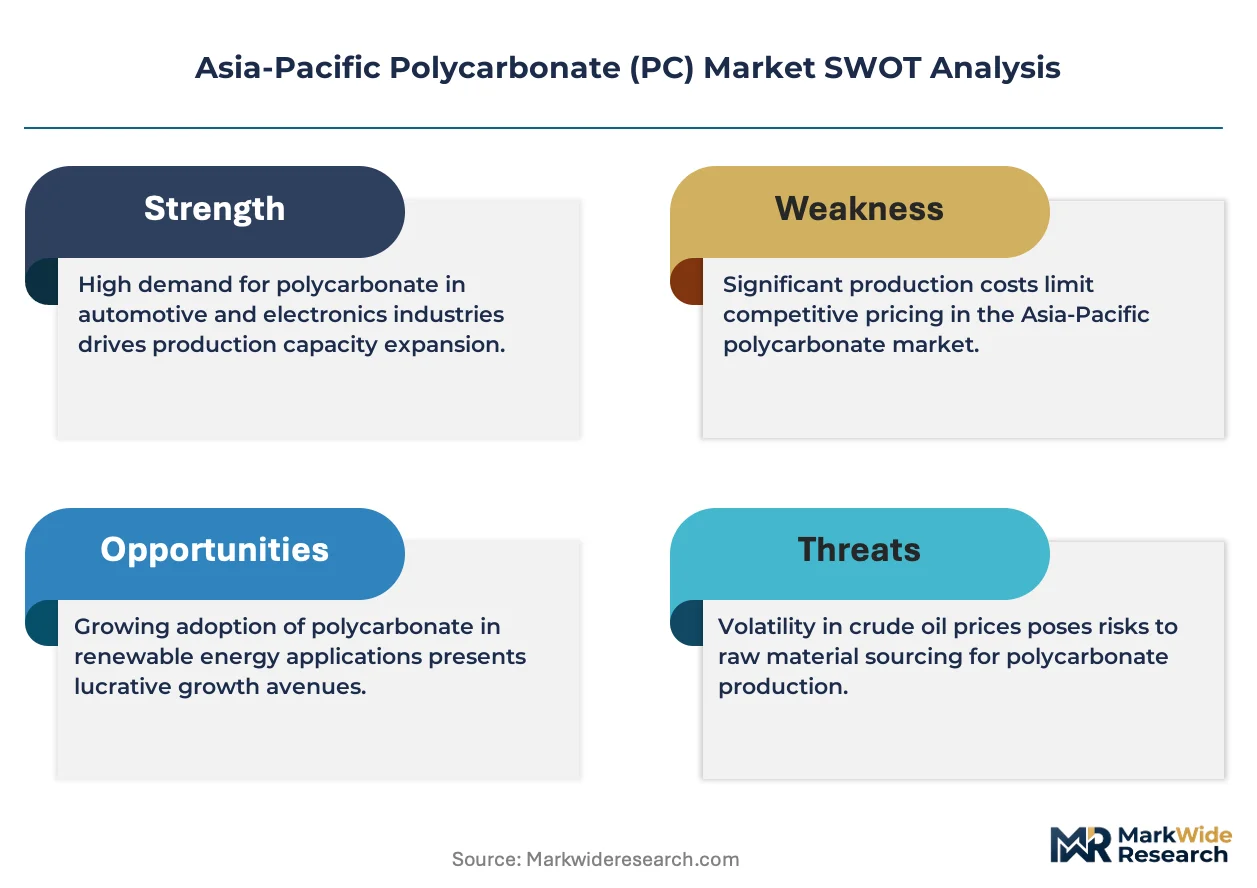
- Bisphenol A Feedstock Concentration:Captive phenol-acetone integration at Yeosu, Ulsan, and Yantai complexes creates supply vulnerability when regional cracker maintenance cycles align.
- Phosgene Process Regulatory Friction:China's MEE environmental enforcement and extended producer responsibility schemes are elevating compliance costs for conventional interfacial polymerization capacity.
- Polyamide Substitution in Thermal Management:High-temperature nylon grades from Japanese compounders are displacing PC in certain EV power electronics housings where continuous-use temperatures exceed 150 degrees Celsius.
Strategic Opportunities
- Chemical Recycling Infrastructure:China's dual carbon trajectory and provincial EPR pilots are creating first-mover advantage for non-phosgene melt transesterification investments with post-consumer feedstock integration.
- Optical Lens Module Specialization:Smartphone camera array proliferation is concentrating margin pools in low-birefringence, high-purity grades for periscope and folded-optic designs.
- Indonesia and Vietnam Manufacturing Migration:Electronics assembly relocation from coastal China is pulling compounding and sheet extrusion capacity toward ASEAN industrial zones with preferential trade access.
Industry Challenges
- Halogen-Free Formulation Expertise Gap:Automotive tier-one molders face certification delays transitioning from brominated flame retardants to phosphorus-based systems meeting simultaneous GB and JIS thermal cycling protocols.
- Optical Grade Purity Capital Intensity:Birefringence control and particulate contamination management require dedicated reactor trains and cleanroom finishing infrastructure that strain mid-scale compounder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Polycarbonate (PC) Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Molding, Extrusion, Sheets, Films End User: Consumer Electronics, Automotive, Construction, Medical Devices Application: Optical Lenses, Safety Glasses, Light Fixtures, Packaging Form: Granules, Pellets, Blends, Compounds |
| Companies Covered | LG Chem, Wanhua Chemical Group, Covestro AG, Chimei Corporation, Teijin Limited, Mitsubishi Chemical Corporation, SABIC, Formosa Chemicals & Fibre Corporation, LOTTE Chemical Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Polycarbonate (PC) Market Trends and Innovations
Bio-based feedstock integration and mechanical recycling process refinement are bifurcating technical development paths, with virgin resin producers defending specification premiums while downstream compounders capture circularity credentials.
Non-phosgene melt transesterification technology is fragmenting process technology licensing across the supplier base. Chinese state-owned engineering firms and European technology licensors are competing to deploy continuous melt processes that eliminate chlorine handling and enable post-consumer content integration. Korean petrochemical complexes are adopting hybrid configurations that preserve phosgene lines for optical grades while adding melt capacity for automotive and construction volumes. This process divergence is fragmenting capital deployment strategies and creating technology-dependent supply moats.
China's dual carbon goals and extended producer responsibility schemes are compressing timelines for chemical recycling infrastructure deployment. Provincial pilot programs in Zhejiang and Jiangsu are mandating post-consumer content minimums for construction and packaging applications by 2027. Japanese METI circular economy roadmaps are coordinating cross-industry consortia for optical disc and automotive shredder residue recovery. These regulatory frameworks are redirecting R&D expenditure from conventional capacity expansion toward depolymerization and purification process development.
Specification consolidation among automotive OEMs is compressing supplier qualification cycles and elevating compounder technical service requirements. Korean and Chinese EV manufacturers are consolidating housing and interior component specifications to fewer resin grades with broader temperature and flame-retardancy envelopes. This concentration is displacing fragmented specialty grade portfolios and forcing resin producers to defend position through integrated color and additive masterbatch capabilities rather than discrete material differentiation.
Asia-Pacific Polycarbonate (PC) Market Segmentation
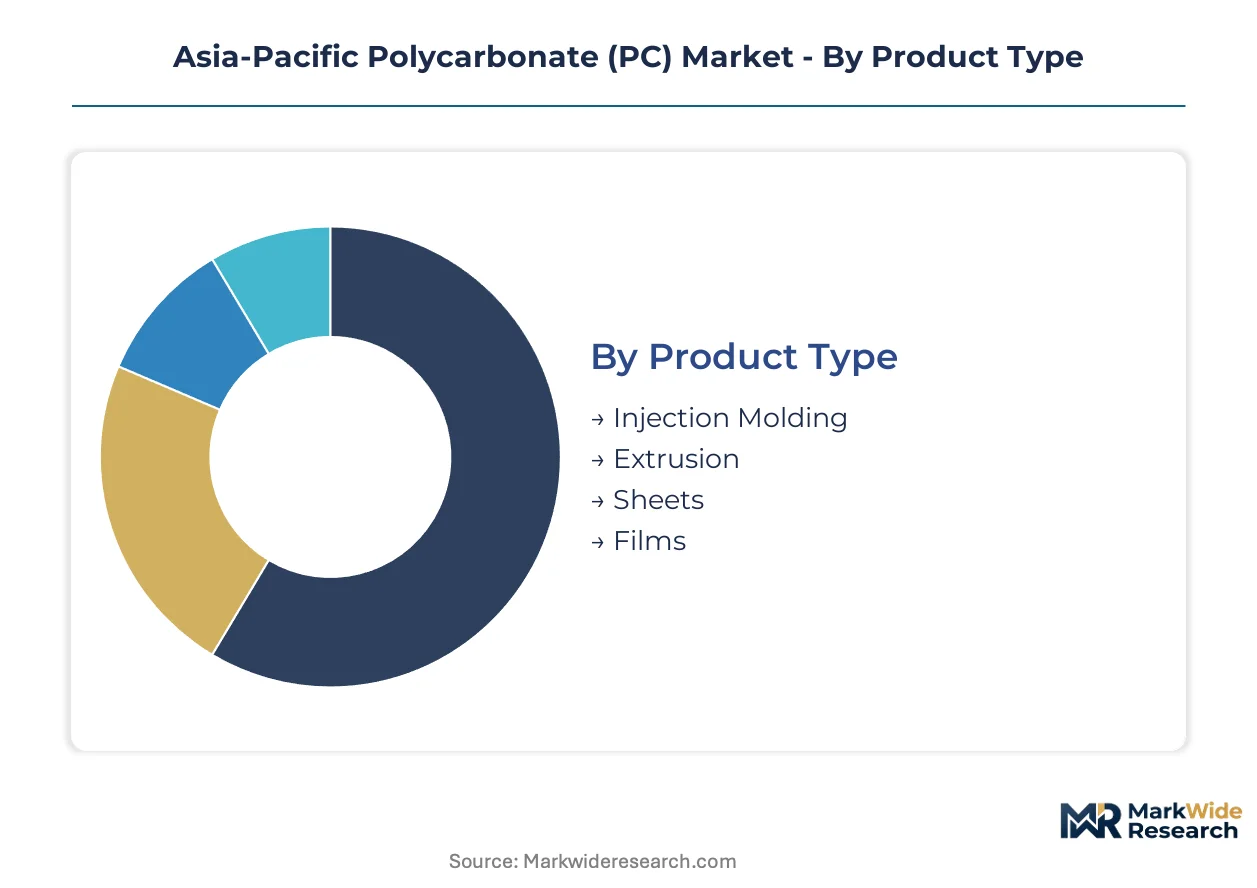
Polycarbonate market segmentation reveals how specification tiers align with regulatory pressure points across the Asia-Pacific region. Each category reflects distinct technical barriers and compliance pathways that reshape supplier positioning.
Product Type:
MIIT flame-retardancy mandates for automotive interiors and METI optical-grade standards create divergent processing requirements across manufacturing methods.
- Injection Molding:Thin-wall precision formulations dominate EV battery housing and smartphone chassis production. Yangtze River Delta molders command premium pricing for halogen-free PC-ABS blends meeting simultaneous GB and JIS thermal cycling protocols.
- Extrusion:Continuous sheet production serves photovoltaic backsheet substitution and safety glazing applications. Eastern China solar module manufacturers are displacing fluoropolymer films with extrusion-grade polycarbonate for cost and supply security reasons.
- Sheets:Multi-wall and solid configurations target construction glazing and architectural applications.
- Films:Optical-grade and protective variants serve display lamination and electronics surface protection.
Established volume favors injection molding; emerging adoption favors extrusion.
End User:
Customer procurement patterns concentrate around electrification mandates and medical device reshoring incentives.
- Automotive:Korean and Chinese EV manufacturers consolidate battery enclosure specifications toward fewer grades with broader temperature envelopes. Phosphorus-based flame retardant systems are displacing legacy brominated formulations under tightening MIIT enforcement.
- Consumer Electronics:Smartphone camera array proliferation concentrates margin pools in low-birefringence optical grades for periscope lens modules. Japanese compounders defend specification premiums through cleanroom finishing infrastructure.
- Construction:China's dual carbon goals and provincial EPR pilots mandate post-consumer content minimums for glazing and insulation applications.
- Medical Devices:South Korea's MFDS biocompatibility frameworks and Japan's PMDA quality protocols concentrate dialysis equipment housing demand within regulated domestic supply chains.
Automotive procurement scales fastest; medical device qualification timelines stretch longest.
Application:
Functional performance requirements stratify across optical precision, impact protection, and barrier properties.
- Optical Lenses:Birefringence control and particulate contamination management demand dedicated reactor trains. Periscope and folded-optic smartphone designs concentrate margin extraction among specialized compounders with cleanroom compounding capability.
- Safety Glasses:Impact resistance and optical clarity specifications serve industrial PPE and consumer eyewear markets.
- Light Fixtures:Diffusion and heat resistance properties target LED housing and architectural illumination.
- Packaging:Barrier and transparency requirements serve food contact and pharmaceutical blister applications.
Optical lens specialization captures margin concentration; packaging volume expands through circular content integration.
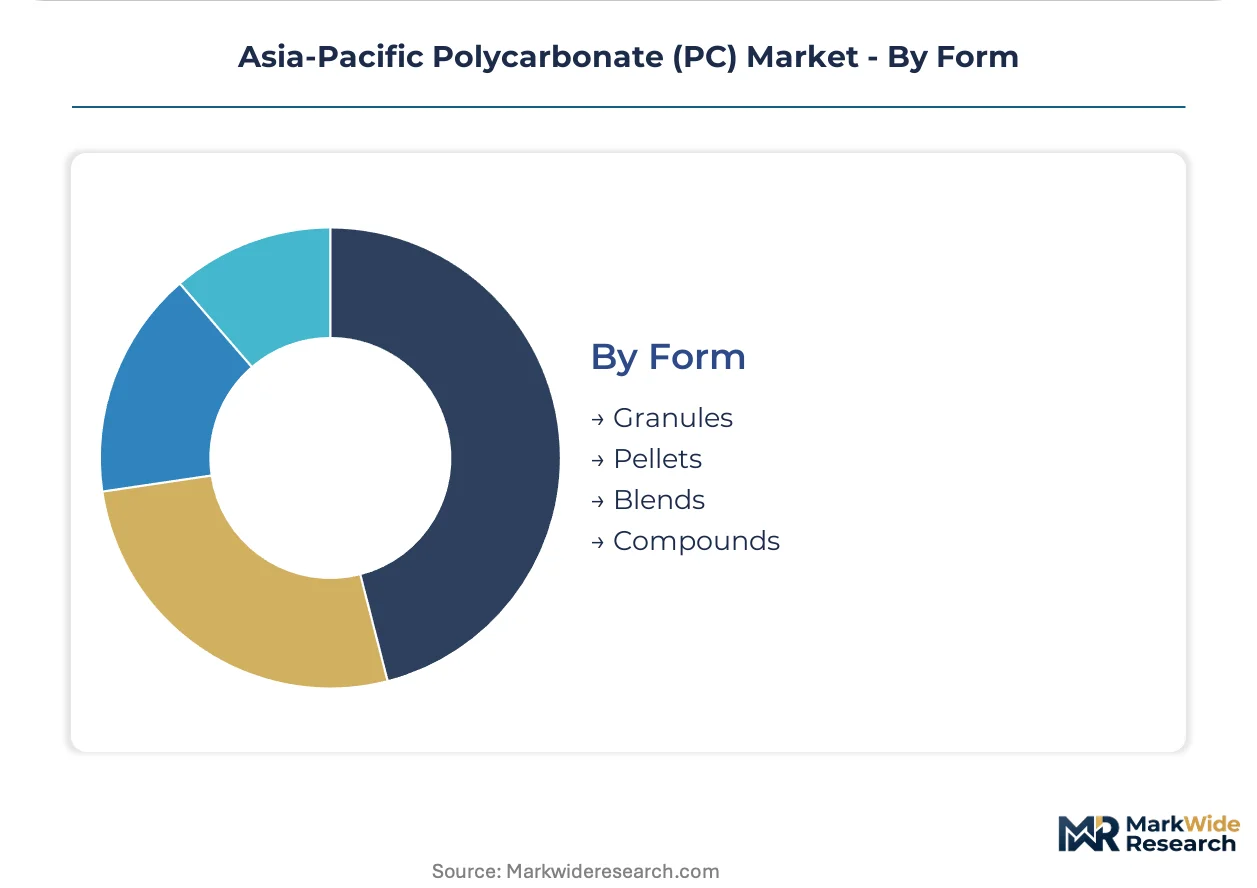
Form:
Supply chain configuration determines how resin producers defend position through integrated capabilities versus discrete material differentiation.
- Granules:Virgin resin in bulk particulate form serves compounders and direct processors with in-house coloring capability.
- Pellets:Standardized extrusion and molding feedstock dominates volume throughput across automotive and electronics molders.
- Blends:PC-ABS and PC-PBT alloy formulations address simultaneous flame-retardancy and impact requirements for EV battery housings.
- Compounds:Pre-colored and additive-loaded grades reduce molder technical service burdens. Korean petrochemical complexes are adding compounding capacity to preserve captive resin flows against ASEAN manufacturing migration.
Pellet commodity volume anchors supply security; compound value-add climbs fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated petrochemical complexes in Yeosu, Ulsan, and Yantai concentrate upstream bisphenol A and PC resin capacity. Regional cracker maintenance cycles align periodically, creating supply vulnerability windows. Demand clusters concentrate in eastern China's Yangtze River Delta and Korea's southern industrial corridor.
China
MIIT flame-retardancy mandates for automotive interiors elevate halogen-free PC-ABS blend specifications. Dual carbon goals and provincial EPR pilots in Zhejiang and Jiangsu mandate post-consumer content minimums by 2027. Yangtze River Delta molders command premium pricing for battery housing and smartphone chassis production.
Japan
METI optical-grade standards govern lens-grade material consistency for smartphone camera arrays. PMDA quality protocols concentrate dialysis equipment housing demand within regulated domestic supply chains. Chubu and Kansai industrial zones maintain cleanroom finishing infrastructure for low-birefringence specialty grades.
South Korea
MFDS biocompatibility frameworks regulate medical device PC for surgical instrument housings. KATS standards coordinate with automotive electrification programs accelerating high-heat grade demand. Yeosu and Ulsan petrochemical complexes sustain captive bisphenol A integration for EV battery enclosure supply.
Vietnam
Electronics assembly relocation from coastal China pulls compounding and sheet extrusion capacity toward ASEAN industrial zones. Preferential trade access under regional agreements redirects specification flows. Northern industrial provinces near Hanoi concentrate emerging mold-to-assembly operations.
Indonesia
Manufacturing migration incentives attract downstream processing investment from Chinese and Korean resin producers. Construction sector expansion drives glazing and insulation applications. Java-based industrial estates develop integrated polymer distribution infrastructure serving domestic and export markets.
Asia-Pacific Polycarbonate (PC) Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates and optical-grade specialists. Korean and Chinese state-affiliated chemical groups anchor upstream capacity through captive phenol-acetone integration. European technology licensors compete on non-phosgene melt process licensing. Strategic moves center on chemical recycling infrastructure deployment and ASEAN manufacturing migration to preserve resin flows.
Among Asia-Pacific-based suppliers, LG Chem, Wanhua Chemical Group, and Covestro AG exemplify divergent competitive positioning. LG Chem represents integrated petrochemical complex operators leveraging captive feedstock security. Wanhua Chemical Group anchors domestic Chinese supply through Yantai operations. Covestro AG occupies a position emphasizing optical-grade specialization for precision applications. These three archetypes illustrate how process technology choices and geographic integration strategies fragment competitive dynamics across the region.
| Leading Market Players |
|---|
| LG Chem |
| Wanhua Chemical Group |
| Covestro AG |
| Chimei Corporation |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| SABIC |
| Formosa Chemicals & Fibre Corporation |
| LOTTE Chemical Corporation |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day resin inventory cycles at Yangtze River Delta compounders signal how captive phenol-acetone integration at Yeosu and Yantai translates into asymmetric pricing power across specification tiers. This lead-time band compresses when regional cracker maintenance aligns, forcing spot market premiums for halogen-free automotive grades.
Pricing Analysis
MIIT flame-retardancy mandates dictate the pricing tier structure across automotive PC-ABS blends, separating certified halogen-free formulations from legacy brominated grades. Three-tier pricing structure across premium optical, certified automotive, and standard extrusion levels reflects birefringence control and GB standard compliance as primary differentiation drivers. Cost compression in construction-grade sheet runs through fluoropolymer substitution dynamics in photovoltaic backsheet applications. Tier-one EV battery molders exhibit lowest price sensitivity due to qualification lock-in, while packaging compounders face margin tightening from post-consumer content mandates.
Supply Chain Analysis
China and South Korea anchor upstream bisphenol A and PC resin production through integrated Yeosu, Ulsan, and Yantai petrochemical complexes. Feedstock flows draw from captive phenol-acetone streams, with phosgene and non-phosgene process routes creating technology-dependent supply moats. Single-source vulnerability concentrates around optical-grade reactor trains dedicated to low-birefringence specifications. Distribution runs through Yangtze River Delta compounding hubs serving EV and electronics OEMs, with emerging ASEAN extrusion capacity capturing electronics assembly migration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific polycarbonate sits in early-cycle expansion as automotive electrification programs across China, Japan, and South Korea accelerate specification consolidation for high-heat, flame-retardant grades.
For Market Incumbents: Fortify captive bisphenol A integration through maintenance cycle coordination and halogen-free formulation certification investments. Polyamide substitution in EV power electronics above 150°C represents a material displacement threat requiring phosphorus-based flame retardant R&D acceleration. Backward integration into chemical recycling infrastructure preserves resin flows against extended producer responsibility mandates. For New Entrants and Emerging Players: Technical service gaps in halogen-free formulation transitions present entry points for compounders with JIS-GB dual certification capabilities. Indonesia and Vietnam manufacturing migration offers the most penetrable geography, with northern Vietnamese industrial zones near Hanoi concentrating mold-to-assembly demand. A go-to-market angle anchored in regional EPR compliance and post-consumer content integration captures provincial pilot program procurement. For Investors and Strategic Acquirers: Long-term, this sits as a circularity infrastructure play because chemical recycling and non-phosgene melt process investments determine competitive viability under China's dual carbon trajectory. Acquisition targets with cleanroom optical-grade finishing capability and ASEAN extrusion footprint command structural scarcity premiums. The signal to watch is provincial EPR pilot enforcement timelines in Zhejiang and Jiangsu mandating post-consumer content floors.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Phosgene Melt Process Capacity Addition | Eliminates chlorine handling and enables post-consumer feedstock integration under MEE enforcement. |
| Chemical Recycling Infrastructure Deployment | Captures first-mover advantage in Zhejiang and Jiangsu provincial EPR pilot programs. |
| Halogen-Free Formulation Certification Investment | Secures qualification for MIIT GB standard automotive battery enclosure specifications. |
| ASEAN Compounding and Extrusion Expansion | Preserves resin flows as electronics assembly relocates to Vietnam and Indonesia industrial zones. |
| Optical-Grade Cleanroom Finishing Capability | Defends margin concentration in smartphone periscope lens module specifications. |
Research Methodology
Operator-level perspectives from plant managers at integrated petrochemical complexes, procurement leads at Korean and Chinese EV battery molders, distribution channel partners in the Yangtze River Delta, and technical R&D directors at optical-grade compounders anchored the qualitative base. Secondary validation drew from MIIT GB standard filings, METI JIS documentation, customs and trade data tracking bisphenol A flows, and SEC disclosures from listed chemical conglomerates. Bottom-up volume estimates triangulated with top-down macroeconomic drivers across the analysis window.
Sensitivity analysis tested forecast robustness against alternative scenarios for automotive electrification penetration and EPR enforcement intensity. Segmentation dimensions modeled include product type, end-use industry, application function, and regional production hub configuration. CAGRs derived from historical trajectory analysis and adoption curve positioning, with EV battery housing content per vehicle and smartphone camera array proliferation serving as key demand-side inputs.
Material uncertainties — regulatory acceleration in dual carbon enforcement, polyamide substitution rates in thermal management, and cracker maintenance cycle alignment — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding specification consolidation timelines and circular infrastructure deployment. Recalibration cycles align with material shifts in MIIT mandate enforcement and provincial EPR pilot expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Polyimide and Imide Polymers Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Cyclic Olefin Polymers (COP) Polymer Syringes Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Vinyl Acetate Emulsion Polymers Market