
 Rubber Bulb Seals Market | 2026-2036
Rubber Bulb Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Bulb Seals Market Analysis
Aftermarket repair shops is collapsing as a buyer archetype as fleet operators and Tier-1 automotive suppliers consolidate procurement under long-term OEM contracts. Exactseal Inc. leverages its custom extrusion capabilities to serve aerospace certification requirements. Hebei Shida Seal Group Co., Ltd. anchors high-volume EPDM production for Asian automotive platforms. Vip Rubber and Plastic Company differentiates through silicone formulations targeting HVAC and electrical insulation segments.
Rubber bulb seals are extruded elastomeric profiles featuring a hollow bulb cross-section designed to compress and rebound, creating airtight and watertight barriers; EPDM variants withstand temperature ranges from -50°C to 150°C while maintaining ozone resistance. Standard bulb seals dominate volume sales across automotive door and window applications where design templates repeat across model lines. Custom bulb seals capture elevated margins in aerospace and specialized industrial equipment where geometry tolerances tighten and batch sizes shrink. Silicone material grades are gaining fastest in electrical and HVAC segments due to flame-retardant and thermal stability requirements.
FDA regulations govern silicone bulb seals deployed in food-processing equipment, while EPA emission standards push automotive OEMs toward denser sealing architectures that reduce cabin air leakage and improve HVAC efficiency. NHTSA door retention and side-impact protocols directly specify compression-set limits that EPDM and silicone compounds must satisfy for homologation. Procurement teams must weigh material certification lead times against platform-specific durability testing as regulatory scope broadens from safety into lifecycle sustainability metrics.
Market Dynamics
Automotive electrification is compressing sealing specification cycles as OEMs redesign door and trunk architectures for battery-electric platforms, forcing EPDM compounders to validate formulations against tighter compression-set tolerances.
Growth Catalysts
- NHTSA Door Retention Protocols:Side-impact safety mandates specify maximum compression-set degradation thresholds, compelling Tier-1 suppliers to upgrade EPDM grades for homologation.
- Electric Vehicle Platform Expansion:Battery pack thermal management requires bulb seals with expanded temperature resilience, pulling silicone and advanced EPDM formulations into door sealing systems.
- REACH SVHC Restrictions:European chemical hazard classifications are phasing out legacy plasticizers, redirecting formulation investment toward bio-based process oils and peroxide-cured compounds.
Market Restraints
- EPDM Feedstock Volatility:Ethylene and propylene monomer prices track naphtha and natural gas liquids, compressing compounder margins during upstream petrochemical cycles.
- German Supply Chain Concentration:Bosch and Continental anchor advanced extrusion capacity in Baden-Württemberg and Lower Saxony, creating single-source vulnerability for specialized automotive grades.
- Silicone Substitution Ceiling:Per-unit silicone costs exceed EPDM by factors of three to five, limiting penetration in high-volume passenger vehicle door seals despite superior thermal performance.
Strategic Opportunities
- India Automotive Manufacturing:PLI scheme incentives for electric vehicle production are drawing sealing system suppliers to Tamil Nadu and Gujarat assembly corridors.
- HVAC Electrification:Heat pump deployment in residential and commercial buildings is expanding specification of flame-retardant silicone bulb seals for refrigerant line insulation.
- CSRD Lifecycle Reporting:European corporate sustainability disclosure rules are creating first-mover advantage for compounders with ISO 14040-compliant environmental product declarations.
Industry Challenges
- Automotive Homologation Timelines:OEM platform validation cycles extend eighteen to thirty-six months, locking working capital in compound development before volume orders materialize.
- Extrusion Die Engineering Shortage:Precision bulb geometry tolerances below 0.1 millimeter require specialized tool-and-die expertise concentrated among aging workforces in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Bulb Seals Market |
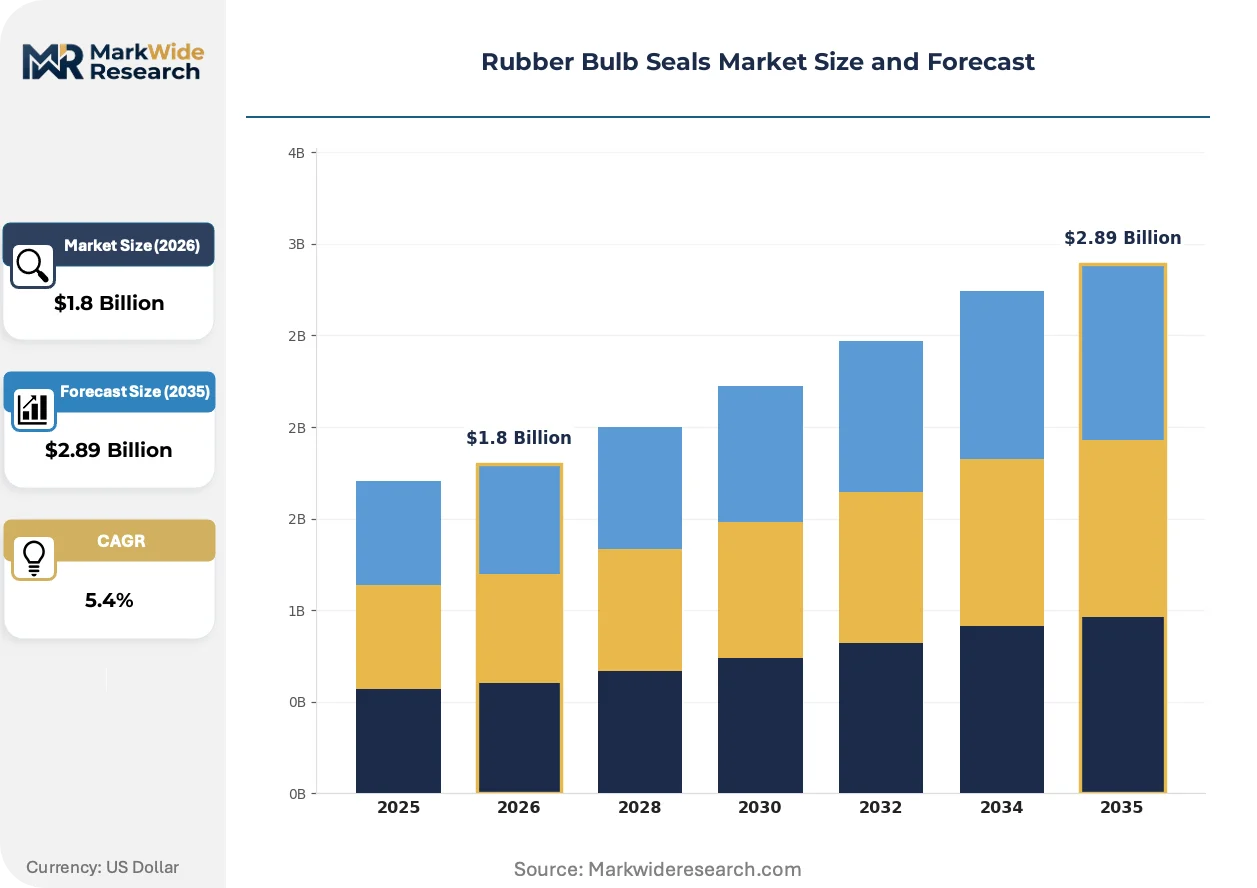
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bulb Seals, Custom Bulb Seals, Expandable Bulb Seals, Self-adhesive Bulb Seals Material: NBR, EPDM, PVC, Silicone Application: Aerospace, Automotive, HVAC, Electrical End User: Manufacturers, Repair Shops, Distributors, Contractors |
| Companies Covered | Exactseal Inc., Vertex, Inc., Uni-Grip Inc., Netherland Rubber Company, Hebei Shida Seal Group Co., Ltd., Simolex Rubber Corporation, RPM Industrial Rubber Parts Inc., Vip Rubber and Plastic Company, Accurate Rubber Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Bulb Seals Market Emerging Trajectories
Material science advances and regulatory disclosure requirements are converging to reshape compound formulation priorities, extrusion process control, and buyer-supplier contracting structures across automotive and industrial segments.
Multi-layer co-extrusion technology is miniaturizing. This process fuses rigid carrier substrates with compliant bulb sections in single-pass operations, eliminating assembly steps. Tier-1 automotive suppliers in Germany and Japan are adopting these lines for electric vehicle door seal programs. The technology is miniaturizing equipment footprints while tightening wall-thickness tolerances to 50 microns, enabling weight reduction targets.
EPA fuel-efficiency standards are tightening cabin air leakage specifications to improve HVAC load efficiency. Automotive OEMs respond by specifying denser bulb seal architectures with increased compression force. This regulatory pressure most acutely affects mid-size sedan and crossover platforms assembled in the United States, where fleet-average compliance penalties escalate.
Long-term OEM contracting is displacing spot aftermarket procurement. Fleet operators and vehicle manufacturers are consolidating sealing system purchases under five-to-seven-year platform agreements, collapsing the independent repair shop channel. This concentration is most visible in Germany, where Volkswagen Group and Mercedes-Benz have centralized sealing procurement under direct Tier-1 nominations.
Rubber Bulb Seals Market Segmentation
Rubber bulb seal procurement diverges sharply across specification tiers, with automotive OEMs demanding validated EPDM grades under NHTSA protocols while industrial buyers prioritize silicone for thermal resilience. Material selection cascades through application requirements, creating distinct margin pools and certification burdens.
Product Type:
EPA fuel-efficiency standards and NHTSA safety mandates impose divergent testing burdens across specification tiers, compressing aftermarket flexibility while elevating OEM-grade validation requirements.
- Standard Bulb Seals:Extruded EPDM profiles with fixed cross-sectional geometries repeat across high-volume automotive door and window lines. Procurement concentrates at Volkswagen Group and Mercedes-Benz centralized Tier-1 nominations in Germany, where five-to-seven-year platform contracts displace spot purchasing.
- Custom Bulb Seals:Application-specific geometries with sub-0.1 millimeter tolerances serve aerospace airframe sealing and specialized industrial equipment. Exactseal Inc. leverages custom extrusion capabilities for FAA certification requirements, capturing elevated margins where batch sizes shrink below ten thousand units.
- Expandable Bulb Seals:Hollow profiles with internal expansion chambers accommodate installation variability in retrofit construction applications.
- Self-adhesive Bulb Seals:Pressure-sensitive backing layers eliminate mechanical fastening in HVAC ductwork and electrical enclosure retrofits.
Established volume favors Standard Bulb Seals; emerging adoption favors Custom Bulb Seals.
Material:
Cost tiers stratify sharply, with per-unit silicone multiples of three to five over EPDM constraining penetration despite superior thermal performance.
- EPDM:Ethylene-propylene-diene monomer compounds dominate automotive door and trunk sealing with -50°C to 150°C operational windows and ozone resistance. REACH SVHC restrictions are phasing out legacy plasticizers, redirecting Bosch and Continental formulation investment toward peroxide-cured grades in Baden-Württemberg facilities.
- Silicone:Polysiloxane formulations with flame-retardant additives capture HVAC electrification and electrical insulation segments. Vip Rubber and Plastic Company differentiates through thermal stability grades specified for heat pump refrigerant line sealing.
- NBR:Nitrile butadiene rubber offers fuel and oil resistance in limited automotive underhood applications.
- PVC:Polyvinyl chloride compounds serve cost-constrained construction and general industrial sealing with reduced temperature resilience.
EPDM commands the deepest procurement volumes; silicone climbs the fastest on electrification tailwinds.
Application:
Customer maturity varies dramatically, with automotive homologation cycles of eighteen to thirty-six months locking working capital against aerospace prototype-to-production transitions.
- Automotive:Battery-electric platform redesigns compress sealing specification cycles, forcing EPDM compounders to validate against tighter compression-set tolerances for door and trunk architectures. EPA cabin air leakage specifications tighten HVAC load efficiency requirements, pulling denser bulb seal architectures into mid-size sedan and crossover platforms.
- Aerospace:FAA certification requirements and airframe-specific geometry tolerances concentrate demand at Exactseal Inc. and specialized extrusion houses with AS9100 quality systems.
- HVAC:Residential and commercial heat pump deployment expands flame-retardant silicone specification for refrigerant line insulation and ductwork sealing.
- Electrical:Enclosure sealing and cable penetration applications specify silicone grades for thermal stability and dielectric performance.
Automotive absorbs the largest absolute volumes; HVAC gains share fastest on building electrification mandates.
End User:
Supply concentration reshapes channel economics, with long-term OEM contracting collapsing independent repair shop relevance.
- Manufacturers:Tier-1 automotive suppliers and airframe OEMs consolidate procurement under direct nomination agreements, centralizing specification authority at Bosch, Continental, and Volkswagen Group in Germany.
- Distributors:Industrial supply houses bridge fragmented contractor demand for construction and HVAC retrofit applications.
- Repair Shops:Aftermarket channel collapsing as fleet operators migrate to captive maintenance programs under OEM service contracts.
- Contractors:Installation-focused buyers prioritize self-adhesive and expandable formats for field adaptability.
Manufacturer direct procurement dominates revenue concentration; distributor channels retain construction segment relevance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export precision EPDM grades to North American automotive assembly plants, while Chinese manufacturers supply high-volume standard seals across Southeast Asian industrial corridors.
United States
EPA fuel-efficiency standards and NHTSA door retention protocols tighten cabin air leakage specifications for mid-size sedans and crossovers. The IRA manufacturing incentives draw sealing system suppliers to battery-electric vehicle assembly corridors in Michigan and Tennessee. Detroit anchors Tier-1 procurement consolidation under long-term OEM contracts.
Germany
REACH SVHC restrictions phase out legacy plasticizers in automotive EPDM formulations. Bosch and Continental anchor advanced extrusion capacity in Baden-Württemberg and Lower Saxony, creating concentrated supply chains for Volkswagen Group and Mercedes-Benz centralized nominations. Stuttgart and Wolfsburg dominate platform-specific sealing development.
China
MIIT dual carbon goals accelerate heat pump deployment in residential buildings, expanding silicone specification for HVAC refrigerant line insulation. Yangtze River Delta and Pearl River Delta clusters house high-volume EPDM compounders serving domestic electric vehicle platforms. Shanghai and Shenzhen anchor export-oriented standard seal production.
India
PLI scheme incentives for electric vehicle production draw sealing system suppliers to Tamil Nadu and Gujarat assembly corridors. BIS certification requirements tighten material specification for automotive homologation. Chennai and Ahmedabad concentrate new extrusion capacity for Maruti Suzuki and Tata Motors platforms.
Japan
METI building electrification mandates expand flame-retardant silicone demand for heat pump ductwork sealing. JIS standards govern compression-set tolerances for automotive door seal applications. Nagoya and Osaka anchor precision extrusion expertise serving Toyota and Honda platform specifications.
Rubber Bulb Seals Market Vendor Landscape
Player mix skews toward mid-cap specialists with captive compound formulation capabilities. Market structure fragments across regional supply clusters rather than consolidating under multinational champions. Three archetypes dominate: precision aerospace certifiers, high-volume Asian compounders, and North American custom extrusion houses. Competitive moves center on backward integration into EPDM compounding and geographic expansion into Indian automotive corridors.
Within the precision-certification tier, Exactseal Inc. occupies a position exemplifying aerospace-grade custom extrusion capabilities. Hebei Shida Seal Group Co., Ltd. and Vip Rubber and Plastic Company represent scale-oriented archetypes serving diverging material segments—EPDM automotive volumes and silicone thermal applications respectively. These three anchors illustrate the geographic and technological stratification binding competitive positioning to regional demand clusters and regulatory certification requirements.
| Leading Market Players |
|---|
| Exactseal Inc. |
| Vertex, Inc. |
| Uni-Grip Inc. |
| Netherland Rubber Company |
| Hebei Shida Seal Group Co., Ltd. |
| Simolex Rubber Corporation |
| RPM Industrial Rubber Parts Inc. |
| Vip Rubber and Plastic Company |
| Accurate Rubber Corporation |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-thirty-six-month automotive homologation cycles lock working capital in compound development before volume pricing power materializes, concentrating margin leverage with German EPDM compounders who anchor precision extrusion capacity. This lead-time compression cascades through supplier tiers, forcing Tier-1 automotive buyers into long-term platform contracts that collapse spot-market flexibility and elevate certification-grade premiums.
Pricing Analysis
Current-generation peroxide-cured EPDM formulations command substantial premiums over legacy sulfur-cured grades, while next-generation bio-based process oil variants remain in pilot-scale pricing. Three-tier pricing structure across aerospace-certified custom extrusion, automotive OEM-grade standard seals, and construction-grade PVC alternatives separates Exactseal Inc. FAA-tier margins from high-volume Asian commodity supply. Cost compression in standard automotive EPDM is intensifying because REACH SVHC plasticizer phase-outs force reformulation investment. Fleet operators under long-term OEM service contracts exhibit lowest price sensitivity; independent repair shops facing channel collapse show acute elasticity.
Supply Chain Analysis
Strait of Malacca transit risk underwrites raw material security calculations for Asian EPDM compounders serving European automotive assembly. German precision extrusion capacity in Baden-Württemberg and Lower Saxony, Chinese high-volume compound production in Yangtze River Delta clusters, and Japanese tool-and-die expertise in Nagoya collectively anchor global supply. Ethylene and propylene monomer feedstocks, specialty peroxide curatives, and aerospace-grade silicone resins constitute critical input dependencies. Single-source vulnerability concentrates in German precision extrusion for sub-0.1 millimeter tolerance applications. Distribution runs through Tier-1 automotive supplier nominations and industrial distributor networks bridging fragmented HVAC retrofit demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision extrusion expertise for aerospace certification and automotive homologation has contracted to aging workforces in Germany and Japan, creating acute capability scarcity that reshapes competitive entry economics. This skill concentration elevates acquisition premiums for AS9100-qualified facilities and extends platform-lock advantages for incumbents with validated compound libraries.
For Market Incumbents: Consolidate backward integration into captive EPDM compounding to defend margin position against ethylene-propylene feedstock volatility and REACH SVHC reformulation costs. Expand peroxide-cured capacity in Baden-Württemberg to capture Volkswagen Group and Mercedes-Benz centralized nomination volume. Lock five-to-seven-year platform agreements before Indian PLI scheme incentives mature local supply alternatives. For New Entrants and Emerging Players: Anchor in Tamil Nadu and Gujarat automotive corridors to exploit PLI scheme electric vehicle assembly pull and underdeveloped local sealing system supply. Target HVAC electrification segments specifying flame-retardant silicone for heat pump refrigerant line insulation, where Vip Rubber and Plastic Company differentiation models prove replicable. Pursue BIS certification early to compress Maruti Suzuki and Tata Motors homologation timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized aerospace extrusion capabilities stranded outside core divisions. Long-term viability hinges on compound formulation IP and regulatory certification moats rather than capacity scale alone. Watch for CSRD lifecycle reporting mandates accelerating ISO 14040 environmental product declaration adoption as inflection signal for premium-tier pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EPDM Compounding | Captive supply of peroxide-cured grades insulates Bosch and Continental from naphtha price cycles. |
| Aerospace Certification Investment | AS9100 quality systems unlock Exactseal Inc. elevated-margin FAA-tier contract access. |
| Geographic Expansion into Indian Automotive Corridors | PLI scheme incentives in Tamil Nadu draw sealing suppliers toward Maruti Suzuki platform volume. |
| Multi-Layer Co-Extrusion Technology Adoption | German Tier-1 suppliers deploy single-pass rigid-carrier fusion for electric vehicle weight targets. |
| CSRD-Compliant Lifecycle Reporting | ISO 14040 environmental product declarations create first-mover advantage in European OEM procurement. |
Methodological Framework
Initial hypotheses were tested against primary input from Tier-1 automotive procurement managers, aerospace quality systems directors, HVAC equipment specification engineers, and EPDM compound R&D leads, then refined against secondary validation. Customs trade data for ethylene-propylene rubber imports, SEC filings from sealing system suppliers, IHS Markit vehicle production databases, and REACH SVHC regulatory filings furnished quantitative benchmarks. Bottom-up segment sizing triangulated against top-down macroeconomic elasticity assumptions.
Variance decomposition across material grade, application thermal requirements, end-user procurement concentration, and regional regulatory stringency shaped the analytical framework over the projection horizon. CAGRs derived from segment-level elasticity modeling against automotive platform cycle timing and building electrification mandate trajectories. Electric vehicle content-per-vehicle sealing architecture shifts and heat pump deployment curves constituted industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable petrochemical feedstock pricing and unchanged REACH implementation timelines; material deviation would warrant model refresh. Forecasts embed assumptions regarding NHTSA protocol continuity and MIIT dual carbon goal persistence. Practitioners should keep alternative scenarios live as EPDM feedstock volatility and German supply chain concentration evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Rubber Process Oil Market
Rubber
Rubber Plated Hose Market
Rubber
Rubber Seal Plugs Market
Rubber
Metallurgical Rubber Roller Market
Rubber
Rubber Wear Liners Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Industrial Rubber Market
Rubber
Rubber Roller Cleaner Market
Rubber
Rubber Splicing Tape Market
Rubber
Flexible Rubber Sheets Market
Rubber
Polyacrylate Rubber Market
Rubber
Global Rubber Coated Fabrics Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Solution Styrene Butadiene Rubber (S-SBR) Market
Rubber
Isobutylene Market
Rubber
Abrasion-Resistant Rubber Pipe Market