
 Ethylene Copolymer Market | 2026-2036
Ethylene Copolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylene Copolymer Market Analysis
Automotive interior applications is decoupling from traditional polypropylene dominance as OEMs specify softer-touch dash panels and acoustic-dampening layers. Dow leverages its Engage portfolio to anchor position in TPO-based instrument clusters. Exxon Mobil Corporation sustains supply relationships with tier-one seating suppliers through its Vistamaxx propylene-ethylene elastomer range. SABIC competes on cost-optimized reactor-grade copolymers serving Middle Eastern vehicle assembly plants.
Ethylene copolymers are thermoplastic resins synthesized through coordination polymerization of ethylene with alpha-olefin comonomers such as butene, hexene, or octene, yielding controlled short-chain branching densities that tune crystallinity, melt flow index, and impact resistance for film extrusion, injection molding, and adhesive formulations. Ethylene vinyl acetate commands expanding margin pools in photovoltaic encapsulant films and hot-melt adhesives where optical clarity and low-temperature flexibility justify premium positioning. High-density polyethylene copolymer grades dominate blow-molded fuel tank and industrial container applications where ESCR performance and stiffness requirements are non-negotiable. Ethylene butylene copolymer occupies a narrower but defensible niche in medical tubing and soft-touch overmolding where Shore A flexibility and USP Class VI compliance intersect.
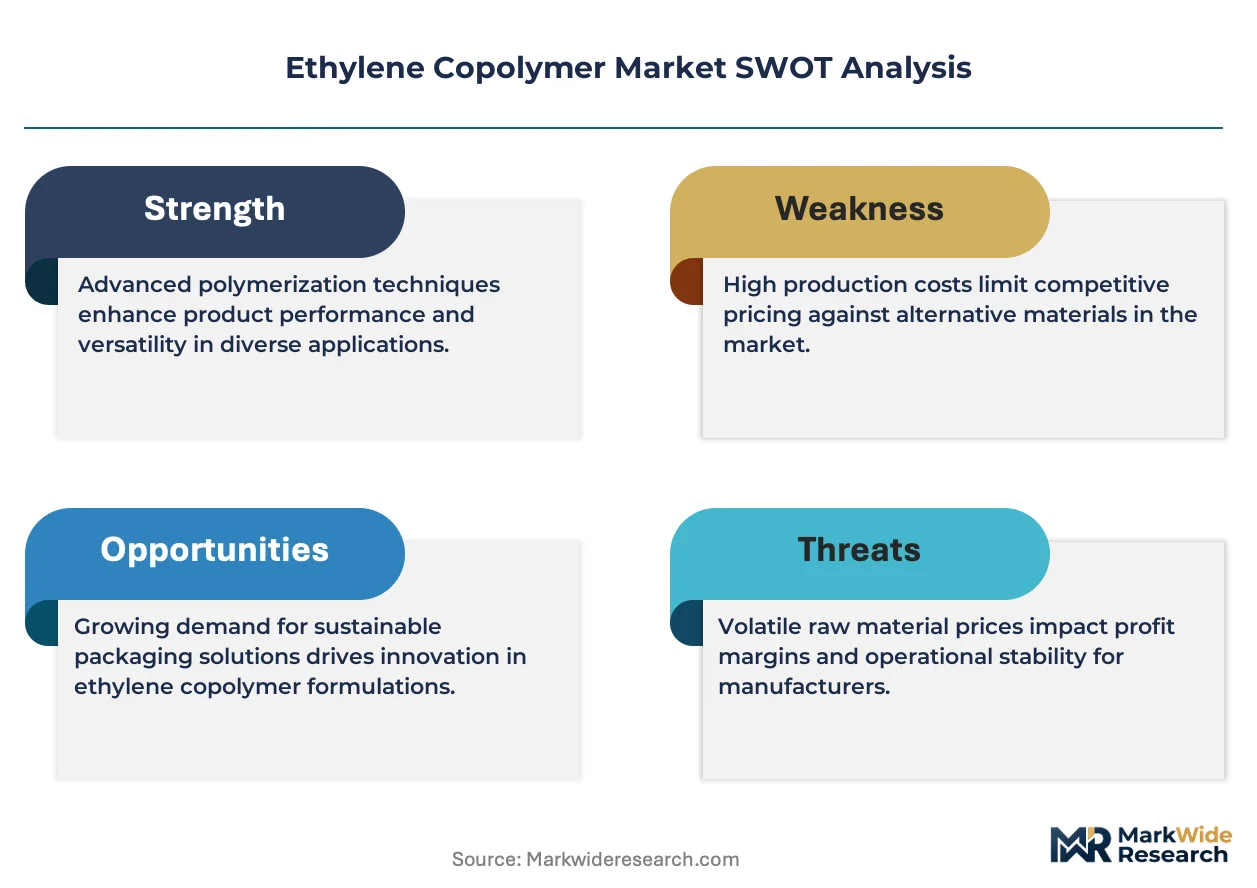
FDA food-contact notifications and EPA TSCA Section 5 premanufacture review govern new copolymer chemistries entering U.S. packaging and consumer goods channels, while REACH Annex XVII restrictions on phthalate plasticizers indirectly steer formulators toward non-migrating ethylene-based alternatives. ISO 9001 and IATF 16949 certifications function as baseline qualifiers for automotive and medical offtake, with audit scope expanding to carbon footprint disclosure under emerging CSRD-aligned supplier questionnaires. Stakeholders must monitor comonomer feedstock cost spreads and regulatory divergence between U.S. and EU migration test protocols when allocating R&D budgets and regional capacity.
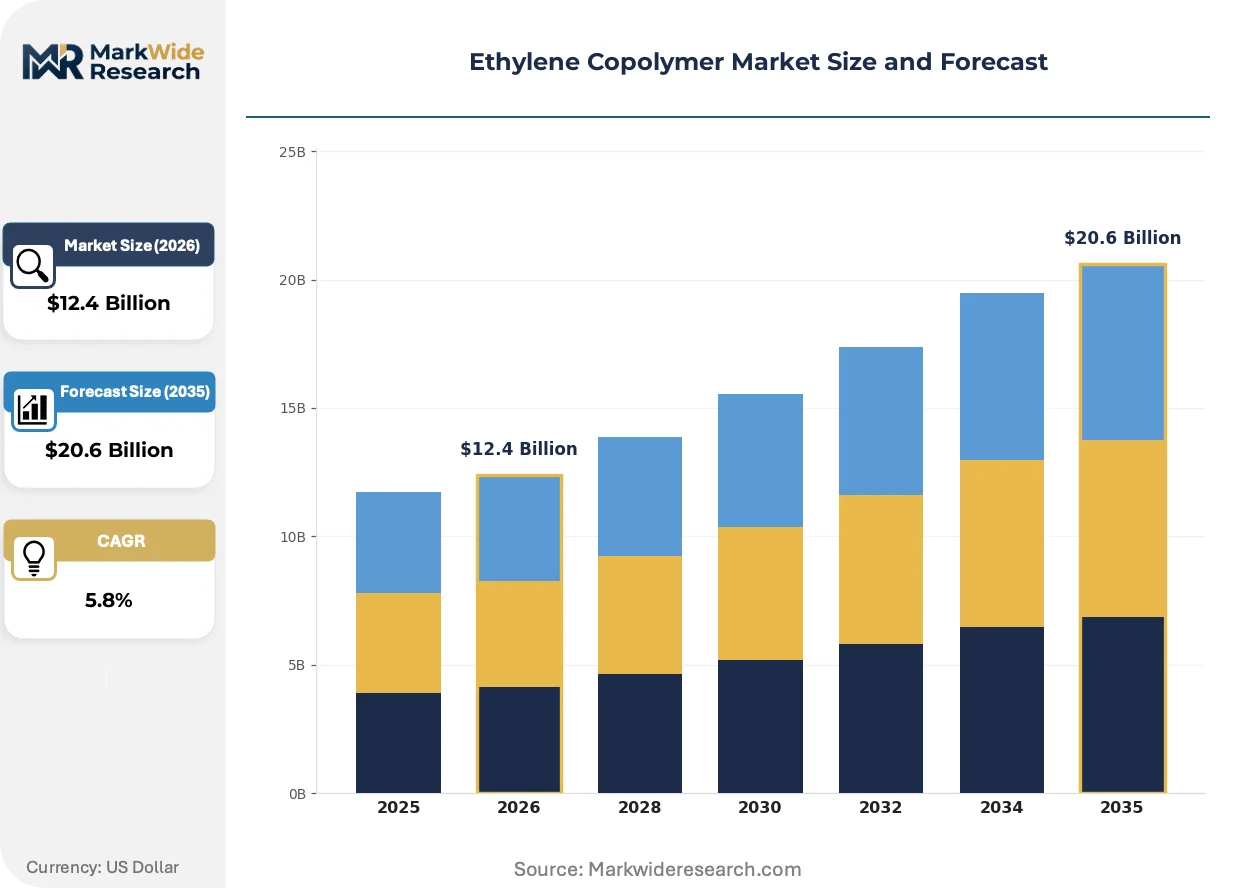
Market Dynamics
Reformulation cycles are compressing as REACH migration limits and FDA food-contact standards tighten simultaneously, forcing resin producers to validate new copolymer grades against divergent test protocols before commercial rollout.
Growth Catalysts
- Photovoltaic encapsulant demand:Solar module manufacturers in China specify ethylene vinyl acetate for optical clarity and UV resistance, drawing capacity additions from SABIC and Borealis.
- Automotive interior specification:OEMs specify softer-touch TPO-based instrument clusters and acoustic-dampening layers, displacing traditional polypropylene in dash panels.
- REACH Annex XVII compliance:Phthalate plasticizer restrictions steer formulators toward non-migrating ethylene-based alternatives in European medical tubing and flexible packaging.
Market Restraints
- Alpha-olefin feedstock volatility:Butene, hexene, and octene comonomer cost spreads fluctuate with naphtha and ethylene pricing, compressing margin predictability for reactor-grade copolymer producers.
- Supply concentration in GCC states:Cost-optimized reactor-grade output from Middle Eastern crackers creates price floor pressure for European and North American producers lacking integrated feedstock access.
- High-density polyethylene substitution:Blow-molded fuel tank applications favor HDPE copolymer grades where ESCR performance requirements remain non-negotiable, limiting ethylene copolymer penetration.
Strategic Opportunities
- CSRD-aligned supplier qualification:Emerging carbon footprint disclosure requirements under EU corporate sustainability reporting create first-mover advantage for producers with ISO 14064-verified emissions data.
- Hot-melt adhesive formulation:Ethylene vinyl acetate grades command premium positioning in bookbinding and woodworking adhesives where low-temperature flexibility and optical clarity justify price differentiation.
- Medical tubing overmolding:Ethylene butylene copolymer occupies a defensible niche where Shore A flexibility and USP Class VI compliance intersect, with demand concentrating in German and Swiss device manufacturing clusters.
Industry Challenges
- IATF 16949 certification timelines:Automotive offtake requires 12-18 month audit cycles for new copolymer grades, delaying revenue recognition from TPO instrument cluster specifications.
- Coordination polymerization expertise:Shortage of catalyst chemists and process engineers with metallocene single-site reactor experience constrains R&D throughput for custom comonomer ratios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylene Copolymer Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Density Polyethylene, High-Density Polyethylene, Ethylene Vinyl Acetate, Ethylene Butylene Copolymer Application: Adhesives, Packaging, Automotive Parts, Consumer Goods End User: Construction, Electronics, Pharmaceuticals, Agriculture Form: Granules, Films, Sheets, Liquids |
| Companies Covered | BASF SE, Dow, Exxon Mobil Corporation, DuPont, SABIC, INEOS, Borealis AG, Arkema, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylene Copolymer Market Emerging Trajectories
Metallocene catalyst advances and post-reactor modification techniques are rewriting performance benchmarks for seal integrity and downgauging, while regulatory divergence between EU and US migration protocols forces parallel validation tracks.
Single-site metallocene catalyst systems are rewriting the economics of film extrusion by enabling precise short-chain branching control. Packaging film converters specify these grades for downgauging performance without sacrificing seal integrity. The technology is compressing material usage rates per thousand square meters of finished film.
REACH Annex XVII restrictions on phthalate plasticizers are accelerating reformulation cycles across European medical and consumer goods channels. Industrial consequence includes mandatory migration testing under EN 1186 protocols for all new copolymer chemistries. Flexible packaging producers serving German retail chains respond by pre-qualifying non-migrating ethylene-based alternatives ahead of enforcement deadlines.
Specification-driven procurement now dominates solar encapsulant purchasing, with module manufacturers requiring batch-level optical clarity certification and UV aging test data. Direct mill relationships are displacing distributor intermediaries for ethylene vinyl acetate volumes above threshold tonnages. This pattern concentrates in Chinese photovoltaic manufacturing clusters where vertical module integrators enforce supplier consolidation.
Ethylene Copolymer Market Segmentation
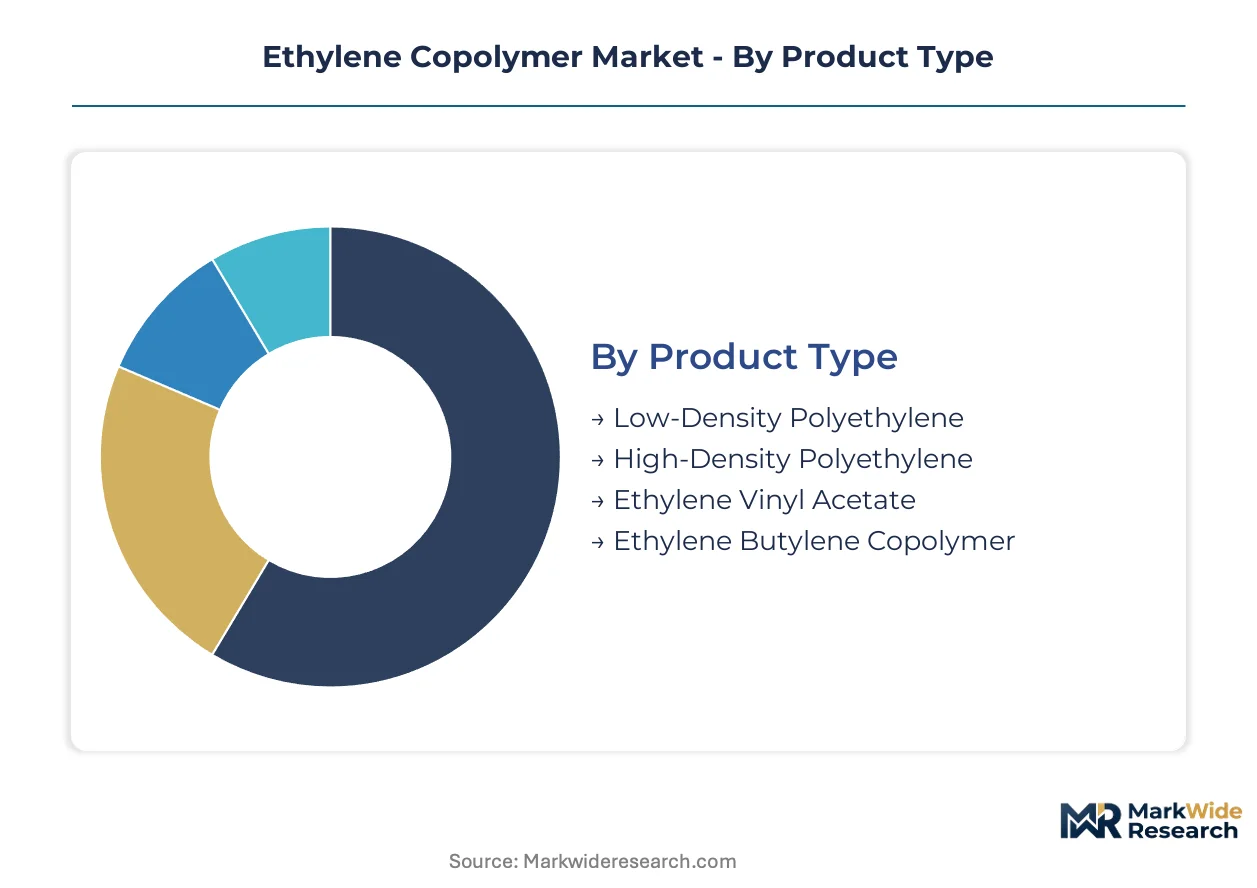
Segmentation in ethylene copolymers reveals divergent capital requirements and margin structures across product chemistries and conversion formats. Reactor configuration, comonomer handling systems, and downstream compounding infrastructure create distinct investment thresholds that shape competitive entry.
Product Type:
High-pressure tubular reactors demand the steepest upfront investment, while solution-phase metallocene systems occupy the mid-tier and gas-phase fluidized bed units offer the lowest barrier to entry.
- Low-Density Polyethylene:Produced via high-pressure free-radical polymerization in tubular or autoclave reactors, yielding long-chain branching that enhances melt strength for blown film extrusion. Chinese flexible packaging converters in Zhejiang and Jiangsu provinces absorb the majority of spot market volumes, driven by downgauging mandates from German retail chains.
- Ethylene Vinyl Acetate:Incorporates 5-40% vinyl acetate comonomer via high-pressure copolymerization, delivering optical clarity and low-temperature flexibility. Photovoltaic encapsulant demand from LONGi and JinkoSolar manufacturing clusters in Hefei and Xi'an is compressing lead times for 28-33% VA grades.
- High-Density Polyethylene:Gas-phase or slurry-phase polymerization with controlled short-chain branching for stiffness and ESCR performance. Blow-molded fuel tank specifications from Stellantis and Toyota anchor demand.
- Ethylene Butylene Copolymer:Single-site catalysis enables precise comonomer distribution for Shore A flexibility. Medical tubing applications in Swiss device manufacturing clusters require USP Class VI validation.
Low-Density Polyethylene absorbs the bulk of installed capacity; Ethylene Vinyl Acetate is expanding most quickly.
Application:
Volume concentration and margin profiles diverge sharply across application segments, with specification-driven automotive and medical channels commanding premium positioning over commodity packaging.
- Packaging:Multilayer coextrusion films for meat and dairy applications dominate tonnage offtake. German retail compliance with EFSA migration limits is accelerating reformulation toward non-phthalate sealant layers.
- Automotive Parts:TPO-based instrument clusters and acoustic-dampening layers displace polypropylene in dash panels. IATF 16949 certification cycles extend 12-18 months for new resin qualifications.
- Adhesives:Hot-melt formulations for bookbinding and woodworking command premium positioning where low-temperature flexibility justifies price differentiation.
- Consumer Goods:Soft-touch overmolding for personal care packaging competes on Shore A tactile performance.
Packaging channels concentrate the highest absolute volumes; Automotive Parts generates the steepest margin expansion.
End User:
Regulatory stringency and qualification timelines create distinct customer archetypes, with pharmaceutical and electronics segments imposing the most rigorous audit requirements.
- Construction:Geomembrane and vapor barrier applications specify HDPE copolymer grades for tensile strength and UV resistance. German infrastructure stimulus is drawing import volumes from SABIC.
- Electronics:Wire and cable insulation demands flame-retardant compounding with metal hydrate fillers. REACH RoHS compliance steers halogen-free formulations.
- Pharmaceuticals:Blow-fill-seal containers and medical tubing require USP Class VI and ISO 10993 biocompatibility validation. Swissmedic and EMA device regulations tighten extractables testing protocols.
- Agriculture:Greenhouse films and silage stretch wrap compete on cost per hectare covered. Seasonal demand patterns in France and Italy create inventory management complexity.
Construction end users absorb the bulk of commodity-grade output; Pharmaceuticals is climbing the fastest on specification premiums.
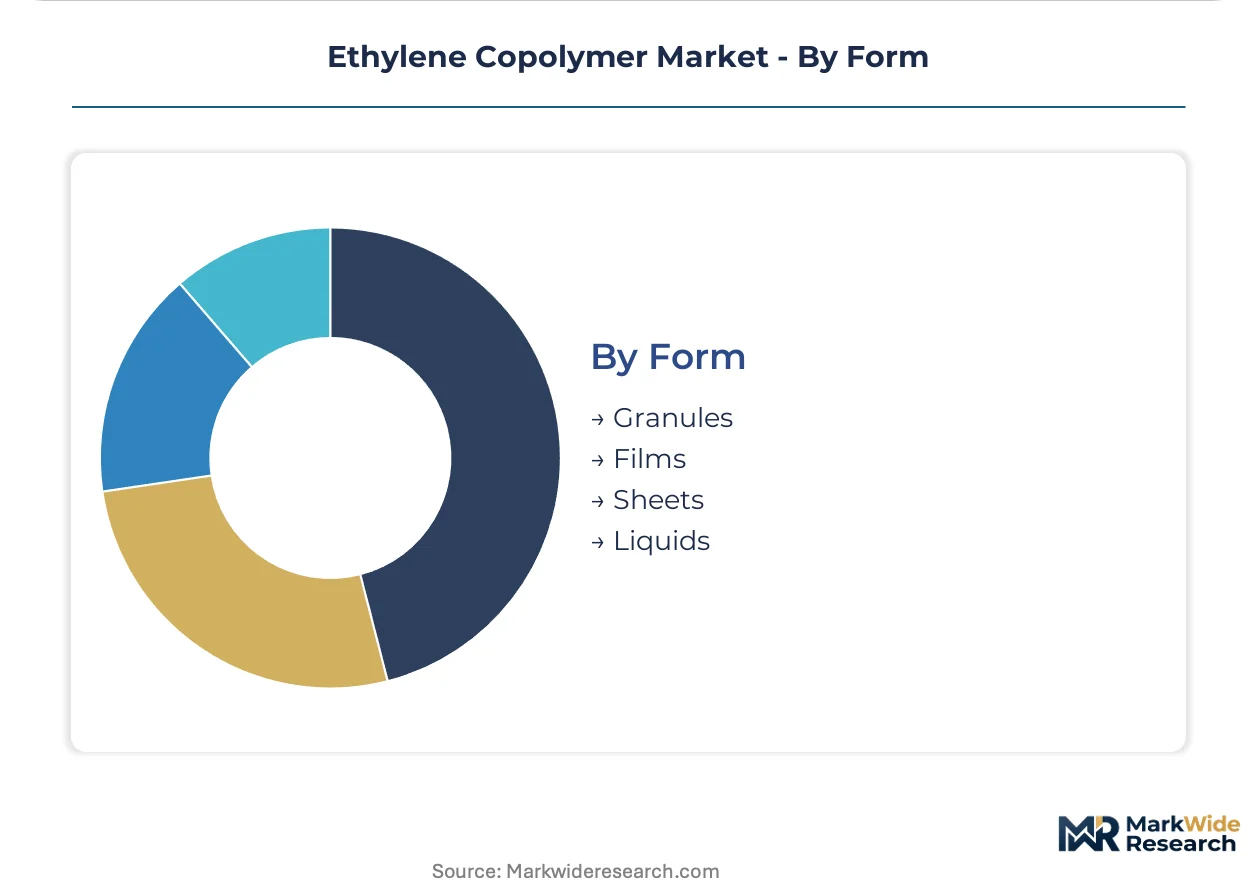
Form:
Conversion infrastructure and logistics economics favor granule and film formats, while liquid and sheet segments serve narrower specialty niches with distinct handling requirements.
- Granules:Pelletized resin for injection molding and extrusion compounding represents the standard delivery format. Compounders in the US Gulf Coast and Rotterdam-Antwerp corridor maintain strategic safety stocks.
- Films:Cast and blown film for flexible packaging and photovoltaic encapsulant commands the highest value-add per kilogram. Chinese module manufacturers enforce batch-level optical clarity certification.
- Sheets:Thermoformed tray and blister pack applications for medical device packaging require thickness uniformity within tight tolerances.
- Liquids:Dispersions and emulsions for adhesive and coating formulations occupy a narrow specialty niche with dedicated tank car logistics.
Granules absorb the bulk of resin production capacity; Films is gaining share fastest on photovoltaic and premium packaging demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in China's Yangtze River Delta and Saudi Arabia's Jubail Industrial City concentrate reactor-grade capacity and downstream compounding infrastructure. These zones attract multinationals through tax holidays and duty exemptions on alpha-olefin feedstock imports.
United States
Flexible packaging converters in the US Gulf Coast region expand orders for ethylene vinyl acetate grades to meet FDA food-contact standards for seal integrity. EPA TSCA Section 5 premanufacture review governs new copolymer chemistries entering consumer goods channels. Houston-area compounders maintain strategic safety stocks of pelletized resin for injection molding customers.
Germany
Automotive OEMs in Stuttgart and Munich specify softer-touch TPO-based instrument clusters displacing traditional polypropylene in dash panels. REACH Annex XVII restrictions on phthalate plasticizers steer formulators toward non-migrating ethylene-based alternatives for medical tubing. The Rhine-Ruhr corridor hosts specialty compounders serving flexible packaging producers pre-qualifying sealant layers ahead of enforcement deadlines.
China
Photovoltaic module manufacturers in Hefei and Xi'an specify ethylene vinyl acetate for optical clarity and UV resistance in solar encapsulant films. MIIT industrial standards and dual carbon goals accelerate local capacity additions from SABIC and Borealis. Zhejiang and Jiangsu province packaging converters absorb the majority of spot market volumes for downgauging mandates.
Saudi Arabia
Cost-optimized reactor-grade copolymers from integrated crackers serve Middle Eastern vehicle assembly plants and construction geomembrane applications. SABIC leverages feedstock integration to anchor position in regional export markets. Jubail Industrial City concentration creates price floor pressure for European and North American producers lacking comparable feedstock access.
Switzerland
Medical device manufacturers in Basel and Zurich require ethylene butylene copolymer grades with USP Class VI validation for tubing and soft-touch overmolding. Swissmedic regulations tighten extractables testing protocols for biocompatibility. German and Swiss device manufacturing clusters concentrate demand where Shore A flexibility intersects regulatory compliance.
Ethylene Copolymer Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical majors commanding reactor-grade output and independent compounders occupying formulation niches. The vendor base concentrates around three strategic archetypes: feedstock-integrated Gulf producers, technology-licensed European specialists, and Asia-Pacific scale players. Dominant competitive moves include backward integration into alpha-olefin production and geographic expansion through joint venture structures in Chinese free trade zones.
Among diversified chemical majors, BASF SE and Dow exemplify the technology-licensed archetype through metallocene catalyst expertise and post-reactor modification capabilities. SABIC occupies a position as the feedstock-integrated anchor, leveraging Saudi ethane access to serve Middle Eastern vehicle assembly and Asian photovoltaic manufacturing clusters with reactor-grade output.
| Leading Market Players |
|---|
| BASF SE |
| Dow |
| Exxon Mobil Corporation |
| DuPont |
| SABIC |
| INEOS |
| Borealis AG |
| Arkema |
| LyondellBasell Industries Holdings B.V. |
| Others |
Supply Flow & Price Mechanics
Captive alpha-olefin production at Saudi Aramco-SABIC integrated complexes anchors both feedstock security and pricing power for reactor-grade copolymer exports. Gulf producers leverage ethane cracking economics to undercut naphtha-dependent European and North American competitors on spot market quotations.
Pricing Analysis
Short lead-time premiums for 28-33% vinyl acetate grades serving Chinese photovoltaic module manufacturers compress spot discounts for standard packaging film resins. Three-tier pricing structure across photovoltaic-certified, automotive-IATF, and commodity packaging grades differentiates by certification burden and batch-level testing. Cost compression in standard LDPE film resins is intensifying because Zhejiang province converters negotiate volume aggregations. Automotive tier-one seating suppliers exhibit lowest price sensitivity due to 12-18 month qualification lock-ins.
Supply Chain Analysis
Specialized catalyst chemist availability in Basel, Rotterdam-Antwerp, and Houston petrochemical corridors constrains metallocene reactor expansion timelines. Manufacturing concentrates in Saudi Arabia, China, and Belgium, with each hub serving distinct regional demand clusters. Supply chains draw from butene, hexene, and octene comonomer streams tethered to naphtha and ethylene pricing volatility. Single-source vulnerability sits with metallocene catalyst licensors controlling single-site reactor technology. Distribution runs through direct mill relationships for photovoltaic volumes above threshold tonnages, with distributor intermediaries retained for smaller packaging converter accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock integration economics and regulatory compliance burdens are forcing reactor-grade specialists without captive ethane access toward exit or acquisition. Consolidation accelerates as REACH migration testing costs and IATF 16949 certification timelines discriminate against sub-scale compounders.
For Market Incumbents: Cement position through backward integration into alpha-olefin production or joint venture structures in Yangtze River Delta free trade zones. Threat substitution from bio-based polyolefins in European flexible packaging demands accelerated R&D in post-reactor modification capabilities. Channel control via direct mill relationships with LONGi and JinkoSolar manufacturing clusters locks out distributor-dependent competitors. For New Entrants and Emerging Players: Launch via specialty compounding partnerships serving Swiss medical device manufacturers requiring USP Class VI validation. Medical tubing and soft-touch overmolding segments offer lowest incumbent density and shortest qualification pathways. Go-to-market angle centers on carbon footprint disclosure under CSRD-aligned supplier questionnaires, capturing first-mover premium from EU automotive OEMs. For Investors and Strategic Acquirers: Exit pathways concentrate in technology-licensed European specialists with metallocene catalyst expertise and established automotive qualifications. Long-term viability favors producers with ISO 14064-verified emissions data and direct relationships with Chinese photovoltaic integrators. Signal to watch is MIIT industrial standard revisions tightening local content requirements for solar encapsulant resins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alpha-Olefin Production | Captive butene and hexene supply from Saudi ethane crackers eliminates feedstock cost spread volatility for SABIC. |
| Joint Venture in Chinese Free Trade Zone | SABIC-Borealis Yangtze River Delta capacity additions capture photovoltaic demand from LONGi and JinkoSolar clusters. |
| CSRD-Aligned Carbon Footprint Certification | ISO 14064 verification qualifies producers for EU automotive supplier questionnaires from Stuttgart and Munich OEMs. |
| Direct Mill Relationship with Module Manufacturers | Bypassing distributor intermediaries for ethylene vinyl acetate volumes above threshold tonnages secures batch-level optical clarity commitments. |
| Post-Reactor Modification Capability Investment | Metallocene catalyst advances enable precise short-chain branching control for downgauging mandates from German retail chains. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this ethylene copolymer market assessment. Primary interviews with plant managers at reactor-grade facilities, procurement leads at flexible packaging converters, distribution channel partners in Rotterdam-Antwerp, and technical R&D directors at metallocene catalyst licensors combined with secondary validation from Cefic polymer statistics, SEC 10-K petrochemical segment disclosures, and Chinese customs ethylene copolymer import records. Bottom-up capacity modeling and top-down demand triangulation cross-verified volume estimates.
Reconciliation of production capacity databases, downstream offtake surveys, and price discovery from spot market quotations informed the analytical framework across the projection horizon. Segmentation dimensions modeled include comonomer chemistry, reactor configuration tier, end-use industry application, and regional production hub concentration. CAGRs derived from elasticity-adjusted demand curves incorporating photovoltaic installation forecasts and automotive interior specification trends. Industry-specific forecast inputs encompassed MIIT industrial standard implementation timelines and REACH Annex XVII enforcement phase-in schedules.
Alpha-olefin feedstock cost volatility, regulatory divergence between EU and US migration test protocols, and Chinese photovoltaic demand cyclicality are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding metallocene catalyst licensing availability and free trade zone tax holiday continuity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Nylon Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
India Flooring Resins Market
Polymers & Resins
United States Polyols Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Polyimides Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market