
 TPEE in Automotive Industry Market | 2026-2036
TPEE in Automotive Industry Market Size, Share, and Industry Trends Forecast 2026-2036
TPEE in Automotive Industry Market Analysis
South Korean petrochemical producers is rebalancing TPEE resin output toward automotive grades as domestic EV assembly scales. SK Chemicals leverages its PCTG copolymer expertise to anchor supply contracts with Hyundai-Kia suppliers. Celanese Corporation sustains cost competitiveness through backward integration into acetyl chain feedstocks. Mitsubishi Chemical Corporation specializes in high-heat TPEE variants for under-hood applications in Japanese OEM platforms.
Thermoplastic polyester elastomer (TPEE) combines the mechanical strength of engineering plastics with the elasticity of rubber, typically exhibiting Shore D hardness of 35-82 and continuous service temperatures up to 140°C; automotive grades prioritize flex fatigue resistance for constant velocity joint boots and airbag door tear seams. The Application dimension shows Engine Compartment and Electrical Components segments outpacing Interior demand as thermal management and high-voltage insulation requirements intensify. Injection Molding dominates the Technology split due to cycle time advantages, though Extrusion is capturing share in wire jacketing as EV architectures proliferate.
EPA tailpipe emissions rules and NHTSA fuel economy standards in the United States compel OEMs to adopt lighter TPEE components that reduce vehicle mass without sacrificing durability. ECHA REACH restrictions on phthalate plasticizers and halogenated flame retardants in Europe redirect formulation toward bio-based polyol feedstocks and phosphorus-based chemistries. Stakeholders must monitor how China's GB standards for new energy vehicle electrical safety and MIIT dual carbon targets reshape material qualification protocols for TPEE suppliers serving BYD and SAIC Motor.
Market Dynamics
Electric vehicle wire harness sheathing is rewriting material qualification protocols as OEMs confront thermal management demands and mass reduction imperatives simultaneously. The transition from rubber to thermoplastic elastomers concentrates procurement power among EV-dedicated Tier 1 suppliers.
Growth Catalysts
- EPA tailpipe emissions rules:NHTSA fuel economy standards compel Detroit Three OEMs to adopt lighter TPEE constant velocity joint boots and airbag tear seams.
- Halogen-free formulation shifts:ECHA REACH restrictions on brominated flame retardants redirect European compounders toward phosphorus-based TPEE chemistries.
- Stuttgart-Wolfsburg belt concentration:Germany's automotive engineering cluster generates concentrated demand for high-heat TPEE grades in under-hood applications.
Market Restraints
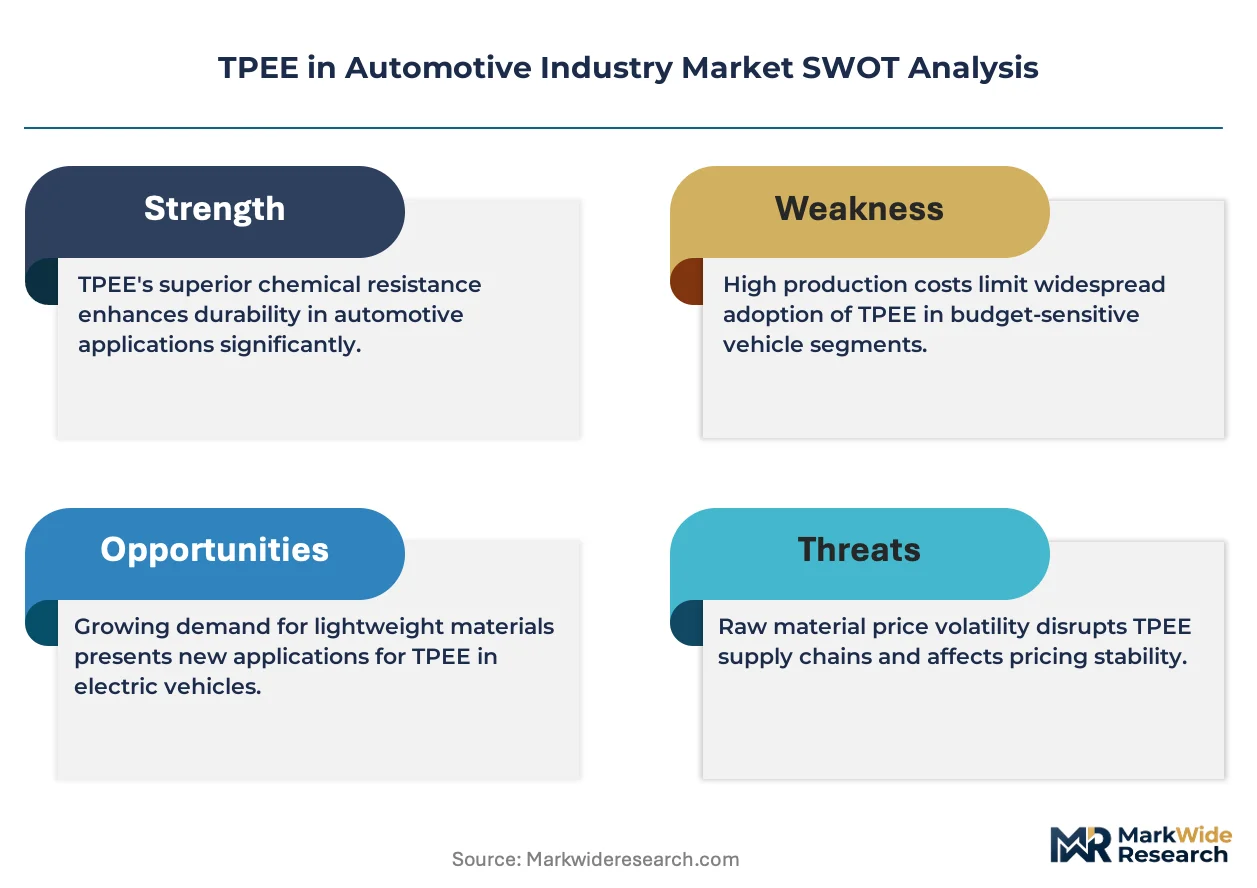
- Acetyl chain feedstock volatility:Celanese-style backward integration into methanol-to-acetic acid pathways remains capital-intensive for mid-tier compounders.
- Polyol supply concentration:Bio-based 1,4-butanediol capacity clusters in China and Thailand, exposing European TPEE producers to freight cost swings.
- Shore D hardness floor:TPEE's minimum 35 Shore D limits penetration in ultra-soft sealing applications where silicone TPVs dominate.
Strategic Opportunities
- India's PLI scheme for EV components:Domestic TPEE compounding for Tata Motors and Mahindra & Mahindra wire harnesses remains underdeveloped versus polymer imports.
- 800V architecture proliferation:High-voltage insulation requirements in premium EV platforms favor TPEE over XLPE in orange cable jacketing.
- Injection molding-extrusion hybrid cells:Tier 1 suppliers in South Korea are retrofitting lines to produce complex CVJ boot geometries in single cycles.
Industry Challenges
- Multi-standard qualification timelines:China's GB/T 25085 electrical safety protocols, UL 758 in North America, and LV 112-1 in Germany impose parallel certification burdens on compounders.
- Color-stable orange masterbatch sourcing:RAL 2003 pigmentation for high-voltage visibility must survive 140°C continuous service without degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TPEE in Automotive Industry Market |
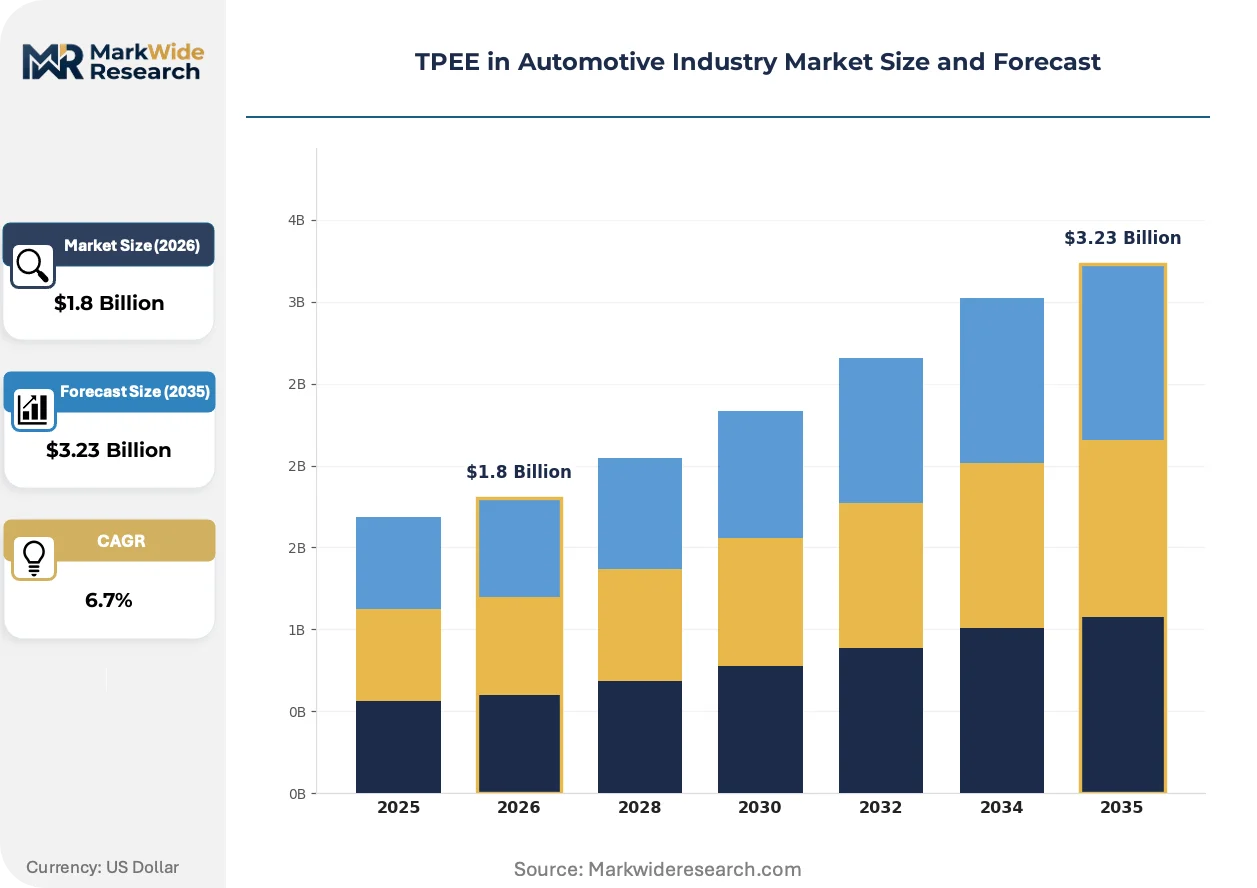
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic Elastomers, Compounds, Blends, Additives Application: Interior, Exterior, Engine Compartment, Electrical Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Injection Molding, Blow Molding, Extrusion, Thermoforming |
| Companies Covered | SK Chemicals, Arkema Group, Celanese Corporation, Radici Partecipazioni SpA, Eastman Chemical Co., LG Chem, Toyobo Co Ltd, Chang Chun Group, Mitsubishi Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TPEE in Automotive Industry Market Emerging Trajectories
Material-process convergence is compressing development cycles as TPEE suppliers co-engineer grades with Tier 1 injection molders. The intersection of thermal performance and processing efficiency dominates R&D allocation.
High-heat TPEE variants rated for 150°C continuous service are rewriting under-hood application boundaries. Japanese OEM platforms now specify these grades for turbocharger hoses previously reserved for heat-resistant rubber. The shift compresses supplier development timelines from 36 months to 18 months for platform approval.
REACH Annex XVII phthalate restrictions are forcing reformulation across European automotive supply chains. Compounders must validate alternative plasticizers without sacrificing flex fatigue performance in constant velocity joint boots. German OEMs are accelerating qualification of bio-based polyol feedstocks to preempt regulatory exposure.
Buyer concentration among EV-dedicated Tier 1s is consolidating procurement leverage. Hyundai-Kia suppliers now demand volume commitments spanning 5-year platform lifecycles, displacing spot purchasing. South Korean petrochemical producers are responding with captive TPEE resin capacity dedicated to automotive grades.
TPEE in Automotive Industry Market Segmentation
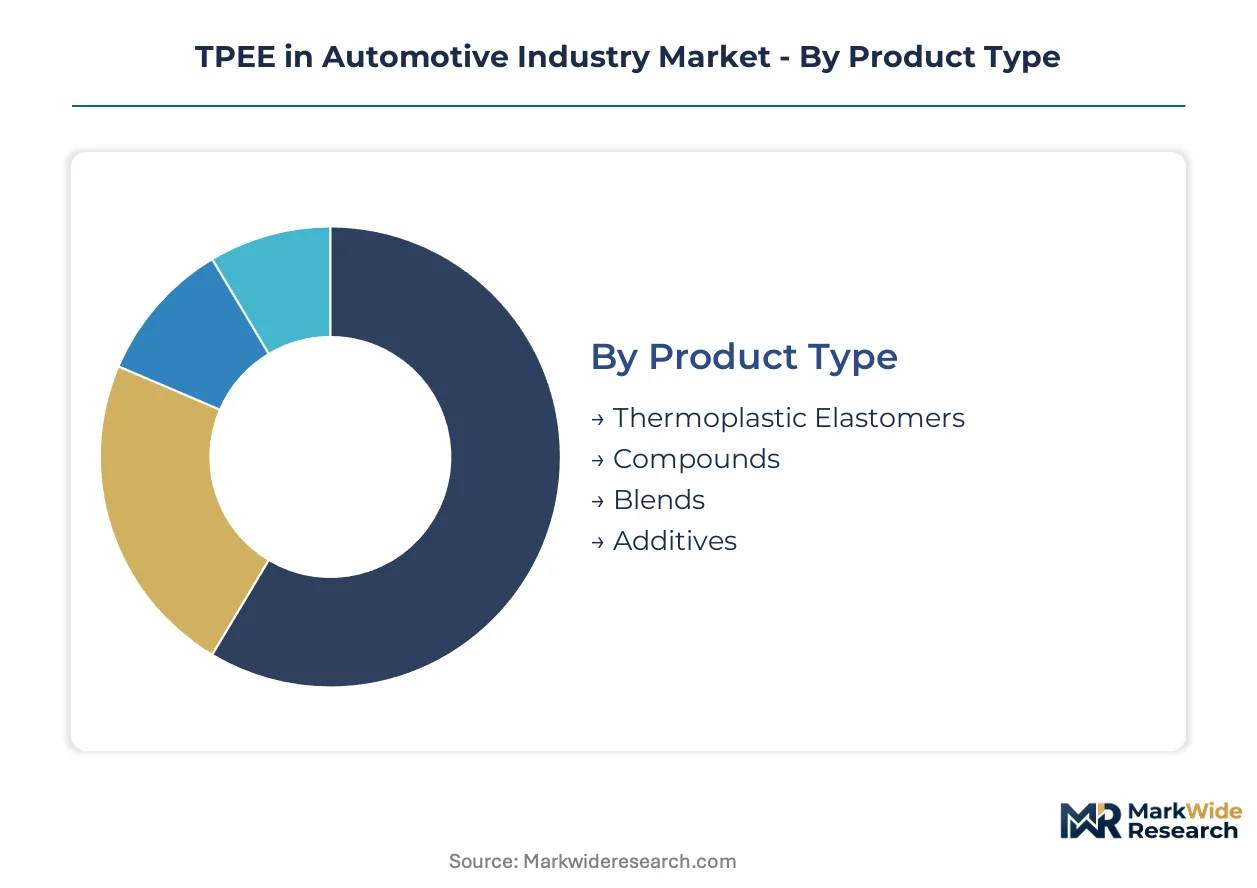
Automotive TPEE procurement splits across four distinct purchasing logics: material form, functional location, supply chain position, and processing method. Each dimension carries specific qualification protocols and margin structures that reshape supplier competitive positioning.
Product Type:
Buyers differentiate by technical risk tolerance and compounding capability, with resin purity requirements varying sharply between captive compounders and merchant market purchasers.
- Thermoplastic Elastomers:Virgin TPEE resin grades exhibit Shore D hardness of 35-82 and continuous service temperatures to 140°C. Demand concentrates in Germany's Stuttgart-Wolfsburg belt for constant velocity joint boots requiring flex fatigue resistance exceeding 500,000 cycles.
- Compounds:Pre-formulated TPEE with integrated stabilizers and colorants reduce downstream processing complexity. Korean EV wire harness suppliers favor these grades to compress qualification timelines for 800V architecture platforms.
- Blends:TPEE-PA or TPEE-TPU alloys balance chemical resistance with elasticity for airbag door tear seams. Japanese OEMs specify these for specific platform geometries.
- Additives:Flame retardant and UV stabilizer masterbatches enable REACH-compliant formulations. Phosphorus-based halogen-free packages are climbing fastest as ECHA restrictions harden.
Volume sits with Thermoplastic Elastomers; growth tilts toward Compounds as Tier-1 suppliers outsource formulation complexity.
Application:
Thermal exposure thresholds and electrical safety requirements create divergent material specifications across vehicle zones.
- Engine Compartment:Under-hood TPEE grades withstand 150°C continuous service for turbocharger hoses. Japanese platforms now qualify these for applications previously reserved for heat-resistant rubber.
- Electrical Components:Orange cable jacketing for high-voltage harnesses demands RAL 2003 color stability at 140°C. EV architecture proliferation is expanding this segment most quickly.
- Interior:Soft-touch surfaces and trim components prioritize aesthetic consistency over thermal performance. Lower specification barriers attract commodity compounders.
- Exterior:Weatherstrip seals and body cladding require UV and ozone resistance. Shore D hardness floors limit penetration against silicone TPV alternatives.
Procurement concentrates in Engine Compartment for value; Electrical Components are gaining share fastest on EV transition momentum.
End User:
Contract duration and technical collaboration intensity vary by position in the automotive value chain.
- Tier-1 Suppliers:Hyundai-Kia dedicated harness producers now demand 5-year volume commitments, displacing spot purchasing. These buyers co-engineer grades with resin producers.
- OEMs:Direct material qualification by Volkswagen, BMW, and Mercedes-Benz imposes parallel certification against LV 112-1, UL 758, and GB/T 25085 protocols.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-qualified compounds to bypass lengthy platform approval cycles.
- Aftermarket Providers:Replacement CVJ boots and seals prioritize cost over original specification matching. Price sensitivity limits premium grade penetration.
Revenue pools with Tier-1 Suppliers; OEM direct sourcing is expanding most rapidly as platform complexity increases.
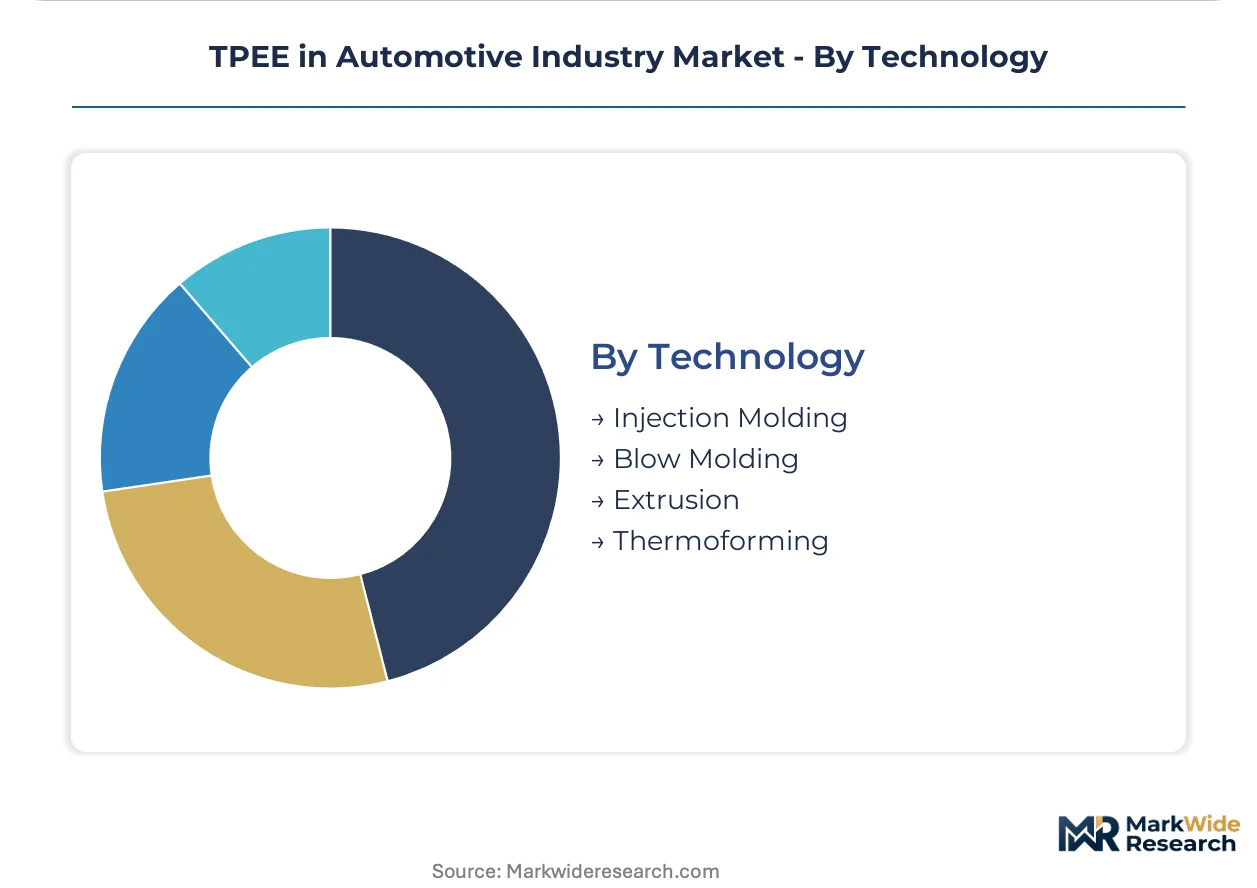
Technology:
Cycle time economics and part geometry complexity drive processing method selection.
- Injection Molding:Dominates for constant velocity joint boots and airbag components with complex geometries. Korean suppliers are retrofitting hybrid cells to combine molding with extrusion in single cycles.
- Extrusion:Wire jacketing and hose production favor continuous processing. EV harness scaling is capturing share as line speeds improve for thin-wall insulation.
- Blow Molding:Hollow components like ducts and reservoirs require specific melt strength grades. Limited to niche geometries with lower volume throughput.
- Thermoforming:Sheet-based processing for large interior panels and exterior cladding. Secondary operations for trimming and finishing add cost layers.
Equipment investment concentrates in Injection Molding; Extrusion is climbing fastest on EV electrical architecture proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyol feedstock concentration in China's Shandong and Jiangsu provinces anchors TPEE resin supply chains. Germany's automotive belt drives premium-grade demand. South Korean petrochemical complexes pivot output toward EV-dedicated automotive grades.
United States
EPA tailpipe emissions rules and NHTSA fuel economy standards compel Detroit Three OEMs to adopt lighter TPEE constant velocity joint boots and airbag tear seams. Federal regulatory pressure intensifies material substitution away from rubber. Michigan's automotive corridor concentrates demand engineering for under-hood thermal management applications.
Germany
ECHA REACH restrictions on brominated flame retardants redirect compounders toward phosphorus-based TPEE chemistries for wire harness sheathing. The Stuttgart-Wolfsburg automotive engineering cluster generates concentrated demand for high-heat grades. Bavarian chemical producers accelerate bio-based polyol qualification to preempt regulatory exposure.
China
MIIT dual carbon targets and GB standards for new energy vehicle electrical safety reshape material qualification protocols for suppliers serving BYD and SAIC Motor. Domestic bio-based 1,4-butanediol capacity expansion reduces import dependency. Yangtze River Delta chemical parks concentrate TPEE compounding for domestic EV platform scaling.
South Korea
Hyundai-Kia suppliers now demand 5-year volume commitments spanning platform lifecycles, displacing spot purchasing. The country's national industrial policy supports petrochemical rebalancing toward automotive-grade resin output. Seoul Capital Area engineering centers co-develop grades with dedicated EV Tier-1 harness producers.
Japan
METI industrial standards and JIS certification protocols govern high-heat TPEE variants for turbocharger hoses previously reserved for heat-resistant rubber. Japanese OEM platforms compress supplier development timelines from 36 months to 18 months. Kanto region engineering clusters specialize in 150°C continuous service grade qualification.
TPEE in Automotive Industry Market Vendor Landscape
Global majors compete with regional champions across feedstock integration and automotive qualification depth. The vendor base stratifies between acetyl-chain-integrated resin producers and formulation-specialist compounders. Three archetypes dominate: petrochemical conglomerates with backward integration, regional compounders with OEM co-development relationships, and specialty polymer divisions of diversified chemical groups. Capacity expansion and strategic partnerships constitute the dominant competitive moves as EV platform volumes harden.
Among Asian petrochemical producers, SK Chemicals and LG Chem exemplify the conglomerate archetype leveraging existing polymer expertise to anchor automotive supply contracts. Celanese Corporation occupies a position representing North American feedstock-integrated competitiveness through acetyl chain control. Mitsubishi Chemical Corporation sits within the specialty high-heat tier, with Japanese-market platform relationships supporting premium grade positioning.
| Leading Market Players |
|---|
| SK Chemicals |
| Arkema Group |
| Celanese Corporation |
| Radici Partecipazioni SpA |
| Eastman Chemical Co. |
| LG Chem |
| Toyobo Co Ltd |
| Chang Chun Group |
| Mitsubishi Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into acetyl chain feedstocks anchors Celanese-style cost positions while compressing margin buffers for non-integrated compounders serving Detroit Three and Stuttgart-Wolfsburg OEM clusters. This structural asymmetry concentrates pricing power among resin producers with captive methanol-to-acetic acid pathways, forcing merchant purchasers into long-term offtake commitments to secure volume certainty.
Pricing Analysis
Warranty-backed technical service separates premium TPEE grades from commodity resin transactions, with Korean EV harness suppliers bundling five-year platform support into compound pricing. Three-tier pricing structure across automotive-certified, industrial-standard, and aftermarket-economy levels reflects divergent qualification burdens. Price differentiation rests on UL 758 and LV 112-1 certification tiers alongside volume scale commitments. Cost compression in standard grades is intensifying because Chinese bio-based polyol capacity expansion is flooding merchant markets with lower-cost 1,4-butanediol feedstock. Aftermarket replacement boot suppliers exhibit highest price sensitivity, while OEM direct qualification programs show lowest elasticity due to switching costs.
Supply Chain Analysis
Ocean freight rate volatility between China's Shandong-Jiangsu chemical parks and European compounders is amplifying working capital requirements for just-in-time automotive programs. Raw material sourcing draws from bio-based 1,4-butanediol clusters in China and Thailand, acetyl chain intermediates from North American methanol complexes, and phosphorus-based flame retardant precursors from German specialty chemical producers. Single-source vulnerability concentrates in high-heat additive packages qualified for 150°C continuous service. Distribution runs through captive resin supply to Tier 1 compounders, with spot market access restricted by platform-specific qualification timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic elastomer substitution for rubber in 800V EV architectures is compressing supplier development cycles from legacy 36-month platform approvals toward 18-month qualification windows. This technology-transition phase rewards compounders with pre-integrated halogen-free formulation capabilities and established OEM co-development relationships.
For Market Incumbents: Deepen backward integration into acetyl chain feedstocks to defend margin position against Chinese polyol cost advantages. Prioritize captive production of phosphorus-based flame retardant masterbatches to preempt REACH Annex XVII regulatory exposure. Lock in five-year volume commitments with Hyundai-Kia dedicated harness suppliers before spot market alternatives mature.
For New Entrants and Emerging Players: 800V cable jacketing qualification for premium EV platforms offers the most penetrable wedge, as incumbent compounders struggle with color-stable RAL 2003 masterbatch sourcing at 140°C service thresholds. Target India's PLI-supported EV component ecosystem for Tata Motors and Mahindra wire harness programs. Lead with injection molding-extrusion hybrid cell co-development to bypass equipment investment barriers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty high-heat grade producers with Japanese OEM platform relationships and sub-24-month qualification track records. Long-term viability over the next decade hinges on bio-based polyol feedstock qualification progress against ECHA regulatory tightening. Monitor GB/T 25085 certification velocity among Chinese compounders serving BYD and SAIC as inflection indicator for regional supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acetyl Chain Feedstocks | Celanese-style methanol-to-acetic acid control compresses resin cost position versus merchant compounders. |
| Halogen-Free Formulation Qualification | REACH Annex XVII compliance redirects European procurement toward phosphorus-based TPEE chemistries. |
| 800V Architecture Material Certification | High-voltage insulation requirements favor TPEE over XLPE in orange cable jacketing for premium EVs. |
| India PLI Scheme Localization | Domestic compounding for Tata Motors harnesses bypasses polymer import dependency and freight exposure. |
| Injection Molding-Extrusion Hybrid Cell Deployment | Korean Tier 1 retrofitting enables single-cycle production of complex CVJ boot geometries. |
Methodological Framework
Document review covered customs and trade flow databases, automotive production registries, and chemical industry association reports, complemented by interviews with Tier 1 supplier procurement directors, OEM platform engineers, and resin producer technical sales leads. Secondary validation drew from SEC filings of listed petrochemical groups, EPA and ECHA regulatory dockets, and MIIT new energy vehicle standard publications. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, and technology segmentation dimensions.
Segmented projections across resin grade, vehicle zone thermal exposure, and processing method dimensions anchored value and volume trajectories over the projection horizon. CAGRs derived from regression analysis of historical automotive content-per-vehicle trends, weighted by EV platform rollout schedules and regional regulatory compliance timelines. Forecast inputs incorporated polyol feedstock cost curves, qualification timeline compression effects, and substitution elasticity between TPEE and heat-resistant rubber alternatives.
Several conditions sit outside the modeled scope, including unforeseen raw material supply disruptions, abrupt regulatory timeline accelerations, and breakthrough silicone TPV formulations breaching Shore D hardness floors. Forecasts reflect stated assumptions regarding OEM platform standardization and EV adoption curves. Stakeholders should weight assumptions against their own operating context and regional supply chain exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Middle East and Africa Polyurethane Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Biobased Polypropylene PP Size Market