
 GCC Vinyl Flooring Market | 2026-2036
GCC Vinyl Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Vinyl Flooring Market Foresight
Project finance tied to giga-project developments is tilting competitive access toward suppliers with balance-sheet capacity to bond large hospitality and infrastructure contracts. Avant Holding leverages its regional distribution network to secure specification roles across mixed-use developments. Floorworld LLC anchors retail presence through showrooms in Dubai and Riyadh that target contractor and designer channels. RAK Ceramics extends its ceramic brand recognition into adjacent hard-surface categories including vinyl plank systems.
GCC vinyl flooring comprises multi-layer synthetic products built around PVC wear layers, printed design films, and stabilizing cores, manufactured through calendering or extrusion processes to deliver water resistance and dimensional stability for high-traffic commercial and residential environments. Luxury vinyl tile commands specification preference in hospitality and premium retail fit-outs where stone and wood visual replication drives aesthetic decisions. Sheet vinyl sustains volume in healthcare facilities across the Gulf where seamless hygiene surfaces and welded installation meet infection-control protocols. Click lock systems are gaining traction in residential housing applications across Saudi Arabia's new master-planned communities as dry-install methods reduce skilled-labor dependency.
Saudi Arabia's Saudi Building Code and the UAE's civil defense fire-safety regulations shape product certification requirements for flame-retardant performance and indoor air quality emissions across vinyl flooring imports. Dubai Municipality's green building regulations and Qatar's GSAS framework increasingly reference low-VOC material standards that filter supplier eligibility for public infrastructure tenders. Stakeholders must monitor evolving conformity-assessment pathways as Gulf standardization bodies tighten alignment between national building codes and EU REACH-derived substance restrictions.
Market Dynamics
Project finance tied to giga-project developments across Saudi Arabia and the UAE is concentrating procurement power with developers who demand bonded supply capacity and LEED-aligned certification documentation from vinyl flooring vendors.
Growth Catalysts
- GSAS and LEED alignment:Qatar's Global Sustainability Assessment System and LEED certification requirements for Dubai South developments are mandating low-VOC vinyl specifications that filter supplier eligibility.
- Healthcare infrastructure expansion:Seamless sheet vinyl installations with welded seams are required across hospital and clinic construction in Saudi Arabia's Health Sector Transformation Program.
- Click-lock dry installation:Saudi master-planned communities are specifying interlocking LVT systems that reduce skilled-labor dependency and accelerate residential fit-out timelines.
Market Restraints
- PVC resin cost volatility:Feedstock price swings for polyvinyl chloride create margin compression for calendering and extrusion manufacturers serving the Gulf.
- Import concentration risk:Heavy reliance on Asian manufacturing clusters for printed design films and stabilizer cores exposes distributors to shipping lane disruptions through the Strait of Hormuz.
- Fire-safety certification friction:UAE civil defense regulations and Saudi Building Code flame-retardant testing protocols extend product approval timelines for new entrants.
Strategic Opportunities
- Kuwait residential underpenetration:Lower LVT adoption rates in Kuwaiti housing stock compared to UAE and Saudi Arabia present whitespace for click-lock system distributors.
- Digital specification platforms:BIM-integrated product libraries are enabling architects in Riyadh and Dubai to pre-qualify vinyl finishes during schematic design phases.
- Circular material mandates:EU REACH-derived substance restrictions are pressuring Gulf standardization bodies to develop recyclable vinyl content standards ahead of import regulation tightening.
Industry Challenges
- Welded seam technician scarcity:Healthcare and commercial projects requiring hot-weld installation of sheet vinyl face bottlenecks from limited certified installer pools in Oman and Bahrain.
- Multi-certification capex burden:Manufacturers must maintain parallel testing regimens for Saudi Building Code, UAE civil defense, and Qatar GSAS compliance, duplicating laboratory validation spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Vinyl Flooring Market |
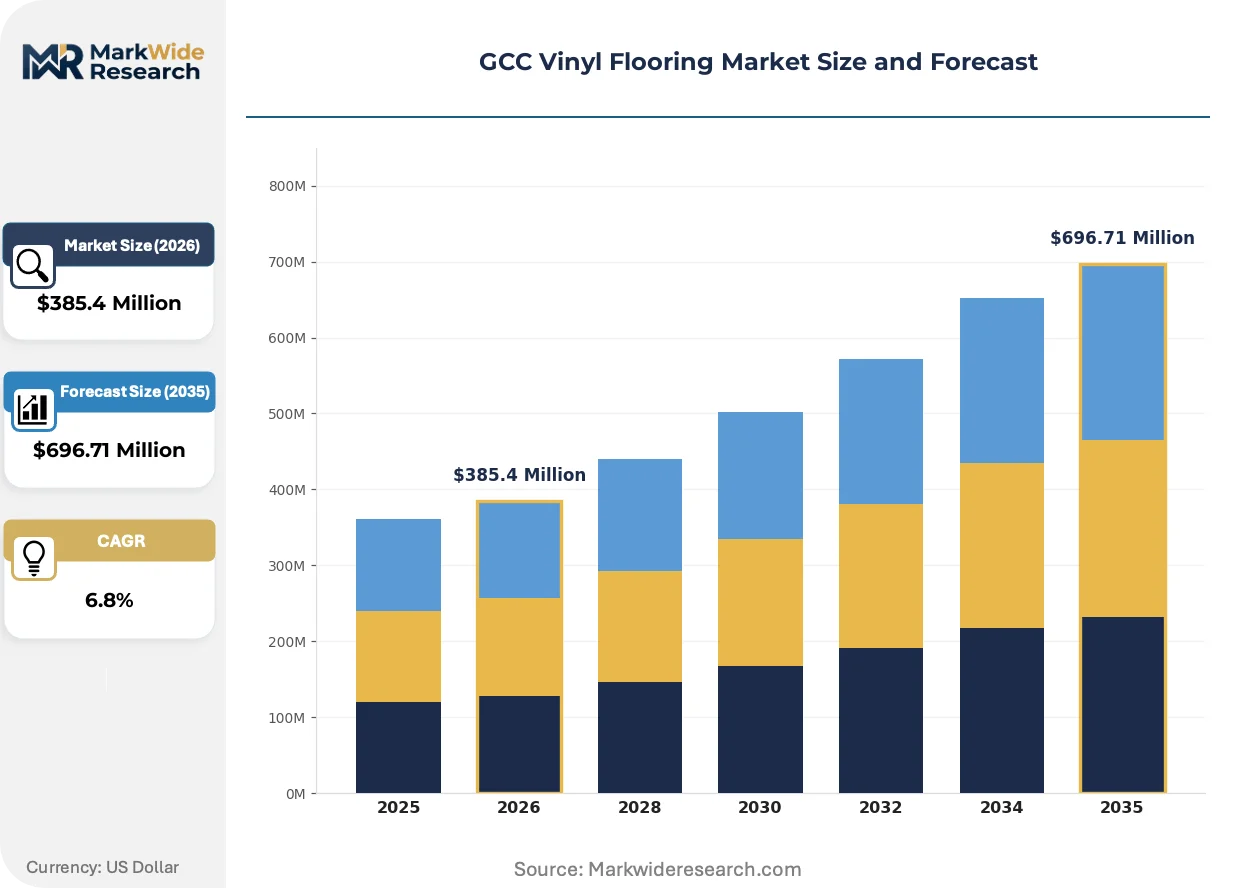
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury Vinyl Tile, Vinyl Composite Tile, Sheet Vinyl, Solid Vinyl Plank Installation Method: Glue-down, Loose Lay, Click Lock, Self-adhesive End User Industry: Commercial Offices, Hospitality Venues, Healthcare Facilities, Educational Institutions Application Area: Residential Housing, Retail Outlets, Public Infrastructure, Leisure Centers |
| Companies Covered | Dubai Vinyl Flooring, Avant Holding, Dutco Tennant LLC, Floorworld LLC, RAK Ceramics, Fusion Floors Building materials Trading LLC, Rosetta, Al Sorayai Group, Red Magma General Trading LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Vinyl Flooring Market Shifts & Advancements
Digital design replication and installation automation are compressing specification cycles while regulatory alignment with European chemical standards is reshaping supplier qualification pathways across Gulf procurement offices.
High-definition digital printing is digitizing wood and stone visual replication in luxury vinyl tile manufacturing. Hospitality developers in Riyadh's King Abdullah Financial District are specifying 0.5mm wear-layer products with embossed-in-register texture at triple the rate of conventional rotary-printed alternatives. This capability is digitizing aesthetic decision-making by enabling real-time design customization without physical sample production.
REACH-derived substance restrictions are tightening alignment requirements for Gulf vinyl flooring imports. Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology are drafting low-phthalate and heavy-metal limits that mirror EU chemical safety frameworks. Sheet vinyl products for healthcare applications face the steepest compliance recalibration as welded-seam hygiene specifications intersect with evolving emissions testing protocols.
Buyer concentration among giga-project developers is compressing distributor margin structures. Large-format procurement teams at Dubai South and Neom are consolidating specification authority and demanding direct manufacturer relationships that bypass traditional dealer networks. Saudi Arabia's residential sector retains fragmented contractor purchasing, but hospitality and mixed-use verticals are centralizing vinyl flooring selection through designated materials consultants with bonded supply mandates.
GCC Vinyl Flooring Market Segmentation
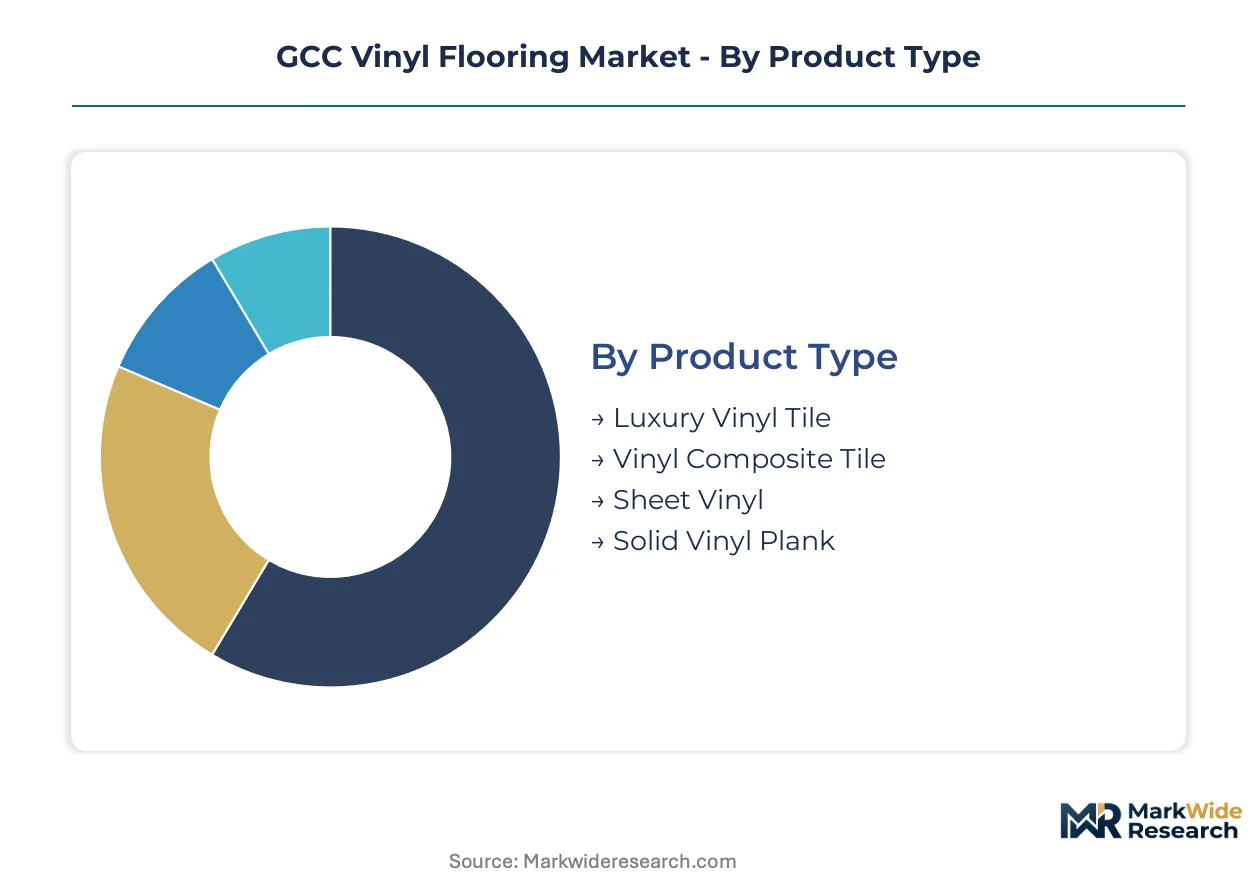
Vinyl flooring procurement across the Gulf Cooperation Council fragments across specification hierarchies that prioritize wear-layer durability, installation labor economics, and regulatory compliance. Understanding how product types, installation methods, end-use verticals, and application areas partition demand reveals where bonded supply capacity and certification documentation concentrate competitive advantage.
Product Type:
Cost tier differentiation separates specification-grade luxury vinyl tile from economy-oriented sheet vinyl and intermediate composite systems.
- Luxury Vinyl Tile:Multi-layer rigid or flexible planks with 0.3mm to 0.7mm transparent PVC wear layers protecting printed design films. Hospitality venues in Riyadh's King Abdullah Financial District specify embossed-in-register textures at triple the rate of conventional alternatives. Demand concentrates where LEED-aligned material choices and stone-wood visual replication drive aesthetic decisions.
- Sheet Vinyl:Continuous rolls manufactured through calendering processes with homogeneous or heterogeneous layer construction. Healthcare facilities across Saudi Arabia's Health Sector Transformation Program require seamless surfaces with welded seams meeting infection-control protocols. Procurement runs through designated materials consultants with bonded supply mandates.
- Vinyl Composite Tile:Solid vinyl chips compressed into modular tiles with through-pattern coloration. Commercial offices in Dubai South specify these for high-traffic elevator lobbies and circulation corridors.
- Solid Vinyl Plank:Dense homogeneous construction with color and pattern extending through full thickness. Residential housing in Saudi master-planned communities adopts these for moisture-prone ground-floor installations.
Sheet vinyl commands the established base in healthcare and institutional procurement. The steepest expansion runs through luxury vinyl tile as hospitality developers pursue premium aesthetic replication.
Installation Method:
Application context and skilled-labor availability determine whether adhesive bonding, floating systems, or pressure-sensitive backing prevail.
- Click Lock:Interlocking edge profiles enabling dry installation without adhesives or underlayment fastening. Saudi Arabia's new master-planned communities specify these systems to reduce skilled-labor dependency and accelerate residential fit-out timelines. Demand climbs fastest where contractor capacity constraints and project speed requirements intersect.
- Glue-down:Full-spread or perimeter-bonded adhesive attachment requiring substrate preparation and trowel-applied bonding agents. Commercial offices and retail outlets in the UAE specify these for dimensional stability under heavy rolling loads and point-source furniture concentrations.
- Loose Lay:Friction-fit installation relying on product weight and perimeter anchoring without adhesive. Leisure centers and temporary retail installations favor these for future reconfiguration flexibility.
- Self-adhesive:Factory-applied pressure-sensitive backing activated during installation. Residential housing in Kuwait and Bahrain adopts these for DIY renovation segments and small-scale contractor projects.
Glue-down systems anchor commercial and institutional specification. Click lock methods are gaining share fastest as Saudi residential construction scales.
End User Industry:
Customer type segmentation maps divergent performance requirements across hygiene protocols, traffic loading, and fire-safety certification.
- Hospitality Venues:Hotels, resorts, and food-service environments requiring slip resistance, stain protection, and acoustic underlayment compatibility. Developers across Neom and Red Sea Project giga-developments specify luxury vinyl tile with 0.5mm wear layers for guest room and corridor applications.
- Healthcare Facilities:Hospitals, clinics, and eldercare requiring seamless sheet vinyl with welded seams and chemical resistance to disinfectant protocols. Saudi Arabia's Health Sector Transformation Program mandates these specifications across new construction and renovation.
- Commercial Offices:Corporate headquarters and co-working spaces prioritizing acoustic performance and furniture castor compatibility. Dubai South and Riyadh's King Abdullah Financial District concentrate bulk procurement for large-format installations.
- Educational Institutions:Schools and universities balancing durability against maintenance simplicity. Qatar's GSAS framework and Dubai Municipality green building regulations filter supplier eligibility for public sector tenders.
Healthcare facilities command the established base through welded-seam hygiene specifications. Hospitality venues are expanding most quickly as giga-project developments concentrate procurement.
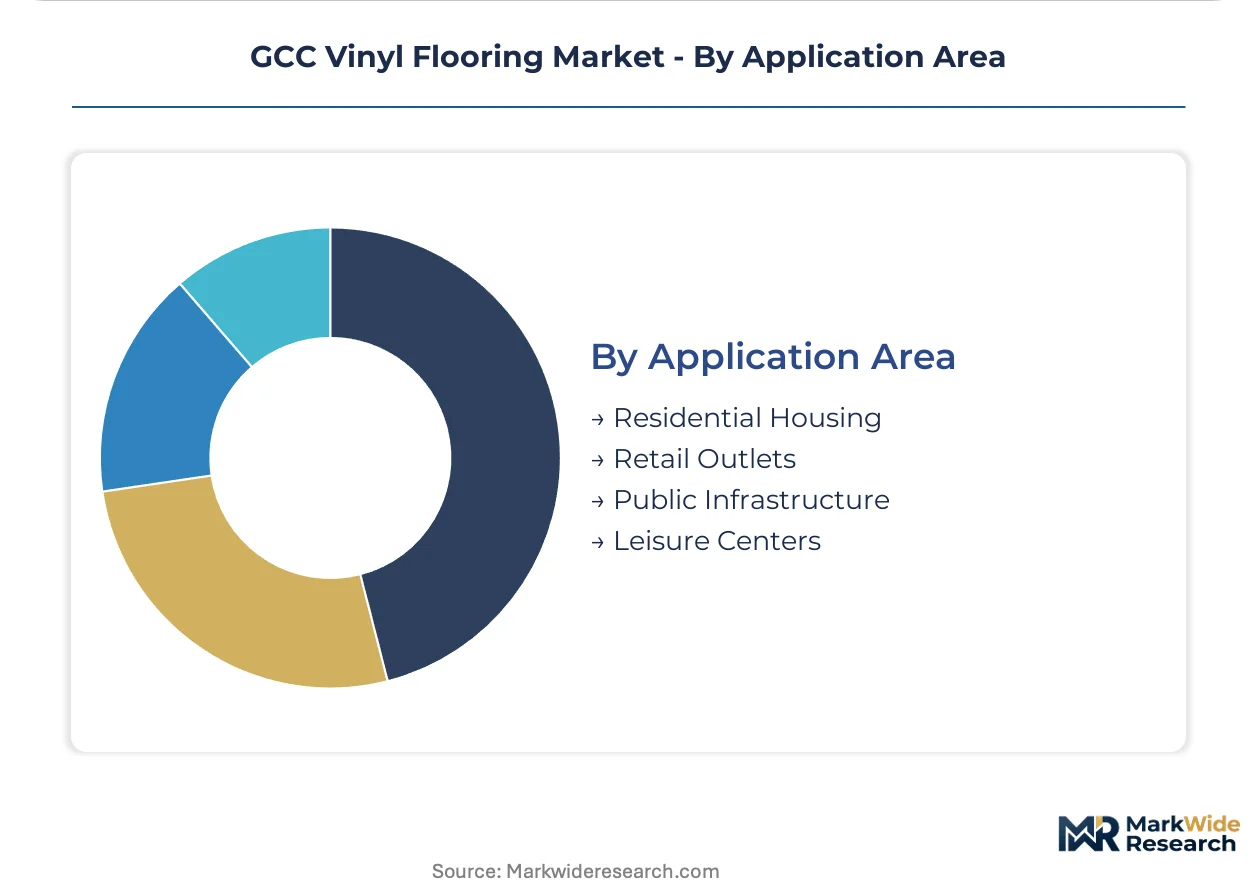
Application Area:
Geography and facility type within the GCC determine whether residential, retail, infrastructure, or leisure specifications dominate procurement volume.
- Public Infrastructure:Airports, transit stations, and government facilities requiring flame-retardant certification and high-traffic durability. UAE civil defense regulations and Saudi Building Code shape product approval timelines and supplier qualification.
- Residential Housing:Single-family and multi-family dwellings across Saudi master-planned communities and UAE expatriate housing stock. Click-lock luxury vinyl tile displaces ceramic tile and engineered wood in moisture-prone climates.
- Retail Outlets:Shopping malls, flagship stores, and quick-service restaurants requiring rapid installation and visual merchandising flexibility. Dubai Mall and Riyadh Park specifications influence regional distributor inventory.
- Leisure Centers:Fitness facilities, entertainment venues, and sports complexes demanding impact resistance and acoustic dampening. Qatar's World Cup legacy developments and Saudi entertainment city projects concentrate demand.
Public infrastructure commands the established base through regulatory-filtered procurement. Residential housing is climbing the fastest as Saudi master-planned communities scale construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Giga-project developers in Saudi Arabia and the UAE concentrate bulk procurement authority, tilting competitive access toward suppliers with bonded contract capacity and multi-jurisdiction certification documentation. Qatar's healthcare and education infrastructure programs filter supplier eligibility through GSAS sustainability frameworks. Kuwait and Bahrain present whitespace for residential click-lock systems amid lower current penetration.
Saudi Arabia
Neom and Red Sea Project developments specify luxury vinyl tile with 0.5mm wear layers for hospitality fit-outs at scale. The Saudi Building Code mandates flame-retardant testing protocols that extend product approval timelines for imported sheet vinyl. Riyadh's King Abdullah Financial District concentrates procurement teams demanding direct manufacturer relationships.
United Arab Emirates
Dubai South and Expo City legacy developments drive specification of large-format LVT installations in commercial office verticals. Dubai Municipality green building regulations and UAE civil defense fire-safety standards shape low-VOC and flame-retardant certification requirements. Abu Dhabi's Al Reem Island clusters hospitality procurement for bonded supply capacity.
Qatar
World Cup legacy leisure centers and healthcare infrastructure expansion sustain demand for seamless sheet vinyl with welded seams. The Global Sustainability Assessment System mandates low-emissions material standards that filter supplier eligibility for public sector tenders. Lusail City development concentrates bulk procurement authority through designated materials consultants.
Kuwait
Residential housing stock shows lower LVT adoption compared to UAE and Saudi markets, presenting whitespace for click-lock system distributors. The country's national standardization body maintains alignment with Gulf technical regulations for vinyl flooring imports. Kuwait City and Jahra governorate master-planned communities specify dry-install methods to reduce skilled-labor dependency.
Bahrain
Healthcare and commercial projects face bottlenecks from limited certified hot-weld technician pools for sheet vinyl installation. The national civil defense authority enforces flame-retardant performance standards parallel to UAE and Saudi protocols. Manama's financial district and Diyar Al Muharraq developments concentrate hospitality and retail fit-out demand.
GCC Vinyl Flooring Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification-driven segments where giga-project procurement authority tilts toward bonded supply capacity. The vendor base fragments between regional distributors with showroom networks and ceramic manufacturers extending into adjacent hard-surface categories. Two archetypes dominate: balance-sheet-heavy suppliers securing direct developer relationships, and retail-anchored specialists targeting contractor and designer channels. Competitive moves center on certification documentation breadth and geographic footprint expansion into underpenetrated residential markets.
Among UAE-based distributors, Dubai Vinyl Flooring and Floorworld LLC occupy positions within the retail-specialist tier, leveraging showroom presence in Dubai and Riyadh to anchor contractor channel access. Avant Holding represents the bonded-supply archetype, securing specification roles across mixed-use developments through regional distribution network scale. RAK Ceramics exemplifies category-extension strategy, translating ceramic brand recognition into adjacent vinyl plank positioning. These three entities illustrate how competitive positioning fragments across channel control, retail anchoring, and brand extension vectors.
| Leading Market Players |
|---|
| Dubai Vinyl Flooring |
| Avant Holding |
| Dutco Tennant LLC |
| Floorworld LLC |
| RAK Ceramics |
| Fusion Floors Building materials Trading LLC |
| Rosetta |
| Al Sorayai Group |
| Red Magma General Trading LLC |
| Others |
Supply & Pricing Matrix
Strait of Hormuz shipping lanes carry PVC resin and printed design films from Asian manufacturing clusters to Gulf distributors, with freight cost volatility feeding directly into landed cost structures and compressing margin pools for calendering-dependent product tiers. This logistics corridor's instability amplifies pricing power for suppliers with bonded inventory positions near Riyadh and Dubai, while forcing smaller distributors toward spot-market exposure.
Pricing Analysis
Cost-plus contracts with PVC resin indexation dominate procurement agreements between Gulf distributors and Asian manufacturers, locking margin structures to feedstock volatility. Three-tier pricing stratifies across premium LVT with 0.5mm wear layers and embossed-in-register textures, standard glue-down sheet vinyl for healthcare, and economy self-adhesive residential planks. Price differentiation hinges on certification grade—Saudi Building Code and UAE civil defense flame-retardant tiers command 15-20% premiums—and bonded supply capacity for giga-project eligibility. Cost compression in standard-grade sheet vinyl is intensifying because Asian manufacturers are absorbing resin spikes rather than passing through. Residential contractors in Saudi master-planned communities exhibit highest price sensitivity, while hospitality developers at Neom and Red Sea Project show lowest.
Supply Chain Analysis
Upstream PVC resin production concentrates in China, South Korea, and Japan, with ethylene feedstock drawing from regional naphtha crackers and integrated chlor-alkali complexes. Printed design films and stabilizer cores hinge on Taiwanese and South Korean specialty chemical suppliers, creating single-source vulnerability for embossed-in-register texture capabilities. Distribution runs through Dubai Jebel Ali and King Abdullah Port bonded warehouses, with last-mile fulfillment splitting between specification-grade direct-to-developer channels and retail showroom networks targeting contractor segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat: multi-jurisdiction certification documentation creates switching costs that lock giga-project developers into incumbent supplier relationships across Saudi Building Code, UAE civil defense, and Qatar GSAS compliance pathways.
For Market Incumbents: Insulate specification positions by deepening backward integration into PVC compounding and wear-layer extrusion to capture resin volatility margins. Add bonded warehouse capacity in Riyadh's King Abdullah Financial District and Dubai South to compress delivery windows for hospitality procurement teams. Certification investment in Qatar GSAS and Dubai Municipality green building tiers filters competitor eligibility for public infrastructure tenders.
For New Entrants and Emerging Players: Pursue whitespace in Kuwait residential click-lock systems, where LVT penetration trails UAE and Saudi benchmarks by 40-50 percentage points. Target Bahrain and Oman healthcare sheet vinyl segments facing acute certified hot-weld technician scarcity, enabling service-bundle differentiation. Anchor go-to-market through digital specification platforms with BIM-integrated product libraries that pre-qualify finishes during Riyadh and Dubai schematic design phases.
For Investors and Strategic Acquirers: Regional distributors with showroom networks in Dubai and Riyadh represent the most defensible acquisition archetype, combining contractor channel control with specification influence over mixed-use developments. Long-term viability centers on GSAS and LEED alignment mandates tightening across Gulf procurement offices, favoring suppliers with existing low-VOC certification infrastructure. Watch for REACH-derived substance restriction announcements from Saudi Standards, Metrology and Quality Organization and Emirates Authority for Standardization and Metrology as inflection signals for compliance recalibration spend.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Portfolio Expansion | GSAS and Saudi Building Code compliance unlocks Neom and Red Sea Project hospitality tenders. |
| Bonded Warehouse Network Buildout | Jebel Ali and King Abdullah Port proximity accelerates giga-project delivery timelines. |
| Digital Specification Platform Launch | BIM-integrated libraries capture architect pre-qualification during Riyadh schematic phases. |
| Certified Installer Training Program | Hot-weld technician pipelines address Bahrain and Oman healthcare project bottlenecks. |
| Backward Integration into PVC Compounding | In-house resin processing absorbs Strait of Hormuz freight volatility and margin compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary fieldwork, including hospitality development procurement directors at Neom and Red Sea Project, healthcare facility materials consultants under Saudi Arabia's Health Sector Transformation Program, vinyl flooring distribution executives at Dubai and Riyadh showroom networks, and calendering plant managers at Asian manufacturing clusters. Secondary validation drew from Saudi Standards, Metrology and Quality Organization technical regulations, Dubai Municipality green building documentation, Qatar GSAS certification databases, and customs manifests through Jebel Ali and King Abdullah Port. Bottom-up volume triangulation across product type, installation method, and end-use vertical reconciled against top-down macroeconomic drivers.
Calibration anchored quantitative outputs to observed specification patterns across the analysis window, with segmentation modeling across luxury vinyl tile, sheet vinyl, and composite systems by installation method and end-user industry. CAGRs derived from elasticity-adjusted demand curves incorporating giga-project construction pipelines, healthcare infrastructure spend, and residential housing completion rates. Industry-specific forecast inputs included LEED and GSAS certification adoption curves, click-lock system penetration rates in Saudi master-planned communities, and welded-seam technician pool expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in oil price volatility, construction labor availability, or Strait of Hormuz shipping disruptions would shift the trajectory. Forecasts reflect assumptions around regulatory alignment timelines and giga-project execution schedules. Cross-checking against Dubai Municipality building permit data and Saudi Ministry of Housing completion statistics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Resin Dispersion Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Metallocene Polyolefin Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Flame Retardant Thermoplastics Market