
 High-Speed Production Inkjet Printer Paper Market | 2026-2036
High-Speed Production Inkjet Printer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
High-Speed Production Inkjet Printer Paper Market Analytics
The EU Green Deal is restructuring fiber sourcing requirements across European paper supply chains. International Paper Company leverages its North American pulp network to sustain coated paper output for commercial printers. Mondi Group anchors Central European supply through integrated kraft pulp operations. Nippon Paper Industries Co., Ltd. competes on specialty grades engineered for aqueous inkjet absorption.
High-speed production inkjet printer paper denotes substrate engineered for continuous-feed inkjet systems operating above 300 feet per minute, incorporating controlled porosity and surface chemistry to prevent ink bleed while enabling rapid drying. Its primary purpose serves variable-data print runs requiring offset-comparable quality at digital economics. Uncoated paper dominates volume in direct mail applications where postal weight optimization matters. Coated paper captures premium margin pools in advertising materials demanding photographic reproduction fidelity. Specialty paper extends fastest in packaging materials as inkjet presses penetrate corrugated and folding-carton segments.
The EPA regulates pulp mill effluent discharge under Cluster Rules that elevate bleached fiber costs for US manufacturers. REACH compliance in Europe constrains optical brightening agent formulations used in coated grades. Japan's METI promotes recycled content targets that In-Plant Printers must document in public-sector procurement. Stakeholders must monitor how divergent chemical compliance regimes between EPA, ECHA, and METI reshape cross-border grade standardization and sourcing economics.
Market Dynamics
The EU Green Deal and F-Gas Regulation are forcing fiber sourcing and coating chemistry overhauls across European supply chains, while commercial printer capacity expansions in Germany, Japan, and the United States pull substrate volumes toward aqueous inkjet compatibility.
Growth Catalysts
- Regulatory push for sustainable fiber:The EU Green Deal mandates deforestation-free supply chains, accelerating certified pulp adoption in coated paper grades destined for German commercial printers.
- Packaging inkjet penetration:Corrugated and folding-carton converters are installing continuous-feed inkjet systems above 300 feet per minute, creating substrate demand for controlled-porosity specialty grades.
- Variable-data economics:Direct mail operators in the United States prioritize uncoated paper for postal weight optimization while maintaining offset-comparable image quality.
Market Restraints
- Bleached fiber cost elevation:EPA Cluster Rules on pulp mill effluent discharge tighten bleaching process economics for US manufacturers serving coated paper segments.
- Coating chemistry constraints:REACH compliance in Europe restricts optical brightening agent formulations, limiting coated grade brightness specifications for premium advertising applications.
- Recycled content mandates:Japan's METI recycled documentation requirements for public-sector procurement create fiber sourcing friction for in-plant printers.
Strategic Opportunities
- Underpenetrated packaging verticals:Food-contact folding cartons in Japan present white space for barrier-coated inkjet substrates meeting PMDA migration limits.
- Carbon accounting differentiation:The EU Green Deal's embedded emissions reporting creates premium positioning for mills with integrated kraft pulp and renewable energy.
- Digital-physical convergence:Web-to-print platforms and automated finishing lines are compressing job turnaround times, favoring regional substrate warehouses over mill-direct fulfillment.
Industry Challenges
- Cross-border grade standardization:Divergent chemical compliance regimes between EPA, ECHA, and METI force mills to maintain parallel formulation portfolios, complicating inventory management.
- Press-substrate matching complexity:Rapid inkjet press generation turnover requires continuous R&D coordination between substrate engineers and OEM fluid chemists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Speed Production Inkjet Printer Paper Market |
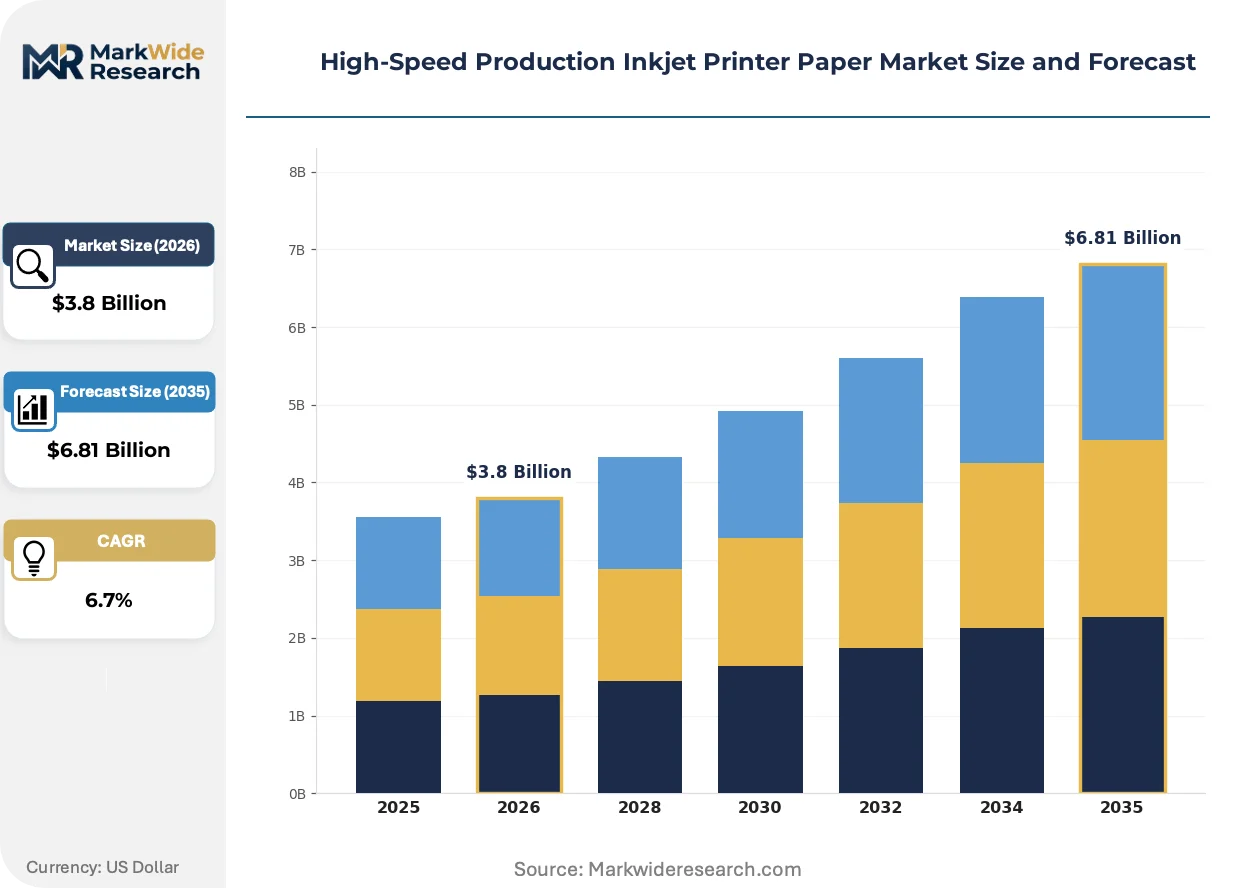
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Paper, Uncoated Paper, Specialty Paper, Recycled Paper End User: Commercial Printers, In-Plant Printers, Publishing Houses, Educational Institutions Application: Advertising Materials, Books, Direct Mail, Packaging Materials Size: A4, A5, Legal, Custom Sizes |
| Companies Covered | Domtar Corporation, International Paper Company, Mondi Group, Sappi Limited, Stora Enso Oyj, Nippon Paper Industries Co., Ltd., UPM-Kymmene Corporation, Verso Corporation, Oji Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Speed Production Inkjet Printer Paper Market Evolving Landscape
Substrate engineering is converging with press chemistry and regulatory tracking systems, compressing the traditional specification cycle from months to weeks.
Surface treatment technology is modularizing around pre-coat and top-coat layers that can be tuned independently for porosity, brightness, and barrier properties. Commercial printers in the United States are adopting these configurable substrates to handle mixed job portfolios without press downtime. This modularity is compressing the minimum economical run length for coated applications.
REACH restrictions on perfluorinated compounds are eliminating legacy grease-resistant coatings in European food packaging grades. Mills serving German corrugated converters are pivoting to bio-based barrier chemistries certified under EFSA migration testing protocols. The transition is accelerating qualification timelines for folding-carton substrates.
Specification authority is migrating from procurement departments to pressroom operators who test substrate-ink-fluid combinations in real production environments. North American commercial printers now demand sample rolls with full chemical disclosure sheets before volume commitments. This behavioral shift is fragmenting the traditional mill-distributor-printer channel structure.
High-Speed Production Inkjet Printer Paper Market Segmentation
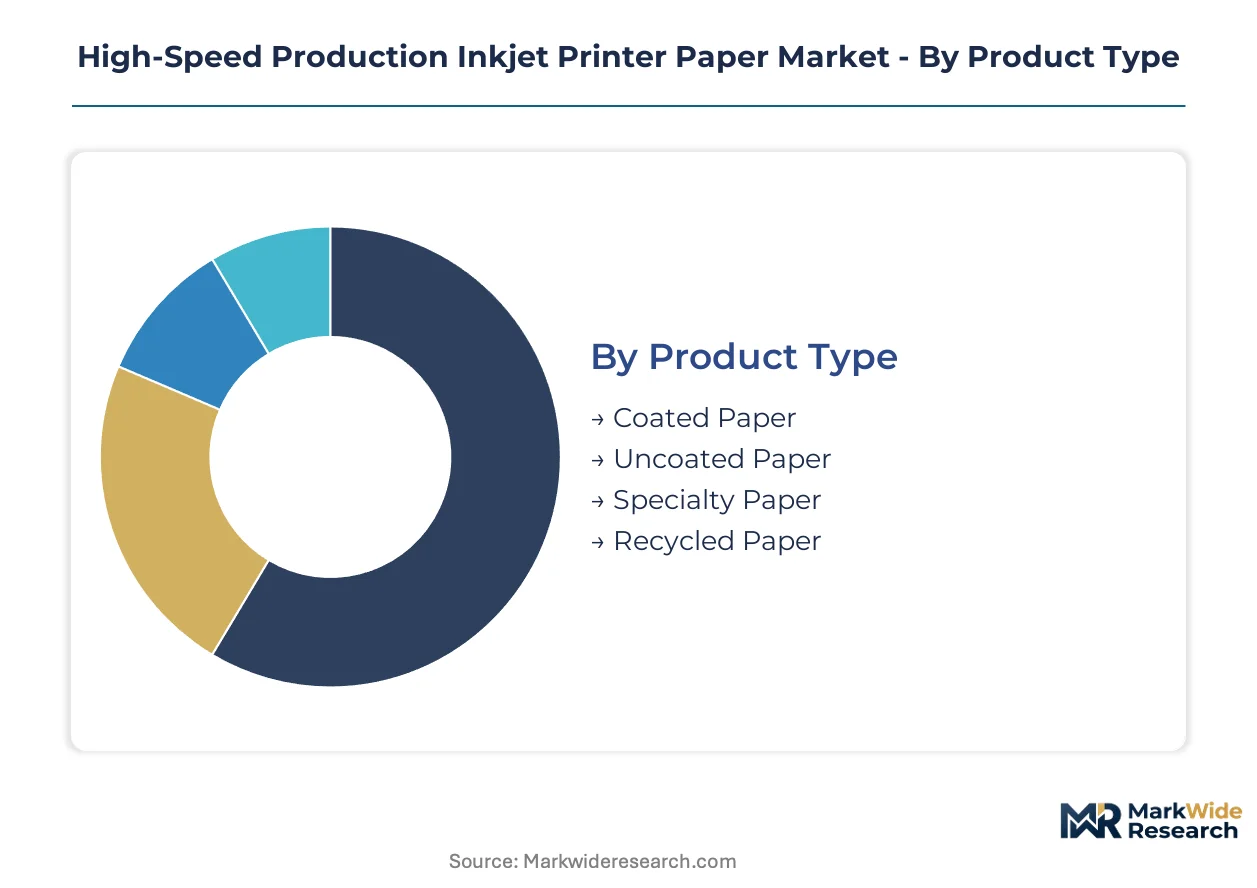
Substrate specification varies dramatically across press configurations and end-use requirements. Each segmentation axis reveals distinct margin structures, regulatory exposures, and supply chain configurations that shape procurement strategy.
Product Type:
Surface chemistry and fiber engineering define performance thresholds for continuous-feed inkjet systems operating above 300 feet per minute.
- Coated Paper:Clay and calcium carbonate surface treatments control porosity for photographic reproduction fidelity. German commercial printers specify these grades for premium advertising work despite REACH constraints on optical brightening agents.
- Uncoated Paper:Engineered fiber orientation and internal sizing deliver rapid ink absorption without coating weight. United States direct mail operators dominate consumption here, prioritizing postal weight optimization over brightness specifications.
- Specialty Paper:Barrier-coated formulations for corrugated and folding-carton inkjet applications.
- Recycled Paper:Post-consumer fiber blends meeting Japan METI documentation requirements for public-sector procurement.
Uncoated paper leads on scale; specialty paper leads on momentum.
End User:
Procurement authority and specification complexity diverge sharply across organizational types.
- Commercial Printers:Independent operations in Germany, Japan, and the United States drive aqueous inkjet capacity expansion. These buyers negotiate directly with mills for configurable substrate portfolios supporting mixed job schedules.
- In-Plant Printers:Corporate and institutional facilities face Japan's METI recycled content mandates for public-sector contracts. Documentation burdens favor suppliers with certified chain-of-custody systems.
- Publishing Houses:Short-run book manufacturing demands consistent sheet-to-sheet moisture content for binding compatibility.
- Educational Institutions:Cost-constrained procurement with limited specification authority.
Commercial printers concentrate volume purchasing power; in-plant printers concentrate compliance-driven premium positioning.
Application:
End-use performance requirements cascade back through coating weight, brightness targets, and barrier specifications.
- Advertising Materials:Photographic reproduction fidelity demands coated substrates with controlled gloss levels. REACH restrictions on perfluorinated compounds are eliminating legacy grease-resistant finishes in European food-contact advertising inserts.
- Direct Mail:Postal weight optimization drives uncoated paper specification across high-volume United States operations. Variable-data economics require rapid drying chemistry to enable inline finishing.
- Books:Opacity and bulk specifications for perfect binding compatibility.
- Packaging Materials:Corrugated and folding-carton converters in Japan are installing continuous-feed systems, creating demand for barrier-coated grades meeting PMDA migration limits.
Direct mail anchors current volume; packaging materials are climbing the fastest.
Size:
Format standardization versus customization reflects regional press fleet configurations and finishing equipment constraints.
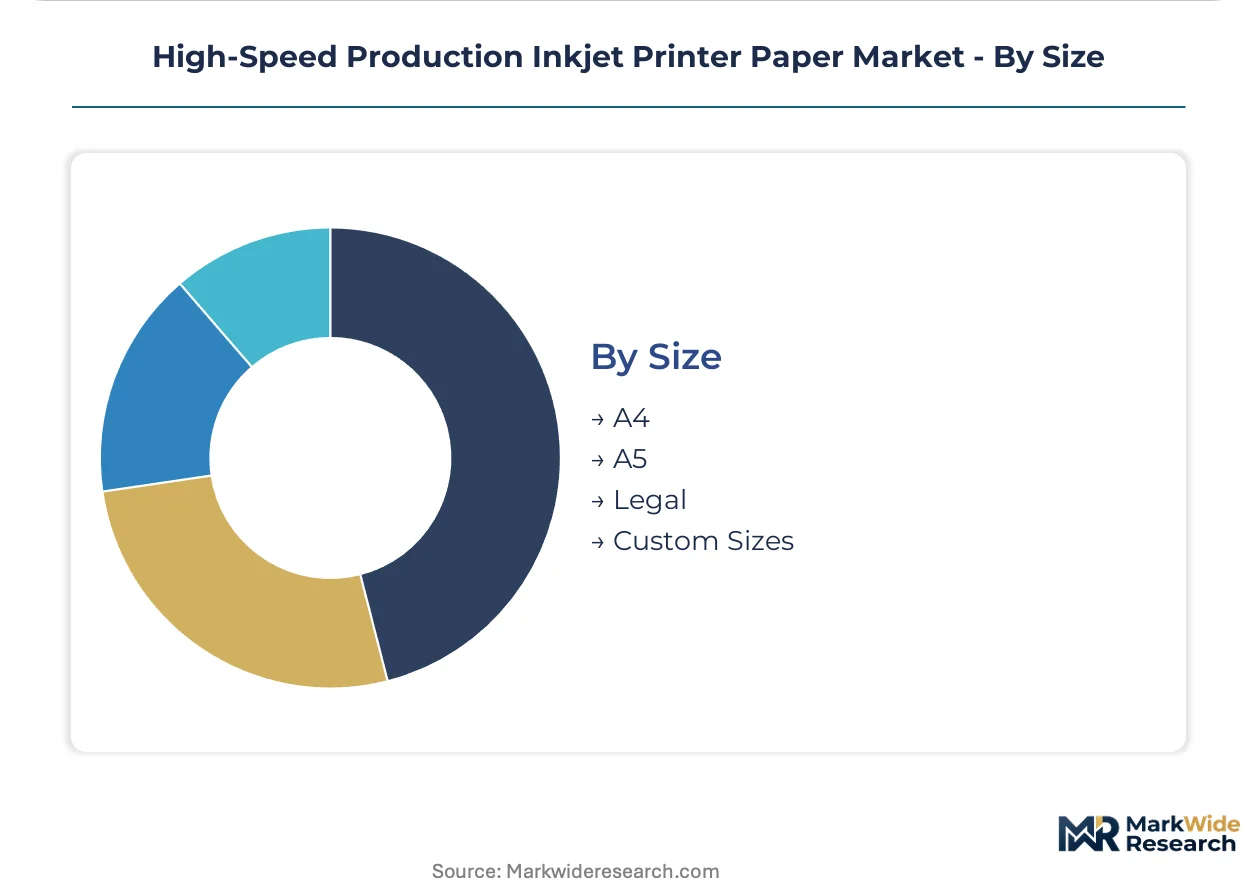
- A4:Dominant format for European commercial printing, aligned with ISO standard finishing lines.
- A5:Specialized direct mail and booklet applications with dedicated cutter configurations.
- Legal:United States-specific format for financial and legal document production.
- Custom Sizes:Web-to-print platforms are compressing turnaround times, favoring regional substrate warehouses with slitting capability over mill-direct fulfillment.
A4 leads on standardization economics; custom sizes lead on service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled press operators and substrate engineers cluster in Germany, Japan, and the United States where high-speed inkjet installations exceed 300 feet per minute. These talent concentrations anchor regional supply chain configurations and R&D coordination between mills and OEMs.
United States
Commercial printers in the Midwest and Southeast dominate uncoated paper consumption for direct mail weight optimization. EPA Cluster Rules on pulp mill effluent discharge elevate bleached fiber costs for coated grade producers. Chicago and Atlanta host dense clusters of variable-data print houses negotiating configurable substrate portfolios.
Germany
Premium advertising work drives coated paper specification despite REACH constraints on optical brightening agents. The EU Green Deal mandates deforestation-free supply chains, accelerating certified pulp adoption across Baden-Württemberg and North Rhine-Westphalia. Düsseldorf anchors commercial printer capacity expansion with direct mill relationships.
Japan
Corrugated and folding-carton converters in the Kanto region are installing continuous-feed inkjet systems above 300 feet per minute. METI recycled content documentation requirements for public-sector procurement create fiber sourcing friction for in-plant printers. Tokyo-Osaka industrial corridors concentrate specialty grade demand for aqueous inkjet absorption.
China
Packaging inkjet penetration accelerates in the Yangtze River Delta and Pearl River Delta as converters seek digital economics for short-run corrugated. Dual carbon goals tighten energy intensity standards for integrated pulp-paper operations. Shanghai and Shenzhen host emerging substrate qualification labs coordinating with press OEMs.
High-Speed Production Inkjet Printer Paper Market Competitive Landscape
Capital-heavy integrated pulp producers compete with asset-light specialty converters for specification authority in high-speed inkjet substrates. The market structure concentrates around North American and European integrated mills with captive fiber supply, while Asian specialists compete on engineered absorption chemistry. Three archetypes dominate: integrated kraft pulp operators, coated specialty converters, and barrier-coating innovators. Competitive moves center on backward integration into certified fiber sourcing and geographic expansion through regional slitting and warehousing networks.
Among North American integrated producers, International Paper Company and Domtar Corporation exemplify the scale-driven archetype with captive pulp networks sustaining coated paper output. Verso Corporation occupies a position within the specialty converter tier, representing asset-light operators focused on configurable substrate portfolios. Nippon Paper Industries Co., Ltd. anchors the Asian specialist segment, exemplifying mills competing on aqueous inkjet absorption engineering rather than fiber integration depth.
| Leading Market Players |
|---|
| Domtar Corporation |
| International Paper Company |
| Mondi Group |
| Sappi Limited |
| Stora Enso Oyj |
| Nippon Paper Industries Co., Ltd. |
| UPM-Kymmene Corporation |
| Verso Corporation |
| Oji Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Continuous-feed inkjet press generation turnover above 300 feet per minute is compressing substrate qualification cycles while concentrating purchasing power among German, Japanese, and United States commercial printers with direct mill relationships. This technology cadence simultaneously elevates R&D cost recovery requirements for coated grade producers and rewards regional substrate warehouses with slitting capability over mill-direct fulfillment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates photographic reproduction fidelity grades from postal weight-optimized uncoated and commodity recycled blends. Price differentiation hinges on REACH-compliant optical brightening agent certification and volume scale commitments from Midwest direct mail operators. Pricing pressure stems from EPA Cluster Rules elevating bleached fiber costs for coated segment producers. In-plant printers facing Japan METI documentation requirements show least price sensitivity; high-volume United States direct mail houses anchor the economy tier with maximum pressure.
Supply Chain Analysis
Single-source vulnerability sits with bleached kraft pulp supply from integrated North American mills serving coated paper segments. Geographic concentration centers on United States, Germany, and Japan where commercial printer clusters anchor demand. Raw material dependencies encompass certified deforestation-free fiber, calcium carbonate surface treatments, and aqueous inkjet-compatible sizing chemistries. Tariff exposure on European optical brightening agent formulations under REACH restrictions presents structural risk. Distribution runs through regional substrate warehouses with modular slitting capability rather than mill-direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as packaging inkjet penetration in corrugated and folding-carton segments shifts specification authority toward barrier-coated specialty grades with PMDA migration compliance.
For Market Incumbents: Deploy backward integration into certified pulp networks to defend coated grade margins against EPA Cluster Rules cost elevation. Anchor capacity in Baden-Württemberg and North Rhine-Westphalia to capture EU Green Deal deforestation-free supply chain premiums. Channel control through regional slitting warehouses counters asset-light specialty converters fragmenting procurement relationships. For New Entrants and Emerging Players: Barrier-coating chemistry for food-contact folding cartons in Japan's Kanto region offers the most penetrable white space given PMDA migration limit compliance gaps among incumbent integrated mills. Web-to-print platform partnerships provide direct go-to-market access without traditional distributor relationships. Modular surface treatment technology licensing compresses capital requirements versus greenfield mill construction. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light specialty converters with configurable substrate portfolios rather than integrated kraft pulp operators. Five-to-ten year viability favors mills with captive renewable energy and EFSA-certified bio-based barrier chemistry pipelines. The signal to watch is qualification timeline compression for folding-carton substrates as corrugated converters accelerate continuous-feed inkjet adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Fiber | Captive pulp supply insulates coated grade producers from EPA Cluster Rules cost volatility. |
| Regional Slitting Warehouse Network | Modular fulfillment infrastructure compresses turnaround times for web-to-print platform partners. |
| Bio-Based Barrier Chemistry Certification | EFSA migration testing protocols qualify folding-carton substrates for European food packaging conversion. |
| Modular Surface Treatment Platform | Independent pre-coat and top-coat tuning enables mixed job portfolios without press downtime. |
| Direct Mill-Printer Procurement Relationships | Bypassing distributor channels captures specification authority migrating to pressroom operators. |
Research Methodology
Bottom-up commercial printer capacity modeling reconciled against top-down integrated pulp mill output tracking forms the analytical core of this study. Primary interviews with pressroom operators, substrate engineers at coated specialty converters, procurement leads at direct mail houses, and regulatory compliance officers at in-plant printers were cross-validated against secondary sources including EPA effluent discharge filings, ECHA REACH registration databases, Japan METI recycled content documentation, and customs trade data for bleached kraft pulp flows.
Historical trendline analysis of aqueous inkjet press installations and substrate qualification timelines informed projection framework construction across the analysis window. Segmentation dimensions encompassed surface chemistry tier, end-user procurement authority, application performance requirements, and regional regulatory cluster. CAGRs were derived from elasticity modeling of press capacity expansion against substrate consumption intensity, incorporating fiber cost pass-through coefficients and coating chemistry compliance cost estimates.
The model holds under stable regulatory enforcement of EPA Cluster Rules, REACH restrictions, and METI documentation requirements; deviation in F-Gas Regulation scope expansion or EU Green Deal embedded emissions reporting acceleration would shift coated grade margin structures. Forecasts reflect documented assumptions regarding press OEM-substrate engineer R&D coordination cycles and corrugated converter adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Specialty Paper Market
Paper Products
Stone Paper Market
Paper Products
Europe Thermal Paper Market
Paper Products
Carbonless Paper Market
Paper Products
Liquid Paperboard Market
Paper Products
Plywood Market
Paper Products
Pp Synthetic Paper Market
Paper Products
Saturated Kraft Paper Market
Paper Products
Global Cellulose Sponge Market
Paper Products
North America Thermal Paper Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Europe Medium-Density Fiberboard Market
Paper Products
Global Pulp and Paper Machinery Market
Paper Products
Chemical Cellulose Market
Paper Products
Uncoated Fine Paper Market
Paper Products
Leatheroid Paper Market