
 Orthophthalic Resins Market | 2026-2036
Orthophthalic Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Orthophthalic Resins Market Analytics
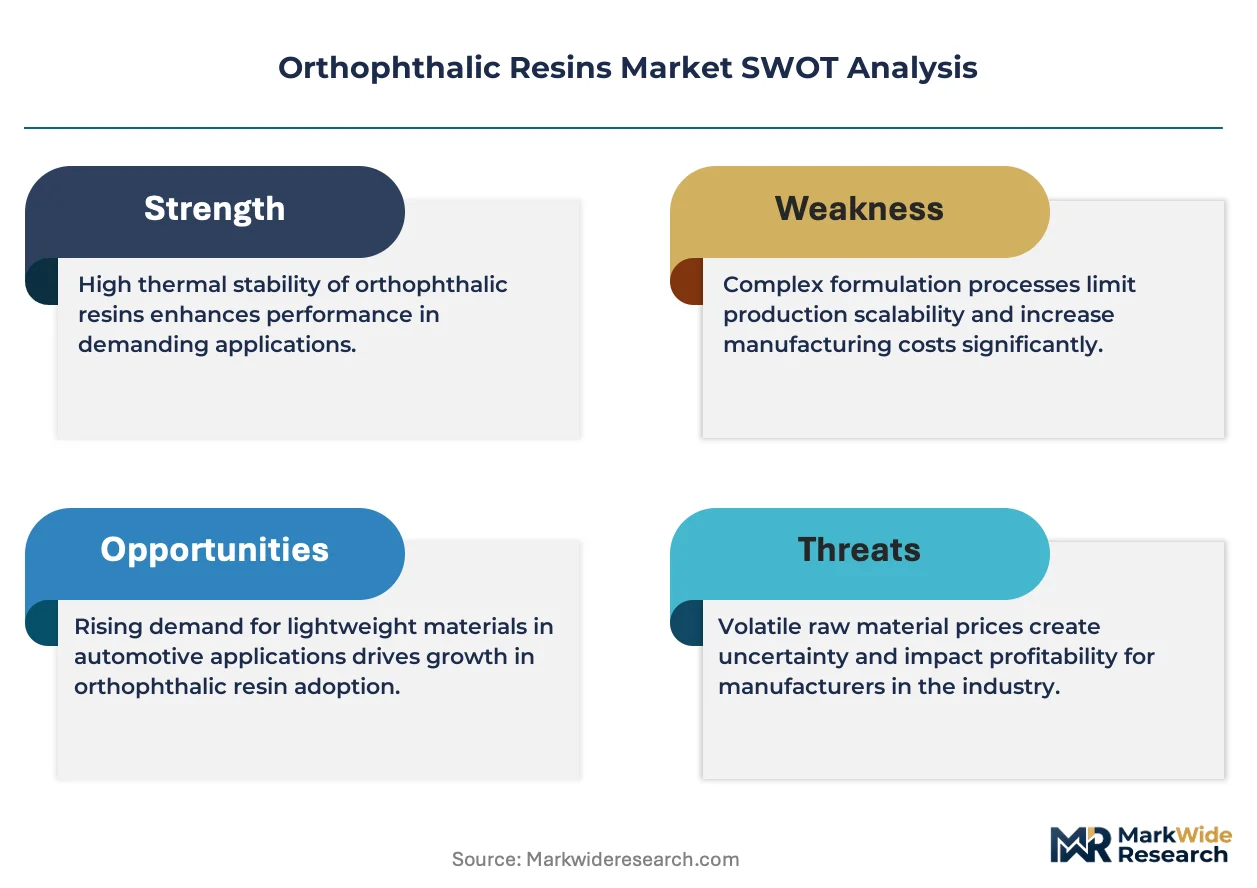
Asset-light toll manufacturing and third-party resin compounding arrangements is fragmenting competitive boundaries in orthophthalic polyester supply. DSM leverages captive upstream phthalic anhydride supply to sustain margin control across European formulations. Ashland competes through specialized corrosion-resistant grades for chemical processing infrastructure. INEOS Group anchors volume leadership via integrated marine and construction distribution networks in Northern Europe.
Orthophthalic resins are unsaturated polyester formulations synthesized from phthalic anhydride and maleic anhydride reacted with glycols, yielding viscous liquids with styrene monomer dilution typically between 35% and 45% by weight; these thermosetting polymers cure through free-radical crosslinking to produce fiber-reinforced composites for structural applications requiring moderate chemical resistance and cost efficiency. The unsaturated polyester product category dominates volume throughput across construction moldings and standard marine laminates. Vinyl ester formulations command premium positioning in corrosive industrial environments where epoxy alternatives prove cost-prohibitive. Marine and transportation applications channel the fastest structural expansion as shipbuilders and rail component manufacturers substitute metal with fiber-reinforced polymer assemblies.
EPA air quality standards and REACH chemical registration protocols in the United States and European Union impose styrene emission thresholds that compel reformulation toward low-styrene or styrene-free alternatives. China's MEE enforces parallel VOC discharge limits at manufacturing facilities, creating compliance complexity for multinational resin suppliers operating across jurisdictions. Stakeholders must monitor evolving cross-border chemical hazard classifications that threaten to restrict orthophthalic chemistries in consumer-facing applications regardless of industrial demand trajectories.
Market Dynamics
Styrene emission thresholds under EPA air quality standards and REACH protocols are forcing wholesale reformulation of orthophthalic polyester systems, compressing margins for suppliers while opening substitution pathways for vinyl ester and epoxy alternatives.
Growth Catalysts
- Marine composite hull demand:Shipbuilders in Vietnam's industrial zones near Ho Chi Minh City are substituting steel with fiber-reinforced polymer assemblies for cargo vessels and leisure craft.
- REACH chemical registration protocols:Compliance-driven R&D spending is accelerating low-styrene formulation development across European resin compounders serving chemical processing infrastructure.
- Rail component manufacturing:Transportation OEMs are specifying unsaturated polyester for interior panels and structural seat supports to reduce vehicle weight.
Market Restraints
- Phthalic anhydride input volatility:Captive upstream supply concentrates among integrated petrochemical groups, exposing toll manufacturers to margin squeeze during feedstock price spikes.
- Styrene monomer substitution threat:Methyl methacrylate and dicyclopentadiene diluents are capturing share in premium marine applications where odor and emission controls dominate specification.
- Technical performance ceiling:Orthophthalic chemistries lack the hydrolytic stability and elevated-temperature resistance demanded by offshore oil platform grating and subsea pipeline protection systems.
Strategic Opportunities
- China's dual carbon goals:MEE enforcement of VOC discharge limits at manufacturing facilities is creating first-mover advantage for domestic suppliers with compliant low-emission formulations.
- Construction moldings in Indonesia:Underpenetrated demand for standardized building panels and sanitary fixtures offers volume expansion outside saturated Southeast Asian marine clusters.
- Hybrid epoxy-urethane convergence:Blending technologies that combine orthophthalic cost structures with vinyl ester corrosion resistance are opening specification in industrial tank and pipe markets.
Industry Challenges
- Formulation chemist scarcity:Free-radical polymerization expertise and styrene emission control engineering talent pools are thinning as veteran technicians retire without pipeline replacement.
- Cross-border hazard classification complexity:Divergent chemical registry requirements between EPA, ECHA, and China's MEE are fragmenting product portfolios and extending compliance timelines for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orthophthalic Resins Market |
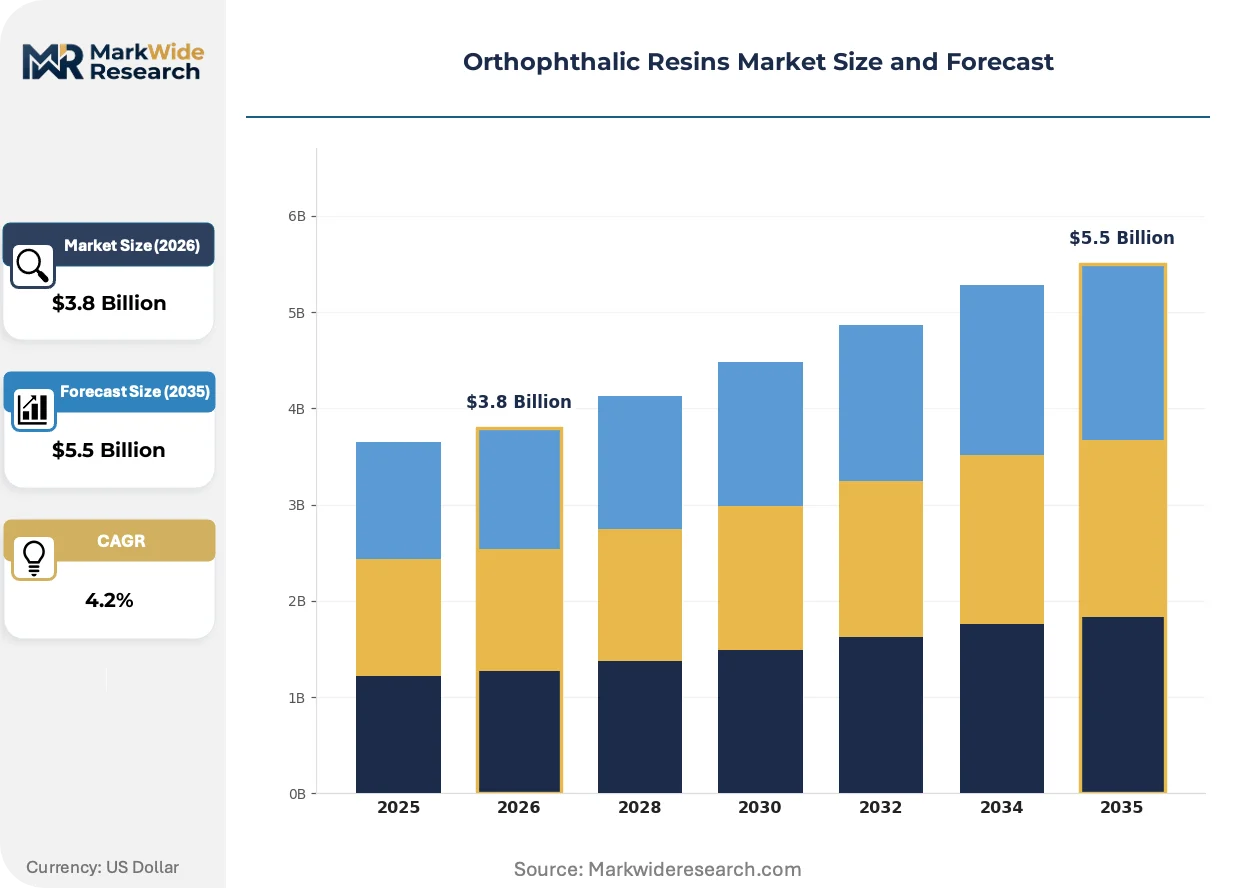
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsaturated Polyester, Vinyl Ester, Epoxy, Polyurethane Application: Construction, Transportation, Marine, Electrical End User: Aerospace, Automotive, Electronics, Building & Construction Distribution Channel: Direct Sales, Distributors, Retailers, Online Sales |
| Companies Covered | DSM, Ashland, Polynt Group, BASF, Scott Bader, AOC, INEOS Group, Dow Chemical, CCP Composites, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orthophthalic Resins Market Evolving Landscape
Digital formulation platforms and predictive curing models are compressing development cycles for customized resin grades, while regulatory pressure on styrene emissions accelerates investment in alternative monomer systems and closed-mold processing technologies.
Low-styrene unsaturated polyester formulations incorporating dicyclopentadiene modification are virtualizing traditional open-mold lamination workflows in Southeast Asian boatyards. Vietnamese and Indonesian shipbuilders are adopting these systems at accelerating pace to preempt GB standards enforcement. This virtualization is compressing the viable market window for conventional high-styrene orthophthalic grades in export-oriented manufacturing zones.
REACH registration requirements for styrene monomer are compelling European formulators to document full supply chain toxicity profiles and exposure scenarios. Industrial consequence includes mandatory reformulation of standard marine laminates and construction moldings previously optimized for cost rather than emission control. Chemical processing infrastructure applications in Germany and the Netherlands are responding fastest, with specification committees rewriting material standards to favor low-styrene alternatives.
Buyers in marine and transportation sectors are consolidating procurement around qualified resin compounders with captive testing and certification capabilities. Distributor networks that previously stocked generic grades are losing share to direct technical service relationships with formulation houses. This concentration is most visible in Northern Europe, where INEOS Group and DSM have integrated distribution with on-site technical support for hull lamination and rail interior projects.
Orthophthalic Resins Market Segmentation
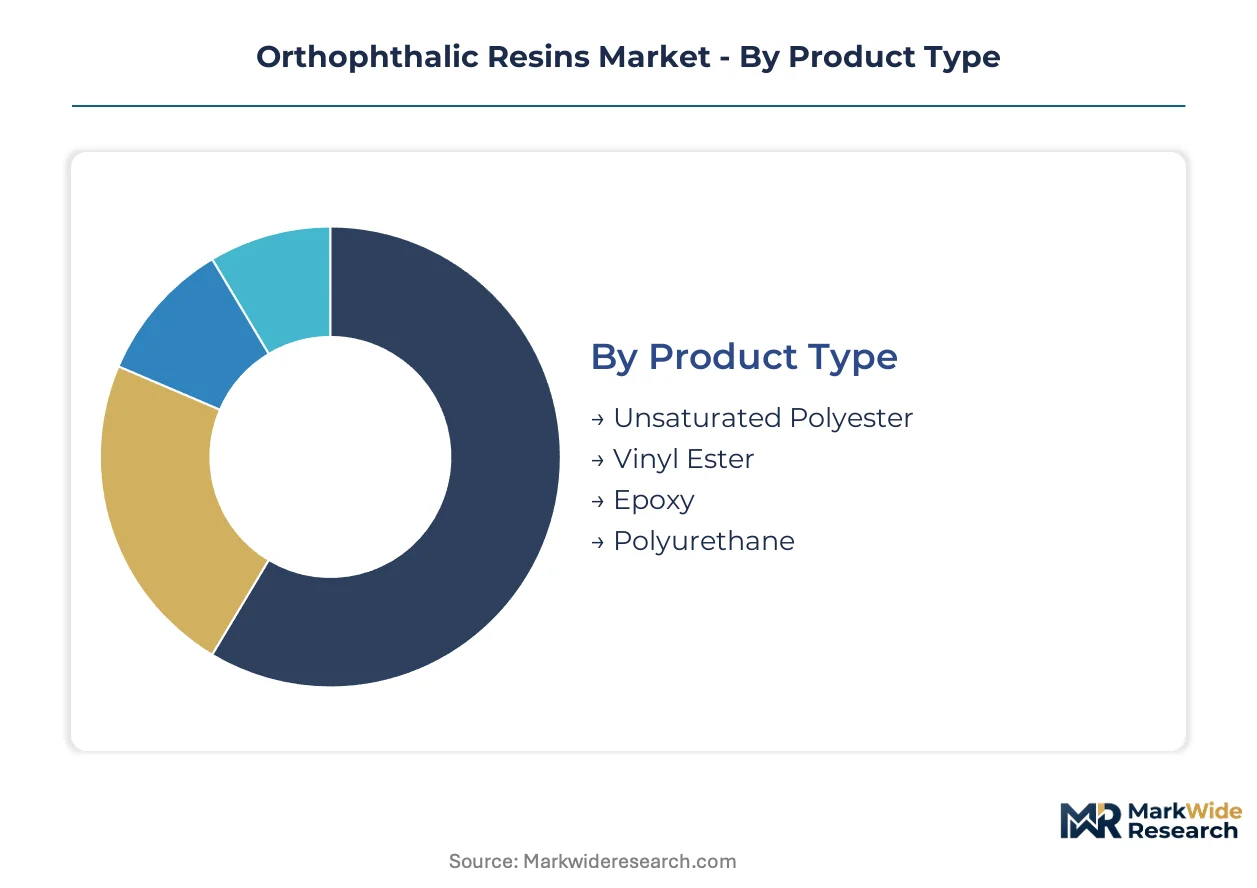
Orthophthalic resin procurement patterns diverge sharply across formulation chemistry and end-use specification, with marine hull laminates cycling inventory monthly while infrastructure moldings operate on quarterly replenishment schedules. Segmentation discipline separates volume-driven commodity grades from corrosion-resistant premium formulations commanding technical service premiums.
Product Type:
Cycle times compress most dramatically in commodity unsaturated polyester, where Vietnamese boatyards turn inventory weekly during peak season, while epoxy-urethane hybrids for chemical processing infrastructure extend to six-month procurement windows due to qualification protocols.
- Unsaturated Polyester:Formulations synthesized from phthalic anhydride and maleic anhydride with 35-45% styrene dilution dominate construction moldings and standard marine laminates. Demand concentrates in Vietnam's industrial zones near Ho Chi Minh City as shipbuilders substitute steel hulls with fiber-reinforced polymer assemblies for cargo vessels.
- Vinyl Ester:Methacrylate-terminated epoxy backbones deliver superior hydrolytic stability and elevated-temperature resistance for corrosive industrial environments. Chemical processing infrastructure in Germany and the Netherlands is rewriting material standards to favor these grades over orthophthalic alternatives where emission controls dominate specification.
- Epoxy:Diglycidyl ether of bisphenol-A formulations serve subsea pipeline protection and offshore platform grating where orthophthalic chemistries fail.
- Polyurethane:Isocyanate-cured systems penetrate rail interior panels and structural seat supports seeking weight reduction beyond polyester capabilities.
Unsaturated polyester dominates installed base. Vinyl ester is where expansion concentrates.
Application:
Cost tier stratification separates marine specifications requiring certification-grade formulations from construction moldings optimized for raw material cost per kilogram.
- Construction:Standardized building panels and sanitary fixtures in Indonesia utilize orthophthalic resins for cost-efficient fiber-reinforced moldings. Underpenetrated demand outside saturated Southeast Asian marine clusters offers volume expansion for suppliers with compliant low-emission formulations.
- Marine:Composite hull manufacturing for cargo vessels and leisure craft drives fastest structural expansion as Vietnamese and Indonesian shipbuilders adopt closed-mold processing to preempt China's GB standards enforcement on VOC emissions.
- Transportation:Rail component OEMs specify unsaturated polyester for interior panels and structural seat supports to reduce vehicle weight.
- Electrical:Insulation-grade formulations serve transformer housings and switchgear enclosures requiring flame-retardant certification.
Construction commands volume throughput. Marine is climbing the fastest.
End User:
Customer type fragmentation separates qualified resin compounders with captive testing capabilities from distributors losing share to direct technical service relationships.
- Building & Construction:Standardized panel manufacturers in Indonesia and Vietnam procure orthophthalic resins through distributor networks, though procurement is shifting toward direct formulation house relationships for certified low-styrene grades.
- Automotive:Tier suppliers specify unsaturated polyester for interior structural components as OEMs pursue weight reduction targets.
- Aerospace:Secondary structure applications utilize epoxy-dominant formulations with orthophthalic resins limited to non-structural moldings.
- Electronics:Encapsulation and insulation applications demand flame-retardant grades with regulatory compliance documentation.
Building & Construction anchors volume demand. Automotive is gaining share fastest.
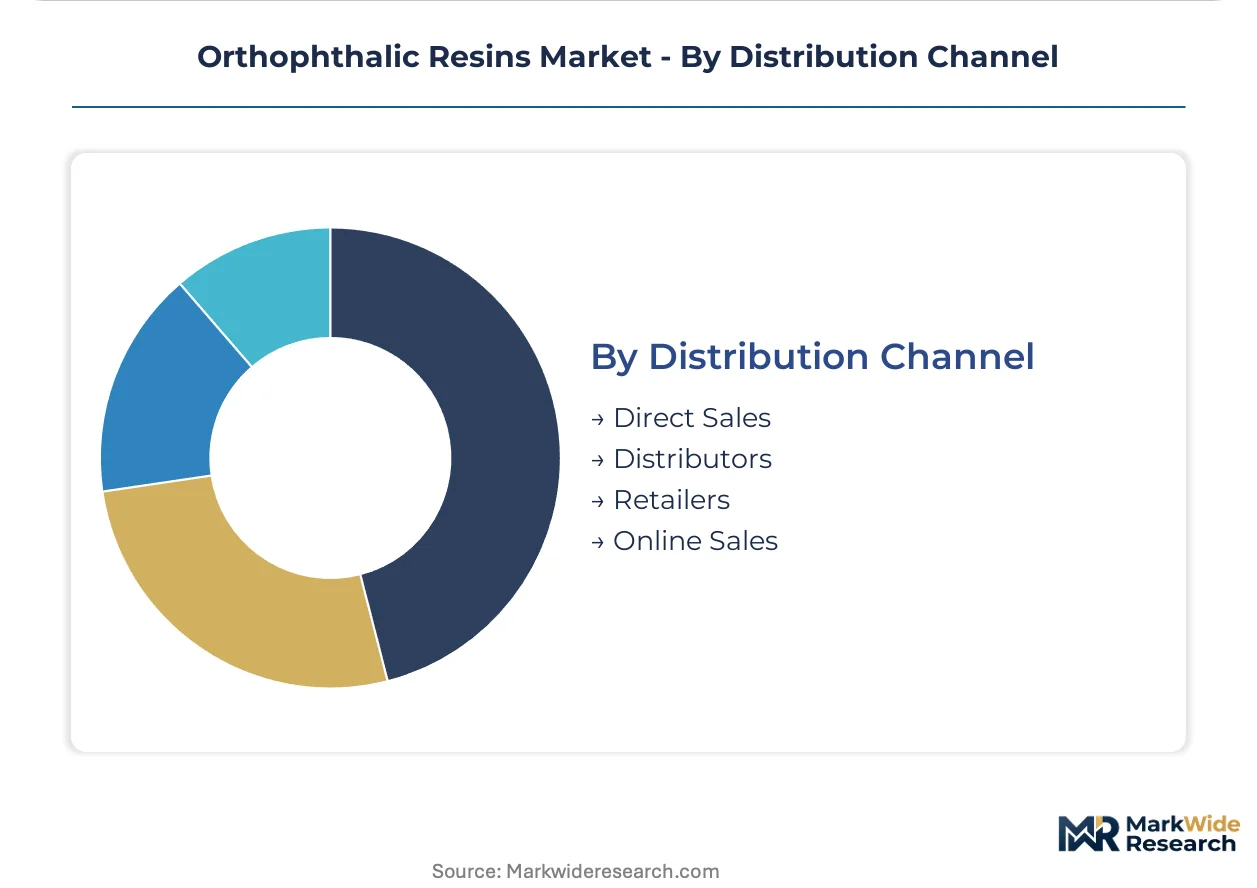
Distribution Channel:
Supply concentration favors direct technical service models in Northern Europe, while Southeast Asian markets retain distributor intermediaries for fragmented boatyard procurement.
- Direct Sales:INEOS Group and DSM have integrated distribution with on-site technical support for hull lamination and rail interior projects in Germany and the Netherlands, consolidating procurement around qualified resin compounders with captive testing capabilities.
- Distributors:Generic grade stocking networks in Vietnam and Indonesia are losing share to direct relationships as specification committees rewrite material standards.
- Retailers:Small-volume repair and maintenance applications in marine aftermarket channels.
- Online Sales:Emerging procurement pathway for standardized grades with documented certification.
Direct sales dominates premium specification. Distributors retain commodity volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in European formulation houses serving REACH-compliant chemical processing infrastructure, while Vietnamese boatyards operate on thin margins dictated by export competitiveness to EU and US marine markets.
China
GB standards on volatile organic compound emissions are forcing reformulation across Pearl River Delta manufacturing zones. MEE enforcement creates first-mover advantage for domestic suppliers with compliant low-emission formulations. Marine composite production clusters in Guangdong province are adopting closed-mold processing to preempt regulatory penalties.
Germany
Chemical processing infrastructure in the Rhine-Ruhr region is rewriting material standards to favor low-styrene alternatives. REACH registration protocols compel full supply chain toxicity documentation from BASF and specialty compounders. Specification committees in North Rhine-Westphalia are accelerating corrosion-resistant grade adoption for industrial tank applications.
Vietnam
Shipbuilders in industrial zones near Ho Chi Minh City are substituting steel hulls with fiber-reinforced polymer assemblies for cargo vessels and leisure craft. Export-oriented manufacturing must preempt China's GB standards enforcement on VOC emissions. Marine composite hull demand drives fastest structural expansion across Southeast Asian supply chains.
United States
EPA air quality standards impose styrene emission thresholds that compress margins for suppliers while opening substitution pathways. Construction moldings in Texas and Florida utilize orthophthalic resins for cost-efficient fiber-reinforced building panels. Rail component OEMs specify unsaturated polyester for interior structural components to reduce vehicle weight.
Indonesia
Underpenetrated demand for standardized building panels and sanitary fixtures offers volume expansion outside saturated marine clusters. Domestic procurement runs through distributor networks serving fragmented construction contractors in Java and Sumatra. Direct technical service relationships are displacing generic grade stocking as specification committees tighten emission standards.
Orthophthalic Resins Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream feeding formulation houses with captive phthalic anhydride supply. Market structure tilts toward consolidation among integrated petrochemical groups with backward control over maleic anhydride and glycol inputs. Three archetypes dominate: European REACH-compliant formulators, Asian export-oriented compounders, and North American construction-grade suppliers. Competitive moves concentrate on M&A for captive testing capabilities and geographic expansion into Vietnam's industrial zones.
Among European integrated specialists, DSM leverages captive upstream phthalic anhydride supply to sustain margin control across formulations. INEOS Group anchors volume leadership via integrated marine and construction distribution networks in Northern Europe. Ashland occupies a position exemplifying specialized corrosion-resistant grade development for chemical processing infrastructure.
| Leading Market Players |
|---|
| DSM |
| Ashland |
| Polynt Group |
| BASF |
| Scott Bader |
| AOC |
| INEOS Group |
| Dow Chemical |
| CCP Composites |
| Others |
Value Network & Pricing Analysis
Singapore-Johor freight corridors carry phthalic anhydride and maleic anhydride feedstocks from integrated petrochemical complexes to Vietnamese compounding facilities, with freight cost dynamics amplifying margin pressure for toll manufacturers lacking captive upstream supply while enabling price differentiation between REACH-compliant European formulators and export-oriented Asian compounders.
Pricing Analysis
Configured-to-order pricing for corrosion-resistant vinyl ester grades commands substantial premiums over standard unsaturated polyester formulations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale, with ISO-compliant low-styrene formulations extracting technical service premiums from chemical processing infrastructure buyers. Price erosion runs through commodity construction grades as Indonesian panel manufacturers consolidate procurement around direct supplier relationships. Marine hull laminators in Vietnam exhibit highest price sensitivity, while German industrial tank specifiers prioritize performance over unit cost.
Supply Chain Analysis
Extended payment terms from integrated petrochemical groups to Southeast Asian toll manufacturers are compressing working capital for non-integrated compounders. Supply concentrates in China, Germany, and the Netherlands for phthalic anhydride and maleic anhydride feedstocks, with formulations drawing from styrene monomer, glycols, and specialty methacrylate-terminated epoxy backbones. Single-source vulnerability concentrates around Dutch and German integrated producers controlling maleic anhydride supply. Distribution runs through direct technical service relationships in Northern Europe and distributor networks in Vietnam and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Free-radical polymerization expertise and styrene emission control engineering talent pools are thinning as veteran technicians retire, creating persistent capability gaps that reshape competitive advantage toward firms with captive formulation R&D and testing infrastructure.
For Market Incumbents: Pre-empt methyl methacrylate and dicyclopentadiene substitution threats by accelerating low-styrene formulation certification for marine export markets. Capture backward integration into maleic anhydride supply through long-term offtake agreements with Rhine-Ruhr petrochemical complexes. Defend margin position through direct technical service relationships displacing Vietnamese distributor networks. For New Entrants and Emerging Players: Mid-market construction moldings in Indonesia represent the most penetrable entry point, with underpenetrated demand for standardized building panels and sanitary fixtures outside saturated Southeast Asian marine clusters. Vietnam's industrial zones near Ho Chi Minh City offer secondary beachhead through toll manufacturing arrangements serving export-oriented boatyards. Establish go-to-market presence through qualification for China's GB standards compliance ahead of MEE enforcement acceleration. For Investors and Strategic Acquirers: Carve-out targets emerge from European chemical majors divesting non-core resin formulation divisions lacking REACH registration scale. Long-term viability hinges on positioning within low-emission formulation transitions rather than commodity orthophthalic volume exposure. Watch for MEE enforcement acceleration in Guangdong province as inflection indicator for compliant formulation premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Maleic Anhydride | Captive feedstock supply insulates DSM and INEOS from Pearl River Delta price volatility. |
| Low-Styrene Formulation Certification | REACH-compliant grades unlock German chemical processing infrastructure specification committees. |
| Direct Technical Service Expansion | On-site hull lamination support consolidates procurement around qualified resin compounders in Northern Europe. |
| Closed-Mold Processing Technology Transfer | Vietnamese boatyard adoption preempts China's GB standards enforcement penalties. |
| Joint Venture in Indonesian Construction | Local compounding capacity captures underpenetrated building panel demand in Java and Sumatra. |
Research Methodology
Desk research of customs trade data, Cefic industry reports, and SEC 10-K filings preceded structured interviews with plant managers at Vietnamese boatyards, procurement leads at German chemical processing OEMs, distribution channel partners in Indonesia, and technical R&D directors at European formulation houses. Bottom-up volume modeling triangulated against top-down value estimates derived from trade flow analysis and petrochemical capacity disclosures.
Assumptions held fixed include GB standards enforcement timelines and REACH registration maintenance requirements, while variables included styrene substitution rates and marine composite hull adoption curves. Segmentation dimensions encompassed formulation chemistry grade, end-use application, regional production hub, and distribution channel structure. CAGRs were derived from regression analysis of historical trade volumes against projected capacity additions and regulatory compliance cost trajectories, incorporating phthalic anhydride feedstock price elasticity and low-emission formulation premium capture rates.
Practitioners should monitor MEE enforcement intensity in Guangdong province and ECHA substance evaluation timelines for early signals of regulatory acceleration or relaxation. Forecasts reflect assumptions regarding substitution technology maturation and cross-border hazard classification harmonization progress. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
South Korea Engineering Plastics Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
South America Thermoplastics Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Sugar Polymers Market