
 India Polymer Emulsion Market | 2026-2036
India Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
India Polymer Emulsion Market Foresight
A capital-intensity divergence between integrated resin producers and formulation specialists is rotating competitive advantage toward backward-integrated players with captive monomer supply. BASF SE leverages its Ludwigshafen-derived technology base to sustain premium acrylic emulsion output in India. Pidilite Industries Limited anchors its position through deep distribution into tier-two construction markets. Asian Paints Limited controls captive consumption, converting emulsions directly into decorative coatings at scale.
Polymer emulsion denotes a colloidal dispersion of polymer particles in water, typically 40-60% solids content, stabilized by surfactants and manufactured through batch or continuous emulsion polymerization. The formulation serves as a film-forming binder in water-based paints, adhesives, and textile finishes, replacing solvent-borne systems to meet volatile organic compound restrictions. Acrylic emulsions dominate volume owing to exterior durability and ultraviolet resistance in architectural coatings. Water-based technology leads growth as environmental compliance hardens, while low-VOC formulations command margin premiums in premium residential and automotive refinish segments. Polyurethane emulsions occupy a specialized niche in high-performance textile and leather coatings where elasticity requirements exceed acrylic capabilities.
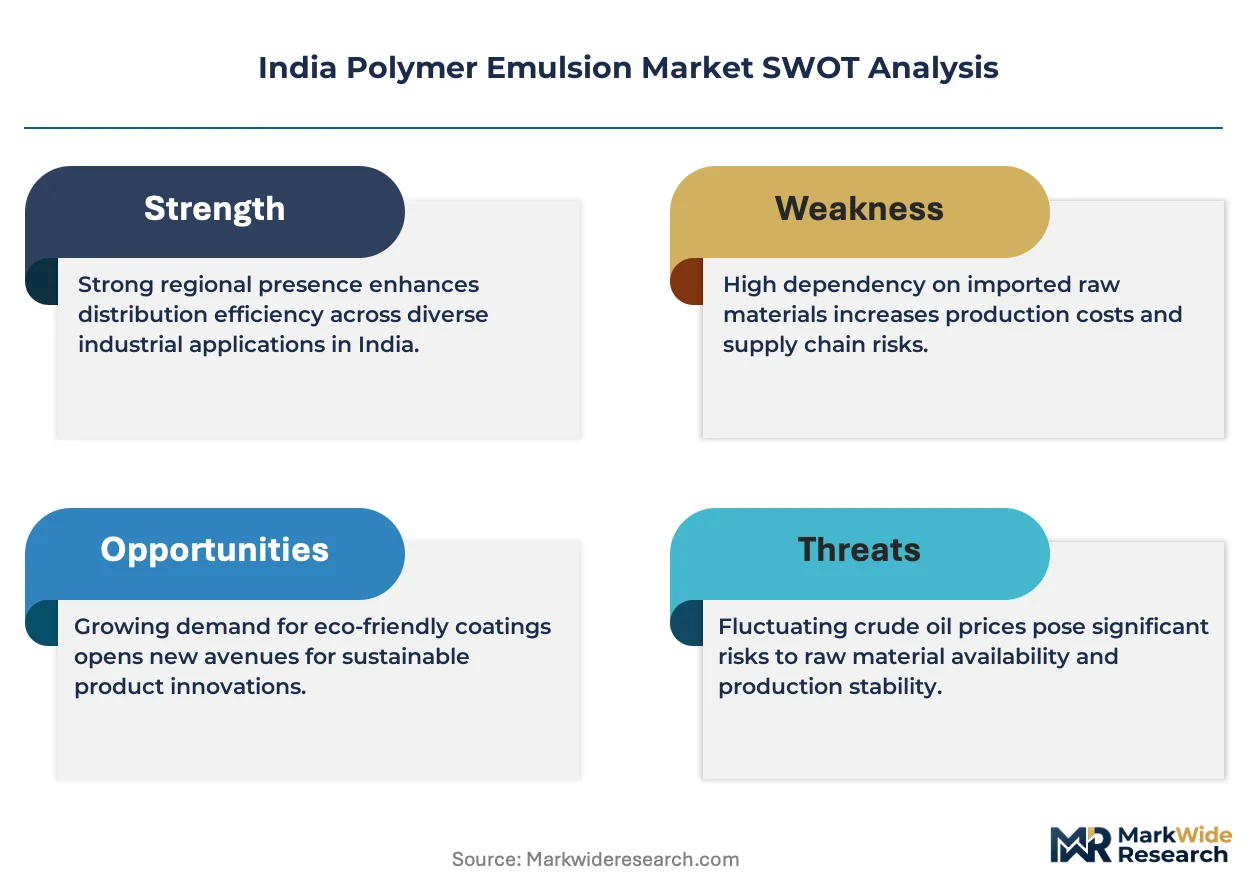
BIS mandates on emulsion quality and the Central Pollution Control Board's VOC emission norms are forcing reformulation investments across domestic manufacturers. The Bureau of Indian Standards has tightened testing protocols for emulsion-based construction chemicals, raising compliance costs for unintegrated producers. Stakeholders must monitor state-level green building codes in Maharashtra and Gujarat, where municipal authorities are embedding low-emission material requirements into public infrastructure tenders. The decisive variable remains whether domestic monomer capacity expansions can narrow the cost gap against Southeast Asian imports before BIS certification becomes mandatory for all emulsion grades.
Market Dynamics
BIS certification mandates for low-VOC emulsion grades are compressing margins for unintegrated producers while rotating procurement power toward western Indian construction corridors with embedded green building codes.
Growth Catalysts
- Green building code adoption:Municipal authorities in Maharashtra and Gujarat are embedding low-emission material requirements into public infrastructure tenders, pulling water-based coating demand from solvent-borne alternatives.
- Central Pollution Control Board norms:VOC emission ceilings for architectural coatings are forcing reformulation across the decorative paints sector, expanding addressable volume for compliant emulsion suppliers.
- Acrylic emulsion durability:Ultraviolet resistance and exterior weathering performance in water-based architectural applications are displacing alkyd systems in premium residential projects.
Market Restraints
- Monomer import dependency:Domestic butyl acrylate and methyl methacrylate capacity deficits force reliance on Southeast Asian feedstock, exposing margins to freight and currency volatility.
- Technical formulation barriers:Polyurethane emulsion stability under freeze-thaw cycling remains inferior to solvent-borne counterparts, limiting penetration in high-performance automotive refinish.
- BIS testing protocol friction:Tightened quality certification timelines and elevated laboratory audit requirements are extending product launch cycles for regional formulators.
Strategic Opportunities
- Tier-two construction penetration:Distribution infrastructure gaps in Madhya Pradesh and Rajasthan create first-mover openings for emulsion suppliers with localized technical service capabilities.
- Textile finishing convergence:Hybrid acrylic-polyurethane emulsions are opening performance gaps in elastic garment coatings where pure acrylic systems fail.
- PLI scheme tailwinds:Production-linked incentives for specialty chemicals are narrowing capital cost disadvantages against integrated resin producers with captive monomer assets.
Industry Challenges
- Emulsion polymerization expertise scarcity:Batch process optimization and surfactant stabilization chemistry talent concentrates with legacy producers, constraining new entrant scale-up velocity.
- Legacy coating system integration:Water-based emulsion compatibility with existing solvent-borne application equipment in small-scale automotive body shops demands costly retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Polymer Emulsion Market |
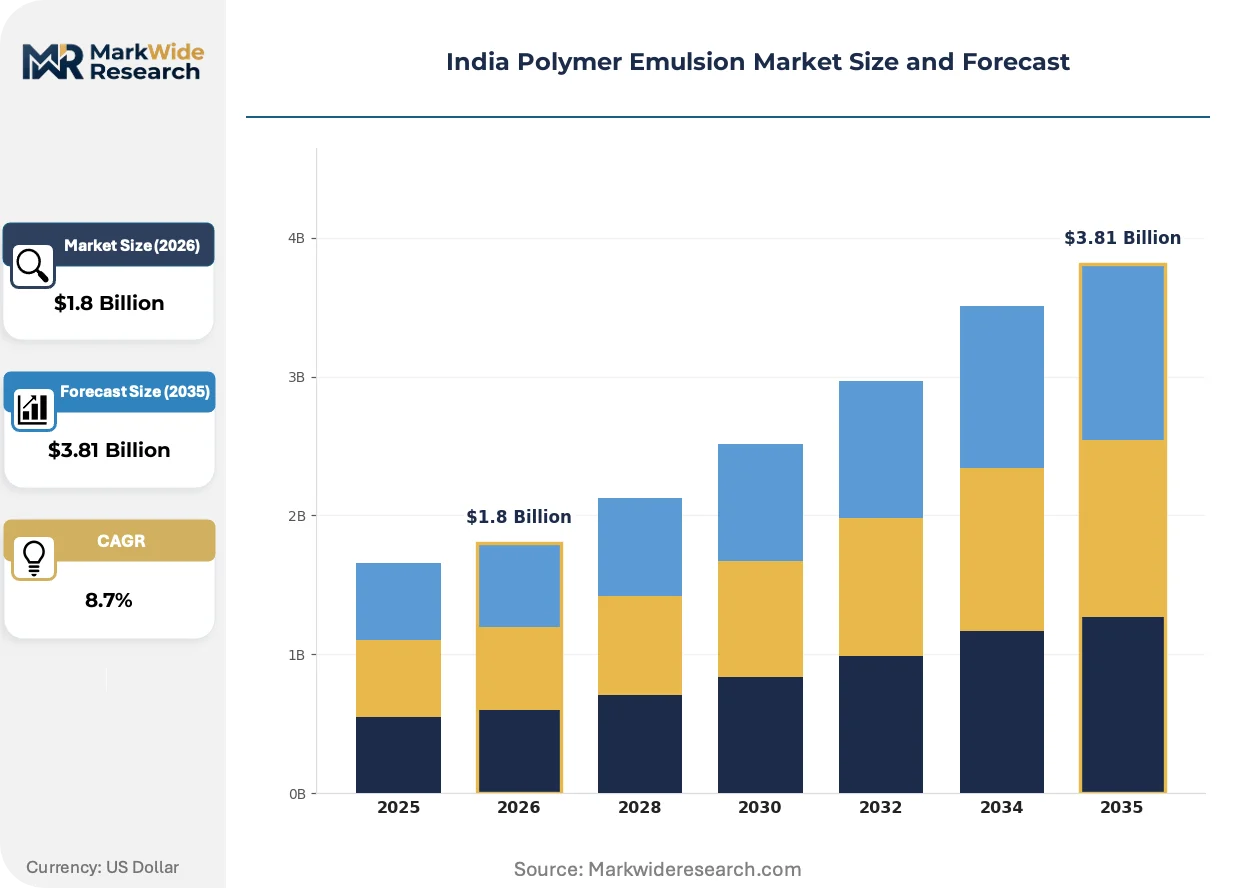
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Vinyl, Styrene, Polyurethane End User: Construction, Automotive, Textiles, Coatings Technology: Water-Based, Solvent-Based, High-Solid, Low-VOC Application: Adhesives, Sealants, Paints, Inks |
| Companies Covered | BASF SE, Arkema Group, Visen Industries Limited, Atul Limited, Apcotex Industries Limited, Asian Paints Limited, Akzo Nobel N.V., Wacker Chemie AG, Pidilite Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Polymer Emulsion Market Shifts & Advancements
Water-based technology platforms are fragmenting the competitive landscape as environmental compliance hardens and formulation capabilities separate integrated producers from commodity blenders.
Hybrid acrylic-polyurethane emulsion chemistry is fragmenting the traditional acrylic-dominated architectural coatings segment. High-performance textile and leather finishers in Tamil Nadu and Karnataka are adopting these systems for elasticity requirements exceeding pure acrylic capabilities. The technology is fragmenting supplier tiers by rewarding players with in-house polymerization expertise over simple formulation blending.
BIS mandates on emulsion quality and VOC content are compressing product launch timelines across domestic manufacturers. The Bureau of Indian Standards has tightened testing protocols for emulsion-based construction chemicals, raising compliance costs for unintegrated producers. Maharashtra and Gujarat municipal authorities are embedding these standards into public infrastructure tenders, forcing reformulation investments before certification becomes mandatory for all grades.
Construction sector buyers in western India are consolidating procurement decisions through specified contractor networks rather than open distributor channels. Large residential developers in Pune and Ahmedabad are direct-contracting emulsion suppliers for volume coating packages, disintermediating traditional paint store distribution. This concentration is most visible in premium residential projects where BIS-certified low-VOC formulations command specification preference.
India Polymer Emulsion Market Segmentation
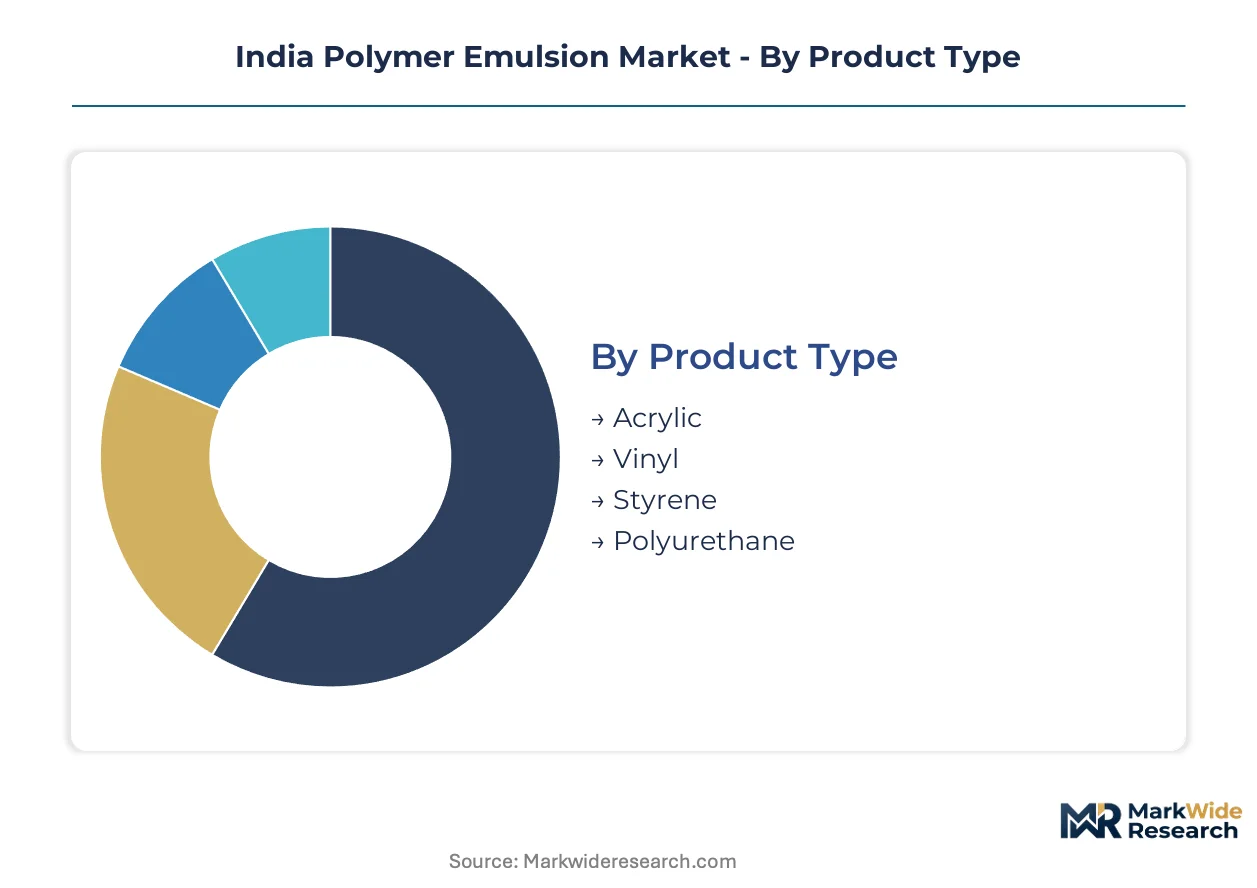
Segmentation reveals where substitution pressure reshapes procurement patterns across India's polymer emulsion landscape. Each dimension exposes distinct vulnerability profiles and margin architectures that determine competitive survival.
Product Type:
Acrylic and polyurethane segments face divergent substitution threats from solvent-borne alternatives in high-performance coatings.
- Acrylic:Aqueous dispersion of polyacrylate polymers delivering ultraviolet resistance and exterior durability. Maharashtra and Gujarat construction corridors specify acrylic emulsions for premium residential facades under tightening BIS low-VOC mandates.
- Polyurethane:Segmented copolymer emulsions with superior elasticity and abrasion resistance. Tamil Nadu and Karnataka textile finishers adopt these for stretch garment coatings where acrylic systems fail performance thresholds.
- Vinyl:Polyvinyl acetate-based binders dominating economy-grade adhesive applications in packaging and woodworking.
- Styrene:Styrene-acrylic hybrid systems penetrating water-resistant construction chemical formulations.
Acrylic retains volume leadership; polyurethane holds the steepest expansion curve.
End User:
Cost tier stratification separates specification-driven buyers from price-sensitive commodity purchasers across end-use verticals.
- Construction:Architectural coatings and waterproofing membranes consuming emulsion volumes at scale. Western Indian industrial corridors in Pune and Ahmedabad consolidate procurement through specified contractor networks demanding BIS-certified low-VOC grades.
- Coatings:Decorative and industrial paint manufacturers driving formulation standardization. Captive consumption by integrated producers like Asian Paints compresses third-party supplier margins.
- Automotive:Refinish and OEM coatings requiring freeze-thaw stability that water-based polyurethane emulsions struggle to deliver.
- Textiles:Garment finishing and leather coating applications in South India seeking hybrid acrylic-polyurethane elasticity.
Construction commands absolute volume; coatings generate the densest margin compression.
Technology:
Application intensity varies sharply across formulation platforms, with environmental compliance redrawing competitive boundaries.
- Water-Based:Primary growth platform displacing solvent systems through VOC regulatory pressure. Central Pollution Control Board emission ceilings accelerate architectural coating reformulation.
- Low-VOC:Certified formulations commanding specification premiums in Maharashtra and Gujarat municipal infrastructure tenders.
- Solvent-Based:Declining share confined to automotive refinish segments where equipment retrofit costs block water-based conversion.
- High-Solid:Reduced-water-content systems penetrating industrial maintenance coatings with specific humidity constraints.
Water-based technology anchors volume; low-VOC certification captures the steepest margin expansion.
Application:
Customer type fragmentation separates project-specified demand from distributor-driven replacement markets.
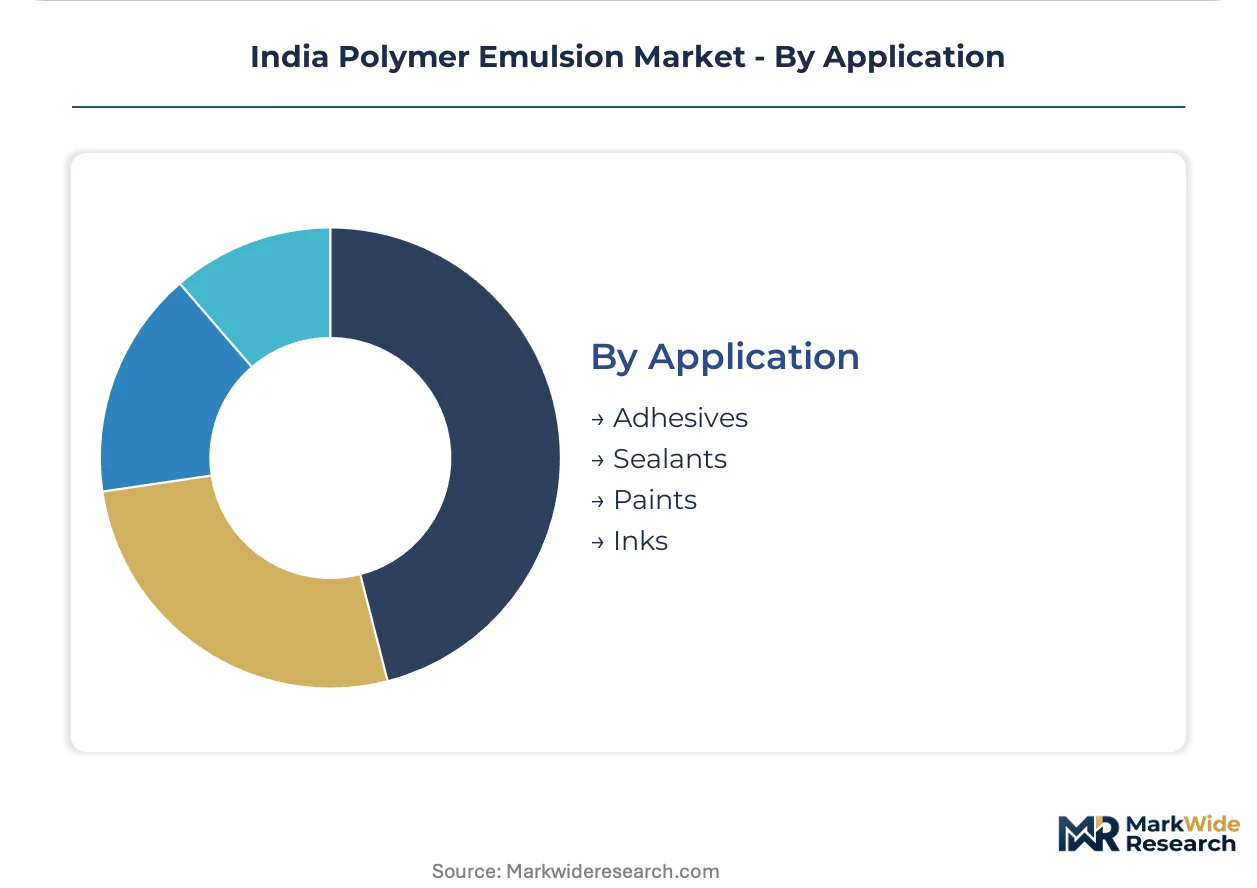
- Paints:Film-forming binders in architectural and decorative coatings. Tier-two city expansion in Madhya Pradesh and Rajasthan creates distribution infrastructure gaps for localized technical service providers.
- Adhesives:Woodworking, packaging, and construction bonding applications. Economy vinyl emulsions dominate volume in price-sensitive segments.
- Sealants:Joint fillers and waterproofing membranes for infrastructure projects specifying BIS-tested construction chemicals.
- Inks:Niche flexographic and gravure printing applications with specialized rheology requirements.
Paints retain volume dominance; adhesives present the most concentrated price competition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's polymer emulsion trade runs a structural deficit in specialty monomers, with western industrial corridors absorbing imported feedstock for water-based coating production. The geographic pattern concentrates formulation capacity near port infrastructure and construction demand nodes.
Maharashtra
Pune and Mumbai industrial zones drive specification-grade acrylic emulsion consumption for premium residential facades. The state's municipal corporations have embedded BIS low-VOC requirements into public housing tenders since 2023. MIDC industrial areas near Nashik host formulation plants serving the western India construction corridor.
Gujarat
Ahmedabad and Surat anchor water-based coating demand from large residential developers direct-contracting emulsion suppliers. The state's pollution control board enforces VOC emission ceilings stricter than national baselines. Dahej and Hazira port zones concentrate import terminals for Southeast Asian butyl acrylate feedstock.
Karnataka
Bengaluru and Mysuru textile finishers adopt hybrid acrylic-polyurethane emulsions for stretch garment coatings. The state's Directorate of Industries promotes specialty chemicals through PLI scheme allocations. Peenya industrial estate houses leather coating operations demanding polyurethane elasticity.
Tamil Nadu
Tiruppur and Coimbatore garment exporters drive emulsion demand for elastic textile finishes with export compliance requirements. The Tamil Nadu Pollution Control Board monitors effluent from emulsion-based finishing operations. Ambattur industrial corridor hosts formulation specialists serving South Indian textile clusters.
Telangana
Hyderabad's pharmaceutical and construction chemical sectors pull standard-grade vinyl emulsions for adhesive applications. The state's industrial promotion policy targets specialty chemicals investments with capital subsidy windows. Jeedimetla and Patancheru industrial zones concentrate mid-tier formulation capacity.
India Polymer Emulsion Market Competitive Landscape
Concentration sits with backward-integrated resin producers and captive-consumption paint manufacturers, while unintegrated formulators face margin compression from monomer import volatility. The competitive structure separates three archetypes: multinational chemical majors with proprietary polymerization technology, domestic integrated paint producers consuming emulsions captively, and regional formulation specialists serving tier-two distribution. Dominant competitive moves include capacity expansion in western industrial corridors and technology licensing arrangements for low-VOC formulation platforms.
Among multinational chemical majors, BASF SE and Arkema Group represent the technology-licensing tier with Ludwigshafen and Colombes-derived emulsion polymerization expertise. Domestic integrated producers Asian Paints Limited and Pidilite Industries Limited occupy distinct positions—one converting emulsions captively into decorative coatings at scale, the other penetrating tier-two construction markets through deep distribution infrastructure. Wacker Chemie AG anchors the silicone-modified emulsion segment with Munich-based specialty chemical positioning.
| Leading Market Players |
|---|
| BASF SE |
| Arkema Group |
| Visen Industries Limited |
| Atul Limited |
| Apcotex Industries Limited |
| Asian Paints Limited |
| Akzo Nobel N.V. |
| Wacker Chemie AG |
| Pidilite Industries Limited |
| Others |
Supply & Pricing Matrix
Forty-five to sixty days of butyl acrylate inventory held at Dahej and Hazira port terminals concentrates working capital exposure among unintegrated formulators while amplifying pricing leverage for backward-integrated producers with captive monomer assets in Maharashtra and Gujarat.
Pricing Analysis
Configured-to-order pricing for BIS-certified low-VOC acrylic emulsions commands spreads of fifteen to twenty percent above standard-grade quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with municipal infrastructure tenders in western India specifying premium tiers. Cost compression in economy vinyl emulsions is intensifying because of import parity pressure from Southeast Asian suppliers. Small-scale automotive body shops exhibit highest price sensitivity due to equipment retrofit burdens, while large residential developers in Pune and Ahmedabad demonstrate lowest sensitivity given specification-driven procurement.
Supply Chain Analysis
Strategic stockpiling of methyl methacrylate and butyl acrylate dominates inventory strategy among integrated resin producers, whereas unintegrated formulators run just-in-time procurement exposed to freight volatility. Domestic supply draws from Thailand, Singapore, and South Korea for specialty monomers, while acrylic acid feedstock rests on Saudi Arabian and Korean petrochemical complexes. Single-source vulnerability concentrates in butyl acrylate import terminals at Dahej and Hazira. Distribution runs through specified contractor networks in western India and traditional paint-store channels in tier-two cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's polymer emulsion market sits in early-cycle expansion as BIS low-VOC mandates penetrate municipal infrastructure procurement and displace solvent-borne systems.
For Market Incumbents: Secure captive monomer supply through backward integration into butyl acrylate production or long-term offtake agreements with Southeast Asian suppliers. Expand technical service infrastructure in Madhya Pradesh and Rajasthan to preempt new entrant distribution buildout. Threat of unintegrated regional formulators achieving BIS certification requires accelerated compliance investments to maintain specification-grade positioning. For New Entrants and Emerging Players: Lead with hybrid acrylic-polyurethane emulsion formulations targeting Tamil Nadu and Karnataka textile finishers where elasticity requirements exceed incumbent pure acrylic capabilities. Tier-two construction markets in Rajasthan present most penetrable geography given distribution infrastructure gaps. Deploy localized technical service teams as primary go-to-market mechanism to overcome legacy producer relationship advantages. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because BIS certification barriers and monomer import dependency will compress unintegrated formulator margins and create acquisition opportunities at cyclical lows. Target formulators with established BIS-certified product portfolios and western India distribution presence. Signal to watch is domestic monomer capacity announcement timelines relative to mandatory certification expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Production | Captive butyl acrylate supply insulates margins from Southeast Asian freight volatility and currency swings. |
| BIS Low-VOC Certification Investment | Mandatory certification for municipal tenders in Maharashtra and Gujarat locks out unqualified competitors. |
| Tier-Two Distribution Expansion | Localized technical service presence in Madhya Pradesh and Rajasthan captures construction growth outside saturated western corridors. |
| Hybrid Emulsion R&D Partnership | Acrylic-polyurethane formulation expertise opens textile finishing demand in Tamil Nadu and Karnataka. |
| Long-Term Supply Agreement with Port Terminals | Priority access to Dahez and Hazira import infrastructure reduces inventory risk for unintegrated formulators. |
Research Methodology
Desk research of BIS certification records, Central Pollution Control Board emission compliance filings, and customs import data preceded structured interviews with plant managers at integrated resin facilities, procurement leads at downstream paint manufacturers, distribution channel partners in western India, and technical R&D directors at formulation specialists. Primary fieldwork combined with secondary validation from SEC filings of multinational chemical majors, ACC chemical industry reports, and trade flow databases. Bottom-up emulsion volume estimates triangulated against top-down construction sector coating demand projections.
Variance decomposition across product type, end-use vertical, technology platform, and regional production hub anchored the analytical framework. Modeled segmentation captured acrylic, polyurethane, vinyl, and styrene chemistries against construction, coatings, automotive, and textile demand pools. CAGRs derived from elasticity-adjusted demand curves incorporating BIS regulatory phase-in schedules and monomer import price trajectories. Forecast inputs included municipal infrastructure tender award patterns and state-level green building code adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained BIS enforcement intensity or domestic monomer capacity expansion timelines would require recalibration. Forecasts reflect assumptions regarding regulatory compliance deadlines and import parity pricing. Revision becomes warranted when monomer supply diversification or certification waiver thresholds cross materiality levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Paper Processing Resins Market
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Hydrocarbon Resins Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market