
 Middle East Polyethylene Terephthalate (PET) Market | 2026-2036
Middle East Polyethylene Terephthalate (PET) Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Polyethylene Terephthalate (PET) Market Insights
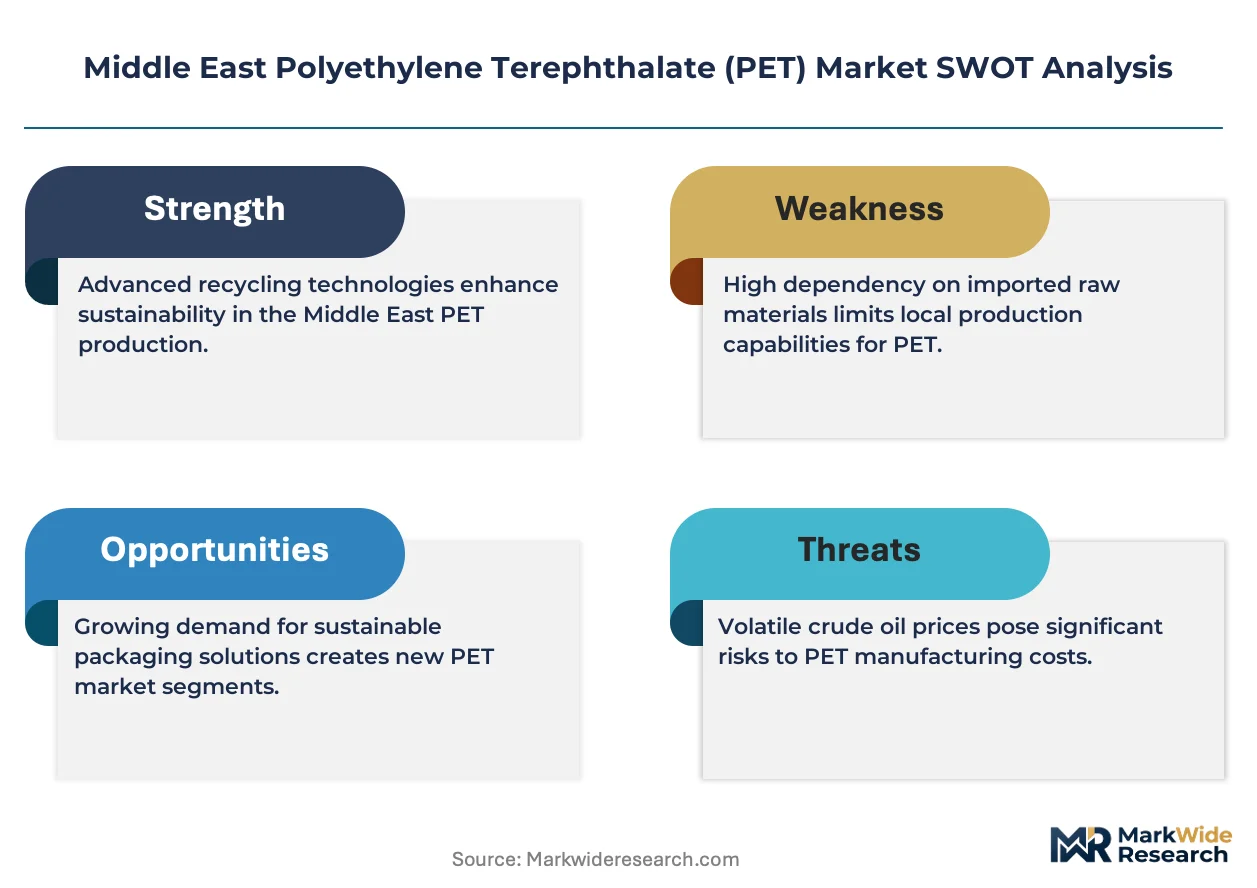
Advanced recycling and chemical depolymerization is reshaping how PET resin achieves circularity in the Middle East. SABIC leverages its integrated feedstock position in Jubail to produce virgin-quality recycled PET at scale. Indorama Ventures Public Company Limited anchors regional supply through its polyester operations in the UAE and Egypt. Equate Petrochemical Company specializes in bottle-grade resin tailored for Gulf beverage bottlers.
Polyethylene terephthalate is a thermoplastic polyester polymerized from purified terephthalic acid and monoethylene glycol, exhibiting crystallinity between 30-40% in standard bottle-grade formulations and melt temperatures near 250°C. Its primary purpose centers on producing lightweight, barrier-resistant containers and synthetic fibers with recyclability through mechanical or chemical reprocessing. Bottle grade dominates value capture across Middle Eastern markets due to concentrated beverage demand and established blow-molding infrastructure. Film grade competes for share in food packaging laminates where clarity and gas barrier properties command premium positioning. Fiber grade sustains steady offtake from Turkey-linked textile operations serving European apparel supply chains.
Saudi Arabia's SFDA enforces migration limits and food-contact compliance testing that shape resin purity specifications for domestic converters. The UAE's Ministry of Climate Change and Environment implements extended producer responsibility frameworks that push brand owners toward recycled content quotas. Turkey's Ministry of Trade applies anti-dumping measures on Asian PET imports that redirect procurement flows toward regional producers. Stakeholders must monitor how carbon border adjustments from European trading partners will alter cost competitiveness for Middle Eastern resin exports.
Market Dynamics
Circular economy mandates across Gulf Cooperation Council member states are forcing PET resin producers to reconfigure feedstock strategies around chemical recycling pathways and mass-balance certification schemes.
Growth Catalysts
- SFDA Packaging Safety Mandates:Saudi Arabia's food-contact compliance requirements are elevating resin purity standards that favor integrated producers with captive purified terephthalic acid supply.
- Beverage Bottling Expansion:Gulf beverage brands are converting to lightweight PET containers to reduce logistics costs and meet extended producer responsibility targets.
- Jubail-Yanbu Industrial Corridor:Concentrated petrochemical infrastructure enables downstream PET resin producers to access monoethylene glycol and purified terephthalic acid through pipeline networks.
Market Restraints
- Crude Oil-Derived Feedstock Exposure:Purified terephthalic acid and monoethylene glycol production remains tethered to naphtha cracking economics, exposing margin compression during hydrocarbon price volatility.
- Asian Import Competition:Turkish anti-dumping measures on Asian PET resin have redirected flows toward Middle Eastern markets, pressuring regional price formation.
- Mechanical Recycling Quality Ceiling:Contamination accumulation in post-consumer PET flake limits food-contact applications without chemical depolymerization intervention.
Strategic Opportunities
- UAE Circular Economy Policy Framework:Extended producer responsibility mandates create guaranteed offtake channels for recycled-content PET resin in beverage and food packaging.
- Egyptian Textile Fiber Demand:Turkey-linked apparel supply chains are sourcing fiber-grade PET from regional producers to circumvent European carbon border adjustment exposure.
- Chemical Depolymerization Scale-Up:Glycolysis and methanolysis technologies enable food-grade recycled PET production without virgin-quality degradation.
Industry Challenges
- Mass-Balance Certification Complexity:ISCC PLUS and RSB certification timelines for chemical recycling facilities extend 12-18 months, delaying commercial offtake agreements.
- Specialized Process Engineering Talent:Chemical depolymerization plant commissioning requires expertise in catalytic reactor design that remains scarce across Gulf engineering labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Polyethylene Terephthalate (PET) Market |
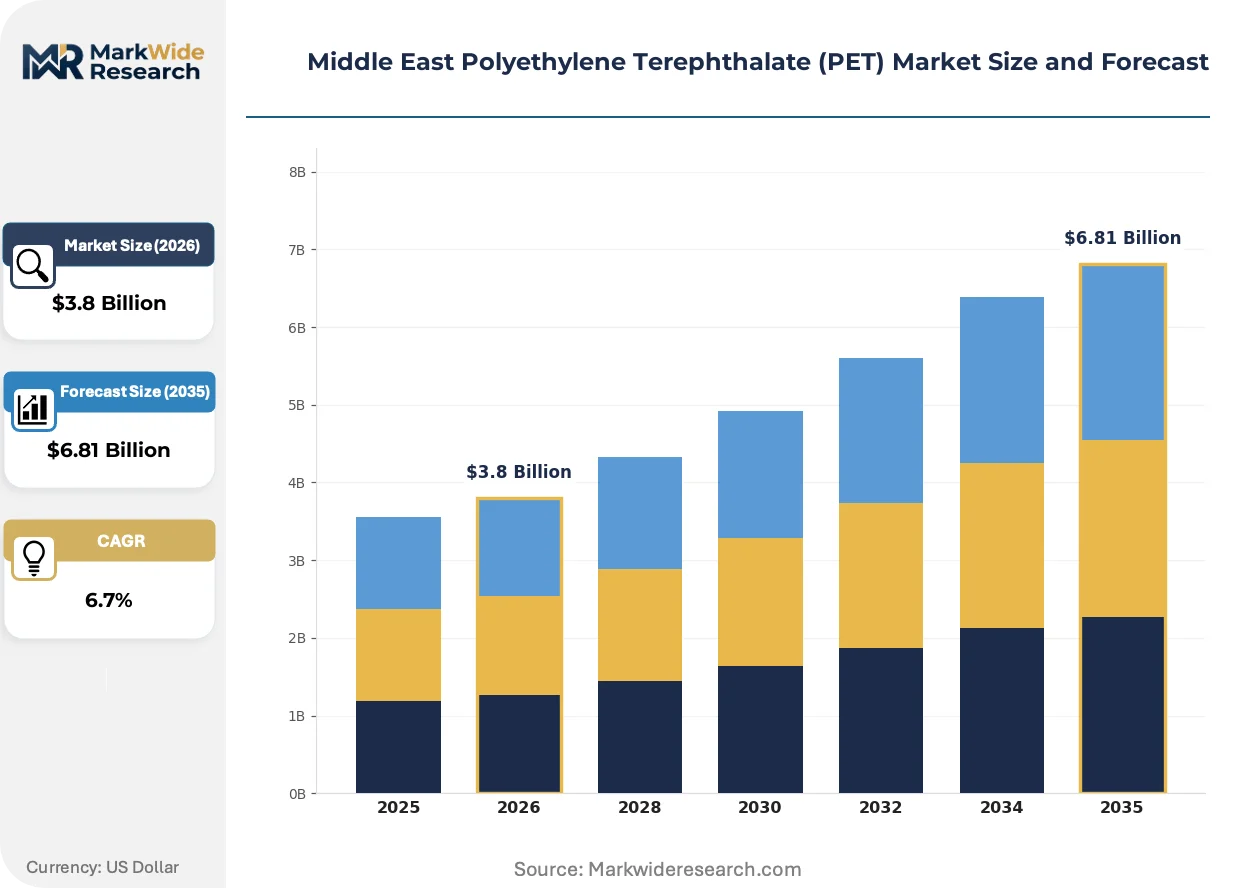
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottle Grade, Film Grade, Fiber Grade, Sheet Grade Application: Bottling, Packaging, Textiles, Automotive Components End User: Packaging Industry, Textile Industry, Automotive Sector, Consumer Goods Technology: Injection Molding, Blown Film Extrusion, Stretch Blow Molding, Fibers Production |
| Companies Covered | SABIC, Indorama Ventures Public Company Limited, Equate Petrochemical Company, Alpek, BASF SE, Eastman Chemical Company, Dow, Lotte Chemical, Reliance Industries, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Polyethylene Terephthalate (PET) Market Trends and Innovations
Digital mass-balance tracking systems are virtualizing how recycled-content PET achieves certification transparency across multi-tier supply chains. These platforms compress audit cycles and enable real-time feedstock provenance verification.
Enzymatic depolymerization technology is virtualizing traditional mechanical recycling infrastructure by enabling selective PET breakdown at ambient temperatures. Beverage bottlers in the UAE are piloting this pathway to bypass energy-intensive thermal processes. The technology is compressing capital requirements for food-grade recycled resin production while expanding feedstock flexibility to colored and contaminated flake streams.
The UAE's Ministry of Climate Change and Environment has implemented extended producer responsibility frameworks that mandate recycled content quotas for plastic packaging. Brand owners must now secure mass-balance certified resin or face compliance penalties. Bottle-grade PET converters are responding by integrating chemical recycling partnerships into their procurement specifications.
Brand-led recycled content commitments are compressing traditional spot-market procurement patterns toward long-term offtake contracts with certified producers. Beverage multinationals operating in Saudi Arabia and the UAE are locking in five-year supply agreements to secure mass-balance credentials. This shift is most visible in the Gulf's premium bottled water segment, where label claims of recycled content now drive shelf placement negotiations.
Middle East Polyethylene Terephthalate (PET) Market Segmentation
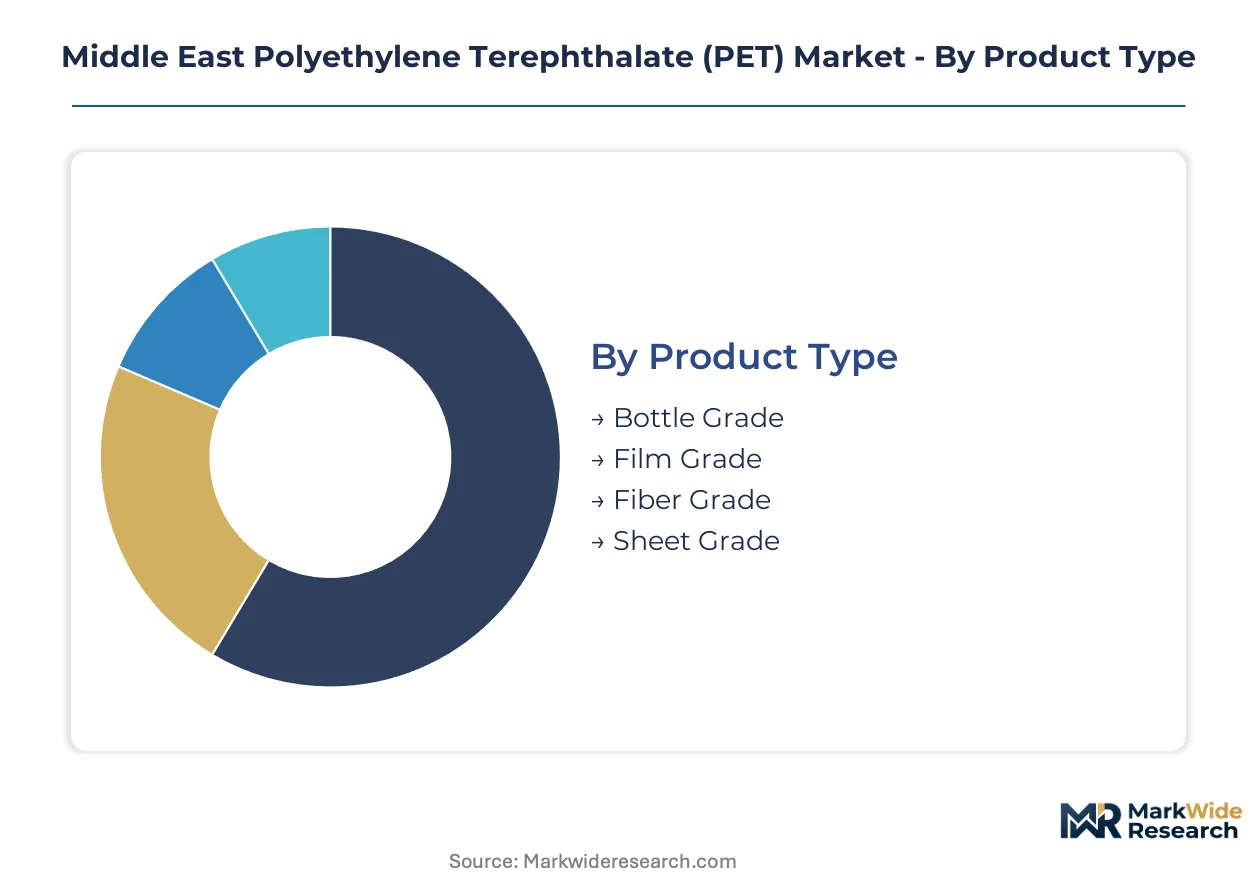
PET resin specifications diverge sharply across Middle Eastern demand centers, with bottle-grade purity mandates from Saudi Arabia's SFDA running parallel to fiber-grade offtake from Turkey-linked textile corridors. Understanding these segment boundaries clarifies why integrated producers maintain parallel production trains rather than flexible single-line configurations.
Product Type:
The use-case spectrum spans rigid container applications through flexible packaging and textile feedstocks, each demanding distinct intrinsic viscosity and crystallinity profiles.
- Bottle Grade:Intrinsic viscosity specifications between 0.76-0.84 dL/g deliver the mechanical strength required for carbonated beverage containers. Demand concentrates in Saudi Arabia's Jubail-Yanbu corridor, where SABIC and Equate Petrochemical Company supply Gulf bottlers facing SFDA migration limit compliance deadlines.
- Film Grade:Lower crystallinity formulations (20-30%) provide the clarity and thermoformability essential for food packaging laminates. Egyptian converters serving European export markets represent the fastest-expanding demand node as carbon border adjustments redirect procurement toward regional sources.
- Fiber Grade:Textile-oriented PET with reduced carboxyl end-group content enables high-speed spinning operations. Turkey-linked apparel supply chains source from UAE and Egyptian producers to circumvent European duty exposure.
- Sheet Grade:Thermoforming-grade resin with enhanced melt strength serves dairy and deli container markets. Local production remains limited, with Gulf converters relying on imported material.
Established volume favors bottle grade; emerging adoption favors film grade as food packaging regulations tighten across GCC markets.
Application:
Application segmentation tracks the downstream value capture hierarchy, from high-unit-value beverage containers through commodity textile fibers.
- Bottling:Carbonated soft drink and bottled water containers dominate value capture, with lightweighting initiatives driving wall-thickness reduction to 0.25mm in premium segments. UAE extended producer responsibility mandates now require 30% recycled content in packaging applications.
- Packaging:Food-contact trays and blister packs demand enhanced barrier properties through co-extrusion or coating technologies. Saudi Arabia's retail modernization is expanding cold-chain packaging requirements.
- Textiles:Polyester staple fiber and filament yarn production serves apparel and home furnishings markets. Egyptian spinning mills represent the regional demand anchor.
- Automotive Components:Under-the-hood applications leverage PET's thermal stability and chemical resistance. Penetration remains nascent across Middle Eastern vehicle assembly operations.
Margin concentration sits with bottling; volume expansion is climbing the fastest in packaging as e-commerce fulfillment drives protective material demand.
End User:
End-user segmentation reveals how procurement authority distributes across converter tiers with varying technical sophistication and certification requirements.
- Packaging Industry:Rigid and flexible packaging converters represent the dominant value channel, with mass-balance certification now mandatory for contracts with multinational beverage brands operating in Dubai and Riyadh.
- Textile Industry:Fiber spinners and fabric weavers in Egypt and Turkey source regional PET to minimize logistics exposure and currency volatility.
- Automotive Sector:Tier-1 suppliers in Morocco and Tunisia utilize PET for electrical insulation and interior trim applications. Specifications align with European OEM material standards.
- Consumer Goods:Durable product manufacturers employ PET for appliance housings and cosmetic containers. Demand fragmentation characterizes this segment.
Procurement consolidation favors packaging industry; specification complexity favors textile industry as technical fiber requirements diverge.
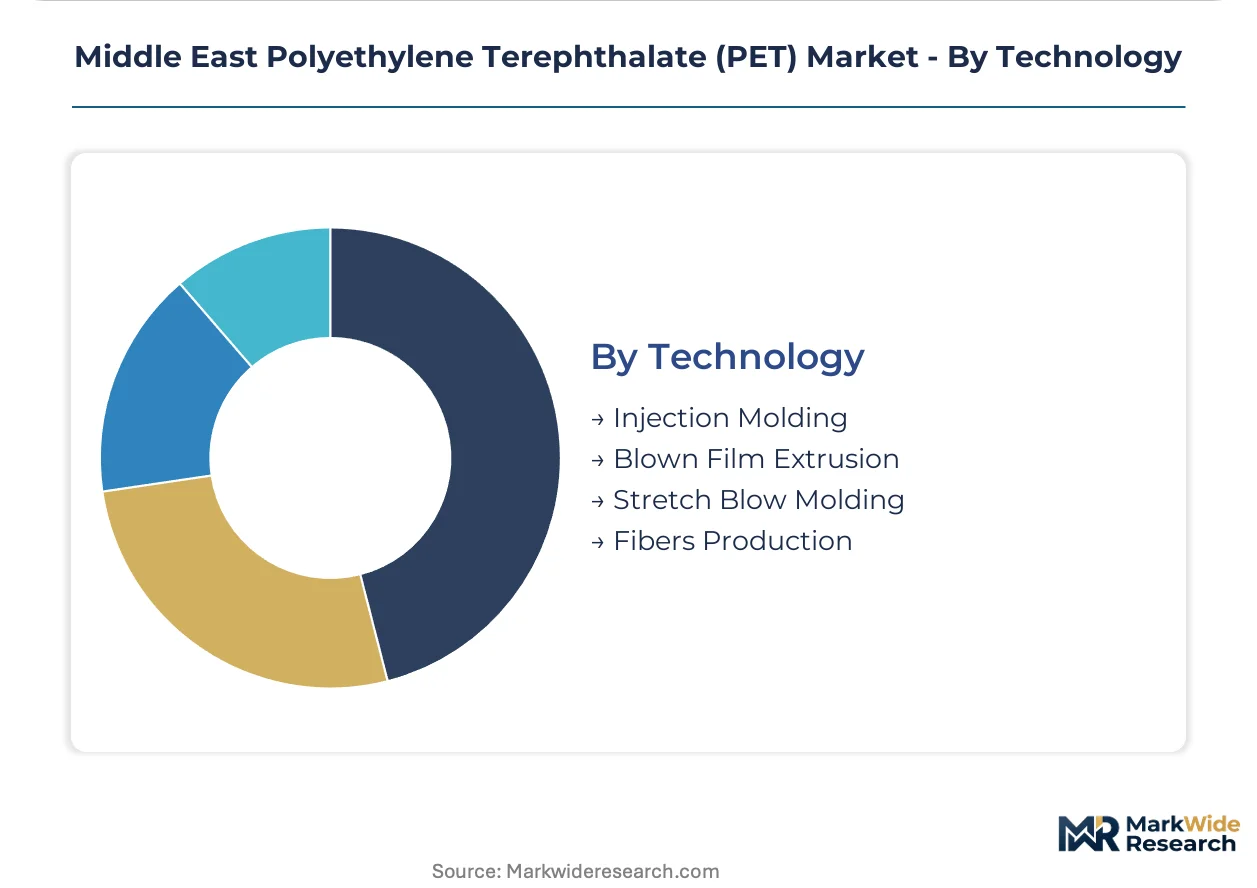
Technology:
Processing technology segmentation determines capital intensity, energy consumption, and the feasible product quality spectrum for regional converters.
- Injection Molding:Preform production for subsequent stretch blow molding dominates beverage container manufacturing. Saudi converters are upgrading to all-electric machines to reduce energy intensity.
- Stretch Blow Molding:Two-stage reheat stretch blow molding produces finished bottles from injection-molded preforms. This technology anchors Gulf beverage bottling infrastructure.
- Blown Film Extrusion:Flat and tubular film production serves flexible packaging laminates. UAE converters are expanding capacity for food-grade applications.
- Fibers Production:Melt spinning and staple fiber cutting operations supply textile manufacturers. Egyptian producers maintain cost advantages through integrated PTA-MEG-PET-fiber operations.
Capacity concentration sits with stretch blow molding; technology refresh is expanding most quickly in injection molding as all-electric platforms displace hydraulic systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports PET resin to beverage bottlers across the Gulf Cooperation Council, with Egyptian textile spinners sourcing fiber-grade material to supply Turkey-linked apparel supply chains serving European markets.
Saudi Arabia
Jubail-Yanbu industrial corridor hosts integrated petrochemical complexes feeding downstream PET resin production for Gulf beverage bottlers. SFDA packaging safety mandates enforce migration limits and food-contact compliance testing that shape resin purity specifications. SABIC leverages its captive purified terephthalic acid supply to produce virgin-quality recycled PET at scale.
United Arab Emirates
Dubai and Abu Dhabi anchor demand for bottle-grade resin as beverage multinationals convert to lightweight containers to reduce logistics costs. Ministry of Climate Change and Environment extended producer responsibility frameworks mandate recycled content quotas for plastic packaging. Local converters are integrating chemical recycling partnerships to secure mass-balance certified resin.
Egypt
Textile spinners in the Nile Delta region source fiber-grade PET to circumvent European carbon border adjustment exposure on Turkish apparel exports. Egyptian polyester operations benefit from integrated PTA-MEG-PET-fiber production chains that maintain cost advantages. Regional producers supply Turkey-linked supply chains with material traceable to regional origins.
Turkey
Apparel manufacturers in Istanbul and Bursa procure regional PET resin to minimize logistics exposure and currency volatility in European export markets. Ministry of Trade anti-dumping measures on Asian PET imports redirect procurement flows toward Middle Eastern producers. Domestic spinning mills represent a steady offtake anchor for fiber-grade material.
Middle East Polyethylene Terephthalate (PET) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three structural tiers. Gulf-based integrated petrochemical groups anchor supply through captive feedstock positions, while global polyester specialists manage regional operations through subsidiary networks. Strategic archetypes include backward-integrated resin producers, pan-regional fiber specialists, and technology-licensed compounders. Dominant competitive moves center on chemical recycling scale-up and mass-balance certification partnerships.
Within the integrated producer tier, SABIC and Equate Petrochemical Company exemplify Gulf-based operators with captive purified terephthalic acid and monoethylene glycol supply. Indorama Ventures Public Company Limited anchors regional polyester operations through its UAE and Egyptian facilities. These three entities represent distinct archetypes: SABIC exemplifies state-linked petrochemical integration, Equate occupies a position as a Kuwait-Saudi joint venture focused on bottle-grade specialization, and Indorama sits within the global specialist tier managing multi-country production networks.
| Leading Market Players |
|---|
| SABIC |
| Indorama Ventures Public Company Limited |
| Equate Petrochemical Company |
| Alpek |
| BASF SE |
| Eastman Chemical Company |
| Dow |
| Lotte Chemical |
| Reliance Industries |
| Others |
Pricing and Supply Chain Analysis
Overcapacity signals from Asian PET resin exporters are compressing margin structures for Gulf producers, forcing integrated players to prioritize long-term offtake contracts over spot-market participation. SABIC and Equate Petrochemical Company leverage captive purified terephthalic acid supply to defend pricing power against import pressure, while converters absorb cost volatility through formula-based raw material pass-through mechanisms.
Pricing Analysis
Mechanical recycling-grade PET commands a discount to chemically depolymerized resin suitable for food-contact applications, with enzymatic processing technologies emerging as a cost-disruptive third tier. Pricing stratifies across premium, standard, and economy tiers based on ISCC PLUS certification status and intrinsic viscosity specifications. Cost compression in standard bottle-grade material is intensifying because Turkish anti-dumping measures have redirected Asian export flows toward Middle Eastern markets. Beverage multinationals operating in Dubai and Riyadh exhibit lowest price sensitivity due to extended producer responsibility compliance requirements, while Egyptian textile spinners represent the most price-elastic demand segment.
Supply Chain Analysis
Export-control regimes on advanced catalytic reactor technologies for chemical depolymerization limit technology transfer to Gulf engineering markets, constraining domestic recycling scale-up. Supply concentrates in Saudi Arabia's Jubail-Yanbu corridor, the UAE's Jebel Ali industrial zone, and Egypt's Nile Delta textile belt. Purified terephthalic acid, monoethylene glycol, and post-consumer PET flake feedstock draw from naphtha cracking economics and regional collection infrastructure. Single-source vulnerability characterizes specialized process engineering talent for plant commissioning. Distribution runs through pipeline networks feeding integrated petrochemical complexes and bulk resin shipments to converter facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Circular economy mandates across Gulf Cooperation Council member states are forcing a technological inflection toward chemical recycling pathways, compressing the viable window for mechanical recycling-only business models.
For Market Incumbents: Build certification moats through ISCC PLUS and RSB mass-balance accreditation ahead of competitor facility commissioning timelines. SABIC and Equate Petrochemical Company should deepen backward integration into glycolysis technology licensing to preempt Asian technology providers from capturing recycling value. Defensive capacity additions in Egypt's textile corridor would counter Turkish spinning mill procurement diversification. For New Entrants and Emerging Players: Establish a beachhead in film-grade PET for Egyptian food packaging exporters serving European markets facing carbon border adjustment exposure. The UAE's extended producer responsibility framework creates guaranteed offtake channels for mass-balance certified resin that incumbent converters cannot fully supply. A go-to-market angle partnering with beverage brand sustainability procurement teams offers faster validation than commodity spot-market penetration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across chemical depolymerization sub-segments as catalytic reactor fabrication costs escalate and certification timelines extend. Five-to-ten year viability favors acquiring mid-scale Egyptian producers with integrated PTA-MEG-PET-fiber operations and existing European customer relationships. The signal to watch is UAE Ministry of Climate Change and Environment enforcement actions against non-compliant packaging converters, which would accelerate certified resin demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Glycolysis and methanolysis investments enable food-grade recycled PET production without quality degradation. |
| Mass-Balance Certification Partnership | ISCC PLUS accreditation secures long-term offtake contracts with multinational beverage brands in Dubai. |
| Backward Integration into PTA Supply | Captive purified terephthalic acid production insulates margin structures from naphtha price volatility. |
| Long-Term Supply Agreement | Five-year contracts with Gulf bottlers compress spot-market exposure and validate recycling capacity investments. |
| Joint Venture with Technology Licensor | Partnerships with enzymatic depolymerization developers bypass scarce catalytic reactor engineering expertise. |
Research Methodology
A spread of perspectives from petrochemical plant managers, beverage converter procurement leads, textile spinner technical directors, and SFDA regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with downstream demand-side stakeholders and upstream resin production executives. Secondary validation drew from customs trade databases, SABIC and Indorama Ventures Public Company Limited SEC disclosures, GCC petrochemical industry association reports, and UAE Ministry of Climate Change and Environment policy documentation. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to constrain forecast variance.
Demand-supply balance dynamics across the analysis window were modeled through segmented capacity utilization rates and offtake contract coverage ratios. Segmentation dimensions included product grade tier, end-use application, processing technology, and regional production hub clustering. CAGRs were derived from fitted growth curves calibrated against historical volume trajectories and policy-mandated recycled content adoption schedules. Industry-specific forecast inputs incorporated SFDA packaging safety mandate compliance deadlines and Turkish Ministry of Trade anti-dumping measure duration assumptions.
Sensitivities concentrate around carbon border adjustment implementation timelines in European trading partner jurisdictions and chemical depolymerization technology cost reduction curves. Forecasts reflect documented assumptions regarding extended producer responsibility enforcement intensity and mass-balance certification adoption rates. Material shifts in Gulf Cooperation Council circular economy policy stringency or breakthroughs in enzymatic processing economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Beverage Processing Polymers Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market