
 Metalized Biaxially Oriented Polypropylene Films Market | 2026-2036
Metalized Biaxially Oriented Polypropylene Films Market Size, Share, and Industry Trends Forecast 2026-2036
Metalized Biaxially Oriented Polypropylene Films Market Intelligence
High-barrier metallization grades is bifurcating the competitive landscape into specification-led and commodity tiers. Uflex Ltd leverages integrated resin-to-film operations across multiple continents to sustain cost leadership in volume segments. Cosmo Films Ltd differentiates through R&D intensity in specialty coated variants for sensitive pharmaceutical applications. Taghleef Industries anchors European supply with dedicated metalized BOPP lines serving premium food and medical packaging accounts.
Metalized biaxially oriented polypropylene films are thermoplastic polymer sheets extruded, stretched in both machine and transverse directions, then vacuum-coated with aluminum to achieve oxygen transmission rates below 0.1 cc/m²/day and moisture barrier performance critical for shelf-stable goods. Heat-sealable variants dominate current output due to their indispensability in form-fill-seal food packaging lines, while pharmaceutical packaging represents the fastest-growing application as serialization and tamper-evidence regulations intensify material-performance requirements. Opaque metalized grades command superior margin pools compared with transparent alternatives because converters prize their light-blocking properties in nutrient-sensitive and photo-degradable product formats.
FDA material-safety standards govern direct food-contact approvals in the United States, while REACH and the EU Packaging and Packaging Waste Directive shape substance restrictions and recyclability mandates across Europe. India's BIS certification requirements for food-contact plastics and the country's PLI scheme for specialty chemicals are accelerating domestic metalized BOPP capacity additions. Stakeholders must monitor how extended producer responsibility frameworks and aluminum-recovery targets reshape film-thickness specifications and metallization-layer economics.
Market Dynamics
Pharmaceutical serialization mandates and aluminum-recovery targets are compressing film-thickness tolerances while redirecting converter procurement toward certified metalized grades with documented barrier-performance traceability.
Growth Catalysts
- REACH compliance in Europe:ECHA substance restrictions are redirecting converter procurement toward certified metalized grades with full material-safety documentation for sensitive food-contact applications.
- India's flexible packaging consumption:Domestic pharmaceutical and processed-food sectors are scaling rapidly, concentrating demand for high-barrier metalized BOPP in Mumbai and Ahmedabad packaging corridors.
- Vacuum metallization technology:Advanced coating processes achieving sub-0.1 cc/m²/day oxygen transmission rates are expanding addressable applications into probiotic and biologic packaging formats.
Market Restraints
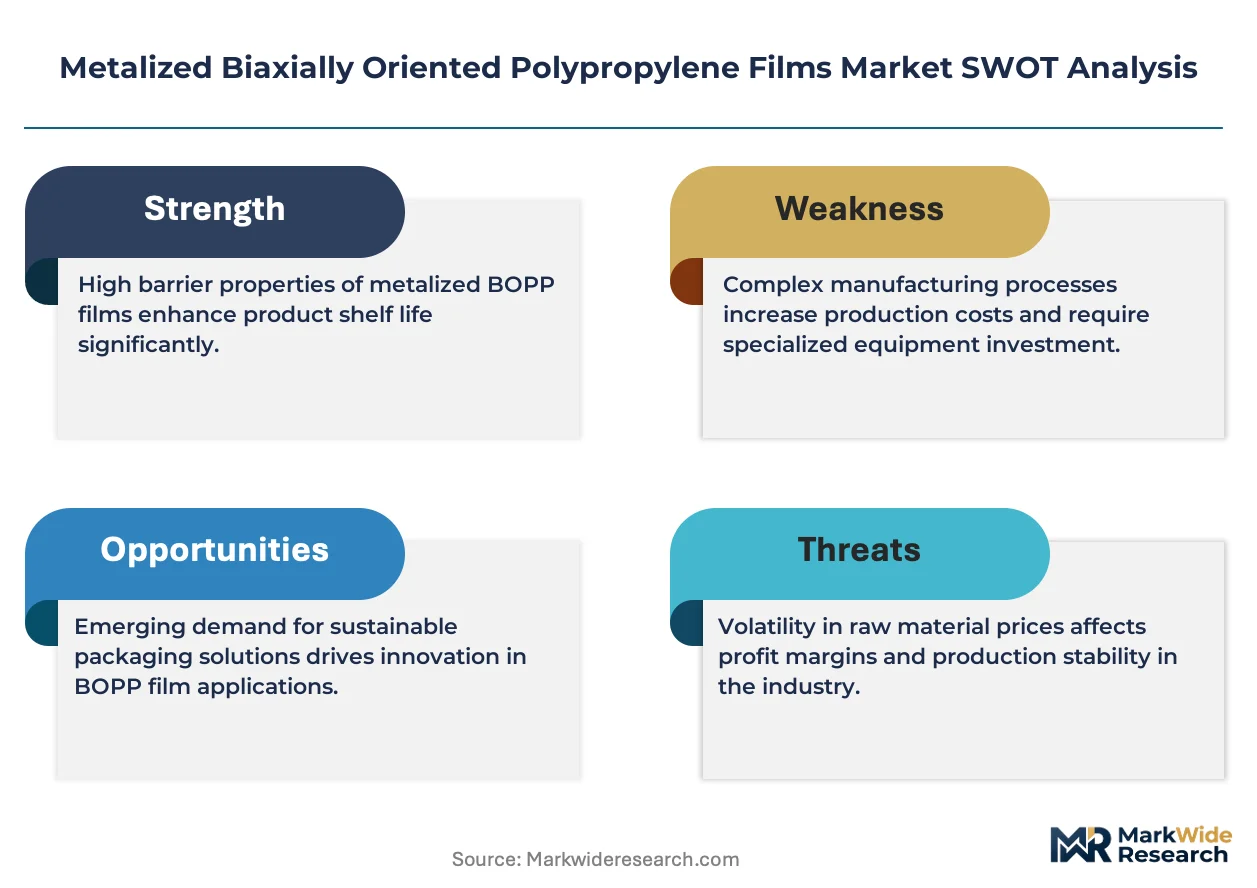
- Aluminum price volatility:Metallization-layer economics remain exposed to London Metal Exchange aluminum fluctuations, squeezing converter margins on fixed-price annual contracts.
- Polypropylene resin concentration:Feedstock supply clusters in the US Gulf Coast and Middle East create geographic vulnerability for Asian film extruders without backward integration into propylene sourcing.
- Mechanical recycling incompatibility:Aluminum-polymer separation complexity limits metalized BOPP eligibility for EU circular-economy packaging mandates under extended producer responsibility frameworks.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Domestic capacity additions for metalized BOPP are attracting fiscal incentives, reducing import dependence for pharmaceutical blister-lidding films.
- Biodegradable substrate convergence:Metallization of bio-based oriented films combines barrier performance with compostability, opening premium positioning in European organic food channels.
- Direct-to-pharma converter relationships:Bypassing traditional distribution layers through dedicated supply agreements with serialization-compliant packaging lines captures specification-led margin pools.
Industry Challenges
- Metallization technician scarcity:Vacuum-coating process optimization requires specialized expertise that outpaces vocational training output in emerging manufacturing hubs.
- FDA material-safety certification timelines:Direct food-contact approval cycles for novel coating chemistries extend 18-24 months, delaying product launches for reformulated barrier variants.
- Legacy form-fill-seal line retrofit costs:Heat-seal temperature compatibility requirements for next-generation metalized grades necessitate capital-intensive sealing-jaw modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metalized Biaxially Oriented Polypropylene Films Market |
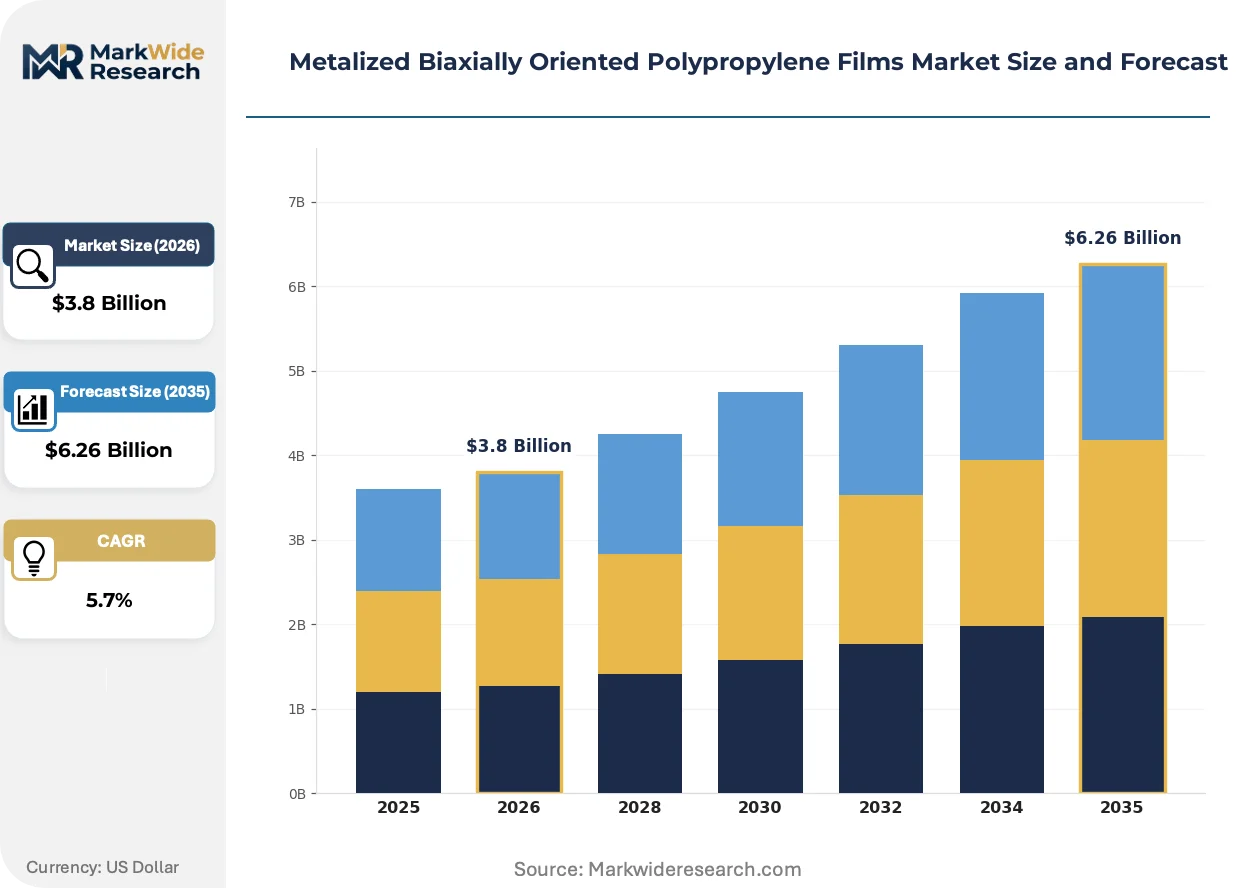
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat-Sealable, Non-Heat-Sealable, Transparent, Opaque Application: Food Packaging, Pharmaceutical Packaging, Industrial Applications, Decorative Use End User: Food Industry, Pharmaceutical Companies, Packaging Manufacturers, Consumer Goods Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Uflex Ltd, Flex Films Inc, Cosmo Films Ltd, VE TIC A S Polinas Plastik, Chiripal Poly Films Ltd, Taghleef Industries, Treofan Group, Shantou Weifeng Plastic Industry Co. Ltd., Jindal Poly Films Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metalized Biaxially Oriented Polypropylene Films Market Strategic Shifts & Innovations
Barrier-performance specifications and circular-economy compliance are converging to redefine metalized film architectures, with substrate innovation and regulatory adaptation outpacing incremental process improvements.
Silicon oxide-coated transparent barrier films are supplanting conventional aluminum-metallized grades in microwaveable and retort applications where metal detection and heating compatibility matter. European ready-meal processors are accelerating qualification timelines for these ceramic-coated alternatives. The shift is compressing addressable volume for standard metalized BOPP in premium food segments while opening margin pools for dual-barrier laminate structures.
EU Packaging and Packaging Waste Directive recyclability mandates are forcing redesign of multi-layer structures containing metalized films. Mechanical recycling incompatibility is driving investment in delamination technologies and mono-material barrier alternatives. German and French packaging converters are prioritizing aluminum-recovery targets that reshape metallization-layer thickness specifications and adhesive selection.
Pharmaceutical buyers are consolidating supplier bases around serialization-ready film providers with integrated track-and-trace documentation. Direct contracting with certified metalized BOPP producers is displacing spot purchasing through regional distributors in North American and European markets. This concentration is most visible in parenteral and oncology drug packaging verticals where tamper-evidence regulations intensify material-traceability requirements.
Metalized Biaxially Oriented Polypropylene Films Market Segmentation
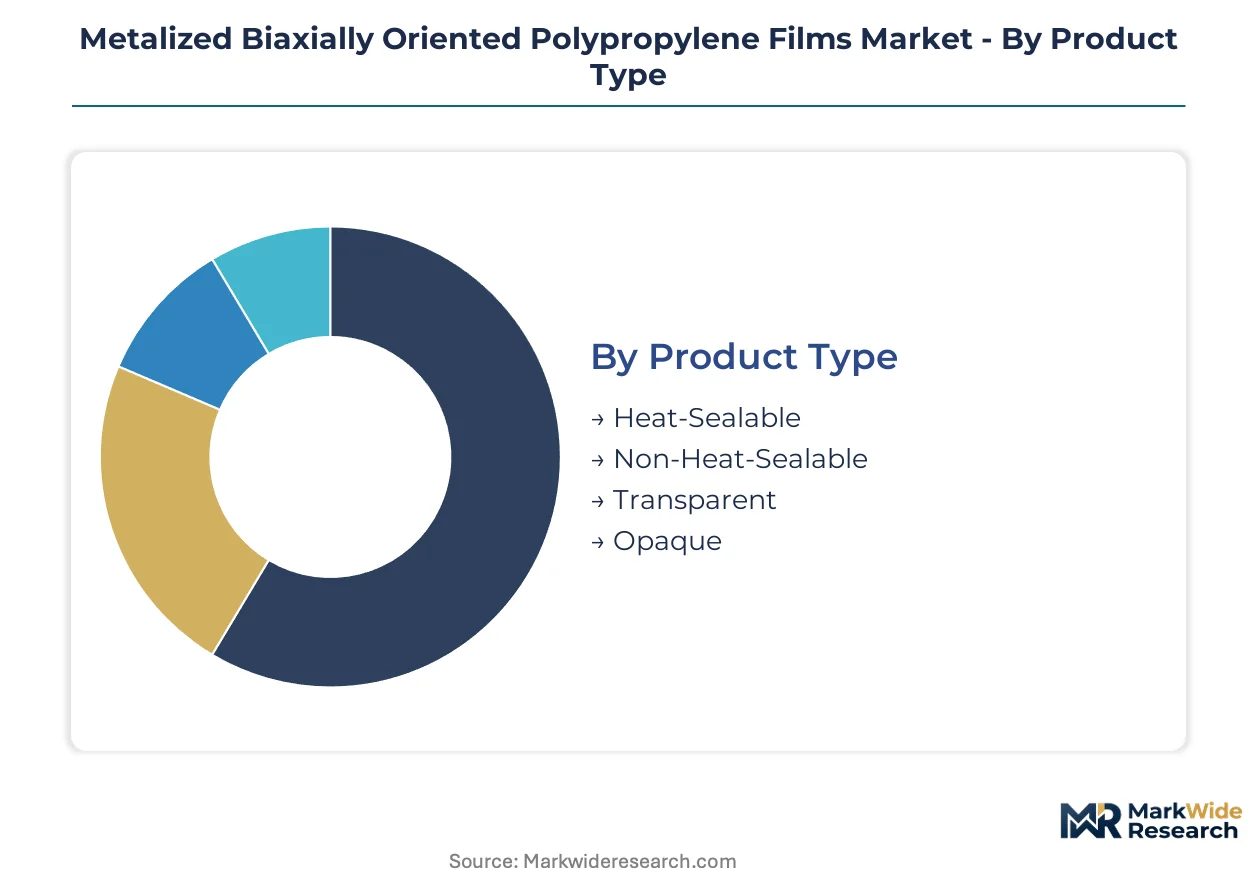
Metalized BOPP procurement patterns diverge sharply across product specifications and end-use requirements. Converter selection criteria prioritize barrier-performance thresholds, heat-seal compatibility, and regulatory certification tiers that reshape volume allocation across segment boundaries.
Product Type:
Silicon oxide and ceramic-coated transparent barriers are displacing conventional aluminum-metallized grades in premium food segments, forcing product-type strategists to defend position through specification differentiation.
- Heat-Sealable:Modified surface layers enable reliable sealing at 120-150°C for high-speed form-fill-seal lines. Pharmaceutical blister packs and snack food pouches in India and Germany concentrate procurement here due to serialization throughput requirements.
- Opaque:Thicker aluminum deposits block light transmission below 0.1% to protect photo-sensitive nutrients and biologics. European organic food channels and parenteral drug packaging in the United States drive specification premiums for this grade.
- Non-Heat-Sealable:Standard metallization without sealant layers serves lamination substrates and industrial barrier applications.
- Transparent:Reduced aluminum thickness maintains optical clarity for retail visibility in consumer goods packaging.
Heat-sealable grades retain volume leadership; opaque variants hold the steepest expansion curve.
Application:
Regulatory serialization mandates and aluminum-recovery targets are compressing film-thickness tolerances while redirecting converter procurement toward certified grades with documented barrier-performance traceability.
- Pharmaceutical Packaging:Blister lidding and cold-form foil replacements demand oxygen transmission rates below 0.1 cc/m²/day. CDSCO serialization requirements in India and FDA material-safety standards in the United States are accelerating qualification timelines for certified metalized BOPP suppliers.
- Food Packaging:Retort pouches and shelf-stable ready meals require moisture barriers exceeding 0.5 g/m²/day. German and French converters prioritize aluminum-recovery compatibility under extended producer responsibility frameworks.
- Industrial Applications:Insulation facing and electronics packaging utilize metalized BOPP for static dissipation and thermal management.
- Decorative Use:Gift wrap and premium labeling exploit metallic aesthetics without functional barrier requirements.
Food packaging retains volume leadership; pharmaceutical packaging is climbing the fastest as tamper-evidence regulations intensify.
End User:
Direct contracting patterns are consolidating supplier relationships around serialization-ready film providers with integrated track-and-trace documentation capabilities.
- Pharmaceutical Companies:Parenteral and oncology drug manufacturers in the United States and Europe bypass distributors for certified metalized BOPP with batch-level traceability. EMA serialization mandates and FDA material-safety certifications filter procurement toward specification-led tiers.
- Packaging Manufacturers:Flexible packaging converters in Mumbai and Ahmedabad corridors scale metalized BOPP consumption for domestic pharmaceutical and processed-food sectors.
- Food Industry:Ready-meal processors and snack food brands specify barrier grades based on shelf-life targets and retail channel requirements.
- Consumer Goods:Cosmetics and household product brands utilize decorative metallization for shelf differentiation.
Packaging manufacturers retain volume leadership; pharmaceutical companies are gaining share fastest through direct supply agreements.
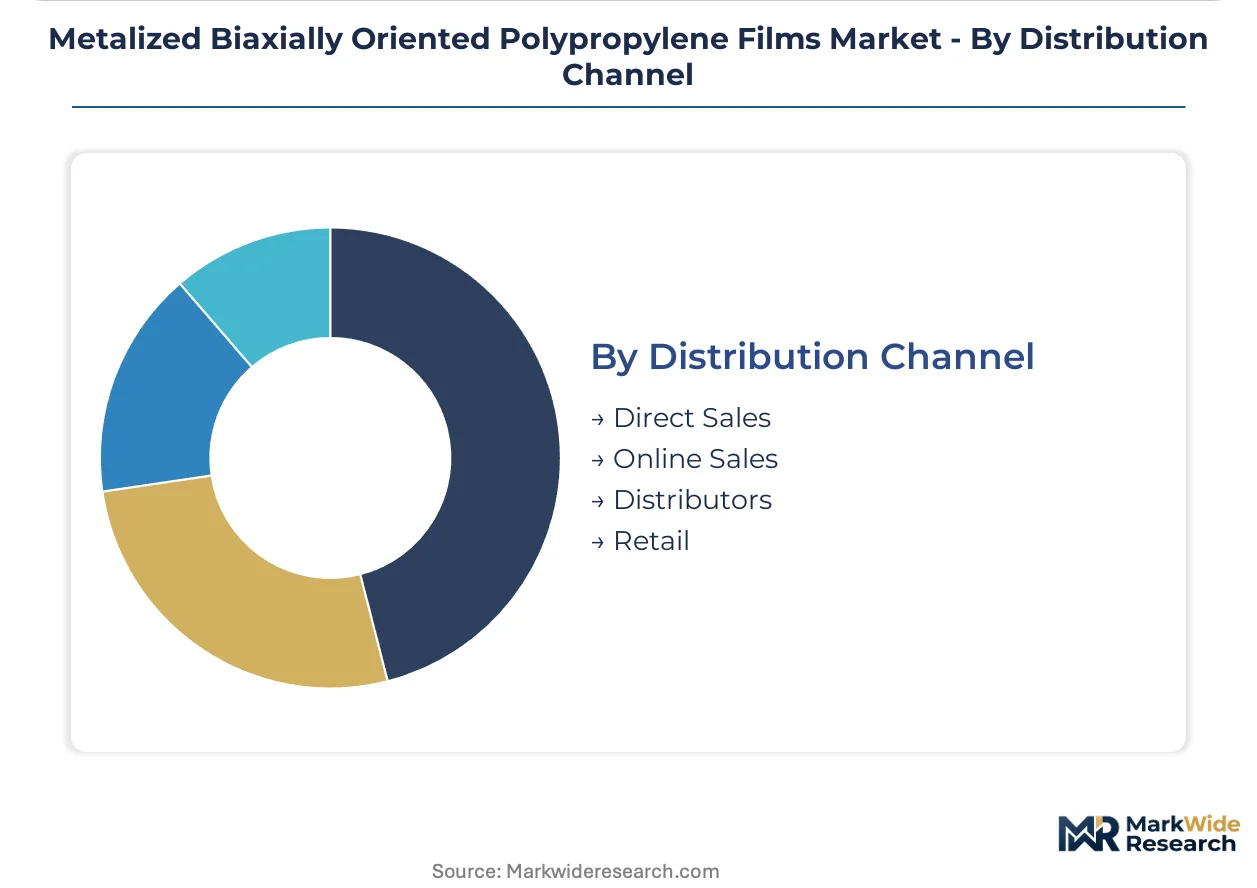
Distribution Channel:
Channel economics reflect the tension between specification complexity requiring technical support and cost pressure favoring transactional purchasing.
- Direct Sales:Dedicated supply agreements with serialization-compliant packaging lines capture specification-led margin pools. North American and European pharmaceutical buyers consolidate procurement here to secure barrier-performance traceability.
- Distributors:Regional inventory stocking serves smaller converters with variable demand patterns and limited technical staff.
- Online Sales:E-procurement platforms penetrate standard-grade segments with documented specifications and rapid quotation turnaround.
- Retail:Limited to small-volume decorative applications and sample procurement for qualification trials.
Direct sales retains volume leadership; online sales is expanding most quickly in commodity-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports metalized BOPP films to pharmaceutical packaging converters across Southeast Asia and the Middle East, while Germany serves as the primary European supply hub for certified barrier-grade films.
United States
FDA material-safety standards govern direct food-contact approvals for metalized BOPP, compressing certification timelines for novel coating chemistries. Serialization mandates for pharmaceutical packaging redirect procurement toward certified suppliers with batch-level traceability. Flexible packaging converters in New Jersey and Pennsylvania concentrate demand for high-barrier grades serving parenteral drug manufacturers.
Germany
EU Packaging and Packaging Waste Directive recyclability mandates force redesign of multi-layer structures containing metalized films. ECHA substance restrictions under REACH redirect converter procurement toward certified grades with full material-safety documentation. Packaging converters in Bavaria and North Rhine-Westphalia prioritize aluminum-recovery targets that reshape metallization-layer specifications.
India
Domestic pharmaceutical and processed-food sectors scale rapidly, concentrating demand for high-barrier metalized BOPP. BIS certification requirements for food-contact plastics and the PLI scheme for specialty chemicals accelerate domestic capacity additions. Flexible packaging corridors in Mumbai and Ahmedabad drive procurement volume for blister-lidding and snack food applications.
China
GB standards for food-contact plastics and dual carbon goals reshape metallization energy intensity requirements for film producers. Vacuum metallization technology investments achieve sub-0.1 cc/m²/day oxygen transmission rates for probiotic packaging formats. Manufacturing clusters in Zhejiang and Jiangsu provinces supply both domestic converters and export markets across Southeast Asia.
Japan
METI industrial policy supports advanced barrier film development for sensitive pharmaceutical and electronics applications. PMDA serialization requirements for drug packaging intensify material-traceability demands on metalized BOPP suppliers. Industrial packaging demand concentrates in the Osaka-Kobe corridor for high-precision electronics barrier applications.
Metalized Biaxially Oriented Polypropylene Films Market Key Industry Players
Listed leaders compete with private specialists across capital intensity and specification breadth, producing a tiered structure where scale-driven volume players coexist with R&D-focused niche operators. The vendor base separates into three strategic archetypes: integrated resin-to-film producers capturing cost leadership, specialty coaters commanding premium positioning in pharmaceutical grades, and regional converters serving localized flexible packaging demand. Dominant competitive moves include backward integration into propylene sourcing and dedicated line investments for serialization-compliant film production.
Within the integrated producer tier, Uflex Ltd and Jindal Poly Films Limited represent scale-driven operations spanning multiple continents, while Cosmo Films Ltd exemplifies the R&D-intensive specialist archetype focused on coated variants for sensitive applications. Taghleef Industries anchors European supply positioning through dedicated metalized BOPP lines. These three named entities collectively illustrate how competitive positioning bifurcates between specification-led and commodity tiers across the analysis window.
| Leading Market Players |
|---|
| Uflex Ltd |
| Flex Films Inc |
| Cosmo Films Ltd |
| VE TIC A S Polinas Plastik |
| Chiripal Poly Films Ltd |
| Taghleef Industries |
| Treofan Group |
| Shantou Weifeng Plastic Industry Co. Ltd. |
| Jindal Poly Films Limited |
| Others |
Cost & Logistics Intelligence
Capacity utilization at integrated resin-to-film facilities in India and the Middle East establishes cost floors that commodity-grade producers cannot undercut without sacrificing metallization-layer uniformity. These scale economies concentrate pricing power among backward-integrated operators while forcing independent extruders toward specialty coated variants where certification premiums offset feedstock disadvantage.
Pricing Analysis
Next-generation silicon oxide barrier films command 40-60% premiums over conventional aluminum-metallized grades, while legacy transparent variants face persistent margin compression. Three-tier pricing structure across pharmaceutical-certified, food-contact standard, and industrial economy levels reflects divergent barrier-performance traceability requirements. Pricing pressure stems from London Metal Exchange aluminum volatility squeezing converter margins on annual fixed-price contracts. Pharmaceutical companies exhibit lowest price sensitivity due to serialization compliance imperatives, while snack food converters in India demonstrate highest elasticity to metallization-layer cost fluctuations.
Supply Chain Analysis
Strait of Hormuz transit vulnerability exposes polypropylene resin shipments from Middle Eastern crackers to Asian film extruders, amplifying cost volatility during regional tensions. Propylene feedstock clusters in the US Gulf Coast, Saudi Arabia, and South Korea anchor global BOPP substrate supply. Metallization-grade aluminum sourcing draws from Australian bauxite refining and Chinese smelter output. Single-source vulnerability concentrates in vacuum metallization equipment where German and Japanese OEMs dominate coating line installations. Distribution runs through direct sales agreements with serialization-compliant pharmaceutical converters and regional distributor networks serving smaller flexible packaging operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon oxide and ceramic-coated transparent barriers threaten aluminum-metallized BOPP incumbents with superior microwave compatibility and simplified recycling streams, forcing defensive repositioning around pharmaceutical serialization moats.
For Market Incumbents: Secure pharmaceutical serialization-ready capacity with integrated track-and-trace documentation to defend against ceramic-coated substitute penetration in premium food segments. Deepen backward integration into propylene sourcing to insulate margin structures from Gulf Coast feedstock volatility. Prioritize CDSCO and FDA material-safety certification investments that create switching costs for parenteral drug packaging accounts.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized specialty chemicals corridor where domestic blister-lidding film demand outpaces local metallization capacity. Target pharmaceutical packaging converters in Mumbai and Ahmedabad bypassing established distributor relationships through dedicated supply agreements. Exploit metallization technician scarcity by recruiting vacuum-coating specialists from legacy European operations to accelerate qualification timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors R&D-intensive specialists with coated variant pipelines over commodity-scale extruders facing ceramic substitution headwinds. Long-term viability hinges on serialization compliance infrastructure and pharmaceutical direct-contracting relationships rather than spot-market food packaging exposure. Watch aluminum-recovery target implementation in Germany and France as inflection indicator for metallization-layer thickness specification shifts that favor delamination-technology investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Sourcing | Captive feedstock supply from US Gulf Coast crackers insulates margin structures from resin price volatility. |
| Pharmaceutical Serialization Certification | FDA material-safety and CDSCO track-and-trace documentation create switching costs for parenteral drug packaging accounts. |
| Silicon Oxide Coating Line Investment | Ceramic barrier technology captures microwaveable ready-meal processors abandoning aluminum-metallized grades. |
| Direct-to-Pharma Converter Relationships | Bypassing regional distributors secures specification-led margin pools in oncology and biologics packaging verticals. |
| Aluminum Recovery Technology Partnership | Delamination capabilities address EU Packaging and Packaging Waste Directive recyclability mandates for multi-layer structures. |
Research Approach
Cross-validation between primary interviews with vacuum metallization technicians, pharmaceutical packaging procurement directors, and flexible packaging converter operations managers anchors the qualitative findings on barrier-performance specification evolution. Secondary validation draws from BIS certification databases, ECHA REACH substance restriction filings, FDA material-safety approval records, and customs trade data on polypropylene resin shipments. Bottom-up triangulation across film extrusion capacity installations and top-down reconciliation against pharmaceutical packaging demand aggregates support volume and value estimates.
Sensitivity analysis on aluminum price trajectories, propylene feedstock spreads, and pharmaceutical serialization compliance timelines frames the projection uncertainty across the analysis window. Segmentation modeling incorporates product type differentiation, application-specific barrier-performance thresholds, end-user direct-contracting patterns, and regional regulatory cluster variations. CAGRs derive from installed capacity utilization trends and qualification pipeline velocities for serialization-compliant film grades.
Material uncertainties — EMA serialization mandate acceleration, EU aluminum-recovery target enforcement, and ceramic-coated barrier film adoption curves — sit outside the modeled envelope. Forecasts reflect assumptions on metallization-layer thickness specifications and pharmaceutical direct-penetration rates. Revision becomes warranted when silicon oxide coating cost curves cross aluminum-metallized grade parity thresholds in European ready-meal packaging applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
Battery Separator Films Market
Specialty Materials
Europe Polyether Ether Ketone (Peek) Market
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Jesmonite Market
Specialty Materials
Non-Semiconductor Neon Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
Medical Grade Silicone Market
Specialty Materials
Barium Fluoride Market
Specialty Materials
Retro Reflective Materials Market
Specialty Materials
Global Synthetic Zeolite Market
Specialty Materials
Specialty Carbon Black Market
Specialty Materials
Polyetherimide (PEI) Market
Specialty Materials
Global Beeswax Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market