
 Global Healthcare Content Management System Market | 2026-2036
Global Healthcare Content Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Content Management System Market Foresight
HITRUST CSF certification is bifurcating the competitive landscape into qualified and non-qualified vendors. Epic Systems leverages its deep integration with hospital EHR workflows to anchor enterprise deployments across major academic medical centers. Microsoft competes through Azure cloud infrastructure and Teams-based collaboration layers that extend into clinical environments. Hyland Software specializes in document capture and content services, occupying niche positions where legacy archive modernization drives procurement decisions.
A healthcare content management system comprises software platforms that ingest, index, secure, and route clinical and administrative content through structured workflows, typically supporting HL7 FHIR interoperability and DICOM image handling. These systems serve the primary commercial purpose of replacing paper-based records with searchable digital repositories that synchronize with electronic health records. Cloud-based deployment leads segment adoption as hospitals prioritize capital expenditure reduction and remote access resilience. Patient data management represents the fastest-growing application area where real-time synchronization between diagnostic devices and enterprise archives reduces retrieval latency. On-premise installations retain share in research institutes where local data sovereignty requirements govern specimen and trial record handling.
FDA 21 CFR Part 11, HIPAA Security Rule, and GDPR shape product development roadmaps by mandating audit trails, encryption standards, and patient consent workflows that vendors must embed at the platform layer. EMA's MDR and FDA quality system regulations further tighten validation requirements for systems managing clinical trial documentation and post-market surveillance records. Stakeholders must monitor how emerging EU AI Act provisions classify algorithmic content extraction tools and whether NIST cybersecurity frameworks extend mandatory certification timelines for cloud-hosted clinical archives.
Market Dynamics
Cloud migration mandates from HIPAA and GDPR enforcement are compressing hospital procurement cycles, forcing vendors to embed compliance certifications directly into platform architectures rather than retrofitting legacy installations.
Growth Catalysts
- Interoperability mandates:HL7 FHIR adoption requirements from the US Office of the National Coordinator for Health IT are accelerating replacement of siloed document archives with synchronized clinical repositories.
- Diagnostic device proliferation:DICOM imaging volumes from MRI and CT manufacturers are overwhelming on-premise storage capacities, pushing radiology departments toward elastic cloud architectures.
- Research institute digitization:Specimen tracking protocols at German Max Planck Institutes and US NIH facilities are generating demand for validated content platforms that satisfy 21 CFR Part 11 audit trail requirements.
Market Restraints
- Specialized engineering talent scarcity:Healthcare IT architects with dual expertise in clinical workflows and cloud security command premium compensation, constraining vendor expansion velocity.
- Input cost volatility:GPU-intensive AI indexing modules face pricing pressure from NVIDIA datacenter chip allocation constraints and energy cost spikes at hyperscale facilities.
- Regulatory friction:EU AI Act classification uncertainty for algorithmic document extraction tools is freezing procurement decisions at French and Dutch hospital networks awaiting compliance clarity.
Strategic Opportunities
- Underpenetrated secondary markets:Brazil's ANVISA is streamlining medical software registration, opening procurement pathways for cloud-native vendors previously blocked by import certification complexity.
- Technology convergence:Natural language processing engines are merging with voice-to-text clinical documentation, creating new product categories for ambulatory surgical centers.
- Regulatory tailwind:India's PLI scheme for medical device manufacturing is incentivizing domestic production of diagnostic equipment, generating localized content management demand.
Industry Challenges
- Integration complexity:Epic Systems and Cerner EHR environments require custom API development for content platform connectivity, extending implementation timelines and inflating professional services costs.
- Certification timeline compression:HITRUST CSF validation cycles now span 14-18 months, delaying revenue recognition for vendors pursuing enterprise hospital contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Content Management System Market |
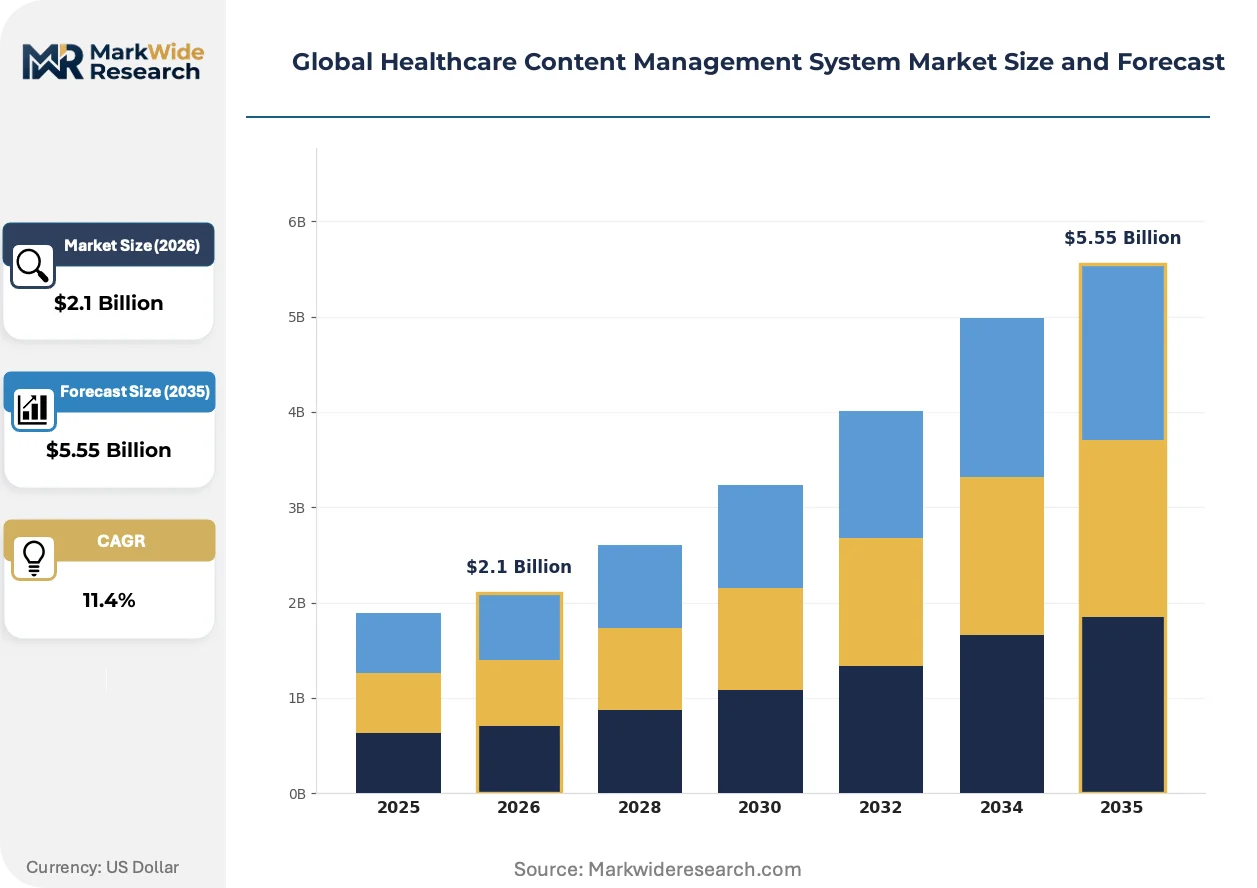
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Digital Asset Management, Records & Archive Management, Workflow Management, Collaboration Tools Application: Patient Data Management, Clinical Documentation, Regulatory Compliance, Billing & Coding, Research Data Handling End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutes, Telehealth Providers Deployment: Cloud-based, On-Premise, Hybrid, Managed Services |
| Companies Covered | Microsoft, Epic Systems, Hyland Software, athenahealth, Oracle Health, OpenText, Oracle, Xerox Corporation, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Content Management System Market Shifts & Advancements
Artificial intelligence is embedding into clinical documentation workflows, compressing the gap between diagnostic capture and EHR synchronization while forcing vendors to rearchitect security models around algorithmic data handling.
Edge computing nodes for clinical content processing are miniaturizing to fit within hospital server closets, enabling real-time document indexing without latency to distant cloud regions. Community health systems with limited IT infrastructure are deploying these compact units to achieve sub-second retrieval speeds previously reserved for academic medical centers. This distributed architecture is miniaturizing the traditional enterprise content management footprint, allowing smaller facilities to bypass multi-year datacenter construction projects.
The EU AI Act's risk classification framework for medical software is forcing vendors to restructure algorithm development pipelines, separating high-risk diagnostic tools from administrative automation features. Systems managing clinical trial documentation now require conformity assessments under MDR Annex XVI, extending validation timelines. German university hospitals are responding by bifurcating procurement, purchasing administrative modules separately from AI-enabled clinical functions to isolate regulatory exposure.
Hospital purchasing committees are consolidating vendor relationships, preferring integrated platform suites over point solutions that require separate security audits. This concentration is displacing standalone document capture specialists from multi-hospital IDN contracts. The shift is most visible across US integrated delivery networks, where procurement teams now mandate single-vendor accountability for both EHR and content archive performance metrics.
Global Healthcare Content Management System Market Segmentation
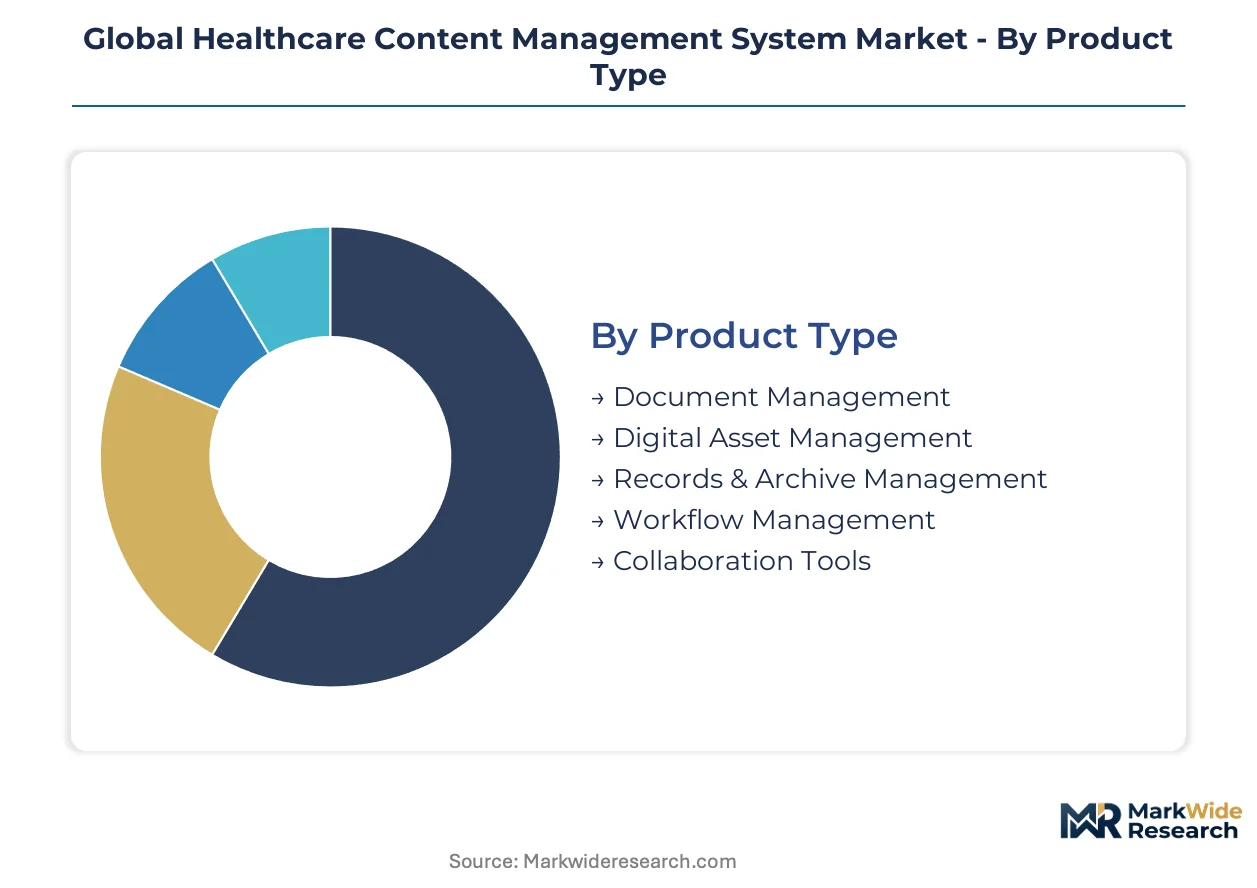
Healthcare content management systems fragment across four structural dimensions that determine procurement patterns and vendor positioning. Product architecture dictates integration complexity with Epic and Cerner environments. Deployment mode governs capital intensity and compliance certification requirements. Application focus separates high-growth patient data synchronization from mature billing automation segments.
Product Type:
Margin pools concentrate in workflow orchestration layers that command recurring subscription premiums, while document capture utilities face commoditization from open-source alternatives.
- Document Management:Core ingestion and indexing engines process HL7 FHIR messages and DICOM imaging streams into searchable repositories. US academic medical centers in Boston and Houston are consolidating procurement around platforms with embedded FDA 21 CFR Part 11 validation, replacing fragmented legacy archives that required manual audit trail reconciliation.
- Workflow Management:Clinical pathway automation tools route documents through approval hierarchies and trigger EHR synchronization events. German university hospitals in Munich and Heidelberg are prioritizing these modules to satisfy GDPR Article 32 security requirements while reducing administrative bottlenecks in multi-site care networks.
- Digital Asset Management:Specialized repositories for marketing materials and physician education content with version control and rights management.
- Records & Archive Management:Long-term retention systems with WORM storage and legal hold capabilities for litigation readiness.
- Collaboration Tools:Real-time co-authoring and annotation features for multidisciplinary care team coordination.
Workflow Management holds installed capacity. Document Management is rotating up the share rankings.
Application:
Application segmentation separates high-velocity clinical workflows from administrative back-office functions with divergent latency and compliance requirements.
- Patient Data Management:Real-time synchronization platforms connecting diagnostic devices, wearable sensors, and enterprise archives through FHIR APIs. Diagnostic laboratories at Mayo Clinic and Cleveland Clinic are deploying these systems to eliminate retrieval delays that previously extended specialist consultation timelines.
- Clinical Documentation:Voice-to-text and NLP-powered transcription tools that structure unstructured physician notes for EHR ingestion. Telehealth providers across California and Texas are adopting these solutions to maintain documentation quality amid rapid virtual visit expansion without proportional scribe hiring.
- Regulatory Compliance:Audit trail generation and consent management modules for HIPAA and GDPR documentation.
- Billing & Coding:Automated charge capture and ICD-10 classification tools integrated with revenue cycle management.
- Research Data Handling:Specimen tracking and clinical trial document repositories with 21 CFR Part 11 electronic signature support.
Patient Data Management commands the steepest expansion trajectory. Clinical Documentation is gaining share fastest in ambulatory settings.
End User:
Customer type determines implementation complexity, with integrated delivery networks demanding enterprise-wide standardization while independent clinics prioritize rapid deployment.
- Hospitals:Multi-department deployments spanning radiology, pathology, and administrative services with 99.99% uptime SLAs. Kaiser Permanente and Intermountain Healthcare are mandating HITRUST CSF certification as a non-negotiable qualification criterion, filtering vendor pools before technical evaluation begins.
- Research Institutes:Validated environments for FDA-regulated clinical trials with stringent change control protocols. NIH facilities in Bethesda and Max Planck Institutes in Berlin require local data sovereignty guarantees that restrict cloud-only deployment options.
- Clinics:Smaller-scale implementations prioritizing interoperability with regional hospital EHR networks.
- Diagnostic Laboratories:High-throughput DICOM storage and retrieval systems for imaging-heavy operations.
- Telehealth Providers:Lightweight cloud-native solutions with minimal on-premise infrastructure requirements.
Hospitals anchor procurement volume. Research Institutes are climbing the fastest in specialized platform investment.
Deployment:
Deployment architecture governs total cost of ownership trajectories and regulatory audit scope, with hybrid models emerging as the compromise position for risk-averse institutions.
- Cloud-based:Elastic infrastructure with automatic patching and geographic redundancy delivered through AWS, Azure, or Google Cloud. French hospital networks in Paris and Lyon are accelerating migration to satisfy CNIL guidance on data localization while avoiding capital-intensive datacenter construction.
- On-Premise:Dedicated hardware installations with full administrative control over encryption key management. Saudi Arabia's SFDA is incentivizing this model for government hospitals through domestic server procurement mandates that support Vision 2030 localization objectives.
- Hybrid:Split architectures keeping sensitive patient data local while archiving non-critical content to cloud tiers.
- Managed Services:Outsourced operational responsibility including backup, disaster recovery, and compliance monitoring.
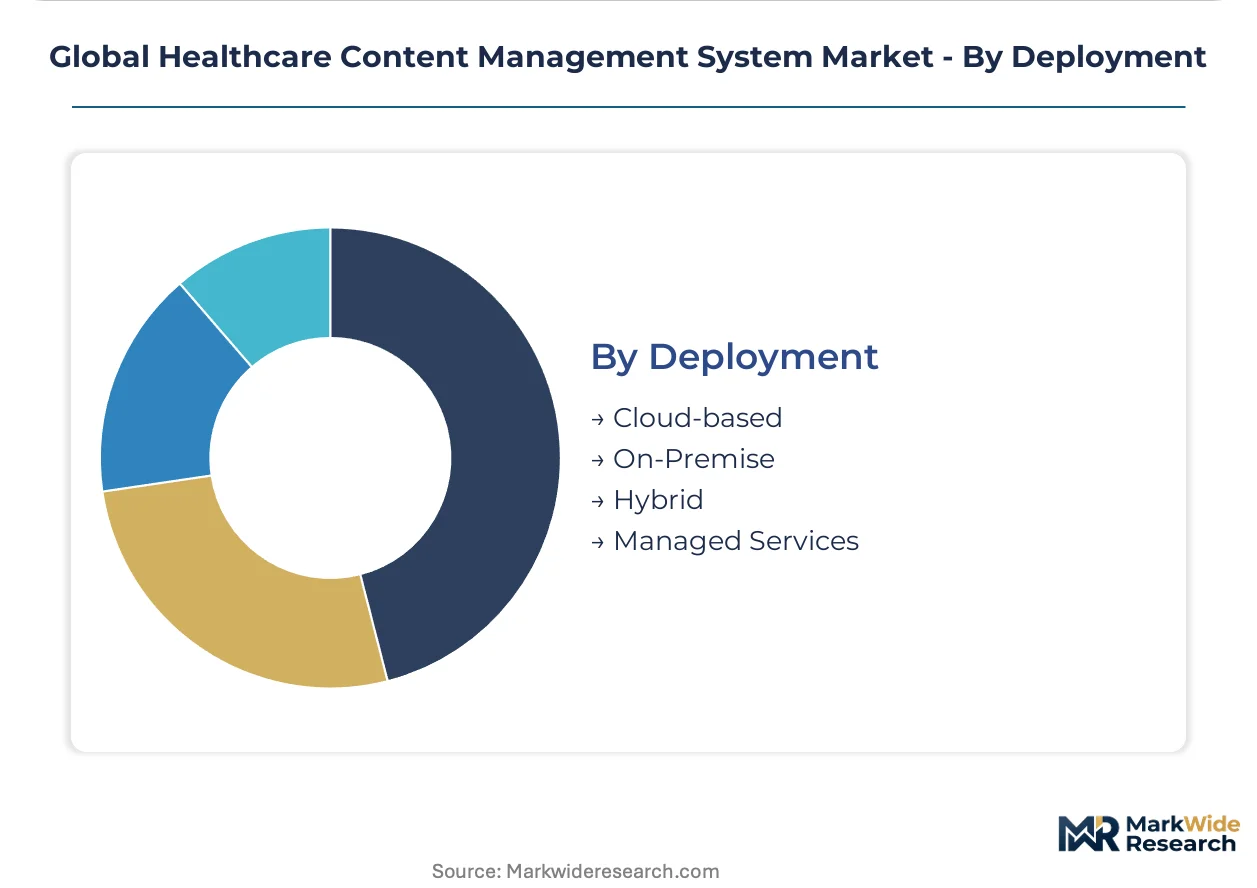
Cloud-based dominates new contract flow. Hybrid is rotating up the share rankings as migration strategies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in integrated delivery networks dominate purchasing authority, with cloud migration mandates compressing vendor qualification timelines across major healthcare markets.
United States
Kaiser Permanente and Intermountain Healthcare are mandating HITRUST CSF certification as a non-negotiable gate for enterprise contracts. HIPAA Security Rule enforcement from the Office for Civil Rights is accelerating replacement of legacy document archives. Academic medical centers in Boston and Houston are consolidating procurement around platforms with embedded FDA 21 CFR Part 11 validation.
Germany
University hospitals in Munich and Heidelberg are prioritizing workflow automation modules to satisfy GDPR Article 32 security requirements. The BfArM is tightening medical software registration timelines, filtering vendor pools before technical evaluation. Max Planck Institutes across Bavaria and Baden-Württemberg require local data sovereignty guarantees that restrict cloud-only deployment options.
France
Hospital networks in Paris and Lyon are accelerating migration to cloud infrastructure to satisfy CNIL guidance on data localization. ANSM is streamlining conformity assessment pathways for clinical documentation platforms. The Île-de-France cluster is consolidating vendor relationships, preferring integrated platform suites over point solutions requiring separate security audits.
Brazil
ANVISA is streamlining medical software registration, opening procurement pathways for cloud-native vendors previously blocked by import certification complexity. Large hospital networks in São Paulo and Rio de Janeiro are compressing procurement cycles to satisfy emerging interoperability mandates. Domestic health IT integrators are forming partnerships with international platform vendors to meet local data residency requirements.
India
India's PLI scheme for medical device manufacturing is incentivizing domestic production of diagnostic equipment, generating localized content management demand. CDSCO is tightening software-as-medical-device classification, extending validation timelines for foreign vendors. Hospital chains in Maharashtra and Karnataka are deploying hybrid architectures to balance cloud elasticity with data sovereignty preferences.
Global Healthcare Content Management System Market Competitive Landscape
Player mix skews toward cloud infrastructure specialists with healthcare compliance certifications, creating a tiered structure where HITRUST-qualified vendors command premium positioning. The competitive landscape fragments across three strategic archetypes: EHR-integrated platform vendors, standalone document management specialists, and hyperscale cloud providers extending into clinical environments. Dominant competitive moves include strategic partnerships with hospital networks and portfolio diversification into adjacent workflow automation modules.
Within the EHR-integrated tier, Epic Systems and Oracle Health exemplify vendors leveraging deep workflow integration to anchor enterprise deployments. Microsoft occupies a distinct position among hyperscale providers, extending Azure infrastructure and collaboration layers into clinical environments. Hyland Software represents the document capture specialist archetype, occupying niche positions where legacy archive modernization drives procurement decisions.
| Leading Market Players |
|---|
| Microsoft |
| Epic Systems |
| Hyland Software |
| athenahealth |
| Oracle Health |
| OpenText |
| Oracle |
| Xerox Corporation |
| IBM |
| Others |
Supply & Pricing Matrix
Cloud infrastructure substitution for on-premise datacenter hardware simultaneously shifts supply geography toward hyperscale regions in Virginia and Frankfurt while compressing pricing economics through consumption-based billing models that eliminate upfront capital recovery premiums.
Pricing Analysis
Cost-plus contracts with CPI indexation anchor enterprise hospital procurement, though HITRUST CSF certification tiering now stratifies pricing across qualified and non-qualified vendor pools. Subscription tiers separate Epic-integrated deployments from standalone document management licenses, with customization depth and API volume driving variance. Pricing pressure stems from GPU-intensive AI indexing modules facing NVIDIA datacenter allocation constraints. Independent clinics exhibit highest price sensitivity, while academic medical centers prioritize compliance-grade premiums.
Supply Chain Analysis
Hyperscale cloud region concentration in Northern Virginia, Frankfurt, and Singapore underwrites global service delivery for clinical content platforms. Software development draws from engineering talent pools in Bangalore, Warsaw, and São Paulo, with specialized healthcare IT architects commanding scarcity premiums. Single-source vulnerability sits with NVIDIA GPU supply for AI-enabled document extraction. Distribution runs through direct enterprise sales teams and certified implementation partners serving hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as GDPR Article 32 and HIPAA Security Rule enforcement bifurcates procurement between compliance-ready platforms and legacy archives requiring expensive retrofitting.
For Market Incumbents: Shield installed base through embedded HITRUST CSF certification workflows that raise switching costs for hospital IDNs. Deepen API integration with Epic and Cerner environments to extend professional services revenue. Counter emerging cloud-native entrants by acquiring workflow automation specialists that compress implementation timelines.
For New Entrants and Emerging Players: Anchor in Brazil's ANVISA-streamlined registration pathway and India's PLI-scheme diagnostic equipment ecosystem where incumbent presence remains thin. Target ambulatory surgical centers with voice-to-text clinical documentation bundles that bypass complex EHR integration requirements. Pursue channel partnerships with domestic health IT integrators to satisfy data residency mandates.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed document capture specialists holding legacy archive modernization contracts at German Max Planck Institutes and US research facilities. Five-to-ten year viability hinges on successful cloud migration execution and AI feature monetization. Monitor EU AI Act conformity assessment timelines as inflection indicator for algorithmic content extraction tool valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Epic-integrated deployments at Kaiser Permanente anchor multi-year recurring revenue streams. |
| Platform Integration | FHIR API connectivity with Cerner environments reduces implementation friction for IDN procurement. |
| Acquisition of Specialist Firm | Workflow automation modules from German university hospital suppliers compress GDPR compliance timelines. |
| Geographic Expansion | ANVISA registration in São Paulo opens procurement pathways previously blocked by import certification. |
| Software Companion Development | Edge computing nodes for clinical content processing enable sub-second retrieval at community health systems. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, hospital GPO contracts, and hyperscaler healthcare compliance disclosures. Primary inputs drew from hospital CIOs, biomedical informatics directors, HITRUST certification auditors, and EHR integration specialists. Secondary validation incorporated CMS Medicare reimbursement data, Epic Systems user group documentation, and EU MDR conformity assessment records. Bottom-up facility-level deployment estimates triangulated against top-down vendor revenue attribution.
Segmentation dimensions modeled span deployment architecture, application focus, end-user type, and geographic regulatory cluster. Revenue projections across the analysis window derived from facility penetration rates, module attachment rates, and subscription pricing trajectories. CAGR derivation incorporated replacement cycle compression from HIPAA enforcement and cloud migration elasticity assumptions.
Material uncertainties — EU AI Act classification finalization, NVIDIA GPU supply allocation shifts, and hospital capital expenditure freezes — sit outside the modeled envelope. Forecasts reflect assumptions regarding interoperability mandate timelines and certification standardization. Practitioners should keep alternative scenarios live as GDPR enforcement intensity and hyperscale data sovereignty requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Data Democratization in Healthcare Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Medical Record Management System Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market