
 Point-Of-Care Data Management Software Market | 2026-2036
Point-Of-Care Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Point-Of-Care Data Management Software Market Analytics
Homecare agencies are recalibrating procurement priorities as decentralized care models expand. Siemens Healthineers leverages its diagnostic hardware footprint to bundle data management tools across European hospital networks. Abbott Laboratories anchors its position through embedded software on connected glucose monitoring devices. Danaher Corporation competes by sustaining R&D intensity in laboratory informatics that feeds point-of-care workflows.
Point-of-care data management software comprises clinical information systems that capture, store, and transmit diagnostic and patient data at or near the site of care, typically integrating with HL7 FHIR protocols and ISO 27001 security frameworks to ensure interoperability and protection of health records. Cloud-based systems lead deployment preferences as health systems seek elastic infrastructure for multi-site coordination. On-premises solutions retain share in jurisdictions with strict data residency mandates. Mobile applications represent the fastest-expanding feature layer, though margin pools remain concentrated in hybrid platforms that bridge legacy and modern architectures.
FDA software-as-a-medical-device guidance and HIPAA security rules shape product development requirements for US vendors, while GDPR and EU MDR constrain cross-border data flows and clinical validation standards in Europe. Stakeholders must monitor evolving interoperability mandates from ONC and parallel frameworks in other jurisdictions to anticipate certification burdens that will determine market access trajectories.
Market Dynamics
Health system consolidation is compressing vendor procurement cycles while simultaneously demanding interoperable data architectures that bridge acute and ambulatory care environments. This structural pressure rewards platforms capable of unifying diagnostic workflows across fragmented care delivery networks.
Growth Catalysts
- Remote patient monitoring protocols:Homecare agencies now mandate real-time data transmission capabilities as standard contract terms. This operational shift pulls cloud-native architectures into mainstream procurement specifications.
- FDA software-as-a-medical-device guidance:Clarified regulatory pathways reduce compliance uncertainty for algorithm-enabled diagnostic tools. Developers accelerate validation timelines for clinical decision support modules.
- HL7 FHIR protocol adoption:Interoperability mandates from the Office of the National Coordinator for Health IT force legacy system upgrades. Health information exchanges prioritize vendors with certified FHIR application programming interfaces.
Market Restraints
- Data residency compliance costs:Jurisdictions including Germany and France impose strict local storage requirements for protected health information. Cloud providers must maintain fragmented infrastructure footprints.
- Cybersecurity insurance premiums:Ransomware targeting healthcare institutions has tripled policy costs for software vendors. Smaller developers face exclusion from health system vendor panels.
- Legacy hardware dependency:Embedded diagnostic devices with decade-long replacement cycles constrain software refresh rates. Point-of-care instruments lack processing capacity for modern analytics workloads.
Strategic Opportunities
- Rural health clinic digitization:Federally qualified health centers in the United States receive capital grants for telehealth infrastructure. Modular data management platforms capture this underserved installation base.
- Artificial intelligence and edge computing convergence:On-device inference reduces latency for critical diagnostic alerts. Combined architectures enable ambulatory settings to deploy sophisticated triage algorithms.
- Subscription-based service models:Per-patient-per-month pricing aligns vendor revenue with care volume. This structure penetrates price-sensitive community health organizations previously excluded from enterprise licensing.
Industry Challenges
- Clinical informatics specialist scarcity:Health systems compete for talent capable of bridging biomedical knowledge with data architecture design. Implementation timelines extend due to staffing gaps.
- Multi-jurisdiction certification complexity:ISO 27001, SOC 2 Type II, and HITRUST validations require parallel audit tracks. Compliance teams must maintain concurrent documentation for overlapping frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Point-Of-Care Data Management Software Market |
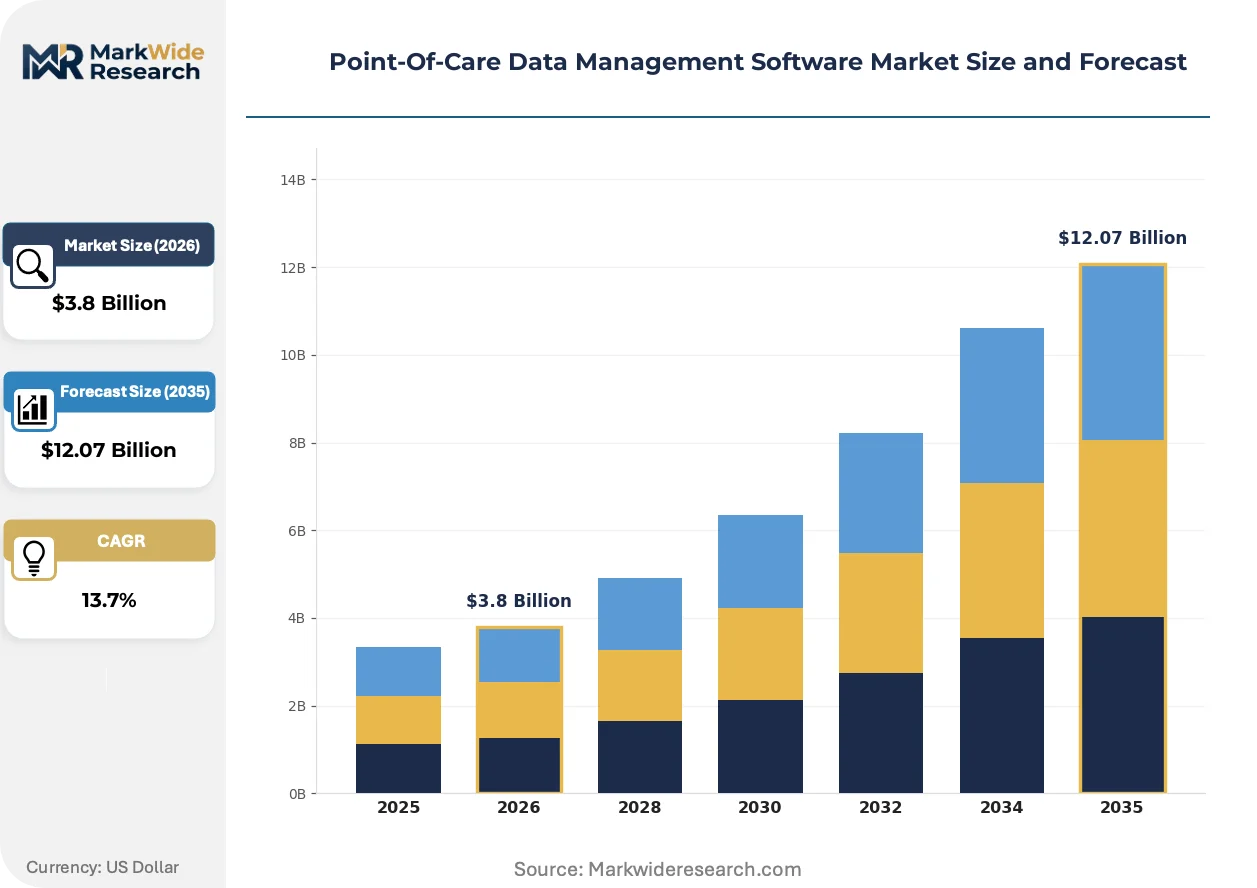
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based Systems, On-premises Solutions, Hybrid Platforms, Mobile Applications End User: Clinics, Hospitals, Homecare Agencies, Diagnostic Centers Deployment Model: Public Cloud, Private Cloud, On-premise, Hybrid Cloud Feature: Data Visualization, Patient Engagement, Interoperability, Analytics Tools |
| Companies Covered | Siemens Healthineers, Abbott Laboratories, Danaher Corporation, Roche Diagnostics Corporation, TELCOR Inc., Thermo Fisher Scientific, Randox Laboratories, Orchard Software Corporation, DataLink Software, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Point-Of-Care Data Management Software Market Evolving Landscape
Edge computing architectures are redistributing analytical workloads away from centralized data centers. This infrastructure shift enables real-time clinical decision support at the point of diagnostic capture.
Containerized microservices are decentralizing software deployment across distributed care networks. Hospital systems operating dozens of satellite clinics adopt modular architectures that update independently. This approach compresses rollout timelines from months to weeks while reducing downtime risks during maintenance windows.
The European Union Medical Device Regulation imposes stricter clinical validation requirements on software with diagnostic functions. Manufacturers must generate prospective performance data for algorithm updates previously deployed through simple patches. This regulatory friction disproportionately affects artificial intelligence-enabled tools, forcing developers to restructure quality management systems around continuous learning models.
Health system procurement committees now unbundle software licensing from hardware procurement decisions. Independent evaluation of data management platforms occurs before diagnostic instrument selection in an increasing share of competitive tenders. This behavioral shift is most pronounced in United States integrated delivery networks consolidating vendor relationships across previously autonomous member hospitals.
Point-Of-Care Data Management Software Market Segmentation
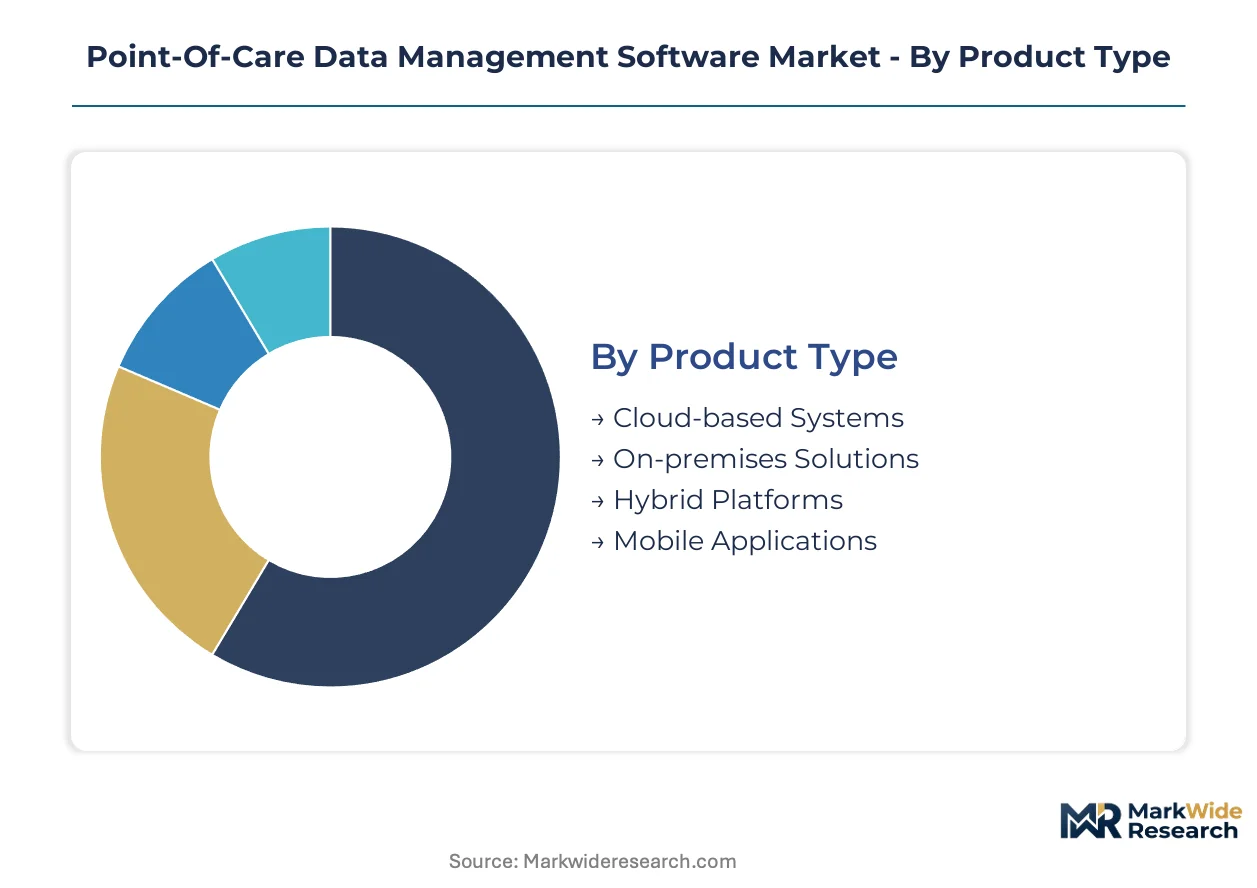
Point-of-care data management software segments diverge sharply across infrastructure maturity and care delivery settings. Procurement patterns cluster around regulatory tolerance for cloud migration and the technical debt carried by legacy diagnostic hardware.
Product Type:
Customization versus standardization tensions surface most acutely here, with cloud-native architectures offering configurable workflows while on-premises solutions demand bespoke integration engineering.
- Cloud-based Systems:Multi-tenant architectures with elastic compute provisioning support real-time synchronization across distributed care sites. Hospital systems in the United States favor these for multi-site coordination under HIPAA business associate agreements, though data residency constraints limit penetration in German-speaking markets.
- On-premises Solutions:Dedicated hardware installations with localized data storage meet strict jurisdictional mandates for protected health information. Diagnostic centers in France and Germany retain these configurations to satisfy CNIL and federal data protection requirements.
- Hybrid Platforms:Bridge architectures connecting legacy instruments to cloud analytics layers.
- Mobile Applications:Lightweight front-ends for bedside data capture and physician alerting.
Most installed capacity flows through Hybrid Platforms. Expansion is steepest in Cloud-based Systems.
End User:
Cost tier stratification separates enterprise health systems from resource-constrained community providers, with procurement authority concentrating at different organizational levels.
- Hospitals:Enterprise license agreements spanning hundreds of connected devices require centralized governance frameworks. Integrated delivery networks in the United States negotiate multi-year contracts bundling software with diagnostic instrument procurement.
- Homecare Agencies:Decentralized workforce models demand lightweight deployment and offline synchronization capabilities. Remote patient monitoring protocols now mandate real-time data transmission as standard contract terms.
- Clinics:Federally qualified health centers access modular platforms through capital grant programs.
- Diagnostic Centers:High-throughput environments prioritize instrument connectivity over patient-facing features.
Hospital procurement dominates current revenue. Homecare Agencies are climbing the fastest.
Deployment Model:
Application criticality and latency requirements determine infrastructure placement, with clinical decision support algorithms driving edge-proximity decisions.
- Public Cloud:Shared infrastructure with consumption-based pricing suits non-critical analytics and population health reporting. Community health organizations leverage these cost structures for previously unaffordable capabilities.
- Private Cloud:Single-tenant environments with dedicated security controls serve health systems with elevated risk tolerance thresholds. Large United States academic medical centers deploy these for research-clinical data integration.
- On-premise:Air-gapped installations for maximum control over threat surface.
- Hybrid Cloud:Workload-specific placement balancing latency against cost.
Private Cloud carries the heaviest current deployment. Hybrid Cloud is gaining share fastest.
Feature:
Customer type differentiation separates clinically oriented modules from operational efficiency tools, with purchasing committees evaluating ROI on divergent timelines.
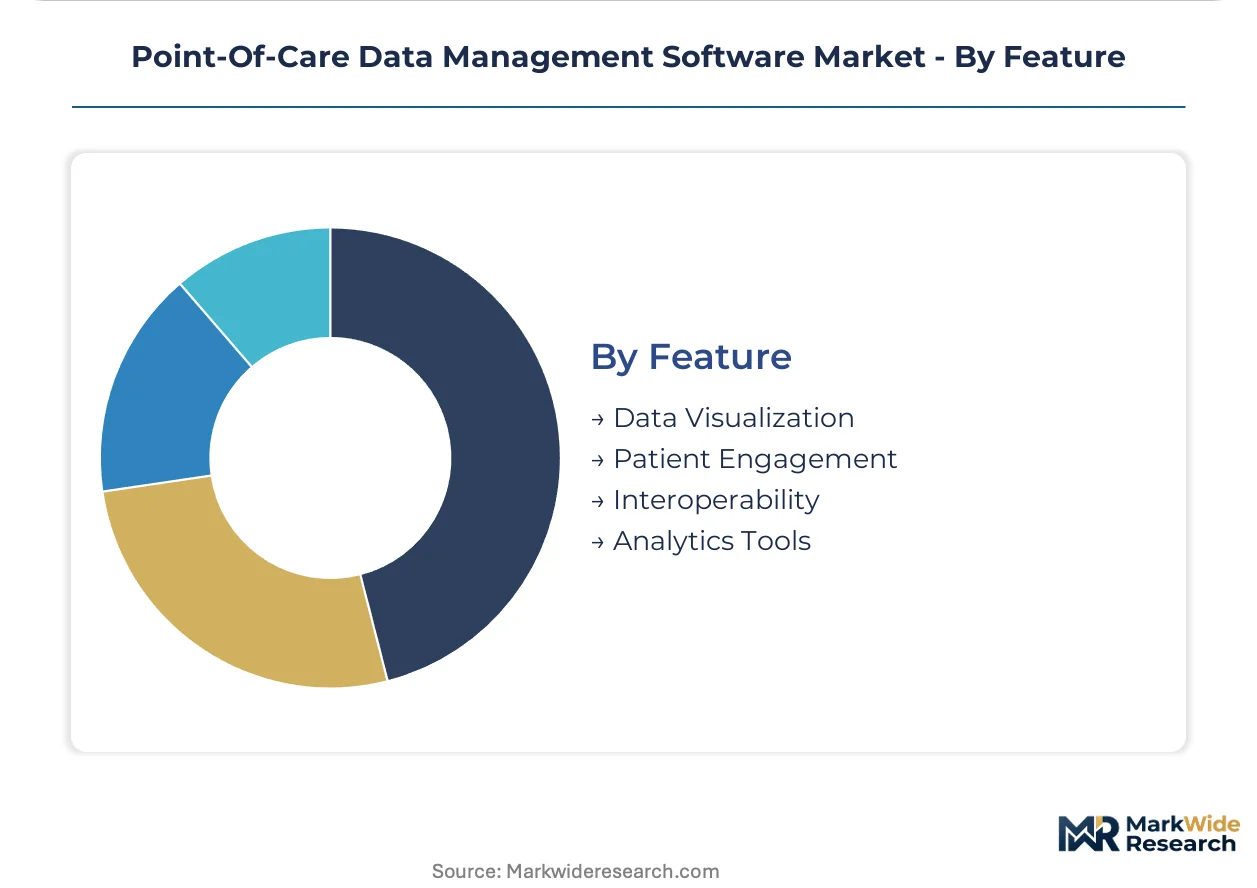
- Interoperability:HL7 FHIR protocol implementations and health information exchange connectivity constitute mandatory evaluation criteria. ONC certification requirements in the United States force upgrades from legacy HL7 v2 interfaces.
- Analytics Tools:Algorithm-enabled diagnostic support and population risk stratification command premium pricing. FDA software-as-a-medical-device guidance clarifies validation pathways for clinical decision support modules.
- Data Visualization:Dashboard configurations for clinical and administrative stakeholders.
- Patient Engagement:Portal and mobile communication features for care plan adherence.
Interoperability capabilities anchor procurement decisions. Analytics Tools show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing point-of-care software development capacity toward jurisdictions with clarified compliance pathways. Vendors migrate engineering resources to markets where FDA guidance and HIPAA frameworks reduce certification uncertainty, while European operations absorb GDPR and EU MDR overhead for premium-tier contracts.
United States
Health system consolidation drives enterprise procurement of cloud-native platforms across integrated delivery networks. ONC interoperability mandates and FDA software-as-a-medical-device guidance accelerate validation timelines for clinical decision support modules. The Boston-Cambridge corridor anchors development clusters where academic medical centers pilot edge-computing architectures for real-time diagnostic alerts.
Germany
Diagnostic centers sustain demand for on-premises installations under strict federal data protection requirements. CNIL-equivalent state regulators and EU MDR clinical validation rules constrain algorithm update cycles for AI-enabled tools. The Rhine-Ruhr metropolitan region concentrates laboratory informatics vendors serving hospital networks with hybrid cloud requirements.
France
Hospital procurement committees unbundle software licensing from diagnostic hardware decisions under tightening budget oversight. ANSM oversight and CNIL data residency mandates preserve market share for localized infrastructure deployments. The Paris-Saclay cluster hosts validation laboratories generating prospective performance data for software with diagnostic functions.
United Kingdom
NHS Digital interoperability standards and post-Brexit regulatory divergence create dual certification burdens for multinational vendors. MHRA guidance on software medical devices parallels FDA pathways while retaining EU MDR equivalence requirements. The Cambridge-Oxford-London triangle sustains healthtech incubators bridging academic research and clinical deployment.
India
Community health organizations adopt subscription-based per-patient-per-month pricing for previously unaffordable capabilities. CDSCO medical device rules and state-level data protection drafts introduce emerging compliance frameworks. Hyderabad and Bengaluru development centers supply engineering talent for HL7 FHIR protocol implementations serving US and European clients.
Point-Of-Care Data Management Software Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around diagnostic hardware incumbents bundling software with instrument portfolios, while independent developers capture modular interoperability contracts. Three archetypes dominate: integrated diagnostic conglomerates, laboratory informatics specialists, and cloud-native healthtech entrants. M&A activity targets FHIR-certified platforms, and strategic partnerships bridge legacy HL7 v2 infrastructure with modern APIs.
Within the integrated diagnostic tier, Siemens Healthineers and Abbott Laboratories exemplify hardware-anchored strategies. Siemens Healthineers leverages European hospital network relationships to bundle data management tools with imaging and laboratory systems. Abbott Laboratories occupies a position through embedded software on connected glucose monitoring devices, representing the device-embedded archetype. Danaher Corporation sits within the laboratory informatics specialization, sustaining R&D intensity in workflows feeding point-of-care environments.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott Laboratories |
| Danaher Corporation |
| Roche Diagnostics Corporation |
| TELCOR Inc. |
| Thermo Fisher Scientific |
| Randox Laboratories |
| Orchard Software Corporation |
| DataLink Software |
| Others |
Value Network & Pricing Analysis
HIPAA security rule compliance and FDA software-as-a-medical-device guidance gate both qualified supply and premium-tier pricing access for point-of-care data management platforms. Vendors bearing HITRUST and SOC 2 Type II certifications command enterprise licensing premiums from United States integrated delivery networks, while uncertified developers face exclusion from procurement panels.
Pricing Analysis
Direct-to-health-system enterprise licensing discounts compress distributor margins as procurement committees unbundle software from hardware bundles. Subscription-based SaaS tiers stratify across premium FHIR-certified platforms, standard interoperability modules, and economy remote monitoring packages. Price differentiation hinges on FDA validation tier and HL7 FHIR certification depth. Pricing pressure stems from cybersecurity insurance premium inflation squeezing vendor margins. Community health organizations exhibit highest price sensitivity; academic medical centers demonstrate lowest.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscaler data center concentration in the United States, Ireland, and Singapore. Software development draws from engineering talent pools in India and Eastern Europe. Raw material dependencies include semiconductor chips for edge computing devices, encryption modules for security layers, and API gateway components. Single-source vulnerability concentrates in cloud provider ecosystems. Distribution runs through direct enterprise sales teams and health IT value-added resellers serving mid-market clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-care data management software functions as a stable compounder. Remote patient monitoring protocol standardization drives steady expansion across homecare agency procurement cycles.
For Market Incumbents: Cement market position through backward integration into edge computing hardware and captive FHIR certification pipelines. Siemens Healthineers and Abbott Laboratories exemplify device-embedded software strategies that raise switching costs. Threaten emerging cloud-native entrants by accelerating clinical validation timelines under FDA guidance. Prioritize R&D intensity in laboratory informatics feeding point-of-care workflows. For New Entrants and Emerging Players: Capture federally qualified health center digitization grants through modular per-patient-per-month pricing models. Rural United States clinics and Indian community health organizations represent the most penetrable white-space segments. Pursue channel partnerships with telehealth infrastructure vendors to bypass direct health system procurement barriers. For Investors and Strategic Acquirers: Roll-up economics work for FHIR-certified interoperability specialists because health system consolidation demands unified data architectures across fragmented networks. Five-to-ten year viability hinges on regulatory compliance moats rather than feature differentiation. Target acquisition archetypes: platforms with ONC certification and established hospital GPO contracts. Watch FDA algorithm validation backlog as inflection signal for AI-enabled diagnostic tool valuations.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification | ONC mandates force legacy system upgrades, privileging certified vendors in procurement evaluations. |
| Edge Computing Partnership | Diagnostic hardware bundling with Siemens Healthineers and Abbott Laboratories raises competitive barriers. |
| Subscription Model Transition | Per-patient-per-month pricing penetrates price-sensitive community health organizations previously excluded. |
| Cybersecurity Insurance Captive | Self-insurance pools reduce premium inflation risks excluding smaller developers from health system panels. |
| Rural Health Grant Capture | Federally qualified health center capital grants create installation base for modular platform expansion. |
Research Methodology
Coverage spans the United States, Germany, France, United Kingdom, and India, with primary inputs from each market cluster. Data synthesis combines structured interviews with hospital CIOs, homecare agency operations directors, biomedical informatics specialists, and health IT procurement managers with secondary validation against FDA 510(k) filings, ONC certification databases, CMS Medicare reimbursement schedules, and hospital GPO contract repositories. Bottom-up installation base modeling and top-down health IT spending allocation triangulate market sizing across deployment models.
Rate-of-change decomposition separates volume expansion from pricing evolution across cloud-based, on-premises, and hybrid platform architectures. Segmentation dimensions encompass product type, end-user category, deployment model, and feature module complexity. CAGRs derive from fitted growth curves against historical health system software procurement cycles. Forecast inputs incorporate HL7 FHIR adoption velocity and FDA software-as-a-medical-device guidance implementation timelines.
Regulatory guidance revision, cybersecurity incident frequency, and health system consolidation pace are the dominant revision risks. Forecasts reflect documented assumptions about interoperability mandate enforcement and cloud infrastructure cost trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Clinical Data Management Systems (CDMS) Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
Global Healthcare Financial Analytics Market