
 Medical Laser Cutting Device Market | 2026-2036
Medical Laser Cutting Device Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Laser Cutting Device Market Insights
Preventive maintenance contracts and software-defined beam parameter modules are pivoting vendor revenue models from hardware-only sales to recurring service architectures. Lumenis Ltd. leverages its installed base across dermatology and surgical suites to lock in multi-year service agreements. El.En. S.p.A. anchors its competitive stance through captive supply of laser sources and optical components. Boston Scientific Corporation differentiates by integrating proprietary cutting heads with its stent and catheter manufacturing lines.
A medical laser cutting device directs amplified coherent light through fiber delivery or free-beam optics to vaporize, ablate, or section biological tissue and engineered biomaterials with thermal damage zones typically below 50 micrometers. Solid-state and fiber laser architectures now dominate new installations due to superior wall-plug efficiency and beam quality stability compared with legacy CO2 systems. Ultra-fast laser technology commands premium positioning in ophthalmic and neurosurgical applications where minimal heat-affected zones determine clinical outcomes. Pulsed laser configurations lead wound healing and tissue ablation segments because controlled pulse energy reduces collateral thermal injury.
FDA 510(k) premarket notification and EU MDR conformity assessment frame product entry timelines and clinical evidence requirements for manufacturers targeting the United States and European markets. ISO 13485 quality management certification and IEC 60601-1-2 electromagnetic compatibility standards further constrain design and production protocols. Stakeholders must monitor evolving notified body capacity under MDR and FDA guidance on laser-tissue interaction modeling to anticipate compliance cost trajectories.
Market Dynamics
Preventive maintenance contracts and software-defined beam parameter modules are pivoting vendor revenue models from hardware-only sales to recurring service architectures. Solid-state and fiber laser architectures now dominate new installations due to superior wall-plug efficiency and beam quality stability compared with legacy CO2 systems.
Growth Catalysts
- FDA 510(k) pathway streamlining:Accelerated clearance timelines for predicate-device submissions reduce time-to-revenue for manufacturers targeting cardiovascular stent production.
- Ultra-fast laser adoption:Femtosecond and picosecond systems enable sub-50-micrometer thermal damage zones in ophthalmic and neurosurgical applications where tissue preservation determines clinical outcomes.
- German precision manufacturing clusters:Concentrated OEM demand in Stuttgart and Munich creates captive infrastructure for laser system validation and field service deployment.
Market Restraints
- Rare-earth fiber supply concentration:Ytterbium-doped fiber laser gain modules depend on Chinese rare-earth processing capacity, creating input cost volatility and geopolitical exposure.
- EU MDR notified body bottleneck:Reduced certification capacity under Medical Device Regulation extends conformity assessment timelines for European market entry.
- CO2 laser installed base inertia:Legacy cutting systems in wound healing and general surgery segments delay replacement cycles despite efficiency disadvantages.
Strategic Opportunities
- Japanese neurosurgical robotics integration:Untapped demand for laser-tissue interaction modules in navigated surgical platforms serving aging demographics.
- Bioresorbable stent manufacturing:Polymeric scaffold cutting requires UV and green wavelength systems absent from current metal-focused product portfolios.
- US IRA domestic production incentives:Advanced manufacturing tax credits for precision medical device production equipment reduce effective acquisition costs for US-based OEMs.
Industry Challenges
- Laser-tissue interaction modeling expertise:Shortage of computational biophotonics specialists delays FDA submission preparation and clinical evidence generation.
- ISO 13485 audit preparation:Quality management system certification requires 12-18 month implementation cycles that compress product launch windows.
- Multi-wavelength system integration:Combining fiber, solid-state, and ultra-fast sources in single platforms increases optical alignment complexity and field service training burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Laser Cutting Device Market |
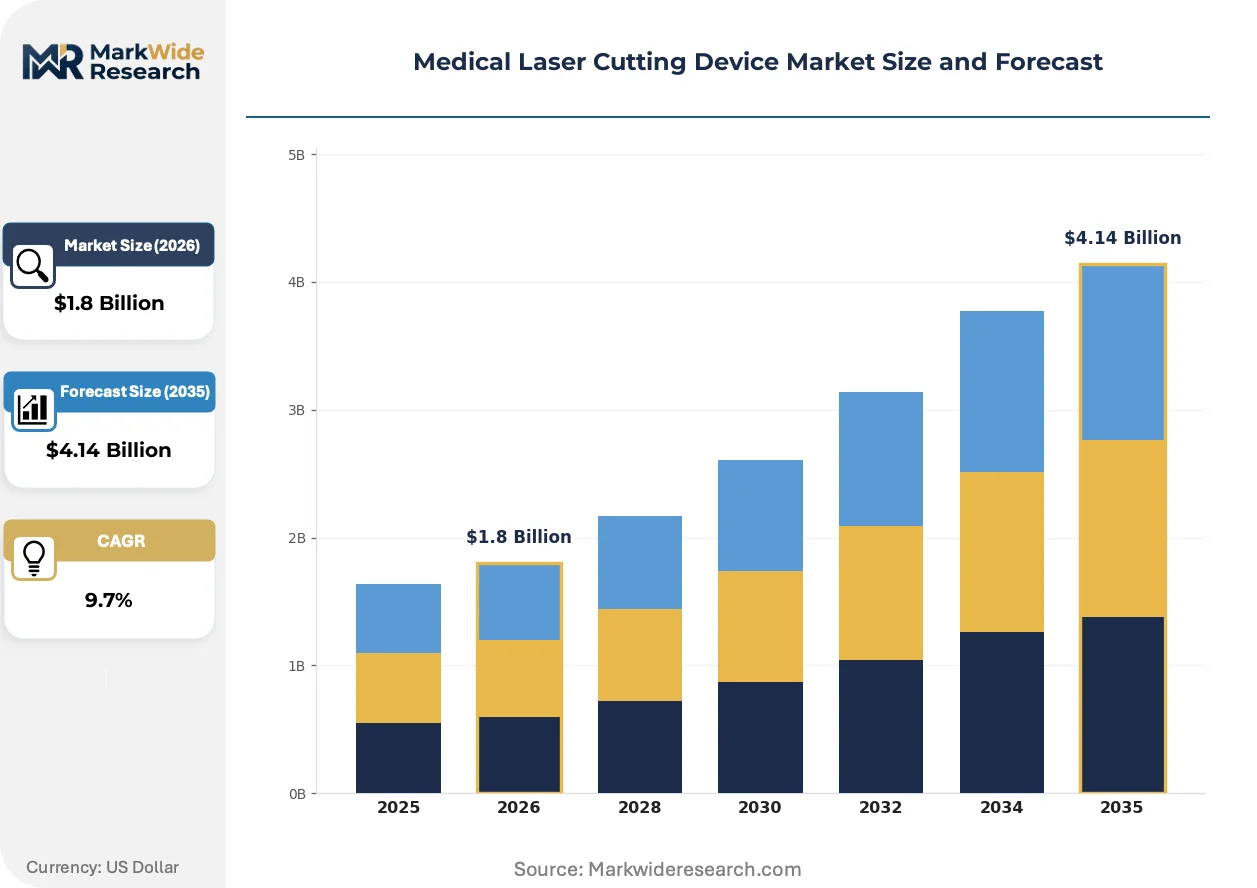
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid State Lasers, Fiber Lasers, CO2 Lasers, Diode Lasers Application: Surgery, Wound Healing, Diagnostic Procedures, Tissue Ablation End User: Hospitals, Outpatient Surgical Centers, Research Laboratories, Clinics Technology: High-Powered Systems, Pulsed Lasers, Continuous Wave Lasers, Ultra-Fast Lasers |
| Companies Covered | Lumenis Ltd., Alma Lasers Ltd., BIOLASE Inc., Cutera Inc., El.En. S.p.A., Alcon Inc., Boston Scientific Corporation, Cynosure Inc., TOPCON Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Laser Cutting Device Market Trends and Innovations
Software-defined beam parameter control is fragmenting hardware value capture and enabling subscription-based service architectures across surgical and manufacturing segments. Three distinct developments are restructuring competitive positioning.
Femtosecond laser technology is modularizing into compact, fiber-delivered platforms that separate the oscillator-amplifier chain from the cutting head interface. Ophthalmic OEMs in Japan and Germany are adopting these systems at accelerated replacement cycles. This architecture is modularizing vendor business models by decoupling capital equipment from consumable fiber delivery components.
EU MDR clinical evidence requirements are tightening post-market surveillance obligations for laser-tissue interaction devices. Manufacturers must now submit periodic safety update reports and real-world performance data. Cardiovascular cutting applications face the steepest compliance cost escalation as notified bodies demand expanded biocompatibility testing protocols.
Hospital procurement committees are consolidating vendor relationships through multi-year managed service agreements that bundle equipment, maintenance, and software updates. Integrated delivery networks in the United States are displacing capital purchase committees with value-analysis teams that prioritize total cost of ownership metrics. This shift concentrates purchasing authority among health systems with centralized supply chain operations.
Medical Laser Cutting Device Market Segmentation
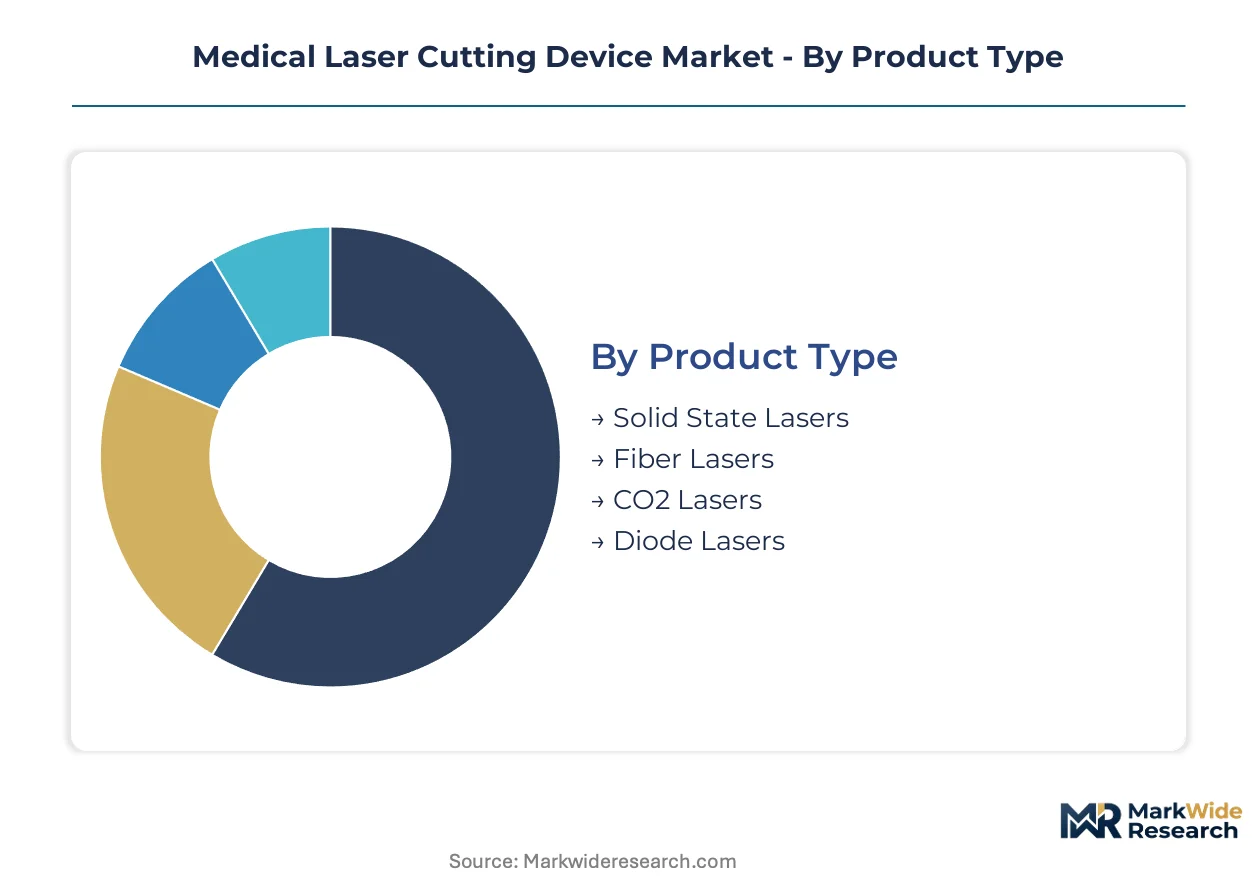
Segmentation in medical laser cutting devices reveals distinct capital requirements, regulatory pathways, and service intensity across laser architectures and clinical settings. Understanding these divides enables vendors to align R&D spend with reimbursement trajectories and OEM procurement priorities.
Product Type:
Capital intensity varies sharply across laser architectures, with fiber and solid-state platforms demanding the highest upfront investment in rare-earth doping infrastructure and precision optical alignment.
- Solid State Lasers:Nd:YAG and Yb:YAG crystal gain media deliver high peak power densities for cardiovascular stent cutting. German OEMs in Stuttgart concentrate demand for these systems due to established validation protocols for nitinol processing.
- Fiber Lasers:Ytterbium-doped fiber architectures achieve superior wall-plug efficiency above 30% and beam quality stability across medical tubing applications. Japanese precision manufacturers drive adoption for neurovascular device production where thermal damage zone minimization determines yield rates.
- CO2 Lasers:Gas discharge systems persist in wound healing and general surgery segments despite replacement pressure from solid-state alternatives.
- Diode Lasers:Compact semiconductor sources serve low-power diagnostic and therapeutic applications with minimal cooling infrastructure.
Fiber lasers absorb the bulk of installed capacity; solid-state platforms are expanding most quickly in cardiovascular manufacturing.
Application:
Reimbursement codes and clinical evidence requirements create divergent margin profiles across therapeutic versus diagnostic deployment.
- Surgery:Ophthalmic and cardiovascular specialties deploy femtosecond and high-powered continuous systems for corneal flap creation and stent fabrication. FDA 510(k) predicate pathways accelerate clearance for cardiovascular cutting heads, compressing time-to-revenue for manufacturers targeting US hospital procurement cycles.
- Wound Healing:Low-level laser therapy devices operate at sub-thermal intensities to accelerate tissue repair. Outpatient clinics in Germany and Japan represent concentrated demand centers where preventive care reimbursement frameworks support capital acquisition.
- Diagnostic Procedures:Optical biopsy and confocal microscopy integration requires precise wavelength control for cellular imaging.
- Tissue Ablation:Pulsed configurations dominate renal and dermatological applications where controlled vaporization limits collateral thermal injury.
Surgery commands the dominant share of system revenue; wound healing is climbing the fastest as ambulatory settings expand laser therapy protocols.
End User:
Procurement authority and service contract structures differ materially across integrated health systems versus independent clinical operators.
- Hospitals:Centralized value-analysis committees in US integrated delivery networks prioritize total cost of ownership metrics over acquisition price. Multi-year managed service agreements bundle equipment, preventive maintenance, and software-defined beam parameter updates into recurring revenue streams for vendors.
- Outpatient Surgical Centers:Freestanding facilities concentrate ophthalmic and dermatological volume with compressed capital cycles. Japanese aging demographics expand demand for cataract and refractive procedures performed in ambulatory settings.
- Research Laboratories:Academic medical centers and contract research organizations drive ultra-fast laser adoption for preclinical tissue interaction studies.
- Clinics:Private practice dermatology and podiatry operators favor portable diode systems with minimal facility infrastructure requirements.
Hospitals retain the largest installed base; outpatient surgical centers are gaining share fastest as procedure migration accelerates.
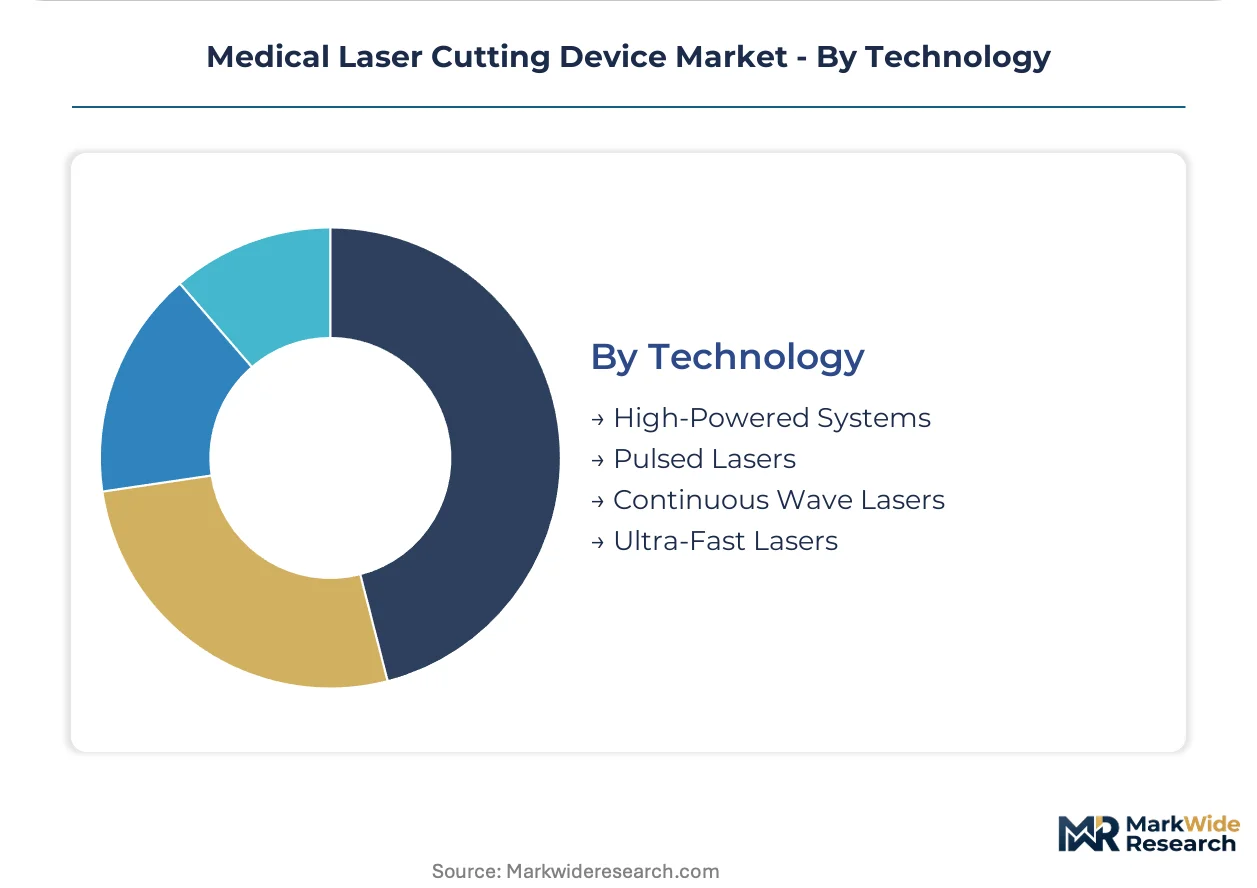
Technology:
Performance tier and thermal damage specifications determine pricing stratification and regulatory evidence burdens.
- Ultra-Fast Lasers:Femtosecond and picosecond pulse durations enable sub-50-micrometer thermal damage zones critical for ophthalmic and neurosurgical outcomes. EU MDR notified bodies demand expanded biocompatibility testing for these systems, extending conformity assessment timelines.
- Pulsed Lasers:Q-switched and mode-locked configurations balance peak power with controlled energy deposition. Wound healing and tissue ablation segments favor these architectures for their reduced collateral thermal injury profiles.
- High-Powered Systems:Multi-kilowatt continuous sources serve industrial-scale medical device manufacturing rather than clinical deployment.
- Continuous Wave Lasers:Steady-state emission supports general surgical cutting and coagulation with simpler optical delivery requirements.
Pulsed lasers dominate current installations; ultra-fast systems are expanding most quickly as ophthalmic OEMs accelerate replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of precision laser systems exported worldwide, while Japan and the United States consume advanced units for domestic surgical device manufacturing. Demand concentrates in metropolitan manufacturing clusters where OEM validation protocols and regulatory expertise coexist.
United States
FDA 510(k) predicate pathways accelerate clearance timelines for cardiovascular stent cutting heads, compressing manufacturer time-to-revenue. The Inflation Reduction Act's advanced manufacturing tax credits reduce effective acquisition costs for domestic OEMs expanding precision production capacity. Minneapolis and Boston corridors concentrate demand from integrated delivery networks consolidating vendor relationships through multi-year managed service agreements.
Germany
Stuttgart and Munich precision manufacturing clusters generate captive infrastructure for laser system validation and field service deployment serving European medical device OEMs. EU MDR conformity assessment requirements under notified body oversight extend certification timelines but reinforce quality leadership positioning. Baden-Württemberg's industrial density supports rare-earth fiber laser module integration into nitinol processing workflows.
Japan
Aging demographics expand demand for cataract and refractive procedures performed in ambulatory settings, driving ophthalmic laser replacement cycles. METI industrial policy prioritizes domestic production of femtosecond oscillator-amplifier platforms for neurosurgical robotics integration. Nagoya and Osaka precision manufacturers anchor supply chains for navigated surgical platforms requiring minimal thermal damage zone specifications.
Switzerland
Swissmedic device clearance pathways emphasize clinical evidence generation for ultra-fast laser systems targeting ophthalmic applications. Geneva and Basel clusters concentrate contract research organization demand for preclinical tissue interaction studies using modular fiber-delivered platforms. The country's precision engineering heritage supports niche positioning in bioresorbable scaffold cutting equipment.
China
NMPA medical device registration reforms streamline domestic market entry for imported laser cutting systems while incentivizing local production partnerships. Yangtze River Delta manufacturing hubs absorb fiber laser capacity for export-oriented medical tubing production. Rare-earth processing concentration in Inner Mongolia creates input cost advantages for ytterbium-doped gain module fabrication.
Medical Laser Cutting Device Market Competitive Landscape
Top-tier vendors anchor premium positioning through captive optical component supply and multi-year service contract architectures, while mid-tier specialists compete on modular platform flexibility and regional proximity. The vendor base stratifies across three archetypes: integrated surgical device manufacturers with in-house laser capabilities, pure-play laser system specialists with rare-earth fiber supply control, and diversified photonics conglomerates spanning industrial and medical applications. Dominant competitive moves include backward integration into laser source production and geographic expansion through distributor partnerships in Asian manufacturing corridors.
Among Israel-based surgical laser specialists, Lumenis Ltd. and Alma Lasers Ltd. exemplify the installed-base leverage archetype, converting dermatology and surgical suite penetration into recurring preventive maintenance revenue streams. El.En. S.p.A. anchors the captive supply archetype through its Italian corporate structure and in-house production of laser sources and optical components. Boston Scientific Corporation represents the integrated device manufacturer archetype, embedding proprietary cutting heads within stent and catheter manufacturing lines to capture margin across the production workflow.
| Leading Market Players |
|---|
| Lumenis Ltd. |
| Alma Lasers Ltd. |
| BIOLASE Inc. |
| Cutera Inc. |
| El.En. S.p.A. |
| Alcon Inc. |
| Boston Scientific Corporation |
| Cynosure Inc. |
| TOPCON Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive supply of ytterbium-doped fiber gain modules anchors both cost position and pricing power for laser system vendors serving cardiovascular stent manufacturers. German and Japanese OEM procurement committees leverage multi-year service bundling to compress hardware margins while locking in recurring software-defined beam parameter revenue streams.
Pricing Analysis
Cost compression in standard fiber laser tiers reflects Chinese rare-earth processing concentration and ytterbium supply volatility. Three-tier pricing structure across premium femtosecond systems, standard fiber platforms, and economy CO2 alternatives differentiates by thermal damage zone specification and FDA 510(k) predicate pathway access. ISO 13485 certification tier and multi-wavelength integration complexity command 15-25% brand premiums. Outpatient surgical centers exhibit highest price sensitivity due to compressed capital cycles; integrated US delivery networks prioritize total cost of ownership over acquisition price.
Supply Chain Analysis
Dual-sourcing requirements for rare-earth fiber gain modules now mandate qualification of Chinese and German suppliers simultaneously, extending procurement timelines. Ytterbium-doped fiber, precision optical coatings, and ceramic gain media draw from concentrated processing in China, Germany, and Japan. Single-source vulnerability in Inner Mongolia rare-earth refining creates geopolitical exposure for ytterbium supply. Distribution runs through direct OEM relationships in Stuttgart and Minneapolis corridors, supplemented by regional service hubs in Nagoya and Boston.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body capacity constraints and expanded biocompatibility testing protocols erect compliance cost barriers that favor incumbents with established quality management systems. New entrants face 12-18 month ISO 13485 implementation cycles that compress product launch windows against predicate-device competitors.
For Market Incumbents: Anticipate femtosecond platform commoditization by deepening captive supply of oscillator-amplifier chains and securing multi-year preventive maintenance contracts across dermatology installed bases. Defend against modular fiber-delivery disintermediation through software-defined beam parameter subscription lock-in.
For New Entrants and Emerging Players: The mid-tier price-point gap between premium ultra-fast systems and legacy CO2 platforms offers white-space entry for compact solid-state architectures targeting wound healing ambulatory settings. Japanese neurosurgical robotics integration represents the most penetrable segment due to METI industrial policy support and aging-demographic procedure volume expansion.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated device manufacturers seeking in-house laser cutting capabilities for stent production workflows. Long-term viability hinges on rare-earth fiber supply control and FDA submission preparation expertise. Watch notified body capacity expansion under EU MDR as inflection signal for European market entry cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Laser Sources | Captive ytterbium-doped fiber production insulates margin from Chinese rare-earth price volatility. |
| FDA 510(k) Predicate Pathway Investment | Accelerated cardiovascular stent cutting head clearance compresses time-to-revenue in US hospital procurement cycles. |
| Software-Defined Beam Parameter Development | Subscription architectures pivot vendor economics from hardware sales toward recurring service revenue streams. |
| EU MDR Notified Body Pre-Engagement | Early conformity assessment preparation reduces certification timeline risk for ultra-fast laser platforms. |
| Japanese Neurosurgical Robotics Partnership | METI-supported integration opportunities capture aging-demographic demand for minimal thermal damage procedures. |
Research Methodology
Document review covered FDA 510(k) premarket notification databases, EU MDR conformity assessment guidance, and ISO 13485 audit protocols, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and laser system field service directors. Secondary sources included SEC filings from listed medical device OEMs, notified body capacity reports, and rare-earth trade flow data. Bottom-up triangulation across installed base estimates and top-down validation against OEM capital expenditure disclosures anchored market sizing.
Segment-level outputs across laser architecture, clinical application, end-user setting, and thermal damage specification tier were generated through the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and OEM capacity expansion announcements, incorporating femtosecond adoption curves and EU MDR compliance cost escalation as industry-specific inputs.
Inputs from notified body capacity trackers and rare-earth processing facility operating rates were available through the study window; gaps in real-time laser-tissue interaction clinical outcome data introduce uncertainty bands around ophthalmic segment forecasts. Deviation in FDA guidance on computational biophotonics modeling requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Global Intrauterine Contraceptive Devices (IUD) Market
Medical Devices
Asia-Pacific Ultrasound Probe Disinfection Market
Medical Devices
Artificial Corneal Implants Market
Medical Devices
Disposable Medicine Measuring Cups Market
Medical Devices
Depression Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Medical Goggle Market
Medical Devices
Medical Device Films Market
Medical Devices
Intubation Accessories Market
Medical Devices
Global Self-Injection Device Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
External Nasal Dilator Market
Medical Devices
Kidney Stone Management Devices Market
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Minimally Invasive Neurosurgical Devices Market