
 Medical Machine Battery Market | 2026-2036
Medical Machine Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Machine Battery Market Insights
Japan's domestic cell production expansion is reshaping competitive dynamics in the Medical Machine Battery Market. Panasonic Corporation leverages its cylindrical cell heritage to dominate imaging equipment power systems. EaglePicher Technologies LLC anchors the North American supply base through defense-grade lithium-thionyl chloride expertise. Saft competes in European hospital networks with its primary cell portfolio for long-life implantable applications.
Medical machine batteries electrochemically store and deliver direct current to powered diagnostic, therapeutic, and monitoring equipment, typically operating at voltages from 3.7V to 14.4V with cycle life requirements exceeding 500 full discharges. Lithium-ion chemistry now leads product type segmentation due to energy density advantages in portable imaging and surgical tools, while nickel-metal hydride retains share in cost-sensitive patient monitors where lower discharge rates suffice. Wireless charging technology represents the fastest-growing segment as hospitals eliminate cable contamination risks in operating theaters, though wired systems still occupy the bulk of installed diagnostic equipment.
FDA enforcement of IEC 60601-1 third-edition safety standards constrains market access for uncertified battery suppliers, while the EU Medical Device Regulation mandates traceable cell supply chains for CE-marked equipment. Japan's METI circular economy directives are accelerating domestic recycling infrastructure for end-of-life medical cells. Stakeholders must monitor how solid-state electrolyte maturation reshapes the trade-off between energy density and thermal stability in next-generation surgical power systems.
Market Dynamics
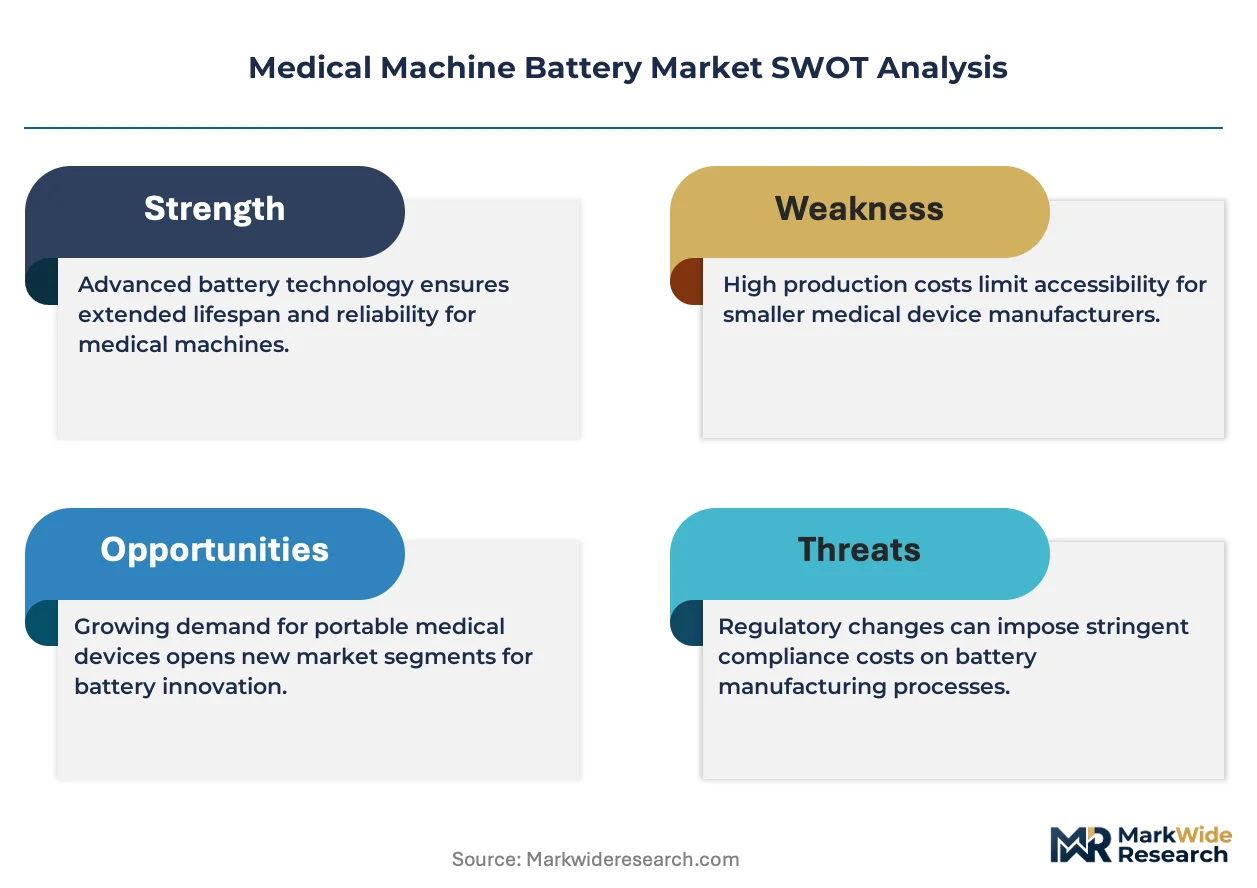
FDA enforcement of IEC 60601-1 third-edition safety standards is compressing supplier access windows while solid-state electrolyte development rewrites the energy density-thermal stability trade-off in surgical power systems.
Growth Catalysts
- Portable Surgical Device Demand:Hospitals in Germany, Japan, and the United States are replacing corded equipment with battery-powered alternatives to eliminate cable contamination risks in sterile environments.
- EU Medical Device Regulation Traceability Mandates:CE-marked equipment now requires documented cell supply chains, creating procurement preference for certified battery suppliers with verified upstream partnerships.
- Wireless Charging Infrastructure:Operating theater managers are eliminating contact points through inductive power transfer, reducing infection vectors and maintenance overhead in critical care settings.
Market Restraints
- Cobalt Supply Concentration:Democratic Republic of Congo dominance in cobalt mining exposes lithium-ion cathode supply to geopolitical disruption and ethical sourcing scrutiny.
- Thionyl Chloride Handling Complexity:Defense-grade lithium-thionyl chloride cells require specialized manufacturing facilities and hazardous material certifications that limit supplier entry.
- Nickel-Metal Hydride Energy Density Ceiling:Patient monitors and low-discharge applications remain locked into older chemistry due to cost constraints, blocking upgrade cycles.
Strategic Opportunities
- Japan METI Circular Economy Directives:Domestic recycling infrastructure mandates for end-of-life medical cells create first-mover advantage for integrated collection-to-refinement operators.
- Solid-State Electrolyte Convergence:Ceramic-polymer hybrid separators combined with silicon-anode architectures promise 40% volumetric energy gains for next-generation imaging equipment.
- Direct Hospital Procurement Platforms:Group Purchasing Organizations are disintermediating traditional distributor networks, enabling battery manufacturers to capture margin previously lost to middle-tier logistics providers.
Industry Challenges
- Certification Timeline Compression:IEC 60601-1 third-edition testing protocols now require 18-24 month validation cycles, delaying product launches and freezing R&D roadmaps.
- Electrochemical Engineering Talent Scarcity:Solid-state battery development demands specialists in ceramic processing and interface chemistry that medical device manufacturers rarely retain in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Machine Battery Market |
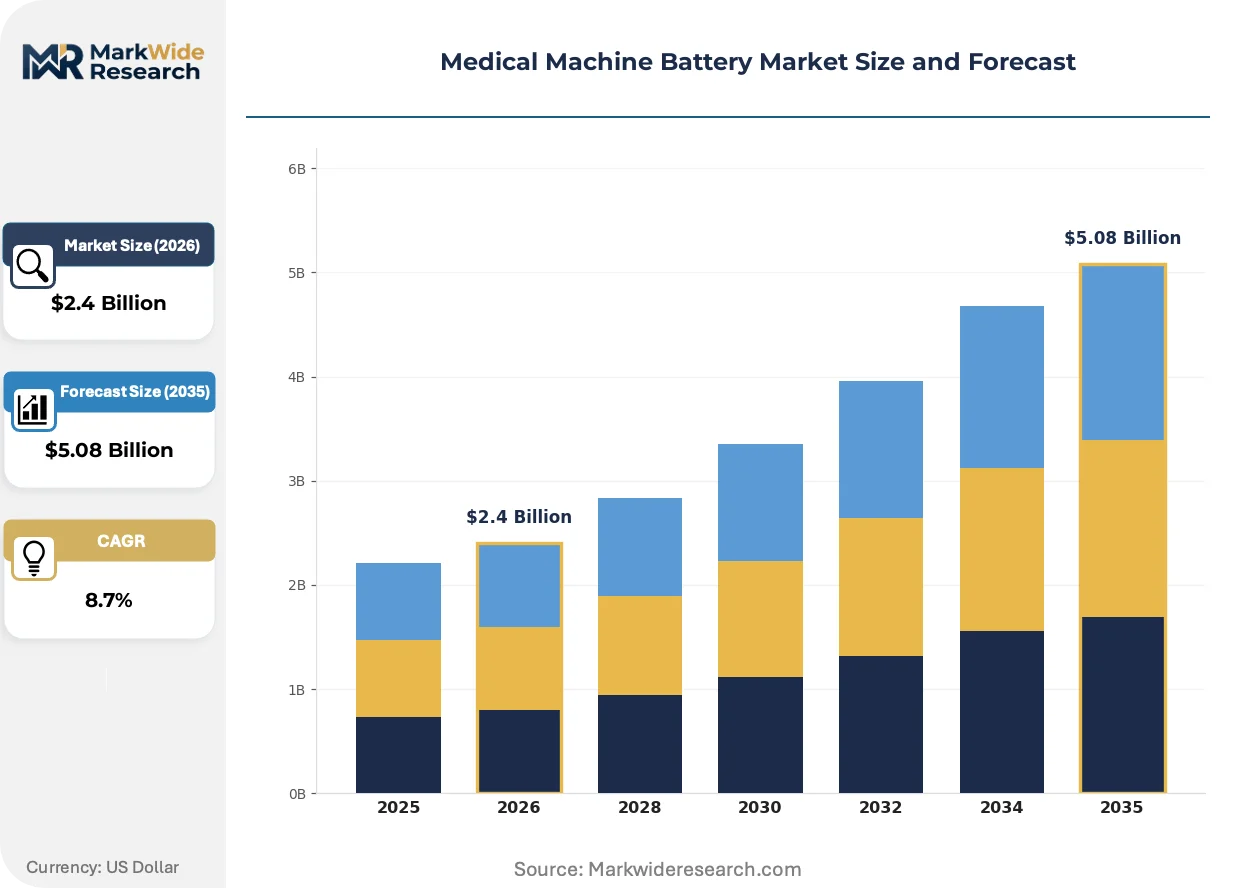
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-Cadmium, Nickel-Metal Hydride, Lead Acid End User: Hospitals, Clinics, Home Care, Diagnostic Centers Technology: Wireless, Wired, Hybrid, Rapid Charge Application: Imaging Equipment, Patient Monitors, Surgical Devices, Infusion Pumps |
| Companies Covered | Panasonic Corporation, EaglePicher Technologies LLC, Ultralife Corporation, Energizer Holdings Inc., Saft, VARTA Microbattery GmbH, Tadiran Batteries Ltd., Murata Manufacturing Co. Ltd, Renata AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Machine Battery Market Trends and Innovations
Solid-state electrolyte maturation and wireless power transfer adoption are converging to eliminate thermal runaway risks and cable management burdens simultaneously across surgical and diagnostic equipment categories.
Solid-state ceramic-polymer hybrid electrolytes replace flammable liquid separators with non-combustible ion-conductive membranes. Implantable device manufacturers in Switzerland and Germany are piloting these cells for cardiac rhythm management applications. The technology is rendering obsolete the trade-off between energy density and intrinsic safety that has constrained lithium-ion penetration in long-life implantables.
EU Medical Device Regulation Article 10 mandates full supply chain traceability for cells incorporated into CE-marked equipment. Battery suppliers must now document mining origin, refining location, and manufacturing batch through blockchain-verified records. European hospital procurement departments are disqualifying vendors without ISO 13485 quality management certification and auditable cell genealogy.
Hospital supply chain managers are consolidating vendor relationships from twelve-plus battery suppliers to three or fewer strategic partners per equipment category. German university hospital networks now require ten-year service agreements bundled with cell supply, displacing spot purchasing through medical distributors. This concentration is most visible in Baden-Württemberg and Bavaria, where precision equipment manufacturing clusters create localized procurement consortia.
Medical Machine Battery Market Segmentation
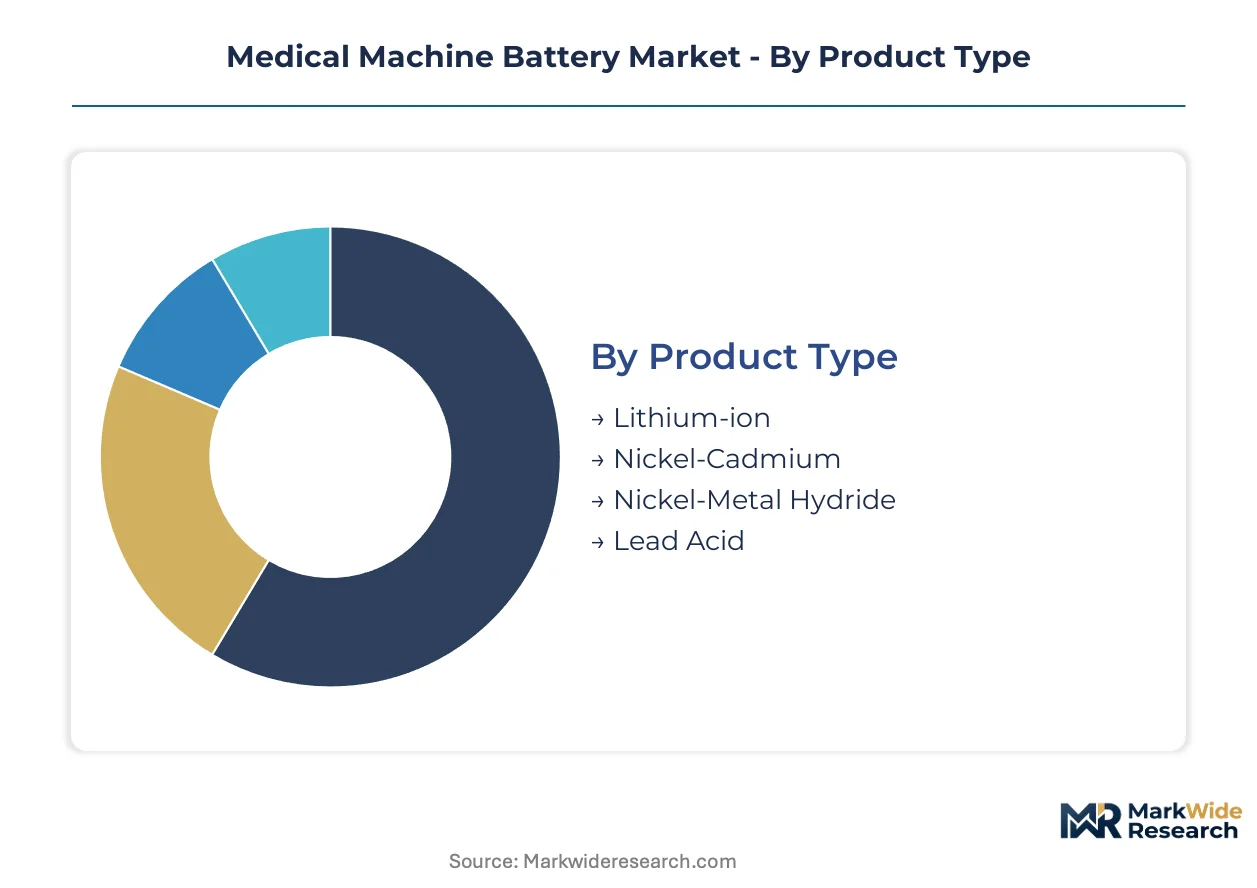
Medical machine battery procurement patterns diverge sharply across chemistry types, care settings, and power delivery architectures. Hospital supply managers segment suppliers by IEC 60601-1 certification status and wireless integration capability rather than commodity specifications alone.
Product Type:
Chemistry selection determines energy density, cycle life, and thermal safety profiles for specific device categories.
- Lithium-ion:Cobalt-oxide and lithium-iron-phosphate cathodes deliver 150-250 Wh/kg for portable CT scanners and surgical robots. German university hospitals in Stuttgart and Munich specify these cells for equipment requiring 500+ discharge cycles in sterilized environments.
- Nickel-Metal Hydride:Rare-earth alloy anodes provide safer operation in patient monitors where lower discharge rates suffice. Cost-sensitive procurement in US outpatient clinics retains this chemistry despite 40% lower volumetric density versus lithium-ion alternatives.
- Nickel-Cadmium:Sintered plate construction tolerates deep discharge cycles in emergency backup systems for ventilators and anesthesia machines.
- Lead Acid:Absorbed glass mat variants serve stationary diagnostic equipment with minimal mobility requirements.
Lithium-ion holds installed capacity. Nickel-Metal Hydride is rotating up the share rankings in cost-constrained replacement cycles.
End User:
Care setting dictates power reliability requirements, regulatory exposure, and procurement contract structures.
- Hospitals:Acute care facilities in Germany, Japan, and the United States bundle ten-year service agreements with cell supply, consolidating vendor relationships to three strategic partners per equipment category. Operating theater managers prioritize wireless charging infrastructure to eliminate cable contamination vectors.
- Home Care:Portable oxygen concentrators and infusion pumps for ambulatory patients demand lightweight lithium-polymer packs with onboard battery management systems. Japan's METI circular economy directives are accelerating domestic recycling infrastructure for end-of-life cells in this channel.
- Clinics:Outpatient facilities prioritize capital cost minimization over energy density, extending nickel-metal hydride deployment in basic monitoring equipment.
- Diagnostic Centers:High-throughput imaging suites require rapid-swap battery systems to maintain patient scheduling density.
Hospitals command procurement volume concentration. Home Care is expanding most quickly as discharge protocols shift care outside institutional walls.
Technology:
Power delivery architecture determines infection control compliance and maintenance overhead in critical care environments.
- Wireless:Inductive power transfer eliminates contact points in operating theaters, reducing infection vectors. EU hospital procurement departments specify these systems for new surgical suite construction.
- Wired:Conventional connector systems retain dominance in installed diagnostic equipment where retrofit costs exceed wireless upgrade benefits.
- Hybrid:Dual-mode systems combine wired reliability with wireless convenience for mobile imaging carts.
- Rapid Charge:Silicon-anode architectures and advanced thermal management enable 80% charge recovery in under 30 minutes for emergency equipment rotation.
Wired retains legacy footprint. Wireless is gaining share fastest as greenfield hospital construction accelerates.
Application:
Device mobility requirements and duty cycles segment battery specifications across therapeutic and diagnostic categories.
- Surgical Devices:Battery-powered scalpels, drills, and robotic arms demand 14.4V lithium-polymer packs with instantaneous high-current delivery. FDA enforcement of IEC 60601-1 third-edition standards compresses supplier access windows for uncertified vendors.
- Imaging Equipment:Portable X-ray and ultrasound systems require 500+ Wh energy reserves with minimal self-discharge during transport between patient rooms.
- Patient Monitors:Continuous telemetry devices prioritize operational longevity over energy density, accepting nickel-metal hydride trade-offs for cost containment.
- Infusion Pumps:Ambulatory drug delivery systems specify primary lithium-thionyl chloride cells for multi-year implantable applications.
Imaging Equipment holds installed capacity. Surgical Devices is climbing the fastest as corded equipment replacement accelerates in sterile environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing concentrates in Japan and Germany where precision equipment supply chains intersect with battery chemistry expertise. Hospital procurement clusters in these markets drive specification standards that radiate outward to secondary markets.
Germany
Precision medical equipment manufacturing clusters around Stuttgart and Munich generate concentrated demand for IEC 60601-1 certified cells. The EU Medical Device Regulation mandates traceable supply chains for CE-marked equipment, compressing vendor qualification windows. Baden-Württemberg university hospitals now bundle ten-year service agreements with cell procurement.
United States
Acute care facilities in Boston and Cleveland are replacing corded surgical equipment with battery-powered alternatives to eliminate cable contamination risks. FDA enforcement of third-edition safety standards constrains market access for uncertified suppliers. Minnesota's medical device corridor anchors North American demand for implantable primary cells.
Japan
Domestic cell production expansion is reshaping competitive dynamics as METI circular economy directives accelerate recycling infrastructure for end-of-life medical cells. Osaka-based manufacturers supply imaging equipment power systems to domestic hospitals. Kanto region procurement consortia are consolidating vendor relationships to three strategic partners per equipment category.
Switzerland
Implantable device manufacturers in Basel and Zurich are piloting solid-state ceramic-polymer hybrid electrolytes for cardiac rhythm management applications. Swissmedic regulations align with EU MDR traceability requirements for CE-marked equipment. The country's precision engineering heritage supports specialized cell assembly for long-life implantables.
China
Domestic hospital construction in Shanghai and Beijing is driving procurement of wireless charging infrastructure for new surgical suites. NMPA alignment with IEC standards is compressing certification timelines for imported cells. Yangtze River Delta manufacturing bases are expanding lithium-ion capacity for portable diagnostic equipment.
Medical Machine Battery Market Competitive Landscape
Defense-grade specialists and consumer electronics heritage players split the market between high-reliability implantable applications and portable diagnostic power systems. The vendor base organizes around three strategic archetypes: cylindrical cell manufacturers with industrial scale, primary cell specialists with long-life chemistry expertise, and diversified electronics conglomerates with vertical battery operations. Competitive moves concentrate on IEC 60601-1 certification acquisition and ten-year hospital service agreement bundling.
Within the defense-grade specialist tier, EaglePicher Technologies LLC and Tadiran Batteries Ltd. exemplify the lithium-thionyl chloride expertise required for multi-year implantable applications. Panasonic Corporation anchors the consumer-industrial crossover segment, leveraging cylindrical cell heritage developed in electronics applications. Saft occupies a position bridging European hospital networks with primary cell portfolios for life-critical equipment.
| Leading Market Players |
|---|
| Panasonic Corporation |
| EaglePicher Technologies LLC |
| Ultralife Corporation |
| Energizer Holdings Inc. |
| Saft |
| VARTA Microbattery GmbH |
| Tadiran Batteries Ltd. |
| Murata Manufacturing Co. Ltd |
| Renata AG |
| Others |
Pricing and Supply Chain Analysis
Stuttgart's precision equipment manufacturing cluster channels IEC 60601-1 certified cell demand toward premium-tier suppliers, compressing margins for uncertified competitors while concentrating procurement leverage among Baden-Württemberg university hospital networks. This geographic supply-demand alignment rewards verified upstream partnerships with pricing power that spot-market vendors cannot replicate.
Pricing Analysis
FDA enforcement of IEC 60601-1 third-edition safety standards dictates the pricing tier structure across the Medical Machine Battery Market, separating ISO 13485-certified suppliers commanding premium positioning from uncertified vendors trapped in commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling, with German hospital procurement committees least sensitive to unit cost when ten-year service agreements are attached. Pricing pressure stems from cobalt cathode feedstock volatility, while US outpatient clinics exhibit highest price sensitivity as they extend nickel-metal hydride replacement cycles.
Supply Chain Analysis
Extended payment terms from German hospital procurement consortia are forcing working capital discipline on cell suppliers, with supply-chain finance facilities emerging as a competitive differentiator for qualified vendors. Manufacturing concentrates in Japan, South Korea, and China, with raw material flows drawing from Chilean lithium, Australian spodumene, and Congolese cobalt. Single-source vulnerability in thionyl chloride refining creates structural risk for implantable primary cell lines. Distribution runs through Group Purchasing Organizations that are disintermediating traditional medical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrochemical engineering talent scarcity constrains solid-state battery development timelines, with ceramic processing and interface chemistry expertise concentrated among defense contractors and national laboratories rather than medical device manufacturers. This capability gap defines competitive mobility across the market.
For Market Incumbents: Harden certification moats by accelerating IEC 60601-1 third-edition validation cycles before regulatory windows compress further, while securing captive cobalt supply through offtake agreements with Australian and Chilean mining operators. Vertical integration into silicon-anode processing mitigates substitution risk from solid-state electrolyte convergence.
For New Entrants and Emerging Players: Southeast Asian hospital construction greenfield presents the most penetrable geographic underpenetration, with wireless charging infrastructure for new surgical suites offering a technology leapfrog angle. Target procurement managers in Vietnam and Indonesia with inductive power transfer systems that bypass wired legacy installed bases.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors defense-grade lithium-thionyl chloride specialists with FDA master files and implantable device track records. Long-term viability rests on solid-state electrolyte maturation timelines and hospital vendor consolidation patterns. Watch METI recycling infrastructure buildout as circular economy compliance cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| IEC 60601-1 Third-Edition Certification | FDA enforcement compresses supplier access windows for uncertified battery vendors. |
| Hospital System Partnership | German university networks bundle ten-year service agreements with cell procurement. |
| Solid-State Electrolyte Development | Ceramic-polymer hybrid separators promise 40% volumetric energy gains for imaging equipment. |
| Backward Integration into Cobalt Supply | Chilean and Australian mining offtakes reduce exposure to Congolese geopolitical disruption. |
| Wireless Charging Infrastructure Deployment | EU hospital procurement departments specify inductive systems for new surgical suite construction. |
Research Methodology
The analysis maps lithium-ion, nickel-metal hydride, and primary lithium chemistry sub-sectors, each validated through hospital procurement managers, biomedical engineers, GPO contracts specialists, and cell manufacturing executives. Primary interviews combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation, METI circular economy directives, and hospital procurement database extracts. Bottom-up cell shipment modeling and top-down equipment installation data triangulate market sizing across the projection horizon.
Assumptions held regulatory enforcement timelines and cobalt price bands fixed while varying solid-state electrolyte commercialization pace and wireless charging adoption curves. Segmentation dimensions span chemistry type, end-user care setting, power delivery architecture, and device application category. CAGRs derive from equipment replacement cycle analysis and hospital capital expenditure patterns, with surgical device electrification rates and imaging equipment portability indices as key forecast inputs.
Practitioners should monitor FDA inspection citation rates, EU MDR notified body capacity constraints, and solid-state battery pilot production yields for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Guide Extension Catheter Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Radiofrequency Skin Rejuvenation Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Insulin Delivery Devices (Idd) Market
Medical Devices
Oral Appliance Market
Medical Devices
Percutaneous Nephrostomy Catheters Market
Medical Devices
Medical Germicidal Lamps Market
Medical Devices
Glass Syringe Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Peripheral Interventions Market
Medical Devices
Intubation Tubes Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Global Holter ECG Market