
 Patient Data Management Systems Market | 2026-2036
Patient Data Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Data Management Systems Market Outlook
Cloud infrastructure is rebalancing traditional on-premises economics in patient data management, reducing capital intensity for mid-sized providers. Epic Systems leverages its deep integration with academic medical centers to sustain workflow dominance. Oracle Health anchors enterprise-scale deployments across multi-hospital networks. IQVIA Holdings Inc. differentiates through real-world evidence linkages that extend beyond clinical records into research analytics.
Patient Data Management Systems encompass software platforms that aggregate, store, and exchange clinical information across care settings, typically processing structured and unstructured data through HL7 FHIR APIs and ISO 27001-certified security architectures to enable coordinated treatment decisions. Their primary purpose is to eliminate information silos between providers, payers, and patients. Electronic Health Records occupy the largest installed base, though interoperability platforms command premium pricing due to regulatory mandates for seamless data exchange. Cloud-based delivery is expanding fastest as hospitals migrate from capital-intensive server farms to subscription models with automatic compliance updates.
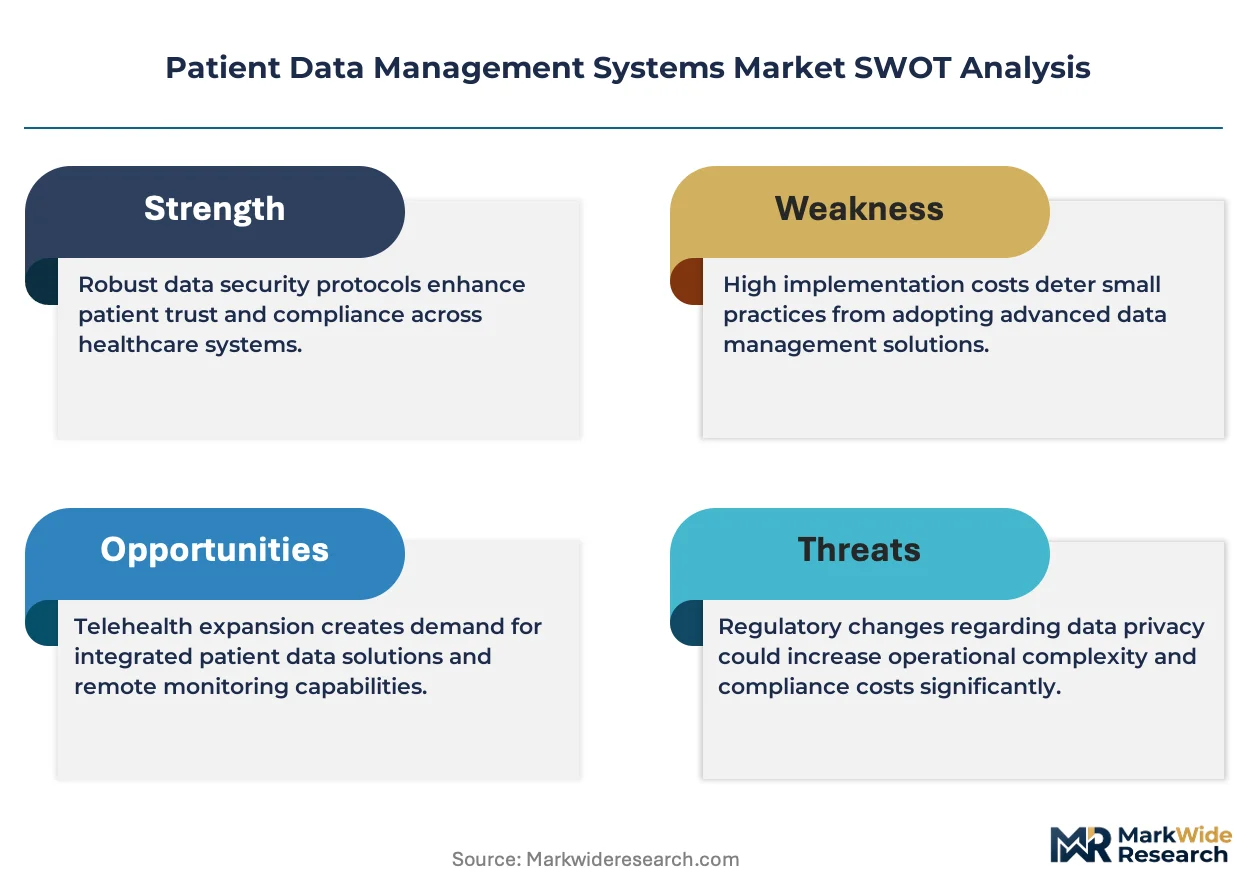
FDA guidelines on software as a medical device intersect with HIPAA privacy rules and ONC certification requirements to shape product development roadmaps and market access conditions in the United States. The EU AI Act and GDPR impose additional algorithmic transparency and data residency obligations for vendors serving European providers. Stakeholders must monitor evolving interoperability standards and reimbursement policies that determine whether integrated solutions or standalone systems capture the next wave of health system procurement cycles.
Market Dynamics
Interoperability mandates from the 21st Century Cures Act and HIPAA are forcing health systems to dismantle data silos between competing EHR platforms, creating immediate procurement pressure for middleware solutions that bridge incompatible legacy architectures.
Growth Catalysts
- HL7 FHIR API standardization:The ONC certification program in the United States mandates standardized data exchange protocols, compelling hospitals to upgrade integration layers. Ambulatory networks accelerate cloud migrations to meet compliance deadlines.
- Germany's Hospital Future Act:Federal funding streams for digital infrastructure modernization drive EHR replacement cycles across university hospitals and municipal health systems. Regional health networks consolidate procurement around certified vendors.
- Real-world evidence integration:Pharmaceutical manufacturers demand longitudinal patient data linkages for post-market surveillance. Data management platforms capturing both clinical and claims records command premium positioning in research partnerships.
Market Restraints
- Cloud concentration risk:Three hyperscale providers dominate health data hosting infrastructure, creating single-point-of-failure exposure for mid-sized hospital systems lacking multi-cloud failover architectures.
- GDPR data residency friction:European providers face operational complexity maintaining patient records within jurisdictional boundaries while enabling cross-border care coordination for mobile populations.
- Technical debt accumulation:Decades of proprietary EHR customizations in academic medical centers resist standardization, requiring expensive middleware translation layers that erode cloud migration ROI calculations.
Strategic Opportunities
- Japan's regional medical coordination:Prefecture-level integrated care systems under METI digital health initiatives seek population health platforms connecting acute hospitals with long-term care facilities. Vendors with aging-care workflow expertise capture first-mover positioning.
- Remote patient monitoring convergence:Wearable device data streams and home-based diagnostic tools create demand for edge-computing architectures that preprocess biometric signals before cloud transmission.
- Subscription-based interoperability:Revenue models shift from perpetual licenses to API-call pricing, enabling smaller clinics to access enterprise-grade data exchange without capital expenditure commitments.
Industry Challenges
- Health informatics talent scarcity:Health systems compete with technology firms for clinical data engineers capable of mapping unstructured physician notes to standardized terminologies like SNOMED CT.
- Legacy system integration complexity:Mainframe-based patient accounting systems from the 1990s persist in safety-net hospitals, requiring costly custom interface engines that delay modernization timelines.
- Multi-jurisdictional compliance burden:Vendors serving cross-border health networks must simultaneously satisfy HIPAA breach notification rules, GDPR subject access requests, and Japan's Act on Protection of Personal Information amendment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Data Management Systems Market |
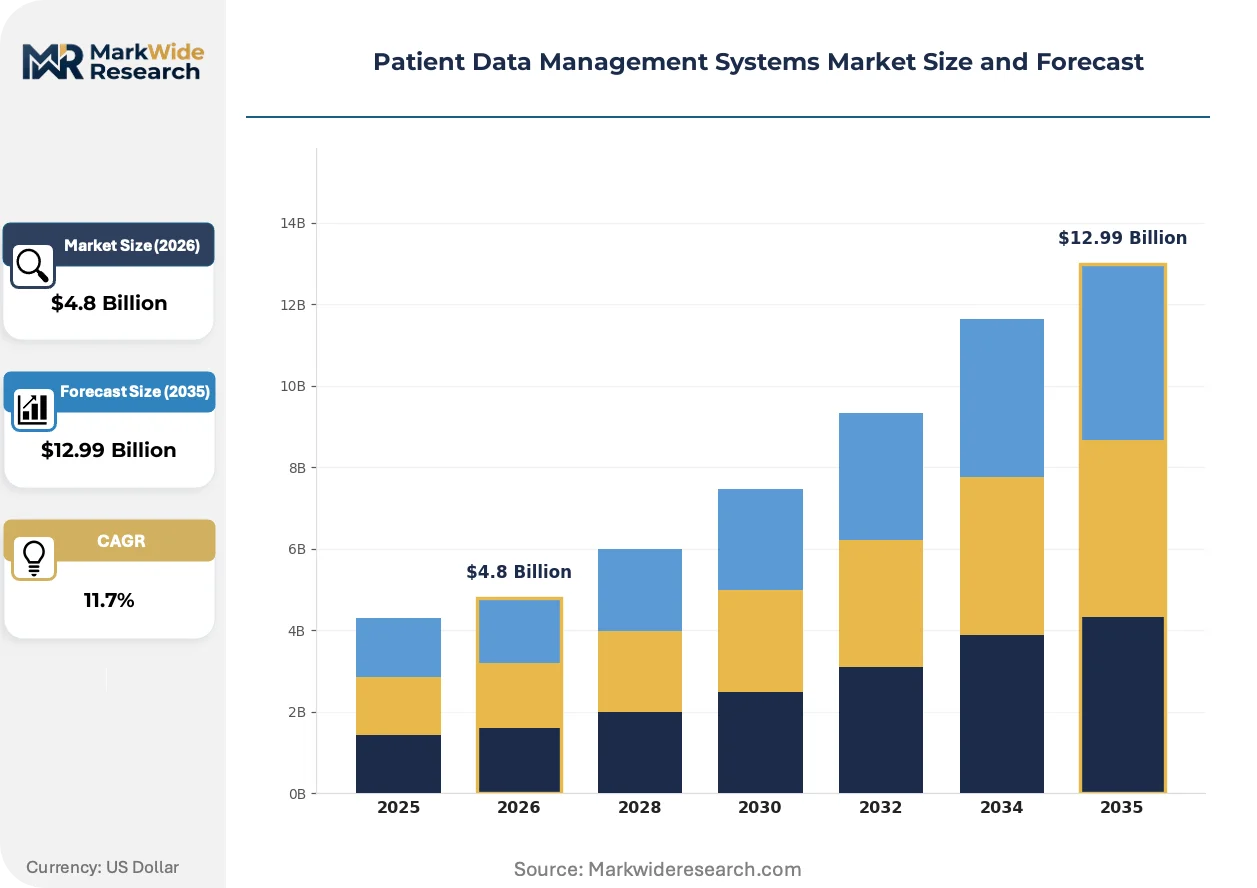
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Health Records, Practice Management Systems, Patient Portals, Health Information Exchanges Delivery Mode: Cloud-based, On-premises, Hybrid, Mobile End User: Hospitals, Ambulatory Care Centers, Specialty Clinics, Research Institutions Integration Level: Standalone Systems, Integrated Solutions, Interoperable Platforms, Others |
| Companies Covered | IBM, IQVIA Holdings Inc., Health Catalyst Inc., Oracle Health, Epic Systems, MEDITECH, UnitedHealth Group, Innovaccer, Veradigm Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Data Management Systems Market Strategic Shifts
Artificial intelligence and edge computing architectures are restructuring how patient data flows between point-of-care devices and centralized repositories, compressing latency requirements for time-critical clinical decisions.
Natural language processing engines for clinical documentation is converging with ambient listening hardware deployed in examination rooms. Primary care networks in the United States adopt these systems to reduce physician keyboard time. Real-time transcription is compressing the gap between patient encounter and structured billing code generation.
The EU AI Act risk classification framework imposes conformity assessment obligations on diagnostic algorithms embedded within patient data platforms. Vendors must maintain technical documentation and human oversight protocols for high-risk AI applications. European hospital procurement committees now prioritize vendors with established notified body relationships.
Consolidated purchasing through regional health information exchanges is displacing standalone hospital negotiations in several United States markets. State-designated entities aggregate demand across competing delivery systems to standardize data sharing agreements. California and New York exhibit the most advanced exchange-mediated procurement patterns.
Patient Data Management Systems Market Segmentation
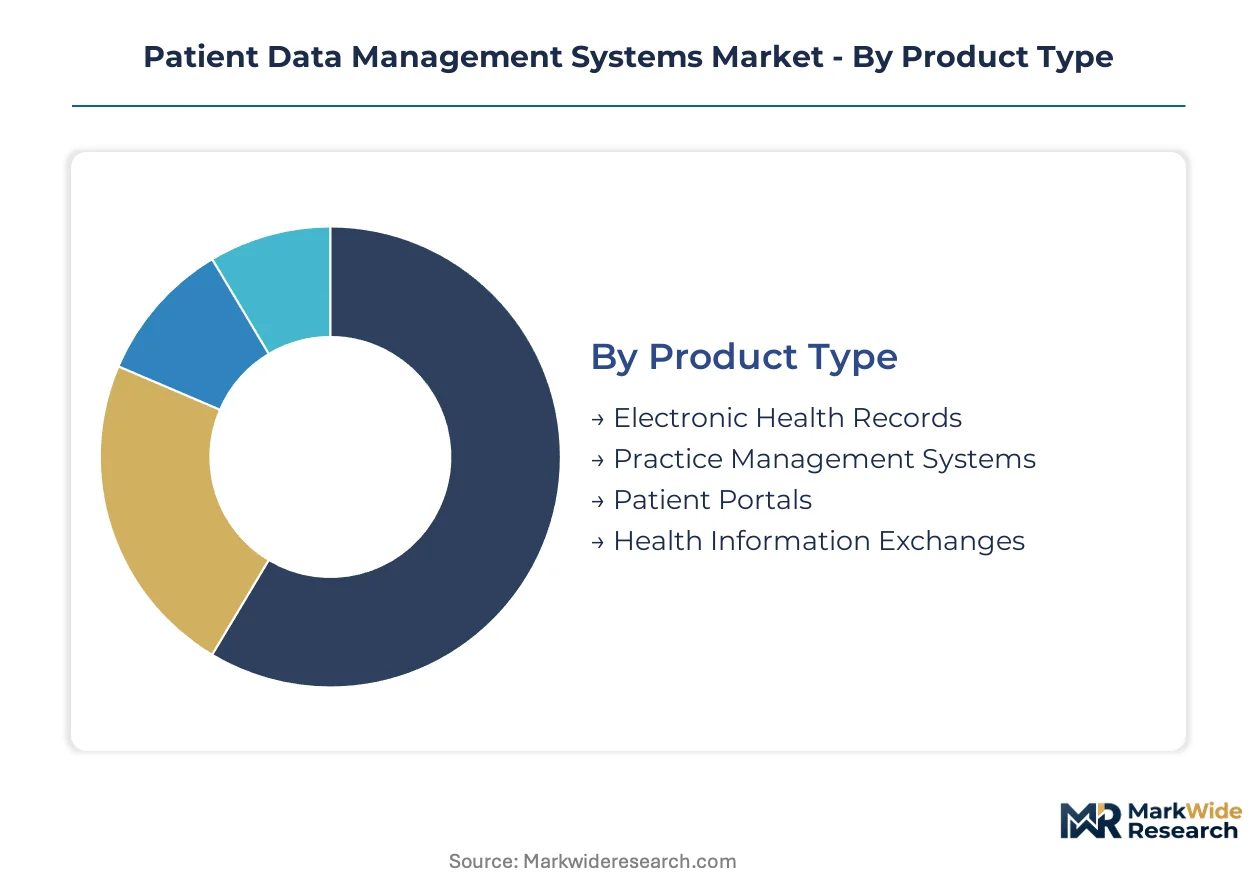
Patient data management systems fragment across four structural dimensions that determine procurement priorities and vendor positioning. Product type and delivery mode capture technology architecture decisions, while end user and integration level segments reflect operational complexity and regulatory compliance requirements.
Product Type:
Electronic Health Records dominate installed base volume, while interoperability platforms command premium pricing due to regulatory mandates for seamless data exchange.
- Electronic Health Records:Core platforms aggregate structured clinical data across encounters, supporting CPOE and clinical decision support. Academic medical centers in the United States drive demand for Epic and Cerner deployments that integrate with revenue cycle management. HIPAA meaningful use requirements sustain replacement cycles even where legacy systems persist.
- Practice Management Systems:Scheduling, billing, and administrative workflow engines designed for outpatient revenue optimization. German ambulatory networks under the Hospital Future Act prioritize these systems for municipal health system consolidation. Federal funding streams accelerate procurement timelines for certified vendors.
- Patient Portals:Consumer-facing interfaces enabling appointment scheduling, prescription refill, and lab result access.
- Health Information Exchanges:Regional data sharing infrastructure connecting competing provider networks.
Mature deployment sits with Electronic Health Records. Newer deployment is concentrated in Health Information Exchanges.
Delivery Mode:
Cloud-based delivery is expanding most quickly as hospitals migrate from capital-intensive server farms to subscription models with automatic compliance updates.
- Cloud-based:Multi-tenant SaaS architectures with ISO 27001-certified security and automatic HIPAA updates. Mid-sized United States hospitals lacking dedicated IT infrastructure favor this model for predictable opex budgeting. ONC certification deadlines accelerate migration away from on-premises alternatives.
- On-premises:Dedicated server infrastructure maintained within hospital data centers. Japanese university hospitals with strict data residency requirements under METI guidelines retain these deployments for jurisdictional control. High capital intensity limits adoption to well-capitalized systems.
- Hybrid:Sensitive data remains on-site while analytics workloads shift to cloud.
- Mobile:Point-of-care applications running on tablets and smartphones for bedside documentation.
Capital concentration favors On-premises at large academic centers. Operational flexibility drives Hybrid adoption among regional networks.
End User:
Hospitals anchor revenue concentration, though ambulatory networks represent the steepest expansion trajectory as outpatient volume shifts accelerate.
- Hospitals:Inpatient-focused platforms requiring 24/7 uptime, disaster recovery, and integration with laboratory and pharmacy systems. United States health systems under 21st Century Cures Act mandates prioritize interoperability middleware for multi-facility networks. Epic Systems captures dominant share through deep academic medical center relationships.
- Ambulatory Care Centers:Outpatient-focused deployments emphasizing scheduling efficiency and referral management. Germany's regional health networks consolidate procurement around certified vendors serving municipal systems. Federal digital infrastructure funding enables EHR replacement at previously underserved sites.
- Specialty Clinics:Workflow-optimized systems for cardiology, oncology, and orthopedics with procedure-specific documentation templates.
- Research Institutions:Platforms supporting clinical trial data capture and regulatory submission workflows.
Regulatory complexity concentrates at Hospitals. Workflow specialization drives Specialty Clinics toward niche vendors.
Integration Level:
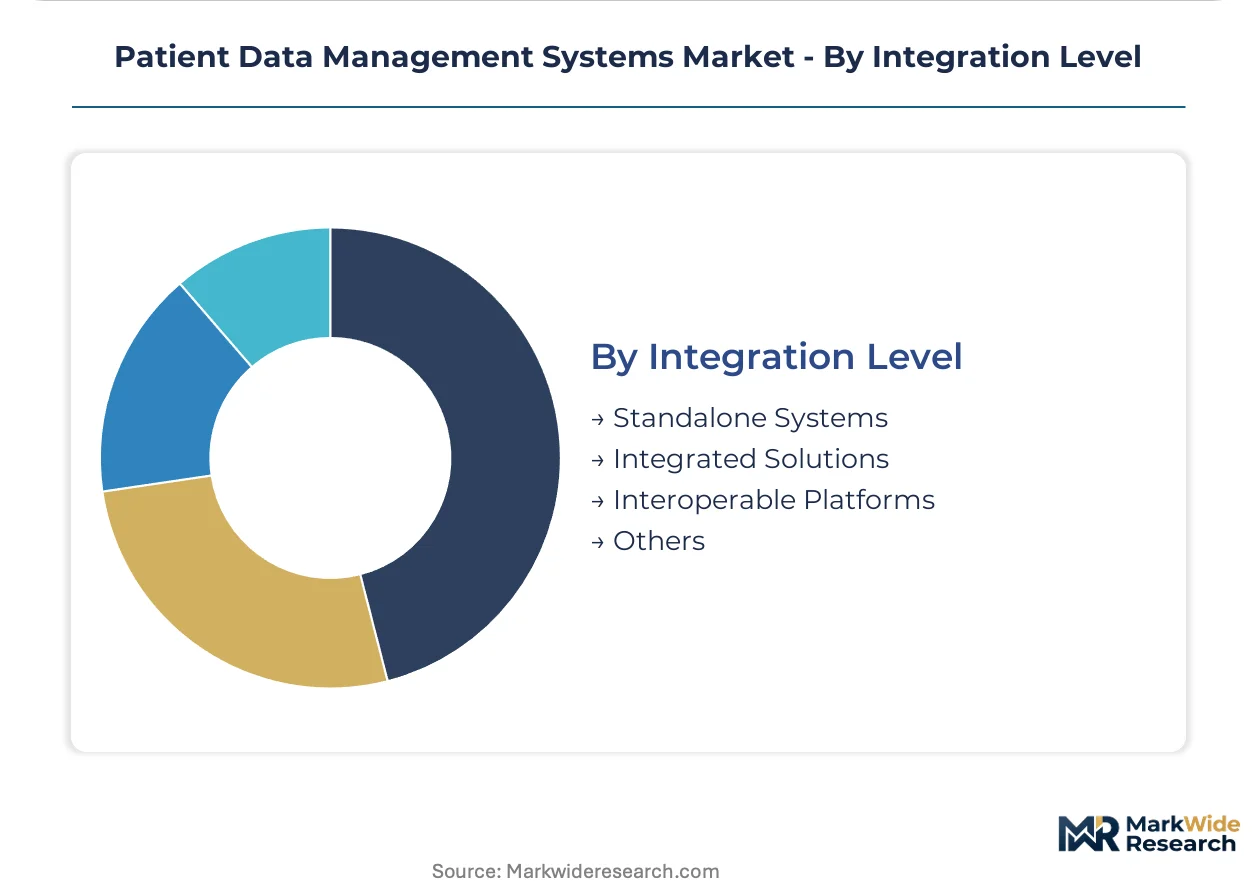
Standalone systems retain installed base in resource-constrained settings, while integrated solutions capture procurement preference at health systems prioritizing unified workflows.
- Standalone Systems:Single-function applications operating without real-time data exchange to external platforms. Safety-net hospitals in the United States with 1990s-era mainframe accounting systems retain these for cost containment. Technical debt accumulation delays modernization timelines.
- Integrated Solutions:Unified platforms spanning clinical, financial, and operational domains through common data models. Oracle Health anchors enterprise-scale deployments across multi-hospital networks seeking single-vendor accountability. Consolidated purchasing through regional exchanges favors these comprehensive architectures.
- Interoperable Platforms:Middleware solutions bridging incompatible EHR systems through HL7 FHIR APIs.
- Others:Emerging architectures including blockchain-based consent management and federated learning infrastructure.
Budget constraints sustain Standalone Systems in undercapitalized markets. Regulatory pressure drives Interoperable Platforms into procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health technology special economic zones in Research Triangle Park and Boston's Seaport Innovation District concentrate vendor headquarters and pilot deployment sites for next-generation patient data platforms.
United States
Academic medical centers in Boston and the Research Triangle Park drive demand for enterprise-scale interoperability platforms. HIPAA and the 21st Century Cures Act mandate standardized data exchange through ONC-certified FHIR APIs. Epic Systems anchors deployments across the University of Wisconsin-Madison and Stanford Health Care networks.
Germany
University hospitals in Berlin and Munich prioritize EHR replacement cycles under federal digital infrastructure programs. The Hospital Future Act channels funding toward municipal health system consolidation and certified vendor procurement. Baden-Württemberg's regional health networks standardize around interoperable middleware connecting competing delivery systems.
Japan
Prefecture-level integrated care initiatives in Kanagawa and Osaka link acute hospitals with long-term care facilities through METI-guided digital health platforms. The Act on Protection of Personal Information amendment protocols enforce strict data residency requirements. Tokyo's university hospitals retain on-premises architectures for jurisdictional control over sensitive patient records.
United Kingdom
NHS England's integrated care systems in London and Manchester aggregate procurement demand across former clinical commissioning groups. GDPR and the NHS Data Security and Protection Toolkit impose algorithmic transparency obligations on diagnostic AI vendors. Cambridge's biomedical cluster attracts real-world evidence partnerships linking clinical records to pharmaceutical research analytics.
India
Corporate hospital chains in Bengaluru and Hyderabad adopt cloud-based patient data platforms for multi-facility network management. The Digital India initiative and proposed Digital Information Security in Healthcare Act shape vendor certification requirements. Telangana's medical technology corridor hosts pilot programs for wearable device integration with hospital information systems.
Patient Data Management Systems Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise software vendors commanding premium positioning in health system networks while modular component providers serve ambulatory point solutions. The vendor landscape organizes into three tiers: dominant platform incumbents with deep academic medical center relationships, mid-scale interoperability specialists bridging legacy EHR architectures, and emerging cloud-native entrants targeting subscription-based API pricing. Consolidation pressure intensifies through strategic acquisitions of data analytics capabilities and geographic expansion into federally funded modernization markets.
Within the dominant platform tier, Epic Systems and Oracle Health exemplify contrasting scale strategies—Epic leverages tight integration with research-intensive academic centers while Oracle anchors multi-hospital network deployments seeking single-vendor accountability. IQVIA Holdings Inc. occupies a distinct position linking clinical data management to pharmaceutical real-world evidence partnerships, extending platform utility beyond traditional care coordination into post-market surveillance and research analytics.
| Leading Market Players |
|---|
| IBM |
| IQVIA Holdings Inc. |
| Health Catalyst Inc. |
| Oracle Health |
| Epic Systems |
| MEDITECH |
| UnitedHealth Group |
| Innovaccer |
| Veradigm Inc |
| Others |
Value Chain & Pricing Dynamics
Cloud infrastructure commodity indices cascade through patient data management supply chains, compressing margins for on-premises vendors while expanding pricing power for multi-tenant SaaS providers serving mid-sized United States hospitals under ONC certification deadlines.
Pricing Analysis
Short lead-time premiums distinguish urgent EHR replacement contracts from standard procurement cycles in Germany's Hospital Future Act-funded deployments. Three-tier pricing structure across premium, standard, and economy levels segments by integration complexity, with ONC-certified FHIR API modules commanding tier-one positioning. Cost compression in economy-tier standalone systems is intensifying because safety-net hospitals delay modernization amid technical debt accumulation. Ambulatory care centers exhibit highest price sensitivity, while academic medical centers prioritize workflow continuity over unit economics.
Supply Chain Analysis
Japan's Act on Protection of Personal Information amendment protocols reshape sourcing toward domestic data residency-compliant hosting infrastructure. Supply concentration centers on United States hyperscale cloud providers, German middleware specialists, and Japanese systems integrators serving METI-guided regional care networks. Software development draws from global talent pools for HL7 FHIR engineers, ISO 27001-certified security architects, and clinical informaticists. Single-source vulnerability persists in cloud infrastructure dependencies. Distribution runs through direct enterprise sales teams for hospital networks and regional value-added resellers for ambulatory deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient data management functions as a vertical-integration race where control over real-world evidence pipelines and edge-computing infrastructure determines long-term margin capture.
For Market Incumbents: Anticipate cloud-native entrants undercutting subscription pricing in ambulatory segments by acquiring interoperability middleware specialists with established FHIR API libraries. Consolidate procurement influence through regional health information exchange partnerships in California and New York. Deepen backward integration into wearable device data preprocessing to defend against edge-computing disintermediation.
For New Entrants and Emerging Players: Ambient clinical documentation AI offers technology-first wedge positioning in United States primary care networks seeking to reduce physician administrative burden. Target Japan's prefecture-level integrated care systems under METI digital health initiatives for first-mover positioning in aging-care workflow optimization. Pursue API-call pricing models to bypass capital expenditure barriers at smaller German municipal hospitals.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale interoperability specialists with established ONC certification and hospital system reference accounts in United States markets. Long-term viability hinges on regulatory compliance automation capabilities across HIPAA, GDPR, and Japan's APPI amendment protocols. Watch HL7 FHIR API standardization enforcement as inflection indicator for middleware consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FHIR API Certification Investment | ONC certification deadlines in United States hospitals accelerate procurement preference for standardized data exchange modules. |
| Real-World Evidence Partnership | Pharmaceutical manufacturer data linkages extend platform utility into post-market surveillance and research analytics revenue streams. |
| Edge-Computing Architecture Deployment | Wearable device data preprocessing capabilities capture remote patient monitoring convergence demand in Japanese prefecture networks. |
| Regional Health Exchange Integration | Consolidated purchasing through California and New York state-designated entities displaces standalone hospital negotiations. |
| Multi-Jurisdictional Compliance Automation | Simultaneous HIPAA, GDPR, and APPI amendment protocol satisfaction reduces vendor operational burden in cross-border deployments. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this patient data management systems analysis. Primary interviews with hospital CIOs, health informatics directors, GPO contracts managers, and EHR implementation specialists combined with FDA 510(k) databases, ONC certification registries, CMS Medicare reimbursement data, and hospital procurement databases. Bottom-up facility-level deployment tracking and top-down vendor revenue analysis enabled triangulation across the analysis window.
Granularity-level modeling captured product type, delivery mode, end user, and integration level dimensions at country-level resolution. Deployment model, organization size, and regional regulatory cluster variations shaped value projections throughout the forecast period. CAGRs derived from facility replacement cycle analysis, federal funding authorization trajectories, and interoperability mandate compliance timelines. Cloud migration velocity and real-world evidence integration adoption curves informed segment-specific growth assumptions.
Several conditions sit outside the modeled scope, including hypothetical repeal of 21st Century Cures Act information blocking provisions, catastrophic cloud infrastructure security breaches, and unforeseen HL7 FHIR standard revision disruptions. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and hospital capital expenditure recovery. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
US Mobile Health Market
Health Data Management
Hospital Management Software Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Big Data Healthcare Market