
 Clinical Trial Data Management Software Market | 2026-2036
Clinical Trial Data Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Trial Data Management Software Market Analysis
North America is narrowing its lead in clinical data infrastructure investment as regulatory complexity intensifies. Medidata leverages vertical integration across electronic data capture and patient engagement tools to sustain platform stickiness. Veeva Systems anchors its position through cloud-native architecture purpose-built for life sciences compliance workflows. Oracle competes by extending enterprise database dominance into trial-specific analytics modules.
Clinical trial data management software comprises integrated technology platforms that capture, validate, store, and analyze patient data throughout pharmaceutical and biologics research protocols, typically operating under 21 CFR Part 11 audit trails with ALCOA+ data integrity standards to support regulatory submission packages. EDC and CTMS deployments command the largest installed bases due to their status as foundational trial infrastructure, while AI and machine learning integrations represent the fastest-expanding technology layer as sponsors automate query resolution and predictive enrollment forecasting. Cloud-based and SaaS delivery models are displacing on-premise installations across mid-sized biotech firms and academic institutions seeking elastic compute capacity without capital-intensive server commitments.
FDA enforcement of 21 CFR Part 11 shapes software validation requirements and audit trail specifications for all US-targeted trials, while EMA's Policy 0070 on clinical data publication drives demand for redaction-capable analytics platforms in European submissions. ISO 14155 and ICH E6(R2) GCP guidelines further standardize data quality expectations across multinational study designs. Stakeholders must monitor evolving FDA guidance on decentralized trials and real-world evidence integration to align platform roadmaps with inspection priorities.
Market Dynamics
Cloud-native architectures are compressing deployment timelines for clinical data platforms, forcing legacy on-premise vendors to accelerate SaaS migrations or cede mid-market biotech accounts to agile competitors.
Growth Catalysts
- FDA 21 CFR Part 11:Audit trail mandates compel sponsors to upgrade electronic data capture systems, creating replacement cycles across Phase II-III trial portfolios.
- Decentralized trial protocols:Direct-to-patient data collection models require mobile-enabled ePRO and telemedicine integrations, expanding software subscription scopes.
- Biotech R&D expansion:Venture-funded cell and gene therapy developers prioritize cloud-based CTMS deployments to accelerate IND-to-NDA timelines without capital infrastructure.
Market Restraints
- Validation cost structure:IQ/OQ/PQ documentation requirements for GxP software inflate implementation budgets by 40-60% versus standard enterprise SaaS.
- Specialized talent scarcity:Clinical data managers with combined therapeutic domain and technical platform expertise command premium compensation, constraining sponsor hiring velocity.
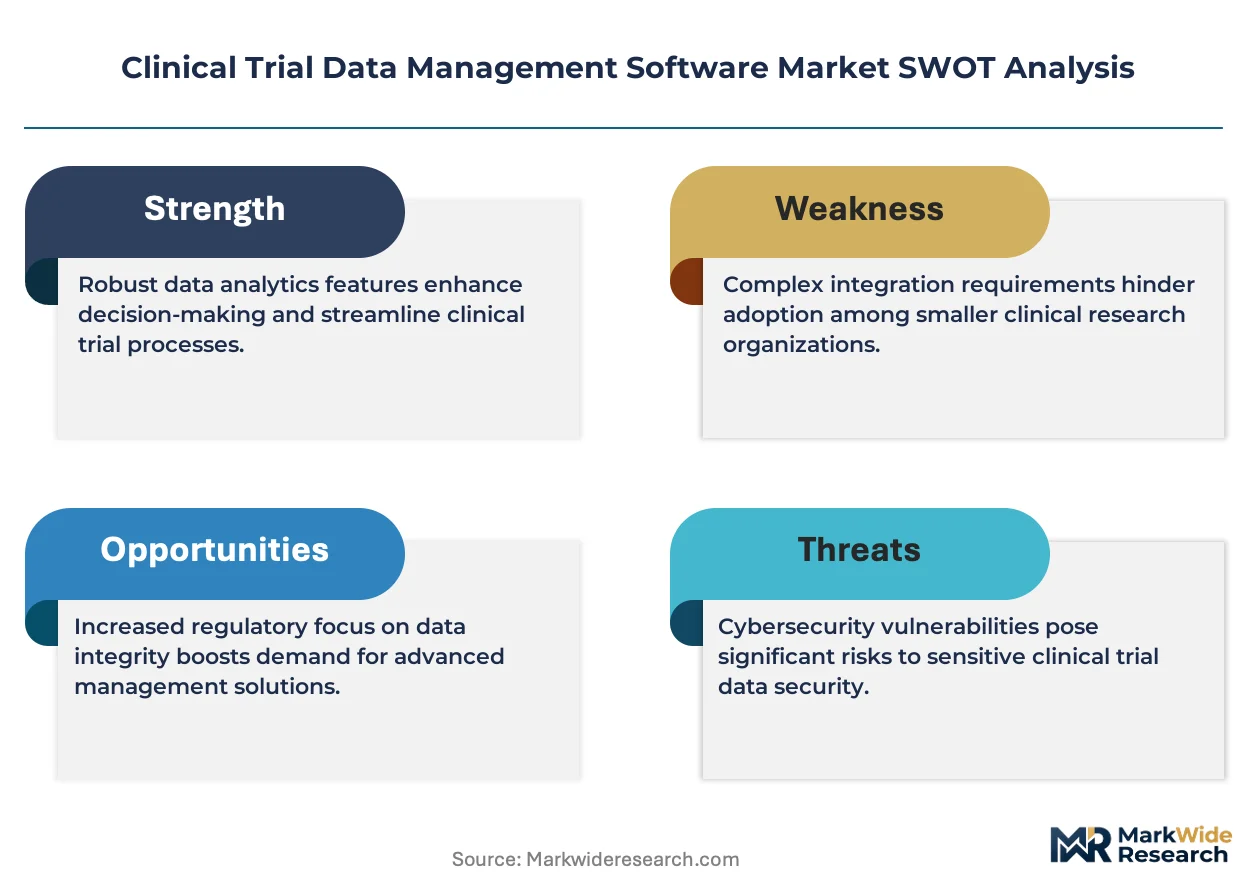
- Interoperability friction:Proprietary data formats across EDC, CTMS, and eTMF platforms force expensive custom integration projects.
Strategic Opportunities
- EMA Policy 0070 compliance tools:Automated redaction and anonymization modules for clinical study reports open specialized analytics sub-segments in European submissions.
- Real-world evidence convergence:Integration of EHR-derived data streams with traditional trial datasets creates new platform tiers for hybrid protocol designs.
- Academic medical center digitization:Underpenetrated research institutions in India and Brazil present greenfield SaaS conversion opportunities as national funding agencies mandate electronic data standards.
Industry Challenges
- ALCOA+ data integrity enforcement:FDA Warning Letters citing Attributable, Legible, Contemporaneous, Original, and Accurate violations force costly remediation of legacy spreadsheet-based processes.
- Multi-vendor integration complexity:Sponsors operating heterogeneous software estates face escalating technical debt as point solutions proliferate across functional silos.
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 attestations extend vendor onboarding cycles, delaying study startup milestones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Trial Data Management Software Market |
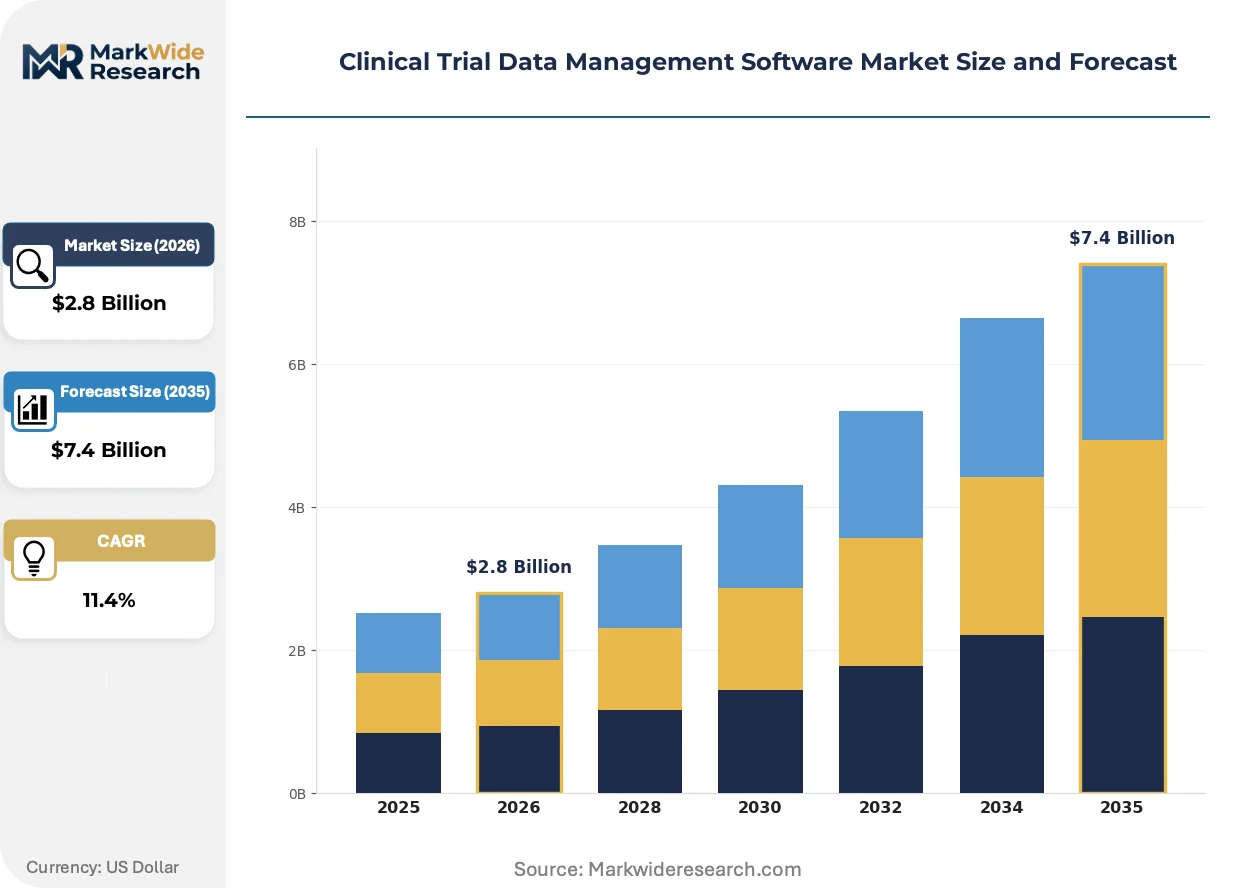
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EHR, CTMS, EDC, Data Analytics End User: Pharmaceutical Companies, Biotech Firms, CROs, Academic Institutions Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Technology: AI, Machine Learning, Blockchain, Data Integration |
| Companies Covered | Medidata, Veeva Systems, Oracle, IQVIA, IBM, Advarra, Clario, BioClinica, Datatrak, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Trial Data Management Software Market Emerging Trajectories
Artificial intelligence is embedding into core clinical data workflows, compressing query resolution timelines and enabling predictive enrollment modeling that reshapes trial feasibility assessments.
Machine learning algorithms for automated query generation and source data verification are hybridizing traditional EDC architectures with cognitive automation layers. Large pharmaceutical sponsors deploy these modules in Phase III cardiovascular and oncology studies, reducing manual data manager workload by automating discrepancy detection. This hybridization is compressing database lock timelines from weeks to days, forcing competitive vendors to embed native AI capabilities or risk displacement in enterprise evaluations.
EMA's Policy 0070 on clinical data publication mandates transparent disclosure of patient-level data, compelling analytics platform vendors to develop automated anonymization and redaction engines. Sponsors targeting European submissions must demonstrate technical compliance with disclosure requirements or face regulatory rejection. Biostatistics teams in Germany and France are prioritizing platforms with built-in disclosure workflows, shifting procurement criteria toward regulatory-ready feature sets.
Subscription-based SaaS procurement is displacing perpetual license arrangements across mid-sized biotech and academic sponsor segments. Finance departments favor operational expenditure treatment and elastic user scaling over capital-intensive on-premise deployments. This preference shift concentrates most visible in United States and United Kingdom markets, where venture-backed biotechs prioritize cash conservation and rapid study startup over long-term asset ownership.
Clinical Trial Data Management Software Market Segmentation
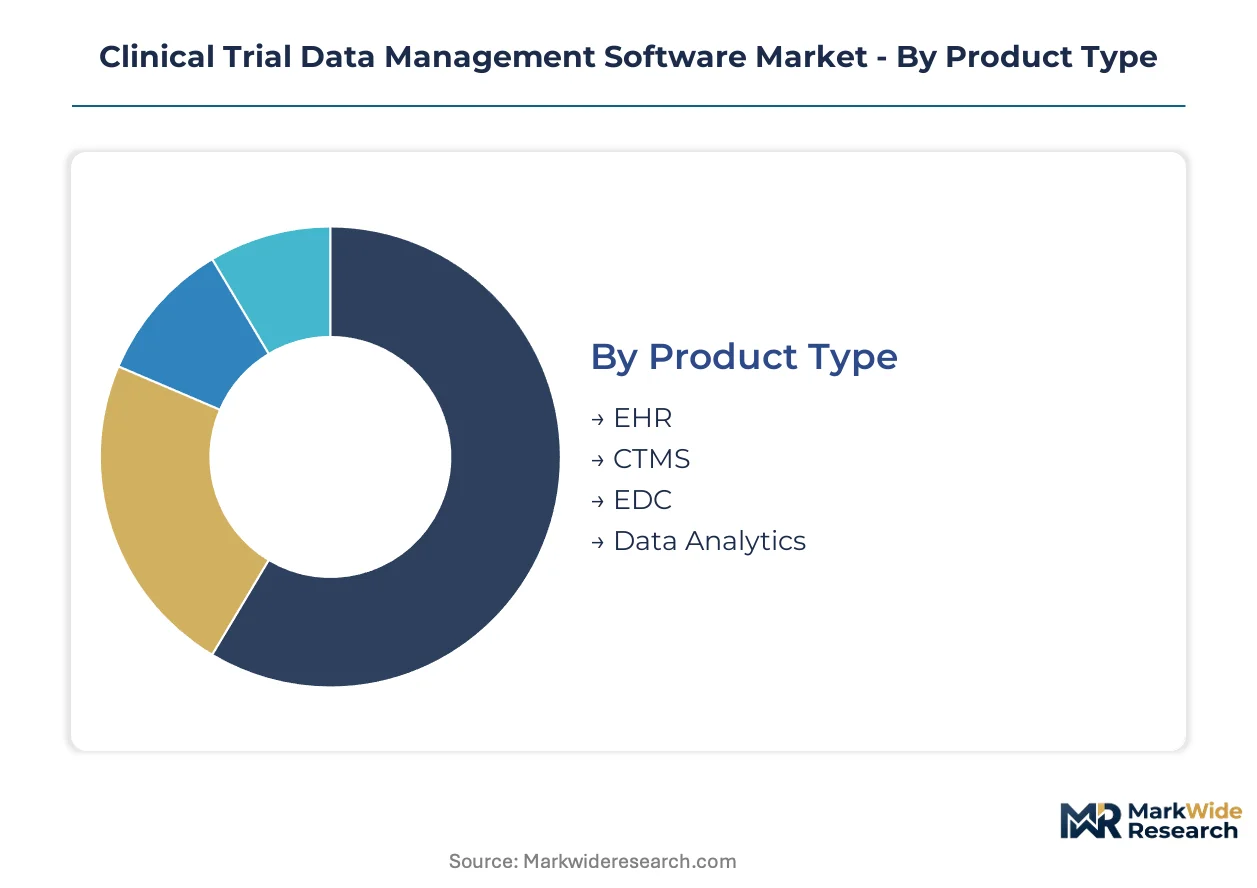
Segmentation in clinical trial data management software reveals how regulatory requirements, R&D funding patterns, and infrastructure maturity create divergent technology needs across sponsor types and deployment environments. Understanding these splits enables vendors to align platform roadmaps with buyer readiness and compliance timelines.
Product Type:
After-sales service intensity varies sharply across product categories, with EDC and CTMS platforms requiring continuous validation support while analytics modules demand ongoing algorithm retraining.
- EHR:Electronic health record integrations bridge hospital information systems with trial databases, enabling direct patient data ingestion. Demand concentrates in United States academic medical centers pursuing FDA real-world evidence guidance, constrained by HIPAA interoperability friction.
- CTMS:Clinical trial management systems orchestrate site activation, monitoring schedules, and regulatory document workflows across decentralized protocols. Biotech sponsors in Massachusetts and California prioritize cloud-native CTMS deployments to compress IND-to-first-patient timelines without capital infrastructure commitments.
- EDC:Electronic data capture platforms remain the foundational revenue layer, with 21 CFR Part 11 audit trail mandates forcing replacement cycles across Phase II-III portfolios.
- Data Analytics:Advanced analytics modules for predictive enrollment and safety signal detection are expanding most quickly as sponsors automate biostatistics workflows.
By volume, EDC leads. By growth pace, Data Analytics is ahead.
End User:
Cost tier segmentation separates enterprise-grade deployments from scaled-down configurations, with pharmaceutical companies absorbing full validation burdens while academic institutions seek stripped-down SaaS tiers.
- Pharmaceutical Companies:Large sponsors operate heterogeneous software estates spanning EDC, CTMS, eTMF, and safety platforms, driving demand for unified data lakes and API orchestration layers. Roche and Novartis procurement teams in Basel prioritize vendors with pre-validated GxP documentation packages to accelerate study startup.
- Biotech Firms:Venture-funded developers prioritize operational expenditure treatment and elastic scaling over capital-intensive on-premise deployments. Cell and gene therapy specialists in Cambridge and South San Francisco favor subscription CTMS models to conserve cash through preclinical-to-Phase I transitions.
- CROs:Contract research organizations demand multi-tenant architectures supporting simultaneous sponsor engagements with data segregation guarantees.
- Academic Institutions:University medical centers present greenfield conversion opportunities as NIH and Wellcome Trust funding mandates push electronic data standards adoption.
Pharmaceutical Companies dominate absolute spend. Biotech Firms are expanding most quickly.
Deployment:
Application context determines deployment choice, with multinational Phase III studies requiring hybrid architectures while single-site early-phase trials run pure SaaS.
- On-Premise:Legacy installations persist at top-20 pharmaceutical sponsors with captive data centers and customized validation frameworks, though new commitments are rare.
- Cloud-Based:Elastic compute deployments enable mid-sized biotechs to scale user counts across study phases without infrastructure renegotiation.
- Hybrid:Split configurations keep sensitive patient identifiers on-premise while pushing anonymized analytics to public cloud tiers, satisfying German and French data residency requirements.
- SaaS:Subscription delivery is displacing perpetual licenses across United States and United Kingdom venture-backed sponsors prioritizing cash conservation and rapid study startup over long-term asset ownership.
SaaS commands new deal flow. Hybrid architectures show steepest expansion trajectory among European sponsors.
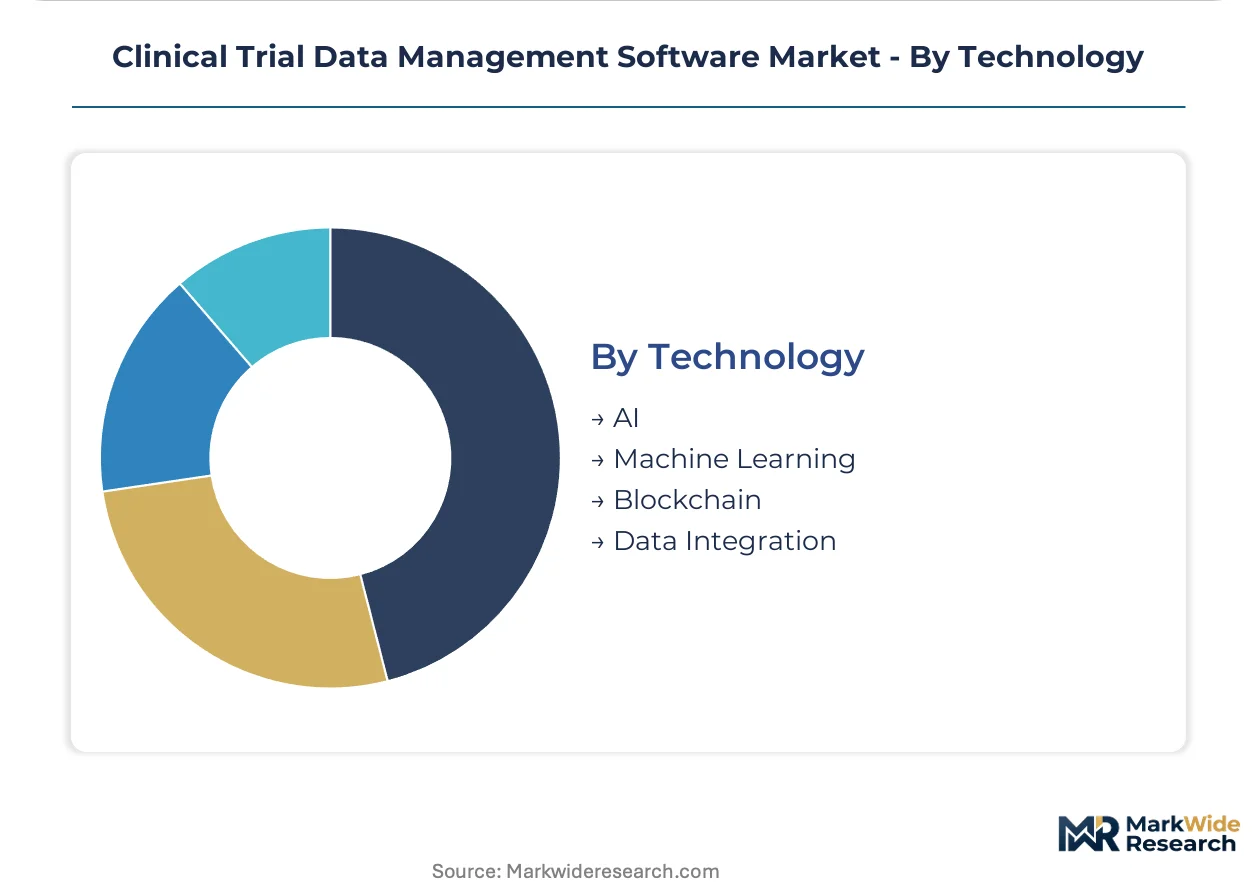
Technology:
Customer type sophistication splits the technology stack, with AI and machine learning penetrating large sponsor R&D budgets while blockchain remains experimental.
- AI:Cognitive automation layers embed into EDC architectures for automated query generation and source data verification, compressing database lock timelines from weeks to days at Pfizer and AstraZeneca.
- Machine Learning:Predictive enrollment models reshape trial feasibility assessments by forecasting site performance and patient recruitment velocity across cardiovascular and oncology indications.
- Blockchain:Distributed ledger pilots target consent management and supply chain provenance, though production deployments remain limited by validation uncertainty.
- Data Integration:Interoperability middleware connects heterogeneous vendor ecosystems, addressing the friction from proprietary formats across EDC, CTMS, and eTMF platforms.
AI leads technology investment. Machine Learning is climbing the fastest as sponsors automate biostatistics workloads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: United States sponsors prioritize cloud-native SaaS deployments for decentralized trials, while European buyers emphasize data residency compliance and German manufacturers anchor hybrid architecture demand.
United States
FDA 21 CFR Part 11 enforcement drives replacement cycles across Phase II-III trial portfolios, compelling sponsors to upgrade electronic data capture audit trails. Massachusetts and California biotech clusters in Cambridge and South San Francisco favor subscription CTMS models to conserve cash through preclinical-to-Phase I transitions.
Germany
EMA Policy 0070 clinical data publication mandates accelerate demand for automated redaction and anonymization modules in European submissions. Baden-Württemberg and Bavaria pharmaceutical hubs in Basel-proximate regions prioritize vendors with pre-validated GxP documentation packages to compress study startup timelines.
United Kingdom
Venture-backed biotechs in London and Cambridge prioritize operational expenditure treatment and elastic user scaling over capital-intensive on-premise deployments. MHRA alignment with FDA data integrity standards post-Brexit maintains software validation requirements equivalent to 21 CFR Part 11 specifications.
India
CDSCO electronic data standards mandates and NIH-equivalent funding agency digitization requirements open greenfield SaaS conversion opportunities at underpenetrated academic medical centers. Maharashtra and Karnataka research institutions in Mumbai and Bangalore present conversion targets as national regulators mandate ALCOA+ compliance.
Japan
PMDA GCP inspection intensity and ICH E6(R2) guideline adoption standardize data quality expectations across multinational study designs. Tokyo and Osaka pharmaceutical R&D clusters demand platforms with Japanese-language validation documentation and local hosting options for patient identifier protection.
Clinical Trial Data Management Software Market Vendor Landscape
Capability concentration sits with cloud-native specialists; scale advantage sits with enterprise database incumbents. The market structures around three tiers: vertically integrated platform vendors, modular point-solution providers, and legacy on-premise vendors accelerating SaaS migrations. Dominant competitive moves include M&A for patient engagement tool consolidation and strategic partnerships for EHR interoperability.
Within the cloud-native tier, Medidata and Veeva Systems exemplify platform stickiness through vertical integration across electronic data capture and compliance workflows. Oracle occupies a position as the enterprise database incumbent extending infrastructure dominance into trial-specific analytics modules.
| Leading Market Players |
|---|
| Medidata |
| Veeva Systems |
| Oracle |
| IQVIA |
| IBM |
| Advarra |
| Clario |
| BioClinica |
| Datatrak |
| Others |
Supply Flow & Price Mechanics
Cloud infrastructure overcapacity in United States hyperscaler regions is compressing SaaS hosting costs and enabling aggressive subscription pricing for clinical data platforms, while simultaneously pushing vendors toward multi-tenant architectures that accelerate deployment velocity for biotech buyers.
Pricing Analysis
Three-year subscription contracts with annual escalation clauses dominate procurement for enterprise EDC and CTMS deployments, displacing perpetual licenses across mid-sized biotech sponsors. Pricing stratifies across validated-GxP, standard-compliant, and academic-tier service levels, with FDA 21 CFR Part 11 certification premiums widening spreads between tiers. Cost compression in the academic segment is intensifying because NIH funding agencies mandate electronic data standards without corresponding budget increases. Venture-backed cell and gene therapy developers in Cambridge and South San Francisco exhibit highest price sensitivity, while Basel-proximate pharmaceutical procurement teams absorb premium pricing for pre-validated documentation packages.
Supply Chain Analysis
Export control restrictions on advanced AI training hardware under US Commerce Department regulations limit compute capacity flows to Chinese clinical analytics vendors, concentrating cloud-native platform development in United States, Ireland, and Germany data center regions. Software supply chains draw from open-source machine learning frameworks, proprietary encryption libraries, and GxP-validated middleware components. Single-source vulnerability in GPU cloud provisioning creates bottlenecks for sponsors deploying predictive enrollment models at scale. Distribution runs through direct enterprise sales teams for top-20 pharmaceutical accounts, with channel partners and system integrators serving mid-market biotech segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in clinical trial software is reaching an inflection where API-first interoperability determines ecosystem lock-in, with EHR-to-EDC data pipelines emerging as the decisive control point for sponsor switching costs.
For Market Incumbents: Build data moat depth through exclusive EHR network partnerships that embed trial platforms into hospital information system workflows. Incumbents should acquire patient engagement tool specialists to close gaps in decentralized trial coverage, defending against modular point-solution vendors that threaten platform stickiness through best-of-breed pricing. Certification investment in EMA Policy 0070 automated redaction modules anchors European procurement criteria. For New Entrants and Emerging Players: Academic medical centers in Maharashtra and Karnataka represent the most penetrable entry point for cloud-native SaaS conversions as CDSCO mandates ALCOA+ compliance without legacy infrastructure drag. Mid-sized CROs seeking multi-tenant architectures with sponsor data segregation offer second-wave expansion targets. A compliance-first go-to-market emphasizing pre-validated IQ/OQ/PQ documentation packages compresses enterprise sales cycles against incumbent professional services dependencies. For Investors and Strategic Acquirers: Capital is best deployed toward clinical data platforms with demonstrated FDA 21 CFR Part 11 audit trail enforcement and embedded AI query automation capabilities that compress database lock timelines. Long-term viability over the next decade rests on hybrid protocol support spanning traditional site-based and decentralized direct-to-patient models. The signal to watch as inflection indicator is biotech sponsor consolidation of EDC, CTMS, and eTMF spend onto single-vendor platforms versus heterogeneous best-of-breed estates.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified EDC-CTMS-eTMF data lakes reduce sponsor technical debt and accelerate study startup timelines. |
| Acquisition of Specialist Firm | Patient engagement tool consolidation closes coverage gaps in decentralized trial protocol execution. |
| Strategic Partnership | EHR interoperability agreements embed trial platforms into hospital information system workflows at academic medical centers. |
| Product Launch | EMA Policy 0070-compliant redaction modules open specialized procurement criteria in European submissions. |
| Geographic Expansion | CDSCO-mandated electronic data standards in India create greenfield SaaS conversion opportunities at underpenetrated research institutions. |
Methodological Framework
Cross-validation between primary interviews with clinical data managers, regulatory affairs directors, and biostatistics team leads and secondary sources including FDA 21 CFR Part 11 guidance documents, EMA Policy 0070 implementation frameworks, and ClinicalTrials.gov protocol registries anchors the qualitative findings. Bottom-up triangulation aggregates sponsor-level software procurement patterns across pharmaceutical, biotech, CRO, and academic segments, while top-down calibration validates against aggregate R&D IT spending disclosures. The analysis integrates electronic data capture deployment metrics, clinical trial management system subscription data, and patient engagement platform adoption rates.
Calibration against historical FDA inspection citation patterns and EMA submission rejection rates refines the projection framework across the analysis window. Segmentation modeling spans product type, end-user archetype, deployment model, and technology layer including AI and machine learning integration depth. CAGRs derive from sponsor R&D IT budget growth trajectories, regulatory mandate implementation timelines, and cloud infrastructure cost compression curves. Forecast inputs incorporate decentralized trial protocol expansion rates and real-world evidence integration adoption across hybrid study designs.
Practitioners should monitor FDA guidance evolution on decentralized trials and real-world evidence integration for early signals requiring forecast revision. Cross-checking against sponsor-disclosed software procurement timelines and CDSCO electronic data standard enforcement intensity is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Collection and Labeling Market
Health Data Management
Americas Healthcare Archiving and Ediscovery Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Global Healthcare Fraud Analytics Market