
 Global Precision Medicine Software Market | 2026-2036
Global Precision Medicine Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Precision Medicine Software Market Intelligence
A divergence between comprehensive, clinically validated platforms and basic data management tools is recalibrating the market. Premium software offers integrated genomic and clinical decision support, while lower-tier solutions focus on data storage. IBM Corporation leverages its AI capabilities in Watson Health to offer advanced analytics. IQVIA specializes in integrating clinical trial data with real-world evidence, differentiating through its large-scale data assets.
Precision medicine software comprises digital tools designed to integrate and analyze large-scale patient data, including genomic, proteomic, and clinical information. These platforms often incorporate algorithms for processing next-generation sequencing outputs to identify actionable mutations. Their primary purpose is to enable tailored therapeutic strategies. Oncology applications dominate the market due to the high volume of targeted cancer treatments, while biopharma companies represent a key end-user segment for drug discovery and development.
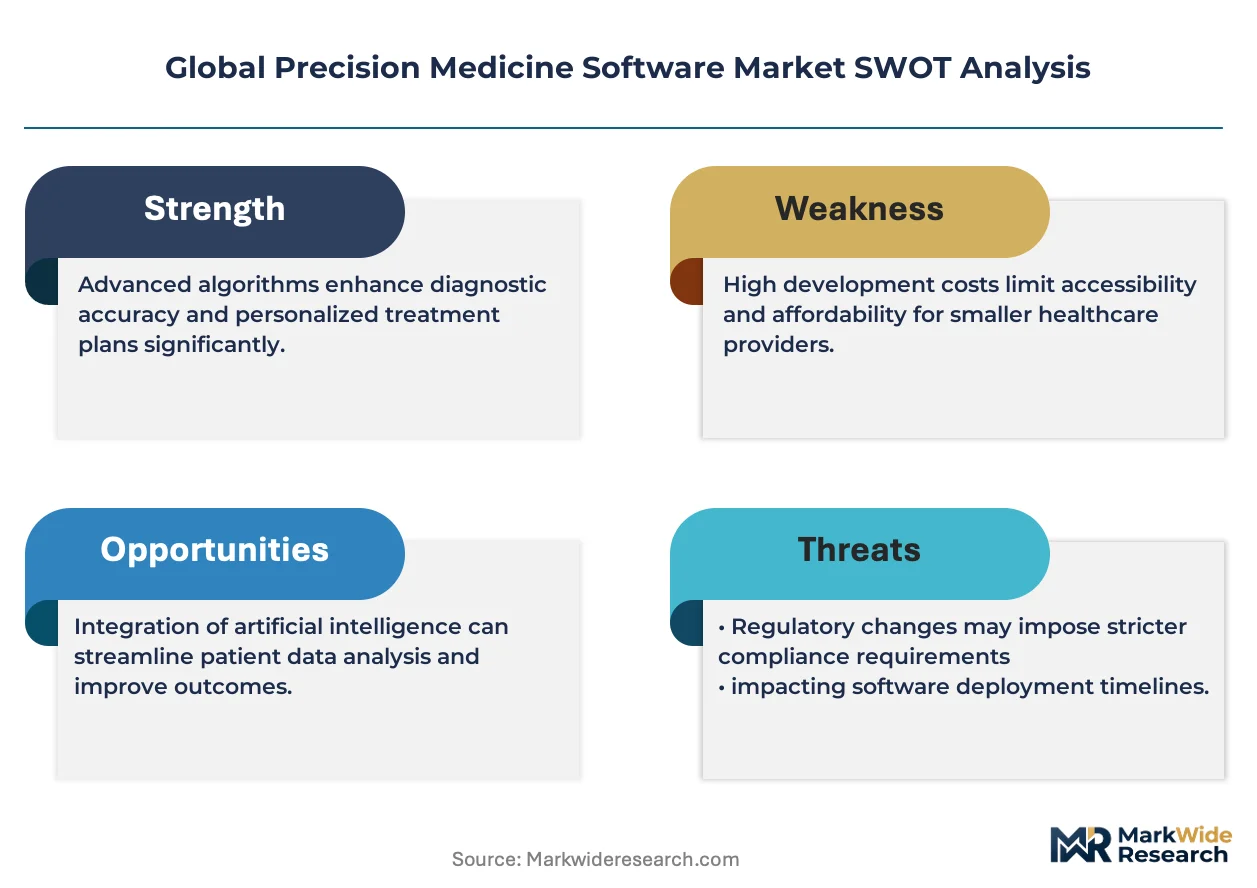
Regulatory frameworks governing data privacy and security are critical. In the United States, HIPAA dictates patient data handling, while the FDA oversees software as a medical device. Europe's GDPR imposes strict rules on personal data processing, impacting cross-border research collaborations. Stakeholders must therefore prioritize building platforms that ensure compliance with evolving international data governance and clinical validation standards.
Market Dynamics
A structural divergence between the need for standardized data exchange and the proprietary algorithms driving platform differentiation is defining the market. This creates a competitive environment where interoperability with hospital systems and unique analytical power are equally critical for vendor success.
Growth Catalysts
- Artificial Intelligence Integration:The application of machine learning algorithms to analyze next-generation sequencing data accelerates the identification of pathogenic variants, a core function demanded by oncology research and clinical diagnostics.
- Government-Led Genomic Initiatives:National projects, such as the United States' All of Us Research Program, generate massive datasets that require sophisticated software for management and analysis, directly stimulating platform demand.
- Biopharma Adoption for R&D:Pharmaceutical companies increasingly use precision medicine software to stratify patient populations for clinical trials, improving trial success rates and accelerating drug development timelines for targeted therapies.
Market Restraints
- High Implementation Costs:The significant upfront investment required for software licensing, integration with existing Electronic Health Record systems, and staff training presents a substantial barrier for smaller hospitals and clinics.
- Data Interoperability Challenges:A lack of universal standards for genomic and clinical data formats across different healthcare systems hinders seamless data sharing and aggregation, limiting the software's analytical power.
- Stringent Regulatory Hurdles:Navigating complex data privacy laws like Europe's GDPR and securing FDA clearance for software as a medical device (SaMD) creates long development cycles and high compliance costs.
Strategic Opportunities
- Expansion into Pharmacogenomics:Developing modules that integrate pharmacogenomic (PGx) data to guide routine drug prescribing beyond oncology represents a significant opportunity to broaden the software's clinical utility and user base.
- Federated Learning Models:Offering platforms that use federated learning allows for collaborative analysis of sensitive data across institutions without it leaving their firewalls, addressing major data privacy and governance concerns.
- Emerging Market Penetration:Targeting large-scale population health initiatives in countries like China and India provides access to new, large-volume markets as they build out their precision medicine infrastructure.
Industry Challenges
- Bioinformatics Talent Scarcity:A persistent shortage of data scientists and bioinformaticians who possess hybrid expertise in both computational biology and clinical workflows constrains the ability of end-users to fully leverage platform capabilities.
- Legacy System Integration:The technical complexity of integrating advanced software with a diverse and often outdated array of legacy Electronic Health Record (EHR) systems remains a primary operational hurdle for healthcare providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Precision Medicine Software Market |
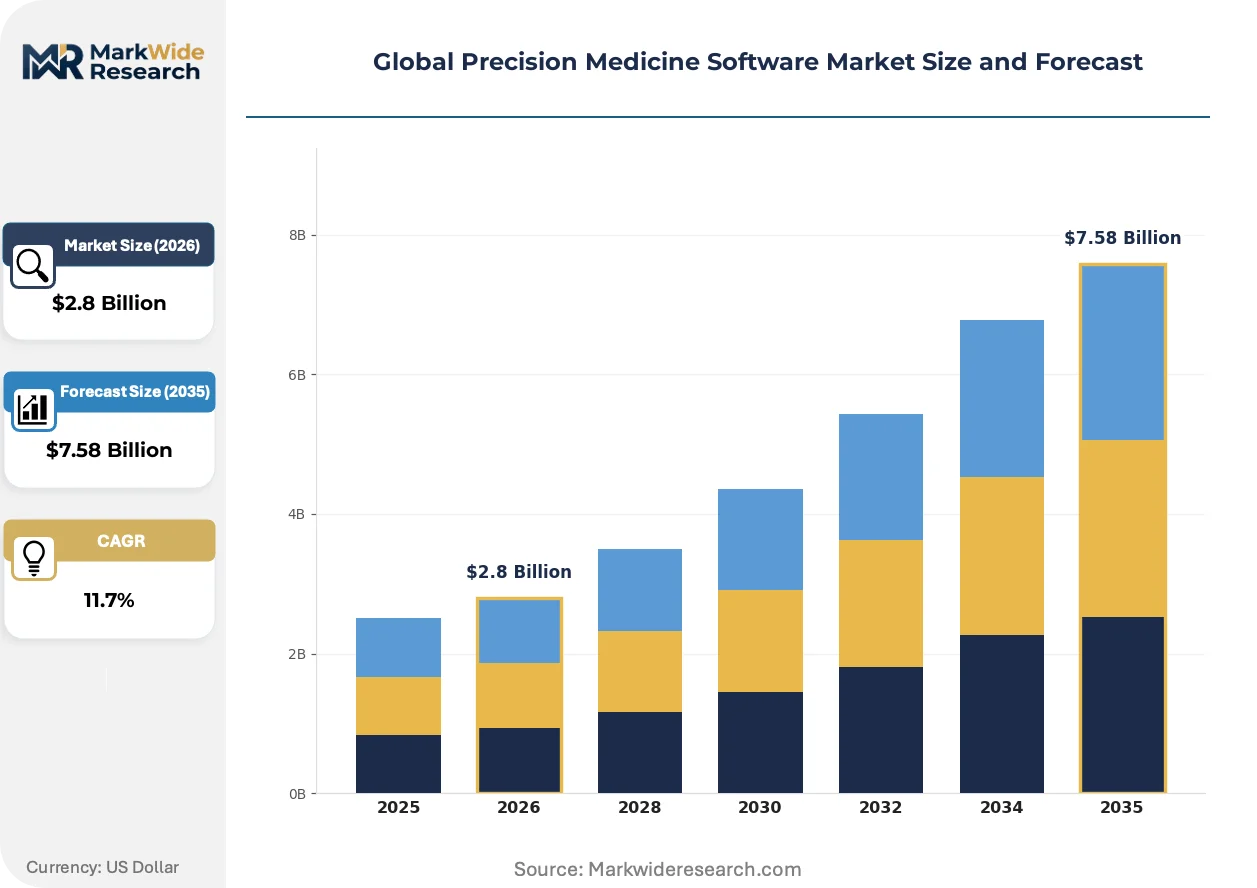
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clinical Decision Support, Genomic Data Analysis, Patient Engagement Platforms, Risk Assessment Tools, Therapeutic Monitoring Application: Oncology, Rare Diseases, Personalized Immunotherapy, Pharmacogenomics, Chronic Condition Management End User: Academic Medical Centers, Biopharma Companies, Diagnostic Laboratories, Health Insurers, Genetic Counseling Services Deployment: Cloud-Based Solutions, On-Premise Installations, Hybrid Models, SaaS Platforms, Edge Computing |
| Companies Covered | IQVIA, Syapse, IBM Corporation, GenomOncology, Fabric Genomics, Cerner Corporation, SOPHiA GENETICS, Human Longevity, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Precision Medicine Software Market Strategic Shifts & Innovations
The market's evolution is marked by a decisive shift from data storage and basic analysis toward integrated, point-of-care clinical decision support. This transition emphasizes actionable insights delivered directly within existing clinical workflows, prioritizing real-time utility over retrospective research.
Cloud-native platforms provide scalable, on-demand computational power for processing immense genomic datasets. Large academic medical centers and biopharma research organizations are the primary adopters, seeking to manage data from large-scale sequencing projects. This cloud architecture is absorbing the functions previously handled by on-premise servers and siloed data analysis workstations, centralizing analytics and fostering collaboration.
Regulatory bodies globally are actively defining pathways for software as a medical device (SaMD). Europe's Medical Device Regulation (MDR) imposes stringent requirements on clinical validation and post-market surveillance for decision support software. This affects all vendors operating in the EU, forcing them to invest more heavily in generating robust clinical evidence to support their platform's claims and maintain CE marking.
A move toward modular software acquisition is altering purchasing patterns within research and academic segments. End-users are increasingly opting out of monolithic platform licenses, instead subscribing to specific functional modules like variant annotation or clinical trial matching tools on a project basis. This behavioral shift is most pronounced in specialized biopharma research hubs in the United States and Germany seeking greater flexibility.
Global Precision Medicine Software Market Segmentation
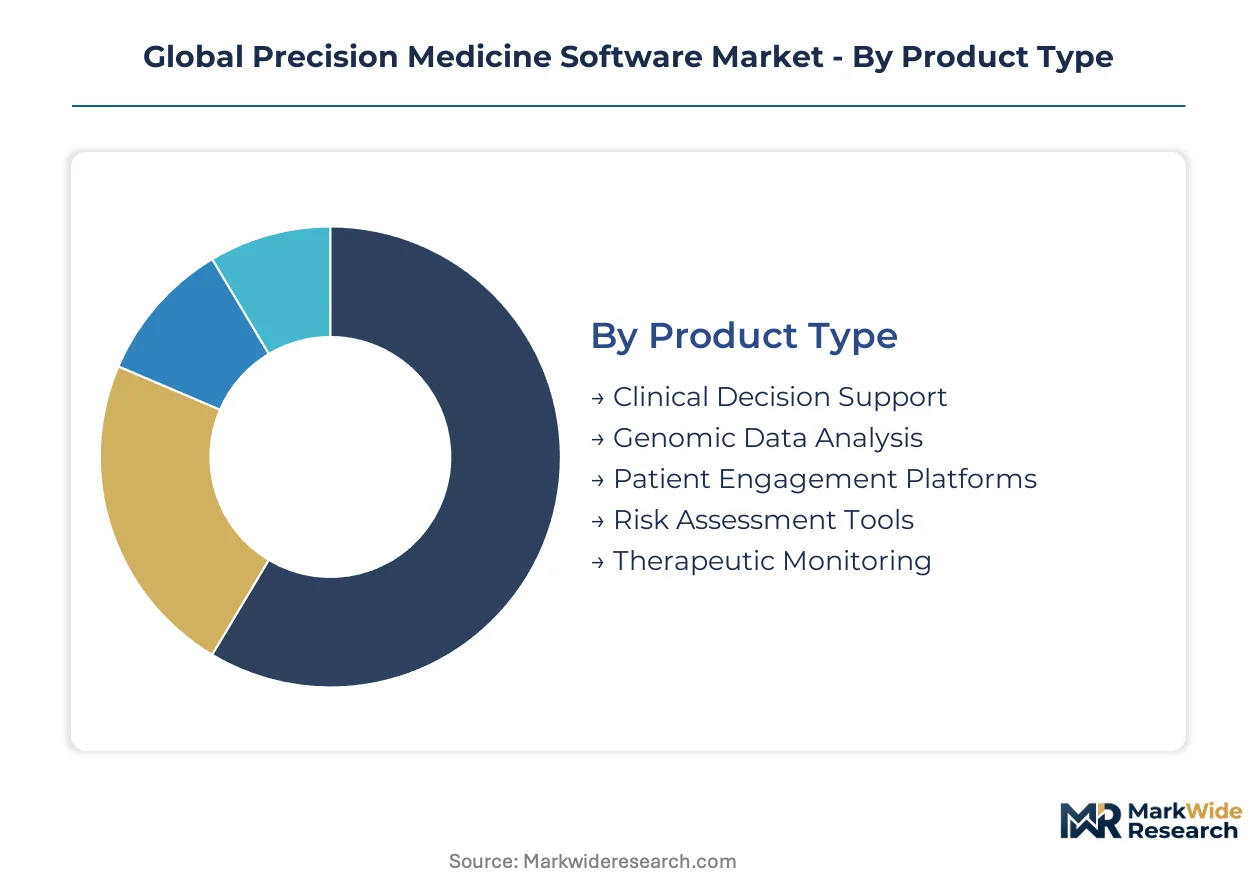
Market segmentation provides a granular view of the Global Precision Medicine Software Market, dissecting it into distinct categories based on functional attributes, application areas, user types, and deployment models. This analysis reveals the specific demand drivers and technological preferences shaping competitive dynamics across various market verticals.
Product Type:
Purchasing decisions for precision medicine software often center on the specific functional capabilities required by clinical and research teams to address complex biological data challenges.
- Genomic Data Analysis:These platforms process raw next-generation sequencing data to identify genetic variants, copy number alterations, and structural changes. Demand concentrates in large academic medical centers in the United States, driven by extensive research initiatives.
- Clinical Decision Support:Clinical decision support tools integrate patient data, genomic insights, and medical guidelines to provide actionable recommendations at the point of care. Biopharma companies utilize these systems to stratify patients for targeted clinical trials.
- Patient Engagement Platforms:Patient engagement platforms facilitate communication, data collection, and education between providers and individuals receiving precision therapies.
- Risk Assessment Tools:Risk assessment tools leverage genetic and clinical data to predict disease susceptibility and inform preventive strategies for individuals.
- Therapeutic Monitoring:Therapeutic monitoring software tracks patient response to targeted treatments, often integrating biomarker data to optimize clinical outcomes.
Volume sits with Genomic Data Analysis; growth tilts toward Clinical Decision Support.
Application:
The utility of precision medicine software is primarily defined by its specific therapeutic or diagnostic focus within healthcare.
- Oncology:Oncology applications involve software for identifying actionable mutations, guiding targeted cancer therapies, and monitoring treatment response. This segment dominates the market due to the high volume of targeted cancer treatments globally.
- Pharmacogenomics:Pharmacogenomics integrates genetic information to predict individual drug responses and optimize medication dosages. Expansion into this area beyond oncology represents a significant opportunity to broaden clinical utility across Europe.
- Rare Diseases:Software for rare diseases supports diagnosis, patient stratification, and therapeutic development for conditions with limited treatment options.
- Personalized Immunotherapy:Personalized immunotherapy applications focus on tailoring immune-based treatments by analyzing tumor genomics and patient immune profiles.
- Chronic Condition Management:Software for chronic condition management uses precision data to personalize treatment plans and monitor long-term health outcomes for diseases like diabetes or cardiovascular conditions.
The segment for Oncology holds the largest share, while Pharmacogenomics exhibits the steepest expansion trajectory.
End User:
The adoption of precision medicine software varies significantly based on the operational scale and specific data needs of different healthcare entities.
- Biopharma Companies:Biopharma companies leverage these platforms for drug discovery, development, and patient stratification in clinical trials. These organizations represent a key end-user segment for accelerating drug development timelines.
- Academic Medical Centers:Academic medical centers utilize precision medicine software for large-scale research projects, genomic data management, and integrating advanced analytics into patient care. They are primary adopters, especially in the United States.
- Diagnostic Laboratories:Diagnostic laboratories employ the software for processing next-generation sequencing data and generating clinical reports for actionable insights.
- Health Insurers:Health insurers use precision medicine software for risk stratification, treatment efficacy evaluation, and developing value-based care models.
- Genetic Counseling Services:Genetic counseling services utilize these platforms to interpret complex genetic data and communicate findings to patients.
Demand from Biopharma Companies accounts for the majority of installations, with Diagnostic Laboratories demonstrating increasing strategic importance.
Deployment:
Infrastructure considerations and data security requirements critically influence the choice of deployment models for precision medicine software.
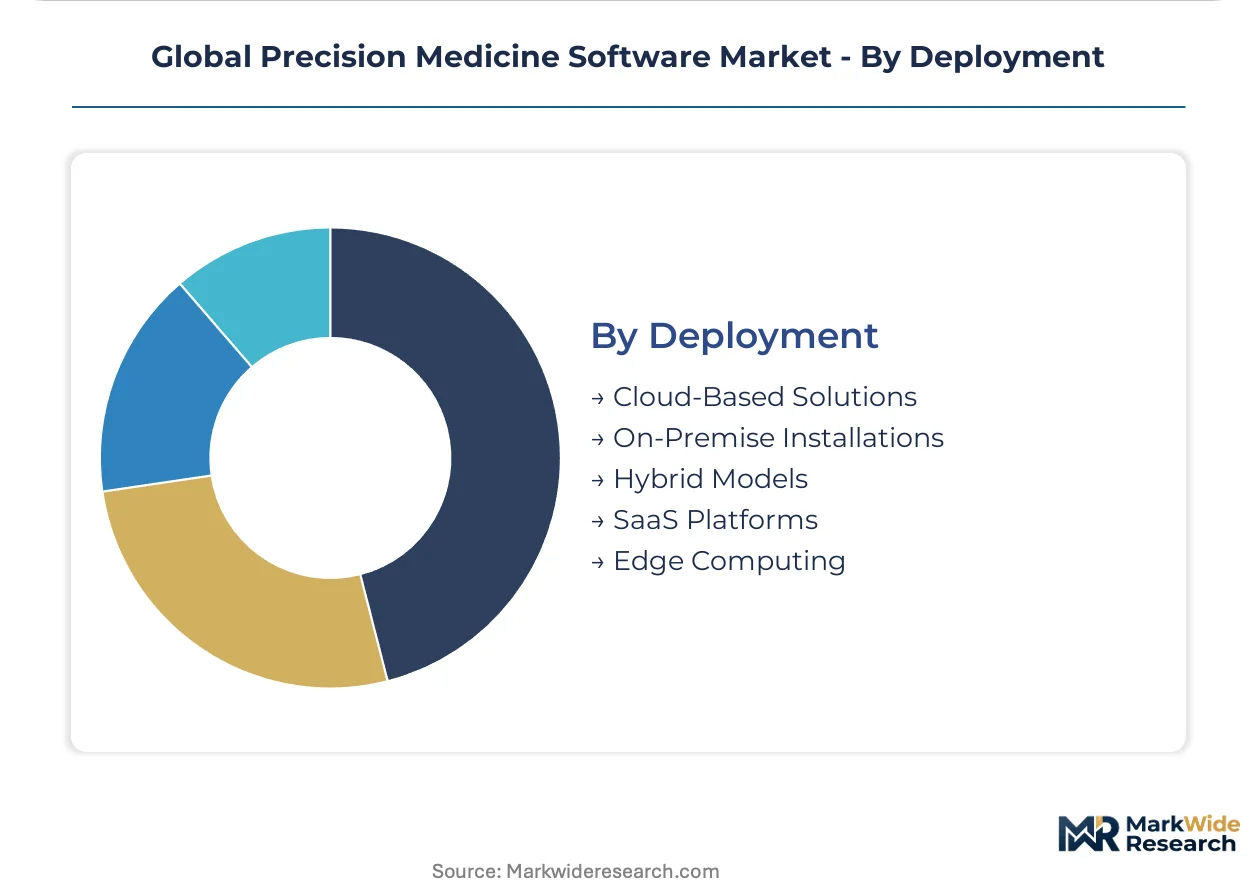
- Cloud-Based Solutions:Cloud-based platforms offer scalable, on-demand computational power necessary for processing immense genomic datasets and collaborative research. Large academic medical centers are primary adopters seeking to manage data from large-scale sequencing projects.
- SaaS Platforms:Software-as-a-Service (SaaS) platforms provide subscription-based access to precision medicine tools, reducing upfront IT investment and simplifying maintenance. This model appeals to smaller research hubs and diagnostic labs in Europe.
- On-Premise Installations:On-premise installations provide maximum control over data security and customization, preferred by institutions with strict data governance policies.
- Hybrid Models:Hybrid models combine the flexibility of cloud resources with the security of on-premise infrastructure, balancing data control and scalability.
- Edge Computing:Edge computing solutions process data closer to its source, enabling real-time analysis and reducing latency for critical clinical applications.
The market currently leans towards Cloud-Based Solutions for scalability, but Hybrid Models are gaining traction for data governance flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biopharma corridor and academic medical centers drive significant demand for precision medicine software, particularly for genomic data analysis and clinical decision support. This robust ecosystem fosters innovation in personalized therapies and advanced diagnostics. The concentration of research institutions and pharmaceutical companies makes it a global hub for software adoption.
United States
Demand for precision medicine software in the United States stems from extensive genomic research initiatives and the presence of major biopharma companies. The FDA oversees software as a medical device (SaMD), ensuring rigorous validation for clinical use. Academic medical centers in cities like Boston and San Francisco actively integrate these platforms for large-scale sequencing projects and patient stratification.
Germany
Germany demonstrates strong demand for precision medicine software, especially within its advanced pharmaceutical sector and academic research institutions. Europe's Medical Device Regulation (MDR) imposes stringent requirements on clinical validation for decision support software. Biopharma clusters in regions like Bavaria and North Rhine-Westphalia leverage these tools for targeted therapy development.
China
China's large-scale population health initiatives and expanding healthcare infrastructure are stimulating significant demand for precision medicine software. The NMPA regulates medical software, influencing market entry and product development. Major technology hubs in cities like Shanghai and Beijing are developing localized solutions for genomic data management and analysis.
India
India's burgeoning biopharmaceutical industry and increasing investment in healthcare technology are fueling precision medicine software adoption. The CDSCO governs medical device regulations, including software, within the country. Research centers in cities such as Hyderabad and Bengaluru are exploring pharmacogenomics applications and developing cost-effective diagnostic tools.
Global Precision Medicine Software Market Key Industry Players
Premium-margin players sit above commodity-margin players across the depth of integrated genomic and clinical decision support. The market exhibits a tiered structure, with comprehensive platform providers differentiating from basic data management tools. Strategic archetypes include integrated solution providers, specialized data analytics firms, and clinical workflow integrators. Companies are primarily focused on strategic partnerships to enhance interoperability and portfolio diversification to capture new application areas.
Specialists in advanced analytics and data integration, such as IQVIA and IBM Corporation, exemplify the premium-tier offerings by leveraging large-scale data assets and artificial intelligence capabilities for complex genomic analysis. IQVIA differentiates through its focus on integrating clinical trial data with real-world evidence, providing a comprehensive view for patient stratification. IBM Corporation, with its Watson Health AI, delivers advanced analytics for identifying actionable insights from diverse datasets. These entities primarily serve biopharma companies and large academic medical centers, offering platforms crucial for drug discovery and personalized treatment development. Their strategies often involve deepening interoperability with existing healthcare systems and expanding their functional modules to address evolving clinical needs across various therapeutic areas.
| Leading Market Players |
|---|
| IQVIA |
| Syapse |
| IBM Corporation |
| GenomOncology |
| Fabric Genomics |
| Cerner Corporation |
| SOPHiA GENETICS |
| Human Longevity |
| Koninklijke Philips N.V. |
| Others |
Cost & Logistics Intelligence
Vertical integration of genomic data analysis capabilities anchors the supply position for premium precision medicine software providers, directly influencing their pricing power in specialized market segments. This integration allows for greater control over data quality and analytical depth.
Pricing Analysis
Value-based pricing tied to clinical outcomes and diagnostic accuracy drives premium software sales within precision medicine. The dominant pricing model is subscription-based SaaS, often tiered by user count or data volume. Price differentiation stems from the level of AI integration for complex genomic interpretation and the depth of clinical validation (e.g., FDA clearance). Pricing softness runs through basic data management tools due to increased competition. Smaller hospitals exhibit higher price sensitivity compared to large biopharma companies.
Supply Chain Analysis
Reverse data flows, including continuous model retraining and feedback loops from clinical applications, are crucial for software refinement and compliance. The supply of specialized bioinformatics talent and advanced AI development concentrates in the United States, Germany, and China. Key dependencies include access to large, diverse genomic datasets and high-performance cloud infrastructure. A structural risk is the scarcity of hybrid computational biology expertise. Distribution runs primarily through direct sales teams and strategic partnerships with Electronic Health Record vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioinformatics talent scarcity and the complexity of data interoperability represent significant capacity bottlenecks propping up pricing in the precision medicine software market.
For Market Incumbents: Anticipate continued regulatory evolution, particularly concerning software as a medical device (SaMD) in Europe, necessitating sustained investment in clinical validation. Deepen integration with existing Electronic Health Record (EHR) systems to counter new entrant platforms offering specialized AI analytics. Acquire niche AI and federated learning startups to expand capabilities and mitigate competitive threats.
For New Entrants and Emerging Players: Enter via specialized modules focusing on underpenetrated areas like pharmacogenomics beyond oncology, or rare disease diagnostics. Target smaller research hubs and diagnostic labs in Europe with flexible Software-as-a-Service (SaaS) models. A compelling go-to-market angle involves offering open-source integration capabilities to enhance platform interoperability with diverse systems.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized data analytics firms and clinical decision support providers with robust AI capabilities. The long-term viability for integrated precision medicine platforms remains strong over the next decade. Monitor the adoption rate of universal data exchange standards across healthcare systems as a key inflection indicator for market scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Seamless integration with Electronic Health Record systems enhances clinical workflow adoption and data utility. |
| Strategic Partnership | Collaborations with cloud providers or diagnostic labs expand market reach and data access. |
| Product Launch | Introducing specialized modules for pharmacogenomics broadens clinical utility beyond oncology. |
| Acquisition of Specialist Firm | Acquiring AI-driven analytics startups strengthens competitive advantage in genomic interpretation. |
| Geographic Expansion | Penetrating emerging markets like China and India unlocks new large-volume user bases. |
Research Approach
Independent corroboration across industry whitepapers, regulatory filings, and academic publications underwrites the qualitative findings of this study. The research combines extensive primary interviews with biopharma R&D heads, academic medical center CIOs, and diagnostic lab directors, complemented by secondary validation from sources like FDA filings, EMA submissions, and clinical trial databases. This approach ensures bottom-up and top-down triangulation.
The rate-of-change decomposition framing guided the quantitative analysis across the analysis window, modeling market growth based on product type, application, end-user, deployment model, and regional regulatory landscapes. Compound annual growth rates were derived from historical trends and projected market drivers, incorporating inputs such as global genomic sequencing volumes and targeted therapy approval rates. This framework ensures robust market sizing.
Revisions become necessary when major regulatory shifts, unexpected technological breakthroughs, or significant changes in healthcare funding materialize. Forecasts reflect assumptions regarding the continued expansion of targeted therapies and the integration of AI into clinical workflows. Practitioners should monitor global data privacy regulations and the pace of bioinformatics talent development for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Health Care Quality Management Software Market
Health Data Management
North America Healthcare Analytics Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Population Health Management (PHM) Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
US Population Health Management Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Healthcare Data Interoperability Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
United States Healthcare Big Data Analytics Market
Health Data Management
Global Healthcare Fraud Analytics Market