
 Master Data Management in Healthcare Market | 2026-2036
Master Data Management in Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Master Data Management in Healthcare Market Insights
ISO 27001 certification for healthcare data security is rotating as a baseline gate for vendor participation in enterprise procurement cycles. IBM leverages its long-standing healthcare analytics footprint to sustain multi-hospital data federation contracts across North American systems. Cerner anchors its competitive position through deep EHR integration capabilities that dominate hospital IT environments. Profisee differentiates via cloud-native master data hub architectures that compete directly with legacy on-premises installations.
Master Data Management in Healthcare encompasses the systematic creation, governance, and synchronization of core data entities—patients, providers, medications, and facilities—across disparate clinical and administrative systems, typically operating through persistent identifier resolution engines and real-time API orchestration layers to ensure single-source-of-truth accuracy for care coordination and billing integrity. Data Governance solutions command the deepest margin pools as pharmaceutical companies and insurers face escalating audit scrutiny over data lineage and provenance. Cloud-Based deployment is displacing on-premises infrastructure fastest among mid-size hospital networks seeking to defer capital expenditure while scaling interoperability. The Master Data Hub segment occupies a maturing position in large integrated delivery networks that have already consolidated core record systems and now prioritize maintenance over expansion.
The ONC Cures Act Final Rule and HIPAA together shape vendor product roadmaps by mandating standardized APIs and patient-directed data portability, forcing MDM platforms to embed FHIR-native connectivity as a default architecture requirement rather than optional module. FDA guidance on real-world evidence data quality further tightens provenance standards for pharmaceutical companies deploying MDM to harmonize clinical trial and post-market surveillance datasets. Stakeholders must weigh interoperability mandates against the operational drag of legacy system migration when selecting deployment architectures.
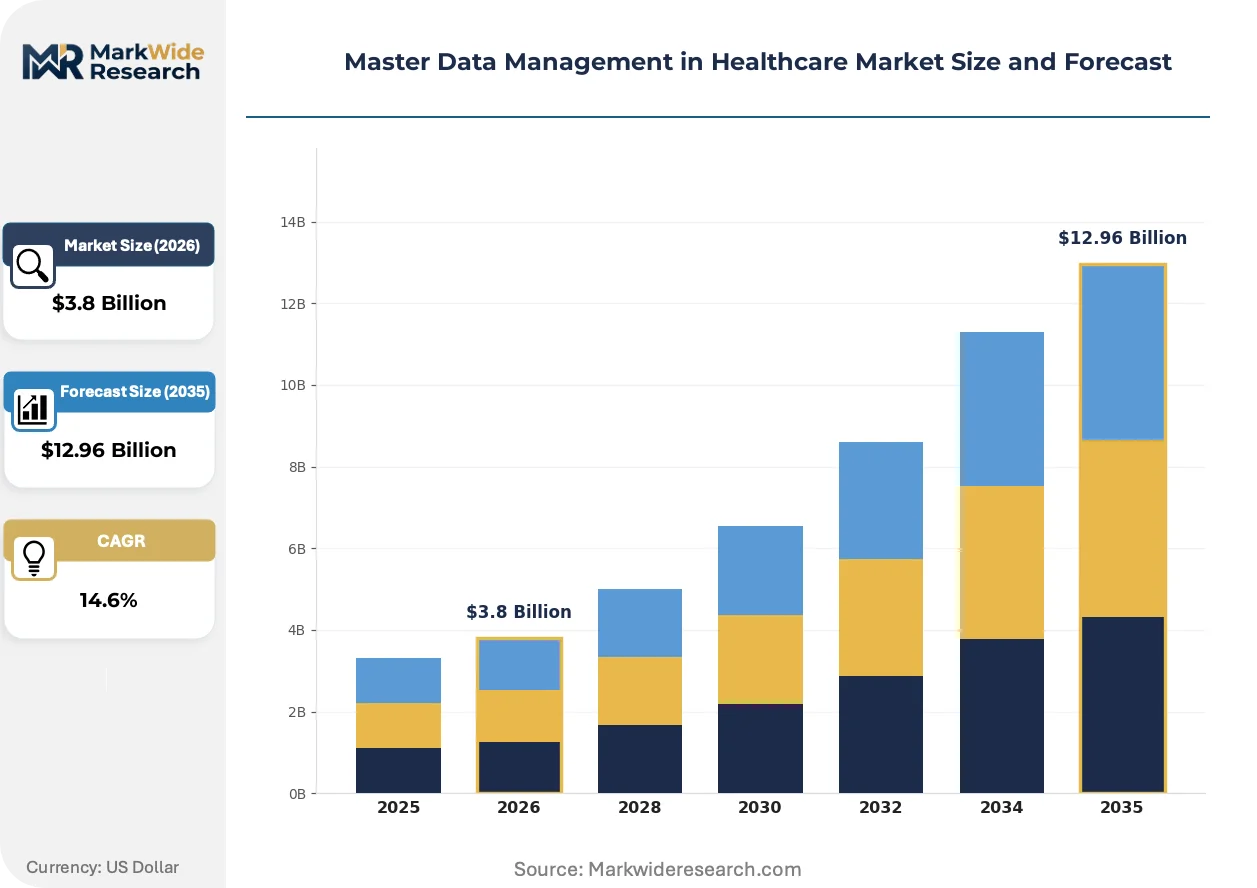
Market Dynamics
The ONC Cures Act Final Rule is compressing vendor product cycles by mandating FHIR-native interoperability as a baseline architecture requirement, forcing legacy MDM platforms to reengineer their integration layers or cede procurement cycles to cloud-native competitors.
Growth Catalysts
- Hospital Future Act funding:Germany's federal digitization grants are channeling capital toward centralized data governance infrastructure, accelerating procurement of cloud-based master data platforms across hospital networks.
- FHIR API standardization:The interoperability mandate is eliminating proprietary data silos, creating procurement pull for vendors offering native FHIR-compliant integration layers.
- ISO 27001 certification gating:Enterprise healthcare buyers are rotating data security certification into mandatory RFP criteria, filtering vendor participation and consolidating procurement around qualified suppliers.
Market Restraints
- Legacy EHR migration drag:Deep Cerner and Epic installations create technical debt that slows MDM platform replacement cycles and extends sales-to-implementation timelines.
- Specialized FHIR engineering scarcity:Healthcare IT labor markets face acute shortages of developers capable of building and maintaining FHIR-native orchestration layers.
- HIPAA compliance friction:Cloud migration of protected health information triggers extended legal review cycles that stall procurement decisions.
Strategic Opportunities
- Pharmaceutical real-world evidence harmonization:FDA guidance on post-market surveillance data quality is creating demand for MDM platforms capable of unifying clinical trial and observational datasets.
- Mid-size hospital cloud bypass:Networks with 200-500 beds are deferring capital expenditure by adopting subscription-based master data hubs rather than on-premises infrastructure.
- AI-readiness infrastructure:Machine learning deployment in clinical decision support requires clean, unified master data, positioning MDM as prerequisite infrastructure for predictive analytics adoption.
Industry Challenges
- Multi-source identifier resolution complexity:Reconciling patient records across fragmented EHR systems requires probabilistic matching algorithms that generate false positives, eroding clinical trust in unified records.
- Data provenance audit readiness:Pharmaceutical and insurer customers demand granular lineage tracking that many legacy MDM architectures cannot provide without expensive reengineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Master Data Management in Healthcare Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Integration, Data Governance, Data Quality, Master Data Hub End User: Hospitals, Clinics, Insurers, Pharmaceutical Companies Deployment: On-Premises, Cloud-Based, Hybrid, Open Source Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Merative, Accenture, Semarchy, Cerner, GE Healthcare, Ataccama, Cognizant, IBM, Profisee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Master Data Management in Healthcare Market Trends and Innovations
Cloud-native master data hub architectures are decomposing the traditional on-premise software license model, compressing implementation timelines and shifting revenue recognition patterns across the vendor base.
FHIR-native API orchestration is decomposing point-to-point integration architectures that previously dominated hospital IT environments. Mid-size hospital networks in the United States are adopting these platforms fastest, seeking to unify patient records without the capital intensity of legacy data federation projects. The structural consequence is collapsing maintenance revenue for incumbent vendors while expanding recurring subscription pools for cloud-native competitors.
The EU AI Act's risk classification framework for clinical decision support systems is tightening data quality requirements for algorithm training datasets. Pharmaceutical companies deploying MDM to harmonize multi-source clinical data must now embed technical documentation and human oversight protocols into their governance workflows. Germany and France represent the most advanced implementation environments, with national health data access bodies interpreting compliance obligations.
Subscription-based procurement is displacing perpetual license purchases among hospital networks seeking to align MDM expenditure with operational budgets. Health system CFOs are prioritizing opex-friendly contracts that bundle implementation, maintenance, and scaling capacity into predictable annual payments. This pattern concentrates most visibly in the United States, where nonprofit hospital systems face margin pressure from labor cost inflation and are deferring large capital commitments.
Master Data Management in Healthcare Market Segmentation
Healthcare MDM procurement patterns diverge sharply by organizational scale and regulatory exposure, with pharmaceutical companies prioritizing provenance-heavy governance tools while hospital networks favor cloud-based deployment models that defer capital commitment.
Product Type:
Margin pools concentrate most densely in governance and quality modules where audit scrutiny from FDA and EMA creates pricing power for vendors demonstrating lineage capabilities.
- Data Governance:Encompasses policy frameworks, stewardship workflows, and metadata management that enforce regulatory compliance across distributed clinical datasets. Pharmaceutical companies in Germany and the United States are channeling procurement toward solutions with embedded technical documentation protocols mandated by the EU AI Act and FDA real-world evidence guidance.
- Data Quality:Delivers profiling, cleansing, and monitoring functions that ensure patient record accuracy for billing integrity and care coordination. Hospital networks facing ONC Cures Act interoperability deadlines are prioritizing quality modules that automate FHIR-native validation rules.
- Data Integration:Provides ETL pipelines and API orchestration layers connecting fragmented EHR systems.
- Master Data Hub:Centralizes persistent identifier resolution and golden record management for enterprise-scale deployments.
The dominant share belongs to Data Governance, while Data Quality is closing the gap fastest.
End User:
Volume concentration tracks directly to IT budget scale, with integrated hospital systems representing the deepest implementation pipelines and pharmaceutical companies showing the steepest expansion trajectory for real-world evidence harmonization.
- Hospitals:Span academic medical centers, community hospitals, and specialty facilities requiring patient-provider-facility master data unification. German hospital networks are deploying Hospital Future Act funding toward centralized governance infrastructure that consolidates records across previously siloed departmental systems.
- Pharmaceutical Companies:Deploy MDM to harmonize clinical trial, post-market surveillance, and observational datasets for regulatory submission. FDA guidance on data quality standards is compressing vendor selection cycles around platforms with native provenance tracking.
- Clinics:Outpatient and ambulatory settings with lighter IT infrastructure needs.
- Insurers:Payers requiring member-provider relationship mapping for claims accuracy and network management.
Hospitals command the installed base, though pharmaceutical companies are gaining share fastest as real-world evidence requirements tighten.
Deployment:
Cost tier stratification separates capital-intensive on-premises installations from subscription models that align expenditure with operational budgets.
- Cloud-Based:Delivers multi-tenant or dedicated instance architectures with API-first integration layers. Mid-size United States hospital networks with 200-500 beds are bypassing on-premises infrastructure entirely, deferring capital expenditure while scaling interoperability through subscription contracts.
- Hybrid:Combines on-premises persistence for sensitive records with cloud orchestration for analytics workloads. Large integrated delivery networks are adopting hybrid architectures to satisfy HIPAA compliance review cycles while capturing cloud scalability for non-PHI processing.
- On-Premises:Legacy perpetual-license deployments concentrated in Epic and Cerner-dominated environments with deep technical debt.
- Open Source:Community-supported frameworks with commercial support overlays for cost-constrained implementations.
Cloud-Based holds the procurement momentum, with Hybrid architectures expanding most quickly among risk-averse enterprise buyers.
Service Type:
Maturity curves vary by customer sophistication, with implementation services dominating initial deployments and support contracts driving recurring revenue in stabilized accounts.
- Implementation:Encompasses system configuration, data migration, and integration engineering that translates procurement into operational capability. FHIR engineering scarcity is elongating implementation timelines and inflating day-rate premiums for certified specialists.
- Consulting:Delivers data strategy, governance program design, and organizational change management. Pharmaceutical companies are engaging consulting services to architect provenance workflows that satisfy FDA audit protocols for real-world evidence submissions.
- Support:Ongoing technical maintenance, patch management, and incident response.
- Training:Knowledge transfer for stewardship, administration, and end-user adoption.
Implementation services capture the largest project value, while Consulting is climbing the fastest as regulatory complexity deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital networks and pharmaceutical companies concentrate procurement in economies with mature digitization funding and stringent interoperability mandates. Buyer archetypes split between integrated delivery systems seeking cloud-native consolidation and life sciences firms requiring audit-grade data provenance.
United States
Mid-size hospital networks with 200-500 beds are bypassing on-premises infrastructure entirely, adopting subscription-based master data hubs to defer capital expenditure. The ONC Cures Act Final Rule mandates FHIR-native interoperability, compressing vendor product cycles and filtering procurement toward qualified suppliers. The Boston-Cambridge corridor anchors pharmaceutical real-world evidence harmonization demand as FDA guidance tightens post-market surveillance standards.
Germany
Hospital digitization funds from the Hospital Future Act are channeling capital toward centralized data governance infrastructure across previously siloed departmental systems. The EU AI Act's risk classification framework for clinical decision support systems tightens data quality requirements for algorithm training datasets. The Rhine-Ruhr metropolitan region concentrates procurement activity as academic medical centers consolidate core record systems.
United Kingdom
NHS trusts are prioritizing cloud-based deployment models that align expenditure with operational budgets amid sustained margin pressure. GDPR compliance requirements extend legal review cycles for cloud migration of protected health information, stalling procurement decisions. London anchors health technology procurement clusters where integrated care systems seek unified patient records across fragmented provider networks.
India
Hospital networks in metropolitan corridors are accelerating digitization investments as CDSCO regulatory frameworks mature for clinical data management. The country's national pharmaceutical regulator is tightening documentation standards for multi-source clinical trial data harmonization. The Mumbai-Pune and Bengaluru-Hyderabad corridors concentrate vendor implementation services as healthcare IT labor markets expand.
Japan
Integrated delivery networks are adopting hybrid architectures to satisfy domestic data residency requirements while capturing cloud scalability for non-PHI processing. METI industrial policy is channeling investment toward AI-readiness infrastructure that requires clean, unified master data as prerequisite. The Tokyo-Osaka corridor dominates procurement volume as large hospital systems prioritize maintenance over expansion of core record systems.
Master Data Management in Healthcare Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with established healthcare analytics footprints alongside cloud-native specialists competing on implementation velocity. Market structure exhibits tiered consolidation around EHR-integrated incumbents and API-first challengers. Strategic archetypes include legacy platform defenders with deep Cerner-Epic integration capabilities, cloud-native disruptors offering subscription-based master data hubs, and consulting-heavy systems integrators bundling implementation with governance advisory. Dominant competitive moves center on FHIR engineering talent acquisition and ISO 27001 certification achievement to satisfy mandatory RFP criteria.
Within the diversified technology tier, IBM leverages long-standing healthcare analytics positioning to sustain multi-hospital data federation contracts, while Accenture and Cognizant occupy consulting-intensive implementation roles that elongate project timelines but deepen account penetration. Cloud-native specialists including Profisee and Ataccama exemplify the API-first challenger archetype, competing directly with legacy on-premises installations through compressed implementation timelines. Cerner anchors the EHR-integrated incumbent position through deep hospital IT environment dominance, whereas Semarchy represents European-origin governance-focused alternatives gaining traction among pharmaceutical provenance requirements.
| Leading Market Players |
|---|
| Merative |
| Accenture |
| Semarchy |
| Cerner |
| GE Healthcare |
| Ataccama |
| Cognizant |
| IBM |
| Profisee |
| Others |
Pricing and Supply Chain Analysis
Cloud-native platform scale economies among mid-size hospital networks in the United States are compressing implementation timelines and establishing new price floors that legacy on-premise vendors struggle to match without structural cost restructuring. This concentration of procurement momentum around subscription architectures is simultaneously reshaping supplier tiering and buyer negotiation leverage across the vendor base.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate enterprise healthcare procurement, though subscription-based SaaS tiers are displacing perpetual licenses fastest among hospital networks seeking opex alignment. Price differentiation hinges on ISO 27001 certification status and FHIR-native integration depth, with uncertified vendors facing exclusion from mandatory RFP shortlists. Pricing pressure stems from cloud-native competitors offering compressed implementation timelines at lower total cost of ownership. Mid-size hospital networks with 200-500 beds exhibit highest price sensitivity, while pharmaceutical companies prioritize provenance capabilities over cost minimization.
Supply Chain Analysis
Inbound logistics costs for cloud infrastructure hardware face intermittent pressure from port congestion at Long Beach and Rotterdam, though software-delivery models minimize physical supply chain exposure. Engineering talent supply concentrates in India, the United States, and Germany, with FHIR-specialized developers commanding premium day rates. Raw material dependencies center on hyperscaler compute capacity, API gateway licensing, and cybersecurity audit services. Single-source vulnerability rests with concentrated hyperscaler availability zones. Distribution runs through direct enterprise sales teams supplemented by systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
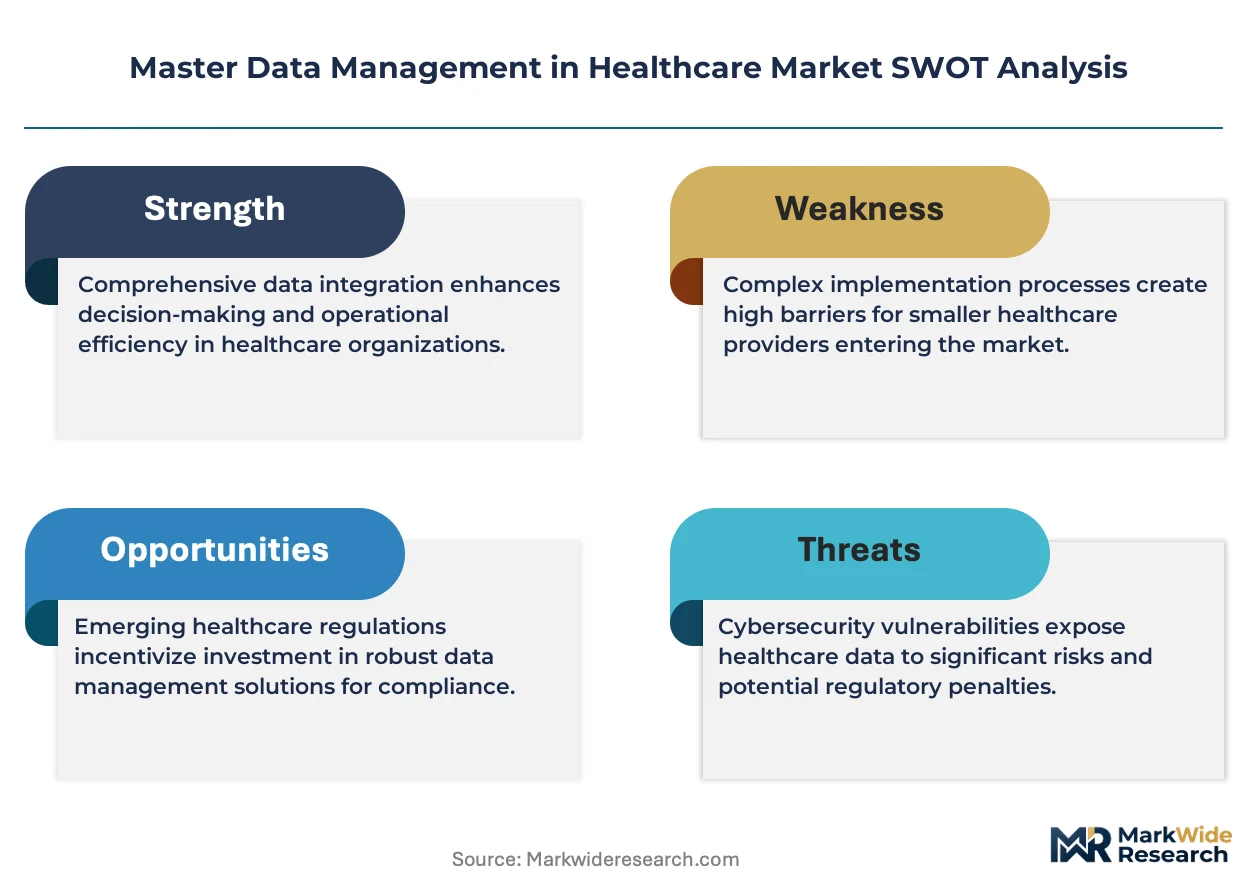
Master Data Management in Healthcare operates as a defensive-moat market where regulatory entrenchment through FHIR compliance mandates and deep EHR integration creates structural switching costs that protect incumbent positions. Network effects from patient record unification across hospital networks further reinforce competitive stickiness.
For Market Incumbents: Fortify defensive positioning by accelerating FHIR engineering talent acquisition ahead of procurement cycle compression, and deepen Cerner-Epic integration layers to extend technical debt advantages against cloud-native challengers. ISO 27001 certification maintenance represents a non-negotiable table stake as enterprise RFPs harden security requirements. For New Entrants and Emerging Players: Differentiate on implementation velocity by targeting mid-size United States hospital networks with 200-500 beds that bypass on-premises infrastructure entirely. Pharmaceutical real-world evidence harmonization offers penetrable white space where legacy provenance architectures require expensive reengineering. Go-to-market success demands native FHIR API orchestration bundled with predictable subscription pricing. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cloud-native platform vendors with established hospital network subscriptions, positioning these archetypes for durable cash flow quality across extended holding periods. Acquisition targets should demonstrate embedded FHIR compliance and expanding annual contract value. The signal to watch is ONC enforcement activity around interoperability deadlines as procurement acceleration trigger.| Strategic Initiative | Industry Significance |
|---|---|
| FHIR-Native Platform Development | ONC Cures Act mandates render proprietary integration layers non-competitive in hospital procurement cycles. |
| ISO 27001 Certification Investment | Enterprise healthcare buyers now rotate data security certification into mandatory RFP gate criteria. |
| Cloud Infrastructure Partnership | Hyperscaler alliances enable mid-size hospital networks to defer capital expenditure while scaling interoperability. |
| Pharmaceutical Provenance Module Launch | FDA real-world evidence guidance tightens audit requirements that legacy MDM architectures cannot satisfy. |
| Implementation Services Expansion | FHIR engineering scarcity elongates project timelines and inflates margins for certified specialist capabilities. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with hospital CIOs, pharmaceutical data governance directors, health system procurement managers, and FHIR integration specialists. Secondary validation drew from ONC regulatory filings, CMS Medicare reimbursement databases, hospital GPO contract repositories, and vendor SEC disclosures. Bottom-up hospital network deployment estimates were triangulated against top-down pharmaceutical IT spending benchmarks.
Across the analysis window, the forecasting framework modeled segmentation dimensions including deployment architecture, organizational scale tier, regulatory exposure intensity, and end-user vertical. CAGRs were derived from weighted average procurement cycle velocities and replacement rate assumptions. Industry-specific inputs incorporated Hospital Future Act funding disbursement patterns and FDA real-world evidence guidance implementation timelines.
Decision-makers should treat outputs as directional under assumptions of sustained interoperability mandate enforcement and stable hyperscaler pricing; material deviation would warrant model refresh. Forecasts reflect base-case assumptions around FHIR adoption curves and cloud migration velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Healthcare Data Integration Market
Health Data Management
Global Healthcare Customer Data Platform Market
Health Data Management
Big Data Healthcare Market
Health Data Management
Wireless Healthcare Asset Management Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Global Healthcare Quality Management Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Point of Care (POC) Data Management Systems Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Healthcare Archiving and Ediscovery Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Healthcare Data Annotation Tools Market
Health Data Management
Medical Record Management System Market
Health Data Management
Population Health Management (PHM) Market