
 North America Healthcare Analytics Market | 2026-2036
North America Healthcare Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Healthcare Analytics Market Outlook
The CMS Hospital Readmissions Reduction Program is pivoting reimbursement structures toward outcomes accountability, forcing health systems to invest in predictive risk stratification tools. IBM Corporation leverages its Watson Health infrastructure to anchor clinical decision support contracts with major academic medical centers. Oracle Corporation sustains competitive positioning through its Cerner acquisition, integrating electronic health record data streams with enterprise analytics clouds.
Healthcare analytics encompasses the systematic computational analysis of clinical, financial, and operational data generated across care delivery organizations, employing statistical algorithms, machine learning models, and natural language processing to extract actionable intelligence from structured and unstructured health records. Predictive analytics leads segment value contribution as health systems prioritize readmission forecasting and sepsis early-warning systems, while prescriptive analytics represents the fastest-expanding category as hospitals deploy real-time optimization engines for emergency department throughput and surgical scheduling. Cloud-based solutions dominate technology deployment, though on-premise installations persist among organizations with stringent data residency requirements.
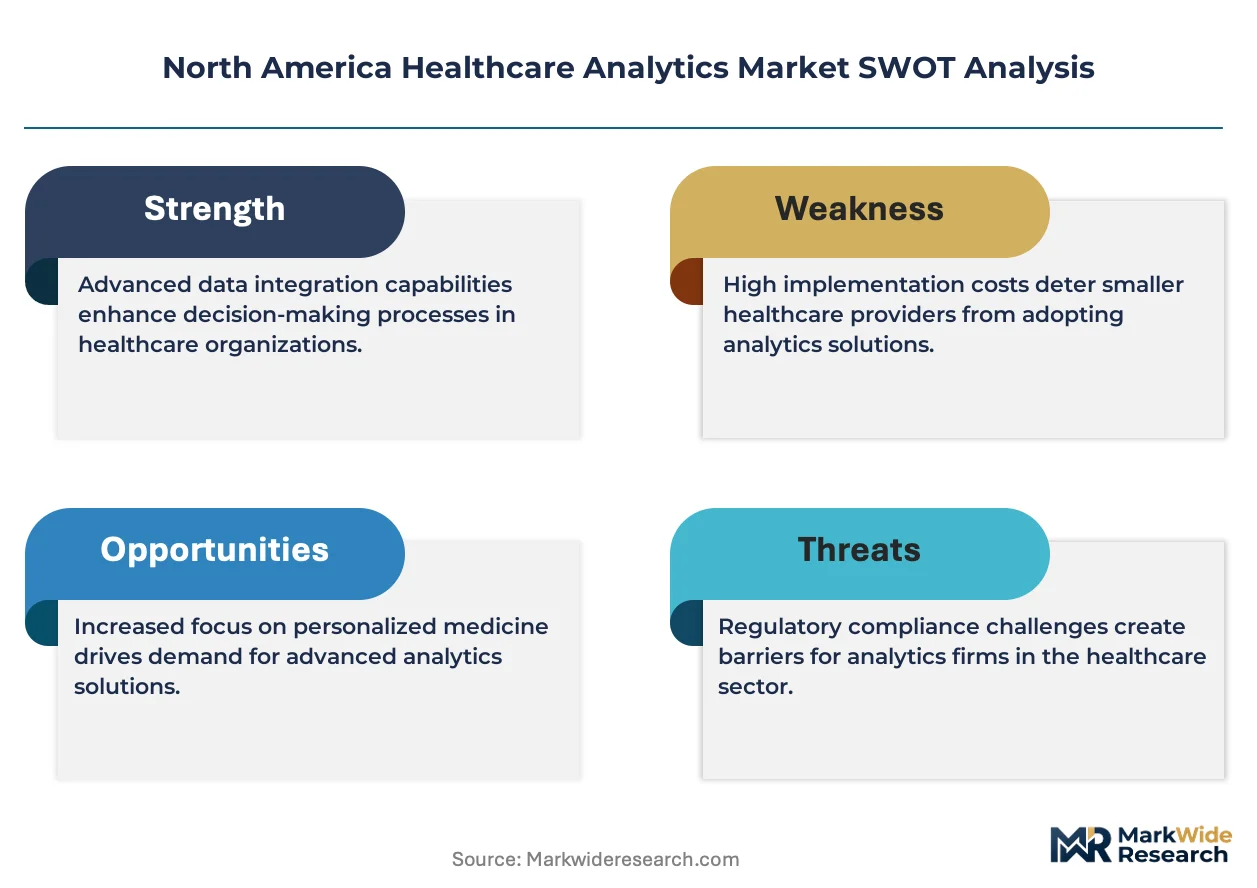
The Office of the National Coordinator for Health IT enforces interoperability standards through the 21st Century Cures Act information blocking provisions, while HIPAA security rules shape vendor data architecture requirements across the United States and Canada. FDA guidance on artificial intelligence and machine learning-based software as a medical device introduces premarket validation expectations that filter vendor eligibility for clinical analytics applications. Stakeholders must monitor evolving state-level privacy legislation in California, Virginia, and Colorado that creates compliance fragmentation beyond federal baseline requirements.
Market Dynamics
CMS value-based reimbursement penalties are forcing US health systems to deploy predictive risk stratification tools at scale, compressing procurement cycles from eighteen months to under six for readmission forecasting platforms.
Growth Catalysts
- Hospital Readmissions Reduction Program:CMS penalties reaching 3% of base DRG payments are compelling integrated delivery networks to invest in real-time patient risk scoring infrastructure.
- Sepsis early-warning algorithms:Clinical decision support mandates in California and New York are driving deployment of machine learning models that process vital sign streams from bedside monitors.
- Cloud migration:Ontario health clusters are consolidating data lakes across regional hospitals, eliminating on-premise server maintenance burdens while enabling cross-facility population health analytics.
Market Restraints
- Interoperability fragmentation:The 21st Century Cures Act information blocking provisions create compliance complexity as vendors retrofit legacy EHR connectors to meet ONC certification timelines.
- Data residency requirements:Provincial privacy statutes in Quebec and British Columbia mandate Canadian-sovereign cloud infrastructure, limiting vendor pool for multi-jurisdictional health systems.
- Algorithmic bias validation:FDA premarket expectations for AI/ML-based software as medical devices extend development cycles, particularly for sepsis prediction tools targeting diverse patient populations.
Strategic Opportunities
- Behavioral health integration:Untapped demand exists for analytics platforms that correlate social determinants data with emergency department utilization patterns in Medicaid expansion states.
- Real-time surgical optimization:Prescriptive analytics engines for block scheduling and turnover management represent white space as ambulatory surgery centers scale across Texas and Florida.
- Canada Health Infoway standards:Federal interoperability investment creates procurement tailwind for vendors aligning with Pan-Canadian Health Data Standards for cross-provincial analytics.
Industry Challenges
- Clinical informatics talent scarcity:Health systems compete for data scientists with dual competency in biostatistics and HIPAA-compliant architecture, particularly in secondary markets.
- Legacy EHR integration friction:Custom API development for older Cerner and Epic instances consumes 40% of implementation timelines, delaying value realization.
- State privacy law fragmentation:Divergent requirements across California CPRA, Virginia CDPA, and Colorado CPA force vendors to maintain multiple data governance frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Healthcare Analytics Market |
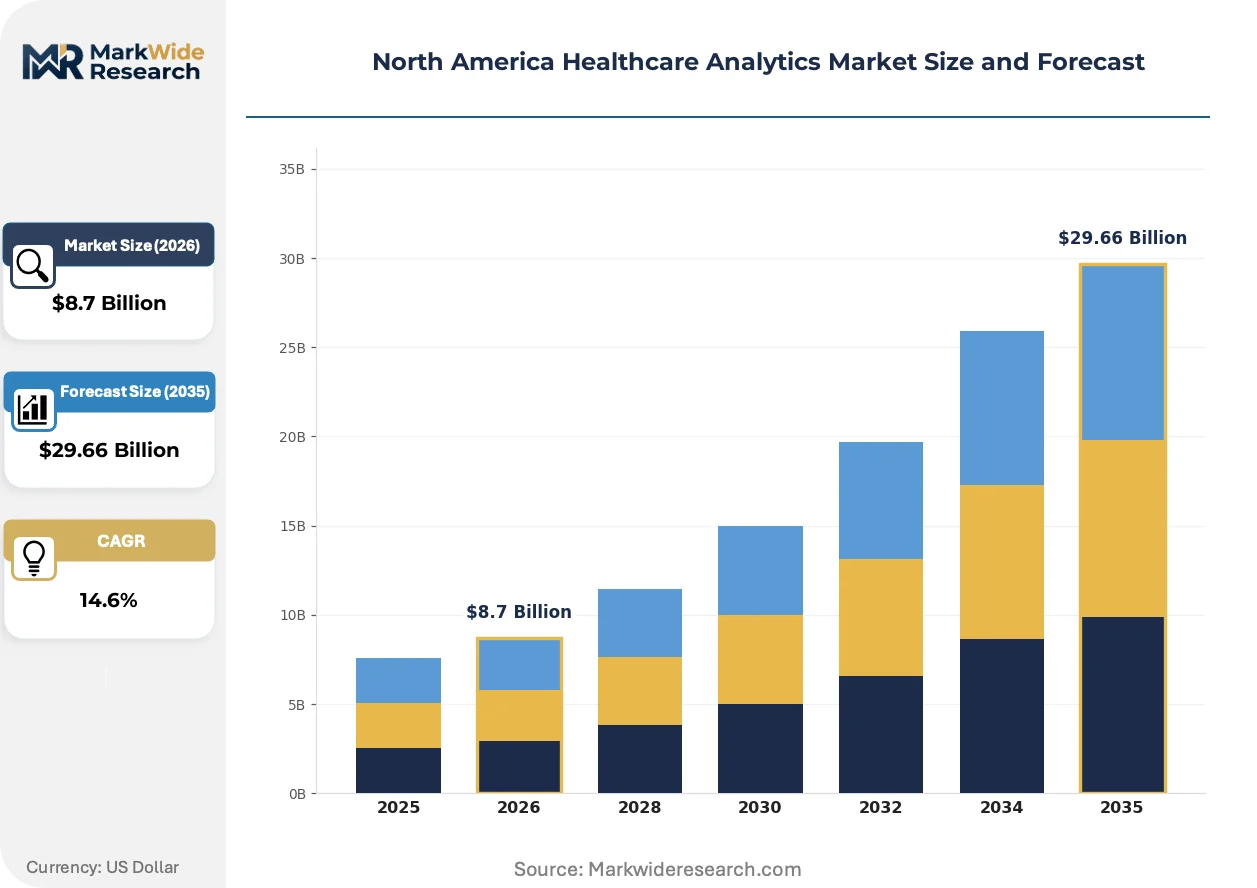
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Descriptive Analytics, Predictive Analytics, Prescriptive Analytics, Real-time Analytics End User: Hospitals, Clinics, Insurance Providers, Research Organizations Application: Clinical Data Analysis, Financial Analytics, Operational Analytics, Patient Engagement Technology: Cloud-based Solutions, On-premise Solutions, Artificial Intelligence, Machine Learning |
| Companies Covered | IBM Corporation, Oracle Corporation, McKesson Corporation, Optum, Inc., Cerner Corporation, SAS Institute, Inc., Allscripts Healthcare Solutions, IQVIA Holdings, Inc., Verisk Analytics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Healthcare Analytics Market Strategic Shifts
Federated learning architectures are reshaping how sensitive clinical data moves across organizational boundaries, enabling multi-site model training without centralizing protected health information. Natural language processing pipelines now extract structured insights from unstructured clinical notes at scale.
Natural language processing engines processing unstructured clinical documentation are electrifying retrospective cohort identification for quality improvement initiatives. Academic medical centers in Massachusetts and Pennsylvania are deploying these tools to automate registry abstraction, compressing chart review timelines from weeks to hours. The technology is electrifying competitive positioning for vendors that bundle NLP with existing EHR contracts.
The FDA's evolving guidance on predetermined change control plans for AI/ML-based software as medical device is tightening premarket submission requirements for clinical analytics vendors. Manufacturers must now document anticipated algorithm modifications and validation protocols before commercialization, raising barriers for early-stage entrants. Sepsis prediction tools face particular scrutiny given their direct patient impact and deployment across diverse hospital environments.
Subscription-based pricing for analytics modules is displacing perpetual license models as health systems prioritize operational expenditure flexibility. Integrated delivery networks in California and Ontario are negotiating outcome-tied contracts where vendor fees scale with demonstrated readmission reduction performance. This shift is most visible among safety-net hospitals managing thin operating margins under value-based care contracts.
North America Healthcare Analytics Market Segmentation
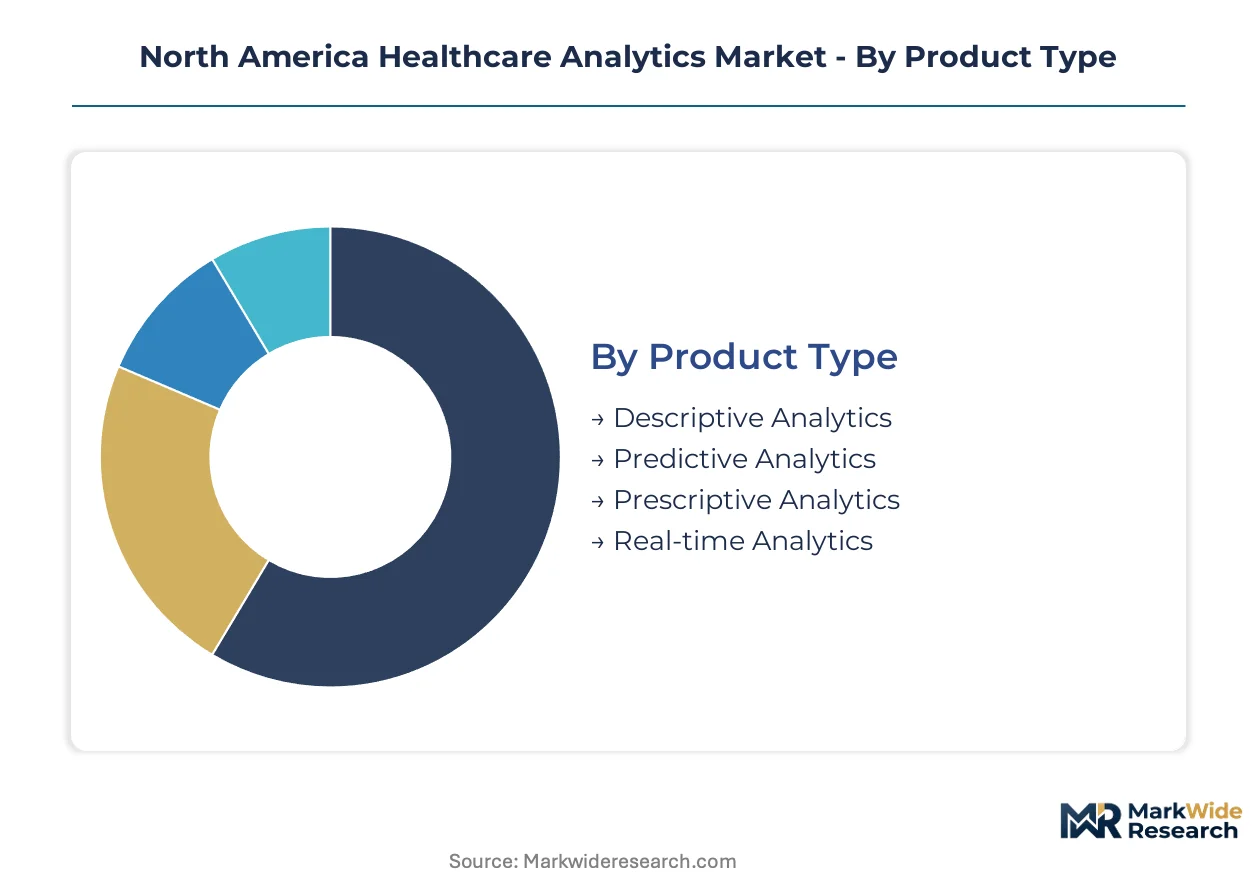
Healthcare analytics procurement in North America follows distinct technical and operational pathways, with product capabilities and deployment models determining vendor selection criteria across integrated delivery networks and independent facilities.
Product Type:
Supply concentration among academic medical centers and large health systems favors platforms with advanced algorithmic capabilities, compressing vendor margins for basic reporting tools while elevating premium positioning for predictive and prescriptive suites.
- Descriptive Analytics:Retrospective dashboards and historical trend reports aggregate EHR, claims, and operational data into standardized visualizations for quality reporting and regulatory submission. Demand concentrates among smaller community hospitals in Texas and Florida that lack dedicated data science teams but face mandatory CMS reporting deadlines.
- Predictive Analytics:Machine learning models forecast patient risk trajectories, readmission probabilities, and disease progression patterns from longitudinal clinical records. Health systems across California and Ontario prioritize these tools to reduce CMS penalties and optimize resource allocation across emergency departments.
- Prescriptive Analytics:Optimization engines recommend specific clinical and operational interventions based on real-time data streams and constraint modeling.
- Real-time Analytics:Continuous processing of bedside monitor feeds and streaming EHR updates enables immediate clinical alerts and workflow triggers.
Today's leader: Predictive Analytics. Tomorrow's challenger: Prescriptive Analytics.
End User:
Procurement authority varies sharply by organization scale, with capital availability and IT infrastructure maturity determining whether deployments target enterprise transformation or point-solution automation.
- Hospitals:Inpatient facilities with 200+ beds drive enterprise analytics adoption, deploying integrated platforms across clinical, financial, and operational domains. Integrated delivery networks in Ontario and California negotiate multi-year contracts spanning dozens of facilities, consolidating data lakes to enable cross-hospital population health management.
- Clinics:Ambulatory settings and physician practices prioritize lightweight, EHR-embedded modules for quality measurement and patient panel management.
- Insurance Providers:Payers deploy analytics for risk adjustment, fraud detection, and network performance optimization across member populations.
- Research Organizations:Academic medical centers and contract research organizations leverage analytics for cohort identification, trial matching, and real-world evidence generation.
Hospital procurement dominates current revenue, though insurance provider spending is climbing fastest as Medicare Advantage plans expand risk-bearing contracts.
Application:
Margin structures diverge by use case complexity, with clinical applications commanding premium pricing due to FDA validation requirements while operational tools compete on implementation speed.
- Clinical Data Analysis:Algorithms process structured and unstructured clinical records to support diagnosis, treatment selection, and outcomes measurement. Academic medical centers in Massachusetts and Pennsylvania deploy natural language processing pipelines to automate registry abstraction and compress research timelines from weeks to hours.
- Financial Analytics:Revenue cycle optimization, cost accounting, and value-based contract performance management tools address thinning margins under CMS reimbursement pressure.
- Operational Analytics:Emergency department throughput, surgical scheduling, and supply chain optimization engines target efficiency gains.
- Patient Engagement:Analytics-driven outreach, risk stratification for care management, and personalized communication platforms address Medicaid expansion populations.
Clinical Data Analysis anchors current spending, while Patient Engagement represents the steepest expansion trajectory as social determinants integration becomes reimbursable.
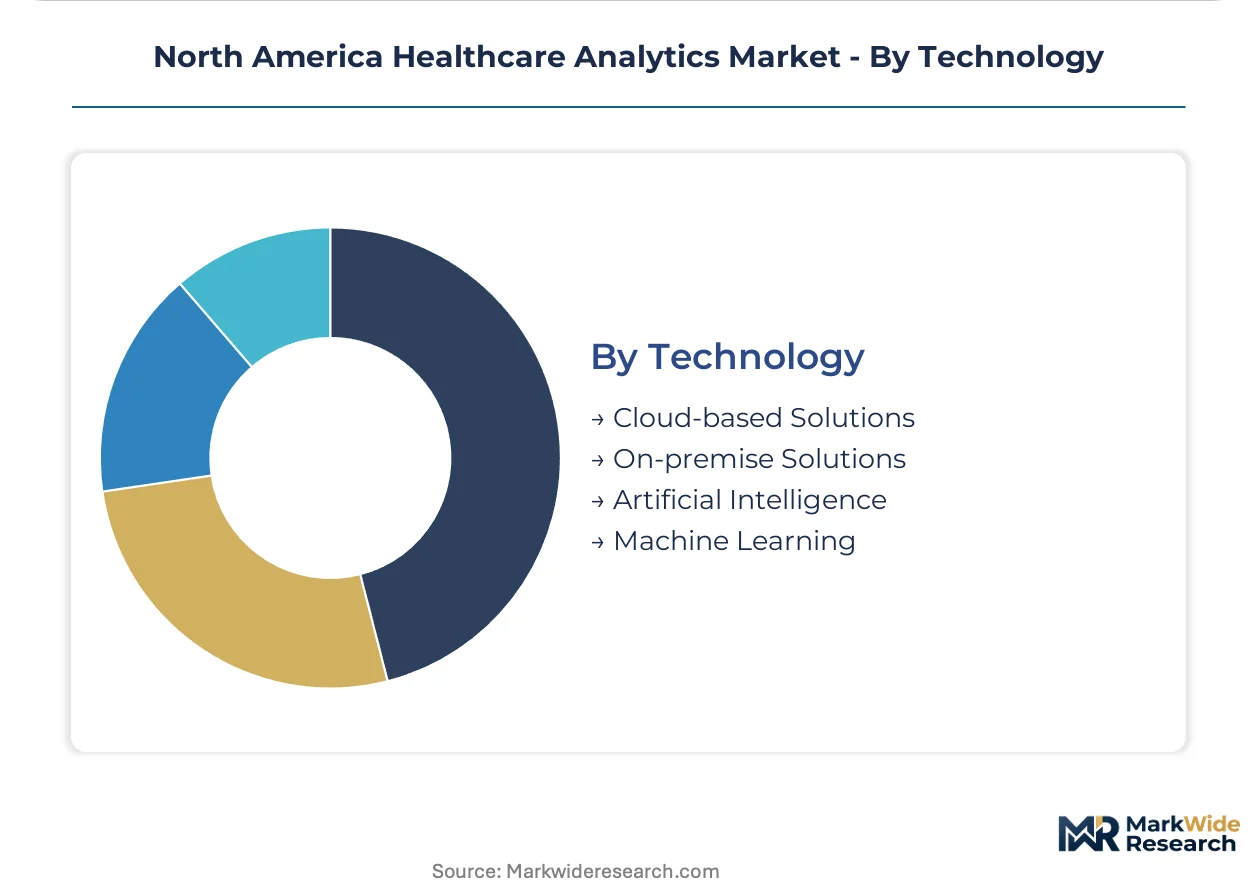
Technology:
Deployment architecture decisions reflect data residency constraints, legacy system integration burdens, and computational intensity requirements for real-time clinical applications.
- Cloud-based Solutions:Scalable infrastructure eliminates capital expenditure for server maintenance while enabling cross-facility data sharing and rapid model deployment. Ontario health clusters consolidate regional data lakes across hospitals, leveraging cloud elasticity for population health analytics without on-premise hardware investments.
- On-premise Solutions:Local server installations persist where provincial privacy statutes in Quebec and British Columbia mandate Canadian-sovereign data storage.
- Artificial Intelligence:Deep learning architectures for imaging analysis, clinical documentation, and predictive modeling face FDA premarket validation requirements.
- Machine Learning:Supervised and unsupervised algorithms for risk stratification, anomaly detection, and pattern recognition deploy across cloud and edge environments.
Cloud-based Solutions command the installed base, though AI deployments are gaining share fastest as FDA guidance clarifies validation pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The healthcare analytics industry traces its commercial roots to the United States, where early adoption of electronic health records in the 1990s created the data infrastructure for subsequent analytical applications. Academic medical centers in Boston and the Bay Area pioneered clinical decision support systems before regulatory mandates accelerated nationwide deployment. This historical foundation established North America as the primary laboratory for value-based care analytics.
United States
Federal reimbursement penalties under the CMS Hospital Readmissions Reduction Program drive predictive analytics procurement across integrated delivery networks. The Office of the National Coordinator for Health IT enforces interoperability standards through 21st Century Cures Act information blocking provisions. Health systems in California and New York deploy sepsis early-warning algorithms to meet state clinical decision support mandates.
Canada
Provincial health authorities consolidate regional data lakes to enable cross-facility population health management without on-premise infrastructure burdens. Federal investment through Canada Health Infoway establishes Pan-Canadian Health Data Standards for interoperability. Ontario health clusters lead cloud migration, while Quebec and British Columbia maintain Canadian-sovereign data residency requirements.
Mexico
Private hospital networks in Mexico City and Monterrey adopt operational analytics for emergency department throughput optimization. The national pharmaceutical regulator shapes data governance expectations for clinical software deployments. Medical tourism hubs in Guadalajara integrate analytics platforms to compete with US facilities on outcomes transparency.
North America Healthcare Analytics Market Competitive Environment
Capital-heavy infrastructure providers compete with asset-light software specialists across the North American healthcare analytics landscape. The market structure concentrates around three tiers: enterprise platforms serving multi-hospital systems, point-solution vendors targeting specific clinical workflows, and consulting-heavy integrators bridging legacy EHR gaps. Dominant competitive moves include strategic acquisitions to consolidate EHR-data integration capabilities and outcome-based contracting models that tie vendor fees to demonstrated readmission reductions.
Within the enterprise platform tier, IBM Corporation and Oracle Corporation exemplify divergent strategic positions. IBM leverages its Watson Health infrastructure to anchor clinical decision support contracts with major academic medical centers. Oracle sustains competitive positioning through its Cerner acquisition, integrating electronic health record data streams with enterprise analytics clouds. SAS Institute, Inc. occupies a specialized position serving health systems with advanced statistical modeling requirements.
| Leading Market Players |
|---|
| IBM Corporation |
| Oracle Corporation |
| McKesson Corporation |
| Optum, Inc. |
| Cerner Corporation |
| SAS Institute, Inc. |
| Allscripts Healthcare Solutions |
| IQVIA Holdings, Inc. |
| Verisk Analytics, Inc. |
| Others |
Value Chain & Pricing Dynamics
Healthcare IT infrastructure cost indices cascade through vendor pricing tiers, compressing margins for on-premise deployments while elevating subscription premiums for cloud-native platforms serving multi-facility health systems.
Pricing Analysis
Outcome-based subscription contracts dominate enterprise procurement, with fees scaling to demonstrated readmission reduction performance. Price differentiation hinges on FDA validation tier and integration complexity with legacy EHR systems. Cost compression in the mid-market intensifies as safety-net hospitals prioritize operational expenditure flexibility over capital-intensive licensing. Community hospitals in Texas and Florida exhibit highest price sensitivity, while academic medical centers in Massachusetts and California absorb premium positioning for predictive and prescriptive suites.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud providers concentrated in the United States, where AWS, Microsoft Azure, and Google Cloud anchor infrastructure for Ontario health clusters and California integrated delivery networks. Software development draws from engineering talent pools in India, Canada, and Eastern Europe, while specialized clinical informatics expertise remains tethered to Boston and Bay Area academic corridors. Tariff exposure on cross-border data flows threatens multi-jurisdictional deployments. Distribution runs through direct enterprise sales teams and strategic partnerships with EHR vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare analytics procurement functions as a geographic-arbitrage play, with Canadian provincial privacy statutes mandating Canadian-sovereign cloud infrastructure that elevates vendor costs relative to US deployments.
For Market Incumbents: Cement platform stickiness through deeper Cerner and Epic integration, reducing the 40% implementation timeline drain from custom API development. Expand clinical informatics talent pipelines in secondary markets to counter scarcity. Prioritize HIPAA-compliant architecture certifications as defensive moat against emerging AI-native entrants. For New Entrants and Emerging Players: Begin with behavioral health integration in Medicaid expansion states, where social determinants data correlation with emergency department utilization remains underpenetrated. Target ambulatory surgery centers in Texas and Florida for real-time surgical optimization tools. Pursue outcome-tied contracting models to bypass incumbent lock-in at safety-net hospitals. For Investors and Strategic Acquirers: Asymmetric upside sits with verticalized NLP specialists bundling natural language processing with existing EHR contracts. Five-to-ten-year viability favors platforms with validated FDA 510(k) pathways for sepsis prediction tools. Monitor CMS penalty threshold adjustments as inflection indicator for predictive analytics demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Premarket validation for AI/ML-based software as medical device unlocks clinical decision support contracts. |
| Hospital System Partnership | Multi-year enterprise agreements with Ontario health clusters consolidate regional data lake infrastructure. |
| Software Companion Development | EHR-embedded modules for quality measurement address procurement authority in ambulatory settings. |
| Reimbursement Strategy | Alignment with CMS Hospital Readmissions Reduction Program penalties drives predictive analytics adoption. |
| Geographic Expansion | Canadian-sovereign cloud infrastructure satisfies Quebec and British Columbia data residency mandates. |
Study Parameters
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market combining interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and clinical informatics officers alongside secondary validation through CMS Medicare data, hospital procurement databases, FDA 510(k) filings, and Canada Health Infoway standards documentation. Bottom-up facility-level deployment tracking triangulates against top-down vendor revenue analysis.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, modeling segmentation dimensions including analytics type, deployment architecture, end-user scale, and application complexity. CAGRs derive from logistic diffusion curves fitted to EHR penetration rates and value-based reimbursement adoption patterns. Forecast inputs incorporate CMS penalty schedule adjustments and provincial cloud migration timelines.
Several conditions sit outside the modeled scope, including unforeseen regulatory reversals on information blocking enforcement and algorithmic bias litigation outcomes. Forecasts reflect documented assumptions about interoperability standard adoption velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Population Health Management Platforms Market
Health Data Management
Health Care Quality Management Software Market
Health Data Management
US Mobile Health Market
Health Data Management
Population Health Management Solutions Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Global Healthcare Content Management System Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
AI Training Dataset in Healthcare Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Healthcare Predictive Analytics Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market