
 Stroke Telemedicine Services Market | 2026-2036
Stroke Telemedicine Services Market Size, Share, and Industry Trends Forecast 2026-2036
Stroke Telemedicine Services Market Insights
The stroke telemedicine services market is pivoting between premium hub-and-spoke networks with embedded AI decision support and commodity video-only consultation tiers. Teladoc Health sustains broad geographic coverage through its multispecialty platform architecture. American Well differentiates via deep payer partnerships that embed telestroke into value-based care contracts. Eagle Telemedicine anchors its position through hospital-employed neurologist models that guarantee response-time compliance.
Stroke telemedicine services encompass real-time audio-visual consultation, diagnostic image transmission, and clinical decision support systems connecting stroke specialists with remote emergency departments. These systems require sub-15-minute physician response protocols and HIPAA-compliant data encryption to enable timely thrombolytic eligibility assessments. Emergency consultation services command the dominant revenue share due to per-case reimbursement premiums and liability coverage requirements. Wearable devices represent the fastest-expanding technology segment as continuous monitoring extends post-acute stroke surveillance into ambulatory settings.
The Centers for Medicare & Medicaid Services, the Food and Drug Administration, and state-level medical boards collectively govern reimbursement eligibility, software-as-medical-device classifications, and interstate licensure for telestroke practitioners. CMS reimbursement parity mandates shape hospital procurement decisions by determining whether remote neurology consultations qualify for equivalent payment to in-person evaluations. Stakeholders must monitor evolving FDA guidance on AI-assisted stroke detection algorithms and state compact agreements that expand physician practice latitude across jurisdictions.
Market Dynamics
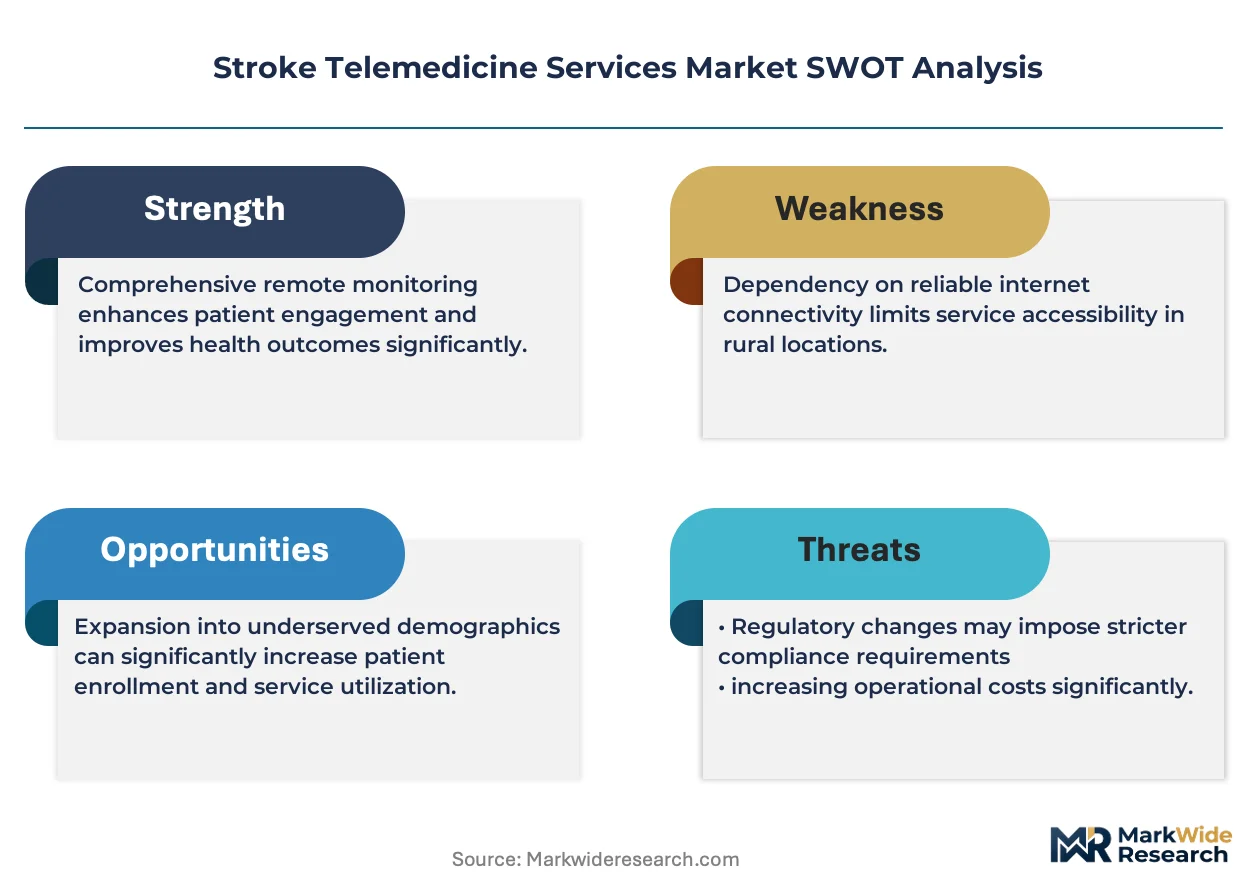
Hospital networks in the United States face CMS reimbursement parity mandates that force rapid telestroke procurement decisions, compressing vendor selection cycles and privileging platforms with embedded AI decision support over standalone video consultation tiers.
Growth Catalysts
- Rural Hospital Closures:Southeastern states have witnessed acute neurology access gaps as community hospitals shutter, creating immediate demand for remote specialist connectivity.
- CMS Reimbursement Parity:Medicare payment equivalence for remote and in-person stroke evaluations removes financial barriers to telestroke adoption across emergency departments.
- AI-Assisted Triage:Machine learning algorithms for hemorrhage detection and large vessel occlusion identification accelerate physician response protocols below the 15-minute threshold.
Market Restraints
- Interstate Licensure Friction:State medical board requirements for multi-jurisdictional practice create administrative burdens that limit neurologist pool availability for 24/7 coverage.
- HIPAA-Compliant Infrastructure Costs:End-to-end encryption, dedicated network circuits, and redundant data centers impose capital requirements that strain independent rural facilities.
- Video-Only Commoditization:Low-cost telehealth platforms without integrated imaging or decision support threaten to erode reimbursement premiums for comprehensive telestroke services.
Strategic Opportunities
- Post-Acute Wearable Integration:Continuous monitoring devices for ambulatory stroke surveillance represent an expansion vector beyond emergency consultation into longitudinal care management.
- Value-Based Care Embedding:Deep payer partnerships that bundle telestroke into total cost-of-care contracts align hospital incentives with reduced readmission metrics.
- State Compact Expansion:Interstate Medical Licensure Compact participation by additional states would unlock cross-border neurologist deployment and reduce staffing costs.
Industry Challenges
- Neurologist Workforce Scarcity:Fellowship-trained vascular neurologists remain concentrated in academic medical centers, complicating recruitment for hub-and-spoke network staffing.
- Legacy EMR Integration:Proprietary telestroke platforms require custom API development to synchronize with diverse hospital electronic medical record systems, extending implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stroke Telemedicine Services Market |
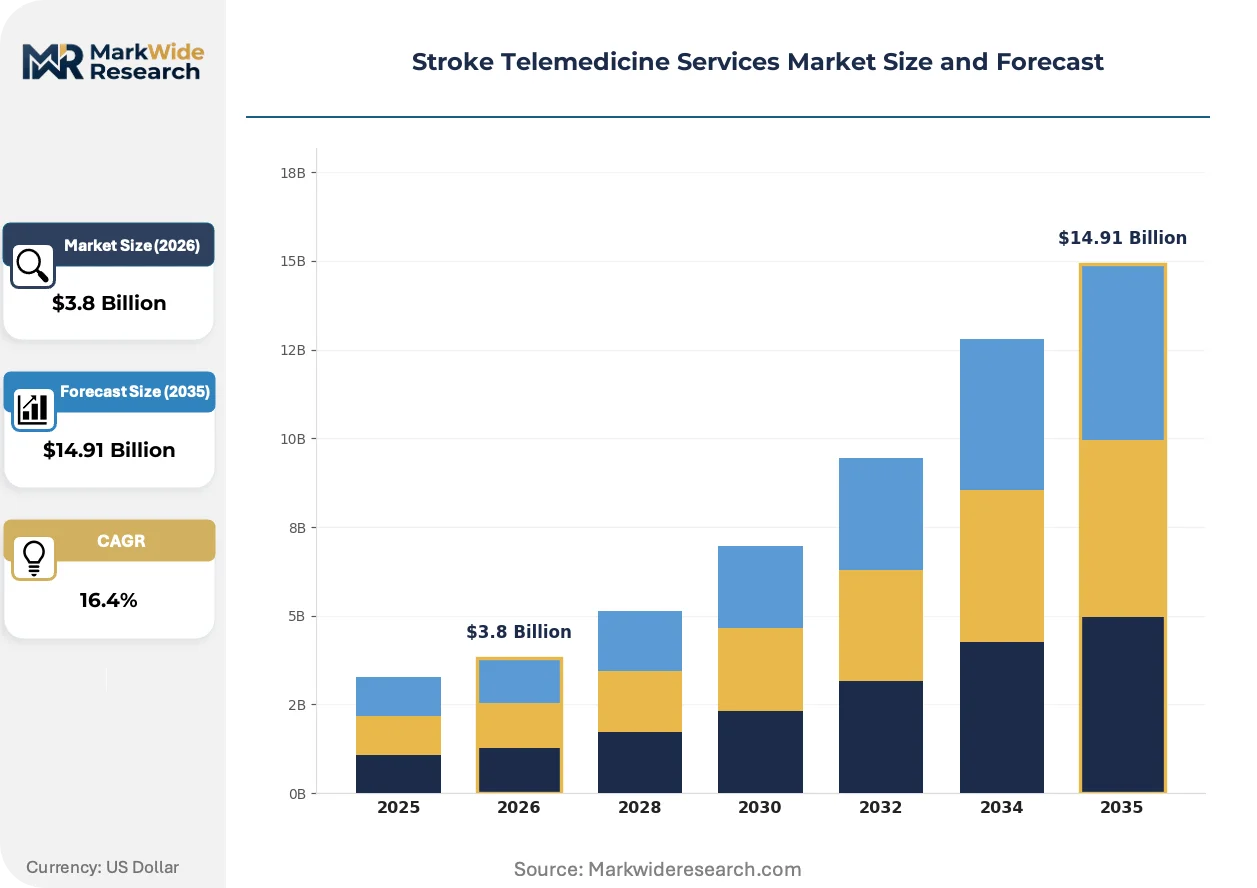
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Emergency Consultation, Remote Monitoring, Patient Education, Follow-Up Care Technology: Web-Based Platforms, Mobile Applications, Video Conferencing, Wearable Devices End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Providers Pricing Model: Subscription-Based, Pay-Per-Use, Tiered Pricing, Bundled Services |
| Companies Covered | Teladoc Health, American Well, Eagle Telemedicine, TeleSpecialists, Sevaro Health, VSee Lab, NeuroCall, Access TeleCare, DispatchHealth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stroke Telemedicine Services Market Trends and Innovations
Telestroke platforms are converging with adjacent acute care technologies, blurring boundaries between emergency neurology, radiology AI, and remote patient monitoring. This integration is compressing vendor categories and reshaping procurement criteria.
AI-powered large vessel occlusion detection is overtaking traditional radiologist-first workflows in comprehensive stroke centers. Emergency departments with embedded algorithms now initiate thrombectomy transfers before specialist video connection, compressing door-to-puncture intervals by eliminating sequential diagnostic steps. This shift privileges platforms with FDA-cleared software-as-medical-device classifications over video-only consultation tiers.
CMS reimbursement reforms for originating site flexibility are expanding telestroke eligibility beyond rural emergency departments to suburban and urban facilities lacking 24/7 neurology coverage. The policy change enables hub hospitals to monetize specialist capacity across broader geographic footprints. Southeastern states with concentrated rural hospital distress are accelerating program launches to capture available reimbursement windows.
Hospital procurement committees now prioritize response-time guarantees and liability coverage over per-case pricing in vendor selection. This behavioral shift favors telestroke providers offering employed neurologist models with contractual compliance metrics over marketplace platforms with variable specialist availability. The preference is most pronounced in hospital networks managing multiple spoke sites under unified risk contracts.
Stroke Telemedicine Services Market Segmentation
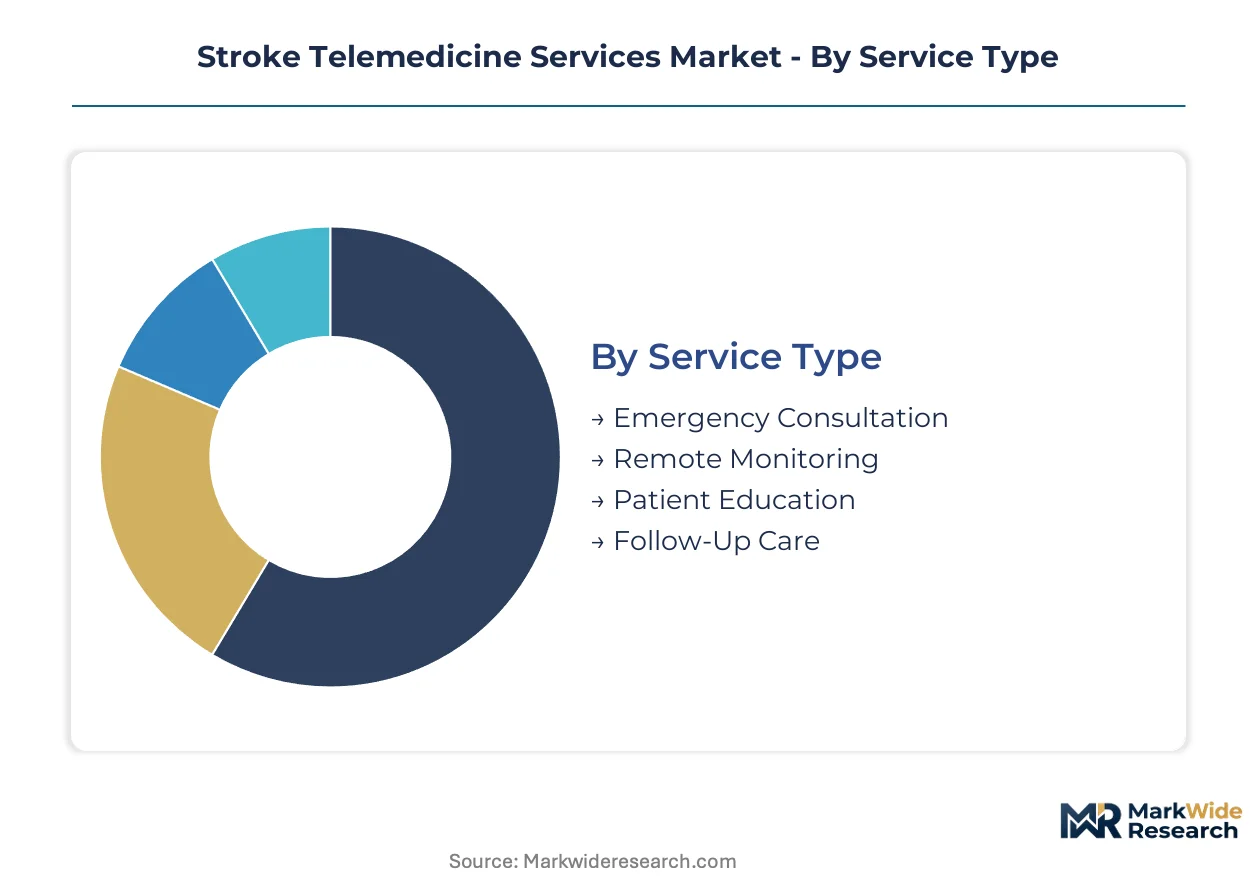
Stroke telemedicine services fragment across service delivery modes, technology stacks, care settings, and commercial structures. Procurement committees evaluate segments against CMS reimbursement eligibility, response-time compliance, and EMR integration requirements.
Service Type:
Supply concentration in emergency consultation services reflects per-case reimbursement premiums and liability coverage mandates that commodity tiers cannot match.
- Emergency Consultation:Real-time audio-visual assessment with sub-15-minute physician response protocols for thrombolytic eligibility determination. Demand concentrates in rural emergency departments across the southeastern United States where neurology access gaps have widened following hospital closures.
- Remote Monitoring:Continuous physiological surveillance via connected devices extending stroke surveillance into ambulatory settings. Post-acute care networks in states with expanding Medicaid managed care contracts are driving procurement for readmission reduction programs.
- Patient Education:Structured modules covering stroke recognition, risk factor modification, and medication adherence delivered through synchronous and asynchronous channels.
- Follow-Up Care:Scheduled specialist consultations for medication titration, rehabilitation coordination, and secondary prevention planning.
Emergency consultation absorbs the bulk of installed capacity; remote monitoring is expanding most quickly.
Technology:
Cost tier differentiation separates enterprise-grade platforms with FDA-cleared AI modules from commodity video infrastructure lacking diagnostic imaging integration.
- Web-Based Platforms:Browser-accessible portals with embedded DICOM viewers and clinical decision support requiring dedicated network circuits and redundant data centers. Hospital networks managing multiple spoke sites under unified risk contracts prioritize these for liability coverage consistency.
- Mobile Applications:Smartphone and tablet interfaces enabling asynchronous specialist review and patient-facing education modules. Rural critical access hospitals with limited IT capital favor lightweight deployment models.
- Video Conferencing:Standalone audiovisual connectivity without integrated imaging or AI triage, facing commoditization pressure from low-cost telehealth entrants.
- Wearable Devices:Continuous monitoring hardware for cardiac rhythm detection, blood pressure surveillance, and activity tracking in post-stroke populations.
Web-based platforms command the highest implementation investment; wearable devices are climbing the fastest as ambulatory surveillance extends longitudinal care management.
End User:
Application intensity varies by care setting complexity, with acute facilities requiring 24/7 coverage guarantees and post-acute settings prioritizing cost efficiency.
- Hospitals:Emergency departments and comprehensive stroke centers requiring hub-and-spoke network connectivity with employed neurologist staffing models. Southeastern states with concentrated rural hospital distress are accelerating program launches to capture CMS reimbursement windows.
- Clinics:Primary care and urgent care facilities seeking episodic specialist access without dedicated neurology employment.
- Rehabilitation Centers:Inpatient and outpatient facilities coordinating recovery protocols with remote physiatry and neurology oversight.
- Home Care Providers:Agencies managing post-discharge surveillance through remote patient monitoring integration.
Hospitals anchor current procurement volume; home care providers are gaining share fastest as value-based contracts extend accountability into community settings.
Pricing Model:
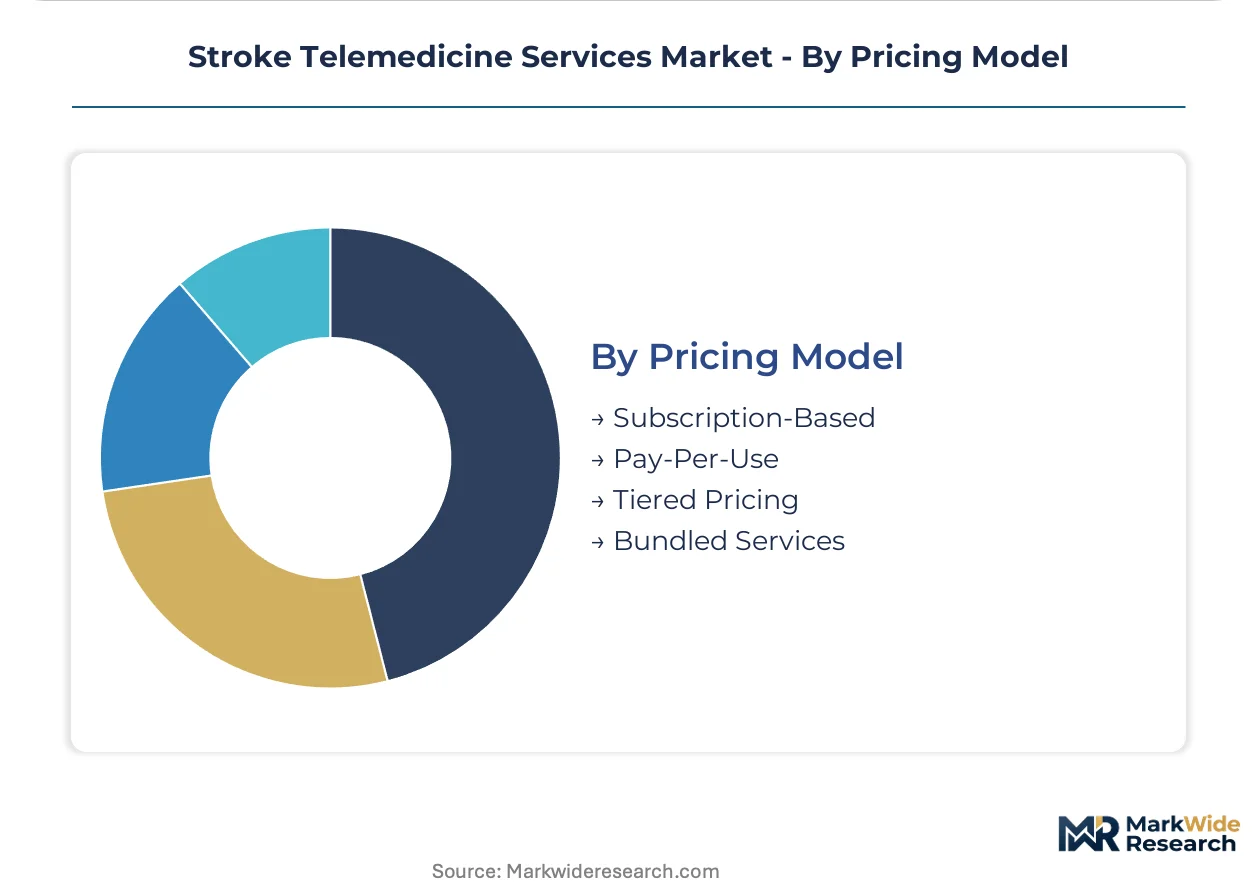
Customer type preferences split between predictable subscription commitments from integrated delivery networks and variable pay-per-use structures suited to independent facilities.
- Subscription-Based:Fixed monthly fees covering unlimited consultations with guaranteed response-time compliance and liability coverage. Payer partnerships embedding telestroke into total cost-of-care contracts favor this structure for budget predictability.
- Pay-Per-Use:Per-consultation fees without minimum commitments, attractive to rural facilities with irregular stroke presentation volumes.
- Tiered Pricing:Differentiated rates by service complexity, response urgency, and specialist credential level.
- Bundled Services:Comprehensive packages combining emergency consultation, remote monitoring, and follow-up care under single contractual frameworks.
Subscription-based models dominate enterprise procurement; bundled services are expanding most quickly as health systems seek unified vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atlanta anchors telestroke network expansion across the southeastern United States, where rural hospital closures have concentrated demand for remote neurology connectivity. Hospital systems in Georgia and surrounding states are deploying hub-and-spoke architectures to capture CMS reimbursement windows for emergency stroke consultations.
United States
Hospital networks across the southeastern United States face acute neurology access gaps following rural facility closures, driving procurement of 24/7 telestroke coverage. CMS reimbursement parity mandates from the Centers for Medicare & Medicaid Services eliminate payment differentials between remote and in-person stroke evaluations. The Atlanta-Charlotte corridor hosts multiple hub hospitals monetizing specialist capacity across broad geographic footprints.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia are consolidating telestroke networks to address regional neurologist shortages in eastern states. The German Medical Association's telemedicine licensing frameworks enable cross-state specialist deployment under unified professional standards. Berlin-Brandenburg health regions are piloting AI-integrated triage protocols to compress door-to-puncture intervals for thrombectomy candidates.
United Kingdom
NHS England's stroke service reconfiguration is centralizing thrombectomy capacity while extending teleconsultation to district hospitals lacking on-site neurology. NICE technology appraisals determine reimbursement eligibility for AI-assisted stroke detection software integrated into emergency workflows. The Greater Manchester and London stroke networks are deploying hub-and-spoke models to meet national 15-minute assessment targets.
Japan
Super-aging prefectures in Tohoku and Hokkaido are adopting telestroke systems to maintain emergency neurology access amid specialist concentration in Tokyo and Osaka. The Ministry of Health, Labour and Welfare's remote medical care fee schedule revisions are expanding reimbursement for emergency specialist consultations. Kyushu region hospitals are integrating mobile stroke units with real-time video connectivity to comprehensive stroke centers.
Australia
Rural and remote hospitals across Queensland and Western Australia rely on telestroke links to metropolitan comprehensive stroke centers in Brisbane and Perth. The Medical Benefits Schedule's telehealth item numbers provide reimbursement parity for remote stroke assessments equivalent to in-person consultations. New South Wales is expanding its statewide telestroke network to cover regional emergency departments previously without neurology coverage.
Stroke Telemedicine Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across response-time guarantee and liability coverage dimensions. Hospital procurement committees now prioritize contractual compliance metrics over per-case pricing, compressing vendor selection cycles toward platforms with embedded AI decision support. Three archetypes dominate: multispecialty telehealth platforms, neurology-specialist providers with employed physician models, and technology vendors supplying imaging-integrated infrastructure. Consolidation through payer partnership embedding and hub-and-spoke network expansion represents the dominant competitive trajectory.
Within the neurology-specialist tier, Teladoc Health, American Well, and Eagle Telemedicine exemplify divergent strategic positioning. Teladoc Health represents the multispecialty platform archetype with broad geographic coverage capabilities. American Well occupies a position tied to deep payer partnerships and value-based care contract integration. Eagle Telemedicine anchors the hospital-employed neurologist model segment with response-time compliance guarantees. Each represents a distinct vector for procurement committee evaluation against CMS reimbursement eligibility and liability coverage requirements.
| Leading Market Players |
|---|
| Teladoc Health |
| American Well |
| Eagle Telemedicine |
| TeleSpecialists |
| Sevaro Health |
| VSee Lab |
| NeuroCall |
| Access TeleCare |
| DispatchHealth |
| Others |
Pricing and Supply Chain Analysis
Captive neurology staffing models anchor both supply security and pricing power in stroke telemedicine, as hospital networks prioritize response-time guarantees over per-case cost minimization. This integration choice insulates premium vendors from commodity video-only competition while concentrating procurement leverage among integrated delivery networks with multi-site coverage mandates.
Pricing Analysis
Value-based pricing tied to door-to-needle time compliance anchors contract structures, with subscription models commanding premiums over pay-per-use alternatives. Price differentiation rests on FDA-cleared AI triage modules and liability coverage depth, not merely audiovisual connectivity. Cost compression in video-only tiers intensifies as low-cost telehealth entrants erode per-consultation reimbursement rates. Rural critical access hospitals exhibit highest price sensitivity, while southeastern hospital networks managing unified risk contracts prioritize compliance guarantees.
Supply Chain Analysis
Fellowship-trained vascular neurologist availability concentrates in academic medical centers across the United States, constraining hub-and-spoke network expansion. Technology sourcing draws from FDA-regulated software developers, HIPAA-compliant cloud infrastructure providers, and DICOM-integrated imaging platform vendors. Single-source vulnerability in AI algorithm licensing creates concentration risk for platforms dependent on third-party stroke detection modules. Distribution runs through direct hospital system contracts with employed physician guarantees, bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates under acute neurologist workforce scarcity, with fellowship pipeline constraints propping pricing for platforms with guaranteed response-time compliance. Supply bottlenecks in specialist recruitment sustain premium tiers against commodity erosion.
For Market Incumbents: To counter video-only commoditization from low-cost telehealth platforms, deepen AI decision support integration and secure exclusive hospital system partnerships with contractual liability coverage. Lock in employed neurologist pools through academic medical center affiliations, preventing competitor access to response-time-guaranteed staffing. For New Entrants and Emerging Players: The premium-economy price-point gap in post-acute wearable monitoring creates white-space opportunity for lightweight remote surveillance platforms targeting home care providers. Penetrate Medicaid managed care networks in southeastern states with readmission reduction value propositions, leveraging asynchronous specialist review to bypass 24/7 staffing requirements. For Investors and Strategic Acquirers: Exit pathways concentrate in payer partnership embedding and hub-and-spoke network rollup transactions. Long-term viability hinges on regulatory capture through FDA software-as-medical-device clearances and CMS reimbursement parity maintenance. Monitor Interstate Medical Licensure Compact expansion as inflection signal for cross-border neurologist deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software-as-Medical-Device Clearance | AI stroke detection algorithms gain reimbursement eligibility under CMS parity mandates. |
| Hospital System Partnership | Multi-site hub-and-spoke contracts lock in response-time compliance and liability coverage. |
| Neurologist Workforce Expansion | Academic medical center affiliations secure specialist pipeline for 24/7 coverage guarantees. |
| Payer Value-Based Contract Embedding | Total cost-of-care alignment reduces readmission penalties and extends reimbursement windows. |
| Post-Acute Wearable Integration | Ambulatory surveillance extends service footprint beyond emergency consultation into longitudinal care. |
Research Methodology
Multi-period observation of CMS reimbursement policy shifts, rural hospital closure patterns, and telestroke program launch timelines anchored the trend analysis, supplemented by interviews with stroke program directors, GPO contracts managers, and telemedicine platform executives. Secondary validation drew from FDA 510(k) clearances, CMS Medicare payment data, state medical board licensure statistics, and hospital procurement database records. Bottom-up installed base estimates triangulated against top-down reimbursement flow projections.
Segment-weighting applied service type, technology stack, and end-user setting dimensions across the modeling period, with emergency consultation and remote monitoring split by AI integration level. CAGRs derived from logistic diffusion curves fitted to telestroke adoption rates in rural versus urban hospital cohorts. Forecast inputs incorporated Interstate Medical Licensure Compact participation trajectories and AI algorithm regulatory approval pipelines.
Inputs from CMS payment rulemaking dockets and state telemedicine legislation trackers were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding reimbursement parity maintenance and specialist workforce growth. Material deviation in FDA AI guidance or compact state participation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telemedicine
Emergency Telemedicine Services Market
Telemedicine
Telehealth Software Market
Telemedicine
Next Generation Telehealth Market
Telemedicine
Telehealth Services Market
Telemedicine
Telemedicine Cart Market
Telemedicine
Asia-Pacific Ehealth Market
Telemedicine
Global Tele Intensive Care Unit Market
Telemedicine
AI in Telemedicine Market
Telemedicine
Remote Healthcare Market
Telemedicine
Real-Time E-Healthcare System Market
Telemedicine
US Telemedicine Market
Telemedicine
5G Telemedicine Platform Market
Telemedicine
Global Healthcare Virtual Assistants Market
Telemedicine
Telemedicine EMR Software Market
Telemedicine
Telemedicine Diagnostic Services Market
Telemedicine
United States Telehealth Pre-Natal Services Market