
 Plastic Resins Market | 2026-2036
Plastic Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Resins Market Intelligence
A shift from single-source to multi-source procurement of specialty resins is expanding to mitigate supply chain vulnerabilities and secure pricing stability. This trend affects both commodity and high-performance segments across the value chain. Dow Inc. leverages its vast production scale to supply commodity resins like polyethylene. In contrast, BASF SE differentiates through its portfolio of engineering plastics for automotive and industrial applications, while SABIC specializes in polycarbonates for the electronics and construction sectors.
Plastic resins are synthetic polymers, typically produced through polymerization of monomers derived from petrochemical feedstocks. These materials, supplied as pellets, granules, or powders, serve as the foundational building blocks for a vast array of plastic products. Polyethylene and Polypropylene dominate global volume, primarily driven by their extensive use in the packaging application segment. Higher-margin growth is concentrated in engineering resins like Polycarbonate, which are critical for durable automotive components and electrical components.
Regulatory frameworks including the EU's REACH directive and ECHA oversight, alongside US EPA rules on chemical substances, define market access and product composition. In China, national GB standards and dual carbon goals are compelling producers to adopt more sustainable manufacturing processes. Consequently, resin producers face a strategic decision regarding investment allocation between virgin petrochemical feedstock capacity and advanced recycling infrastructure.
Market Dynamics
The central structural force shaping the plastic resins market is the conflict between its deep-rooted dependency on petrochemical feedstocks and the intensifying global pressure for a circular economy, driven by regulations like the EU Green Deal.
Growth Catalysts
- Lightweighting Mandates:Demand from the automotive sector for engineering resins to produce lightweight components is rising to meet stringent fuel efficiency standards and support electric vehicle battery range extension.
- Manufacturing Concentration:China's expansive manufacturing base for consumer electronics and appliances creates concentrated, high-volume demand for specific polymers like polycarbonate and ABS.
- Packaging Sector Expansion:The growth of e-commerce and demand for extended food shelf-life propels consumption of commodity resins, particularly polyethylene and polypropylene, for flexible and rigid packaging formats.
Market Restraints
- Feedstock Volatility:Resin production margins are directly exposed to the price volatility of petrochemical feedstocks, such as naphtha and ethylene, which are subject to geopolitical and supply-demand fluctuations.
- Regulatory Fragmentation:Divergent international standards for food-contact plastics and recycled content, including differences between US FDA and European EFSA rules, create compliance complexities and trade barriers.
- Material Substitution:Brand owners in the consumer packaged goods sector are increasingly substituting plastics with paper, glass, and aluminum in packaging to meet corporate sustainability goals and address public perception.
Strategic Opportunities
- Advanced Recycling:Chemical recycling technologies, including pyrolysis and gasification, offer a pathway to convert mixed plastic waste into virgin-quality resins, overcoming the limitations of mechanical recycling.
- Bio-based Polymers:The development of bio-based and biodegradable resins like PLA and PHA presents an opportunity in applications such as agricultural films and disposable food service items where recovery is challenging.
- Recycled Content Mandates:Policies such as the UK Plastic Packaging Tax and extended producer responsibility schemes in several US states create a regulated, high-value market for post-consumer recyclate.
Industry Challenges
- Capital Allocation Dilemma:Producers face a difficult strategic choice in allocating capital between constructing new virgin petrochemical capacity and investing in high-cost, technologically uncertain advanced recycling infrastructure.
- Collection and Sorting Infrastructure:Establishing a consistent, scaled supply chain for high-quality post-consumer plastic feedstock requires significant investment in collection, sorting, and pre-processing capabilities which are currently underdeveloped.
- Certification Complexity:Proving the chain of custody for recycled or bio-based content requires navigating complex third-party certification schemes like ISCC PLUS, adding administrative and cost burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Resins Market |
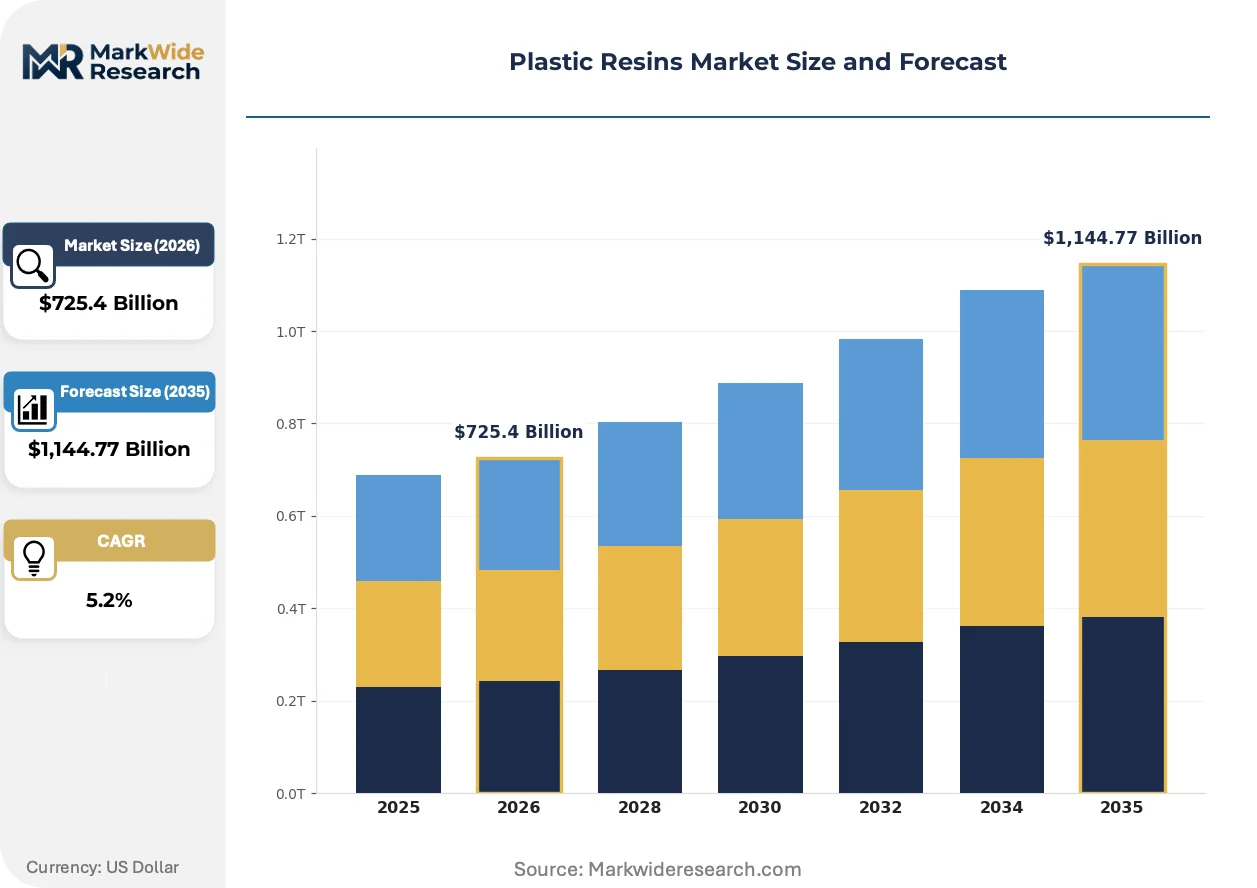
| Market Size in 2026 | $725.4 Billion |
| Market Size in 2035 | $1,144.77 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
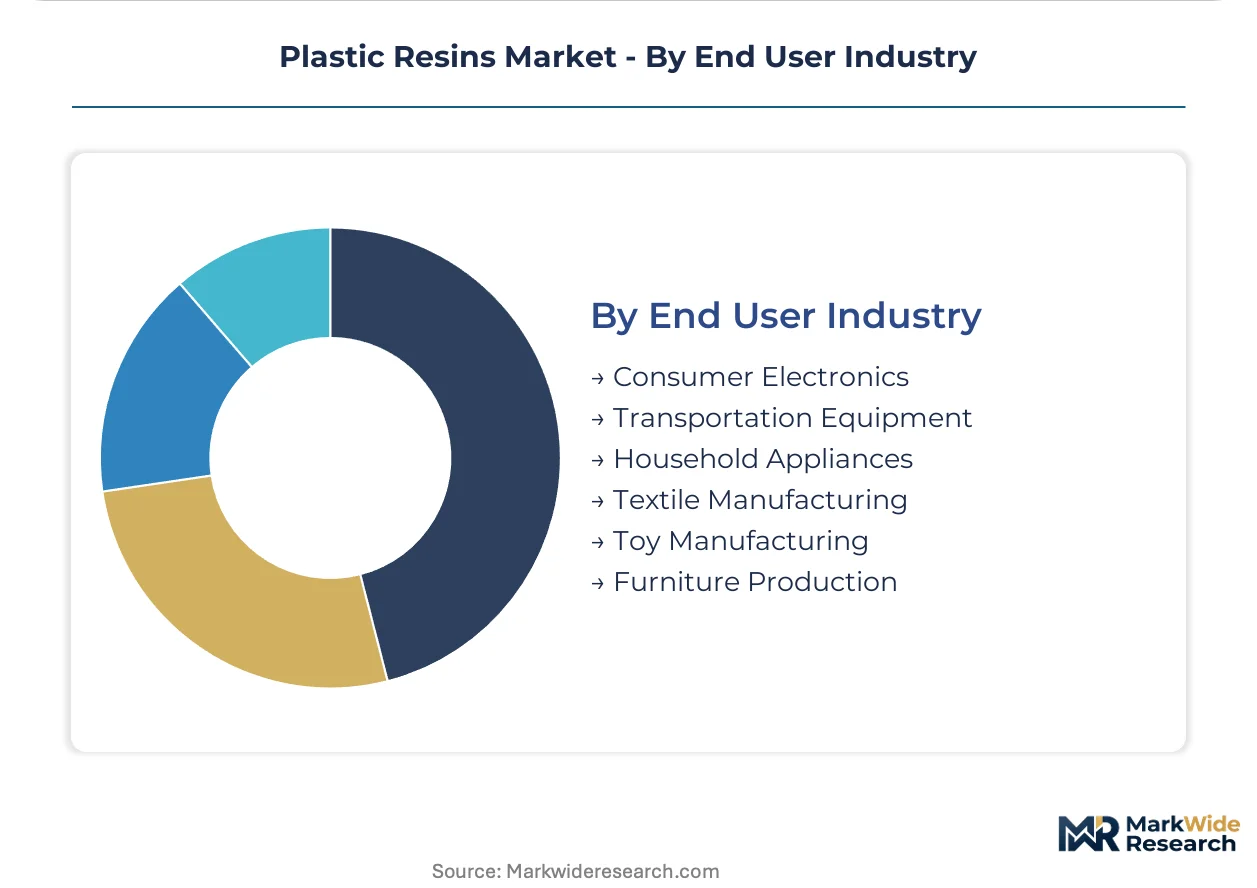
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene, Polycarbonate, Acrylonitrile Butadiene Styrene Form: Pellets, Powder, Granules, Flakes, Liquid, Sheets Application: Packaging, Construction Materials, Electrical Components, Automotive Components, Consumer Goods, Agricultural Films End User Industry: Consumer Electronics, Transportation Equipment, Household Appliances, Textile Manufacturing, Toy Manufacturing, Furniture Production |
| Companies Covered | BASF SE, Dow Inc., SABIC, DuPont de Nemours, Inc., Exxon Mobil Corporation, LyondellBasell Industries, Sumitomo Chemical Co., Ltd., Evonik Industries AG, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Resins Market Strategic Shifts & Innovations
The market's trajectory is being redefined by a fundamental re-evaluation of the polymer lifecycle, from feedstock sourcing to end-of-life management. This shift is a direct response to new regulatory frameworks and evolving expectations from end-use industries.
Chemical recycling technologies, such as pyrolysis, function by breaking down mixed plastic waste into a synthetic oil feedstock. Major petrochemical and materials firms are adopting this process to produce new polymers with performance characteristics identical to their virgin counterparts. This technology is consolidating the value of post-consumer plastic, transforming it from a waste management issue into a viable alternative feedstock for polymer production.
European Union directives, particularly the Corporate Sustainability Reporting Directive (CSRD), are forcing greater transparency in the value chain. The regulation compels resin producers and their customers to quantify and report on circular economy metrics, including recycled content and end-of-life processing. The engineering plastics segment is especially impacted, as suppliers must furnish detailed lifecycle data to automotive OEMs who face their own stringent disclosure requirements.
Multi-source procurement strategies for specialty and engineering resins are becoming standard practice among large original equipment manufacturers. This change disrupts traditional, exclusive supplier relationships, as buyers now qualify several vendors to mitigate supply disruptions and enhance pricing leverage. This trend is most pronounced in the medical device and aerospace sectors, where a secure supply of certified, high-performance polymers is non-negotiable.
Plastic Resins Market Segmentation

Understanding the Plastic Resins Market through segmentation reveals the intricate interplay of material science, application demands, and end-user requirements. This granular view highlights where value creation concentrates and how different resin types address specific industrial needs. Analyzing these segments provides strategic clarity for market participants navigating supply chain dynamics.
Product Type:
Supply concentration in the plastic resins market is heavily influenced by the production scale of foundational polymer types, dictating availability and cost across the value chain.
- Polyethylene:This thermoplastic polymer, derived from ethylene, offers high ductility and excellent moisture barrier properties. Demand concentrates in packaging across India and China, driven by e-commerce expansion.
- Polypropylene:A versatile thermoplastic polymer from propylene, known for its high strength-to-weight ratio and chemical resistance. Consumption is concentrated in the automotive sector within Germany and Japan for lightweighting.
- Polyvinyl Chloride:A durable and cost-effective thermoplastic, PVC is widely used in construction materials for pipes and profiles.
- Polystyrene:This aromatic polymer offers clarity and stiffness, primarily utilized in disposable packaging and insulation.
- Polycarbonate:A high-performance engineering thermoplastic, polycarbonate provides exceptional impact resistance and optical clarity for demanding applications.
- Acrylonitrile Butadiene Styrene:ABS is an amorphous thermoplastic, known for its strength and impact resistance, frequently used in electronic housings.
Polyethylene absorbs the bulk of installed capacity; Polycarbonate is expanding most quickly.
Form:
The volume of plastic resins supplied to downstream manufacturers primarily flows through standardized physical forms, optimizing handling and processing efficiency.
- Pellets:These small, uniform granules are the most common form for virgin and recycled plastic resins, facilitating precise dosing in molding processes. Demand is concentrated in consumer goods manufacturing hubs in China.
- Granules:Similar to pellets, granules are a foundational form for bulk material handling, widely used in various processing techniques. Their use is prevalent in the US construction sector for piping.
- Powder:Fine resin particles are used in specialized applications like rotational molding and coatings.
- Flakes:Derived from recycled plastic waste, flakes serve as feedstock for mechanical recycling.
- Liquid:Resins in liquid form are commonly thermosetting polymers, used in casting, coatings, and adhesives.
- Sheets:Pre-formed flat plastic sheets are used in thermoforming and fabrication for signage and protective barriers.
The market for plastic resins in pellet form accounts for the largest share; liquid forms are gaining market traction.
Application:
Higher-margin growth segments within the plastic resins market are found in specialized applications demanding superior performance and stringent certifications.
- Packaging:This application segment utilizes polyethylene and polypropylene for flexible films and rigid containers. Demand remains strong across Europe, driven by evolving consumer preferences and e-commerce.
- Automotive Components:Engineering resins like polycarbonate and ABS are critical for lightweighting vehicle parts. The automotive sector in Germany and Japan drives demand for high-performance resins to meet fuel efficiency standards.
- Construction Materials:Resins such as PVC and polyethylene are widely used for pipes, fittings, and insulation due to durability.
- Electrical Components:Specialized resins provide insulation, flame retardancy, and structural integrity for connectors and circuit boards.
- Consumer Goods:A broad category for household items, toys, and sports equipment, relying on diverse resins for aesthetics and durability.
- Agricultural Films:Polyethylene is extensively used for greenhouse films, mulching, and silage wrap, enhancing crop yield.
Packaging applications command significant volume; automotive components exhibit the most rapid expansion.
End User Industry:
Different end-user industries procure specific plastic resins based on their unique product requirements, performance specifications, and regulatory compliance needs.
- Consumer Electronics:This industry demands high-performance resins like polycarbonate and ABS for device housings and internal components, balancing durability with design. Manufacturers in South Korea and China drive significant demand.
- Transportation Equipment:Including automotive and aerospace, this sector relies on engineering resins for lightweighting and structural integrity. The transportation sector in the US and Germany seeks advanced materials for EV battery enclosures.
- Household Appliances:Resins provide structural integrity, aesthetic appeal, and functional components for white goods.
- Textile Manufacturing:Synthetic fibers from resins like polyester and nylon are critical inputs for various textile products.
- Toy Manufacturing:This sector uses commodity and engineering resins, prioritizing safety, durability, and vibrant color.
- Furniture Production:Resins are utilized for various furniture components, including frames, molded parts, and upholstery.
Consumer electronics represents the largest purchasing segment; transportation equipment is undergoing the fastest transformation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentration for plastic resins is significant across key manufacturing hubs globally, driven by industrialization and expanding consumer markets. These regions also face evolving regulatory pressures for sustainability, influencing local production and material choices. The strategic decisions of resin producers and downstream manufacturers often align with these regional dynamics.
China
China's expansive manufacturing base for consumer goods and electronics drives concentrated, high-volume demand for polymers like polycarbonate and ABS. National GB standards and dual carbon goals are compelling producers to adopt more sustainable manufacturing processes. The Yangtze River Delta region, a major manufacturing cluster, is witnessing investments in advanced recycling infrastructure to meet future demand.
Germany
The automotive sector in Germany drives substantial demand for high-performance engineering resins to meet stringent fuel efficiency standards. The EU Green Deal and REACH directive influence product composition and emphasize circularity in resin production. Baden-Württemberg, a hub for automotive manufacturing, sees increasing integration of engineering plastics in electric vehicle components.
United States
The US construction sector utilizes significant volumes of PVC and polyethylene for pipes, fittings, and insulation materials. EPA rules on chemical substances define market access, while various state-level extended producer responsibility schemes create demand for recycled content. The Gulf Coast region, a major petrochemical production center, is exploring advanced recycling technologies to diversify feedstock sources.
Japan
Japan's automotive and electronics industries require specialized engineering resins for lightweighting and high-durability applications. METI initiatives promote circular economy practices and investment in sustainable materials development. The Kansai region, home to numerous advanced materials companies, focuses on developing bio-based polymers for diversified applications.
India
Packaging applications, fueled by e-commerce expansion, drive substantial demand for polyethylene and polypropylene across India. BIS standards govern plastic product quality and safety, influencing material selection for various end-use sectors. Maharashtra, a key industrial state, is witnessing growth in plastic processing units to cater to the expanding consumer goods market.
Plastic Resins Market Key Industry Players
Capacity expansion and strategic partnerships dominate the current landscape in the plastic resins market. The market structure is tiered, featuring large, vertically integrated petrochemical giants, specialized engineering resin manufacturers, and an emerging segment of advanced recycling innovators. Dominant competitive moves include capital allocation into new virgin capacity or advanced recycling, alongside strategic partnerships to secure feedstock and meet circularity targets.
At the scale-driven end, Dow Inc. exemplifies the commodity resin producer with vast polyethylene production capabilities. BASF SE represents diversified chemical producers, specializing in engineering plastics for automotive and industrial applications. SABIC occupies a position as a specialist in polycarbonates, serving demanding electronics and construction sectors with high-performance materials.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| SABIC |
| DuPont de Nemours, Inc. |
| Exxon Mobil Corporation |
| LyondellBasell Industries |
| Sumitomo Chemical Co., Ltd. |
| Evonik Industries AG |
| Eastman Chemical Company |
| Others |
Cost & Logistics Intelligence
The EU Green Deal, a significant environmental mandate, gates access to premium-tier pricing for plastic resins by demanding higher sustainability standards. This directive influences both qualified supply and market access for producers.
Pricing Analysis
Volume-driven commodity resins like polyethylene operate on contract-based long-term offtake agreements, while high-performance engineering plastics command value-based pricing. Price differentiation stems from certification level, such as specific automotive OEM approvals, and customization for specialized applications. Pricing softness runs through commodity segments due to feedstock volatility. Consumer goods manufacturers are highly price-sensitive, whereas automotive OEMs prioritize performance over cost for critical components.
Supply Chain Analysis
Regional distribution centers and a hub-and-spoke model characterize the plastic resins supply chain, optimizing delivery to manufacturing clusters. Supply concentrates significantly in China, the US Gulf Coast, and Germany. Production relies on petrochemical feedstocks like naphtha and ethylene. A structural risk is feedstock price volatility, which directly impacts resin production margins. Distribution runs through a network of large-scale distributors and direct sales to major industrial customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic resins market is poised for consolidation, driven by the capital allocation dilemma between virgin capacity and advanced recycling infrastructure. This pressure forces weaker, undifferentiated producers to exit or merge.
For Market Incumbents: Anticipate continued investment in advanced recycling infrastructure, such as pyrolysis plants, to secure circular feedstock. Deepen backward integration into petrochemical feedstocks to mitigate price volatility. The threat of material substitution, particularly in packaging, necessitates R&D into bio-based alternatives and high-performance blends. Control over distribution channels remains a critical lever for market share defense against new entrants.
For New Entrants and Emerging Players: Specialized distributors offer a pathway to penetrate niche markets, particularly for bio-based polymers in agricultural films. Target the high-value engineering plastics segment, focusing on specific automotive components for electric vehicles. The most penetrable application is disposable food service items, where recovery is challenging. A strong certification investment, like ISCC PLUS, provides a compelling go-to-market angle for sustainable offerings.
For Investors and Strategic Acquirers: Increased deployment of chemical recycling technologies is the leading indicator that the market is shifting towards circularity. Long-term viability over the next decade hinges on producers' ability to balance virgin capacity with recycled content mandates. Target acquisition archetypes include specialized advanced recycling technology providers or bio-polymer innovators. Policy shifts, such as stricter EU Green Deal targets, serve as a critical inflection signal for investment strategies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Secure long-term supply of commodity resins for packaging and consumer goods. |
| Green Manufacturing Transition | Meet EU Green Deal and China's dual carbon goals for market access. |
| Long-term Supply Agreement | Mitigate feedstock price volatility for stable production costs. |
| Joint Venture | Share capital and technological risks for advanced recycling infrastructure development. |
| Product Launch | Introduce new bio-based polymers for challenging recovery applications. |
Research Approach
Customs and trade data, company annual reports, and industry association publications formed the secondary backbone for this analysis. Primary interviews with plant managers, procurement leads at automotive OEMs, and distribution channel partners provided qualitative insights. This approach combined bottom-up market sizing with top-down validation from industry experts.
A bottom-up analytical framework, triangulated with top-down market validation, projected market evolution across the analysis window. Segmentation dimensions included product type, form, application, and regional regulatory clusters. Compound annual growth rates were derived from historical growth trends and anticipated technological shifts. Global petrochemical feedstock supply and demand dynamics informed future pricing assumptions.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts and rapid, widespread adoption of entirely new material science. Forecasts reflect assumptions regarding regulatory stability and technological development. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Transparent Polyamides Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Global Resin Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
PCR Polyolefins Market