
 Global Bio-Based Polyethylene Market | 2026-2036
Global Bio-Based Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bio-Based Polyethylene Market Foresight
Polymer chemist talent scarcity is reorganizing production geography across the bio-based polyethylene value chain. Braskem leverages its Brazilian sugarcane ethanol integration to anchor feedstock security for bio-PE output. Dow competes through R&D intensity in catalyst systems that improve polymerization efficiency for renewable ethylene feedstocks. LyondellBasell controls licensing technology that extends process know-how to partners seeking bio-based conversion capabilities.
Bio-based polyethylene is a thermoplastic polymer synthesized from ethylene derived from biomass feedstocks such as sugarcane ethanol, exhibiting density grades from 0.910 to 0.965 g/cm³ and melt flow indices between 0.2 and 50 g/10 min depending on catalytic process conditions. It serves as a drop-in replacement for fossil-based polyethylene in applications requiring identical mechanical properties with reduced cradle-to-gate carbon intensity. High-Density Bio-PE dominates rigid packaging and pipe applications where stiffness and tensile strength command premium positioning, while Linear Low-Density Bio-PE sustains the fastest growth trajectory in flexible packaging films and stretch wrap where puncture resistance and processability drive substitution. Low-Density Bio-PE occupies mature volume positions in consumer goods and wire sheathing where brand sustainability commitments reshape procurement specifications.
The EU Green Deal and REACH framework mandate bio-based content thresholds in packaging, compelling reformulation across food processing and personal care supply chains. EPA renewable fuel standards and Brazil's RenovaBio program create divergent compliance architectures that shape feedstock qualification and carbon accounting methodologies. FDA food contact notifications and EFSA safety assessments govern migration limits for bio-PE in direct food applications, establishing technical barriers that favor producers with documented regulatory dossiers. Stakeholders must monitor feedstock certification scheme fragmentation between ISCC PLUS and Bonsucro standards as procurement specifications harden around traceability requirements.
Market Dynamics
Feedstock certification fragmentation between ISCC PLUS and Bonsucro standards is forcing producers to maintain parallel documentation systems, raising compliance costs and advantaging integrated agricultural-chemical conglomerates with in-house traceability infrastructure.
Growth Catalysts
- EU Green Deal bioeconomy mandates:Binding substitution thresholds for fossil-based plastics in food packaging are compelling reformulation across European supply chains.
- Sugarcane ethanol infrastructure concentration:Brazil's RenovaBio program anchors low-carbon feedstock security for bio-PE producers with backward integration into agricultural supply.
- Drop-in mechanical equivalence:Bio-PE matches fossil-based polyethylene density grades and melt flow indices without equipment retrofit, removing switching friction for converters.
Market Restraints
- Feedstock cost volatility:Agricultural commodity price swings in sugarcane and corn ethanol expose margins to weather-driven supply shocks.
- Catalyst system supply concentration:Specialized metallocene and Ziegler-Natta catalyst production clusters in Germany and the United States create single-source vulnerabilities.
- Technical limitation in high-barrier applications:Bio-PE oxygen transmission rates currently exclude the material from extended-shelf-life food packaging requiring multilayer structures.
Strategic Opportunities
- Underpenetrated Japanese packaging sector:METI's plastic resource circulation strategy has not yet enforced bio-based content floors, leaving first-mover positioning for certified imports.
- Pharmaceutical primary packaging:EMA and FDA migration limit harmonization for bio-PE in blister packs and bottles remains incomplete, creating dossier-building runway.
- Pyrolysis-to-ethylene pathway maturation:Converging chemical recycling and bio-feedstock certification schemes may expand eligible raw material pools beyond first-generation sugars.
Industry Challenges
- Polymer chemist talent scarcity:Specialized expertise in renewable ethylene catalysis and process scale-up concentrates at legacy petrochemical employers, constraining bio-PE specialist hiring pipelines.
- Parallel certification timeline compression:Dual ISCC PLUS and Bonsucro audits require 12-18 month documentation cycles that misalign with annual procurement contract negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bio-Based Polyethylene Market |
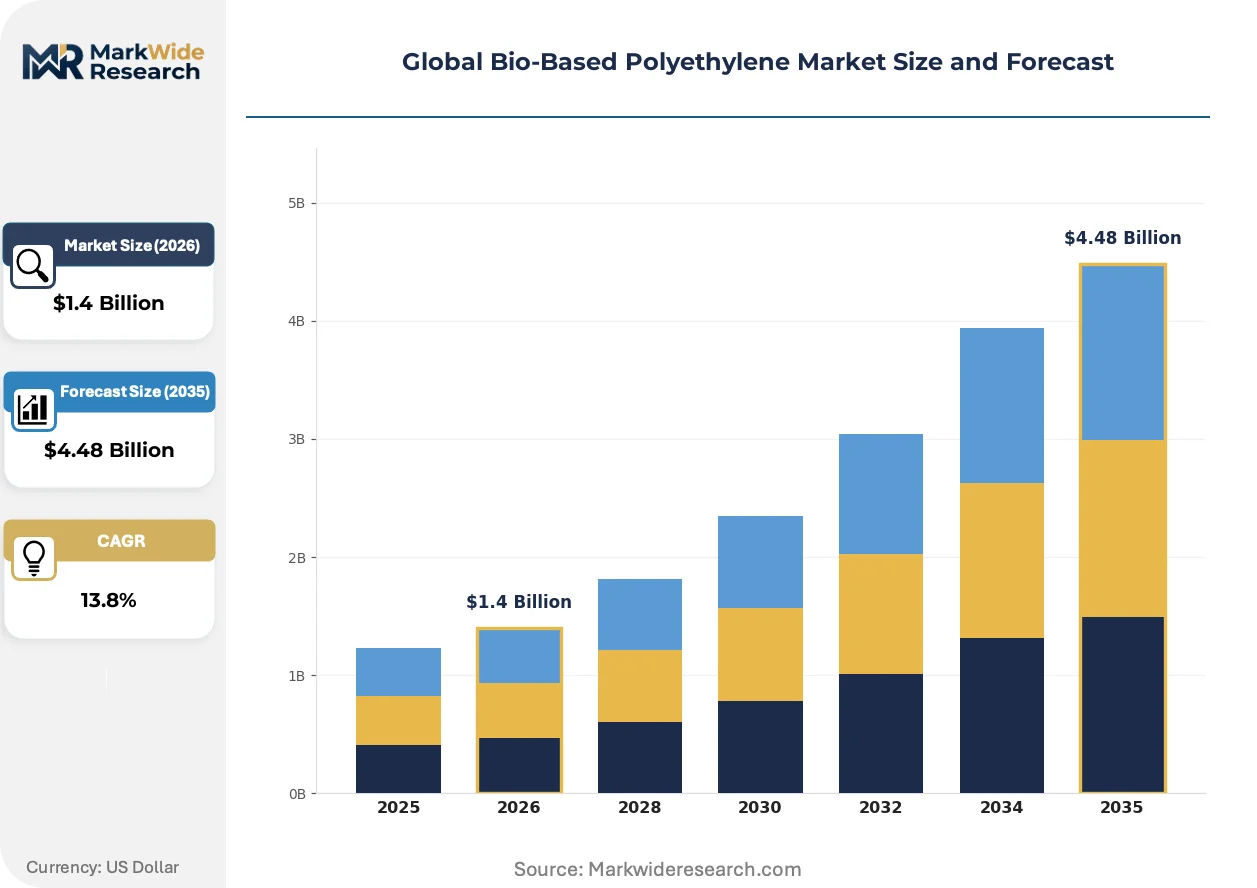
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.48 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Bio-PE, Low-Density Bio-PE, Linear Low-Density Bio-PE, Medium-Density Bio-PE Application: Packaging Films, Agricultural Mulch, Consumer Goods, Wire & Cable Sheathing, Automotive Components End User Industry: Food Processing, Construction, Electronics Manufacturing, Textile Production, Personal Care Distribution Channel: Direct Sales, Distributors, Online Retailers, Industrial Suppliers, Wholesalers |
| Companies Covered | Braskem, LyondellBasell, Dow, SABIC, Avery Dennison Corporation, DuPont, Solvay, Arkema, Borealis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bio-Based Polyethylene Market Shifts & Advancements
Advanced catalytic processes and regulatory tightening are compressing the cost premium between bio-based and fossil-derived polyethylene, while procurement specifications harden around carbon intensity documentation.
Metallocene single-site catalyst systems is supplanting conventional Ziegler-Natta processes in bio-PE production. Food packaging converters in Germany and France are adopting these systems at accelerated procurement cycles. The technology is supplanting older polymerization methods by enabling narrower molecular weight distributions that reduce film gauge without sacrificing puncture resistance.
REACH framework amendments on microplastics and the EU Green Deal's carbon border adjustment mechanism are tightening cradle-to-gate accounting requirements. Industrial consequence includes mandatory third-party verification of agricultural land-use change impacts in bio-PE supply chains. Food processing and personal care segments in Northern Europe are responding by pre-qualifying suppliers with completed EFSA safety dossiers.
Brand sustainability commitments are compressing converter switching cycles from multi-year contracts to annual requalification. Direct procurement between consumer goods manufacturers and bio-PE producers is disintermediating traditional resin distributors in the United States and Western Europe. This pattern is most visible in rigid dairy packaging where private-label retailers enforce mass-balance certification at the finished goods level.
Global Bio-Based Polyethylene Market Segmentation
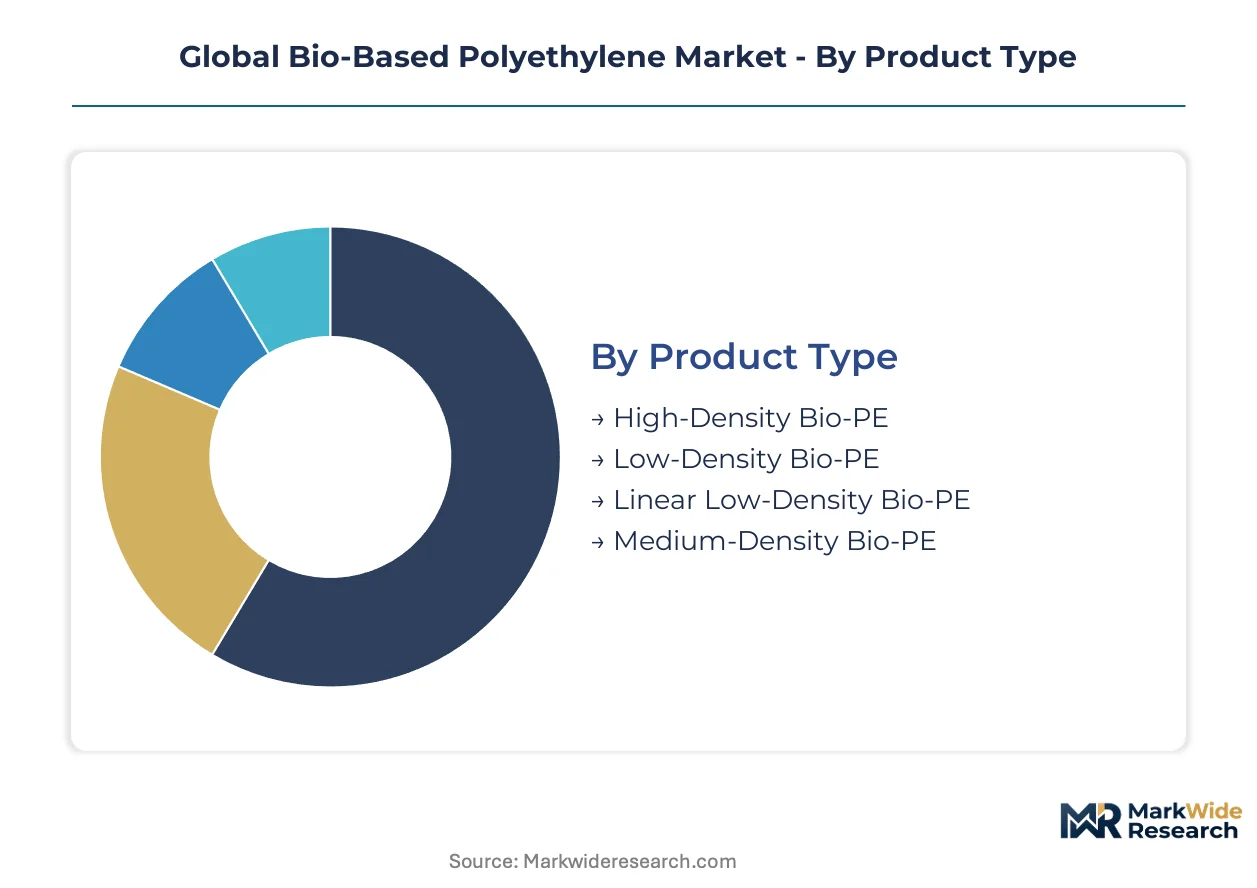
Segmentation in bio-based polyethylene reveals how feedstock proximity, regulatory stringency, and converter technical requirements partition demand across distinct product grades and supply channels. Each dimension exposes different competitive dynamics—from catalyst-limited density specifications to sustainability-driven procurement patterns in food-contact applications.
Product Type:
High-Density Bio-PE and Linear Low-Density Bio-PE concentrate in export-oriented supply chains serving European and North American converters, while Low-Density and Medium-Density grades serve more geographically dispersed domestic packaging markets.
- High-Density Bio-PE:Stiff thermoplastic with density ranging 0.941–0.965 g/cm³ and melt flow indices tuned for injection molding and blow molding processes. Demand concentrates in German and French rigid dairy packaging where EFSA food-contact dossiers and mass-balance certification requirements favor producers with integrated agricultural traceability systems.
- Linear Low-Density Bio-PE:Ethylene-alpha-olefin copolymer exhibiting superior puncture resistance and stretch characteristics versus conventional LDPE. Japanese and South Korean flexible film converters are adopting this grade fastest as METI's plastic resource circulation strategy tightens without yet mandating bio-based floors, creating first-mover positioning for certified imports.
- Low-Density Bio-PE:Branched polymer structure with density 0.910–0.925 g/cm³ serving wire sheathing and consumer goods applications where brand sustainability commitments reshape procurement specifications.
- Medium-Density Bio-PE:Intermediate density grade balancing stiffness and processability for pipe and conduit applications in Brazilian construction markets leveraging local sugarcane ethanol feedstock integration.
High-Density Bio-PE holds the largest share; momentum sits with Linear Low-Density Bio-PE.
Application:
Cost tier differentiation separates commodity film applications from specialized automotive and electrical segments where performance certification commands premium positioning.
- Packaging Films:Flexible and stretch film applications representing the fastest-expanding volume segment. German and French food processing supply chains are reformulating around EU Green Deal substitution mandates with accelerated procurement cycles for ISCC PLUS-certified resins.
- Agricultural Mulch:Soil-biodegradable film applications where RenovaBio carbon intensity accounting and Bonsucro traceability standards create dual compliance requirements for Brazilian producers serving export markets.
- Consumer Goods:Bottles, caps, and household articles where private-label retailers in the United States enforce annual requalification cycles and direct procurement relationships disintermediating traditional distributors.
- Wire & Cable Sheathing:Electrical insulation applications requiring flame-retardant compounding and UL certification that bio-PE suppliers must achieve through specialized additive packages.
- Automotive Components:Interior trim and under-hood applications where OEM sustainability scorecards and IATF 16949 quality system requirements create qualification barriers.
Packaging Films dominates volume; Agricultural Mulch is climbing the fastest as soil-biodegradability specifications harden.
End User Industry:
Customer type fragmentation splits between highly regulated food-contact sectors with documented safety dossiers and industrial applications where technical specifications dominate procurement.
- Food Processing:Direct-contact packaging for dairy, meat, and produce where FDA food contact notifications and EFSA safety assessments govern migration limits. Northern European converters are pre-qualifying suppliers with completed regulatory dossiers ahead of REACH framework amendments on microplastics.
- Construction:Pipe, geomembrane, and insulation applications where Brazilian domestic demand anchors volume through Braskem's captive sugarcane ethanol supply.
- Electronics Manufacturing:Component packaging and cable management where RoHS compliance and halogen-free specifications intersect with bio-based content requirements.
- Textile Production:Fiber and nonwoven applications serving personal care and medical markets where EMA and FDA migration limit harmonization remains incomplete.
- Personal Care:Bottles and tubes for cosmetics and hygiene products where brand sustainability commitments in France and Germany drive reformulation faster than regulatory mandates.
Food Processing commands the largest share; Personal Care is gaining share fastest as brand commitments outpace compliance timelines.
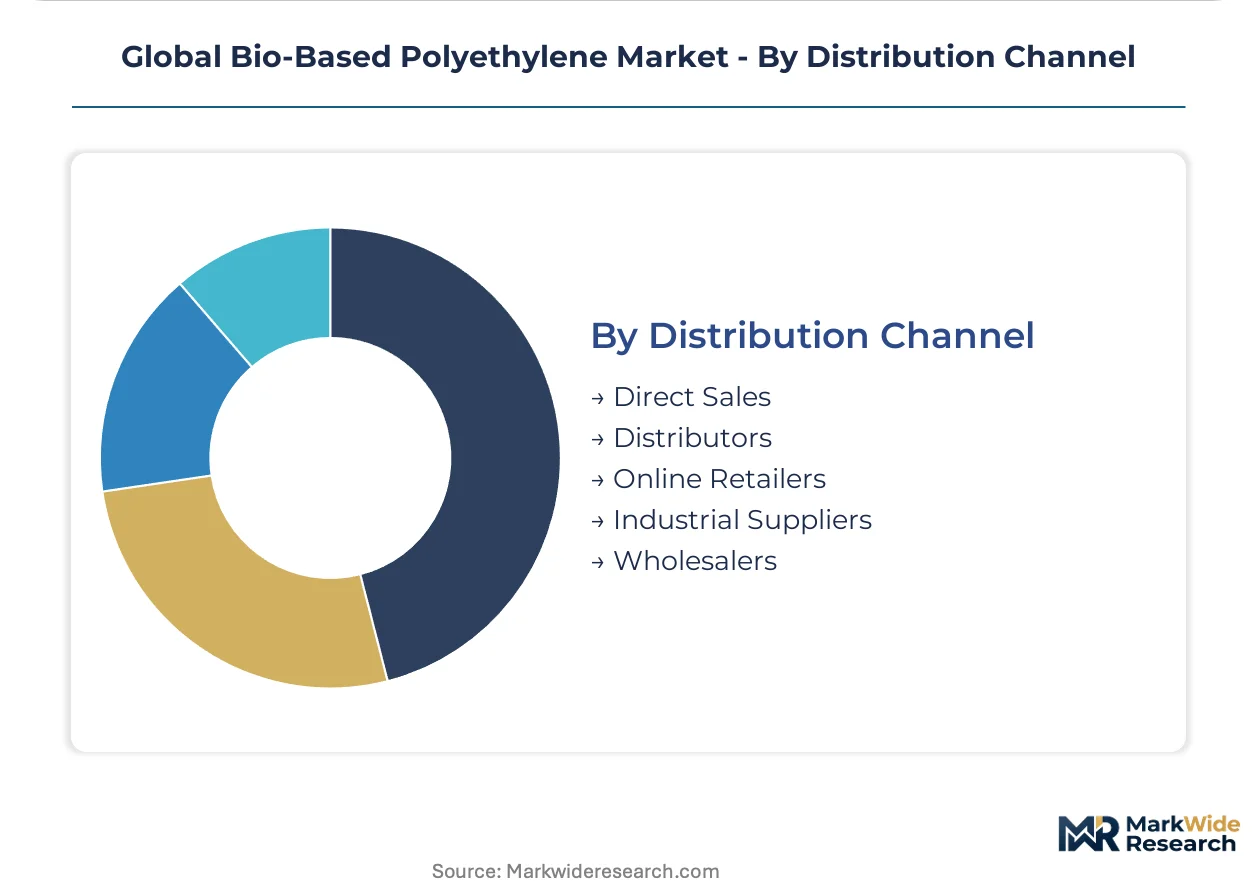
Distribution Channel:
Supply concentration in catalyst production clusters shapes channel efficiency, with direct relationships proliferating where technical service requirements are highest.
- Direct Sales:Producer-to-converter relationships dominating rigid dairy packaging and large-volume film operations where mass-balance certification and carbon intensity documentation require technical collaboration.
- Distributors:Regional resin distributors maintaining inventory positions for small-to-mid converters in the United States and Western Europe, though disintermediation pressure intensifies.
- Online Retailers:Emerging channel for specialty compounders and research quantities, particularly in Japanese and South Korean markets where import certification complexity favors consolidated sourcing platforms.
- Industrial Suppliers:Technical distributors serving wire and cable, automotive, and construction segments with compounding and color-matching services.
- Wholesalers:Volume aggregators for commodity grades in Brazilian domestic construction and agricultural markets with less stringent traceability requirements.
Direct Sales holds the largest share; Online Retailers show the steepest expansion trajectory as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RenovaBio carbon intensity accounting in Brazil anchors feedstock security for bio-based polyethylene producers with backward integration into sugarcane ethanol supply chains. The EU Green Deal's binding substitution thresholds are compelling reformulation across German and French packaging supply chains. Japanese and South Korean converters are positioning ahead of anticipated regulatory tightening under METI's plastic resource circulation strategy.
Brazil
Sugarcane ethanol infrastructure concentration and RenovaBio program incentives drive feedstock cost advantages for bio-PE production. ANVISA food contact regulations govern migration limits for dairy and beverage packaging applications. São Paulo state hosts integrated agricultural-chemical operations where Braskem's captive ethanol supply secures mass-balance certification for export markets.
Germany
EFSA food-contact dossier requirements and REACH framework amendments on microplastics are accelerating converter pre-qualification of certified bio-PE suppliers. EU Green Deal carbon border adjustment mechanisms tighten cradle-to-gate documentation requirements. The Rhine-Ruhr industrial corridor concentrates rigid dairy packaging operations where ISCC PLUS certification has become a procurement prerequisite.
United States
EPA renewable fuel standards create divergent compliance architectures that shape feedstock qualification methodologies for bio-based plastics. FDA food contact notifications govern migration limits in direct food applications. The Gulf Coast petrochemical cluster hosts catalyst system production where specialized metallocene supply concentrates, creating single-source vulnerabilities for bio-PE producers.
Japan
METI's plastic resource circulation strategy has not yet enforced bio-based content floors, leaving first-mover positioning for certified bio-PE imports. JIS standards and PMDA consultation procedures create technical barriers that favor producers with documented regulatory dossiers. The Kanto region around Tokyo concentrates flexible film converters adopting Linear Low-Density Bio-PE grades fastest among Asian markets.
France
ANSM and CNIL data governance intersect with EFSA safety assessments for bio-PE in personal care and food packaging applications. EU Green Deal bioeconomy mandates are compelling reformulation across cosmetics and hygiene product supply chains. The Paris Basin hosts brand headquarters where sustainability commitments are reshaping procurement specifications faster than regulatory compliance timelines.
Global Bio-Based Polyethylene Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in bio-based polyethylene production. Agricultural-chemical conglomerates with captive ethanol supply dominate feedstock-secured volume positions. Technology licensors and catalyst specialists occupy differentiated positions where process know-how commands premium returns. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure mass-balance certification and converter qualification.
Within the integrated agricultural-chemical tier, Braskem anchors Brazilian supply through its sugarcane ethanol infrastructure. Dow and LyondellBasell represent North American and European technology leadership through catalyst systems and licensing arrangements. These three companies exemplify how feedstock integration and process technology confer defensible positioning as procurement specifications harden around carbon intensity documentation.
| Leading Market Players |
|---|
| Braskem |
| LyondellBasell |
| Dow |
| SABIC |
| Avery Dennison Corporation |
| DuPont |
| Solvay |
| Arkema |
| Borealis AG |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month dual certification timelines for ISCC PLUS and Bonsucro standards compress inventory turnover and amplify pricing power for Brazilian integrated producers with captive ethanol supply. This lead-time band forces European converters into annual contract renegotiation cycles that favor backward-integrated suppliers with documented mass-balance chains.
Pricing Analysis
Brazilian export prices for bio-PE resins command premiums over Gulf Coast spot polyethylene equivalent to the carbon intensity documentation value captured by RenovaBio-certified supply. Three-tier pricing structure across ISCC PLUS-certified premium, mass-balance standard, and uncertified economy grades separates food-contact converters from construction wholesalers. Pricing pressure stems from agricultural commodity volatility in sugarcane ethanol feedstock costs. Small-to-mid converters in the United States exhibit highest price sensitivity due to distributor disintermediation and direct procurement compression.
Supply Chain Analysis
Strategic stockpiling of metallocene catalyst systems dominates procurement behavior among German and French rigid packaging converters seeking polymerization efficiency gains. Supply concentrates in Brazil, Germany, and the United States, with Brazilian sugarcane ethanol infrastructure anchoring feedstock security. Raw material dependencies center on agricultural ethanol, specialized catalyst metals, and mass-balance certification documentation. Single-source vulnerability in metallocene catalyst production clusters creates supply chain risk. Distribution runs through direct producer-to-converter relationships for certified grades, with regional distributors serving commodity construction markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion in bio-based polyethylene rests on EU Green Deal substitution mandates accelerating faster than converter qualification capacity, creating temporary supply scarcity for certified resins.
For Market Incumbents: Consolidate feedstock security through backward integration into Brazilian sugarcane ethanol supply or long-term offtake agreements with RenovaBio-certified mills. Defend margin position by accelerating EFSA food-contact dossier completion ahead of REACH microplastics amendments. Priority lever sits with catalyst system partnerships that lock in polymerization efficiency gains.
For New Entrants and Emerging Players: Lead with pharmaceutical primary packaging applications where EMA and FDA migration limit harmonization remains incomplete, creating dossier-building runway. Target Japanese flexible film converters ahead of METI bio-based content floor enforcement. Go-to-market angle centers on ISCC PLUS certification bundled with technical service support for annual requalification cycles.
For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical conglomerates with stranded catalyst R&D assets and underutilized ethanol feedstock positions. Long-term viability frames around bio-PE capturing share in rigid dairy and personal care packaging as brand sustainability commitments harden. Signal to watch is pyrolysis-to-ethylene pathway maturation expanding eligible raw material pools beyond first-generation sugars.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Supply | RenovaBio certification secures mass-balance documentation for EU export markets. |
| Catalyst System Partnership | Metallocene efficiency gains reduce film gauge without sacrificing puncture resistance. |
| EFSA Dossier Completion | Pre-qualified supplier status accelerates converter adoption ahead of REACH amendments. |
| Direct Procurement Channel | Disintermediation captures margin from traditional resin distributors in dairy packaging. |
| Pyrolysis Pathway Investment | Chemical recycling convergence expands feedstock eligibility beyond sugarcane ethanol. |
Research Methodology
Desk research of trade flow databases, customs records, and EFSA regulatory filings preceded structured interviews with polymerization plant managers, downstream packaging procurement leads, catalyst system R&D directors, and sustainability certification auditors. Primary fieldwork with Brazilian ethanol mill operators and German rigid dairy converters validated secondary estimates. Analysis combined bottom-up capacity modeling with top-down demand segmentation triangulation.
Variance decomposition across feedstock cost, certification timeline, and converter adoption rate segments shaped analytical framework over the projection horizon. Modeled dimensions included density grade tier, end-use industry application, regional production hub, and certification scheme type. CAGRs derived from logistic diffusion curves fitted to historical substitution patterns and policy mandate trajectories. Forecast inputs incorporated RenovaBio carbon intensity accounting methodology and EU Green Deal implementation pacing.
Underlying assumptions cover sustained EU substitution mandate enforcement and catalyst supply continuity, with deviation risk concentrated in agricultural commodity price shocks and certification scheme fragmentation. Forecasts reflect documented conditions without forward guarantee. Revision becomes warranted when pyrolysis-to-ethylene pathway economics cross commercial viability thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Silicon Anode Binder Polymers for Lithium-Ion Batteries Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Microcellular Plastics Market