
 Global Colored PU Foams Market | 2026-2036
Global Colored PU Foams Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colored PU Foams Market Foresight
A shift from single-source pigment supply to multi-source qualification is restructuring procurement strategies across colored PU foam converters. BASF SE leverages captive polyol and isocyanate production to control raw material color consistency from molecule to finished slab. Covestro AG anchors its position through proprietary reactive coloring technologies that reduce post-process dyeing steps. Huntsman Corporation differentiates via specialized automotive color labs in Michigan and Shanghai that match OEM interior palettes within Delta-E tolerances.
Colored PU foams are polyurethane cellular materials infused with pigments or reactive colorants during the polymerization or foaming stage, typically exhibiting densities from 20 to 80 kg/m³ for flexible variants and compressive strengths tailored to end-use load requirements; their primary purpose is to combine structural cushioning, thermal insulation, or energy absorption with aesthetic differentiation in visible consumer and industrial products. Flexible PU foams occupy the largest volume share due to entrenched demand from furniture upholstery and bedding producers, though viscoelastic foams command premium pricing in medical and ergonomic applications where slow recovery and precise color matching justify higher formulation costs. Metallic color foams represent the fastest-expanding color type segment as consumer electronics housings and automotive trim panels adopt brushed-aluminum and copper visual effects without secondary painting operations.
EPA regulations under TSCA govern the import and manufacture of polymeric substances containing heavy-metal pigments in the United States, while REACH and the EU F-Gas Regulation restrict fluorinated blowing agents and certain azo dyes in European foam production. China's MEE enforces GB standards on volatile organic compound emissions from PU manufacturing facilities, compelling domestic producers to reformulate colorant carrier systems. Stakeholders must monitor evolving chemical restriction schedules across these three jurisdictions to anticipate reformulation costs and secure alternative pigment approvals before compliance deadlines tighten.
Market Dynamics
REACH chemical restrictions and evolving EU Green Deal standards are forcing colored PU foam converters to abandon solvent-based colorants and reformulate around water-based pigment systems, triggering multi-year qualification cycles with automotive OEMs.
Growth Catalysts
- Automotive Interior Mandates:German and Japanese OEMs now require certified colored foams for visible cabin components, expanding specification volumes for seat cushioning and dashboard applications.
- REACH Annex XVII Expansion:Restrictions on heavy-metal pigments and azo dyes are redirecting formulation investments toward compliant reactive colorant platforms.
- China Eastern Chemical Parks:Integrated PU production clusters in Jiangsu and Zhejiang provinces enable just-in-time color matching and compressed lead times for downstream converters.
Market Restraints
- Raw Material Concentration:Captive polyol and isocyanate supply at major chemical conglomerates limits independent foam converters' negotiating leverage on color consistency.
- Pigment Cost Volatility:Specialty organic pigments and effect colorants face price swings tied to rare earth and metal feedstock availability.
- Fluorinated Blowing Agent Phase-Out:EU F-Gas Regulation restrictions on HFC-based blowing agents force capital-intensive retooling of foam line equipment.
Strategic Opportunities
- Medical Device Ergonomics:Viscoelastic colored foams for hospital bedding and wheelchair cushioning remain underpenetrated in North American healthcare procurement.
- Consumer Electronics Housings:Metallic-effect PU foams for laptop and tablet enclosures offer paint-free aesthetic differentiation.
- India PLI Scheme:Production-linked incentives for domestic manufacturing are attracting foam converters to establish color compounding capabilities near electronics assembly zones.
Industry Challenges
- Colorimetric Talent Scarcity:Delta-E matching within automotive OEM tolerances requires specialized spectrophotometry expertise that remains concentrated among senior formulators.
- Multi-Jurisdiction Certification Overlap:Simultaneous EPA TSCA, REACH, and China GB standard compliance creates conflicting test protocols and extended approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colored PU Foams Market |
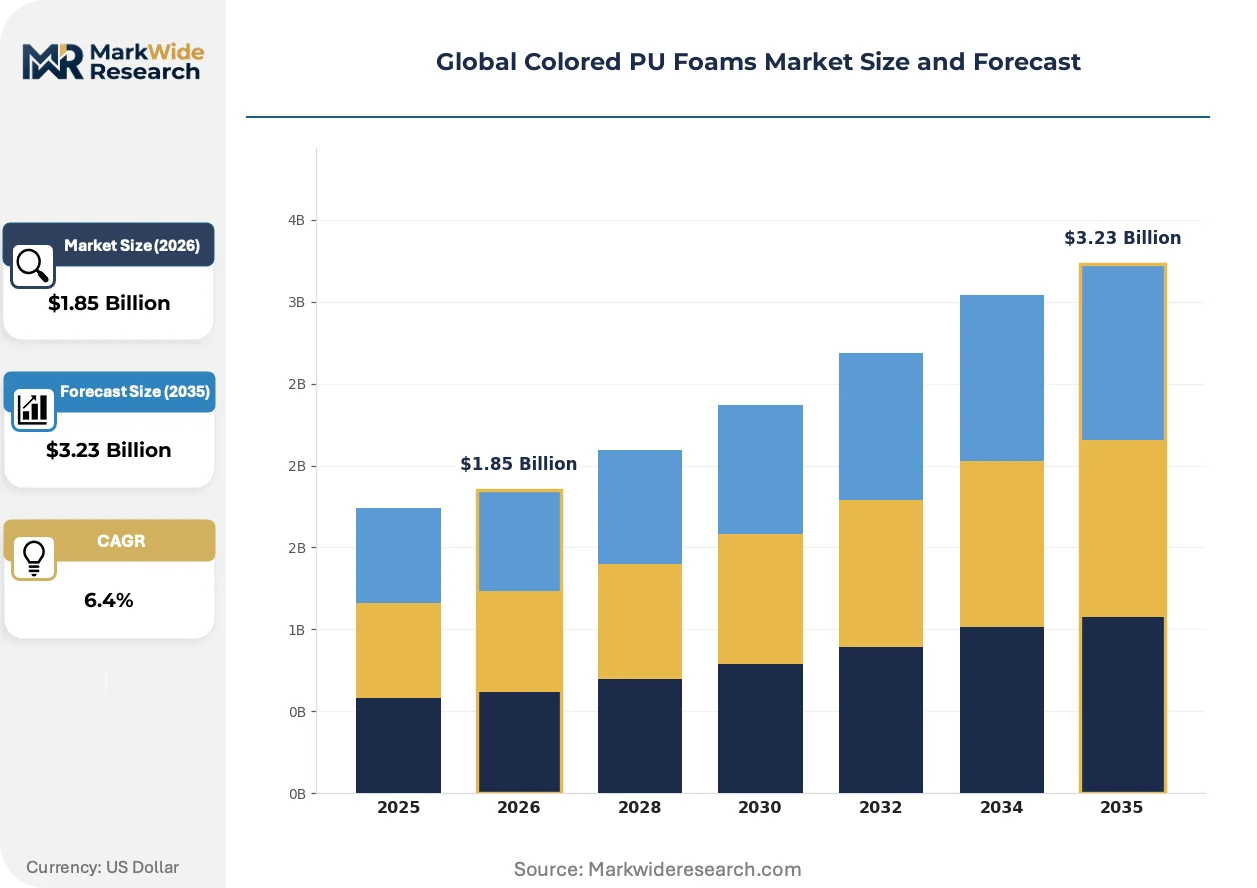
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PU Foams, Rigid PU Foams, Viscoelastic Foams, Integral Skin Foams, High Resilience Foams Color Type: Solid Color Foams, Gradient Color Foams, Metallic Color Foams, Fluorescent Color Foams, Pastel Color Foams Application: Furniture Upholstery, Automotive Interiors, Footwear Components, Packaging Solutions, Sports Equipment End User Industry: Consumer Electronics, Marine Equipment Manufacturers, Bedding Producers, Transportation OEMs, Protective Gear Fabricators |
| Companies Covered | BASF SE, Covestro AG, Huntsman Corporation, Dow Inc, Wanhua Chemical Group Co., Ltd., Rogers Corporation, Saint-Gobain Performance Plastics, Sekisui Chemical Co., Ltd., Recticel NV/SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colored PU Foams Market Shifts & Advancements
Reactive coloring technology is displacing post-foaming dyeing across premium automotive and electronics segments, compressing process steps while tightening color consistency specifications.
Water-based pigment dispersion systems are consolidating formulation strategies as converters face simultaneous pressure from REACH chemical restrictions and automotive OEM sustainability scorecards. Tier-1 seat suppliers in Germany and Japan have accelerated adoption timelines from five-year qualification cycles to eighteen-month pilot programs. This consolidation is eliminating smaller toll compounders lacking in-house dispersion capabilities.
EU F-Gas Regulation phase-down schedules are forcing blowing agent transitions toward hydro-olefin and water-blown systems with modified colorant carrier chemistries. Foam producers serving European automotive markets must revalidate thermal aging and color fastness profiles under new cell morphologies. Medical device manufacturers in Switzerland and the Netherlands are experiencing the longest recertification delays due to biocompatibility re-testing requirements.
Direct mill integration between pigment suppliers and PU chemical producers is compressing traditional distributor channels in China's eastern manufacturing provinces. Large foam converters in Jiangsu now source pre-dispersed color concentrates through pipeline connections rather than drum logistics. This channel consolidation is most visible in consumer electronics supply chains where brushed-aluminum effect foams require precise viscosity-matched delivery systems.
Global Colored PU Foams Market Segmentation
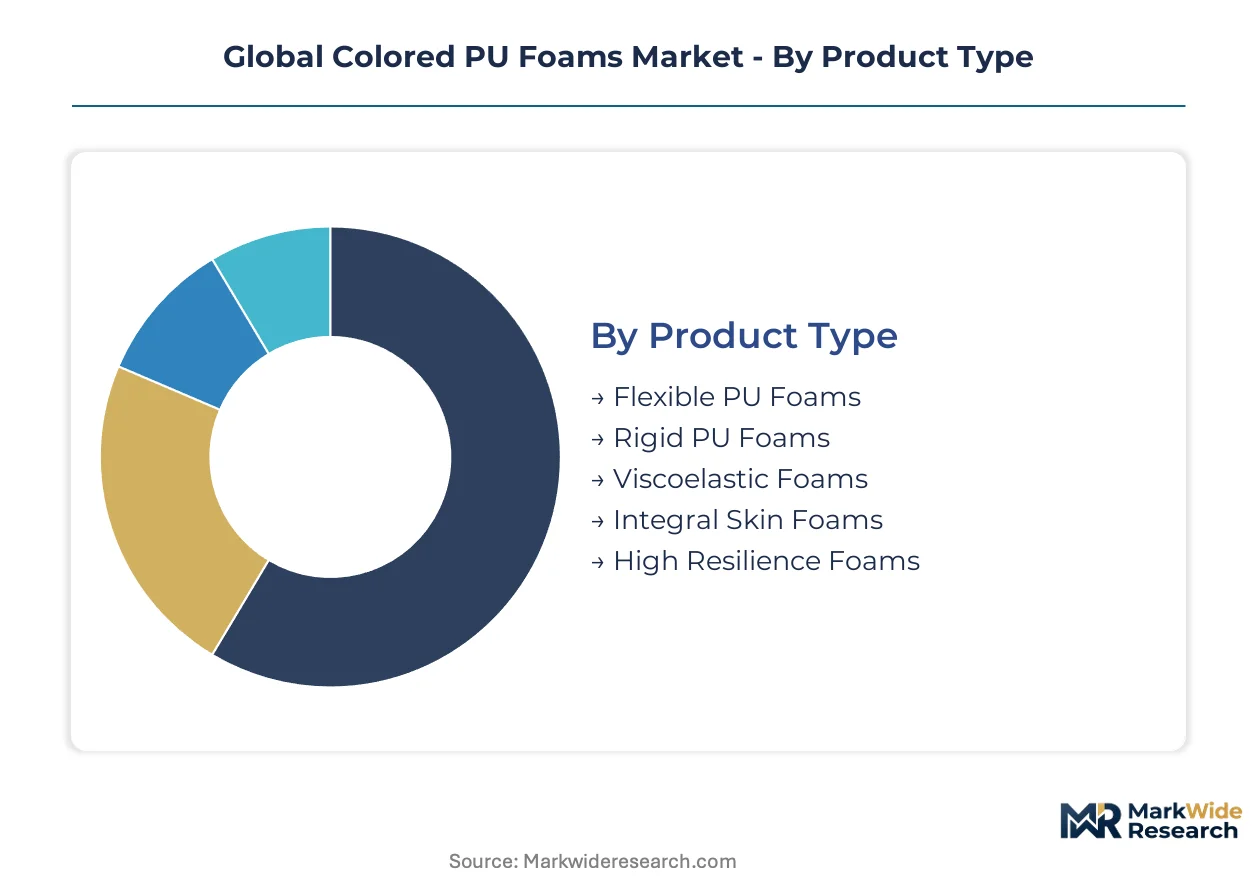
Segmentation in colored PU foams reveals how formulation chemistry, aesthetic specifications, and end-use durability requirements split procurement budgets across entirely different supplier ecosystems. Buyers in automotive and electronics verticals prioritize Delta-E color consistency and regulatory compliance over unit cost, while furniture and packaging purchasers trade color precision for volume pricing.
Product Type:
Material density and recovery characteristics drive purchasing decisions, with each foam category serving distinct load-bearing and comfort specifications.
- Flexible PU Foams:Open-cell polyurethane structures with densities between 20-50 kg/m³ dominate furniture cushioning and bedding applications. German and Japanese automotive seat suppliers specify certified variants for visible cabin components under OEM sustainability scorecards.
- Viscoelastic Foams:Slow-recovery polyurethane formulations with temperature-sensitive cell structures command premium positioning in medical bedding and ergonomic wheelchair cushioning. North American healthcare procurement channels remain underpenetrated relative to European hospital systems.
- Rigid PU Foams:Closed-cell structures with compressive strengths exceeding 150 kPa serve thermal insulation and structural core applications where color coding aids installation identification.
- Integral Skin Foams:Self-skinning polyurethane systems combine a dense outer layer with cellular core in single-shot molding, eliminating secondary finishing for armrests and steering wheel covers.
- High Resilience Foams:Polyether-based formulations with rapid recovery rates sustain repeated compression cycles in premium seating and hospitality mattresses.
Volume sits with Flexible PU Foams; growth tilts toward Viscoelastic Foams.
Color Type:
Surface finish requirements and manufacturing process compatibility determine whether converters specify solid pigments, effect colorants, or reactive dye systems.
- Metallic Color Foams:Brushed-aluminum and copper visual effects achieved through effect pigment dispersion eliminate secondary painting operations for laptop housings and automotive trim panels. Consumer electronics assemblers in China specify these for paint-free aesthetic differentiation.
- Solid Color Foams:Uniform pigmentation through in-mold colorant addition provides the baseline specification for furniture upholstery and bedding where cost efficiency outweighs visual complexity.
- Gradient Color Foams:Multi-tone transitions requiring precise viscosity control and sequential pouring techniques serve premium footwear midsoles and sports equipment grips.
- Fluorescent Color Foams:High-visibility pigments with light-emitting properties address safety equipment specifications for protective gear and marine flotation devices.
- Pastel Color Foams:Low-saturation colorants formulated for medical device housings and pediatric product lines where aggressive hues conflict with user environment expectations.
Volume concentrates in Solid Color Foams; Metallic Color Foams are climbing the fastest.
Application:
End-use exposure conditions—UV stability, abrasion resistance, and chemical contact—filter which foam formulations and colorant systems qualify for each application category.
- Automotive Interiors:Dashboard padding, door panels, and seat cushioning require thermal aging resistance and fogging compliance under OEM specifications. REACH restrictions on heavy-metal pigments are forcing water-based colorant reformulations with eighteen-month requalification cycles.
- Furniture Upholstery:Residential and contract seating applications prioritize cost-efficient color matching across large production batches, with Chinese eastern chemical parks supplying just-in-time pigment dispersions.
- Footwear Components:Midsole cushioning and collar padding demand compression set resistance combined with brand-specific color matching for athletic and fashion lines.
- Packaging Solutions:Protective inserts and display cushioning utilize lower-density formulations where color serves functional identification rather than aesthetic presentation.
- Sports Equipment:Helmets, protective pads, and gym mats require energy absorption certification alongside color durability under sweat and sunscreen exposure.
Volume rests with Furniture Upholstery; expansion concentrates in Automotive Interiors.
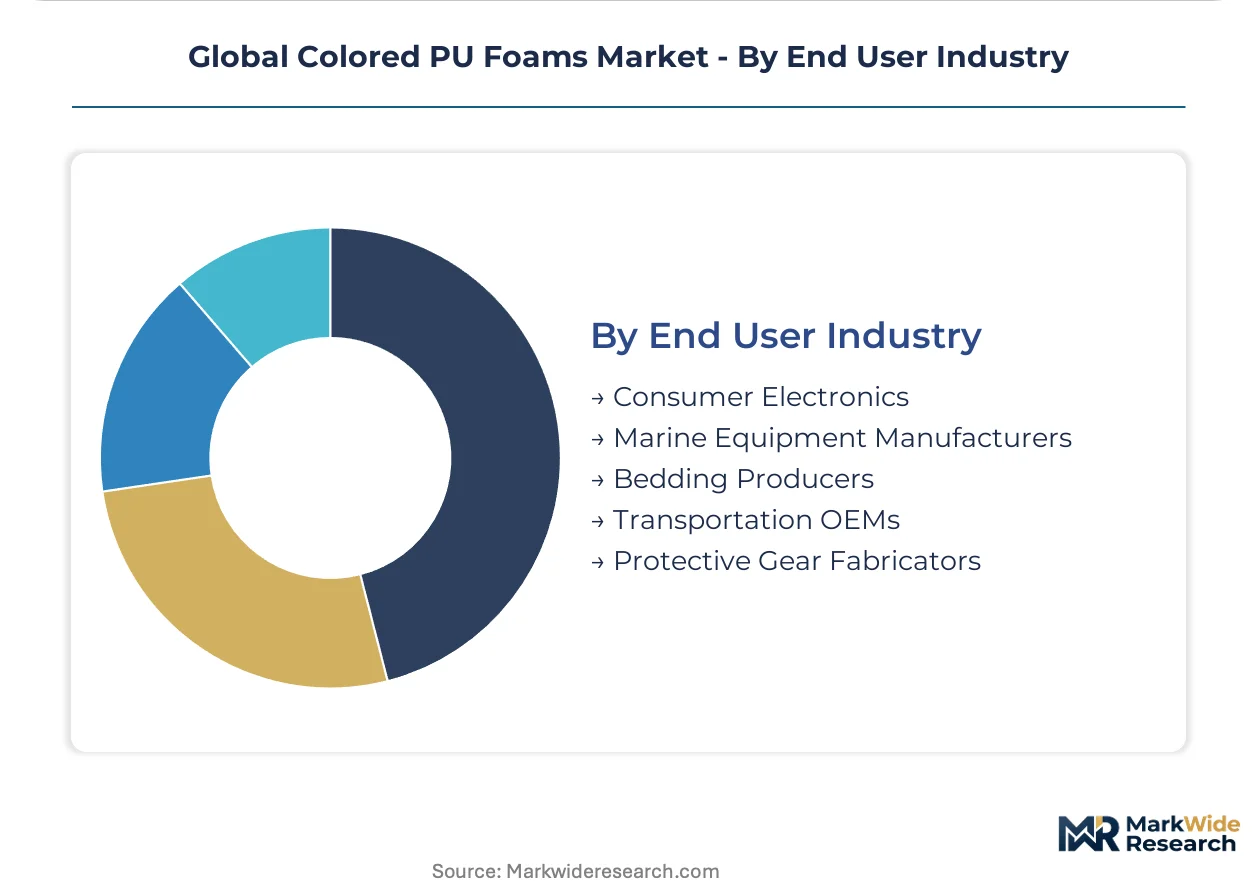
End User Industry:
Procurement scale and technical specification intensity vary sharply across industries, from high-volume bedding producers to low-volume marine equipment fabricators with custom color matching requirements.
- Transportation OEMs:Automotive and aerospace manufacturers impose the most stringent colorimetric tolerances and multi-jurisdiction chemical compliance burdens. German seat suppliers now require REACH-compliant reactive colorant platforms with full supply chain documentation.
- Bedding Producers:Mattress and pillow manufacturers drive the largest absolute volume demand, sourcing flexible and viscoelastic foams through consolidated purchasing agreements with integrated chemical producers.
- Consumer Electronics:Laptop and tablet enclosure manufacturers specify metallic-effect foams for paint-free assembly, with assembly lines concentrated in China's Jiangsu and Zhejiang provinces.
- Protective Gear Fabricators:Industrial safety and sports equipment producers balance visibility requirements against abrasion resistance in high-contact applications.
- Marine Equipment Manufacturers:Boat seating and flotation device producers face saltwater degradation challenges that limit eligible colorant chemistries and foam densities.
Volume accumulates with Bedding Producers; specification value concentrates with Transportation OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for colored PU foams concentrates in manufacturing clusters where automotive assembly and electronics production overlap with integrated chemical supply chains. China absorbs the largest absolute volumes through its eastern province chemical parks, while regulatory pressure in Germany and Japan drives premium specification growth.
China
Jiangsu and Zhejiang provinces host integrated PU chemical parks supplying downstream foam converters with customized color matching and just-in-time delivery. MEE enforcement of GB standards on volatile organic compound emissions compels domestic producers to reformulate colorant carrier systems. Direct mill integration through pipeline connections now replaces drum logistics for large converters serving consumer electronics supply chains.
Germany
Automotive interior designers in Germany expand purchases of certified colored foams for seat cushioning and dashboard applications under OEM sustainability scorecards. REACH chemical restrictions and evolving EU Green Deal standards tighten permissible pigment and blowing-agent chemistries, redirecting formulation strategies toward water-based colorants. Bavaria and Baden-Württemberg anchor production clusters where Tier-1 seat suppliers have compressed qualification cycles from five years to eighteen months.
United States
Medical device ergonomics for hospital bedding and wheelchair cushioning remain underpenetrated relative to European hospital systems, creating procurement expansion potential. EPA regulations under TSCA govern the import and manufacture of polymeric substances containing heavy-metal pigments. Michigan hosts specialized automotive color labs that match OEM interior palettes within Delta-E tolerances.
Japan
Automotive OEMs require certified colored foams for visible cabin components, expanding specification volumes for seat cushioning applications. METI oversight aligns with REACH-equivalent chemical management frameworks for substances of very high concern. Kanto and Kansai industrial corridors concentrate formulation expertise for reactive coloring technologies that reduce post-process dyeing steps.
India
Production-linked incentives under the PLI scheme attract foam converters to establish color compounding capabilities near electronics assembly zones. BIS standards on polyurethane product quality create certification thresholds for import substitution. Maharashtra and Gujarat emerge as primary destinations for capacity expansion serving domestic automotive and consumer goods manufacturing.
Global Colored PU Foams Market Competitive Landscape
Backward integration into captive polyol and isocyanate supply dominates the current landscape as chemical conglomerates tighten control over raw material color consistency. The vendor base stratifies into three tiers: integrated multinational chemical producers with molecule-to-slab control, specialized foam converters with OEM qualification relationships, and regional toll compounders facing elimination. Two competitive moves define positioning: strategic partnerships between pigment suppliers and PU chemical producers compressing distribution channels, and technology licensing agreements for reactive coloring platforms accelerating adoption timelines.
Within the integrated chemical producer tier, BASF SE and Covestro AG exemplify archetypes of upstream control and proprietary process technology respectively. Huntsman Corporation occupies a position bridging chemical production and specialized application expertise through automotive-focused color matching capabilities. Wanhua Chemical Group Co., Ltd. represents the scale-driven Asian producer archetype with domestic supply chain integration. These three companies anchor the competitive structure without exhausting the field.
| Leading Market Players |
|---|
| BASF SE |
| Covestro AG |
| Huntsman Corporation |
| Dow Inc |
| Wanhua Chemical Group Co., Ltd. |
| Rogers Corporation |
| Saint-Gobain Performance Plastics |
| Sekisui Chemical Co., Ltd. |
| Recticel NV/SA |
| Others |
Supply & Pricing Matrix
Automotive OEM sustainability scorecards mandating REACH-compliant reactive colorants are forcing foam converters to absorb multi-year qualification costs, compressing margins at the standard tier while premium certified variants capture pricing power through supply scarcity.
Pricing Analysis
Volume concentrates in standard-grade flexible foams for furniture and bedding where Chinese eastern chemical parks drive cost compression, while premium automotive and medical viscoelastic variants sustain margin buffers through Delta-E certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates REACH-certified reactive colorant platforms from conventional pigment systems and unqualified toll-compounded alternatives. Pricing pressure stems from raw material concentration at integrated polyol producers limiting independent converters' negotiating leverage. Bedding producers exhibit highest price sensitivity, while German and Japanese automotive seat suppliers prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs now mandate multi-supplier qualification for colorant platforms, extending procurement cycles but reducing single-source vulnerability. Supply concentrates in China, Germany, and Japan, with Jiangsu province chemical parks and Bavaria production clusters anchoring regional hubs. Formulation chemistry draws from captive isocyanate supply, specialty organic pigments, and water-based colorant dispersions. Tariff exposure on rare earth metal feedstocks for effect pigments creates input cost volatility. Distribution runs through direct mill integration with pipeline connections replacing drum logistics for large converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over captive polyol supply and in-house colorant dispersion capabilities determines margin capture and OEM qualification access.
For Market Incumbents: Lock in backward integration into isocyanate and polyol production to secure raw material color consistency from molecule to finished slab, while acquiring specialized spectrophotometry talent to defend against emerging toll compounders with reactive coloring technology licenses. REACH Annex XVII expansion timelines threaten reformulation cost spikes for non-integrated players. For New Entrants and Emerging Players: Begin with underpenetrated North American medical device ergonomics channels for viscoelastic colored foams, where hospital procurement remains less consolidated than European systems and certification barriers favor specialized formulators over commodity producers. A technical service-led go-to-market approach accelerates biocompatibility requalification timelines. For Investors and Strategic Acquirers: The window for entry favors mid-cap foam converters with existing OEM color-matching relationships and unintegrated pigment dispersion capabilities that integrated chemical conglomerates may acquire to compress channel structure. Watch for EU F-Gas Regulation phase-down acceleration as the inflection signal that triggers capital-intensive blowing agent retooling and consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Polyol Supply | BASF SE and Covestro AG control color consistency from raw molecule through finished slab specifications. |
| Reactive Coloring Technology Licensing | Covestro AG's proprietary platforms eliminate post-process dyeing steps for automotive OEMs. |
| Specialized Automotive Color Lab Expansion | Huntsman Corporation matches Delta-E tolerances for German and Japanese seat suppliers. |
| Direct Mill Integration with Pipeline Delivery | Jiangsu province converters replace drum logistics with pre-dispersed color concentrate connections. |
| Water-Based Colorant Platform Qualification | Tier-1 suppliers compress automotive OEM approval cycles from five years to eighteen months. |
Research Methodology
Multi-period observation of REACH restriction implementation timelines, EU F-Gas Regulation phase-down schedules, and automotive OEM sustainability scorecard adoption anchored the trend analysis, supplemented by interviews with foam plant managers, procurement leads at Tier-1 seat suppliers, distribution channel partners in China's eastern chemical parks, and technical R&D directors at pigment dispersion specialists. Secondary validation drew from ECHA regulatory filings, MEE GB standard enforcement records, customs and trade data, and SEC 10-K disclosures from integrated chemical producers. Bottom-up volume modeling across product type, color type, application, and end-user industry segments triangulated against top-down macroeconomic drivers.
Segment-weighting approaches assigned differential growth coefficients to flexible versus viscoelastic foam categories, metallic versus solid colorant platforms, and automotive interior versus furniture upholstery applications across the analysis window. CAGRs derived from regression analysis of historical shipment volumes and forward projection of regulatory compliance cost absorption. Industry-specific inputs included automotive OEM qualification cycle compression data and medical device biocompatibility re-testing delay patterns.
REACH Annex XVII expansion schedules, EU F-Gas Regulation acceleration triggers, and rare earth metal feedstock availability shocks are the dominant revision risks to modeled outputs. Deviation in automotive OEM sustainability mandate adoption timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Market