
 Asia-Pacific Geopolymer Market | 2026-2036
Asia-Pacific Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Geopolymer Market Insights
Infrastructure procurement agencies are gaining share over residential developers as the dominant buyer archetype in the Asia-Pacific geopolymer market is bifurcating between state-backed megaprojects and private commercial builds. Zeobond Pty Ltd leverages its Australian base to supply geopolymer binders for transport infrastructure across Queensland and New South Wales. Fujita Corporation anchors Japanese demand through specialized precast geopolymer components for seismic-resistant structures. Kiran Geopolymer dominates South Indian supply chains with in-house alkali-activation technology for fly ash-derived cement alternatives.
Geopolymers are inorganic alumino-silicate materials formed through alkali-activation of industrial byproducts such as fly ash or metakaolin, yielding ceramic-like matrices with compressive strengths exceeding 50 MPa and fire resistance above 1,000°C for structural and protective applications. The cement product category leads volume as infrastructure contractors specify geopolymer cement for mass concrete pours with lower embodied carbon than ordinary Portland cement. The 3D printing technology segment grows fastest as Chinese construction robotics firms integrate extrusion-based geopolymer deposition for affordable housing prototypes. Municipal end users concentrate margin pools through long-term maintenance contracts for sewer pipe rehabilitation and coastal defense structures.
China's MEE enforces dual carbon targets that restrict clinker production in Yangtze River Delta provinces, directly expanding geopolymer substitution quotas in state tender documents. India's BIS is drafting performance standards for alkali-activated binders under its green building certification pathway, while Australia's standards body mandates bushfire resistance ratings that geopolymer cladding satisfies. Stakeholders must monitor how procurement rule changes in China and India cascade through subcontractor tiers and reshape raw material qualification requirements for fly ash and slag suppliers.
Market Dynamics
State procurement mandates across China and India are redirecting infrastructure budgets toward alkali-activated binders, compressing ordinary Portland cement volumes in megaproject concrete specifications.
Growth Catalysts
- Dual carbon enforcement:China's MEE restricts clinker production in Yangtze River Delta provinces, expanding geopolymer substitution quotas in state tender documents for bridge and tunnel contracts.
- Fly ash valorization:Thermal power plants in eastern India generate feedstock surpluses that geopolymer manufacturers convert into ASTM C618-compliant pozzolanic binders for precast concrete.
- Seismic engineering specifications:Japan's Building Standard Law amendments favor ceramic-like matrices with fire resistance above 1,000°C for high-rise structural cores in Tokyo and Osaka corridors.
Market Restraints
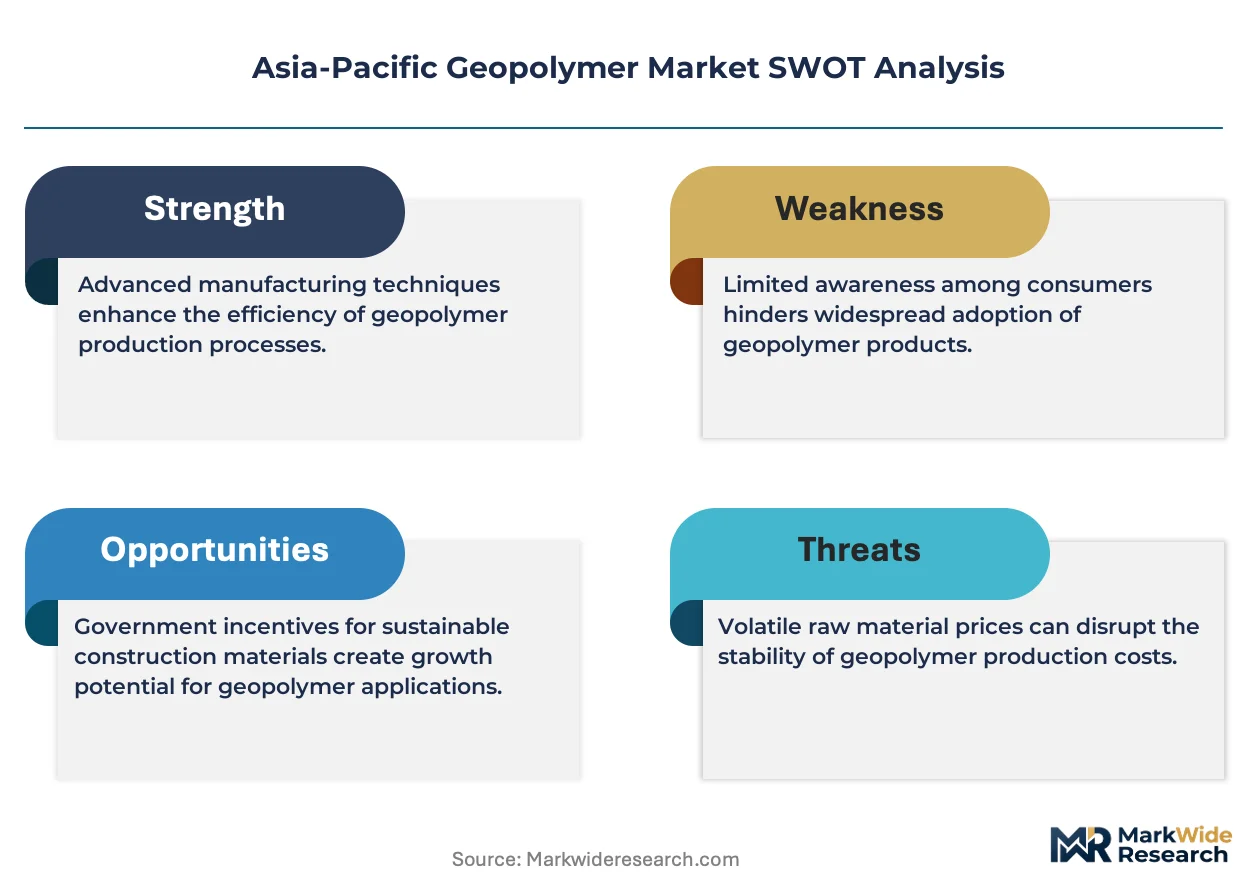
- Alkali activator cost volatility:Sodium silicate and sodium hydroxide prices fluctuate with energy costs, compressing margins for producers without captive chemical supply.
- Slag supply concentration:Steel mill output curbs in China's Hebei province restrict granulated blast furnace slag availability for binder formulations.
- Curing regime incompatibility:Ambient-temperature strength development remains slower than ordinary Portland cement, limiting adoption in cold-climate construction windows.
Strategic Opportunities
- 3D printing integration:Chinese construction robotics firms are extruding geopolymer pastes for affordable housing prototypes, opening deposition-speed optimization contracts.
- Coastal defense applications:Australia's TGA-equivalent building code mandates bushfire and salt-spray resistance that geopolymer cladding satisfies for Queensland waterfront developments.
- Western India corridor buildout:Mumbai-Ahmedabad high-speed rail viaduct specifications create volume anchors for alkali-activated concrete in Gujarat and Maharashtra states.
Industry Challenges
- Alkali-activation expertise scarcity:Formulation chemists with metakaolin and fly ash optimization experience command premium compensation, constraining producer scaling.
- BIS certification timelines:India's standards body has not finalized performance benchmarks for alkali-activated binders, delaying green building certification pathway approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Geopolymer Market |
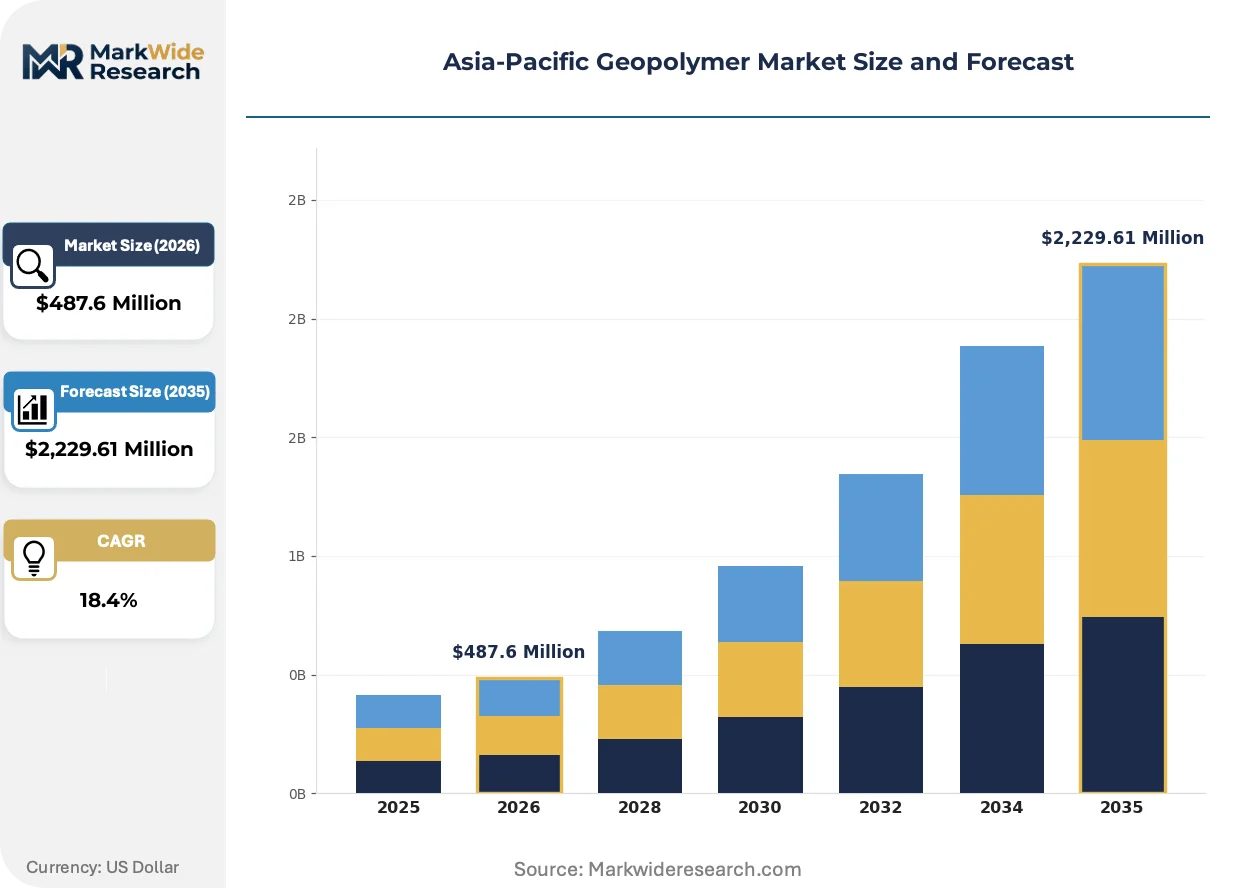
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Concrete, Mortar, Adhesive Application: Construction, Infrastructure, Pipe Manufacturing, Fire Protection End User: Residential, Commercial, Industrial, Municipal Technology: 3D Printing, Precast Manufacturing, Casting, Coating |
| Companies Covered | Betolar Plc, Kuttuva Silicates Private Limited, Zeobond Pty Ltd, Wagners, Mangla Redimix Pvt. Ltd, Fujita Corporation, Kiran Geopolymer, SLB (Schlumberger Limited), Solidia Technologies, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Geopolymer Market Trends and Innovations
Extrusion-based deposition systems and alkali-activation chemistry advances are compressing traditional casting cycles while regulatory carbon accounting tightens material qualification protocols.
Geopolymer 3D printing is displacing conventional formwork-dependent construction in Chinese affordable housing pilots. Construction robotics firms in Shenzhen and Hangzhou deploy gantry-mounted extruders that deposit fly ash-based pastes at rates exceeding 50 kg per minute. This displacement of timber and steel formwork eliminates curing-time bottlenecks that constrain conventional precast yard throughput.
India's BIS is drafting alkali-activated binder standards under its green building certification pathway, creating compliance infrastructure for state procurement agencies. The industrial consequence compresses qualification timelines for domestic fly ash suppliers seeking infrastructure contract eligibility. Western state public works departments in Maharashtra and Gujarat are pre-qualifying geopolymer concrete vendors ahead of formal standard publication.
Municipal maintenance departments are unbundling sewer pipe rehabilitation from integrated civil contractor scope, creating direct material supply relationships with geopolymer lining specialists. This channel restructuring displaces generalist contractor intermediaries in Australian and Japanese urban infrastructure markets. Tokyo Metropolitan Government's 10-year tunnel maintenance program exemplifies the shift toward specification-driven direct procurement of ceramic-like repair matrices.
Asia-Pacific Geopolymer Market Segmentation
Geopolymer formulation chemistry and activation protocols vary sharply across product categories, creating divergent qualification requirements for fly ash sourcing and alkali activator specifications. Regulatory carbon accounting in China and India increasingly ties procurement eligibility to segment-specific embodied carbon thresholds, compressing market access for uncertified formulations.
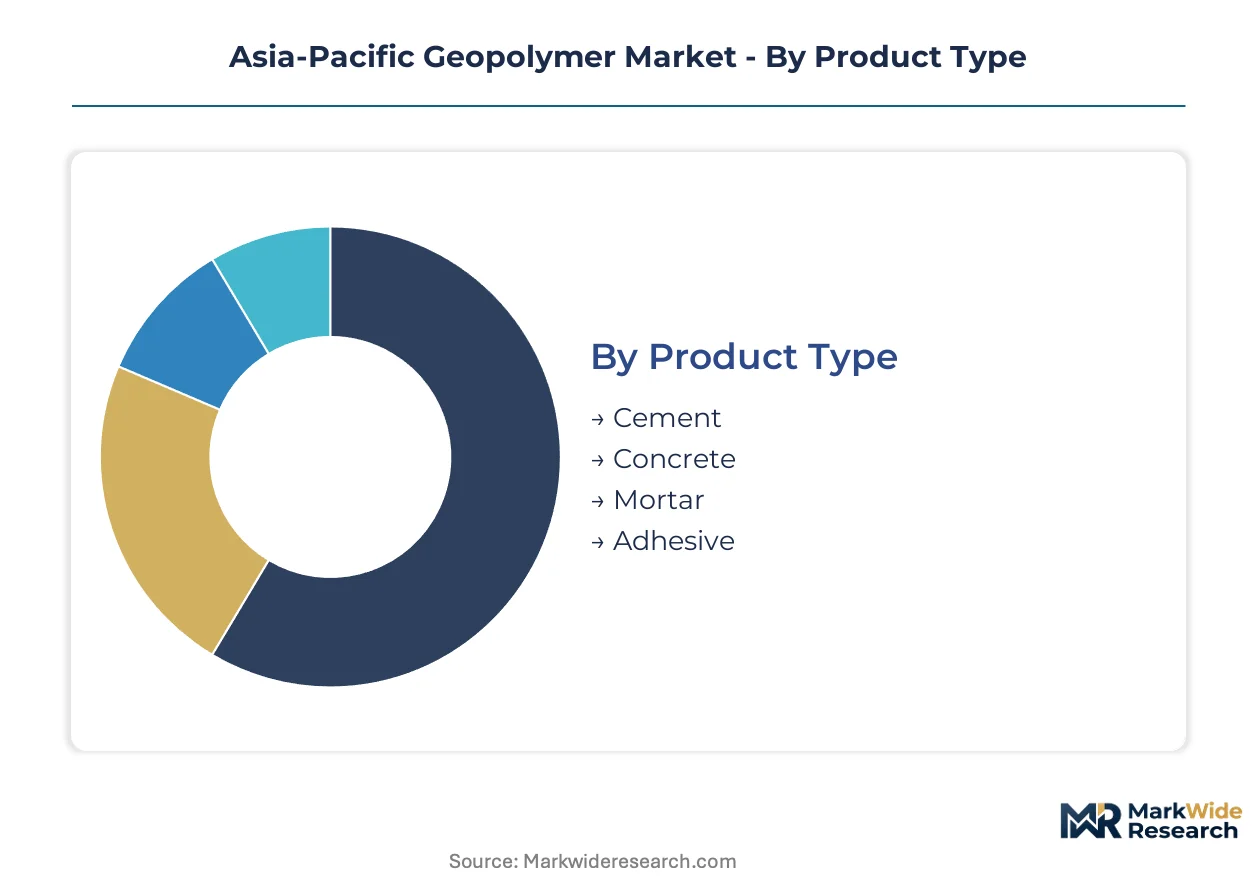
Product Type:
China's MEE enforces dual carbon targets that restrict clinker production in Yangtze River Delta provinces, directly expanding substitution quotas for low-carbon binder categories in state tender documents.
- Cement:Fly ash and slag-based binders displace ordinary Portland cement in carbon-intensive public works, with Yangtze River Delta megaprojects absorbing concentrated volume under MEE procurement mandates.
- Concrete:Mass concrete pours for bridge decks and tunnel linings specify this category for lower embodied carbon than conventional alternatives, with Mumbai-Ahmedabad corridor contracts driving western India demand.
- Mortar:Repair and rehabilitation applications in Japanese seismic zones favor ceramic-like matrices with compressive strengths exceeding 50 MPa.
- Adhesive:Specialized bonding layers for geopolymer cladding systems satisfy Australia's bushfire resistance ratings for Queensland waterfront developments.
Established volume favors cement; emerging adoption favors adhesive.
Application:
Cost tier differentiation separates specification-driven infrastructure procurement from price-sensitive commercial construction, with state-backed megaprojects commanding premium qualification standards.
- Construction:Affordable housing pilots in Shenzhen and Hangzhou deploy extrusion-based deposition systems that compress traditional casting cycles while eliminating timber formwork.
- Infrastructure:Bridge and tunnel contracts across Southeast Asia scale geopolymer procurement for elevated viaducts and subterranean linings, with state agencies gaining share over residential developers as dominant buyers.
- Pipe Manufacturing:Municipal maintenance departments unbundle sewer pipe rehabilitation from integrated civil contractor scope, creating direct supply relationships with lining specialists.
- Fire Protection:Japan's Building Standard Law amendments favor ceramic-like matrices with fire resistance above 1,000°C for high-rise structural cores in Tokyo and Osaka corridors.
Specification density clusters in infrastructure; manufacturing throughput concentrates in pipe applications.
End User:
Customer type bifurcation between state procurement agencies and private developers reshapes channel structures and margin pools across the value chain.
- Residential:Limited penetration due to slower ambient-temperature strength development compared to ordinary Portland cement, constraining adoption in cold-climate construction windows.
- Commercial:Private builds in eastern China absorb volume through precast component specifications, though margin compression from alkali activator cost volatility pressures producer scaling.
- Industrial:Thermal power plants in eastern India generate feedstock surpluses that manufacturers convert into ASTM C618-compliant pozzolanic binders for captive industrial use.
- Municipal:Long-term maintenance contracts for sewer pipe rehabilitation and coastal defense structures concentrate margin pools through specification-driven direct procurement, exemplified by Tokyo Metropolitan Government's tunnel maintenance program.
Procurement scale favors municipal; margin sustainability favors commercial.
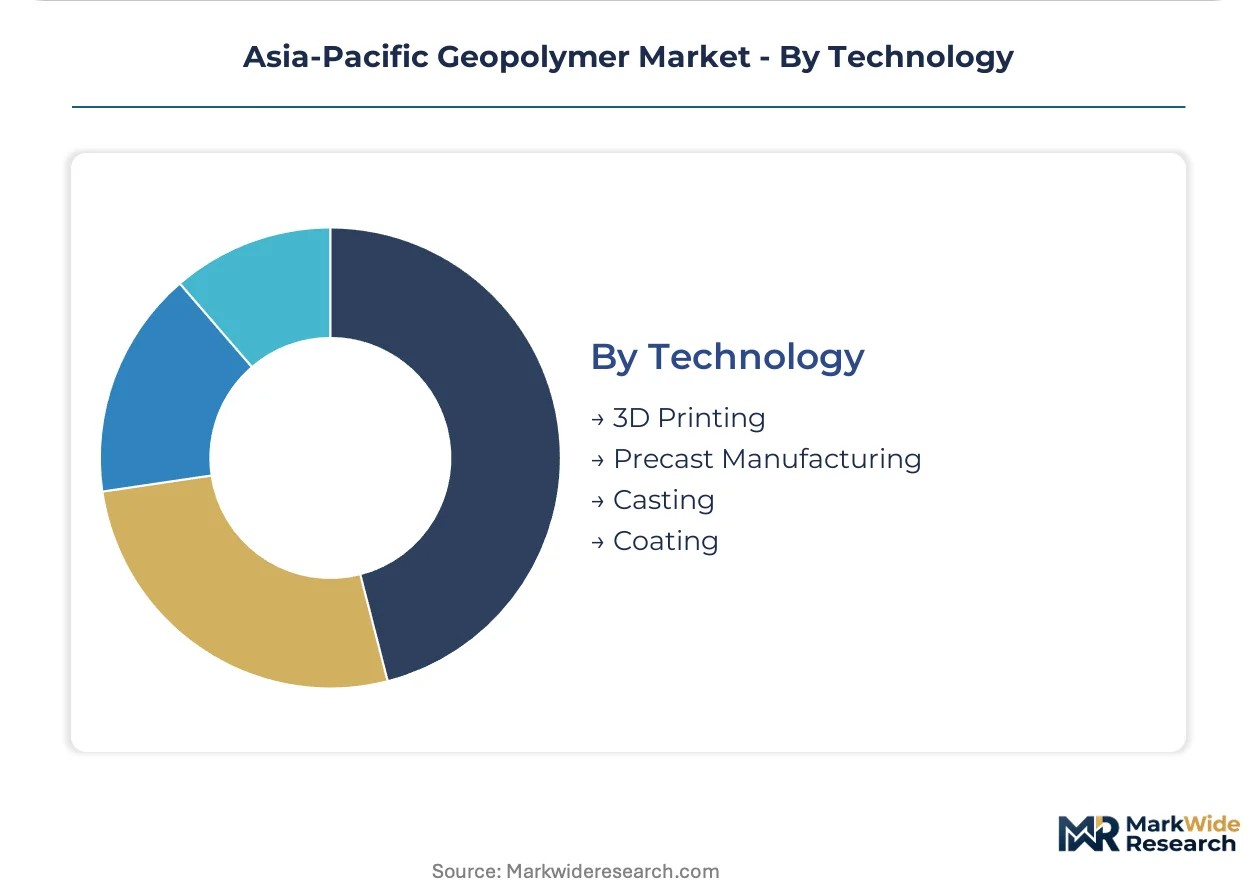
Technology:
Manufacturing maturity separates established precast yard processes from emerging deposition systems that eliminate curing-time bottlenecks.
- 3D Printing:Chinese construction robotics firms integrate extrusion-based geopolymer deposition for affordable housing prototypes, with gantry-mounted extruders depositing fly ash-based pastes at rates exceeding 50 kg per minute.
- Precast Manufacturing:Fujita Corporation anchors Japanese demand through specialized geopolymer components for seismic-resistant structures, leveraging controlled curing environments to overcome ambient-temperature limitations.
- Casting:Conventional formwork-dependent methods persist in Indian western states where BIS certification timelines delay green building certification pathway approvals for novel processes.
- Coating:Cladding applications for Queensland waterfront developments require bushfire and salt-spray resistance that geopolymer formulations satisfy under Australian building code mandates.
Process reliability anchors precast; steepest expansion trajectory attaches to 3D printing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian geopolymer specialists export alkali-activated binders to Southeast Asian infrastructure agencies specifying low-carbon concrete for bridge decks and tunnel linings across Queensland and New South Wales transport corridors.
China
Yangtze River Delta megaprojects absorb concentrated geopolymer volume for mass concrete pours as MEE dual carbon enforcement restricts clinker production across Jiangsu and Zhejiang provinces. State tender documents now mandate substitution quotas for fly ash-based binders in elevated viaduct contracts. Shenzhen and Hangzhou construction robotics firms deploy extrusion-based deposition systems for affordable housing prototypes.
India
Thermal power plants in eastern states generate fly ash feedstock surpluses that western manufacturers convert into pozzolanic binders for Mumbai-Ahmedabad corridor specifications. BIS is drafting performance standards for alkali-activated binders under green building certification pathways. Maharashtra and Gujarat public works departments pre-qualify geopolymer concrete vendors ahead of formal standard publication.
Japan
Seismic-resistant structural cores in Tokyo and Osaka corridors demand ceramic-like matrices with fire resistance above 1,000°C. Building Standard Law amendments favor geopolymer formulations for high-rise applications. Fujita Corporation anchors domestic demand through specialized precast components manufactured in controlled curing environments.
Australia
Queensland waterfront developments specify geopolymer cladding satisfying TGA-equivalent bushfire and salt-spray resistance mandates. Zeobond Pty Ltd supplies transport infrastructure across New South Wales under state procurement frameworks prioritizing low-carbon alternatives. Coastal defense structures in southeastern states concentrate maintenance contract volumes.
South Korea
Industrial byproduct valorization programs in steel-producing regions generate slag feedstock for binder formulations. National construction standards increasingly reference alkali-activated materials in public works specifications. Seoul Capital Area infrastructure agencies pilot geopolymer concrete for subway tunnel rehabilitation projects.
Asia-Pacific Geopolymer Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and regional distribution networks. The vendor base clusters around three tiers: multinational chemical conglomerates with captive alkali activator supply, regional construction material specialists with fly ash sourcing advantages, and technology licensors with proprietary activation protocols. Consolidation pressures favor players controlling both feedstock procurement and formulation chemistry. Dominant competitive moves include backward integration into industrial byproduct sourcing and strategic partnerships with state procurement agencies.
Among Asia-Pacific specialists, Zeobond Pty Ltd and Kiran Geopolymer occupy positions within the regional feedstock-integrated tier, while Fujita Corporation exemplifies the precast manufacturing archetype serving seismic engineering specifications. Wagners represents Australian-scale producers with transport infrastructure concentration. These anchors illustrate how geographic proximity to fly ash generation or steel slag output shapes competitive positioning.
| Leading Market Players |
|---|
| Betolar Plc |
| Kuttuva Silicates Private Limited |
| Zeobond Pty Ltd |
| Wagners |
| Mangla Redimix Pvt. Ltd |
| Fujita Corporation |
| Kiran Geopolymer |
| SLB (Schlumberger Limited) |
| Solidia Technologies |
| Others |
Pricing and Supply Chain Analysis
China's MEE dual carbon enforcement gates both supplier qualification and price differentiation simultaneously, as state tender documents mandate substitution quotas that only certified fly ash and slag-based binder producers can satisfy. This regulatory architecture compresses margin pools for uncertified competitors while concentrating pricing power among feedstock-integrated manufacturers.
Pricing Analysis
Conventional casting technology commands economy-tier positioning against precast manufacturing's standard-tier premiums, while 3D printing deposition systems anchor emerging premium pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with municipal procurement contracts least sensitive to unit cost and residential developers most price-constrained. Cost compression in economy tiers is intensifying because alkali activator price volatility erodes margins for non-integrated producers.
Supply Chain Analysis
Strait of Malacca transit underwrites granulated blast furnace slag flows from Chinese steel mills to Southeast Asian binder manufacturers. Supply concentrates in China, India, and Australia, with raw material dependencies centering on fly ash from thermal power plants, sodium silicate from chemical processors, and metakaolin from calcined clay operations. Single-source vulnerability runs through Hebei province slag output curbs. Distribution runs through state procurement agencies and direct municipal maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific geopolymer market is recovering from alkali-activation expertise scarcity constraints, with China's dual carbon enforcement and India's PLI scheme for green construction materials providing cyclical uplift through state-backed infrastructure procurement.
For Market Incumbents: Shield margin pools by securing captive fly ash supply through backward integration into thermal power plant partnerships, and invest in BIS pre-certification ahead of formal alkali-activated binder standard publication to lock out emerging competitors. For New Entrants and Emerging Players: Technical formulation services for small-scale precast yards represent an underserved layer where incumbents under-serve, creating white-space targets in Gujarat and Maharashtra states ahead of Mumbai-Ahmedabad corridor contract awards. Target 3D printing deposition optimization contracts with Shenzhen construction robotics firms as the most penetrable entry vector. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across 3D printing technology segments as extrusion hardware commoditizes. Long-term viability over the next decade favors acquisition targets combining in-house alkali-activation chemistry with established state procurement relationships. Watch BIS certification timeline acceleration as the inflection signal for Indian market access liberalization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fly Ash Supply | Secures feedstock certainty for Yangtze River Delta megaproject contracts under MEE quotas. |
| 3D Printing Deposition Speed Optimization | Unlocks affordable housing prototype contracts with Shenzhen and Hangzhou robotics firms. |
| BIS Pre-Certification Investment | Positions vendors for Maharashtra and Gujarat public works department qualification ahead of formal standards. |
| Seismic Engineering Certification Pathway | Opens Tokyo and Osaka corridor high-rise structural core specifications under amended Building Standard Law. |
| Long-Term Municipal Maintenance Contracts | Concentrates margin pools through direct supply relationships with Tokyo Metropolitan Government tunnel programs. |
Research Methodology
Operator-level perspectives from geopolymer formulation chemists, state procurement officers at infrastructure agencies, thermal power plant ash sales managers, and precast yard operations directors anchored the qualitative base. Primary interviews combined with secondary validation from China MEE tender document archives, India BIS draft standard publications, Japan Ministry of Land, Infrastructure, Transport and Tourism construction notices, and Australia Building Code amendment records. Bottom-up volume modeling and top-down regulatory impact triangulation cross-checked segment assumptions.
Sensitivity analysis tested alkali activator cost volatility scenarios and slag supply disruption impacts across the projection horizon. Segmentation dimensions modeled include product chemistry, application type, end-user category, and technology generation tier. CAGRs derived from infrastructure contract pipeline analysis and green building certification pathway adoption curves, with fly ash availability indices and clinker production restriction schedules as industry-specific forecast inputs.
Forecasts assume regulatory continuity in China's dual carbon enforcement and India's PLI scheme for green construction materials; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as BIS certification timeline delays and Hebei province steel output curbs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
India Engineering Plastics Market
Polymers & Resins
Solid State Resins Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Indonesia Flooring Resins Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market