
 Medical Polyoxymethylene (POM) Market | 2026-2036
Medical Polyoxymethylene (POM) Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Polyoxymethylene (POM) Market Foresight
Medical-grade copolymer specifications is unwinding upward price elasticity as OEMs demand ISO 10993-compliant feedstock with tighter formaldehyde emission thresholds. Celanese Corporation leverages its captive acetal resin technology to secure long-term supply agreements with European device makers. Mitsubishi Chemical Corporation anchors Asia-Pacific production through integrated formaldehyde-to-POM chains that sustain margin stability against volatile methanol costs.
Medical Polyoxymethylene denotes a high-crystallinity engineering thermoplastic with a melting point near 165°C, manufactured via anionic polymerization of formaldehyde or trioxane to yield chains with exceptional dimensional stability and low friction coefficients for precision medical components. Copolymer grades command the largest volume share due to superior thermal stability and hydrolysis resistance during steam sterilization cycles, while reinforced POM variants with glass or mineral fillers penetrate orthopedic implant tooling where creep resistance under cyclic loading determines instrument lifespan. Drug delivery systems represent the fastest-expanding application segment as pen injectors and inhaler housings migrate from metal to polymer to reduce unit weight and enable complex snap-fit geometries.
FDA 21 CFR Part 177.2470 and EU MDR Class IIa-III device regulations shape material qualification timelines, with notified bodies demanding exhaustive extractables and leachables profiles before commercial release. ISO 10993-5 cytotoxicity and USP Class VI biocompatibility certifications function as non-negotiable market access gates that filter out commodity-grade POM suppliers. Stakeholders must monitor evolving ECHA SVHC candidate list expansions for formaldehyde-related substances that could trigger REACH authorization requirements and disrupt existing formulation portfolios.
Market Dynamics
ISO 10993 biocompatibility certification timelines are compressing commercialization windows for medical-grade POM formulations, forcing resin suppliers to pre-validate copolymer grades against cytotoxicity and extractables profiles before OEM engagement.
Growth Catalysts
- FDA 21 CFR Part 177.2470 compliance mandates:Device manufacturers must source polymer feedstock with documented biocompatibility, creating captive demand for certified medical-grade copolymers over commodity alternatives.
- Minimally invasive surgical instrument proliferation:Laparoscopic and robotic-assisted platforms require precision-molded polymer components with tight dimensional tolerances that POM delivers through injection molding.
- Steam sterilization cycle durability requirements:Hospital central sterile processing departments prioritize copolymer grades that withstand repeated autoclave exposure without hydrolytic degradation.
Market Restraints
- Formaldehyde feedstock volatility:Methanol price swings transmit directly into trioxane monomer costs, squeezing margin stability for non-integrated POM producers.
- ECHA SVHC candidate list expansion:Formaldehyde-related substance scrutiny under REACH authorization procedures threatens formulation continuity for existing medical-grade portfolios.
- High-performance polymer substitution:PEEK and polysulfone alternatives penetrate orthopedic implant tooling where creep resistance under cyclic loading exceeds POM mechanical limits.
Strategic Opportunities
- Home healthcare device expansion:Pen injectors and inhaler housings for diabetes and respiratory therapies migrate from metal to polymer to reduce unit weight and enable complex snap-fit geometries.
- EU MDR Class IIa-III device reclassification:Stricter notified body oversight accelerates demand for pre-certified resin grades with exhaustive extractables documentation.
- Additive manufacturing convergence:Selective laser sintering of POM powders enables patient-specific surgical guides and fixation tooling with geometries impossible through conventional molding.
Industry Challenges
- ISO 17025 laboratory accreditation scarcity:Limited third-party testing capacity for USP Class VI and cytotoxicity validation extends qualification timelines by six to twelve months.
- Legacy molding equipment retrofit costs:Medical-grade copolymer processing requires tighter temperature control and contamination protocols that demand capital-intensive press upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Polyoxymethylene (POM) Market |
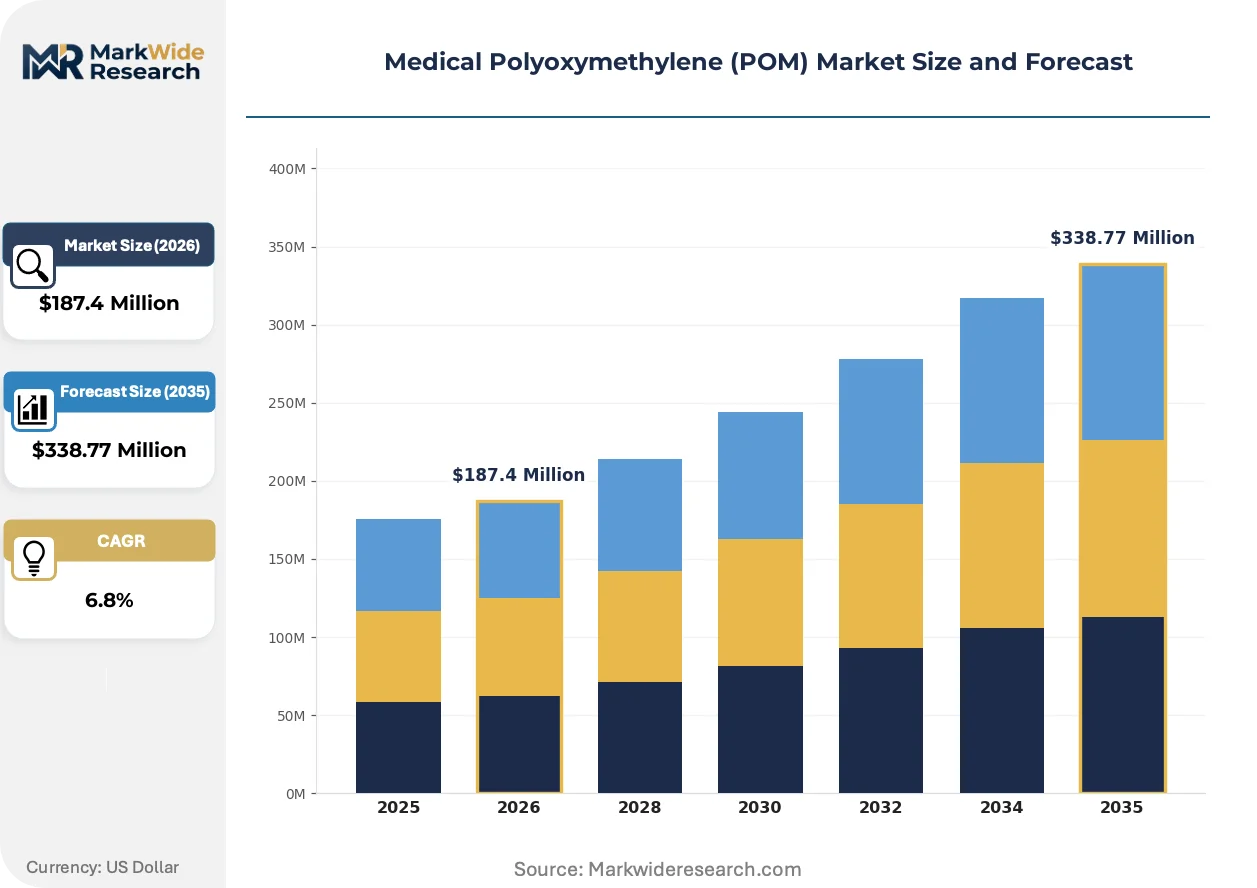
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
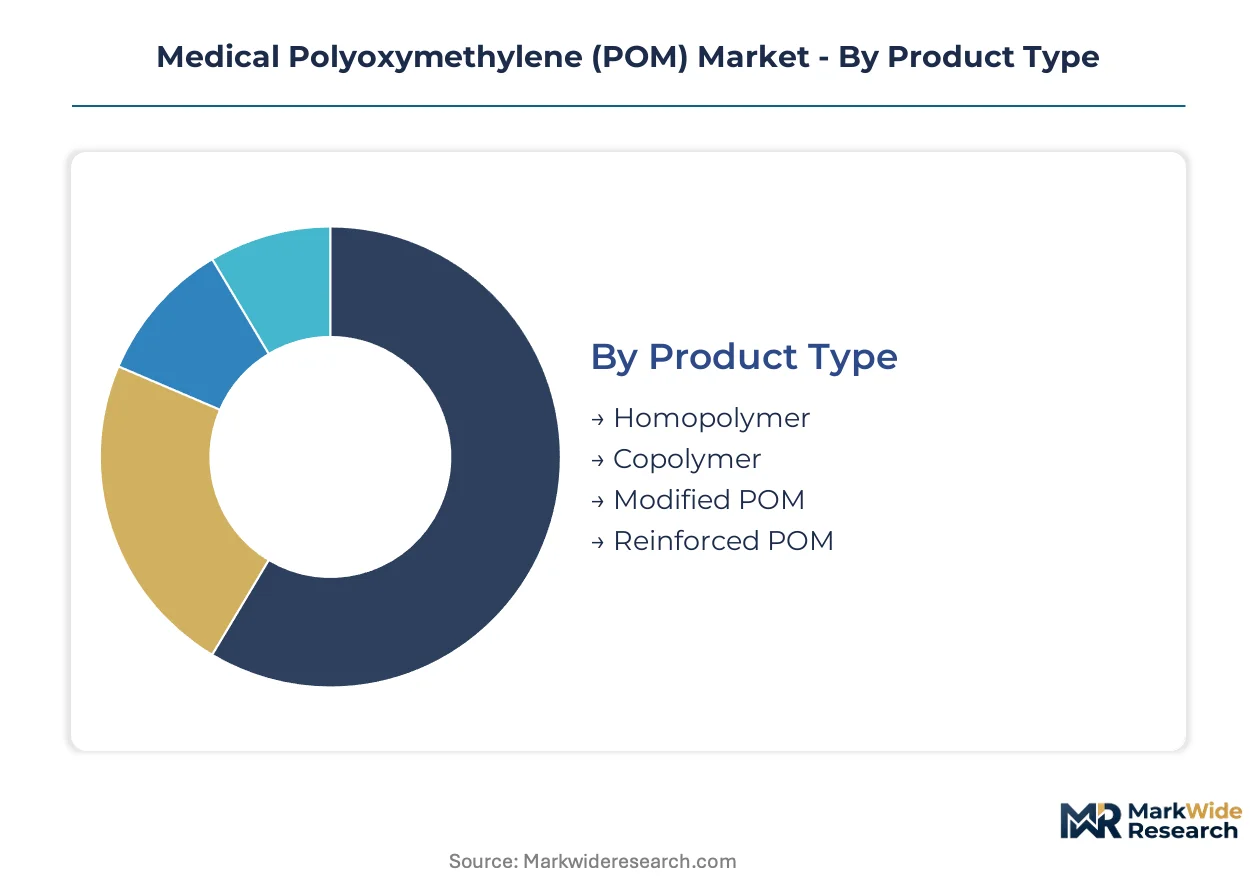
| Segmentation | Product Type: Homopolymer, Copolymer, Modified POM, Reinforced POM Application: Medical Devices, Surgical Instruments, Drug Delivery Systems, Orthopedic Implants End User: Hospitals, Clinics, Research Laboratories, Rehabilitation Centers Delivery Mode: Injection Molding, Extrusion, 3D Printing, Machining |
| Companies Covered | Mitsubishi Chemical Corporation, LG Chem, Celanese Corporation, Asahi Kasei Corporation, Daicel Corporation, BASF SE, DuPont de Nemours, Inc., Korea Engineering Plastics Co., Ltd., Polyplastics Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Polyoxymethylene (POM) Market Shifts & Advancements
Material qualification protocols are accelerating convergence between resin chemistry, regulatory documentation, and precision manufacturing capabilities across the medical device supply chain.
Copolymer-grade POM is bifurcating the market between steam-sterilizable surgical instruments and single-use drug delivery devices. German device manufacturers are adopting higher-molecular-weight formulations for reusable orthopedic tooling, while US pen-injector producers specify lower-viscosity grades optimized for thin-wall molding. This technical segmentation is compressing pricing coherence across what historically functioned as a unified commodity category.
EU MDR technical documentation requirements are reshaping supplier-OEM relationships throughout Europe. Notified bodies now demand batch-specific extractables profiles and formaldehyde emission testing that exceed legacy ISO 10993-5 screening protocols. Small-to-mid device manufacturers in Italy and Spain are consolidating resin purchasing to suppliers with established European Authorized Representative structures and pre-validated regulatory files.
Contract sterilization service unbundling is altering procurement patterns for POM component buyers. Hospital systems and third-party sterilizers now specify resin grades with validated reprocessing limits rather than delegating material selection to device OEMs. This certification-driven preference shift concentrates volume with suppliers offering dedicated medical-grade product lines with published autoclave cycle data, particularly visible in Benelux and Scandinavian healthcare procurement clusters.
Medical Polyoxymethylene (POM) Market Segmentation
Medical POM procurement channels diverge sharply between sterilizable reusable instruments and single-use drug delivery components. Device OEMs source copolymer grades through qualified resin distributors with ISO 13485 warehousing, while hospital systems increasingly mandate direct supplier relationships for extractables documentation.
Product Type:
Channel access separates commodity-grade distributors from medical-certified direct supply agreements.
- Copolymer:Superior thermal stability and hydrolysis resistance during repeated steam sterilization cycles make this the default specification for reusable surgical instruments. German orthopedic device manufacturers specify higher-molecular-weight copolymer grades for instrument handles and fixation tooling that withstands central sterile processing department protocols.
- Homopolymer:Higher crystallinity yields greater stiffness and tensile strength for precision-molded components requiring tight dimensional tolerances. US pen-injector producers favor homopolymer for thin-wall housing geometries where snap-fit assembly demands exact creep resistance.
- Modified POM:Lubricant and UV-stabilized variants serve specific drug delivery applications requiring reduced friction coefficients.
- Reinforced POM:Glass and mineral filler grades penetrate orthopedic implant tooling where cyclic loading resistance exceeds unfilled polymer limits.
Copolymer dominates installed base. Homopolymer is where expansion concentrates.
Application:
End-use requirements dictate resin specification tiers from Class IIa to Class III device standards.
- Drug Delivery Systems:Pen injectors, inhaler housings, and auto-injector components migrate from metal to polymer to reduce unit weight and enable complex multi-part snap-fit geometries. FDA 21 CFR Part 177.2470 compliance mandates documented biocompatibility for these patient-contact devices.
- Surgical Instruments:Laparoscopic and robotic-assisted platforms require precision-molded polymer grips, seals, and articulation components with tight dimensional tolerances. EU MDR technical documentation requirements now demand batch-specific extractables profiles exceeding legacy ISO 10993-5 screening.
- Medical Devices:Diagnostic housings and fluid management components utilize standard medical-grade copolymer formulations.
- Orthopedic Implants:Instrumentation and trial components employ reinforced grades where creep resistance under cyclic loading determines surgical tool lifespan.
Surgical instruments command the largest volume share. Drug delivery systems are climbing the fastest.
End User:
Procurement authority patterns split between centralized hospital supply chains and decentralized clinic purchasing.
- Hospitals:Central sterile processing departments specify resin grades with validated autoclave cycle limits, concentrating volume with suppliers offering published reprocessing data. Benelux and Scandinavian healthcare procurement clusters lead this certification-driven preference shift.
- Clinics:Outpatient surgical centers prioritize single-use disposables over sterilizable reusables, favoring lower-viscosity copolymer grades optimized for high-volume injection molding.
- Research Laboratories:Preclinical device development consumes small-lot certified resin for prototype validation and regulatory submission batches.
- Rehabilitation Centers:Patient-mobility device components utilize standard medical-grade formulations with lower certification burdens.
Hospitals anchor procurement volume. Clinics are gaining share fastest.
Delivery Mode:
Manufacturing process selection determines resin viscosity specifications and supplier technical service requirements.
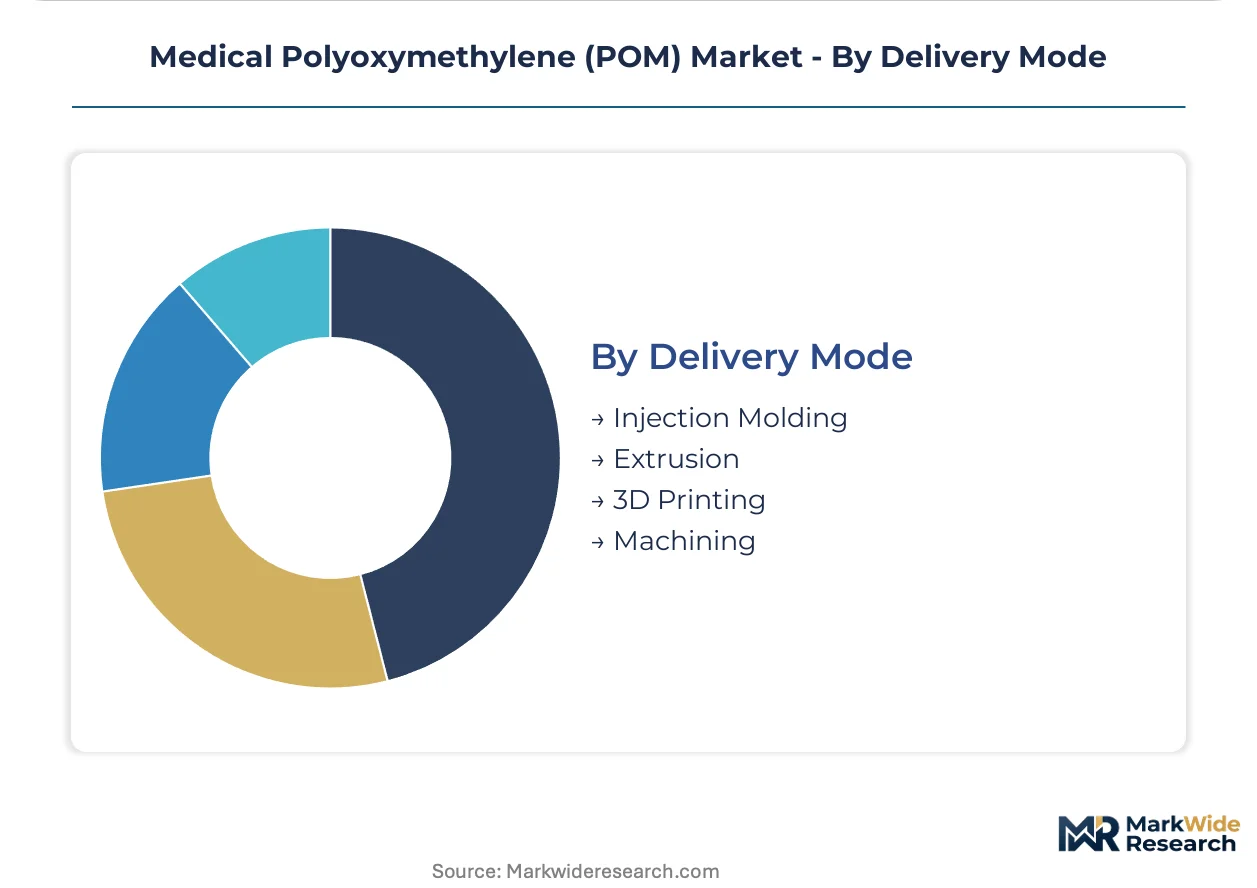
- Injection Molding:Dominant conversion method for precision medical components requiring tight dimensional tolerances and complex geometries. Medical-grade copolymer processing demands tighter temperature control and contamination protocols that drive capital-intensive press upgrades.
- Extrusion:Tubing and profile applications for fluid management and catheter components utilize melt-stabilized copolymer grades.
- 3D Printing:Selective laser sintering of POM powders enables patient-specific surgical guides and fixation tooling with geometries impossible through conventional molding.
- Machining:Stock shape conversion serves low-volume orthopedic instrument prototyping and custom surgical tool modifications.
Injection molding dominates installed base. 3D printing is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for medical-grade POM tightens most acutely in Germany and the United States where ISO 10993 certification premiums command buyer acceptance, while Asian procurement clusters in China and South Korea retain higher substitution sensitivity toward commodity-grade alternatives.
United States
Pen-injector manufacturers in Massachusetts and New Jersey drive homopolymer specifications for thin-wall diabetes device housings. FDA 21 CFR Part 177.2470 compliance mandates documented biocompatibility that filters out uncertified resin suppliers. Minneapolis medical device clusters concentrate procurement authority with sterilization-validated copolymer grades.
Germany
Orthopedic instrument OEMs in Bavaria and Baden-Württemberg specify higher-molecular-weight copolymers for reusable surgical tooling. EU MDR technical documentation requirements now demand batch-specific extractables profiles exceeding legacy ISO 10993-5 screening. Frankfurt-area sterilization service providers unbundle material selection from device OEMs.
China
Domestic drug delivery device producers in Jiangsu and Zhejiang provinces expand POM adoption for inhaler and auto-injector components. NMPA biocompatibility regulations tighten alignment with ISO 10993 standards for Class II device registrations. Shanghai medical polymer distributors consolidate toward direct supplier relationships with extractables documentation.
Japan
Precision molding houses in Aichi and Shizuoka prefectures supply minimally invasive surgical instrument components for export markets. PMDA pharmaceutical device regulations harmonize with FDA and EU MDR standards for polymer qualification timelines. Osaka chemical traders anchor Asia-Pacific distribution for medical-grade copolymer feedstock.
South Korea
Contract manufacturers in Gyeonggi-do and Incheon free economic zones produce pen injectors for global diabetes therapy brands. MFDS medical device regulations accelerate pre-certification requirements for resin suppliers entering domestic supply chains. Seoul-based medical polymer distributors emphasize ISO 17025 laboratory partnerships for cytotoxicity validation.
Medical Polyoxymethylene (POM) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the medical POM supply base. Integrated formaldehyde-to-POM producers command margin stability against methanol volatility, while non-integrated compounders compete on formulation flexibility and regional logistics. Three archetypes dominate: captive resin technology holders, regional distribution-technical service specialists, and precision molding-integrated device suppliers. Competitive intensity concentrates on long-term supply agreements with documented regulatory files and capacity expansion for medical-grade copolymer lines.
Within the integrated technology tier, Celanese Corporation and Mitsubishi Chemical Corporation exemplify archetypes of upstream control over acetal resin production. BASF SE and DuPont de Nemours, Inc. occupy positions spanning engineering polymer portfolios with medical certification infrastructure. Polyplastics Co., Ltd. and Korea Engineering Plastics Co., Ltd. represent Asia-Pacific production anchors serving regional device manufacturing clusters.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| LG Chem |
| Celanese Corporation |
| Asahi Kasei Corporation |
| Daicel Corporation |
| BASF SE |
| DuPont de Nemours, Inc. |
| Korea Engineering Plastics Co., Ltd. |
| Polyplastics Co., Ltd. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day ISO 10993 certification lead-times concentrate pricing power with integrated resin producers holding captive formaldehyde-to-POM chains, while non-integrated compounders absorb margin compression from volatile methanol feedstock costs. Hospital procurement clusters in Germany and the United States now mandate batch-specific extractables documentation that filters uncertified suppliers from qualified vendor lists.
Pricing Analysis
After-sales revenue from sterilization-revalidation services and regulatory file maintenance drives lifetime value for medical-grade POM suppliers. Three-tier pricing structure across ISO 10993-certified premium grades, standard medical copolymers, and economy commodity alternatives stratifies the market. Cost compression in economy tiers intensifies because Asian drug delivery device producers substitute toward lower-specification homopolymer alternatives. Price-sensitive outpatient clinics in Southern Europe favor uncertified commodity grades, while FDA-mandated device manufacturers in Massachusetts and New Jersey absorb premium certification markups without volume elasticity.
Supply Chain Analysis
Ninety-day inventory buffers for trioxane monomer feedstock tether medical-grade POM production to integrated chemical complexes in Germany, Japan, and the United States. Raw material flows draw from methanol-to-formaldehyde crackers, acetal resin polymerization units, and ISO 17025-certified compounding facilities. Single-source vulnerability concentrates in European formaldehyde derivative supply following ECHA SVHC candidate list expansions. Distribution runs through qualified resin distributors with ISO 13485 warehousing and direct supplier relationships for extractables documentation.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 17025 laboratory accreditation scarcity for USP Class VI and cytotoxicity validation compresses commercialization timelines, creating asymmetric returns for stakeholders controlling certified testing infrastructure or pre-validated regulatory files.
For Market Incumbents: Consolidate long-term supply agreements with European device makers by embedding European Authorized Representative structures and batch-specific extractables documentation. Expand captive acetal resin capacity in Germany or the United States to defend margin position against methanol volatility. Pre-validate copolymer grades against evolving EU MDR technical documentation requirements before notified body engagement. For New Entrants and Emerging Players: Differentiate on rapid-regulatory-file delivery for small-to-mid Italian and Spanish device manufacturers consolidating resin purchasing. Target home healthcare pen-injector producers in Massachusetts and New Jersey seeking lower-viscosity homopolymer grades optimized for thin-wall molding. Pursue direct supplier relationships bypassing qualified distributor markups through ISO 13485 warehousing investments. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with undermonetized medical-grade POM product lines lacking dedicated regulatory affairs infrastructure. Long-term viability hinges on backward integration into formaldehyde feedstock and certification capacity expansion across the projection horizon. Watch ECHA SVHC candidate list formaldehyde-related substance determinations as inflection indicators for formulation portfolio disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Formaldehyde Feedstock | Celanese and Mitsubishi Chemical anchor margin stability against methanol volatility through captive trioxane production. |
| ISO 17025 Laboratory Accreditation Expansion | Third-party cytotoxicity validation capacity scarcity extends qualification timelines six to twelve months for non-integrated entrants. |
| European Authorized Representative Structure Deployment | Notified body oversight consolidation favors suppliers with pre-established EU MDR technical documentation capabilities. |
| Long-term Supply Agreement with Extractables Documentation | Hospital procurement clusters in Benelux and Scandinavia mandate published autoclave cycle data and batch-specific testing. |
| Selective Laser Sintering Powder Development | Additive manufacturing convergence enables patient-specific surgical guides with geometries impossible through conventional injection molding. |
Research Methodology
Cross-validation between primary interviews with resin procurement managers, biomedical engineers at orthopedic device OEMs, and regulatory affairs leads at notified bodies anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, and customs trade data for formaldehyde derivative flows. Bottom-up demand modeling from pen-injector and surgical instrument production volumes triangulates with top-down chemical industry capacity assessments.
Sensitivity analysis across copolymer grade penetration scenarios, steam sterilization cycle durability assumptions, and ECHA SVHC candidate list expansion probabilities shapes the analytical framework. Segmentation dimensions span product type, application tier, end-user procurement authority, and delivery mode conversion method. CAGRs derive from installed base erosion rates for metal components and polymer substitution elasticity in drug delivery device design.
Forecasts assume regulatory continuity in FDA 21 CFR Part 177.2470 and EU MDR Class IIa-III device frameworks; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Nylon 66 Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Global VAE Emulsion Market