
 Photocurable Resins Market | 2026-2036
Photocurable Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Photocurable Resins Market Analytics
Material-as-a-service subscription models for photopolymer inventory management is restructuring how manufacturers procure resin systems. BASF SE leverages its integrated monomer-to-oligomer pipeline to control raw material costs across European coating applications. Evonik Industries AG anchors its position through R&D intensity in specialty methacrylates for medical-grade formulations. Henkel AG & Co. KGaA dominates electronics assembly adhesives through direct technical service relationships with Asian OEMs.
Photocurable resins are liquid oligomer systems containing reactive functional groups that polymerize upon exposure to UV, LED, or electron beam radiation, typically achieving full cure in seconds to minutes depending on initiator concentration and irradiance. Their primary industrial purpose centers on enabling solvent-free, energy-efficient manufacturing across coating, joining, and additive fabrication processes. Acrylate formulations lead volume consumption due to their rapid reactivity and broad compatibility with UV-LED curing equipment, while epoxy segments command margin pools in semiconductor encapsulation and high-reliability electronics. Thiol-ene systems represent the fastest-growing chemistry subset, driven by oxygen insensitivity and reduced shrinkage in precision 3D printing applications.
EPA regulates volatile organic compound emissions from UV-curable coatings through National Emission Standards for Hazardous Air Pollutants, while REACH restricts certain photoinitiators and monomers in European formulations. FDA 21 CFR Part 175 indirect food additive rules and ISO 10993 biocompatibility standards govern healthcare applications, creating dual compliance burdens for multi-market suppliers. Stakeholders must monitor evolving restrictions on benzophenone-derived photoinitiators and assess LED curing equipment upgrades against pending energy efficiency mandates.
Market Dynamics
Material-as-a-service subscription models for photopolymer inventory management are restructuring procurement relationships between resin suppliers and industrial coating operations. This shift compresses working capital requirements while locking in formulation continuity for multi-site manufacturers.
Growth Catalysts
- UV-LED curing equipment penetration:Semiconductor packaging lines in Taiwan and South Korea are retrofitting mercury lamp systems to reduce energy consumption and eliminate thermal damage to sensitive substrates.
- REACH Annex XVII restrictions:European reformulation mandates toward lower-migration acrylates are accelerating qualification of next-generation photoinitiators with reduced extractables profiles.
- Biocompatible dental applications:ISO 10993-5 cytotoxicity testing protocols are now standard for chairside 3D printing resins, expanding addressable markets for surgical guide and splint fabrication.
Market Restraints
- Petrochemical feedstock volatility:Acrylate monomer prices track propylene oxide and acrylic acid supply disruptions from Gulf Coast petrochemical complexes.
- Photoinitiator supply concentration:Chinese manufacturers control over 70% of global benzophenone and TPO-L production, creating single-source vulnerability for European formulators.
- Oxygen inhibition in free-radical systems:Surface tackiness in acrylate coatings requires nitrogen inerting or wax additives, adding process complexity and cost.
Strategic Opportunities
- Thiol-ene chemistry expansion:Oxygen-insensitive formulations with low shrinkage are penetrating microfluidic device fabrication and precision optical component manufacturing.
- India electronics assembly growth:Production-linked incentive schemes for semiconductor and mobile phone manufacturing are creating demand for underfill and encapsulant resins.
- Dual-cure epoxy-acrylate hybrids:Convergence of UV snap-cure with thermal post-cure mechanisms enables through-cure in shadowed areas of complex automotive sensor housings.
Industry Challenges
- Photochemistry formulation expertise scarcity:Industrial coating compounders lack sufficient specialists in radical quenching kinetics and LED spectral matching.
- Multi-jurisdictional compliance timelines:FDA 510(k) clearance for medical device resins runs parallel to MDR technical documentation in Europe, stretching regulatory affairs bandwidth.
- Legacy mercury lamp infrastructure stranding:Capital equipment depreciation schedules conflict with LED retrofit mandates, complicating customer conversion economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photocurable Resins Market |
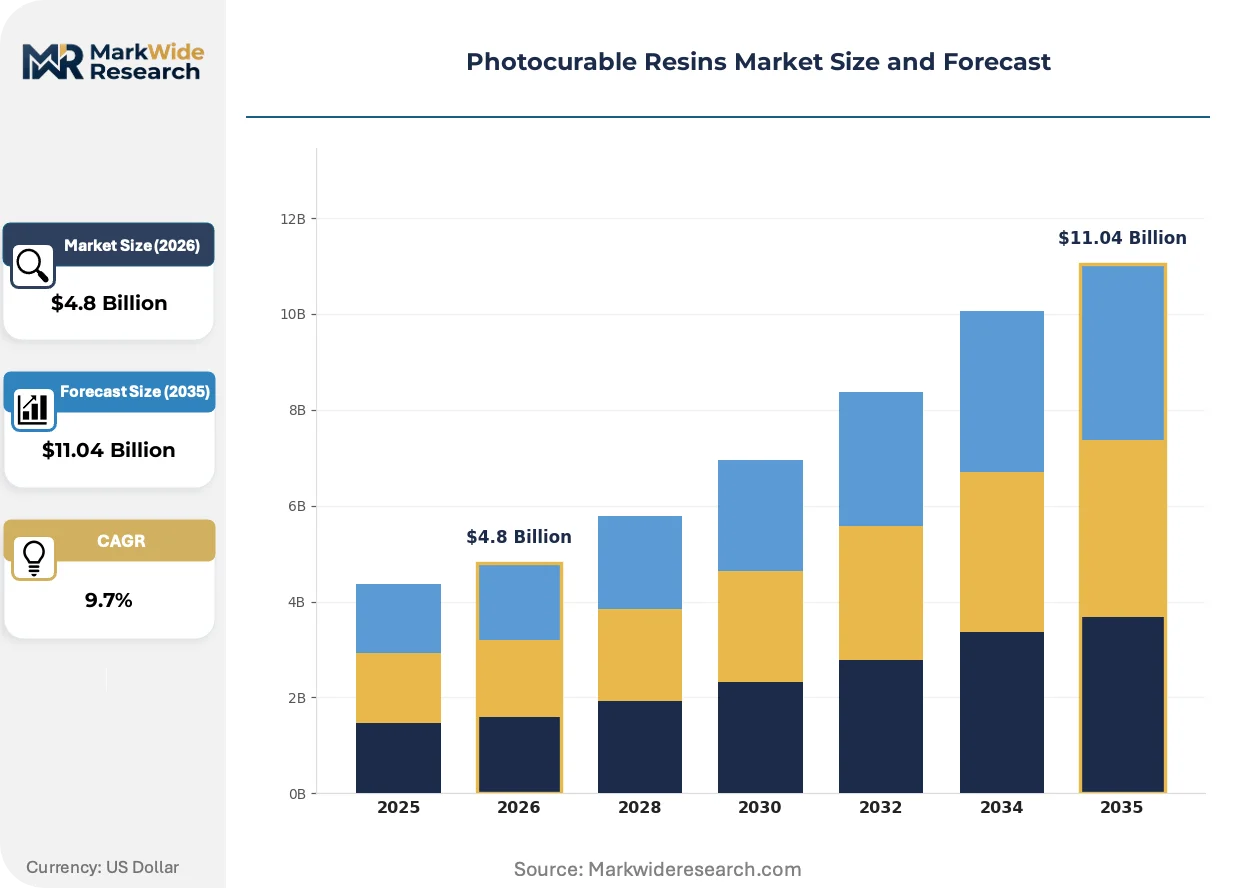
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
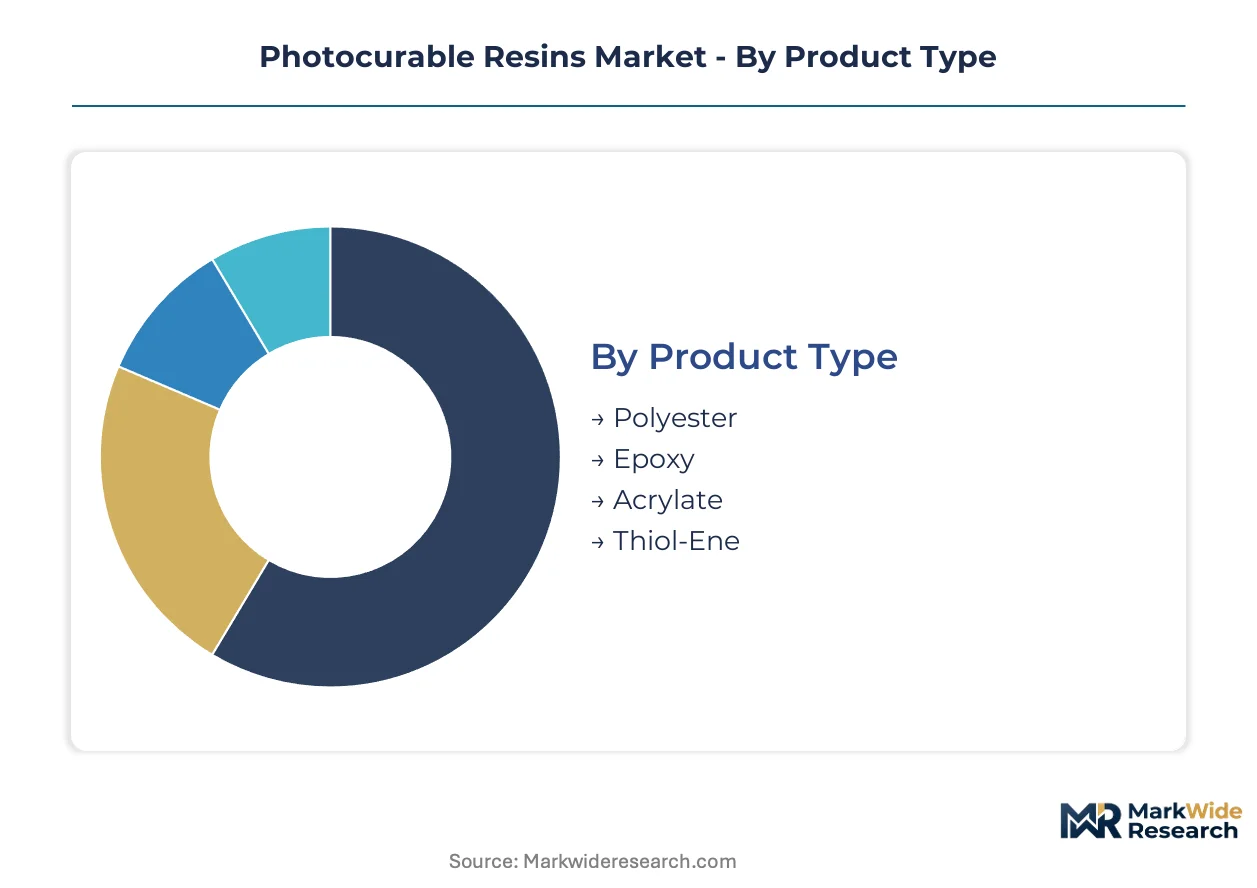
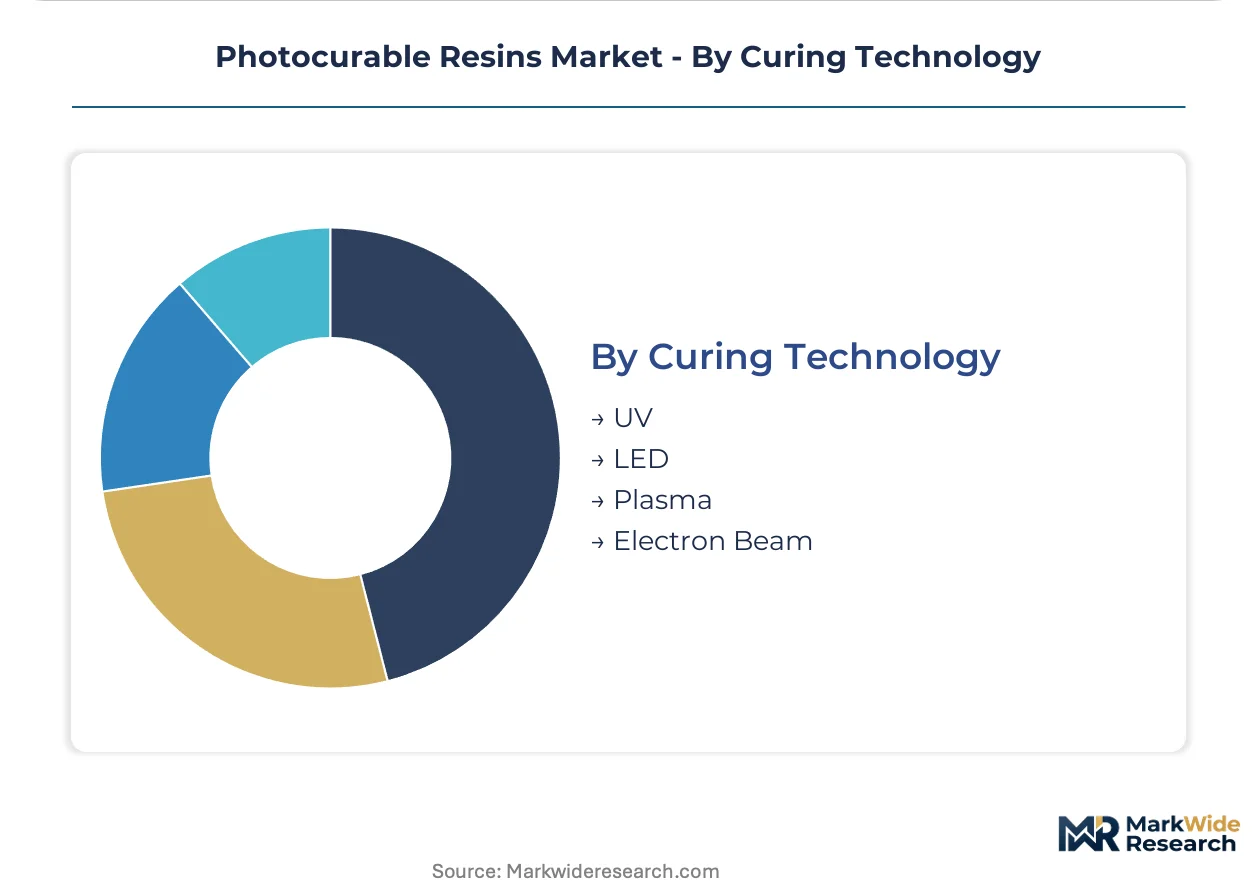
| Segmentation | Product Type: Polyester, Epoxy, Acrylate, Thiol-Ene Application: Coatings, 3D Printing, Adhesives, Inks End User: Aerospace, Automotive, Electronics, Healthcare Curing Technology: UV, LED, Plasma, Electron Beam |
| Companies Covered | 3M Company, DuPont, BASF SE, Evonik Industries AG, Mitsubishi Chemical Corporation, Arkema S.A., Huntsman Corporation, The Dow Chemical Company, Henkel AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photocurable Resins Market Evolving Landscape
Photocurable resin technology is pivoting toward wavelength-specific formulations tuned to emerging LED emission spectra. This evolution demands simultaneous advances in photoinitiator molar extinction coefficients and oligomer viscosity engineering.
Digital light processing hardware is automating layer-by-layer fabrication in dental laboratories and hearing aid manufacturing. Audiologists in Germany and the Netherlands are deploying these systems for custom shell production with 24-hour turnaround. The technology is automating previously manual wax-based workflows while compressing labor content per unit by over half.
ECHA's 2023 restriction proposal on diphenyl(2,4,6-trimethylbenzoyl)phosphine oxide (TPO) is forcing reformulation across European graphic arts and wood coating applications. Industrial inkjet printers and flatline finishing systems must substitute alternative Type I photoinitiators before the anticipated 2026 enforcement window. Nordic coating houses are accelerating qualification of acylphosphine oxide alternatives with comparable 385 nm absorbance profiles.
Subscription-based resin management programs are displacing spot purchasing in high-volume additive manufacturing operations. Tier-one automotive suppliers in Michigan and Bavaria now procure photopolymers through managed inventory agreements with guaranteed uptime clauses. This shift concentrates procurement authority at headquarters level while reducing formulation variability across distributed print farms.
Photocurable Resins Market Segmentation
Photocurable resin selection hinges on matching reactivity profiles to substrate sensitivity and throughput requirements. Formulators balance cure speed against oxygen inhibition, thermal budget, and regulatory migration limits when specifying oligomer systems.
Product Type:
Reactivity mechanisms and shrinkage characteristics distinguish chemistry platforms for precision versus bulk applications.
- Acrylate:Free-radical polymerization delivers sub-second cure speeds under UV-LED irradiance, making these formulations dominant in high-speed wood coatings and graphic arts. German flatline finishing operations specify acrylates for 150+ meters per minute line speeds despite oxygen inhibition challenges at air interfaces.
- Epoxy:Cationic cure chemistry exhibits no oxygen sensitivity and generates low shrinkage, positioning these resins for semiconductor encapsulation and fiber optic coatings. Taiwan semiconductor packaging houses favor epoxy formulations for underfill applications where thermal cycling reliability is paramount.
- Polyester:Hybrid unsaturated systems combine cost efficiency with moderate reactivity for composite tooling and marine gelcoats.
- Thiol-Ene:Step-growth polymerization enables uniform network formation with minimal shrinkage stress for microfluidic device fabrication.
Mature deployment sits with acrylate systems across commodity coating lines. Newer deployment is concentrated in thiol-ene formulations for precision additive manufacturing.
Application:
Process integration requirements shape resin viscosity, pigment compatibility, and depth of cure specifications.
- Coatings:Low-viscosity oligomers with tailored surface tension enable thin-film deposition on heat-sensitive substrates. Automotive interior trim suppliers in Bavaria deploy UV-curable topcoats to replace solvent-borne systems and eliminate thermal oven stages.
- 3D Printing:Photopolymer vat polymerization demands precise viscosity control and low extractables for biocompatible outputs. Dutch dental laboratories utilize DLP systems with customized acrylate formulations for surgical guide production.
- Adhesives:Gap-filling formulations with controlled modulus development bond dissimilar substrates in electronics assembly.
- Inks:Pigment-stable photoinitiator packages maintain cure efficiency across high-resolution inkjet printheads.
Volume concentration centers on coating applications. Value expansion is climbing the fastest in 3D printing resins.
End User:
Certification burdens and performance specifications fragment demand across industrial sectors.
- Electronics:Low-outgassing formulations with ionic purity below 10 ppm protect sensitive circuitry in mobile device assembly. South Korean display manufacturers specify these resins for polarizer lamination adhesives.
- Healthcare:ISO 10993-5 cytotoxicity compliance and USP Class VI testing govern resin selection for patient-contact devices. Michigan hearing aid producers utilize biocompatible photopolymers for custom shell fabrication.
- Automotive:Exterior durability requirements drive specification of weathering-resistant clearcoats and sensor encapsulants.
- Aerospace:Flame-retardant formulations meeting FAR 25.853 standards protect interior cabin components.
Regulatory qualification intensity peaks in healthcare. Operational scale dominates electronics procurement decisions.
Curing Technology:
Equipment capital costs and energy efficiency mandates accelerate transition between irradiation sources.
- UV:Mercury vapor lamps deliver broad-spectrum output with established photoinitiator compatibility across legacy coating lines. Michigan automotive suppliers maintain UV infrastructure for high-build primer surfacers.
- LED:Narrow emission bands at 365 nm, 385 nm, and 395 nm reduce energy consumption and eliminate thermal damage to plastic substrates. Taiwan semiconductor packaging operations are retrofitting mercury systems to LED arrays.
- Electron Beam:High-energy radiation enables solvent-free cure without photoinitiators for food-contact applications.
- Plasma:Low-temperature surface activation pretreats difficult substrates before photocure application.
Installed base concentration remains with conventional UV. Steepest expansion trajectory is occurring in LED curing systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's Yangtze River Delta electronics corridor concentrates the highest density of UV-LED curing system installations for semiconductor packaging applications.
Germany
Automotive interior trim manufacturers in Bavaria specify UV-curable coatings to eliminate thermal oven stages from production lines. REACH Annex XVII restrictions on TPO photoinitiators are accelerating reformulation timelines for flatline finishing operations. The industrial coatings corridor between Stuttgart and Munich hosts the densest concentration of acrylate formulators serving premium automotive OEMs.
United States
Michigan hearing aid producers utilize biocompatible photopolymers for custom shell fabrication with 24-hour turnaround guarantees. FDA 21 CFR Part 175 indirect food additive rules govern resin selection for packaging adhesives in the Midwest manufacturing belt. Tier-one automotive suppliers in Detroit and Grand Rapids procure photopolymers through managed inventory agreements with guaranteed uptime clauses.
China
Shenzhen's electronics assembly zones drive demand for low-outgassing encapsulant resins in mobile device manufacturing. Chinese manufacturers control over 70% of global benzophenone and TPO-L photoinitiator production, creating supply concentration for European formulators. The Pearl River Delta cluster houses the world's largest installed base of mercury vapor lamp curing systems now facing LED retrofit mandates.
South Korea
Display manufacturers in Gyeonggi Province specify ionic-purity resins below 10 ppm for polarizer lamination adhesives. MFDS biocompatibility standards parallel FDA requirements for medical device resins exported to US markets. Semiconductor packaging houses in Suwon and Pyeongtaek are retrofitting mercury lamp systems to LED arrays to reduce thermal damage to sensitive substrates.
Netherlands
Dutch dental laboratories deploy digital light processing systems with customized acrylate formulations for surgical guide production. ECHA restrictions on diphenyl(2,4,6-trimethylbenzoyl)phosphine oxide are forcing Nordic coating houses to qualify alternative Type I photoinitiators. The Eindhoven-Tilburg corridor specializes in precision additive manufacturing for hearing aid and dental device markets.
Photocurable Resins Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across formulation and equipment integration boundaries. The vendor base separates between integrated chemical conglomerates controlling monomer-to-oligomer pipelines and specialty compounders focused on application-specific tuning. Three archetypes dominate: diversified materials giants with captive raw material supply, mid-scale formulators with deep technical service relationships, and niche specialists in medical-grade or semiconductor-grade certifications. Competitive moves concentrate on backward integration into photoinitiator supply and geographic expansion through direct sales offices in Asian electronics manufacturing zones.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated archetype with upstream control over acrylate monomer production. Henkel AG & Co. KGaA occupies a position within the technical service-intensive tier, anchoring electronics assembly adhesive supply through direct OEM relationships. These three entities represent distinct competitive positioning strategies: raw material cost control, R&D intensity in specialty methacrylates, and distribution proximity to high-volume manufacturing clusters.
| Leading Market Players |
|---|
| 3M Company |
| DuPont |
| BASF SE |
| Evonik Industries AG |
| Mitsubishi Chemical Corporation |
| Arkema S.A. |
| Huntsman Corporation |
| The Dow Chemical Company |
| Henkel AG & Co. KGaA |
| Others |
Value Network & Pricing Analysis
Family-owned German mid-cap formulators anchor pricing discipline through captive acrylate monomer supply, compressing working capital cycles while locking in formulation continuity for multi-site automotive coating operations across Bavaria and Baden-Württemberg.
Pricing Analysis
Throughput-guaranteed subscription contracts now anchor pricing for high-volume additive manufacturing operations, replacing spot purchasing with managed inventory agreements featuring uptime clauses. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from industrial coating formulations and commodity wood finishing resins. Cost compression in standard-tier acrylates is intensifying because Chinese photoinitiator supply concentration limits European formulators' bargaining leverage. Electronics assemblers in Taiwan and South Korea exhibit lowest price sensitivity due to yield-critical performance requirements, while furniture coaters in Eastern Europe remain most sensitive to per-kilogram differentials.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Tier-one automotive suppliers in Michigan and Bavaria, while distributor networks serve fragmented dental laboratory markets. Manufacturing concentrates in Germany, China, and South Korea, with Chinese producers controlling over seventy percent of global benzophenone and TPO-L photoinitiator output. Formulation draws from propylene oxide, acrylic acid, and specialty methacrylate feedstocks vulnerable to Gulf Coast petrochemical disruption. Single-source vulnerability in photoinitiator supply creates structural risk for European REACH-compliant formulators facing reformulation deadlines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into photoinitiator production and forward integration into managed resin services represent the dominant vertical-integration race, with players capturing margin pools currently absorbed by Chinese chemical intermediates suppliers and distributor markups.
For Market Incumbents: Lock in formulation continuity through long-term monomer supply agreements with BASF and Evonik, insulating against propylene oxide volatility. Acquire specialty photoinitiator producers in South Korea to reduce Chinese supply dependency. Expand technical service headcount in Shenzhen and Gyeonggi Province to defend electronics adhesive share against emerging local compounders.
For New Entrants and Emerging Players: REACH Annex XVII restrictions on TPO photoinitiators in Europe open a window for alternative Type I photoinitiator qualification services. Target Nordic coating houses accelerating reformulation timelines ahead of anticipated enforcement. Penetrate India's electronics assembly growth corridor through production-linked incentive alignment with semiconductor packaging resins.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale European formulators with stranded mercury lamp infrastructure and strong dental laboratory relationships. Monitor LED curing equipment retrofit rates as inflection indicator for resin demand acceleration. Prioritize targets with ISO 10993 certification infrastructure already deployed.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Photoinitiator Supply | Reduces Chinese supply concentration risk for European REACH-compliant formulators. |
| Managed Inventory Service Expansion | Locks in procurement authority at headquarters level across distributed automotive print farms. |
| LED Curing Equipment Partnership | Accelerates customer conversion from stranded mercury lamp infrastructure in Pearl River Delta. |
| Medical-Grade Certification Investment | Enables premium pricing for ISO 10993-5 compliant surgical guide and hearing aid resins. |
| Geographic Expansion into India Electronics Corridor | Captures production-linked incentive driven demand for underfill and encapsulant formulations. |
Research Methodology
Multi-period observation of UV-LED curing equipment installation rates, photoinitiator price indices, and dental laboratory DLP adoption anchored the trend analysis, supplemented by interviews with resin formulation R&D directors, automotive coating procurement managers, electronics assembly process engineers, and dental laboratory operations heads. Secondary validation drew from ECHA restriction proposals, FDA 510(k) filing databases, SEC 10-K disclosures of listed chemical conglomerates, and customs trade data for acrylate monomer flows. Bottom-up segment sizing triangulated against top-down chemical industry production estimates.
The input-output matrix framed demand as function of coating line speed requirements, substrate thermal sensitivity thresholds, and regulatory migration limits across chemistry platforms. Segmentation dimensions modeled include reactivity mechanism, end-use certification tier, curing technology type, and regional manufacturing hub clustering. CAGRs derived from slope analysis of equipment penetration curves and formulation qualification timelines. Key inputs incorporated LED spectral efficiency improvements and REACH Annex XVII compliance cost assumptions.
The model assumes a particular technology adoption path; alternative pathways for thiol-ene chemistry penetration in microfluidics would alter the outlook. Forecasts reflect base-case assumptions regarding photoinitiator supply continuity and LED retrofit economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Fluorinated Polyimide Market