
 Global Specialty Resins Market | 2026-2036
Global Specialty Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Resins Market Foresight
Advanced bio-based feedstock integration is reshaping how specialty resin manufacturers design curing systems and reduce petrochemical dependency. BASF SE leverages its integrated Verbund structure to sustain cost advantages across epoxy and polyurethane precursor chains. Covestro AG differentiates through polycarbonate and polyurethane resin technology leadership in high-performance coatings. Dow Inc. anchors North American supply security with controlled access to propylene oxide and acrylic acid derivatives.
Specialty resins comprise engineered thermoset and thermoplastic polymers formulated with defined molecular weights, functional groups, and curing profiles to deliver specific mechanical, thermal, or chemical resistance properties; these materials typically achieve glass transition temperatures ranging from 80°C to over 250°C depending on crosslink density and backbone chemistry. Epoxy resins dominate structural composites and electrical insulation due to their exceptional adhesion and dielectric strength, while silicone resins command premium positions in aerospace thermal management and electronics encapsulation where sustained performance above 200°C is mandatory. Polyurethane resins compete aggressively in furniture fabrication and packaging production where flexibility and rapid cure speed offset lower heat tolerance.
EPA oversight of volatile organic compound emissions constrains solvent-borne alkyd and acrylic formulations in the United States, while REACH registration requirements in Europe enforce full toxicological transparency for phenolic and epoxy resin precursors. China's GB standards and MEE enforcement on industrial emissions are tightening manufacturing compliance for local and imported resin systems alike. Stakeholders must monitor how evolving carbon border adjustment mechanisms and per- and polyfluoroalkyl substance restrictions recalibrate raw material sourcing strategies and geographic production footprints.
Market Dynamics
REACH and RoHS compliance in Europe is forcing formulators toward low-VOC epoxy and silicone resin systems, while semiconductor packaging demand in Asia is pulling thermal performance specifications upward across all major resin categories.
Growth Catalysts
- Semiconductor packaging thermal requirements:Advanced node chips require encapsulants with glass transition temperatures exceeding 200°C, driving specialty epoxy and silicone resin specifications in Taiwan, South Korea, and Germany.
- REACH registration mandates:Full toxicological transparency requirements for phenolic and epoxy precursors are consolidating supplier bases toward compliant formulators with established dossiers.
- China's dual carbon goals:Beijing's industrial emissions enforcement through MEE is accelerating domestic substitution of solvent-borne systems with waterborne and high-solids alternatives.
Market Restraints
- Bisphenol A feedstock volatility:Epoxy resin production remains exposed to petrochemical price swings, with aromatic precursors tracking crude oil and naphtha benchmarks without effective hedging instruments for mid-scale formulators.
- Concentrated propylene oxide supply:North American and Middle Eastern producers control bulk oxide derivatives, creating geographic dependency for polyurethane resin chains serving automotive and construction end-uses.
- Per- and polyfluoroalkyl substance restrictions:Emerging PFAS limitations in the EU and several US states threaten fluorinated resin segments used in extreme chemical resistance applications.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu are creating demand for imported high-purity epoxy laminating systems.
- Bio-based curing agent convergence:Integration of lignin-derived hardeners with conventional epoxy backbones offers petrochemical reduction pathways for furniture and coating applications.
- Carbon border adjustment mechanisms:EU CBAM implementation is creating first-mover advantage for resin producers with verified low-carbon process certifications and scope-three transparency.
Industry Challenges
- Formulation chemist scarcity:Deep expertise in thermoset kinetics and rheology control is concentrating among aging technical workforces in Germany, Japan, and the United States.
- Multijurisdictional certification timelines:Simultaneous EPA, REACH, and GB standard compliance requires 18-36 month registration cycles that delay product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Resins Market |
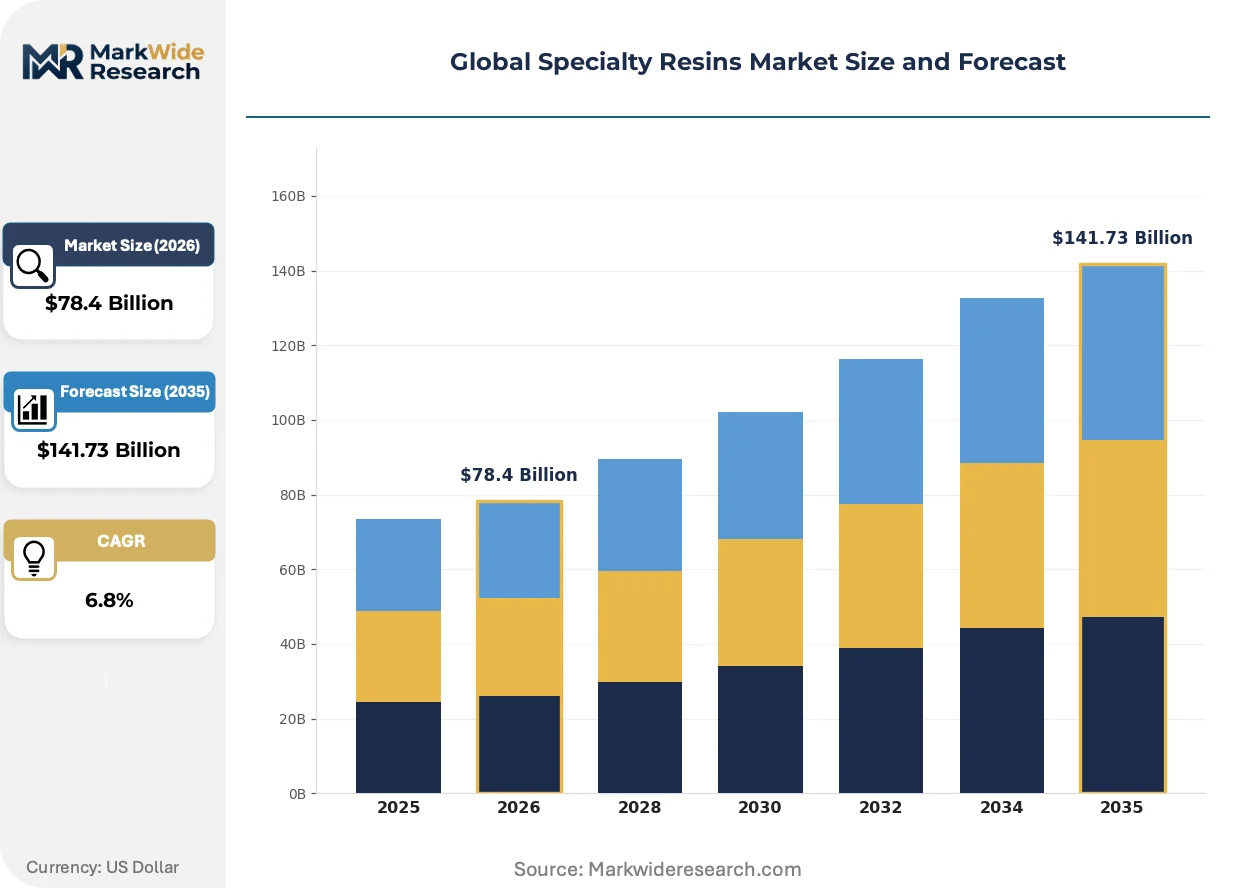
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic Resins, Epoxy Resins, Polyurethane Resins, Phenolic Resins, Silicone Resins, Alkyd Resins Application: Adhesives, Coatings, Electrical Insulation, Composites, Sealants, Encapsulation End User Industry: Construction, Electronics Manufacturing, Aerospace Manufacturing, Marine Manufacturing, Packaging Production, Furniture Fabrication Form: Liquid, Solid, Powder, Emulsion, Paste |
| Companies Covered | Hexion Inc., SABIC, Dow Inc., Covestro AG, Olin Corporation, BASF SE, Arkema SA, DuPont de Nemours Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Resins Market Shifts & Advancements
Digital formulation platforms are compressing development cycles for custom curing profiles, while regulatory pressure on embodied carbon is reshaping raw material sourcing hierarchies across all major resin chemistries.
Computational molecular design is virtualizing the traditional trial-and-error approach to thermoset development. Materials informatics platforms trained on cure kinetics databases allow formulators to predict glass transition temperatures and crosslink densities before synthesis. Automotive and aerospace OEMs in Germany and Japan are adopting these tools to specify resins with 40% faster qualification timelines. This capability is virtualizing the competitive advantage of historical formulation expertise, compressing margins for incumbent suppliers lacking digital infrastructure.
REACH authorization requirements for substances of very high concern are tightening access to legacy aromatic amine hardeners used in electrical laminates. ECHA's candidate list expansion is forcing laminate producers toward aliphatic and cycloaliphatic alternatives with modified cure schedules. Printed circuit board manufacturers in the Netherlands and Austria are absorbing 12-18 month reformulation costs to maintain CE-marked product access.
Specification bundling is consolidating procurement leverage among tier-one automotive and wind energy OEMs. Buyers are consolidating resin, hardener, and additive purchasing into single-source framework agreements with volume-tiered pricing and technical service integration. This pattern is most pronounced in Denmark and Spain, where Vestas and Siemens Gamesa operations have compressed their approved supplier lists for blade infusion epoxy systems from twelve to four qualified vendors.
Global Specialty Resins Market Segmentation
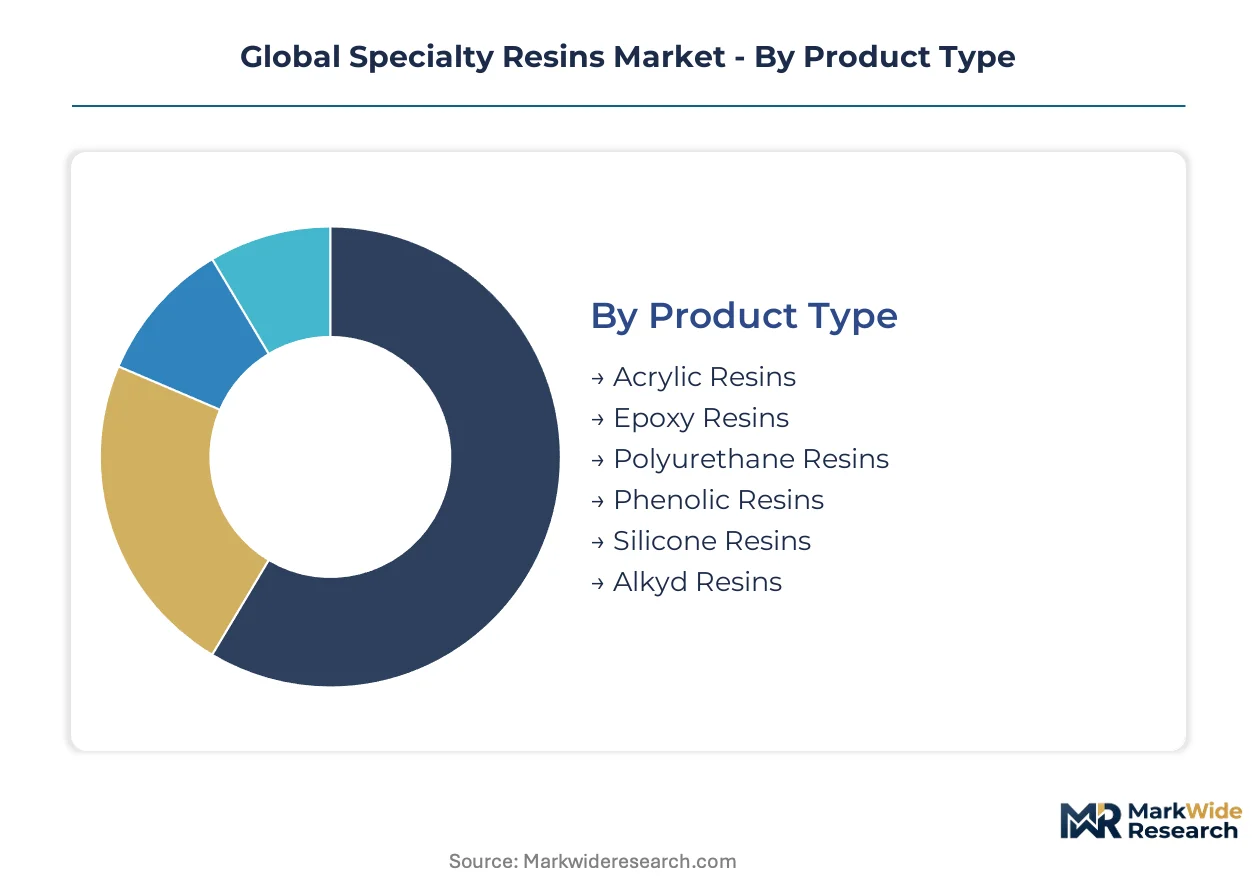
Specialty resin specifications diverge sharply across thermal, mechanical, and chemical resistance requirements. Product chemistry, application method, and end-use certification standards create distinct procurement categories with limited substitutability.
Product Type:
Resin chemistry determines the use-case spectrum from ambient-cure coatings to high-temperature aerospace composites.
- Epoxy Resins:These thermoset polymers achieve exceptional adhesion and dielectric strength through crosslinked bisphenol-A or bisphenol-F backbones with amine or anhydride curing agents. Demand concentrates in Taiwan and Germany for semiconductor encapsulation and printed circuit board laminates, where REACH-compliant low-VOC formulations command premium positioning.
- Silicone Resins:Organopolysiloxane structures deliver sustained performance above 200°C through Si-O-Si backbone stability. Aerospace thermal management in France and electronics encapsulation in South Korea drive specifications for methyl and phenyl silicone variants with tailored cure kinetics.
- Polyurethane Resins:Isocyanate-polyol reaction products dominate furniture fabrication and flexible packaging where rapid cure speed offsets lower thermal tolerance.
- Acrylic Resins:Thermoplastic and thermoset variants serve high-clarity coatings and UV-curable adhesives with weathering resistance.
- Phenolic Resins:Formaldehyde-condensed thermosets provide fire resistance and dimensional stability in electrical laminates and friction materials.
- Alkyd Resins:Polyol-polybasic acid esters modified with drying oils remain cost-competitive in architectural coatings despite solvent-borne regulatory pressure.
Established volume favors epoxy systems; emerging adoption favors silicone resins for thermal management applications.
Application:
Application method dictates viscosity, cure schedule, and regulatory compliance requirements across formulation portfolios.
- Coatings:Film-forming applications span protective industrial finishes to decorative architectural systems. China's MEE enforcement on industrial emissions accelerates waterborne and high-solids substitution in Shanghai and Guangdong manufacturing clusters.
- Electrical Insulation:Dielectric-grade formulations for motors, generators, and transformers require specific dissipation factors and thermal endurance classes. German and Japanese OEMs specify epoxy and polyesterimide systems with IEC 60172 certification.
- Adhesives:Structural bonding applications in automotive and construction demand tailored rheology and open-time control.
- Composites:Fiber-reinforced applications in wind blades and aerospace structures specify resin infusion and prepreg compatibility.
- Sealants:Gap-filling and environmental barrier applications require movement accommodation and weathering resistance.
- Encapsulation:Electronics protection demands ionic purity and coefficient of thermal expansion matching to prevent die stress.
Coatings absorb the largest formulation volumes; encapsulation climbs the fastest on semiconductor packaging demand.
End User Industry:
Customer type determines certification depth, technical service intensity, and contract structuring across resin supply relationships.
- Electronics Manufacturing:Semiconductor packaging and PCB fabrication require ionic purity below 10 ppm and glass transition temperatures exceeding 200°C for advanced node chips. Taiwan's TSMC supply chain and South Korea's Samsung operations specify specialty epoxy and silicone systems with full REACH dossier transparency.
- Aerospace Manufacturing:FAA and EASA certification requirements for flammability, smoke toxicity, and outgassing constrain approved material lists. Boeing and Airbus tier-one suppliers in Germany and France maintain qualified product databases with 18-36 month requalification cycles.
- Construction:Structural adhesives, flooring systems, and protective coatings demand regional building code compliance.
- Marine Manufacturing:IMO and USCG regulations on fire resistance and emissions shape gelcoat and laminating resin specifications.
- Packaging Production:Food-contact compliance through FDA and EFSA frameworks constrains coating and adhesive selections.
- Furniture Fabrication:VOC emissions regulations and sustainability certifications drive waterborne polyurethane and bio-based system adoption.
Electronics manufacturing concentrates premium formulation value; aerospace maintains the steepest certification barriers.
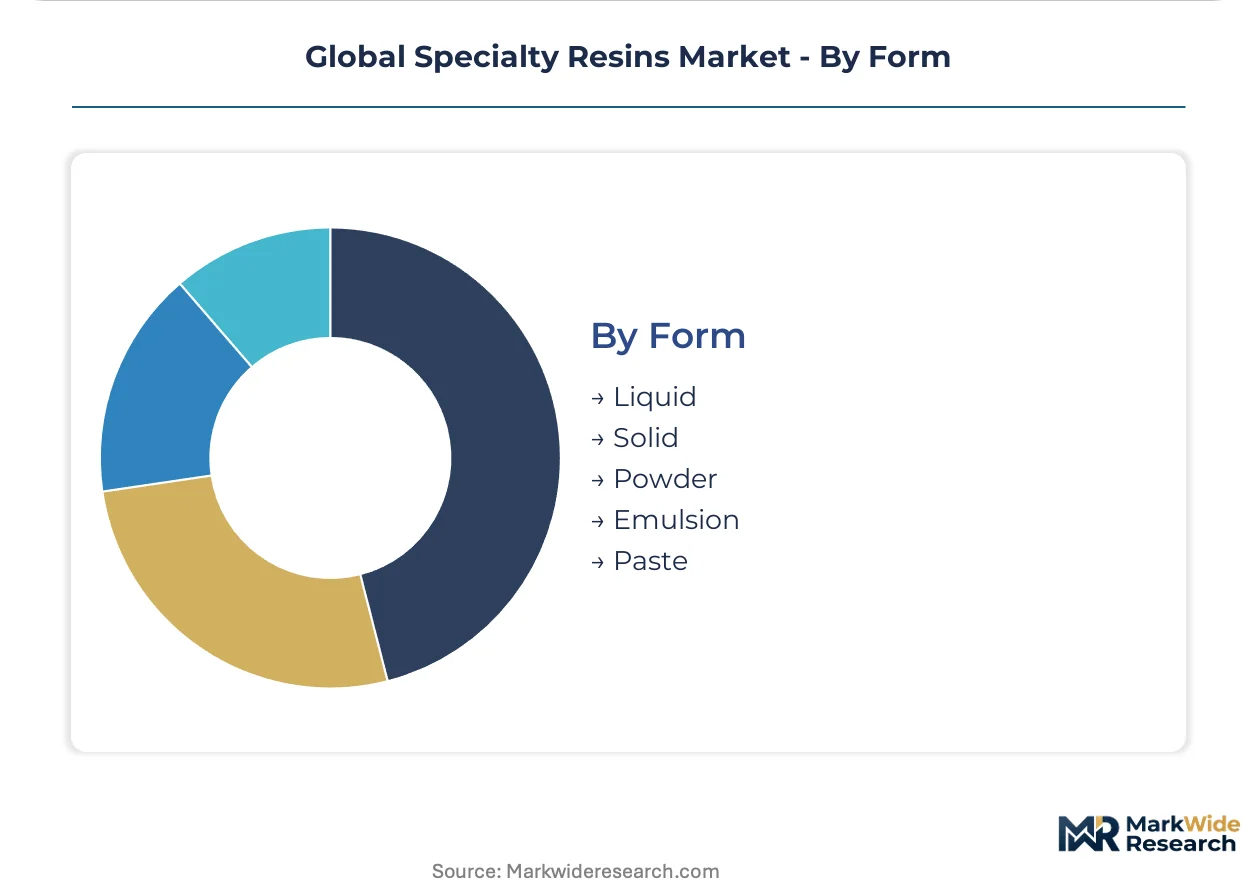
Form:
Physical state determines handling equipment, storage requirements, and application method compatibility.
- Liquid:Pumpable systems with defined viscosity ranges enable spray, dip, and cast application methods. Solvent-borne liquids face EPA and MEE emissions constraints; 100% solids variants gain share in high-performance coatings.
- Solid:Flake, pellet, and block forms support hot-melt adhesive and powder coating applications with zero VOC profiles.
- Powder:Electrostatic spray applications achieve uniform film builds without solvent recovery infrastructure.
- Emulsion:Water-dispersed systems satisfy low-VOC regulatory requirements in architectural and industrial maintenance coatings.
- Paste:Thixotropic formulations enable trowel and caulk-gun application for sealants and gap-filling adhesives.
Liquid forms dominate current shipment volumes; solid and powder formats gain share fastest on emissions compliance pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement power concentrates among German automotive OEMs, Chinese electronics contract manufacturers, and US aerospace primes. Each buyer archetype imposes distinct certification and technical service requirements on resin suppliers. Geographic proximity to these decision centers shapes competitive positioning more than raw material access.
China
Semiconductor packaging demand from TSMC suppliers in Taiwan and domestic chip fabrication in Shanghai drives specialty epoxy consumption. MEE enforcement on industrial emissions accelerates waterborne system substitution in Guangdong manufacturing clusters. Yangtze River Delta chemical parks concentrate domestic resin production capacity expansion.
Germany
BMW and Volkswagen specifications for lightweight composite structures sustain polyurethane and epoxy demand in automotive supply chains. REACH registration mandates for phenolic precursors consolidate supplier bases toward compliant formulators with established dossiers. Bavarian industrial corridors host formulation R&D centers serving European OEM qualification requirements.
United States
Boeing and Lockheed Martin tier-one suppliers maintain qualified material databases with 18-36 month requalification cycles for aerospace thermal management resins. EPA oversight of VOC emissions constrains solvent-borne alkyd formulations in industrial coatings. Texas Gulf Coast petrochemical infrastructure anchors propylene oxide supply security for polyurethane chains.
South Korea
Samsung Electronics and SK Hynix operations specify silicone encapsulants with sustained performance above 200°C for advanced memory packaging. MFDS-aligned quality frameworks govern ionic purity requirements below 10 ppm for semiconductor-grade formulations. Gyeonggi-do province clusters concentrate electronics manufacturing demand for imported high-purity systems.
India
PLI scheme incentives for semiconductor and PCB fabrication in Gujarat and Tamil Nadu create demand for imported epoxy laminating systems. BIS certification requirements for electrical insulation materials extend product commercialization timelines. Mumbai-Pune industrial corridors attract formulation joint ventures targeting domestic electronics supply chain integration.
Global Specialty Resins Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. The vendor base organizes around three strategic archetypes: integrated petrochemical majors with captive precursor supply, mid-scale formulators with application-specific expertise, and regional distributors with technical service integration. Dominant competitive moves include backward integration into bio-based feedstocks and strategic partnerships with electronics OEMs for qualification co-development.
Among integrated chemical majors, BASF SE, Covestro AG, and Dow Inc. exemplify the scale-driven archetype with Verbund or regional supply chain control. These entities occupy positions where captive access to propylene oxide, bisphenol-A, or acrylic acid derivatives insulates margin structures from feedstock volatility. Mid-scale specialists including Hexion Inc. and Huntsman Corporation represent the formulation-expertise tier, concentrating thermoset kinetics capabilities for automotive and aerospace qualification pathways. Olin Corporation and Arkema SA anchor positions in chlorine-derivative and specialty polymer segments respectively. DuPont de Nemours Inc. and SABIC occupy diversified materials portfolios where resin operations intersect with adjacent engineered materials businesses.
| Leading Market Players |
|---|
| Hexion Inc. |
| SABIC |
| Dow Inc. |
| Covestro AG |
| Olin Corporation |
| BASF SE |
| Arkema SA |
| DuPont de Nemours Inc. |
| Huntsman Corporation |
| Others |
Supply & Pricing Matrix
Middle Eastern and North American propylene oxide producers control bulk derivatives that feed polyurethane resin chains, concentrating margin capture upstream while automotive and construction formulators downstream absorb feedstock volatility through cost-plus pass-through mechanisms. This structural asymmetry shapes how specialty resin pricing power distributes across the value chain, with captive precursor access becoming the decisive competitive variable.
Pricing Analysis
Cost-plus contracts with naphtha and crude oil indexation dominate epoxy resin procurement, particularly for bisphenol-A derived systems serving semiconductor packaging in Taiwan and Germany. Pricing stratifies across REACH-compliant premium tiers, standard industrial grades, and economy solvent-borne alternatives, with certification-grade formulations commanding substantial premiums for full toxicological dossier transparency. Cost compression in standard epoxy grades is intensifying as Chinese domestic capacity expansion floods mid-tier segments, while aerospace-qualified silicone systems remain least price-sensitive due to EASA and FAA requalification barriers.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have proliferated among German automotive OEMs and Chinese electronics contract manufacturers, squeezing working capital for mid-scale formulators without Verbund-scale balance sheets. Raw material sourcing concentrates in China, Germany, and the United States for epoxy precursors; Saudi Arabia, Kuwait, and the United States for propylene oxide derivatives; and Japan, South Korea, and Germany for high-purity silicone intermediates. Single-source vulnerability around bisphenol-A feedstock exposes formulators to petrochemical price swings without effective hedging instruments. Distribution runs through qualified supplier programs at tier-one aerospace and automotive OEMs, with technical service integration bundling resin, hardener, and additive purchasing into framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty resin procurement is approaching a platform-economics inflection as computational molecular design tools virtualize historical formulation expertise and consolidate specification-setting power among digitally capable suppliers. Interoperability between materials informatics platforms and OEM qualification databases is reshaping how resin systems achieve approved material status.
For Market Incumbents: Build data moats around cure kinetics databases and predictive glass transition modeling to defend against computational chemistry entrants virtualizing formulation expertise. Incumbent suppliers should deepen backward integration into bio-based feedstocks—lignin-derived hardeners, epoxidized vegetable oils—to preempt regulatory pressure on petrochemical dependency while locking in REACH-compliant precursor supply. Specification bundling through single-source framework agreements with volume-tiered pricing remains essential for retaining procurement leverage against consolidating automotive and wind energy OEMs. For New Entrants and Emerging Players: Pursue white-space opportunities in India's PLI-driven electronics manufacturing clusters, where imported high-purity epoxy laminating systems face insufficient domestic supply for Gujarat and Tamil Nadu semiconductor fabrication incentives. Bio-based curing agent convergence offers another penetrable entry point, with furniture and coating applications tolerating modified cure schedules in exchange for petrochemical reduction pathways. A technical service-heavy go-to-market approach—embedding formulation chemists at customer R&D centers—can overcome qualification timeline barriers that disadvantage distant competitors. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale formulators with established REACH dossiers and aerospace qualification pathways, as regulatory compliance moats widen under ECHA candidate list expansion and multijurisdictional certification timelines extend. Long-term viability across the analysis window hinges on digital infrastructure for computational molecular design and scope-three carbon transparency for EU CBAM positioning. The signal to watch is consolidation velocity among German and Japanese formulation specialists with aging technical workforces and limited succession planning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Secures lignin-derived hardener supply for REACH-compliant epoxy systems ahead of petrochemical restrictions. |
| Computational Molecular Design Platform Deployment | Compresses automotive and aerospace OEM qualification timelines by 40% through virtualized cure kinetics prediction. |
| Long-term Supply Agreement with Electronics OEMs | Locks in ionic purity specifications below 10 ppm for TSMC and Samsung advanced node packaging demand. |
| Joint Venture in Indian Manufacturing Corridor | Positions for PLI scheme semiconductor cluster demand in Gujarat and Tamil Nadu with BIS certification readiness. |
| Green Manufacturing Transition for CBAM Compliance | Generates verified low-carbon process certifications for EU carbon border adjustment mechanism first-mover advantage. |
Research Methodology
Initial hypotheses were tested against primary input from plant managers at specialty resin production facilities, procurement leads at automotive and electronics OEMs, distribution channel partners serving coating and adhesive formulators, and technical R&D directors specializing in thermoset kinetics. These perspectives were refined against secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings of integrated chemical majors, and REACH registration dossiers maintained by ECHA. Bottom-up volume estimates by product chemistry, application method, and end-use industry were triangulated against top-down macroeconomic drivers and petrochemical feedstock demand models.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation dimensions spanning resin chemistry tier, end-use industry certification depth, physical form factor, and regional production hub concentration. CAGRs were derived from slope-intercept modeling of historical consumption patterns and forward-looking OEM capacity announcements, with semiconductor packaging thermal requirements and China's MEE enforcement intensity serving as key industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-backed chemical majors or accelerated PFAS restriction timelines would shift outcomes beyond modeled ranges. Macroeconomic deviation in construction and automotive output, regulatory acceleration on carbon border adjustments, or breakthroughs in bio-based precursor cost parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Polyglycerol Sebacate (PGS) Market
Specialty Chemicals
Bio-Based Phenol Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Monomethylsilanetriol Market
Specialty Chemicals
Middle East and Africa Amino Acids Market
Specialty Chemicals
Photoinitiators Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Copper Ammonium Carbonate Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Organosilicon Electrolyte Market
Specialty Chemicals
Hydroxypropionic Acid Market