
 North America Expanded Polypropylene Foam Market | 2026-2036
North America Expanded Polypropylene Foam Market Size, Share, and Industry Trends Forecast 2026-2036
North America Expanded Polypropylene Foam Market Intelligence
Lightweighting technology is fragmenting traditional metal-and-foam assemblies across North American vehicle platforms. BASF SE leverages its integrated polypropylene supply chain to dominate high-volume molded foam contracts with Detroit automakers. JSP Corporation anchors the technical foam segment through proprietary bead-expansion processes that sustain premium pricing in medical packaging applications. Woodbridge competes on geographic proximity, operating production facilities within two hundred miles of major automotive assembly plants in Michigan and Ohio.
Expanded polypropylene foam consists of closed-cell bead foam manufactured through steam-chest molding of pre-expanded polypropylene resin beads, yielding densities between fifteen and two hundred grams per liter with exceptional energy absorption and thermal insulation properties. The material serves primarily as a protective, lightweight structural medium in applications requiring repeated impact resistance without permanent deformation. Molded foam commands the largest volume share among product types because automotive seating and bumper cores require complex three-dimensional geometries that block foam cannot achieve. Fabricated foam represents the fastest-growing category as packaging converters in the Midwest adopt CNC-cut inserts for precision electronics protection. Coated foam carries the highest margin pool due to specialized medical-grade surface treatments that meet FDA biocompatibility protocols for surgical instrument trays.
The EPA enforces volatile organic compound emission limits under the National Emission Standards for Hazardous Air Pollutants that constrain solvent-based adhesive bonding processes in foam fabrication facilities. NHTSA fuel economy standards indirectly stimulate expanded polypropylene demand by mandating gram-per-mile reductions that favor lighter interior components. OSHA workplace exposure limits for respirable dust shape plant ventilation investments and automation decisions across Canadian and US manufacturing sites. Stakeholders must monitor how California Air Resources Board rulemakings on automotive interior emissions could cascade into binding specifications for foam suppliers serving multistate OEM programs.
Market Dynamics
Automotive lightweighting mandates are compressing metal-to-foam substitution timelines across North American vehicle platforms, forcing Tier-1 suppliers to reconfigure molding capacity for expanded polypropylene seating cores and bumper assemblies.
Growth Catalysts
- NHTSA Fuel Economy Standards:Gram-per-mile reduction targets compel Detroit automakers to specify lighter interior components, expanding molded foam contracts for seat structures and door panels.
- Water-Based Coating Migration:EPA volatile organic compound enforcement is accelerating converter investment in aqueous adhesive systems for fabricated foam bonding, opening compliant capacity expansion.
- Great Lakes Manufacturing Density:Concentrated automotive assembly in Michigan and Ontario creates logistics advantages for just-in-time foam delivery, reducing working capital requirements for tier suppliers.
Market Restraints
- Propylene Feedstock Volatility:Crude oil price swings transmit directly to polypropylene resin costs, compressing converter margins on fixed-price automotive contracts.
- Bead Expansion Equipment Concentration:Proprietary steam-chest molding technology remains concentrated among Japanese and German machinery suppliers, creating capex bottlenecks for new entrants.
- Polyurethane Substitution in Seating:Flexible polyurethane foam retains cost advantages in low-specification seating applications, limiting expanded polypropylene penetration in economy vehicle segments.
Strategic Opportunities
- Medical Packaging Expansion:FDA biocompatibility protocols for surgical instrument trays create premium pricing pools for coated foam converters with validated sterilization resistance.
- CNC Fabrication Adoption:Midwest electronics packaging converters are adopting automated cutting cells for precision insert production, expanding addressable demand beyond molded geometries.
- Canada Clean Fuel Regulations:Carbon intensity reduction mandates favor lightweight materials in commercial vehicle applications, opening provincial procurement channels for thermal insulation foam.
Industry Challenges
- Process Engineering Talent Scarcity:Steam-chest molding optimization requires specialized technicians familiar with bead nucleation control, creating recruitment bottlenecks in Michigan and Ohio manufacturing zones.
- Multi-Specification Certification Burden:OEMs require simultaneous validation against FMVSS 302 flammability, SAE J1756 fogging, and proprietary odor standards, extending program launch timelines.
- Legacy Adhesive System Retrofit Costs:Converters face stranded equipment risk as solvent-based bonding lines require complete ventilation and fire-suppression overhaul for EPA compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Expanded Polypropylene Foam Market |
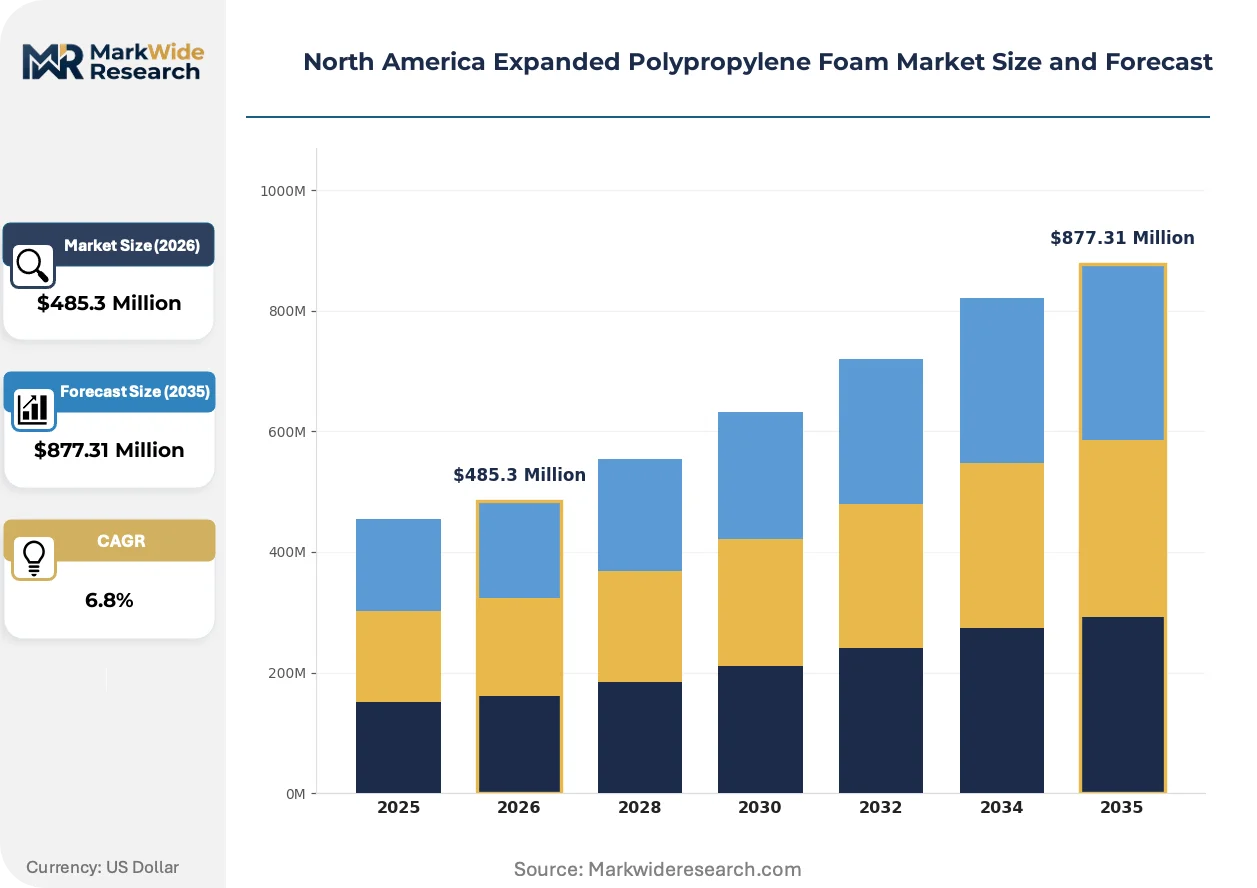
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $877.31 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Foam, Molded Foam, Fabricated Foam, Coated Foam Application: Automotive Interiors, Packaging Solutions, Medical Devices, Consumer Goods End User: Automotive Manufacturers, Packaging Companies, Healthcare Providers, Retailers Distribution Channel: Direct Sales, Distributors, E-commerce, Dealers |
| Companies Covered | Woodbridge, PDM Foam, BASF SE, Bradford Company, Knauf Industries, Sonoco Products Company, Clark Foam Products Corporation, JSP Corporation, Magna International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Expanded Polypropylene Foam Market Strategic Shifts & Innovations
Digital twin technology is penetrating expanded polypropylene process engineering, enabling real-time bead expansion modeling that reduces prototyping cycles and compresses time-to-production for complex automotive seating geometries.
Multi-physics simulation software is virtualizing steam-chest molding optimization, allowing engineers to predict cell structure formation before physical tool cutting. Tier-1 seating suppliers in Michigan are deploying these platforms to reduce tooling iteration counts by half. The technology is virtualizing traditional cut-and-try development methods, collapsing program timelines for new vehicle platforms.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is tightening volatile organic compound limits on foam fabrication facilities. Solvent-based adhesive bonding lines face mandatory emission control retrofit or shutdown across Ohio and Indiana converter plants. Fabricated foam segments serving electronics packaging are most affected, accelerating capital migration toward water-based laminating systems.
Specification consolidation among Detroit automakers is compressing approved material lists, forcing foam suppliers to qualify against bundled performance criteria rather than individual property tests. Tier-2 converters report extended validation cycles as OEMs demand simultaneous flammability, fogging, and odor compliance upfront. This concentration is most visible in seating programs where single-source contracts now span multiple vehicle nameplates.
North America Expanded Polypropylene Foam Market Segmentation
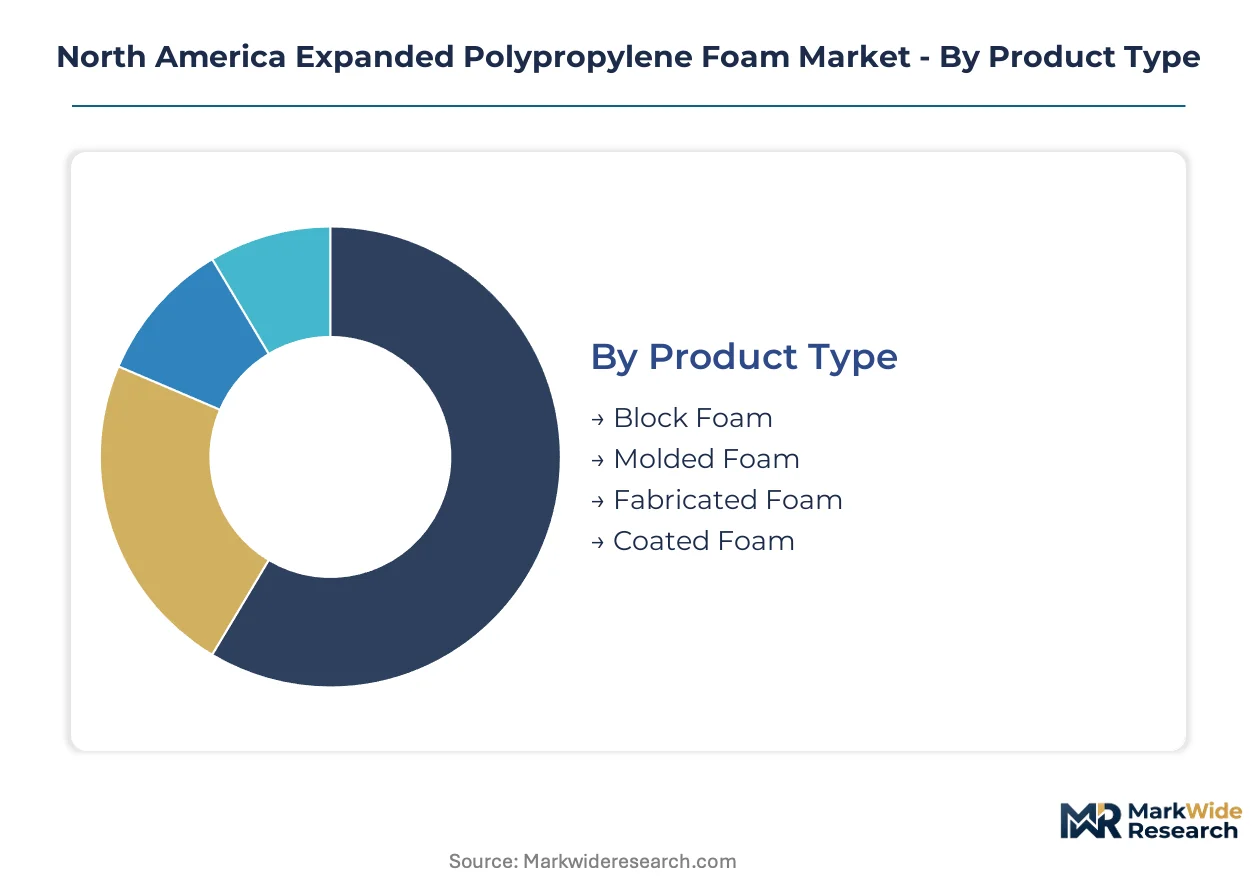
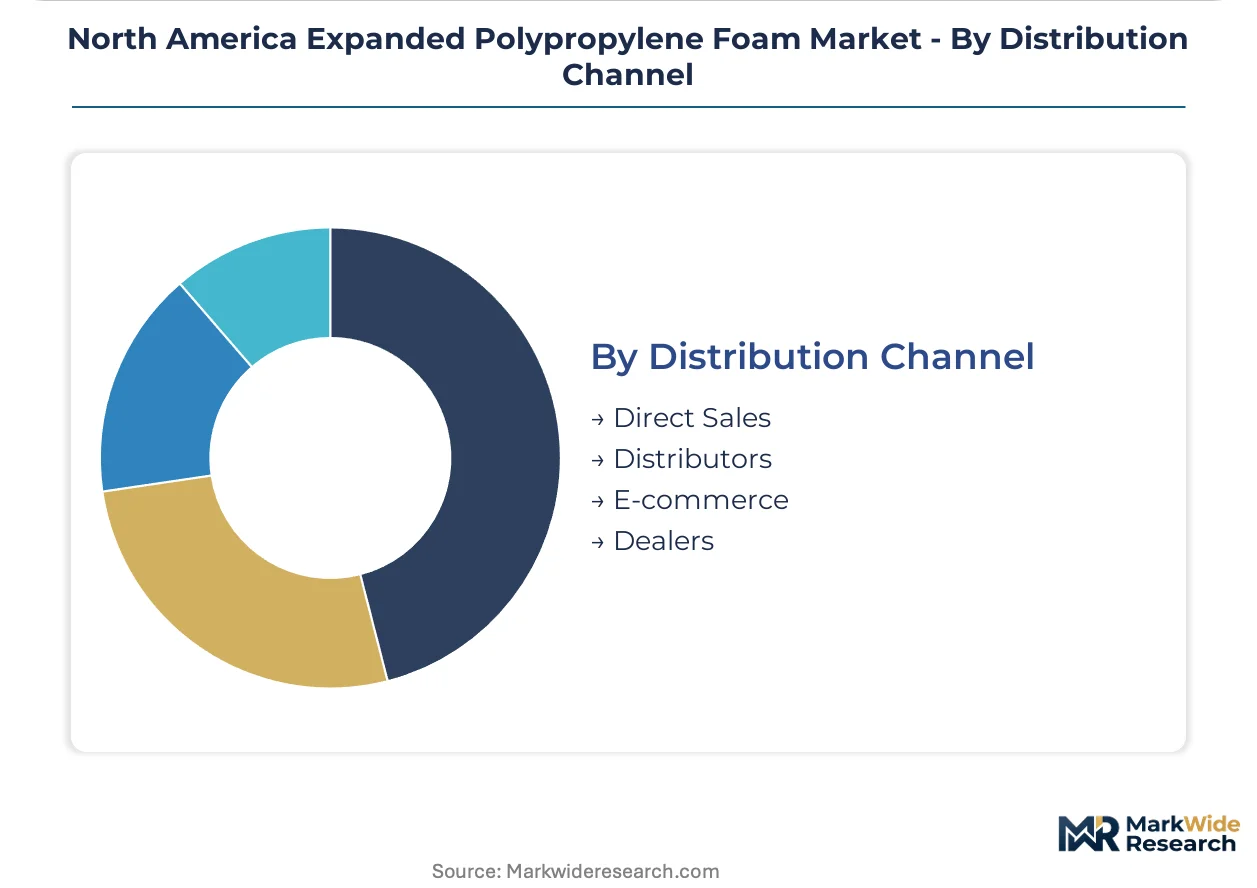
Segmentation in the North America expanded polypropylene foam market reveals how material form, application intensity, and channel economics create divergent margin profiles. Understanding these splits exposes where capital deployment yields the highest returns.
Product Type:
Cycle times vary dramatically across foam formats, with molded geometries locking in automotive platform decisions for years while fabricated inserts turn over quarterly with electronics packaging refresh rates.
- Molded Foam:Steam-chest molded beads achieve complex three-dimensional geometries with densities between fifteen and two hundred grams per liter. Detroit automakers specify these cores for seating structures and bumper assemblies across vehicle platforms with five-to-seven-year lifecycles. NHTSA fuel economy standards accelerate metal-to-foam substitution in these long-duration programs.
- Fabricated Foam:CNC-cut from expanded blocks into precision inserts, this format serves Midwest electronics packaging converters requiring rapid prototyping turnaround. EPA volatile organic compound enforcement on solvent-based bonding is accelerating water-based adhesive migration in these shorter-cycle operations.
- Block Foam:Raw expanded sheets supply downstream converters with standardized starting material for custom cutting operations.
- Coated Foam:Surface-treated variants command premium positioning through FDA biocompatibility validation for surgical instrument trays.
Molded foam dominates installed base. Fabricated foam is where expansion concentrates.
Application:
Cost tier separation is pronounced, with automotive interiors absorbing volume at compressed margins while medical devices sustain pricing power through regulatory barriers.
- Automotive Interiors:Seat cores, door panels, and headliners consume the majority of regional expanded polypropylene volume. Great Lakes manufacturing density creates logistics advantages for just-in-time delivery to Michigan and Ontario assembly plants. NHTSA gram-per-mile reduction targets sustain specification momentum despite propylene feedstock volatility.
- Packaging Solutions:Electronics protection and industrial dunnage represent the most dynamic demand segment. Midwest converters are deploying automated cutting cells to serve precision insert requirements from technology OEMs.
- Medical Devices:Surgical instrument trays and sterilization containers require validated sterilization resistance and surface biocompatibility.
- Consumer Goods:Sporting equipment and recreational product applications utilize lower-density formulations.
Automotive interiors anchor volume scale. Medical devices protect margin pools.
End User:
Customer concentration patterns split between consolidated automotive OEMs with single-source contracting power and fragmented packaging converters with dispersed procurement authority.
- Automotive Manufacturers:Detroit Three OEMs and their Tier-1 seating suppliers drive the majority of molded foam contracts. Specification consolidation is compressing approved material lists and extending validation cycles against bundled FMVSS 302, SAE J1756, and proprietary odor standards.
- Packaging Companies:Electronics protection specialists in Illinois, Ohio, and Michigan operate the fastest equipment refresh cycles. These converters face stranded asset risk as solvent-based bonding lines require ventilation overhaul for EPA compliance.
- Healthcare Providers:Hospital systems and surgical centers procure coated foam through medical device distributors with extended qualification protocols.
- Retailers:Big-box and e-commerce fulfillment operations source fabricated foam for protective shipping applications.
Automotive manufacturers lock in multi-year volume commitments. Packaging companies generate the most frequent specification refresh opportunities.
Distribution Channel:
Channel economics favor direct relationships for high-volume automotive programs while distributor networks capture fragmented packaging demand.
- Direct Sales:Tier-1 seating suppliers and major automotive OEMs negotiate direct contracts with foam converters. These relationships span multiple vehicle nameplates and require dedicated technical service support.
- Distributors:Regional industrial distributors serve packaging converters and smaller fabricators with inventory stocking and cut-to-size services.
- E-commerce:Online channels are penetrating standard-grade fabricated foam for consumer and small-business protective packaging.
- Dealers:Authorized dealer networks handle specialty coated foam for medical device applications requiring technical consultation.
Direct sales capture the largest contract values. Distributor relationships are expanding fastest among mid-tier packaging accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive seating buyers concentrate procurement authority in the Great Lakes manufacturing corridor, while medical device distributors fragment demand across dispersed healthcare systems. Regional performance splits between these concentrated and fragmented buyer archetypes.
United States
Michigan and Ohio anchor molded foam production for Detroit Three seating programs. NHTSA fuel economy standards accelerate gram-per-mile compliance through lighter interior components. The Detroit-Windsor-Flint triangle houses the densest concentration of steam-chest molding capacity serving just-in-time automotive assembly.
Canada
Ontario's automotive supplier base mirrors US Midwest operations across the Windsor border. Clean Fuel Regulations impose carbon intensity reduction mandates favoring lightweight materials in commercial vehicles. Toronto-area medical device converters specialize in FDA-validated coated foam for surgical instrument trays.
Mexico
Querétaro and Guanajuato host expanding automotive assembly plants drawing fabricated foam from US suppliers. PROFEPA environmental enforcement is tightening volatile organic compound limits on imported bonding systems. Electronics packaging converters in Tijuana serve cross-border technology OEMs with CNC-cut protective inserts.
North America Expanded Polypropylene Foam Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered supply positions. The market structure concentrates around integrated resin suppliers and independent converters serving distinct buyer segments. Three archetypes dominate: backward-integrated chemical majors with captive polypropylene supply, geographic-proximity fabricators co-located with automotive assembly, and medical-grade specialists commanding premium positioning through regulatory validation. Competitive moves center on specification consolidation through multi-nameplate contracting and water-based coating capacity retrofit for EPA compliance.
Among integrated chemical suppliers, BASF SE anchors the resin-to-foam value chain through captive polypropylene production. JSP Corporation exemplifies the technical-specialist archetype with proprietary bead-expansion positioning. Woodbridge represents geographic-proximity competition through Michigan and Ohio facilities sited within two hundred miles of major automotive assembly plants.
| Leading Market Players |
|---|
| Woodbridge |
| PDM Foam |
| BASF SE |
| Bradford Company |
| Knauf Industries |
| Sonoco Products Company |
| Clark Foam Products Corporation |
| JSP Corporation |
| Magna International, Inc. |
| Others |
Cost & Logistics Intelligence
Undercapacity in Great Lakes steam-chest molding facilities is tightening supplier leverage and compressing quote-to-contract timelines for Detroit automakers. This utilization squeeze rewards converters with captive polypropylene supply while forcing independent fabricators toward cost-plus indexation clauses that transfer feedstock risk.
Pricing Analysis
Cost-plus contracts indexed to propylene monomer benchmarks dominate automotive molded foam agreements. Price differentiation separates FDA-validated coated foam for surgical trays from commodity block foam serving industrial dunnage. Pricing pressure stems from polyurethane's persistent cost advantage in economy seating segments. Tier-1 automotive buyers exhibit the sharpest price sensitivity, while medical device distributors absorb premiums for validated sterilization resistance.
Supply Chain Analysis
Upstream polypropylene resin production concentrates in Texas, Louisiana, and Alberta petrochemical corridors. EPP foam manufacturing draws from propylene feedstock, steam-chest molding equipment, and water-based adhesive systems. Single-source vulnerability runs through Japanese and German machinery suppliers controlling bead-expansion technology. Distribution runs through direct sales for automotive programs and regional industrial distributors for fragmented packaging accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is cycling through an automotive production recovery. NHTSA fuel economy standards are sustaining gram-per-mile compliance spending that favors lightweight interior substitution.
For Market Incumbents: Insulate core automotive contracts through backward integration into polypropylene resin supply. BASF's captive feedstock model demonstrates how upstream control neutralizes margin compression from propylene volatility. Prioritize water-based coating capacity retrofits ahead of EPA enforcement waves in Ohio and Indiana.
For New Entrants and Emerging Players: Establish a beachhead in CNC-fabricated foam for Midwest electronics packaging converters. Medical device coated foam offers the most penetrable premium tier, with FDA validation protocols creating defendable positioning against commodity competitors. Lead with aqueous adhesive compliance to capture stranded solvent-based capacity.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-based laminating system deployments. Long-term viability favors converters with validated multi-specification certification against FMVSS 302, SAE J1756, and OEM odor standards. Watch EPA NESHAP enforcement intensity in Michigan and Ohio as the inflection signal for distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Coating Retrofit | EPA NESHAP compliance secures operating permits for Ohio and Indiana fabrication facilities. |
| Backward Integration into Resin | Captive polypropylene supply neutralizes feedstock volatility on fixed-price automotive contracts. |
| Medical-Grade Coating Validation | FDA biocompatibility protocols unlock premium pricing pools for surgical instrument tray applications. |
| CNC Fabrication Cell Deployment | Automated cutting capacity serves precision electronics packaging demand from Midwest technology OEMs. |
| Digital Twin Process Engineering | Multi-physics simulation collapses tooling iteration cycles for complex automotive seating geometries. |
Research Approach
Operator-level perspectives from steam-chest molding technicians, Tier-1 seating procurement managers, EPA compliance officers, and medical device packaging engineers anchored the qualitative base. Secondary validation drew from NHTSA fuel economy filings, EPA enforcement databases, automotive production registries, and customs trade records. Bottom-up capacity estimates triangulated against top-down demand segmentation.
Scenario-bracketing around propylene price volatility and automotive production cycles framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product format, application intensity, end-user concentration, and regional manufacturing density. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion pipelines.
Stress conditions across propylene feedstock spikes, NHTSA regulatory stringency, and EPA enforcement timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Cross-checking against IHS Markit vehicle production forecasts and ACC resin demand data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
Impact Sound Insulation Acoustic Mat Market
Insulation Materials
Global Pipe Insulation Market
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Flexible Insulation Market
Insulation Materials
Global Low Smoke Halogen-Free Cable Materials Market
Insulation Materials
Mineral Wool Board Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Global Insulation Market
Insulation Materials
Refrigeration Insulation Materials Market
Insulation Materials
Active Insulation Market
Insulation Materials
Carbon Foam Market
Insulation Materials
Asia-Pacific Insulation Materials Market
Insulation Materials
Thermal Tapes Market
Insulation Materials
Moistureproof Glass Wool Market
Insulation Materials
Low-Frequency Sound-Absorbing Insulation Materials Market
Insulation Materials
High Temperature Insulation Market