
 Expanded Polypropylene Market | 2026-2036
Expanded Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Expanded Polypropylene Market Analysis
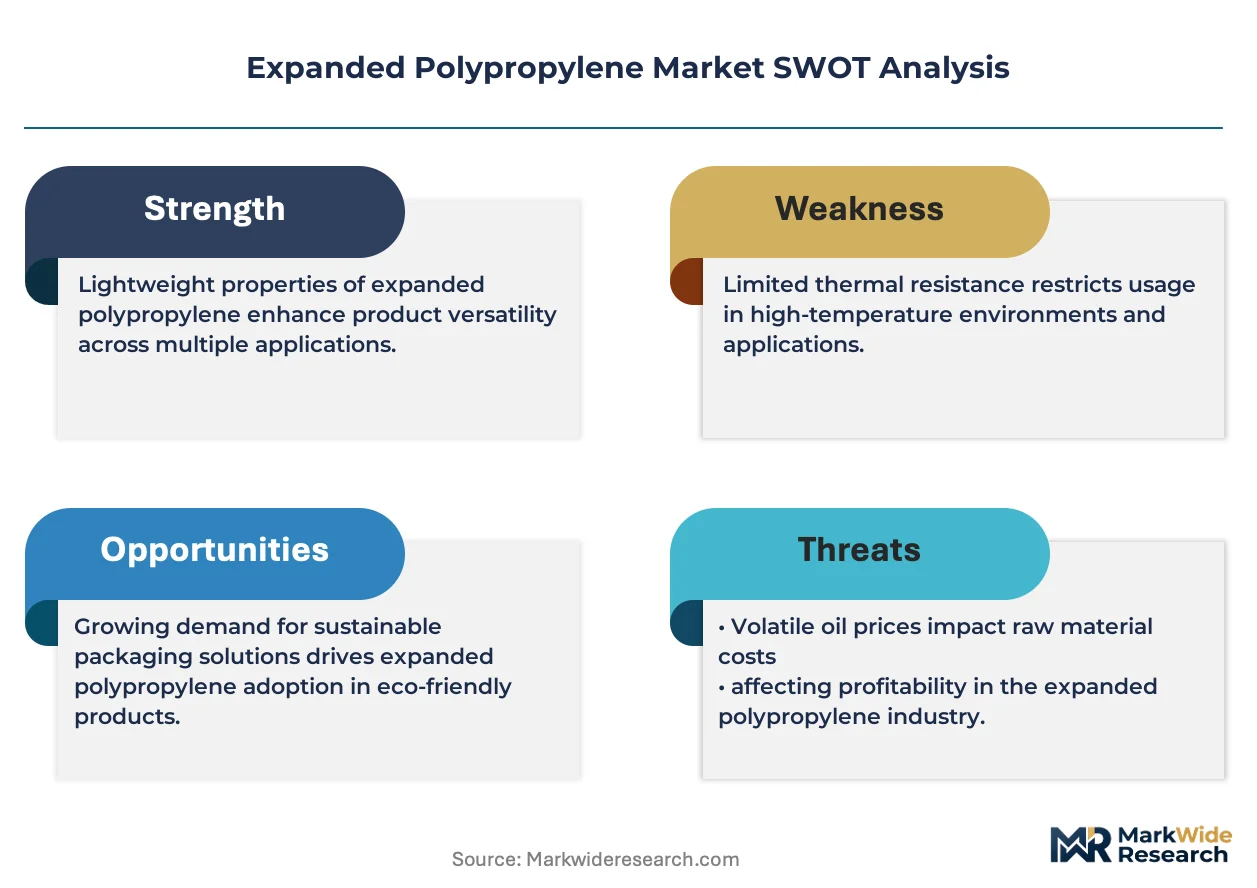
Polymer compounding expertise is bifurcating the competitive landscape between integrated resin producers and specialized foam converters. BASF SE leverages its global catalyst technology network to sustain premium-grade EPP supply chains across European automotive platforms. JSP Corporation anchors Japanese OEM relationships through proprietary bead-foam molding systems that dominate Asia-Pacific passenger vehicle programs. Kaneka Corporation differentiates via high-expansion ratio formulations that serve precision packaging applications in electronics and medical device sectors.
Expanded polypropylene comprises closed-cell foam structures manufactured through autoclave or extrusion expansion of polypropylene resin beads, typically achieving densities between 20 and 200 grams per liter with thermal insulation values competitive against expanded polystyrene. The material serves primarily as a lightweight, impact-absorbing, and thermally stable substrate across automotive bumper cores, protective packaging, and building insulation systems. Foam block formats command the largest volume share within product type segments due to their processing flexibility across molding and fabrication workflows. Automotive interiors represent the fastest-expanding application channel as manufacturers substitute heavier polyurethane and metal assemblies with recyclable EPP instrument panels and door inserts. OEM end users concentrate procurement among qualified tier-one suppliers who maintain IATF 16949 certification and just-in-sequence delivery capabilities.
The EPA oversees volatile organic compound emissions from foam manufacturing facilities under Clean Air Act provisions, while OSHA mandates respiratory protection standards for workers handling expanded bead dust in fabrication environments. REACH restrictions on persistent organic pollutants constrain certain flame-retardant additives used in construction-grade EPP, redirecting R&D toward halogen-free intumescent systems. China's MEE enforces dual carbon goals that pressure domestic producers to adopt steam-recovery expansion technologies and renewable power inputs. Stakeholders must monitor evolving automotive circular-economy mandates that will condition EPP recyclability certifications and post-consumer content requirements across major manufacturing jurisdictions.
Market Dynamics
Automotive OEMs in Germany and Japan are accelerating substitution of metal and polyurethane assemblies with recyclable EPP instrument panels, creating ripple effects through resin supply chains and foam converter qualification programs. This material transition is compressing traditional tier structures and forcing compounders to co-locate near vehicle assembly plants.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon blowing agents is redirecting appliance insulation demand toward EPP's water-based steam expansion processes.
- EV battery packaging:China's eastern manufacturing corridor processors are scaling high-density foam enclosures for lithium-ion cell modules requiring thermal runaway containment.
- Autoclave bead expansion:Process refinements enabling 40:1 expansion ratios are opening medical device cushioning applications previously served by expanded polystyrene.
Market Restraints
- Propylene feedstock volatility:Crude oil and naphtha price swings compress foam converter margins during contract renegotiations with automotive tier-one suppliers.
- REACH persistent organic pollutant restrictions:Flame-retardant additive bans constrain construction-grade EPP formulations, forcing halogen-free system redevelopment.
- Expanded polystyrene cost advantage:Lower resin prices and established molding infrastructure limit EPP penetration in disposable protective packaging segments.
Strategic Opportunities
- India's PLI scheme for automotive:Component localization mandates create greenfield opportunities for EPP molding facilities serving Maruti Suzuki and Hyundai Motor India programs.
- Building energy retrofit mandates:Germany's Building Energy Act is stimulating demand for EPP exterior insulation and finish systems in residential renovation projects.
- Steam-recovery expansion technology:Convergence with renewable power inputs allows Chinese producers to meet MEE dual carbon compliance while reducing operational energy intensity.
Industry Challenges
- IATF 16949 certification timelines:Foam converters face 12-18 month qualification periods to enter automotive just-in-sequence supply chains, delaying revenue recognition.
- Bead foam molding technician scarcity:Specialized process control expertise for density gradient management remains concentrated among Japanese and German equipment specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Expanded Polypropylene Market |
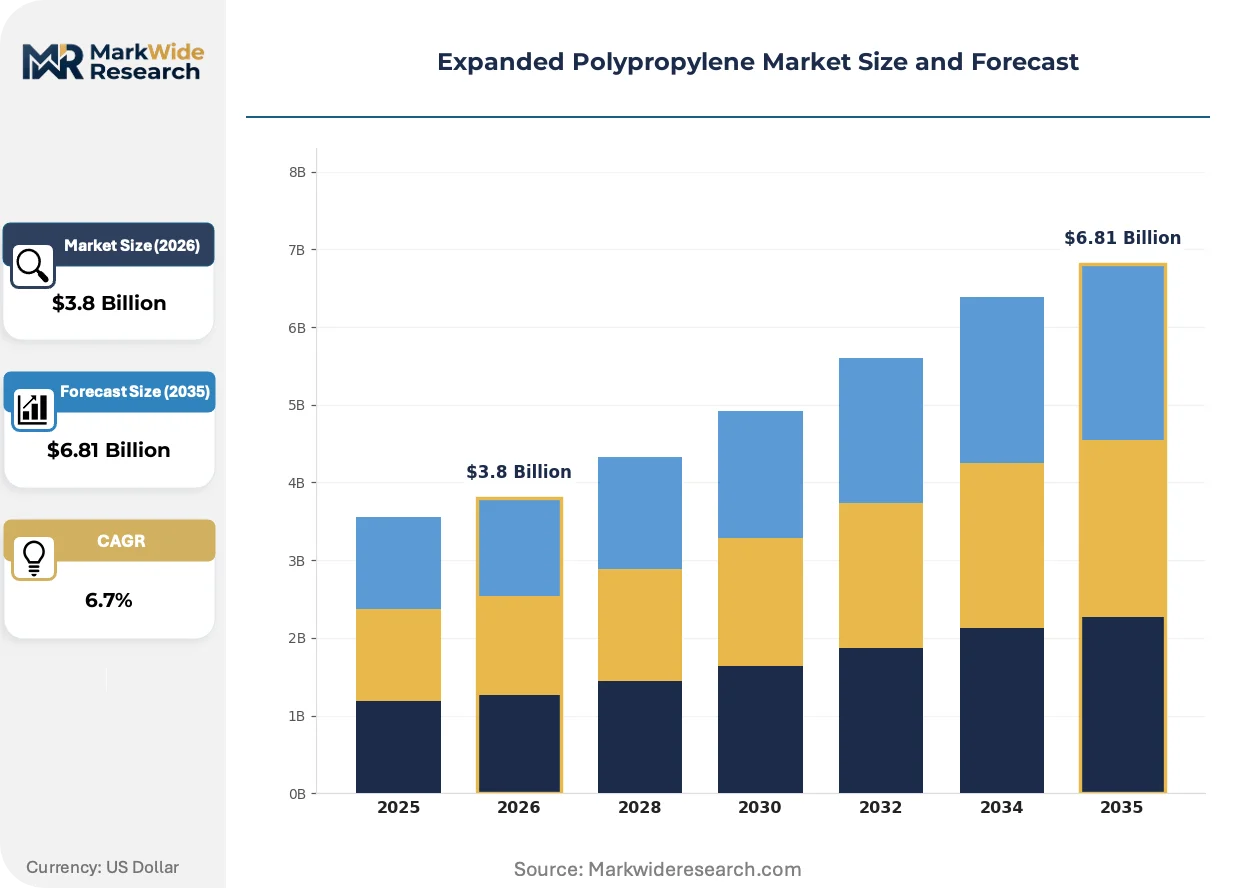
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Sheet, Foam Block, Foam Pellet, Foam Shape Application: Automotive Interiors, Packaging Solutions, Construction Materials, Consumer Goods End User: OEMs, Manufacturers, Retailers, Distributors Form: Solid, Expanded, Composite, Flexible |
| Companies Covered | JSP Corporation, Kaneka Corporation, BASF SE, Sonoco Products Company, DS Smith, Hanwha Corporation, Furukawa Electric Co., Knauf Industries, The Woodbridge Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Expanded Polypropylene Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are converging to reshape how expanded polypropylene compounds are formulated, processed, and specified across end-use verticals. Three distinct vectors are compressing legacy supply arrangements.
High-expansion ratio bead formulations are decomposing the traditional density-performance tradeoff in protective packaging. Electronics OEMs in South Korea and Taiwan are qualifying 60:1 expansion grades for smartphone and tablet cushioning that previously required denser polyurethane foams. This density reduction is decomposing established cost structures in precision logistics, enabling single-material recyclable solutions that bypass mixed-waste separation requirements.
REACH restrictions on halogenated flame retardants are compelling construction-grade compounders to reformulate with intumescent phosphorus-nitrogen systems. ECHA's 2023 substance evaluation roadmap has designated several brominated additives as substances of very high concern, forcing insulation manufacturers to validate new char-forming chemistries through EN 13501 fire performance testing. German and French building material distributors are now prioritizing EPP suppliers with certified halogen-free portfolios in public procurement frameworks.
Automotive interior buyers are consolidating specification authority at the platform engineering level, bypassing traditional tier-two foam converter relationships. BMW and Volkswagen Group programs now mandate direct material approval for EPP grades used in visible cabin components, compressing the supplier base to resin producers with captive compounding capabilities. This concentration is most visible in Bavaria and Lower Saxony, where BASF maintains dedicated technical service teams co-located with OEM styling studios.
Expanded Polypropylene Market Segmentation
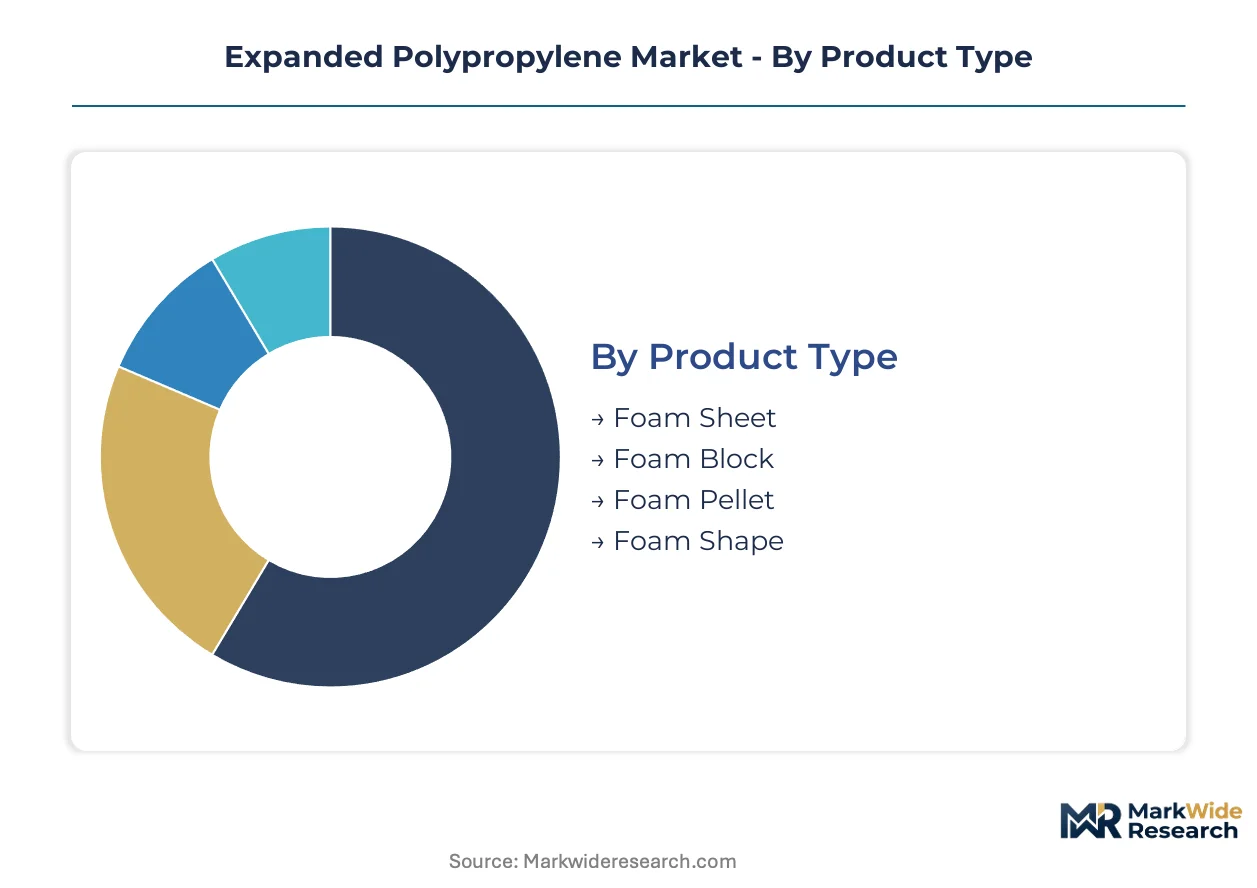
EPP segmentation reveals how material form and customer type dictate geographic sourcing strategies. Foam converters serving automotive OEMs operate under fundamentally different logistics constraints than packaging distributors supplying fragmented retail channels.
Product Type:
Domestic production dominates foam block and pellet supply, while foam sheet and specialized shapes travel longer distances to reach fabrication hubs.
- Foam Block:Large-format molded blocks serve as feedstock for CNC machining and thermoforming operations across automotive bumper core manufacturing. German and Japanese OEMs source primarily from regional compounders maintaining just-in-sequence delivery contracts with assembly plants.
- Foam Sheet:Continuous extruded sheets target building insulation and appliance lining applications. China's eastern manufacturing corridor processors export rolled sheet stock to Southeast Asian appliance assembly facilities facing EU F-Gas Regulation compliance deadlines.
- Foam Pellet:Pre-expanded beads supply custom molders serving medical device cushioning and precision electronics packaging.
- Foam Shape:Net-shape molded components eliminate secondary fabrication for specific automotive interior and consumer goods applications.
Foam block holds the largest share; momentum sits with foam sheet as building energy retrofit mandates accelerate across European member states.
Application:
Cost tier separation is pronounced: automotive interiors command premium pricing against commodity construction and consumer goods volumes.
- Automotive Interiors:Instrument panels, door inserts, and seating substrates substitute metal and polyurethane assemblies. BMW and Volkswagen Group platform engineers now mandate direct material approval for visible cabin components, compressing supplier qualification timelines.
- Packaging Solutions:Protective cushioning for electronics and medical devices leverages high-expansion ratio formulations. South Korean and Taiwanese OEMs are qualifying 60:1 expansion grades for smartphone logistics that previously required polyurethane systems.
- Construction Materials:Exterior insulation and finish systems compete with expanded polystyrene on installed cost. REACH persistent organic pollutant restrictions constrain halogenated flame-retardant formulations, forcing halogen-free system redevelopment.
- Consumer Goods:Furniture cores, toys, and recreational equipment represent price-sensitive volume applications with limited specification authority.
Automotive interiors command premium margins; packaging solutions are expanding most quickly as electronics OEMs consolidate around single-material recyclable solutions.
End User:
Procurement patterns diverge sharply between qualified automotive tier-one suppliers and fragmented retail distribution channels.
- OEMs:Vehicle manufacturers and major appliance brands specify material grades directly, bypassing traditional converter relationships. IATF 16949 certification and just-in-sequence delivery capabilities are mandatory entry requirements.
- Manufacturers:Tier-two component suppliers and foam fabricators purchase standard grades for secondary processing. Margin pressure intensifies during propylene feedstock price volatility.
- Retailers:Big-box chains and e-commerce platforms source protective packaging through distributors with limited technical specification involvement.
- Distributors:Building material and industrial supply wholesalers carry construction-grade insulation and general-purpose foam products.
OEMs concentrate the highest value procurement; distributors represent the most fragmented channel with limited pricing power.
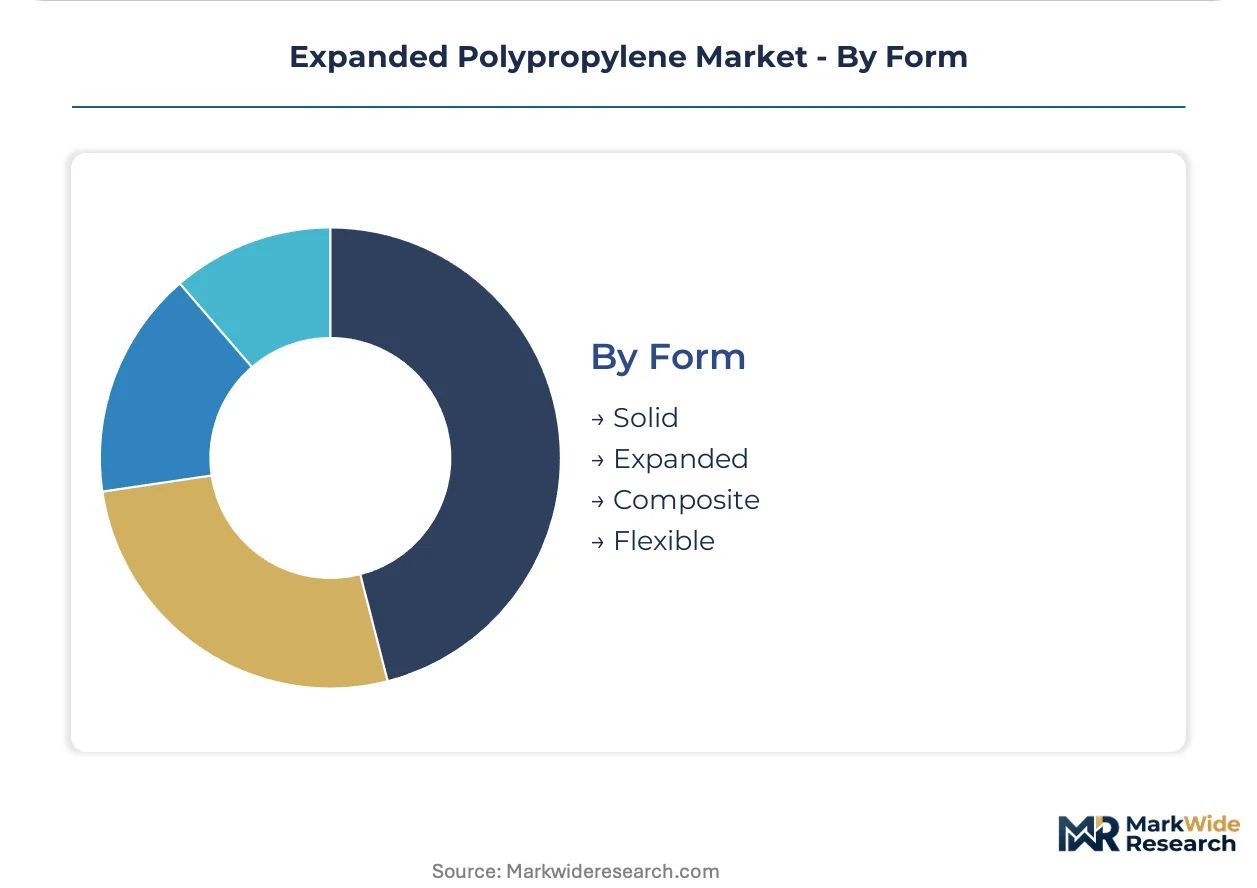
Form:
Supply concentration varies by processing complexity, with expanded and composite forms requiring specialized equipment versus commodity solid grades.
- Solid:Unexpanded resin pellets serve captive compounding operations at integrated resin producers.
- Expanded:Bead and block formats dominate commercial volume, produced through autoclave or extrusion expansion achieving densities between 20 and 200 grams per liter.
- Composite:Multi-layer and fiber-reinforced structures address specific automotive and medical device performance requirements.
- Flexible:Low-density formulations target cushioning and sealing applications with modified resilience characteristics.
Expanded form holds the largest share; composite structures are gaining share fastest as automotive platform engineering consolidates specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE's dual carbon goals anchor China's eastern manufacturing corridor, where domestic foam processors scale EPP production for EV battery packaging and appliance insulation. The EU's F-Gas Regulation and REACH compliance reshape material specifications across member states, while automotive OEMs in Germany and Japan accelerate lightweight interior adoption.
China
Domestic foam processors in Jiangsu and Zhejiang provinces serve lithium-ion cell module enclosures requiring thermal runaway containment. MEE enforcement of dual carbon goals pressures producers toward steam-recovery expansion technologies and renewable power inputs. The Yangtze River Delta cluster concentrates high-density EPP molding capacity for EV battery packaging.
Germany
BMW and Volkswagen Group platform engineers mandate direct material approval for visible cabin EPP components, compressing supplier qualification timelines. The Building Energy Act stimulates demand for exterior insulation and finish systems in residential renovation projects. Bavaria and Lower Saxony host BASF technical service teams co-located with OEM styling studios.
Japan
JSP Corporation anchors relationships with domestic OEMs through proprietary bead-foam molding systems dominating passenger vehicle programs. METI industrial policy supports lightweight material substitution in automotive manufacturing. The Nagoya-Tokyo corridor concentrates specialized process control expertise for density gradient management.
United States
EPA Clean Air Act provisions govern volatile organic compound emissions from foam manufacturing facilities nationwide. OSHA mandates respiratory protection standards for workers handling expanded bead dust in fabrication environments. The Southeast automotive belt attracts EPP compounders seeking proximity to vehicle assembly plants.
South Korea
Electronics OEMs qualify 60:1 expansion ratio EPP grades for smartphone and tablet cushioning previously served by polyurethane systems. MFDS medical device regulations shape precision packaging specifications for pharmaceutical logistics. The Gyeonggi-Seoul cluster concentrates high-expansion formulation R&D for electronics applications.
Expanded Polypropylene Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the EPP value chain. Integrated resin producers with captive compounding capabilities dominate premium automotive specifications, while specialized foam converters compete on molding flexibility and regional logistics. Three archetypes define competitive positioning: global catalyst technology networks, proprietary bead-foam system specialists, and high-expansion ratio formulation innovators. Capacity co-location near vehicle assembly plants and halogen-free flame-retardant redevelopment represent the dominant competitive moves reshaping supply relationships.
Among integrated chemical conglomerates, BASF SE exemplifies the catalyst technology archetype sustaining premium-grade supply chains across European automotive platforms. JSP Corporation and Kaneka Corporation anchor the specialized formulation tier, with the former representing proprietary bead-foam molding dominance in Asia-Pacific passenger vehicles and the latter occupying high-expansion precision packaging positions in electronics and medical device sectors. These three companies collectively illustrate how polymer compounding expertise bifurcates competitive positioning between resin producers and foam converters.
| Leading Market Players |
|---|
| JSP Corporation |
| Kaneka Corporation |
| BASF SE |
| Sonoco Products Company |
| DS Smith |
| Hanwha Corporation |
| Furukawa Electric Co. |
| Knauf Industries |
| The Woodbridge Group |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German automotive OEMs and regional compounders lock in supply access and price visibility across multi-year vehicle platform cycles, insulating qualified suppliers from propylene feedstock volatility while compressing margins for spot-market participants.
Pricing Analysis
Geographic price spreads between European automotive-grade EPP and Asian commodity foam block reach double-digit percentage differentials, reflecting IATF 16949 certification premiums and just-in-sequence logistics costs. Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct automotive specifications from tier-two converter grades and distributor-sourced construction insulation. Cost compression in commodity packaging tiers intensifies as expanded polystyrene maintains resin price advantages, while automotive interior buyers show lowest price sensitivity due to platform engineering consolidation and recyclability mandates.
Supply Chain Analysis
Inbound logistics costs from Yangtze River Delta ports to Southeast Asian appliance assembly facilities fluctuate with container availability on Asia-Europe trade lanes, compressing margin buffers for Chinese foam sheet exporters. Supply concentrates in Germany, Japan, and China's eastern manufacturing corridor, with raw material flows drawing from naphtha crackers and polypropylene resin producers in South Korea and Saudi Arabia. Single-source vulnerability around proprietary bead-foam molding equipment from Japanese specialists creates qualification bottlenecks. Distribution runs through qualified tier-one automotive suppliers and fragmented building material wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through REACH compliance and IATF 16949 certification creates sustainable barriers against unqualified entrants.
For Market Incumbents: Fortify captive compounding capabilities through backward integration into polypropylene resin supply, co-locating expansion capacity near BMW and Volkswagen Group assembly plants in Bavaria and Lower Saxony. Deepen technical service relationships with OEM platform engineers to preempt direct material approval requirements from resin competitors. Prioritize halogen-free flame-retardant R&D to capture German Building Energy Act retrofit demand before REACH restrictions fully constrain legacy additive formulations.
For New Entrants and Emerging Players: Anchor in India's PLI scheme for automotive component localization, where Maruti Suzuki and Hyundai Motor India programs lack qualified domestic EPP molding capacity. Target medical device cushioning applications in South Korea and Taiwan where 60:1 expansion ratio formulations command premium positioning against polyurethane incumbents. Pursue joint development agreements with electronics OEMs seeking single-material recyclable packaging solutions to bypass mixed-waste separation requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated resin producers with captive automotive qualification status and long-term offtake structures. Five-to-ten year viability favors compounders with dual capability in high-expansion precision packaging and construction-grade insulation halogen-free redevelopment. Acquisition targets should demonstrate steam-recovery expansion technology adoption to meet China's MEE dual carbon compliance. Monitor EU F-Gas Regulation phase-down timelines as inflection indicator for appliance insulation demand redirection toward EPP.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive polypropylene resin supply secures margin control against naphtha price volatility. |
| Capacity Co-location | Proximity to German OEM assembly plants enables just-in-sequence delivery compliance. |
| Halogen-free Reformulation | REACH-compliant flame-retardant systems unlock German public procurement frameworks. |
| Steam-recovery Technology | MEE dual carbon alignment reduces operational energy intensity for Chinese producers. |
| High-expansion R&D | 60:1 ratio formulations displace polyurethane in South Korean electronics logistics. |
Methodological Framework
A spread of perspectives from automotive platform engineers, foam converter plant managers, resin procurement leads, and building material distributors converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against customs data, ACC and Cefic industry reports, and SEC filings from integrated chemical conglomerates. Bottom-up volume modeling from named production facilities and top-down demand triangulation from OEM vehicle platform specifications were cross-referenced for convergence.
Segmentation dimensions modeled include product form, application vertical, end-user procurement tier, and geographic production cluster across the analysis window. CAGRs were derived from slope analysis of historical volume trajectories and forward projection of regulatory-driven substitution elasticities. Key forecast inputs encompass EV battery packaging content per vehicle, REACH substance evaluation timelines, and F-Gas Regulation compliance deadlines reshaping appliance insulation specifications.
Material uncertainties — propylene feedstock price swings, REACH SVHC designations, and MEE enforcement intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions about qualification timeline durations and platform engineering consolidation trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East Polyethylene Market
Polymers & Resins
Antimicrobial Plastics Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Global Emulsion Polymer Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Neoprene Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
Nylon 4-6 Market