
 Plastic Dielectric Films Market | 2026-2036
Plastic Dielectric Films Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Dielectric Films Market Intelligence
Direct-to-OEM sales channels for high-volume capacitor applications are rewriting the competitive landscape for film suppliers. Toray Industries, Inc. leverages its immense scale in polypropylene film production to secure these large, strategic contracts. DuPont Teijin Films specializes in high-performance polyester films for niche, high-margin applications, differentiating on technical specifications. SABIC competes on material innovation, particularly in advanced polycarbonate-based films for demanding automotive electronics.
Plastic dielectric films are thin polymer materials specifically engineered for high dielectric strength and a low dissipation factor. Processed to thicknesses often below 10 micrometers, they serve as the primary electrical insulating layer in critical components like capacitors. Polypropylene films dominate the product landscape by volume, driven by their use in standard power capacitor applications. The automotive end-user segment, however, is showing the most rapid expansion, creating new margin opportunities for films with superior thermal stability.
Compliance with chemical regulations, including the EU's REACH framework and substance rules under the US EPA, dictates material formulation and market access. In parallel, China's GB standards for electronic components create specific performance benchmarks that are non-negotiable for suppliers. The ability to tailor polymer formulations to meet these divergent regional safety and performance criteria will separate market leaders from followers.
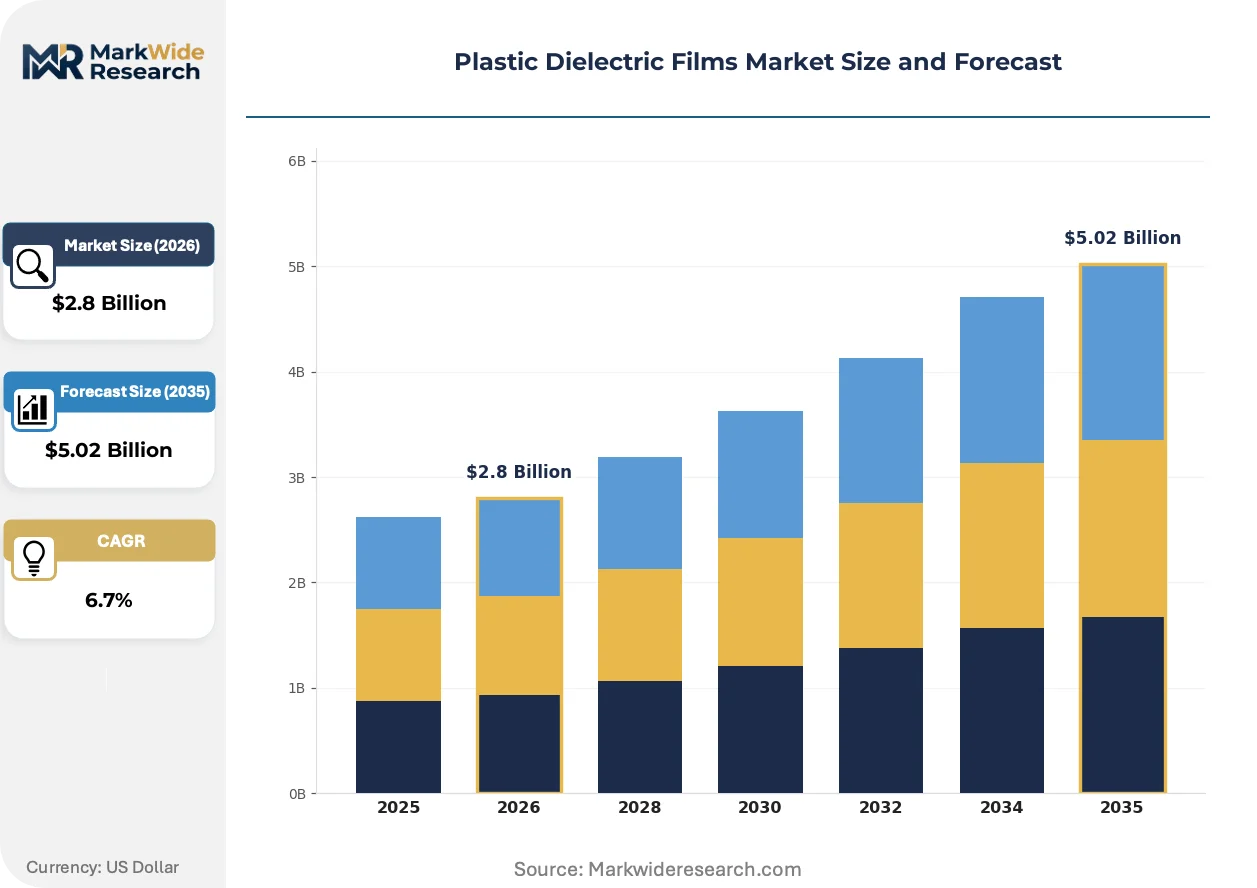
Market Dynamics
The primary force defining the plastic dielectric film market is the tightening web of chemical regulations. Mandates like the EU's REACH and RoHS directives are compelling polymer reformulation, directly influencing which materials can access high-value electronics and automotive markets, separating compliant innovators from commodity suppliers.
Growth Catalysts
- Electric Vehicle Adoption:The proliferation of electric vehicles creates substantial demand for polypropylene and polyester films for capacitors used in on-board chargers, DC-DC converters, and battery management systems.
- Renewable Energy Infrastructure:Expansion of solar and wind power generation requires vast quantities of power capacitors for inverters and grid stabilization, driving volume consumption of metallized polypropylene films.
- Electronics Miniaturization:The continuous drive for smaller, more powerful consumer electronics and telecommunication devices necessitates the use of ultra-thin dielectric films with superior electrical properties.
Market Restraints
- Raw Material Price Volatility:Film pricing is highly sensitive to fluctuations in petrochemical-derived feedstocks like polypropylene and polyethylene terephthalate resins, creating margin pressure for manufacturers.
- High Capital Investment:The manufacturing of high-quality dielectric films requires significant capital expenditure for precision extrusion, stretching, and slitting equipment, creating a high barrier to entry for new players.
- Threat from Ceramic Capacitors:In certain low-voltage and high-frequency applications, multilayer ceramic capacitors (MLCCs) present a viable alternative, competing for design wins in compact electronic devices.
Strategic Opportunities
- High-Temperature Film Development:There is a significant opportunity for films with enhanced thermal stability, capable of reliable operation above 125°C for demanding automotive under-hood and power electronics applications.
- Grid-Scale Energy Storage:The build-out of battery energy storage systems (BESS) for utility grids presents a major new market for large-format, high-voltage capacitors, requiring robust dielectric films.
- Sustainable Polymer Formulations:Developing bio-based or easily recyclable dielectric films offers a path to differentiation for suppliers catering to OEMs with aggressive corporate sustainability and circular economy goals.
Industry Challenges
- Stringent Process Control:Maintaining consistent sub-10 micrometer thickness and eliminating microscopic defects across wide film webs is a major operational challenge that directly impacts capacitor yield and reliability.
- Navigating Divergent Standards:Suppliers face complexity and increased testing costs to ensure film products comply with multiple regional and industry-specific standards, including China's GB standards and automotive AEC-Q200.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Dielectric Films Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polyvinylidene Fluoride, Others Application: Capacitors, Insulators, Automotive Parts, Consumer Electronics End User: Aerospace, Electronics, Automotive, Renewable Energy Form: Rolls, Sheets, Laminates, Tapes |
| Companies Covered | DuPont Teijin Films, Toray Industries, Inc., Mitsubishi Chemical Corp., SABIC, Jindal Films, Steiner GmbH & Co. KG, COVEME S.p.A., Bolloré Group, Tervakoski Film, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Dielectric Films Market Strategic Shifts & Innovations
Material science innovation and regulatory compliance are the defining currents in the plastic dielectric films sector. These forces are pushing manufacturers beyond commodity film production toward specialized materials engineered for specific high-stress applications and regional market access.
High-performance film technology is migrating from standard, single-layer polypropylene to advanced, multi-layer, or surface-treated constructions. Power electronics and electric vehicle inverter manufacturers are rapidly adopting these engineered films for their superior thermal and voltage endurance. This evolution enables the design of more compact and reliable capacitors capable of operating in harsh automotive environments.
The European Union's REACH regulation directly impacts material formulations by restricting specific chemical substances used in polymer production. This forces film manufacturers to invest in R&D for compliant alternatives, often at a higher cost. The automotive electronics segment is most affected, requiring extensive re-qualification of components to maintain access to the European market.
Direct-to-OEM sourcing models are becoming the standard for high-volume applications. Instead of relying on distributors, major electric vehicle and renewable energy equipment makers are forming strategic partnerships with film producers. This shift, most prominent in China’s industrial clusters, allows for co-development of materials and guarantees supply chain stability for critical components.
Plastic Dielectric Films Market Segmentation
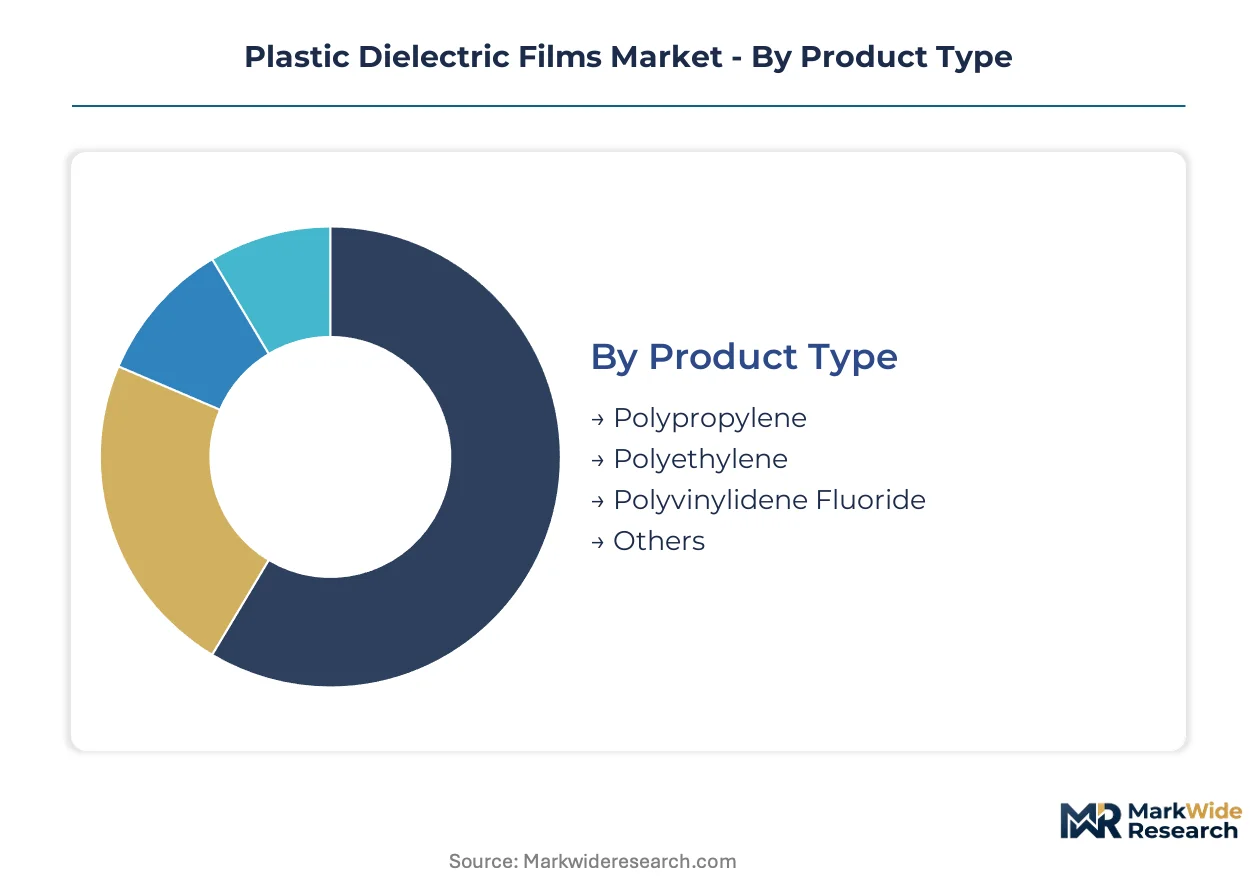
Market segmentation provides a granular view of the plastic dielectric films industry, highlighting specific product compositions, application areas, end-user demand, and physical forms. This detailed breakdown allows suppliers to align their product development and sales strategies with precise market needs and emerging growth opportunities.
Product Type:
The product type segmentation reveals the diverse material science approaches addressing varying performance requirements across the industry.
- Polypropylene:A primary material for power capacitors due to its excellent dielectric strength and low dissipation factor. Demand concentrates in renewable energy inverters and electric vehicle charging systems across China.
- Polyethylene:Utilized in specific low-frequency insulation and cable applications where cost-effectiveness is a primary consideration.
- Polyvinylidene Fluoride:Valued for its high thermal stability and piezoelectric properties, making it suitable for demanding automotive electronics and sensor applications. Adoption is gaining traction in European battery management systems.
- Others:Encompasses specialized polymers like PEN and PPS, engineered for extreme temperature or unique chemical resistance requirements in aerospace.
Established volume favors Polypropylene; emerging adoption favors Polyvinylidene Fluoride.
Application:
Application areas dictate film specifications, influencing both production volume and required performance characteristics.
- Capacitors:This is the largest application segment, where films form the dielectric layer for energy storage and filtering in power electronics. Significant volume is consumed in grid stabilization projects in India.
- Insulators:Dielectric films provide electrical isolation in motors, transformers, and switchgear, protecting components from voltage breakdown.
- Automotive Parts:Films are integrated into various automotive components, including sensors, wiring harnesses, and battery packs, requiring high thermal stability and vibration resistance. Demand is accelerating for electric vehicle platforms in Germany.
- Consumer Electronics:Ultra-thin films enable miniaturization in smartphones, laptops, and wearable devices, contributing to compact designs.
Capacitor manufacturing remains the largest segment, while automotive applications are experiencing the steepest expansion trajectory.
End User:
Different end-user industries present distinct purchasing patterns and performance expectations for plastic dielectric films.
- Aerospace:High-performance films are specified for lightweight, radiation-resistant components in avionics and satellite systems.
- Electronics:The broad electronics industry uses films for general-purpose capacitors, flexible circuits, and various insulating applications.
- Automotive:This sector demands films with extreme temperature resistance and reliability for electric vehicle powertrains and advanced driver-assistance systems. China's electric vehicle manufacturing clusters are major consumers.
- Renewable Energy:Films are critical for power capacitors in solar inverters and wind turbine converters, requiring long-term stability under high voltage. European grid modernization projects consume extensive film quantities.
The Automotive sector drives innovation for thermal stability, while Renewable Energy accounts for substantial film volume.
Form:
The physical form of dielectric films determines their ease of processing and integration into final electronic components.
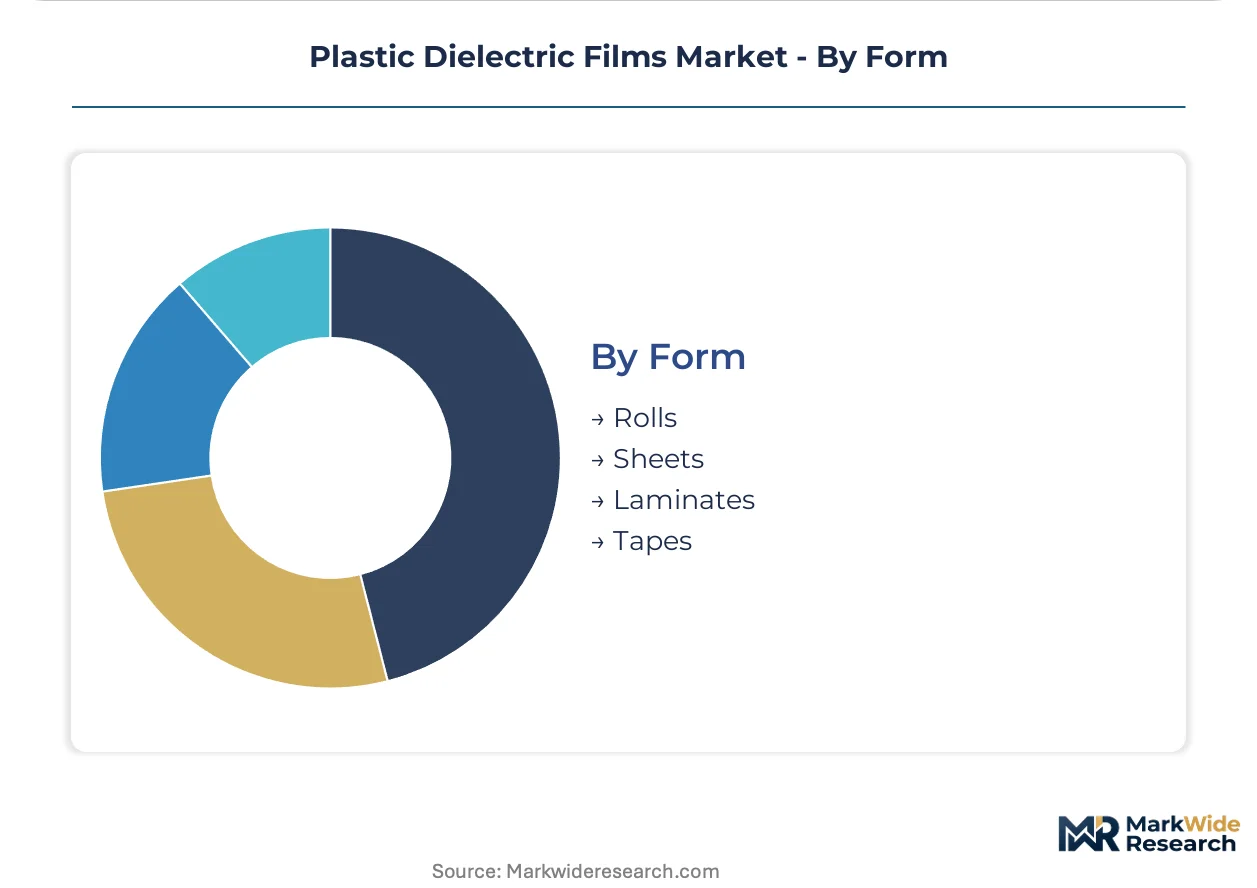
- Rolls:Predominant for high-volume capacitor manufacturing, allowing continuous processing on automated winding machines. This form is essential for large-scale power capacitor production in South Korea.
- Sheets:Utilized for specific insulation applications or prototyping where individual component fabrication is required.
- Laminates:Multi-layered constructions offering enhanced barrier properties or integrated functionalities, often used in flexible printed circuits and specialized insulation. Demand is increasing for compact designs in Japan.
- Tapes:Employed for electrical insulation, bundling, and protection in wiring harnesses and smaller electronic assemblies.
Rolls facilitate high-volume capacitor production, whereas Laminates offer enhanced functional integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards significantly influence plastic dielectric film specifications for electronic components. These stringent performance benchmarks are non-negotiable for manufacturers seeking market access. The country's rapid expansion in electric vehicle and renewable energy drives substantial demand.
China
Demand for polypropylene films concentrates in renewable energy inverters and electric vehicle charging systems. China's GB standards create specific performance benchmarks for suppliers. Major electric vehicle manufacturing clusters in Shenzhen and Shanghai are major consumers of these films.
Germany
The automotive end-user segment in Germany shows rapid expansion for films with superior thermal stability. European regulations like REACH and RoHS dictate material formulation. Stuttgart's automotive industry drives demand for advanced polycarbonate-based films for demanding electronics.
United States
Expansion of solar and wind power generation requires vast quantities of power capacitors. Substance rules under the US EPA dictate material formulation for market access. Silicon Valley, a hub for consumer electronics, necessitates ultra-thin dielectric films for miniaturization.
India
Grid stabilization projects in India consume significant volumes of films for capacitor manufacturing. The Indian government's renewable energy targets boost demand for power capacitors. Bengaluru's electronics manufacturing ecosystem requires robust dielectric films for various applications.
South Korea
High-volume capacitor manufacturing for advanced electronics and electric vehicles drives film consumption. South Korea's industrial policies support the development of high-performance materials. Gyeonggi Province, a major electronics production hub, relies on continuous film processing in rolls.
Plastic Dielectric Films Market Key Industry Players
Scale-driven manufacturers and specialized innovators split the plastic dielectric films market. This market exhibits a tiered structure, with high-volume producers focusing on cost efficiency and economies of scale for standard applications like power capacitors. Specialized players differentiate through advanced material science, technical specifications, and compliance with stringent regional regulations for niche, high-margin uses. Strategic partnerships with key OEMs and continuous capacity expansion represent dominant competitive moves for market participants.
At the scale-driven end, Toray Industries, Inc. exemplifies a major producer leveraging immense polypropylene film production capabilities to secure large, strategic contracts for high-volume capacitor applications. DuPont Teijin Films occupies a position as a specialist in high-performance polyester films, differentiating on technical specifications and reliability for niche, high-margin applications. SABIC, a global chemical company, anchors the market segment focused on material innovation, particularly in advanced polycarbonate-based films designed for demanding automotive electronics. These entities collectively illustrate the divergent strategies for market penetration and value capture across the industry.
| Leading Market Players |
|---|
| DuPont Teijin Films |
| Toray Industries, Inc. |
| Mitsubishi Chemical Corp. |
| SABIC |
| Jindal Films |
| Steiner GmbH & Co. KG |
| COVEME S.p.A. |
| Bolloré Group |
| Tervakoski Film |
Cost & Logistics Intelligence
Petrochemical-derived feedstocks from a concentrated global supply base directly influence plastic dielectric film pricing and downstream capacitor manufacturer profitability. This upstream concentration dictates margin distribution across the value chain.
Pricing Analysis
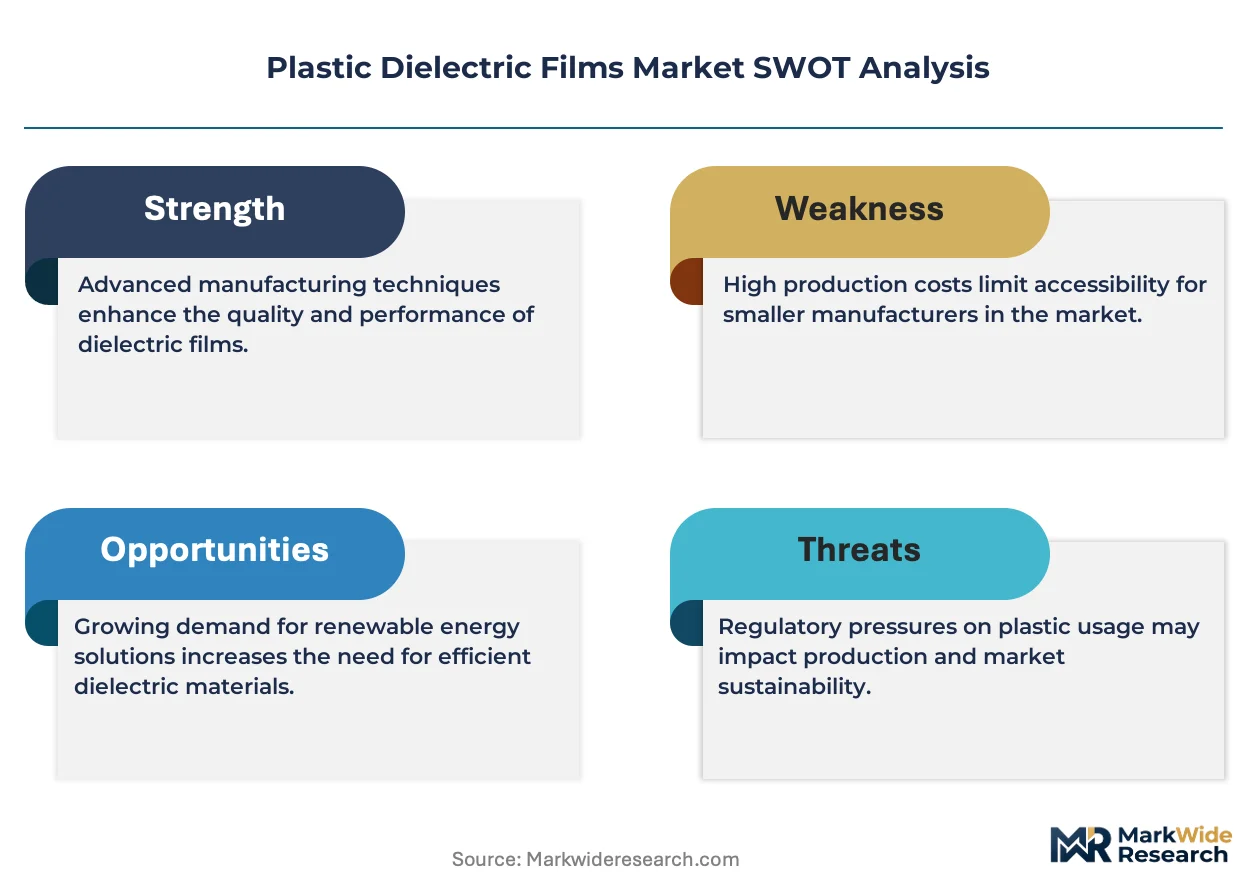
Prices for plastic dielectric films exhibit regional variations, shaped by local regulatory compliance costs and raw material sourcing. The dominant pricing model is contract-based long-term offtake for high-volume applications, with per-unit transactional pricing for niche, high-performance films. Price differentiation stems from technical specifications and compliance certifications like REACH or China's GB standards. Pricing softness reflects raw material price volatility, particularly for petrochemical feedstocks. Consumer electronics manufacturers demonstrate the highest price sensitivity, while automotive and aerospace sectors prioritize performance over cost.
Supply Chain Analysis
Raw material price volatility for petrochemical feedstocks dominates supply chain risk for plastic dielectric films. Supply concentrates in major chemical production hubs across China, South Korea, and Germany, which process polypropylene and polyethylene terephthalate resins. A single-source vulnerability often arises for specialized, high-performance films. Downstream distribution typically involves direct-to-OEM sourcing for high-volume capacitor applications, while specialized distributors serve niche markets requiring tailored materials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic dielectric films market is experiencing high-growth disruption driven by the rapid global expansion of electric vehicle platforms. This technological inflection creates new demands for high-performance, thermally stable materials.
For Market Incumbents:Pre-empt competitive threats from ceramic capacitors by investing heavily in R&D for high-temperature films capable of operating above 125°C. Forge strategic partnerships with major automotive OEMs to co-develop next-generation materials, securing long-term supply agreements. This minimizes margin pressure from commodity films and reinforces market leadership in advanced applications. Expanding capacity for specialized films in key regions like China also mitigates supply chain risks.
For New Entrants and Emerging Players:Underpenetration in grid-scale energy storage systems presents a significant opportunity for robust, large-format dielectric films. Target niche aerospace applications by developing specialized polymers like PEN and PPS for extreme temperature and radiation resistance. Differentiate through sustainable polymer formulations, including bio-based or easily recyclable dielectric films, to align with OEM circular economy goals. Focus on European battery management systems where Polyvinylidene Fluoride adoption is gaining traction.
For Investors and Strategic Acquirers:Capital is best deployed toward vertically integrated specialists possessing proprietary material science and advanced film processing capabilities. The market demonstrates strong long-term viability, underpinned by electrification trends in automotive and renewable energy, alongside ongoing electronics miniaturization. Target companies with proven track records in developing high-temperature or sustainable film solutions. The signal to watch is increased M&A activity focused on intellectual property in advanced polymer formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Polypropylene Films | Secures high-volume contracts for power capacitors in renewable energy projects. |
| R&D in High-Temperature Film Formulations | Meets demanding thermal stability requirements for automotive under-hood electronics. |
| Strategic Partnerships with Electric Vehicle OEMs | Co-develops specialized dielectric films for critical battery management systems. |
| Development of Sustainable Polymer Formulations | Attracts OEMs with aggressive corporate sustainability and circular economy goals. |
| Investment in Regional Compliance Certifications | Ensures market access across divergent regulatory landscapes like EU REACH and China GB. |
Research Approach
A standing panel of R&D directors, procurement leads, capacitor design engineers, and automotive electronics specialists provided ongoing calibration for primary interview insights. This analysis integrated direct interviews with extensive secondary validation from industry association reports, government energy mandates, company financial filings, and patent databases. Bottom-up data aggregation and top-down market sizing techniques were triangulated to ensure robust market estimates.
Scenario-bracketing across optimistic and conservative outlooks informed the market projection over the analysis window. The analytical framework modeled market dynamics across product type, application, end-user, physical form, and regional regulatory compliance. Compound annual growth rates were derived by assessing demand drivers like electric vehicle production forecasts and renewable energy installation targets. Material substitution rates also served as a key forecast input.
Practitioners should monitor raw material price shocks, breakthroughs in ceramic capacitor technology, and shifts in global trade policy for early signals of market revision. Forecasts reflect assumptions regarding technological adoption rates and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Europe Textile Films Market
Specialty Materials
Carbon Blacks for Non-Rubber Applications Market
Specialty Materials
Europe Acrylic Sheet Market
Specialty Materials
Global Ajinomoto Build-Up Film Substrate Market
Specialty Materials
Adhesion Laminated Surface Protection Films Market
Specialty Materials
India Collagen Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
South America Polyether Ether Ketone (Peek) Market
Specialty Materials
Global Conductive Silicone Market
Specialty Materials
Silicone Solutions Market
Specialty Materials
North America Microspheres Market
Specialty Materials
Global Poly Vents Market
Specialty Materials
Europe Microspheres Market
Specialty Materials
Polyester Medical Films Market
Specialty Materials
Vulcanized Fiber Market
Specialty Materials
Engineered Foam Market