
 Phenolic Insulation Market | 2026-2036
Phenolic Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
Phenolic Insulation Market Analysis
Data center cooling infrastructure is repositioning phenolic insulation toward high-performance thermal management specifications. Huntsman Corporation leverages its resin chemistry expertise to supply specialized phenolic formulations for controlled-environment applications. Kingspan Group anchors its competitive stance through integrated panel systems that combine insulation with structural envelope performance. Armacell International S.A. specializes in pre-formed pipe insulation solutions that address thermal bridging in complex mechanical systems.
Phenolic insulation comprises rigid thermoset foam derived from phenol-formaldehyde resin, delivering closed-cell structures with thermal conductivity values near 0.018 W/m·K and exceptional fire resistance characterized by low smoke emission and self-extinguishing properties. Rigid boards dominate commercial building envelopes where compressive strength and dimensional stability under sustained loads prove critical. Spray foam represents the fastest-expanding product configuration, penetrating retrofit markets where irregular substrates and air-sealing integration create premium value capture. Pipe insulation maintains entrenched positions in refrigeration and HVAC distribution networks, sustained by standardized dimensional ranges and established contractor familiarity.
EPA regulations on formaldehyde emissions and REACH restrictions on hazardous substance content in construction materials are reshaping formulation chemistry and testing protocols across manufacturing bases. CE marking requirements under the EU Construction Products Regulation enforce consistent fire-performance declarations, while OSHA workplace exposure limits influence production facility investments in the United States. Stakeholders must evaluate how evolving carbon-accounting frameworks for embodied emissions will alter material selection criteria in public procurement and green building certification pathways.
Market Dynamics
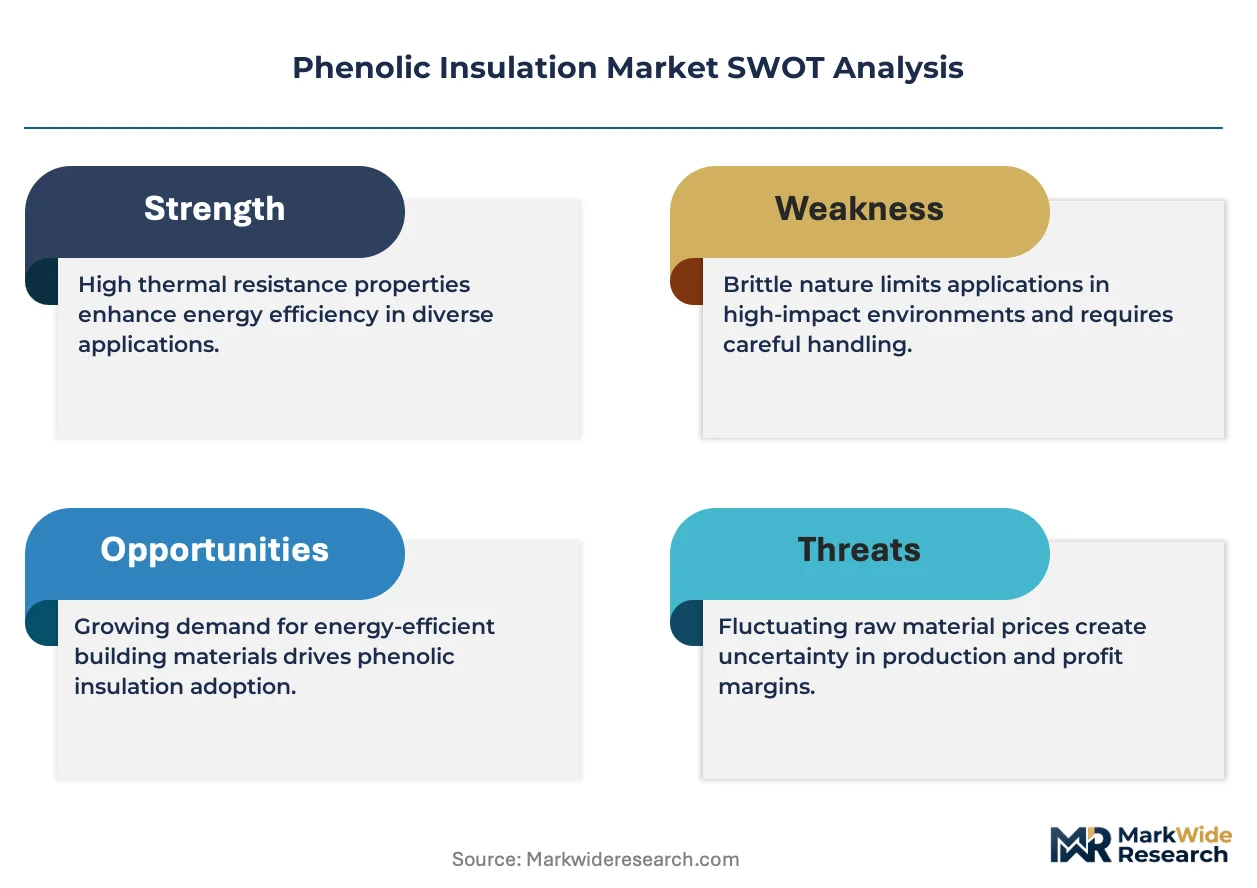
Fire-safety code escalation across commercial construction is compressing specification timelines and forcing rapid material substitution decisions that favor phenolic's low-smoke, self-extinguishing performance profile over conventional alternatives.
Growth Catalysts
- EU Green Deal fire-safety mandates:Tightened building envelope standards across Germany, France, and Italy are accelerating phenolic specification in commercial retrofits where existing mineral wool cannot meet updated smoke-emission thresholds.
- Data center thermal management:Hyperscale facility operators in Northern Virginia and Frankfurt are specifying phenolic for precision cooling infrastructure where thermal bridging control and dimensional stability under sustained compressive loads prove critical.
- Spray foam retrofit penetration:Irregular substrate sealing in aging commercial building envelopes is driving contractor adoption of spray-applied phenolic systems that integrate air-barrier performance with insulation in a single application.
Market Restraints
- Formaldehyde input cost volatility:Petrochemical feedstock price swings directly compress phenolic resin economics, with phenol and formaldehyde representing 35-45% of finished foam material costs.
- REACH substance restriction friction:ECHA's evolving hazardous substance classifications for phenol derivatives are extending formulation approval timelines and increasing testing expenditure for European manufacturing bases.
- Polyisocyanurate substitution pressure:Lower-cost PIR boards with comparable thermal performance are capturing specification share in cost-sensitive warehouse and logistics construction segments where fire-performance premiums cannot be monetized.
Strategic Opportunities
- India commercial building code modernization:BIS adoption of international fire-performance standards in Mumbai and Bangalore commercial corridors is creating first-mover specification windows for phenolic systems in a historically mineral-wool-dominated market.
- Cold chain infrastructure expansion:Refrigerated logistics networks across Poland and the Czech Republic are specifying phenolic pipe insulation for distribution facilities where thermal bridging in complex mechanical systems demands pre-formed dimensional precision.
- Embodied carbon accounting integration:France's RE2020 environmental regulation and evolving LEED v5 protocols are positioning phenolic's manufacturing carbon intensity advantage as a procurement selection criterion in public-sector construction tenders.
Industry Challenges
- Specialized applicator workforce scarcity:Spray foam installation demands certified technicians trained in precise mixing ratios and substrate preparation protocols that standard insulation contractor pools rarely possess.
- CE marking fire-performance testing bottlenecks:EU Construction Products Regulation compliance requires extended burn-testing sequences at notified bodies, compressing product launch timelines for formulation innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Phenolic Insulation Market |
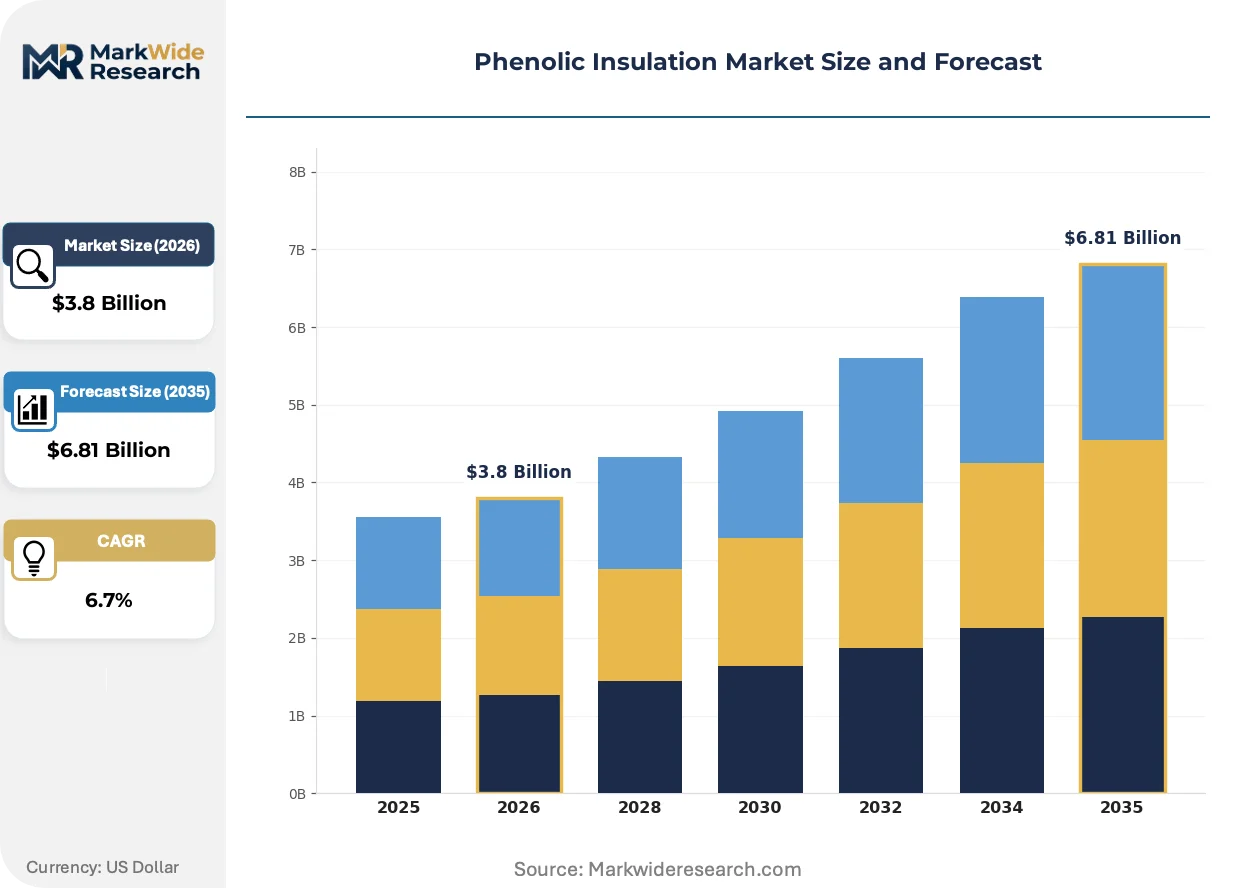
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Boards, Flexible Insulation, Pipe Insulation, Spray Foam Application: Building & Construction, Refrigeration, HVAC, Industrial Equipment End User: Commercial, Residential, Industrial, Government Distribution Channel: Direct Sales, Wholesale, Retail, E-commerce |
| Companies Covered | Huntsman Corporation, Armacell International S.A., Kingspan Group, Dow Inc, Covestro AG, BASF SE, Owens Corning, Rockwool International A/S, Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Phenolic Insulation Market Emerging Trajectories
Digital manufacturing integration and regulatory carbon-accounting requirements are converging to reshape how phenolic insulation is formulated, tested, and specified across commercial construction value chains.
Continuous panel production line automation is automating quality control and thickness calibration in rigid board manufacturing. Kingspan and comparable integrated systems suppliers are deploying machine-vision inspection at European and North American facilities to compress dimensional tolerance variation below 2%. This precision is automating the elimination of manual sorting and rework stages that previously consumed 8-12% of production throughput.
REACH authorization list expansion is forcing phenol-formaldehyde resin reformulation across EU manufacturing bases. ECHA's 2024-2025 substance evaluation timeline is accelerating substitution research for specific catalyst systems used in high-performance foam grades. German and Belgian producers are responding with bio-based phenol pilot programs that maintain fire-performance certification while reducing hazardous substance content declarations.
Specification decisions are migrating from general contractors to owner-operator procurement teams with centralized sustainability mandates. Data center developers in Loudoun County, Virginia, and Frankfurt's Europaviertel district are consolidating insulation selection authority under facility engineering departments that benchmark embodied carbon and fire-performance data through digital product passports. This centralization is compressing the traditional distributor-influenced specification channel that previously dominated commercial building envelope decisions.
Phenolic Insulation Market Segmentation
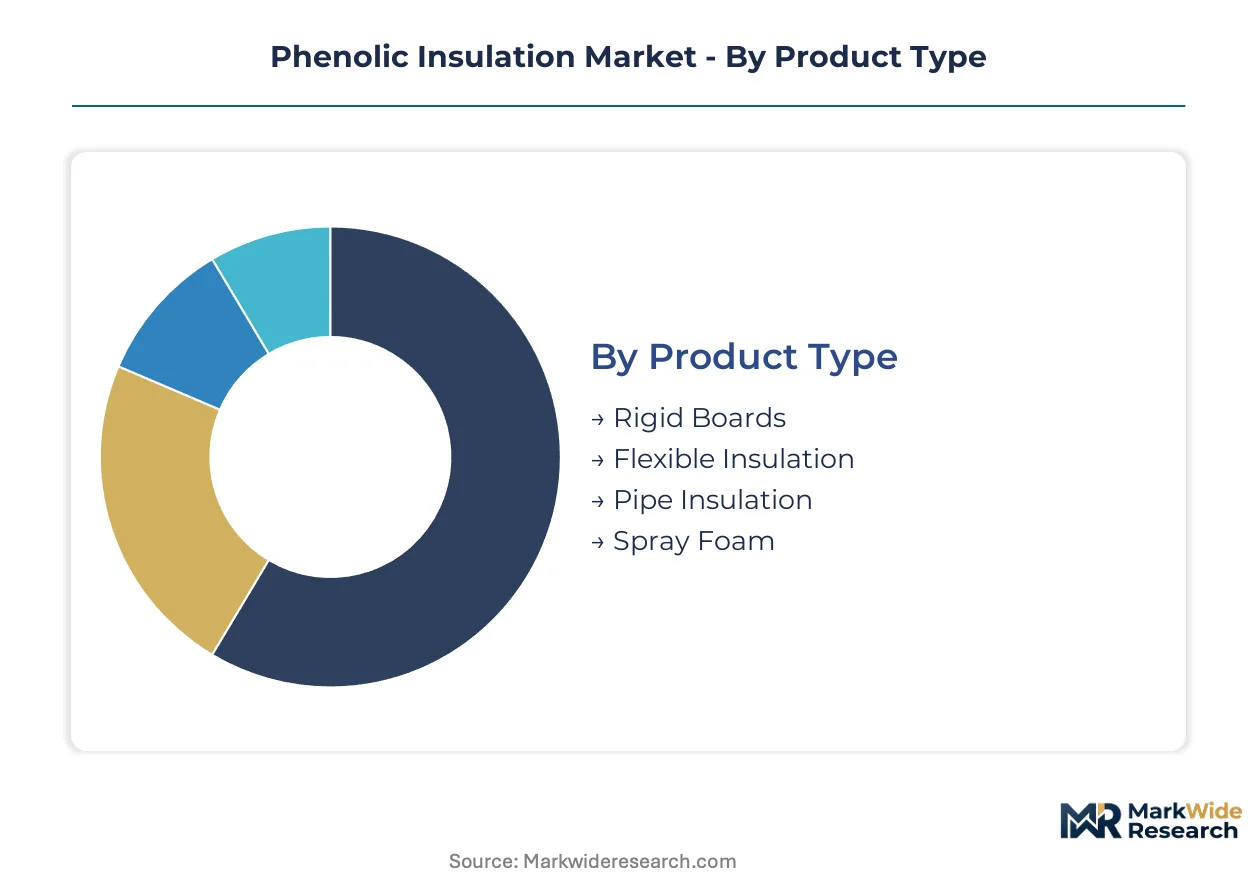
Phenolic insulation specification varies sharply across thermal performance requirements, installation constraints, and regulatory exposure. Understanding these segment boundaries clarifies where formulation investments concentrate and which channels capture premium value.
Product Type:
Thermal conductivity specifications and fire-performance certification requirements differentiate product architectures across installation methodologies.
- Rigid Boards:These closed-cell thermoset panels deliver compressive strength above 150 kPa and dimensional stability under sustained structural loads. Demand concentrates in Germany's commercial envelope retrofits where CE marking fire-performance declarations enforce consistent smoke-emission thresholds. Tightened EU Green Deal mandates accelerate substitution away from mineral wool in high-rise applications.
- Spray Foam:Two-component field-applied systems integrate air-barrier performance with thermal insulation in irregular substrate conditions. Contractor adoption is climbing fastest across the US Southeast warehouse construction belt where aging building envelopes demand seamless retrofit solutions without structural demolition.
- Pipe Insulation:Pre-formed phenolic sections address thermal bridging in complex mechanical distribution networks. Standardized dimensional ranges sustain entrenched positions in refrigeration and HVAC specifications.
- Flexible Insulation:Lower-density formulations accommodate curved surfaces and vibration-prone industrial equipment housings where rigid alternatives fracture under mechanical stress.
Rigid boards lead on scale; spray foam leads on momentum.
Application:
End-use thermal management intensity and regulatory scrutiny intensity shape specification durability and replacement frequency.
- Building & Construction:Commercial envelope and roofing systems demand compressive strength and fire-resistance certification. Northern Virginia data center developers specify phenolic for precision cooling infrastructure where thermal bridging control proves critical under sustained mechanical loads.
- Refrigeration:Cold chain logistics across Poland and the Czech Republic specify phenolic pipe insulation for distribution facilities where pre-formed dimensional precision eliminates thermal bridging in complex mechanical systems.
- HVAC:Distribution network insulation balances thermal performance with installation labor efficiency in commercial and institutional mechanical systems.
- Industrial Equipment:Process vessel and pipeline insulation tolerates higher temperature exposure than building envelope applications.
Building & construction commands volume concentration; refrigeration is expanding most quickly on cold chain infrastructure investment.
End User:
Procurement centralization and sustainability mandate sophistication determine specification authority and price elasticity.
- Commercial:Owner-operator engineering departments in Frankfurt's Europaviertel district consolidate insulation selection authority under facility engineering teams benchmarking embodied carbon through digital product passports.
- Industrial:Manufacturing facility operators prioritize thermal performance durability in process-critical applications with extended capital replacement cycles.
- Residential:Single-family and multi-family construction segments show higher price sensitivity and distributor-influenced specification patterns.
- Government:Public procurement tenders in France incorporate RE2020 environmental regulation carbon-accounting criteria that position phenolic's manufacturing intensity advantage as a selection filter.
Commercial end users dominate specification value; government procurement is gaining share fastest on green building mandate expansion.
Distribution Channel:
Specification influence and technical support requirements vary across channel structures and customer relationship depth.
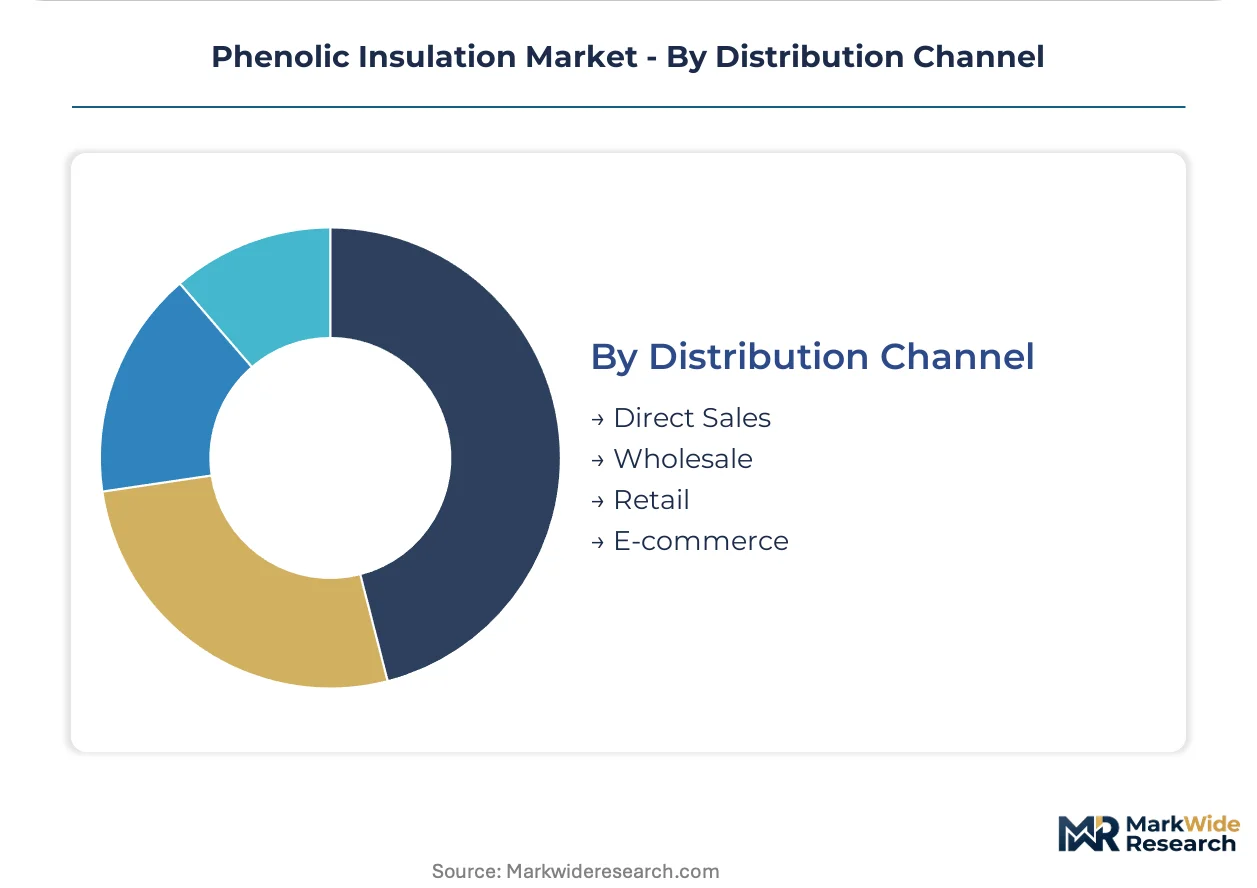
- Direct Sales:Integrated panel system suppliers deploy technical specification teams directly to data center developers and commercial general contractors. This channel captures premium pricing on complex envelope projects requiring engineering coordination.
- Wholesale:Regional distributors maintain inventory positions for standardized rigid board and pipe insulation dimensions serving contractor familiarity and rapid fulfillment requirements.
- Retail:Limited penetration in professional-grade phenolic products due to certification and installation complexity barriers.
- E-commerce:Emerging channel for specification-grade product data and digital product passport access, though physical fulfillment remains logistics-constrained for bulky insulation materials.
Direct sales leads on margin capture; wholesale maintains volume concentration through contractor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial corridor anchors phenolic insulation demand through commercial retrofit mandates and REACH-compliant manufacturing bases. Specification intensity concentrates where EU Green Deal fire-safety codes intersect with established chemical production infrastructure.
United States
Data center thermal management in Northern Virginia's Loudoun County drives specification toward high-performance phenolic systems. EPA formaldehyde emission regulations under TSCA influence resin formulation investments across domestic manufacturing bases. The Southeast warehouse construction belt from Atlanta to Charlotte accelerates spray foam retrofit adoption for aging commercial envelopes.
Germany
Commercial building retrofits in Frankfurt's Europaviertel district prioritize phenolic boards for smoke-emission compliance under tightened EU Green Deal standards. ECHA REACH substance restrictions extend formulation approval timelines for phenol derivatives. The Ruhr industrial corridor maintains concentrated production capacity serving cross-border specification into Benelux markets.
China
Cold chain infrastructure expansion across Yangtze River Delta logistics hubs creates demand for pre-formed pipe insulation solutions. GB standards for building fire safety are converging toward international performance benchmarks in Shanghai and Jiangsu province. Domestic phenolic resin production scales to serve Southeast Asian export markets through Ningbo-Zhoushan port facilities.
India
BIS adoption of international fire-performance standards in Mumbai and Bangalore commercial corridors opens specification windows historically dominated by mineral wool. The country's national construction regulator is modernizing commercial building codes to address high-rise envelope safety. Gujarat's chemical manufacturing belt supplies resin feedstock for emerging domestic phenolic foam production.
United Kingdom
Post-Grenfell regulatory tightening across England and Wales accelerates phenolic specification in high-rise residential retrofits. CE marking alignment under UKCA transition maintains fire-performance testing requirements for imported board systems. Greater Manchester's commercial development pipeline specifies integrated panel systems for warehouse-to-office conversions.
Phenolic Insulation Market Vendor Landscape
Portfolio diversification dominates the current landscape as manufacturers extend from core resin chemistry into integrated building envelope systems. The vendor base organizes around three strategic archetypes: integrated panel system suppliers, specialized pre-formed insulation fabricators, and diversified chemical conglomerates with resin production advantages. M&A activity concentrates on acquiring spray foam application capabilities and regional distribution networks. Geographic expansion into India's emerging specification market represents a secondary competitive vector.
Among diversified chemical conglomerates, Huntsman Corporation and BASF SE exemplify resin-backward competitive positioning, leveraging captive phenol-formaldehyde production to supply specialized foam formulations. Kingspan Group occupies a position within the integrated panel system tier, combining insulation manufacturing with structural envelope engineering. These three anchors demonstrate how competitive advantage in this market derives from either upstream chemical integration or downstream system integration, with mid-scale pure-play insulation specialists facing margin pressure from both directions.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Armacell International S.A. |
| Kingspan Group |
| Dow Inc |
| Covestro AG |
| BASF SE |
| Owens Corning |
| Rockwool International A/S |
| Asahi Kasei Corporation |
| Others |
Supply Flow & Price Mechanics
Data center developers in Northern Virginia consolidating insulation procurement authority under facility engineering departments are compressing traditional distributor-influenced channels and forcing supply chain reconfiguration toward direct technical engagement models that capture premium pricing on specification-grade phenolic systems.
Pricing Analysis
Petrochemical feedstock volatility in phenol and formaldehyde inputs passes directly into finished foam material costs, with these chemicals representing 35-45% of production economics. Pricing stratifies across premium CE-marked fire-performance grades, standard commercial envelope specifications, and economy-tier warehouse applications where polyisocyanurate substitution pressure intensifies. Cost compression in the economy tier reflects PIR board competition, while premium segments maintain pricing power through REACH-compliant formulation certification. Government procurement teams in France exhibit lowest price sensitivity due to RE2020 carbon-accounting mandates, whereas residential construction segments remain most exposed to distributor-driven cost competition.
Supply Chain Analysis
Regional distribution centers in Germany's Ruhr corridor, the US Southeast Atlanta-Charlotte belt, and China's Yangtze River Delta logistics hubs anchor phenolic insulation fulfillment networks. Manufacturing draws from concentrated phenol-formaldehyde resin production in Germany, Belgium, and China, with bio-based phenol pilot programs emerging as alternative feedstock pathways. Single-source vulnerability concentrates in specialized spray foam applicator networks where certified technician scarcity creates installation bottlenecks. Distribution runs through integrated panel system suppliers for data center and commercial envelope projects, while wholesale channels serve standardized rigid board and pipe insulation demand through contractor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in premium fire-performance grades where EU Green Deal mandates and data center thermal management specifications create pricing power, while bio-based formulation investments offer cost-down trajectories through reduced hazardous substance compliance expenditure.
For Market Incumbents: Lock in specification authority with data center developers in Northern Virginia and Frankfurt through embedded technical engineering teams that bypass traditional distributor channels. Defend against polyisocyanurate substitution in warehouse construction by accelerating CE marking fire-performance certification investments that PIR cannot replicate. Prioritize captive phenol-formaldehyde resin production or backward integration into bio-based feedstock pilots to insulate margin structures from petrochemical volatility. For New Entrants and Emerging Players: Digital product passport platforms offering embodied carbon benchmarking data represent the most penetrable route into specification decisions migrating to owner-operator procurement teams. Target India's Mumbai and Bangalore commercial corridors where BIS fire-performance standard modernization creates first-mover windows in a historically mineral-wool-dominated market. Deploy spray foam application training partnerships with regional contractor networks to overcome specialized workforce scarcity barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale phenolic specialists possessing REACH-compliant manufacturing bases and spray foam application capabilities that larger chemical conglomerates lack. Long-term viability hinges on positioning for carbon-accounting integration in public procurement tender evaluation criteria. Watch for ECHA substance restriction timeline acceleration as the inflection signal that would compress formulation approval timelines and favor incumbent compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Phenol | Reduces REACH hazardous substance exposure while maintaining CE fire-performance certification for EU manufacturing bases. |
| Spray Foam Applicator Training Certification | Addresses workforce scarcity that constrains retrofit market penetration in the US Southeast commercial envelope segment. |
| Digital Product Passport Deployment | Captures specification authority from distributor channels by delivering embodied carbon data to Frankfurt data center engineering teams. |
| CE Marking Fire-Performance Pre-Certification | Compresses product launch timelines at notified bodies for formulation innovations targeting high-rise residential retrofits. |
| Direct Sales Technical Team Expansion | Bypasses wholesale channels to capture premium pricing on complex Northern Virginia data center cooling infrastructure projects. |
Methodological Framework
Multiple input streams — primary interviews with plant managers, procurement leads at downstream OEMs, and distribution channel partners; secondary validation through customs/trade data, Cefic industry reports, and SEC 10-K filings; plus technical R&D director consultations — were reconciled through bottom-up and top-down triangulation to construct segment-level demand estimates and supply-side capacity assessments.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to model growth across the projection horizon, with segmentation by product architecture, end-use application intensity, procurement centralization level, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH substance restriction timeline uncertainty and data center capex cycle phasing.
The model assumes a particular technology adoption path; alternative pathways for bio-based phenol feedstock substitution would alter the outlook if ECHA authorization timelines accelerate or petrochemical input costs stabilize. Forecasts reflect documented assumptions around EU Green Deal implementation pace and BIS standard convergence in India. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insulation Materials
UK Industrial Insulation Market
Insulation Materials
Silver Ion Antibacterial Insulation Cup Market
Insulation Materials
Roofing Underlying Materials Market
Insulation Materials
Industrial Pipe Insulation Market
Insulation Materials
Acoustic Materials Market
Insulation Materials
Global Industrial Insulators Market
Insulation Materials
Polypropylene Foams Market
Insulation Materials
Global Advanced Insulation Material Market
Insulation Materials
France Foam Insulation Market
Insulation Materials
Protective Building Materials Market
Insulation Materials
Rock Wool Insulation Board Market
Insulation Materials
Global Tank Insulation Market
Insulation Materials
Dielectric Materials Market
Insulation Materials
Phase Change Thermal Interface Materials Market
Insulation Materials
Fiberglass Duct Wrap Insulation Market
Insulation Materials
Thermal Insulation Material Market