
 Europe Acrylic Sheet Market | 2026-2036
Europe Acrylic Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acrylic Sheet Market Insights
A shift from single-source petrochemical feedstock contracts toward multi-source methyl methacrylate supply is broadening procurement flexibility for European converters. Evonik Industries AG sustains captive monomer capacity at its Worms and Wesseling complexes, insulating margin exposure from spot MMA volatility. Schweiter Technologies AG anchors premium cast sheet output through its Swiss manufacturing footprint, while 3A Composites GmbH competes across display and signage channels with extruded product lines optimized for thermoforming throughput.
Acrylic sheet denotes thermoplastic panels manufactured through cell casting or continuous extrusion of polymethyl methacrylate resin, with light transmission typically exceeding 92% and UV stability achieved through co-extruded cap layers. Cast acrylic commands the thickest specification segments above 25mm where optical clarity and solvent resistance justify premium positioning, while extruded acrylic dominates volume-driven construction glazing and retail fixture applications where dimensional tolerance and lower unit cost predominate. The thickness dimension stratifies margin pools, with ultra-thick architectural and aquarium grades capturing value premiums against commoditized thin-sheet signage feedstock.
REACH registration obligations administered by ECHA constrain monomer and additive chemistries permitted in European sheet formulations, while CE marking requirements under the Construction Products Regulation mandate declared performance characteristics for structural glazing applications. The EU Green Deal's embodied carbon tracking provisions are pressuring producers to document cradle-to-gate emissions profiles across cast and extruded product families. Stakeholders must evaluate bio-based MMA pilot programs and mechanical recycling pathways for post-industrial scrap before regulatory thresholds tighten on petrochemical feedstock intensity.
Market Dynamics
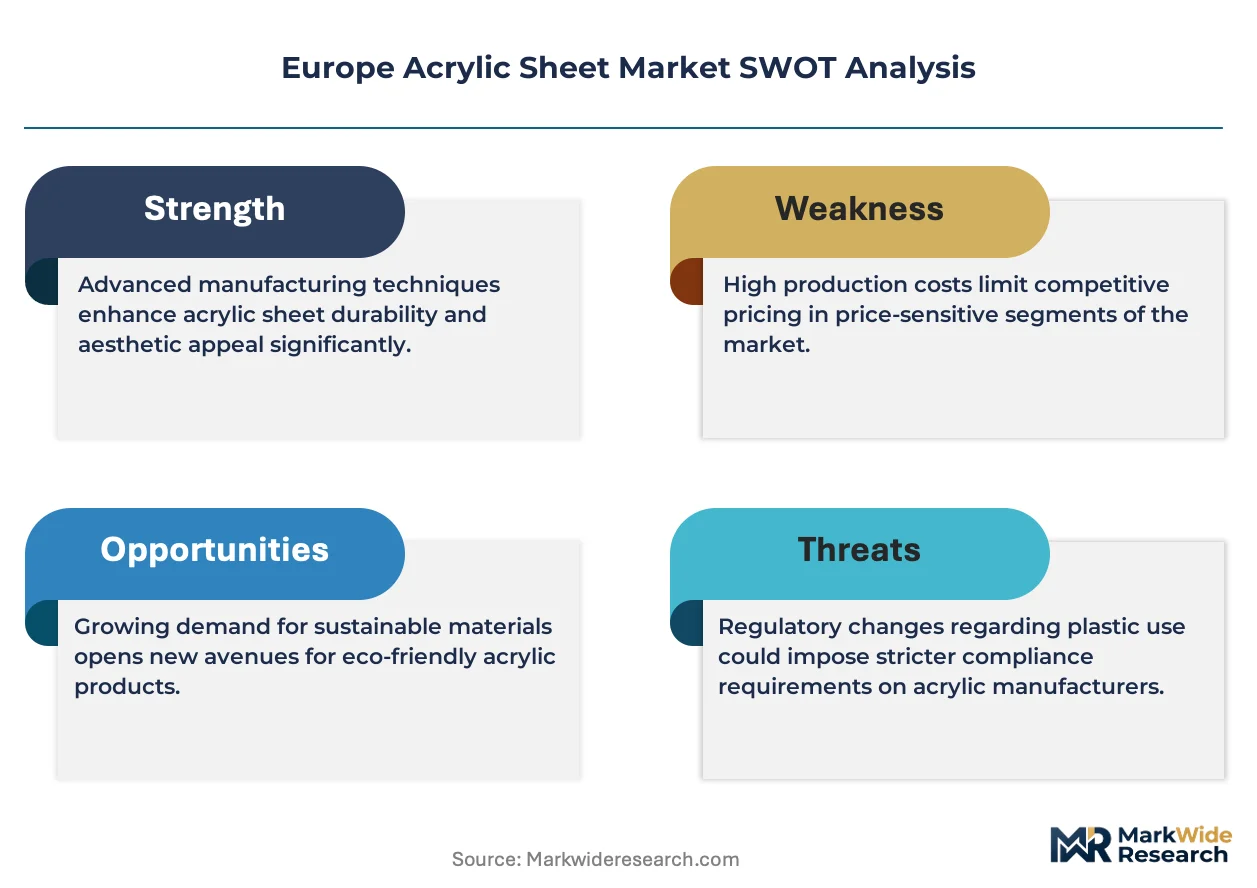
REACH registration obligations administered by ECHA are compressing formulation flexibility for European acrylic sheet converters, forcing reformulation investments that favor producers with captive methyl methacrylate supply and integrated regulatory affairs capabilities.
Growth Catalysts
- Construction Products Regulation:CE marking mandates for structural glazing applications are elevating specification thresholds, filtering out non-compliant imports and protecting domestic premium cast sheet producers.
- Germany:Automotive OEMs and exhibition design studios are specifying optical-grade cast acrylic for head-up display substrates and museum vitrines, commanding thicknesses above 25mm with tight tolerances.
- Cell casting:Ultra-thick architectural and aquarium grades are capturing value premiums against commoditized extruded signage feedstock, insulating margin pools from construction volume cyclicality.
Market Restraints
- MMA spot volatility:European converters without captive monomer capacity face margin compression when spot methyl methacrylate prices spike, disadvantaging pure-play sheet extruders against integrated chemical groups.
- Polycarbonate substitution:Impact-resistant glazing applications above 6mm thickness are migrating to polycarbonate where ballistic rating or vandal resistance outweighs optical clarity requirements.
- REACH compliance costs:ECHA registration fees and toxicology testing burdens for novel additive chemistries are raising barriers to formulation innovation for mid-tier producers.
Strategic Opportunities
- Spain and Italy:Solar thermal collector manufacturing clusters are underpenetrated for UV-stable glazing substrates, offering volume growth outside German automotive concentration.
- EU Green Deal:Embodied carbon tracking provisions are creating first-mover advantage for producers documenting cradle-to-gate emissions profiles and piloting bio-based MMA feedstocks.
- Mechanical recycling:Post-industrial scrap recovery pathways for cast and extruded families are opening circular economy positioning ahead of regulatory thresholds on petrochemical intensity.
Industry Challenges
- Process engineering talent:Cell casting expertise for optical-grade thicknesses above 40mm is concentrated among aging technician cohorts, constraining capacity expansion for aquarium and architectural segments.
- Co-extrusion line retrofitting:UV cap layer integration on legacy extrusion assets requires seven-figure capital commitments with extended commissioning timelines.
- CE marking certification:Construction Products Regulation conformity assessment for structural glazing applications involves multi-year testing protocols with notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acrylic Sheet Market |
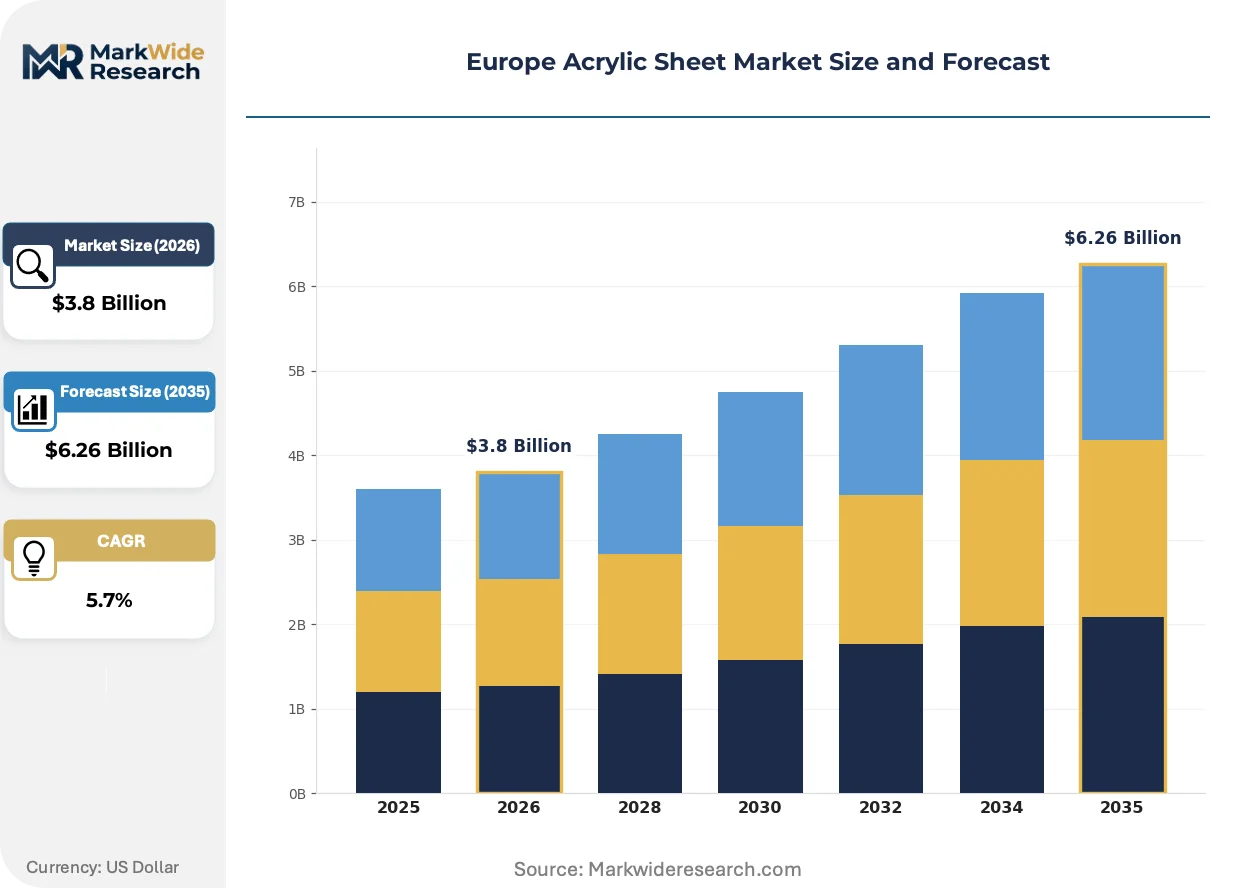
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Acrylic, Extruded Acrylic, Colored Acrylic, Clear Acrylic End User: Construction, Automotive, Furniture, Display Thickness: Thin, Medium, Thick, Ultra-Thick Form: Sheets, Rods, Tubes, Shapes |
| Companies Covered | Schweiter Technologies AG, PyraSied Xtreme Acrylic, Perspex International Ltd., Aristech Surfaces LLC, Lucite International, Evonik Industries AG, Madreperla S.p.A., 3A Composites GmbH, Altuglas International, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acrylic Sheet Market Trends and Innovations
Acrylic sheet manufacturing is pivoting toward emission-transparent supply chains and digitized specification workflows, compressing traditional technical sales cycles while elevating the importance of verified sustainability credentials in buyer evaluation.
Co-extruded nanocomposite cap layers incorporating ceramic UV absorbers are electrifying durability performance for outdoor architectural glazing, extending service life guarantees from ten to thirty years. German facade engineers and Swiss building envelope specialists are specifying these grades for museum extensions and premium residential retrofits. The technology is electrifying competitive positioning for producers with in-house compounding capabilities, compressing margins for commodity extruders dependent on standard additive packages.
EU Green Deal embodied carbon disclosure requirements are mandating product-level environmental product declarations across construction supply chains. Acrylic sheet producers must document cradle-to-gate emissions for both cast and extruded families, with penalties for incomplete transparency in public procurement. Premium specification segments in Germany and the Netherlands are responding fastest, embedding EPD requirements into technical specifications ahead of regulatory deadlines.
Specification workflows are migrating to BIM-integrated material libraries where architects preload performance-certified acrylic grades into design templates. Distributors serving exhibition design and retail fixture channels are losing technical specification influence to platform-enabled direct procurement. This shift is most visible in Scandinavian markets where public project procurement mandates digital material passports.
Europe Acrylic Sheet Market Segmentation
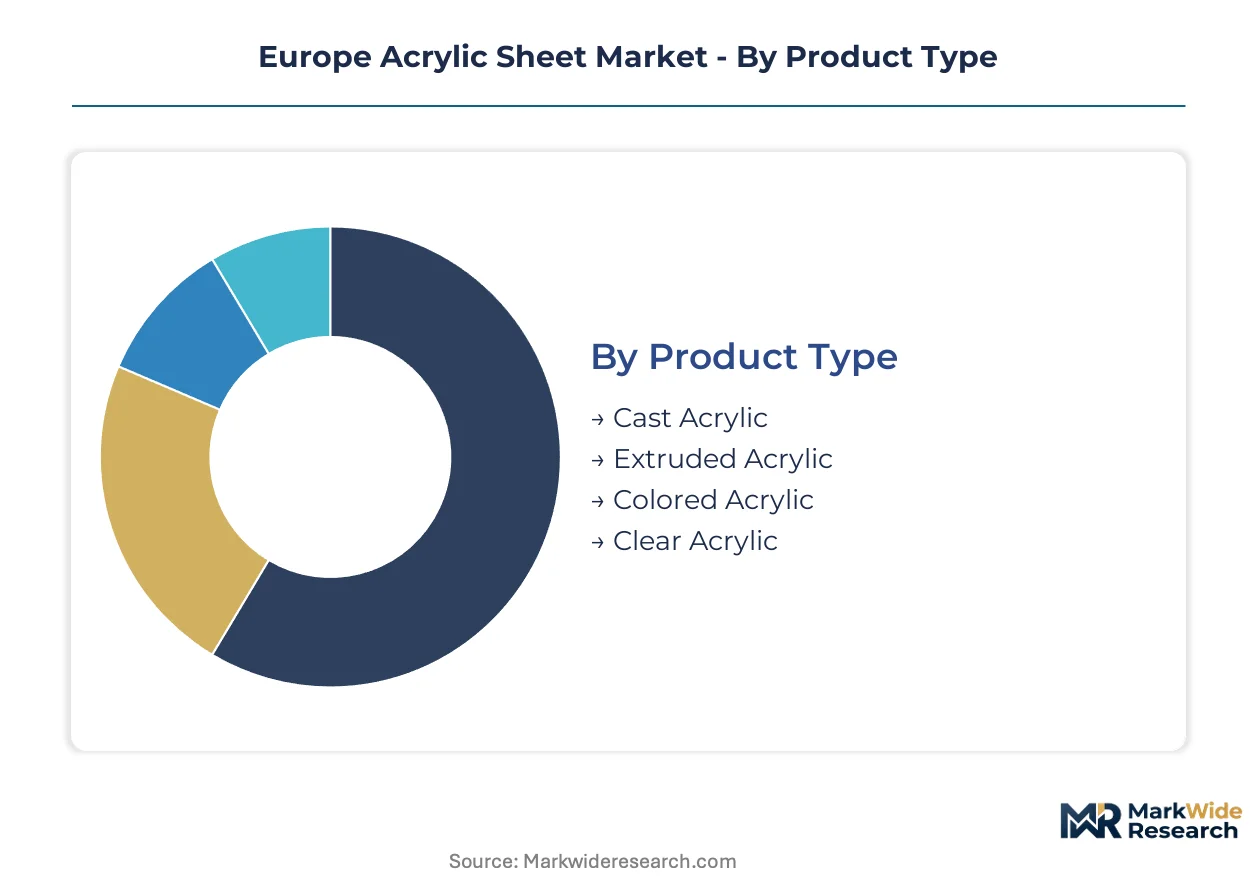
Acrylic sheet segmentation in Europe maps directly onto margin stratification, where manufacturing process and dimensional specification determine competitive positioning against REACH-compliant imports. Producers configure asset mixes across casting and extrusion technologies to capture diverging value pools in construction glazing versus optical-grade applications.
Product Type:
Cell casting capacity clusters in Germany and Switzerland, while continuous extrusion lines concentrate in lower-cost manufacturing zones serving volume construction markets.
- Cast Acrylic:Manufactured through batch cell polymerization of methyl methacrylate monomer between glass plates, delivering optical clarity above 92% light transmission and solvent resistance critical for museum vitrines. German automotive OEMs and Swiss exhibition designers specify cast grades above 25mm for head-up display substrates and architectural installations, with captive monomer supply at Worms and Wesseling insulating integrated producers from spot MMA volatility.
- Extruded Acrylic:Produced via continuous melt extrusion of PMMA resin through die systems, offering tighter dimensional tolerances and lower unit costs for high-volume applications. Construction glazing and retail fixture channels across Spain and Italy absorb the bulk of European extruded output, though margin compression intensifies during methyl methacrylate price spikes for non-integrated converters.
- Colored Acrylic:Pigmented masterbatch integration during polymerization or compounding stages, serving signage and branded retail environments where aesthetic differentiation commands specification premiums.
- Clear Acrylic:Unpigmented base formulations dominating technical applications where optical performance is paramount, from LED light guide panels to medical device housings.
Cast acrylic absorbs the bulk of installed capacity in premium thickness segments; extruded acrylic is expanding most quickly in solar thermal collector glazing across Southern Europe.
End User:
Application-driven procurement patterns split between project-specified construction volumes and OEM-integrated automotive programs, with diverging certification requirements under CE marking and REACH.
- Construction:Structural glazing and facade applications under the Construction Products Regulation mandate declared performance characteristics, filtering non-compliant imports and protecting domestic premium producers. German and Dutch building envelope specialists are embedding environmental product declaration requirements into specifications ahead of EU Green Deal deadlines.
- Automotive:Optical-grade cast acrylic for head-up display substrates and interior trim components, with thickness tolerances below 0.1mm and UV stability specifications extending service life guarantees. German OEM programs concentrate demand in Baden-Württemberg and Bavaria manufacturing clusters.
- Furniture:Decorative and functional components for premium residential and contract interiors, where thermoforming compatibility and surface hardness drive material selection.
- Display:Retail fixtures, exhibition systems, and point-of-sale applications where extruded sheet cost efficiency and vacuum-forming throughput predominate over optical performance.
Construction channels represent the largest volume absorption; automotive specification programs are climbing the fastest as head-up display penetration deepens across German premium vehicle platforms.
Thickness:
Dimensional stratification creates distinct margin pools, with ultra-thick architectural grades capturing value premiums against commoditized thin-sheet signage feedstock.
- Ultra-Thick:Specifications above 40mm for aquarium installations and structural architectural elements, where cell casting expertise is concentrated among aging technician cohorts in German and Swiss facilities. Process engineering talent scarcity constrains capacity expansion despite premium pricing.
- Thick:25-40mm range serving museum vitrines, protective barriers, and high-end furniture applications, balancing optical clarity with fabrication flexibility.
- Medium:6-25mm segments dominating construction glazing and retail fixture thermoforming, where extruded sheet dimensional tolerance advantages reduce downstream processing waste.
- Thin:Below 6mm specifications for signage, lighting panels, and disposable display applications, facing polycarbonate substitution pressure where impact resistance outweighs optical requirements.
Medium thickness absorbs the bulk of European extrusion throughput; ultra-thick cast grades are gaining share fastest as aquarium and museum project pipelines expand.
Form:
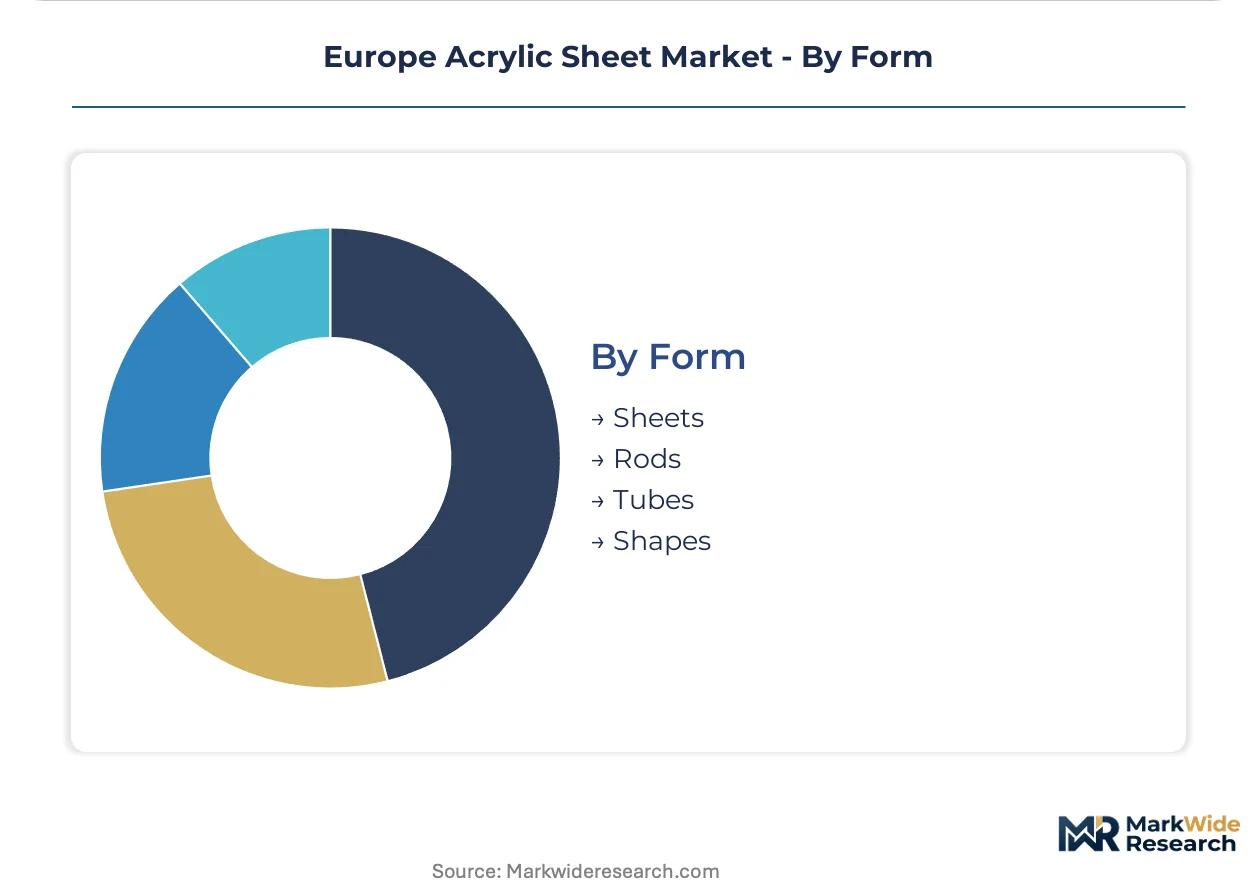
Downstream fabrication requirements determine form factor selection, with sheet dominating planar applications and rods/tubes serving specialized mechanical and lighting functions.
- Sheets:Planar panels representing the overwhelming volume share, processed via cutting, routing, thermoforming, and bonding across all end-use categories. REACH-registered additive packages for UV stabilization and impact modification differentiate supplier offerings.
- Rods:Solid cylindrical extrusions for mechanical applications, furniture components, and decorative lighting elements where machining and polishing operations follow primary forming.
- Tubes:Hollow cylindrical profiles for lighting diffusers, fluid handling, and structural columns, requiring concentricity control and surface finish specifications.
- Shapes:Custom profile extrusions and cast geometries for specialized architectural and industrial applications, often produced on dedicated tooling with extended lead times.
Sheet formats absorb the bulk of polymer consumption; tubes are expanding most quickly in LED lighting diffuser applications across Nordic energy-efficiency retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Methyl methacrylate feedstock clusters in the Rhine-Ruhr corridor and Worms complex anchor European acrylic sheet manufacturing, with downstream conversion capacity radiating toward automotive and construction demand centers.
Germany
Automotive OEMs in Baden-Württemberg and Bavaria specify optical-grade cast acrylic above 25mm for head-up display substrates. REACH registration obligations administered by ECHA constrain monomer chemistries permitted in formulations. The Worms and Wesseling captive monomer complexes insulate integrated producers from spot MMA volatility.
Switzerland
Premium cast sheet output serves museum vitrines and architectural installations across Zurich and Geneva metropolitan corridors. Swissmedic and federal chemical ordinances govern additive packages for UV stabilization. Basel-region compounding expertise supports nanocomposite cap layer development for thirty-year service life guarantees.
Netherlands
Building envelope specialists in the Randstad embed environmental product declaration requirements into specifications ahead of EU Green Deal deadlines. CE marking mandates under the Construction Products Regulation filter non-compliant imports. Rotterdam-Antwerp chemical logistics corridors facilitate MMA distribution to extrusion converters.
Spain
Solar thermal collector manufacturing clusters in Catalonia and Andalusia present underpenetrated demand for UV-stable glazing substrates. Spanish technical building codes align with EU energy efficiency directives for renewable thermal systems. Valencia-region fabrication facilities serve retail fixture and signage channels across Southern Europe.
Italy
Exhibition design studios in Milan and furniture manufacturers in Lombardy absorb medium-thickness extruded sheet for thermoformed components. Italian environmental product declaration frameworks implement EU Green Deal embodied carbon tracking provisions. Turin-based automotive suppliers specify optical grades for interior trim applications.
Europe Acrylic Sheet Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit co-extrusion lines for UV cap layer integration and captive monomer investments. The vendor base stratifies across integrated chemical groups with backward MMA control, specialized cast sheet fabricators with optical-grade expertise, and volume extruders serving construction markets. Two archetypes predominate: integrated producers insulating margin exposure through captive feedstock, and pure-play converters vulnerable to raw material cyclicality. Competitive moves center on co-extrusion line retrofitting and REACH compliance certification for structural glazing segments.
Among integrated chemical groups, Evonik Industries AG exemplifies the captive monomer archetype through its Rhine-Ruhr manufacturing footprint. Schweiter Technologies AG occupies a position within premium cast sheet specialization, while 3A Composites GmbH represents the volume extrusion tier competing across display and signage channels. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Schweiter Technologies AG |
| PyraSied Xtreme Acrylic |
| Perspex International Ltd. |
| Aristech Surfaces LLC |
| Lucite International |
| Evonik Industries AG |
| Madreperla S.p.A. |
| 3A Composites GmbH |
| Altuglas International |
| Others |
Pricing and Supply Chain Analysis
Methyl methacrylate monomer contracts from the Rhine-Ruhr corridor flow through three distinct pricing tiers downstream, with REACH-registered optical grades commanding substantial premiums over extruded construction feedstock as captive supply insulates integrated producers from spot volatility.
Pricing Analysis
Warranty and service bundling separate premium cast acrylic from commodity extruded grades, with thirty-year UV stability guarantees and optical certification included in German automotive specifications while standard construction glazing ships unbundled. Three-tier pricing structure across premium, standard, and economy levels reflects thickness stratification and REACH compliance investment, with ultra-thick architectural grades at the top and thin-sheet signage at the bottom. Pricing pressure stems from polycarbonate substitution in impact-resistant applications above 6mm, compressing margins in medium-thickness extruded segments. Construction procurement teams in Spain and Italy exhibit highest price sensitivity, while Swiss museum designers and German OEMs prioritize optical performance over unit cost.
Supply Chain Analysis
Freight costs from Rotterdam-Antwerp chemical corridors to Southern European extrusion converters have amplified regional pricing spreads, particularly for MMA monomer movements to non-integrated sheet producers. Supply concentrates in Germany, Switzerland, and the Netherlands, with cell casting expertise anchored in aging technician cohorts at Worms and Wesseling. Raw material dependencies center on petroleum-derived methyl methacrylate, ceramic UV absorbers for nanocomposite cap layers, and REACH-registered additive packages. Single-source vulnerability pervades ultra-thick cast capacity above 40mm where process engineering talent scarcity constrains expansion. Distribution runs through technical distributors for premium grades and direct mill relationships for volume construction offtake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell casting technician scarcity constrains ultra-thick capacity expansion, propping pricing power for optical-grade producers with captive monomer supply and established apprenticeship pipelines.
For Market Incumbents: Cement backward integration into methyl methacrylate supply or deepen captive compounding capabilities to insulate margins from spot MMA volatility threatening pure-play extruders. Acquire distressed optical-grade casting assets in Switzerland to consolidate premium positioning before REACH compliance costs escalate for mid-tier competitors. Polycarbonate substitution in medium-thick glazing applications demands defensive specification investment in UV cap layer technology. For New Entrants and Emerging Players: Capture underpenetrated solar thermal collector glazing demand in Spain and Italy, where UV-stable substrate specifications lag German automotive concentration. Target medium-thickness extruded segments for retail fixture channels in Southern Europe, where CE marking compliance filters non-compliant imports but leaves volume opportunities for REACH-registered entrants. Go-to-market through BIM-integrated material libraries to bypass traditional distributor technical influence. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier extrusion converters with CE marking certification and co-extrusion line retrofitting capabilities in the Netherlands and Germany. Long-term viability hinges on bio-based MMA feedstock positioning and mechanical recycling infrastructure ahead of EU Green Deal embodied carbon thresholds. Watch ECHA regulatory tightening on petrochemical intensity as the inflection signal for stranded asset risk in non-integrated capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MMA Supply | Captive monomer production at Worms and Wesseling insulates Evonik from raw material cyclicality. |
| Co-extrusion Line Retrofitting | UV cap layer integration extends service life guarantees from ten to thirty years for German facade specifications. |
| CE Marking Certification Investment | Construction Products Regulation compliance filters non-compliant imports and protects domestic premium producers. |
| Mechanical Recycling Pathway Development | Post-industrial scrap recovery opens circular economy positioning ahead of EU Green Deal petrochemical thresholds. |
| Bio-based MMA Pilot Scaling | First-mover advantage in cradle-to-gate emissions documentation captures Dutch and German public procurement mandates. |
Research Methodology
Document review covered ECHA registration databases, CE marking conformity assessment protocols, and EU Green Deal implementation guidance, complemented by interviews with acrylic sheet plant managers, procurement leads at German automotive OEMs, distribution channel partners in the Netherlands, and technical R&D directors at Swiss compounding facilities. Secondary validation drew from Cefic chemical industry reports, customs trade data for MMA monomer flows, and SEC filings of integrated chemical groups. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Segment-level outputs across the projection horizon reflect discrete modeling of manufacturing process, thickness stratification, and end-use industry dynamics, with CAGRs derived from regression analysis against construction spending indices and automotive production forecasts. Key inputs included REACH compliance cost trajectories, polycarbonate substitution elasticity in impact-resistant glazing, and solar thermal installation targets in Southern Europe.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA regulatory tightening on petrochemical feedstock intensity and breakthrough scaling in bio-based MMA pathways. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Materials
Conductive Carbon Black Market
Specialty Materials
Gutta-Percha Market
Specialty Materials
Carbon Mold Market
Specialty Materials
Methyl Silicone Market
Specialty Materials
Engineered Quartz Surface Market
Specialty Materials
APAC Fluoroelastomer Market
Specialty Materials
Flexible Colored Polyurethane (PU) Foams Market
Specialty Materials
EVA Interlayer for Photovoltaic Market
Specialty Materials
Global Polybenzimidazoles (PBI) Market
Specialty Materials
Sulphur Bentonite Market
Specialty Materials
Advanced Green Septa Market
Specialty Materials
Europe Textile Films Market
Specialty Materials
Cellulose Gel Market
Specialty Materials
Global Fluorosilicone Market
Specialty Materials
Asia-Pacific Colloidal Silica Market
Specialty Materials
Eptfe in Spotlight-Poly-Vents Market