
 Polyethylene Terephthalate Additives Market | 2026-2036
Polyethylene Terephthalate Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate Additives Market Intelligence
Food packaging is hardening as the dominant demand vertical for PET additives as brands migrate toward extended-shelf-life formats and reduced plastic thicknesses. BASF SE leverages its global polymer stabilizer portfolio to anchor supply relationships with major European bottlers. Evonik Industries AG differentiates through high-performance nucleating agent technologies that accelerate crystallization rates in thin-wall containers. Songwon Industrial Co., Ltd. competes aggressively on antioxidant and UV stabilizer chemistry tailored to Asian processing conditions.
Polyethylene terephthalate additives encompass functional chemicals and compounds blended into PET resin to modify thermal stability, crystallization behavior, flame resistance, or processing characteristics during extrusion and injection molding. Typical loadings range from 0.1% to 5% by weight depending on the target performance parameter, with nucleating agents and stabilizers representing the most technically critical categories for high-speed production lines. Flame retardants command premium positioning in electronics and automotive applications where UL-94 and equivalent burn ratings apply, while plasticizers remain a mature, cost-driven segment with thinner margin pools. Stabilizer demand in beverage bottles is accelerating fastest as converters push for lighter-weight designs without sacrificing clarity or recyclability.
REACH in Europe, FDA food-contact regulations in the United States, and GB standards administered by SAMR in China collectively dictate permissible additive chemistries, migration limits, and declaration requirements across major PET consumption zones. These frameworks are forcing additive suppliers to retire legacy brominated and certain heavy-metal-based formulations in favor of compliant alternatives. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs.
Market Dynamics
Lightweighting imperatives in beverage packaging are compressing wall thicknesses below 200 microns, forcing additive suppliers to deliver nucleation and stabilization performance at loadings that preserve optical clarity and recyclability.
Growth Catalysts
- EU REACH compliance deadlines:Phased restrictions on legacy brominated flame retardants are accelerating migration to phosphorus-based alternatives in electronics-grade PET compounds.
- Beverage bottler consolidation:Mega-converters in Germany, China, and the United States are standardizing additive specifications across multi-plant networks, creating volume pull for qualified suppliers.
- rPET integration mandates:Brand-owner commitments to 30-50% recycled content targets are expanding demand for chain extenders and IV boosters that restore molecular weight in mechanically recycled streams.
Market Restraints
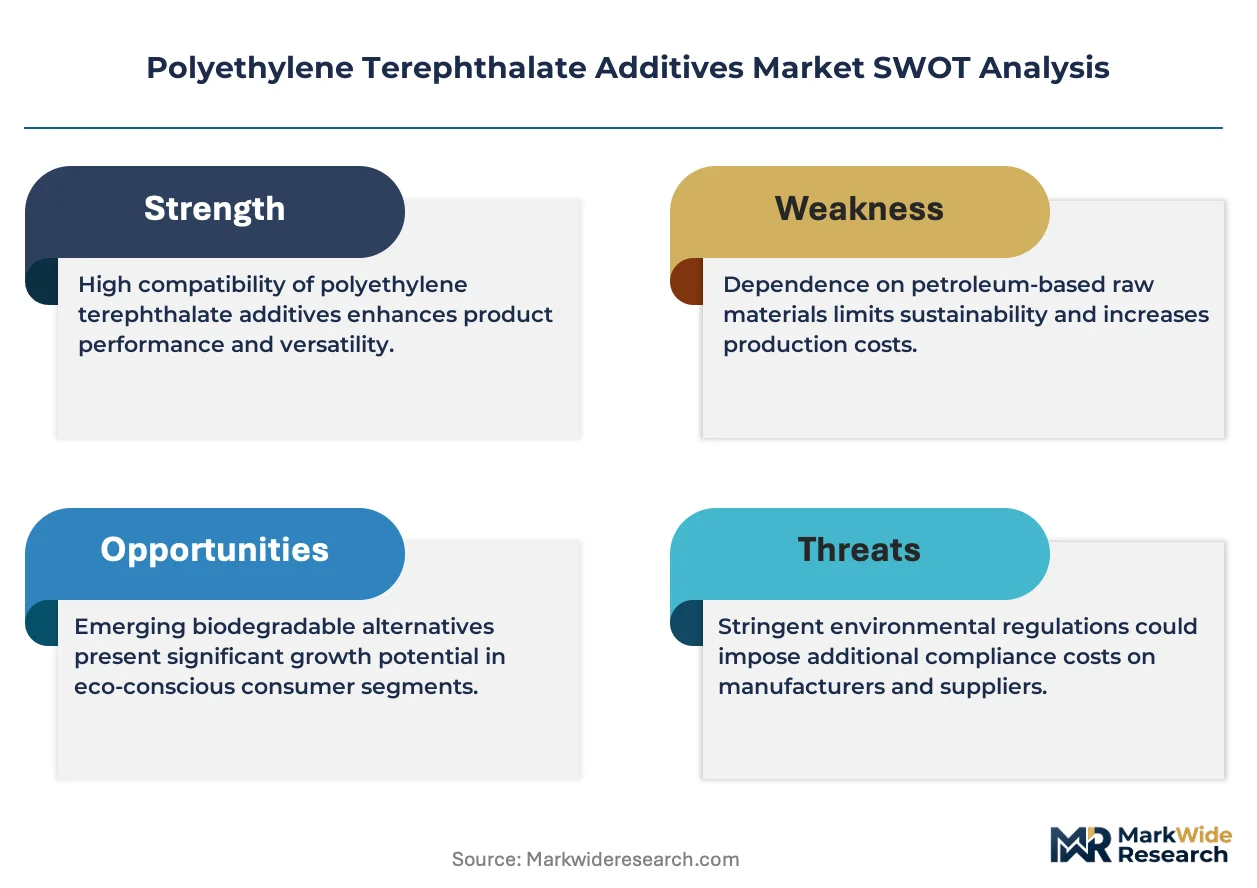
- Ethylene glycol feedstock volatility:PET resin producers pass through raw material swings unpredictably, compressing additive pricing power during margin squeeze periods.
- Antimony catalyst residues:Regulatory scrutiny of heavy metal traces in food-contact applications limits certain stabilization chemistries regardless of additive compliance.
- Polypropylene substitution in hot-fill:Improved barrier PP grades are capturing share in juice and sauce segments above 85°C, constraining PET additive addressable market.
Strategic Opportunities
- India FSSAI food-contact modernization:Upcoming notification alignment with EU migration limits creates first-mover advantage for pre-registered additive portfolios.
- Chemical recycling feedstock preparation:Purification-grade additives that protect resin integrity through pyrolysis or glycolysis loops command technical partnership positions with emerging recyclers.
- Digital twin formulation:AI-driven crystallization kinetics modeling is reducing development cycle times from 18 months to 6 months for custom nucleating packages.
Industry Challenges
- Migration testing capacity bottlenecks:FDA and EFSA notification backlogs extend time-to-market for novel antioxidant structures by 12-24 months.
- Multi-jurisdiction dossier maintenance:Divergent GB standards, REACH SVHC lists, and state-level US restrictions require parallel compliance investments without harmonized data acceptance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate Additives Market |
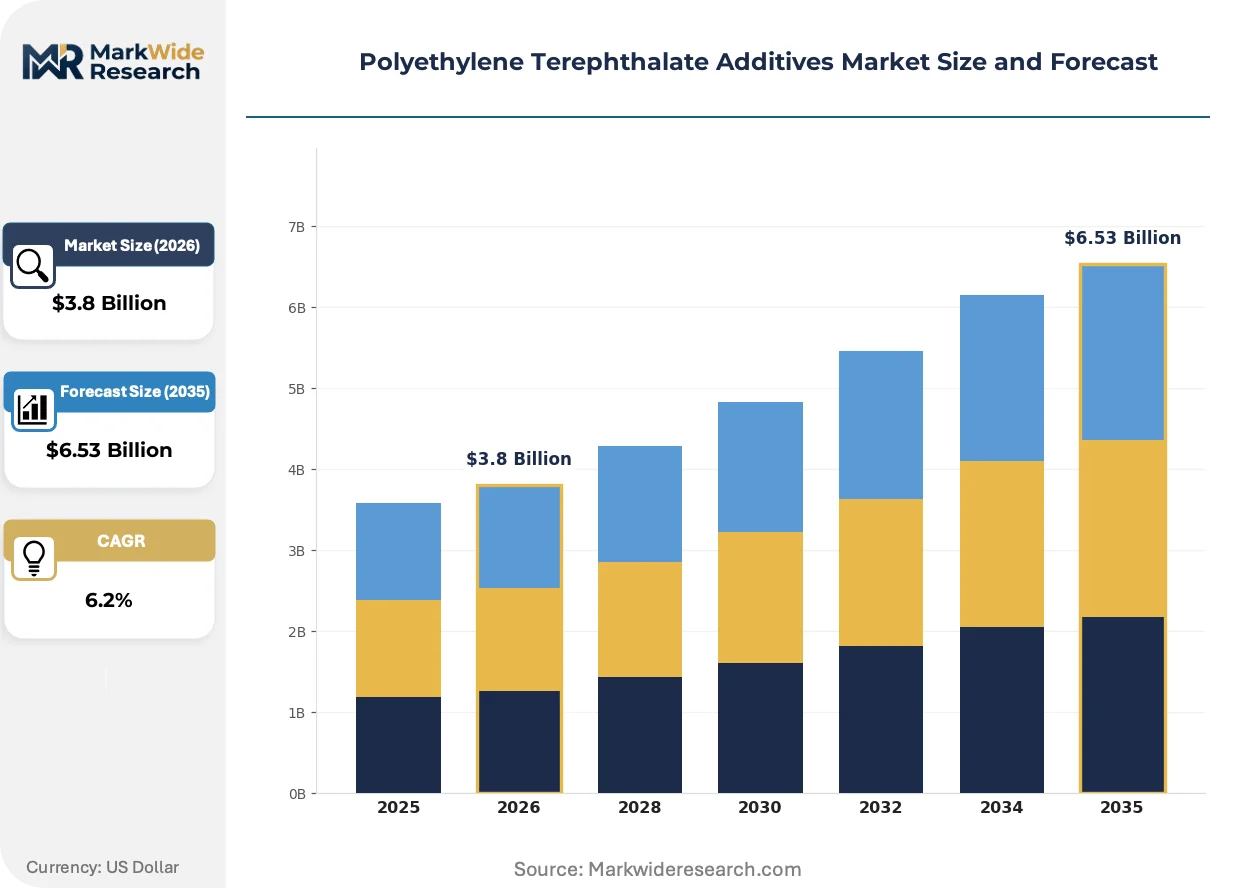
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flame Retardants, Nucleating Agents, Plasticizers, Stabilizers Application: Food Packaging, Beverage Bottles, Textile Fiber, Automotive Components Form: Powder, Granules, Liquid, Concentrate End User: Consumer Goods, Automotive, Electronics, Industrial |
| Companies Covered | Evonik Industries AG, Lanxess AG, BASF SE, Songwon Industrial Co., Ltd., Albemarle Corporation, Clariant AG, ADEKA Corporation, Milliken & Company, Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate Additives Market Strategic Shifts & Innovations
Additive functionality is fragmenting into application-specific modules rather than universal masterbatch platforms, with suppliers building configurable portfolios around processing method and end-use performance tiers.
Reactive chain extenders with epoxy-functional architectures are modularizing rPET upc workflows. Compounders serving Coca-Cola and PepsiCo bottling partners in North America and Western Europe are adopting these systems at pilot scale. The technology is modularizing what had been rigid virgin-rPET blend ratios, enabling higher recycled content without capital-intensive solid-state polymerization.
China's GB 4806.7-2023 food-contact plastics standard tightens specific migration limits for certain phosphite antioxidants and introduces new testing protocols for oligomer extraction. Domestic PET converters face reformulation deadlines in 2025-2026. The regulation is forcing additive suppliers to retire legacy chemistries and accelerate registration of hydrolytically stable alternatives for Asian processing conditions.
Beverage brand technical buyers are consolidating qualified supplier lists from 8-12 vendors to 3-4 strategic partners with full regulatory dossiers. Direct material science collaboration is replacing spot procurement through distributors. This concentration is most pronounced in Germany and the United States, where sustainability scorecard requirements demand supply chain transparency down to additive raw material sourcing.
Polyethylene Terephthalate Additives Market Segmentation
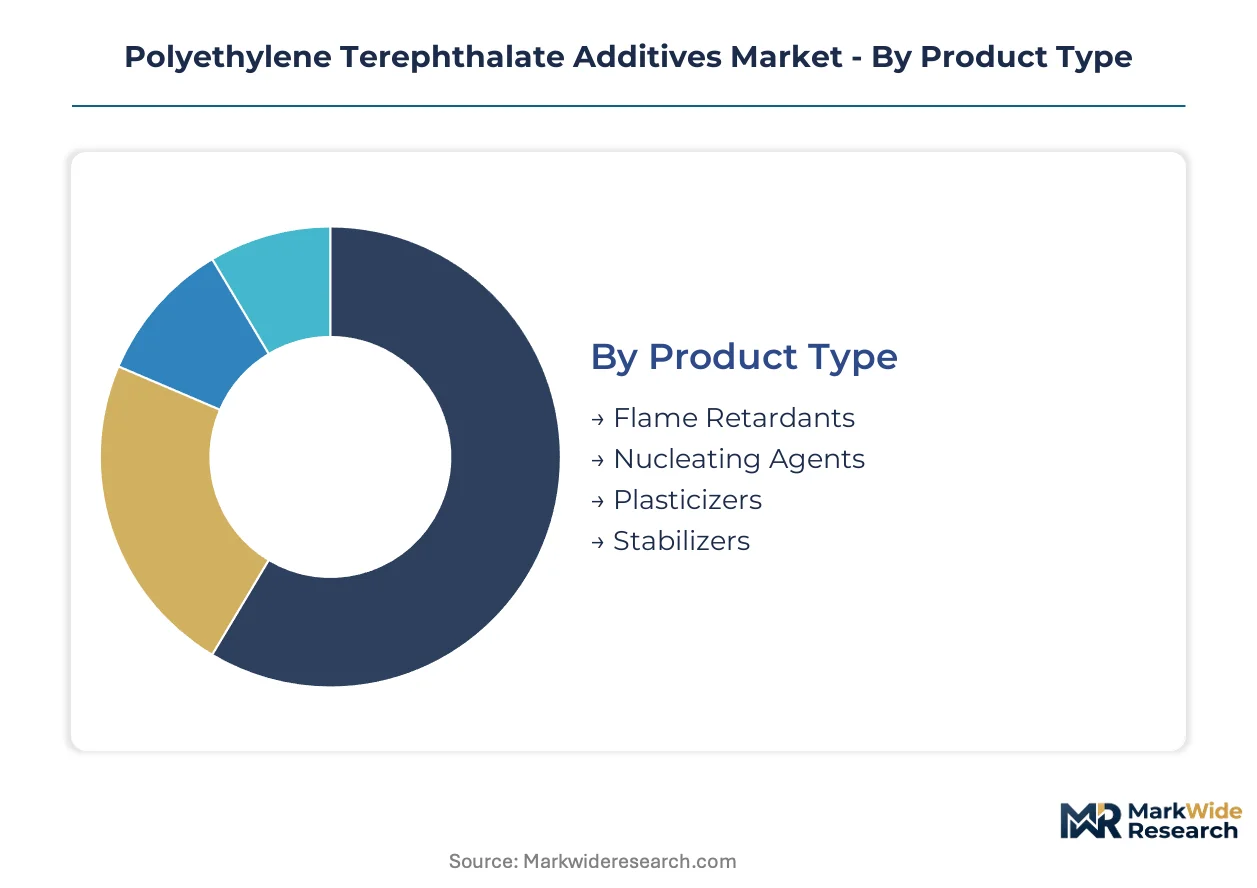
PET additive procurement splits sharply between commodity-driven converters seeking cost minimization and specialty manufacturers demanding performance guarantees. Technical buyers evaluate segments through the lens of regulatory dossier completeness, processing line compatibility, and recyclability certification rather than unit chemistry alone.
Product Type:
Cost tier separates buyers in this category, with premium formulations commanding qualification premiums from multinational bottlers while standard grades serve regional converters.
- Stabilizers:Antioxidant and UV-absorbing chemistries protect PET chains from thermal degradation during high-speed injection molding. Beverage bottlers in Germany and the United States are expanding procurement of hydrolytically stable phosphite alternatives as EFSA and FDA scrutiny tightens on legacy structures.
- Nucleating Agents:These compounds accelerate crystallization kinetics, enabling wall-thinning below 200 microns without clarity loss. Demand concentrates with thin-wall container specialists serving Coca-Cola and PepsiCo networks, where cycle time reduction justifies formulation premiums.
- Flame Retardants:Phosphorus-based and intumescent systems replace brominated alternatives under EU REACH phased restrictions for electronics-grade PET compounds.
- Plasticizers:Mature segment serving flexible PET film and sheet applications where cost minimization dominates supplier selection criteria.
Volume sits with Stabilizers; growth tilts toward Nucleating Agents.
Application:
Application choice tracks end-use temperature requirements and barrier performance specifications that determine additive loading rates and chemistry selection.
- Beverage Bottles:Lightweighting imperatives below 200-micron wall thicknesses drive nucleator and stabilizer demand for carbonated soft drink and water packaging. Major conversion hubs in China and the United States are standardizing additive specifications across multi-plant networks.
- Food Packaging:Extended-shelf-life formats and reduced plastic thicknesses demand enhanced oxygen barrier performance through additive-modified PET. EU REACH and FDA food-contact compliance requirements dominate formulation decisions for tray and film converters.
- Automotive Components:Underhood applications require thermal stability and flame retardancy for connectors and housings subject to UL-94 burn ratings.
- Textile Fiber:Spin finish compatibility and color stability requirements differentiate additive needs from packaging applications.
Revenue concentrates in Beverage Bottles; expansion accelerates most quickly in Food Packaging.
Form:
Supply chain configuration determines form selection, with powder and granule preferences reflecting regional compounding infrastructure and dust-handling regulations.
- Granules:Dust-free handling and precise metering compatibility favor this form for high-speed beverage bottling lines. German and Chinese converters with automated dosing systems specify granule masterbatches to minimize workplace exposure compliance costs.
- Liquid:Pumpable delivery enables continuous dosing in extrusion lines without dry-blending equipment. Asian textile fiber producers prefer liquid systems for spin finish integration and reduced cleaning downtime.
- Powder:Lowest unit cost form serving regional compounders with batch blending capabilities and local dust control infrastructure.
- Concentrate:High-loading formulations for let-down ratios that minimize freight costs for distant processing locations.
Procurement favors Granules for packaging; Liquid gains share in fiber applications.
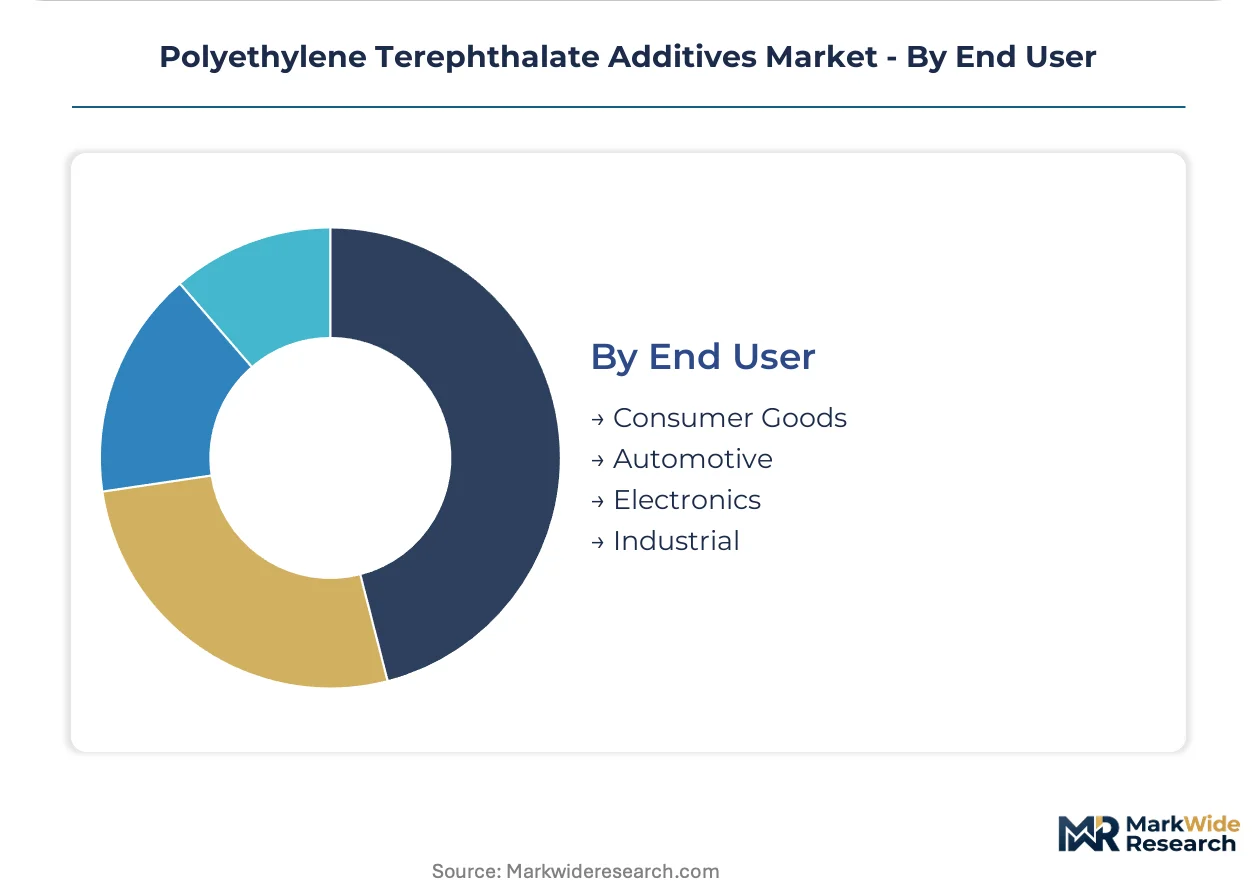
End User:
End user category reflects regulatory exposure intensity, with food-contact and automotive applications demanding full dossier transparency versus industrial buyers prioritizing technical performance.
- Consumer Goods:Brand-owner sustainability scorecards and recycled content mandates drive additive specifications for beverage and food packaging. Direct material science collaboration replaces spot procurement as qualified supplier lists consolidate from 8-12 vendors to 3-4 strategic partners.
- Electronics:UL-94 and equivalent burn ratings mandate flame retardant selection, with EU REACH phased restrictions accelerating phosphorus-based chemistry migration.
- Automotive:OEM material approval processes and underhood thermal requirements create qualification barriers for new additive entrants.
- Industrial:Cost-driven segment with thinner margin pools and lower regulatory scrutiny than food-contact applications.
Specification complexity peaks in Consumer Goods; qualification timelines extend longest in Automotive.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Shanghai, Shenzhen, and Hamburg concentrate additive formulation capacity near major PET conversion clusters. Tax incentives for circular-economy investments are accelerating regional facility upgrades. Supply contracts increasingly specify regional regulatory dossier completeness as a procurement gate.
United States
Beverage bottlers in Georgia and Texas are expanding nucleating agent procurement for sub-200-micron bottle programs. FDA food-contact notification requirements dominate formulation decisions for tray and film converters. The Southeast manufacturing corridor from Atlanta to Charlotte anchors specialty additive blending capacity serving Coca-Cola and PepsiCo networks.
Germany
EU REACH phased restrictions on brominated flame retardants are accelerating phosphorus-based chemistry migration in electronics-grade compounds. EFSA scrutiny of phosphite antioxidants is forcing hydrolytically stable alternative registration. The Rhine-Ruhr industrial cluster hosts BASF SE and Lanxess AG formulation centers supplying European bottler networks.
China
GB 4806.7-2023 food-contact standards are tightening migration limits for phosphite antioxidants and oligomer extraction protocols. SAMR registration timelines are extending market entry for novel stabilizer structures. The Yangtze River Delta concentration of PET converters around Shanghai is driving granule masterbatch demand for automated dosing systems.
India
FSSAI food-contact modernization is aligning notification requirements with EU migration limits for pre-registered additive portfolios. Brand-owner recycled content mandates of 30-50% are expanding chain extender demand for rPET upcycling. Gujarat's petrochemical corridor near Vadodara is emerging as a compounding hub for domestic beverage packaging producers.
Japan
METI circular-economy roadmaps are incentivizing chemical recycling feedstock preparation technologies. PMDA pharmaceutical packaging standards create qualification barriers for antioxidant suppliers serving medical-grade PET applications. The Nagoya-Tokyo industrial belt concentrates automotive and electronics additive demand for underhood and connector applications.
Polyethylene Terephthalate Additives Market Key Industry Players
Top-tier vendors anchor premium formulation tiers, while regional compounders compete on cost-minimization for standard grades. The supplier base organizes around three strategic archetypes: diversified chemical conglomerates with full regulatory dossiers, specialty additive pure-plays with nucleating agent expertise, and regional masterbatch compounders serving local processing conditions. Dominant competitive moves include strategic partnerships with mega-converters for multi-plant specification standardization, and portfolio diversification into rPET-compatible chain extenders and IV boosters.
Within the diversified chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify archetypes built on global polymer stabilizer portfolios and high-performance nucleating technologies respectively. Songwon Industrial Co., Ltd. occupies a position among Asia-Pacific additive specialists competing on antioxidant and UV stabilizer chemistry tailored to regional processing conditions. These three entities represent the concentration of technical capability and regulatory dossier completeness that beverage brand technical buyers now require as qualified supplier lists consolidate from 8-12 vendors to 3-4 strategic partners.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Lanxess AG |
| BASF SE |
| Songwon Industrial Co., Ltd. |
| Albemarle Corporation |
| Clariant AG |
| ADEKA Corporation |
| Milliken & Company |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Reactive chain extender adoption for rPET upcycling is compressing formulation development cycles while simultaneously concentrating procurement power among mega-converters with multi-plant standardization programs. This dual shift is reshaping how additive suppliers structure volume commitments and qualification premiums across European and North American bottler networks.
Pricing Analysis
Short lead-time premiums dominate additive procurement as beverage bottlers in Germany and the United States compress supplier lists and demand rapid qualification turnaround. Three-tier pricing structure across premium, standard, and economy levels separates full-dossier strategic partners from regional compounders and spot-market distributors. Cost compression in standard-grade stabilizers is intensifying because ethylene glycol feedstock volatility passes unpredictably through PET resin producers. Regional converters with batch blending capabilities exhibit highest price sensitivity; multinational bottlers with sustainability scorecard requirements show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with specialized nucleating agent production concentrated in Germany, China, and the United States. Formulation chemistry draws from phosphorus-based flame retardant precursors, hydrolytically stable phosphite antioxidants, and epoxy-functional chain extender monomers. Tariff exposure on specialty chemical intermediates creates margin instability for cross-border masterbatch shipments. Distribution runs through qualified direct partnerships replacing spot procurement, with technical collaboration agreements replacing distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET additives sector is transitioning from legacy brominated and heavy-metal stabilization chemistries toward phosphorus-based and hydrolytically stable alternatives. This replacement cycle compresses reformulation timelines while elevating regulatory dossier completeness as the primary competitive barrier.
For Market Incumbents: Deepen backward integration into hydrolytically stable phosphite precursor manufacturing to defend margin position against feedstock volatility. Accelerate SAMR pre-registration for GB 4806.7-2023 compliance ahead of domestic Chinese converter deadlines. Lock multi-year technical partnership agreements with Coca-Cola and PepsiCo bottling networks to secure volume against emerging pure-play nucleating agent specialists. For New Entrants and Emerging Players: Enter via FSSAI-aligned additive portfolios targeting India's upcoming food-contact modernization before incumbent dossier transfers complete. Focus initial penetration on regional textile fiber producers in Vietnam and Indonesia where liquid additive dosing infrastructure favors pumpable system suppliers. Pursue toll-compounding arrangements with established masterbatch houses rather than greenfield formulation capacity. For Investors and Strategic Acquirers: Re-rating potential sits with nucleating agent pure-plays given lightweighting imperatives pushing wall thicknesses below 200 microns across beverage packaging. Long-term viability hinges on rPET-compatible technology portfolios through the chemical recycling scale-up window. Monitor EFSA and FDA notification backlog resolution as the signal for novel antioxidant structure market entry acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Manufacturing | Captive supply of hydrolytically stable phosphite intermediates insulates margin from ethylene glycol volatility. |
| Multi-Plant Specification Standardization | BASF and Evonik leverage qualified supplier status across Coca-Cola bottler networks to lock volume. |
| Regulatory Dossier Pre-Registration | SAMR and FSSAI alignment investments create first-mover advantage in tightening Asian migration limits. |
| Technical Partnership with Mega-Converters | Direct material science collaboration replaces distributor spot procurement as qualified lists consolidate. |
| rPET-Compatible Formulation Development | Reactive chain extender portfolios enable 30-50% recycled content targets without solid-state polymerization. |
Research Approach
Trade databases, ECHA REACH registration filings, and SEC 10-K chemical segment disclosures formed the secondary backbone for supply-side capacity and competitive positioning assessment. Primary interviews with PET plant managers, beverage bottler procurement leads, masterbatch distribution channel partners, and technical R&D directors at additive suppliers were combined with secondary validation. Bottom-up volume estimates from converter consumption patterns and top-down value estimates from resin production statistics were triangulated to cross-check segmentation outputs.
Historical trendline analysis of additive loading rates by application and grade tier informed the projection framework across the analysis window. Segmentation dimensions modeled include product type, application end-use, physical form, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating lightweighting penetration rates and rPET integration mandates. Industry-specific forecast inputs captured EFSA phosphite antioxidant scrutiny timelines and GB 4806.7-2023 reformulation deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between EU REACH, FDA food-contact, and SAMR GB standards. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Cetane Improver Additives Market
Additives
Refining Additives Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Stabilizers Market
Additives
North America Fuel Additives Market
Additives
Marine Fuel Additives Market
Additives
Sodium Metabisulfite Market
Additives
Isopropyl Acetate Market
Additives
Polysorbate-80 Market
Additives
Global Hindered Amine Light Stabilizers Market
Additives
Gasoline Additives Market
Additives
Feedstuff Additives Market
Additives
Monocalcium Phosphate Market
Additives
Tocopheryl Acetate Market
Additives
Global Corrosion Inhibitor Market
Additives
Friction Modifier Additives Market